Download

Second Quarter in Insurtech Financials

Growth at Lemonade, Root and Metromile may be slowing. Is the reason issues with customer acquisition or a focus on underwriting profitability?

|||||||||||||||

Summary

  1. Growth rates remain robust but may be slowing a bit – are there issues on customer acquisition, or are carriers focusing more on underwriting profitability?
  2. Gross loss ratios are generally stable or improving slightly but still unsustainable
  3. Industry veterans are outperforming the newbies on loss ratio but not premium growth.
  4. It will still take several years to become scale insurers
  5. Reinsurers continue to subsidize losses
  6. Executive compensation appears to be as expected - probably mostly in stock

Context

The networking tips from the great Spanish swordsman Inigo Montoya got us thinking about the insurtech startups climbing the Cliffs of Insanity. While the lumbering incumbents are indeed powerful giants and have a head start on the climb, they are also carrying lots of weight.

Violà, startup vs. incumbent.

The venture-backed, full-stack U.S. insurtech startups continued to gain in the second quarter through rapid premium growth and moderately lower underwriting losses. But they have yet to show the ability to win at a sword fight, battle of wits or ROUS attack or to generate a sustainable loss ratio under 100%.

This is the third installment of our review of U.S. insurtech startup financials. Here are the 2017 edition and first quarter 2018 edition, which generated many social media discussions. For more information on where our data come from and important disclaimers and limitations, see the 2017 edition.

Our scope is only property & casualty companies, so we don’t cover life, health (sorry, Mario), mortgage and title (sorry, Daniel). As before, we respect the management teams highly and admire these companies for earning the right to call themselves an “insurance company” -- more on that below.

To date, we have tracked the three independent P&C startups most commonly associated with the label "insurtech": Lemonade, Metromile and Root. This quarter we’ve looked at newly licensed Next Insurance (which wrote no premium) plus four subsidiaries of larger companies with a direct or insurtech focus.

Overall results

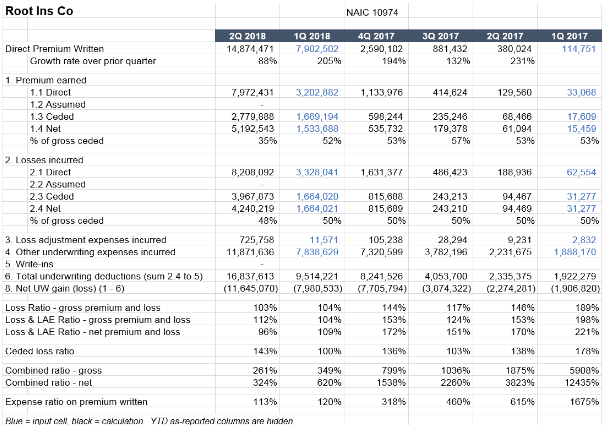
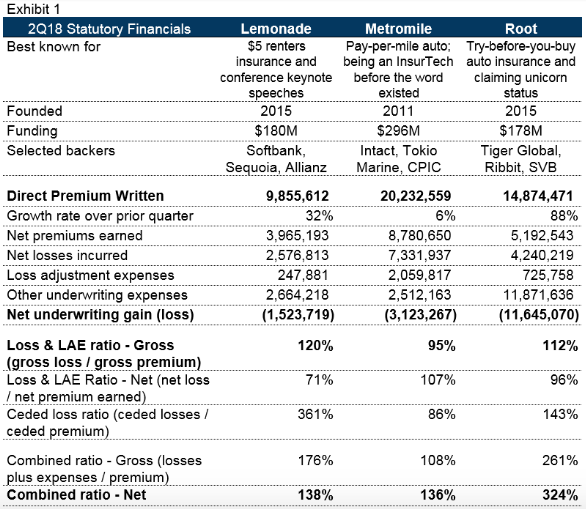
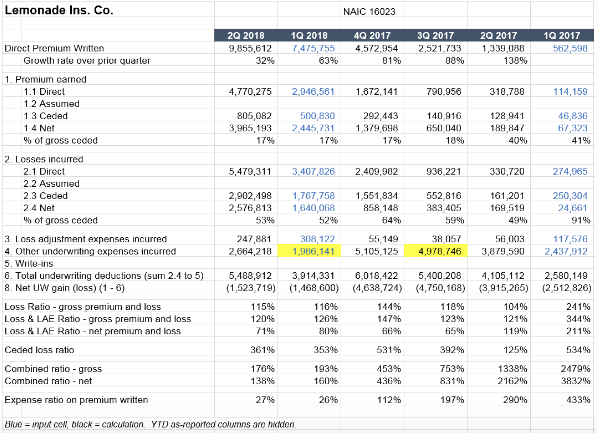
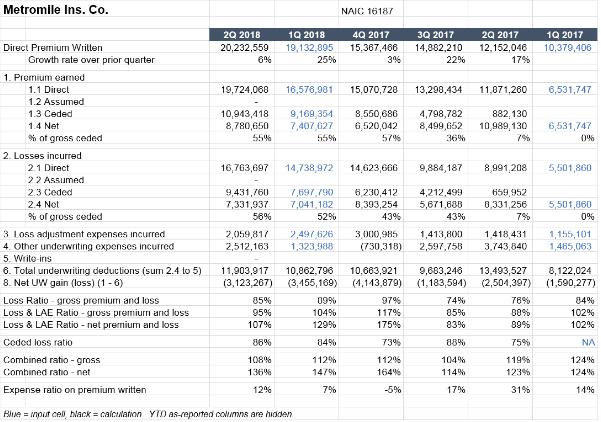
For the real insurance nerds, here is a summary of the 2Q18 statutory financials of three venture-backed insurance companies. Only “insurance companies” have to file statutory results, not agents and brokers (i.e., most insurtech underwriters), which are not “insurance companies.” We present the summary here and quarterly details on each of the venture-backed companies at the very bottom.
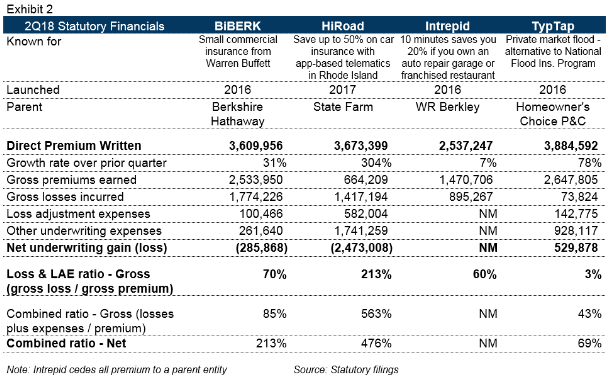
And here are the four subsidiaries of big companies that are selling direct or have a claim on being an insurtech. These companies often depend on parents for reinsurance and infrastructure, so we show mainly the gross figures.
Growth rates remain robust but may be slowing a bit – are there issues on customer acquisition, or are carriers focusing more on underwriting profitability?

Absolute growth was led by Root, which nearly doubled its quarterly gross premium written in three months. Our composite grew at 37% quarter over quarter, but most of the companies had their slowest or second-slowest quarter in the last six.
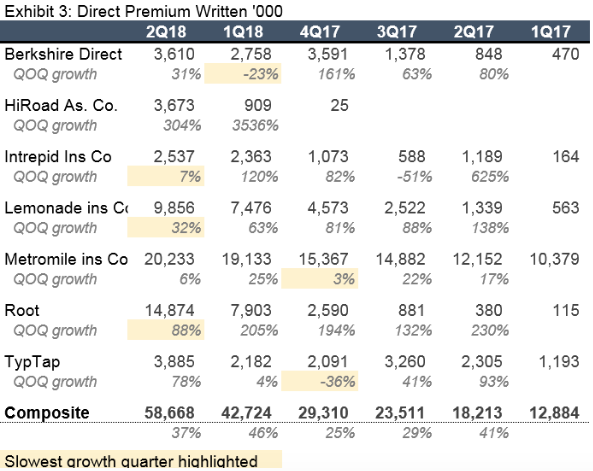
Is this a slight slowing trend? Maybe. Some of the carriers may be seeing seasonal effects. If the pace of growth is really showing the first signs of slowing and not just a blip, the question is whether the slower growth is despite insurers’ efforts to grow or if they are deliberately focusing on profitability. The CEOs of Root and Lemonade have hinted that they are focusing more on underwriting (here, here), so is this affecting growth rates? Here is a point/counter-point. Decide for yourself.

See also: The First Quarter in Insurtech Financials  

Point: Insurtechs are finding growth more difficult

  • Early adopters of direct insurance may already have been won; consumers with a high propensity to buy online may be located in the states that carriers chose first, and future customers may be harder to win.
  • It may be harder to sell the value proposition than expected, particularly if underwriting is being tightened and differentiation is narrowing (e.g. Lemonade’s giveback declined from 10% of premium in 2017 to a less-compelling 1.6% this year.)
  • Retention rates may be less than expected - either because customers defect or the carrier non-renews unprofitable customers.
  • Focusing on state expansion, team growth or fundraising distracts management.

Counter-point: Insurtechs could grow faster but are throttling growth to focus on profit

  • It is unlikely that companies with near-zero brand recognition have penetrated even a fraction of potential customers
  • Startups, their investors or their regulators may have realized that early customers were attracted to unsustainably low prices and produced high loss ratios. As they learn more about their customers, startups are being tougher on underwriting or are raising price in new state filings, meaning they turn away more potential customers through price or declining the application. Lemonade has admitted as much - see page 594 of its recent Oregon filling for this nugget:
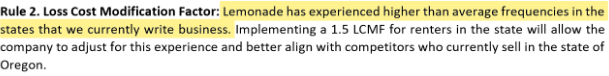
The LCMF is a Loss Cost Modification Factor, and higher LCMFs may indicate higher pricing. In spot-checking some of Lemonade’s recent filings, we find that it is still filing a $5 minimum rate but is pricing higher than incumbents such as State Farm in certain zones, perils, etc. The company’s frequency being higher than average could be a function of (1) a bot-driven claims system inviting fraud, (2) having shlimazels for customers, (3) problems with the coverage or form or (4) the behavioral economics assumptions not working as intended.

Recall Lemonade saying: “If you tried to create a system to bring out the worst in humans, it would look a lot like the insurance of today … We’ve spent recent years deepening our understanding of honesty and trust ... Lemonade aims to reverse the adversarial dynamics that plague the industry, transforming both the economics and experience of insurance.”

What do you think? 

Status of the climb up the Cliffs of Insanity (direct premium written)
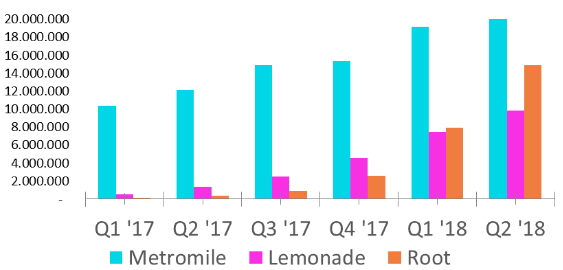
Focusing on the protagonists of our previous analysis Bigger and Redder, Root’s extraordinary growth means it has opened a big gap on Lemonade and is closing the gap with Metromile. This dynamic has helped Root achieve unicorn status, with the last $100 million round of funding at the iconic $1 billion valuation. Root is not the first insurer to test a “try before you buy” (TBYB) approach based on an app, but it is the first insurer in the world to build a sizeable portfolio that way. Will Root succeed where others have abandoned their efforts or chosen different approaches such as usage-based pricing or discounts at renewal?

We commend Root for hitting the symbolic unicorn status so quickly. It appears to have a few years of runway to prove its model. By the time of an exit for the most recent investors, we believe that Root will be evaluated in greater part on the traditional KPIs that we look at in our analysis.

A few weeks ago, Bain Capital – we are Bain & Co. alumni – offered $1.55 billion to buy Esure, a P&C insurer (mainly motor) selling online in the U.K. Esure wrote £880 million (annualized) premium in the first half of 2008 (or about US$1.1 billion) -- and did so at a profit. Looking very simply at price-to-sales ratio (though we prefer ROE and price-to-book), Esure sold a bit over 1.4X, which simplistically corresponds to $700 million of premium for a valuation of $1 billion. Investors will need Root’s management to continue to grow rapidly – their 2Q18 run rate is $60 million.

Whether they can do so, and achieve profitability along the way, will be a bellwether for demonstrating if current valuations are a bubble or smart bets on a rapidly changing industry. Root’s $1 billion valuation (looking abroad, Chinese startup carrier Zhong An has a $7 billion valuation despite a 124% combined ratio in the first half) should cause companies in low-margin commodity lines like home/renters and auto that are operating as MGAs to consider becoming a carrier.

One of the strongest arguments for being an MGA, not a carrier, is that MGAs are more highly valued because they trade on a multiple of earnings rather than book value. For the time being, the most valuable recent startups in insurance underwriting appear to be carriers, not MGAs.

Gross loss ratios are generally stable or improving slightly but still unsustainable

We prefer to look at gross loss ratio, i.e. before any premiums and losses are ceded to reinsurers, because sticking losses to reinsurers isn’t a sustainable long-term strategy. Eventually, gross loss ratios need to be sustainable. This quarter’s numbers are basically unchanged since last quarter, though Lemonade and Metromile have adverse development in this quarter, which raises the reported loss ratio.

If our subject companies are shifting management attention toward profitability, it is not yet obvious in the figures. Improving underwriting results is like steering a slow-moving boat. You can turn the tiller, but the boat may not go the way you want, and it will take some time. Insurance policies last a year, rates are regulated by states and unsettled old losses can get worse if the legal environment changes.

Gross loss ratio evolution
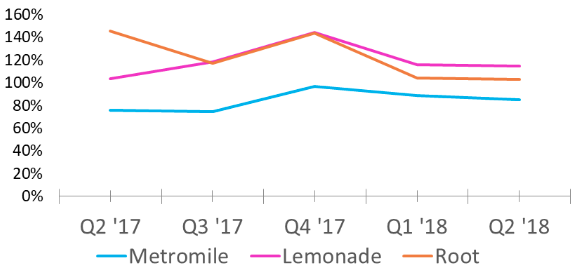
Of the three venture-backed startups, Metromile’s figures have always shown the greatest profitability, and the company shows an improvement on the last quarter, shaving four points off the loss ratio. Not all startups are experiencing unsustainable loss ratios. Hippo -- a homeowner’s MGA -- claimed to have produced better-than-market underwriting straight out of the gate, although we have no way to verify this.

Conference chatter is increasingly turning to profit, not just premium. We welcome these signs of maturity in the insurtech market, which were a big reason we started writing these articles and presenting at conferences.

Industry veterans are outperforming the newbies on loss ratio but not premium growth.

Two of the startup carriers sponsored by highly regarded underwriters are performing very well in terms of profit. BiBerk, which ultimately reports to Ajit Jain, recorded a respectable 70% gross Loss & LAE ratio in the quarter. Intrepid, where Rob Berkley sits on the board, turned in a 60% loss ratio (without LAE). Neither company has cracked even $4 million in quarterly premium, compared with Root at nearly $15 million, but is there something that Ajit and Rob know that the newbies don’t? Or are big public companies just less motivated to grow than venture-backed companies? Or is growth first really the right answer?
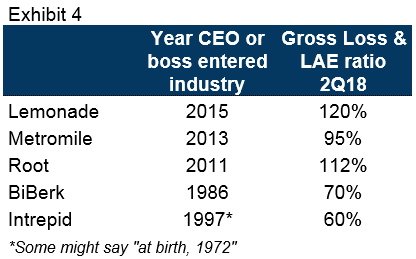
 

We’re not showing State Farm’s HiRoad entity because we’re less clear on how it reports and is managed by State Farm’s executives.

It will still take several years to become a scale insurer

All three venture-backed insurers increased expenses in the quarter. Root lost $11.6 million, a burn rate of $129,000 every day. That still gives two years of runway if the burn rate can be maintained. We get details on expenditures only in annual statements, so we cannot know for sure whether Root is spending on headcount, advertising or other overhead. LinkedIn pegs the company’s headcount at 117, with 30 people joining just in the second quarter.

The company runs a referral program that has paid $860,000 to date. We speculate that $25 is the average referral bonus (so $50 because both parties get the bonus), which equates to 17,000 referrals. If the average premium is $750 (again, a guess; a bit below the national average), then the referral program has generated more than $13 million of premium at a CAC of $50, which would be an impressive 40% of all the premium in these first 18 months.

As the company expands exponentially to grow into its unicorn valuation, the question for investors is if the company can maintain exponential growth and bring down the loss ratio simultaneously, so growing without raising losses exponentially. It’s a difficult balance.

In the meantime, investors added $45 million to the insurance company’s statutory surplus, but -- because of losses -- surplus stands at $43 million at the end of the quarter.

Root’s CEO says that the company is getting better at pricing and predicting the business, and that “conservativeness” in reserves means prior results were better than they appeared. We agree with Root that there is increasing evidence of conservative reserving, but not based on the figure it cited in the blog. Root says that only 66 cents on the premium dollar was paid as claims in 2017 (net) – which appears to exclude payments expected for open claims and losses incurred but not reported (“IBNR”). The more meaningful number, in our view, is that Root has recorded $344,000 of favorable development this year -- meaning it has decided that its estimates of prior-year losses were indeed too high.

The company earned $792,000 of premiums in 2017 and stated losses at Dec. 31, 2017, at $1.3 million, for a net loss ratio of 168%. If 2017 actual losses were in fact $986,000, as they are now estimated, then the developed loss ratio would be 124% -- which is better but doesn’t greatly change the overall view of the year, which was small and volatile and hence of limited use to understand the company (but the best any outsider had at the time).

Root also deserves credit for being the only one of the three venture-backed companies to have made conservative loss picks. Lemonade continues to see its reserves be inadequate. The company had $2.1 million of reserves at the start of the year and has seen $245,000 of adverse development this year. Even a more experienced underwriter, Metromile, started the year with nearly $14 million of reserves and has recorded nearly $1.5 million of adverse development.

Stepping back from the noise of quarterly reserving, we still believe that the companies have to prove underwriting quality and do so with sustainable overheads and expenses. There’s still a long journey ahead, but the companies have the resources (in the form of cash at the holding company) to work on the challenge for years to come.

Reinsurers continue to subsidize losses

Lemonade continues to hand reinsurers $3.61 of losses for every $1 in premium in the quarter. Root handed reinsurers $1.41 of losses for every $1 in premium. Metromile -- as with other metrics -- is playing a safer game, and its reinsurers even made a bit of money in the quarter, getting $0.86 of losses for every $1 in premium.

Root disclosed that it changed its reinsurance program, reducing its quota share from 50% to 25% of premium effective June 1 through the remainder of 2018, meaning it will keep more premium (and losses) and possibly get less capital relief. The company retains a $1M xs $100K per-risk excess of loss treaty(*). Terms were not disclosed. (*)

Explanation of reinsurance basics: In quota share reinsurance, an insurer reinsures a percentage of its book – a fixed percentage of every dollar of premium and loss. The reinsurer pays the insurer a ceding commission to cover the insurer’s expenses and may assume unearned premiums (a liability), which may increase the insurer’s statutory capital. In excess-of-loss reinsurance, the reinsurer covers every dollar above a certain amount (the attachment point) up to a pre-defined limit. Excess of loss reinsurance can be written per event (such as a storm) or per risk.

In Root’s per-risk reinsurance, the reinsurers appear to take each and every loss of more than $100,000 to the extent that the loss exceeds $100,000, up to $1.1 million. Here is a technical resource on the subject of using reinsurance for capital optimization.

See also: Can Insurtech Rescue Insurance?  

Executive compensation appears to be as expected -- likely mostly in stock

Many insurers are required to file an annual Supplemental Compensation Disclosure listing the name, title and compensation of their top 10 executives. The requirement was triggered by an investigation in 1905. (Here’s some trivia for a cocktail party at InsureTech Connect: That’s the same year Las Vegas was founded.) The state of Nebraska will mail the information for all companies that operate in Nebraska to anyone who sends them $80. The hardest part is finding a computer with a CD-ROM drive.

This is a sore point among insurers (the disclosure, not the need for a CD-ROM). Some insurers risk a fine instead of being transparent, such as by putting zeros for their compensation or putting a blank piece of paper over the data before mailing it. We like numbers, and there are reasons for the disclosure in an insurance context. Most insurers are subject to extensive regulation and disclosure of their rates, which need to be reasonable, which means not paying executives excessively and passing costs through in the rate. And, as Lemonade says, insurance is a business of mutual trust, which requires reasonable executive compensation practices, even if not overseen by shareholders. For more on the disclosure, click here.

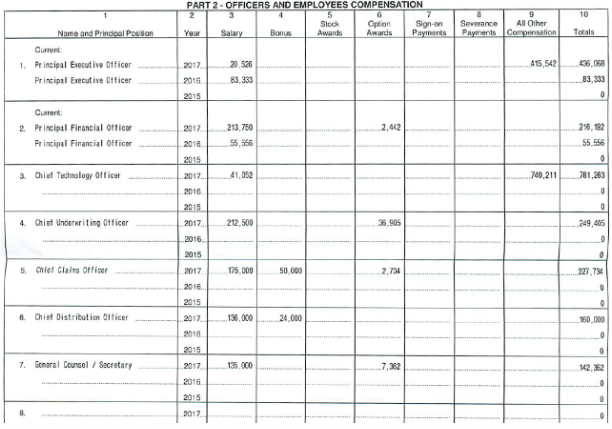
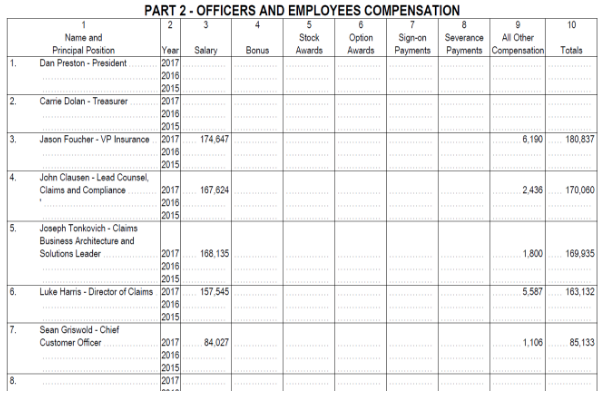
Lemonade and Metromile are required to complete the disclosure, though Lemonade’s commitment to transparency doesn’t extend to putting the required names on the form. Their disclosures are below. The numbers are not huge -- indeed, they are within what one would expect for a startup, where founders and early joiners get big equity grants with salaries that pay the bills but are often dramatically less than what a senior executive at an insurer typically earns. Interestingly, two of Lemonade’s founders sold shares in 2017, which is reflected under “all other compensation.” Metromile seems to have forgotten a few figures in its filing. Note that both Lemonade and Metromile “allocate” compensation to companies within their holding company system, and in absence of information on how this allocation works, it is possible that these figures are materially understated because of the allocation.

Here is Lemonade Insurance:
Metromile Insurance: One last note on compensation. Metromile filed its disclosure electronically, while Lemonade apparently walked down to the Post Office. We don’t know how to explain why a high-tech company like Lemonade would use snail mail. It mailed the disclosure on March 1, a Thursday, so it must have been #TBT in Lemonade’s offices.
Next Insurance U.S.

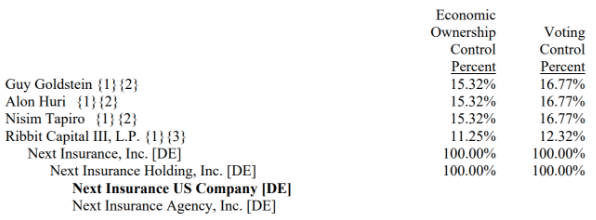
Digital small business insurer Next announced in May a plan to form a new carrier, and it has. The company was formed in September 2017, which indicates that the plan will have been in the works for a year before the carrier writes business. Next’s filing was all zeros except the surplus (or equity) in the company, which is more than $10 million. As of November 2017, the company’s business was described as follows: “The Company will initially offer Contractors Insurance in three levels of coverage for 190 classes including Handymen, Carpenters, Electricians, HVAC Technicians, Landscapers, Janitors and Plumbers. All Contractor Insurance plans will include general liability ($5 million limit), professional liability ($3 million limit) and inland marine ($3 million limit) coverages. The Company will eventually write other types of small business classes including restaurants, daycares, personal training and photographers. These products are currently produced by licensed producers of Next Parent on other insurance carriers’ paper. … The company will eventually offer the following additional types of commercial insurance to small businesses with $3 million maximum limits, unless indicated otherwise: commercial property, commercial auto, director and officer liability, employment practices liability, business interruption, surety bond ($1 million limit), liquor liability, cyber, data breach ($5 million limit). The Company’s planned net retention for all lines will be 20% of the maximum limits.” The remaining 80% of limits will be ceded to Munich Re Americas (MRAm). The company’s directors are Guy Goldstein (the CEO), Nisim Tapiro (co-founder) and Dawn Puro. As of November 2017 (before the most recent $83 million fundraising), the company’s ownership was as follows:
What’s in a name?

A recent startup proclaims: “[Company name] Insurance is a [line of business] insurance company that provides [line of business] coverage to small businesses through a simple online experience. Offering A.M. Best A-rated insurance… direct to customers since 2018...” That wording makes consumers think they’re dealing “direct” with an insurer, not an agent or broker, which is what this company is. Words matter in insurance, as illustrated in the first section of the California Insurance Code.

  • Insurer: “The person who undertakes to indemnify another by insurance.”
  • Broker: “A person who, for compensation and on behalf of another person transacts [insurance] … with, but not on behalf of, an admitted insurer.”
  • Agent: “A person authorized, by and on behalf of an insurer, to transact [insurance] … on behalf of an admitted insurance company.” [emphasis added].

#themoreyouknow “Congratulations, you’re innovating in a highly regulated industry”

Still on the subject of regulation, let’s have some fun with deficiency letters. Part of the joy of getting a new insurance program licensed in a new state is the exchanges with regulators. The insured makes a filing of a few hundred pages, the state reviews it and states its objections, and ‘round we go for, potentially, months. If you’re an insurance nerd, you might find these letters interesting. Particularly Lemonade’s, if only because of how the sausage-making of insurance contrasts with public statements about doing better for consumers.

A recent letter from Oregon to Lemonade had language like this: "Please explain why the insurer is choosing such broad exclusionary language; and if possible, provide an example of why this is necessary to have." Hmm… A letter from Virginia last month listed nine pages of objections, even objecting to Lemonade’s definition of “hovercraft.”

A sample of the objections: "The Company will need to withdraw under the Special Limits, items (g), (h), (i), (j), and (k). The limitations the Company has outlined in these sections are more restrictive than the provisions in the minimum standards set forth in the [Virginia Administrative Code]. It is not permissible for the Company to place limitations or impose special limits that are more restrictive than the minimum standards set forth in the VAC. For items h and i, it is acceptable to impose a special limit or to exclude business property but it is not acceptable to impose a special limit or to exclude property used for business purposes. For example, if I take my laptop (business property) home to do some work, the business property can be limited or excluded. However, if I use my personal computer at home to do some Bureau of Insurance work, that is personal property being used for a business purpose and coverage cannot be limited or excluded." Score a point for the Virginia Bureau of Insurance for using human language.

All this, and we haven’t even gotten to Policy 2.0. Maybe dealing with U.S. regulators is why Lemonade is now keen on international expansion?

Meanwhile, the interviewers at Bloomberg TV have been reading our articles.

See also: Startups Take a Seat at the Table  

Looking forward

The third quarter, which includes most of the summer, could be a big one for the companies in our coverage, because insurance often changes when people move. We are gratified by the increasing focus on insurance fundamentals in insurtech, and the lofty valuations recently seen in the sector will require satisfying both venture metrics as well as solid insurance fundamentals. The startups have the time and the resources but a long way to go to climb the Cliffs of Insanity. They are gaining on the incumbents, but will they make it to the top of the cliffs before running out of power? It’s not inconceivable.
This article was written by Matteo Carbone and Adrian Jones.
How to Cut Litigation Costs for Claims

Using AI, here are three ways to transform workers' comp claims from lose-lose to win-win for both companies and injured workers.

Attorney involvement has been steadily driving up workers’ compensation claims costs over the past decade. In 2014, the California Workers’ Compensation Institute (CWCI) published results of a five-year study that showed that when a single injured party brought in a lawyer the associated costs per claim went up by an average of $40,000 for permanent disability payments and $25,000 for temporary total disability benefits — even if the case never went to court. In Florida from 2016 to 2017, legal fees related to workers’ comp claims totaled nearly $440 million — approximately $254 million of that came from employers defending claims while injured workers themselves were responsible for $186 million (an increase of 36% in just one year). These cases do not bode well for anyone except law firms. Given this present reality, what can companies do to eliminate or at least minimize the effect of lawyers on the claims process? How can they protect themselves and keep costs from ballooning out of control while helping workers get back to their jobs faster? Here are three keys to consider: 1. Stop Litigation Before It Starts This is the No. 1 component in keeping costs down and workers happy. Contrary to popular belief, workers don’t want to sue their companies. They need their jobs and want to return to them quickly. But they also want to get results. Most attorneys are engaged only when injured workers don’t feel like their claims are being properly addressed. For example, they might not know how to get what they need, or they haven’t heard back about who they should see or what the next steps should be. To reduce the potential for attorney involvement, companies should leverage new technologies that apply artificial intelligence (AI) to search claims and assess the risk of litigation. These solutions can quickly flag claims that need intervention so that the right member of a claims team can step in and provide a bit more hand-holding, from making appointments on the worker’s behalf with doctors who have the best outcomes scores to conducting a basic check-in to see how the worker is feeling or how the recovery process is going. See also: Breaking the Cycle of Litigation in WC   Early intervention that cuts off litigation before it starts is the ideal scenario. Claims that steer away from an engaged attorney can save roughly $42,617 from direct claims costs. That’s not spare change, particularly when a company needs to address multiple claims. In one example from a recent CLARA study, a small regional carrier ran a six-month pilot using AI-based software to identify claims that were referred to a high-touch team. At the end of the pilot, the carrier reported that its “litigation rate went from 14% of all claims to 5%. This means that even a smaller carrier, with 20,000 claims per year, would save approximately $42 million in claims costs if it was only half as successful as the pilot example.” That’s a pretty substantial, tangible return on the investment in the software. 2. Identify and Engage the Most Effective Lawyers Some claims will move forward with a lawyer regardless of early intervention. But all is not lost! Just as all workers’ comp physicians are not created equal, neither are attorneys. Claims teams can still save a significant amount of money, time and frustration simply by involving the right lawyer. Outcomes-based attorney scoring is common practice. When this scoring uses machine learning algorithms, as the newest solutions do, the best attorneys for a case are right at the fingertips of claims teams. These lawyers can work toward a fair settlement before going through a long, painful litigation process (though in some cases, it is worth it to engage in litigation if demands are unrealistic, which a good lawyer would quickly recognize). 3. Use Smart Tools to Optimize Settlements It’s worthwhile to adopt AI-based solutions that can lend invaluable insight on optimized settlements for specific cases. Having instant access to quality, detailed information about similar claims can help determine whether to fight or settle a pending lawsuit. Machine learning provides leverage. This saves money. While avoiding attorneys is always the goal, smart tools can stop the bleeding when it is unavoidable. See also: Claims Litigation: a Better Outcome?   AI and machine learning have the capacity to change the upward trajectory in workers’ comp costs. With products and tools incorporating these smart technologies in meaningful ways, the claims process can be transformed from lose-lose to a win-win for both companies and injured workers.

New Power Shift in P&C Insurance

When data and capital were scarce, P&C insurers were highly profitable. But now data and capital are everywhere.

||
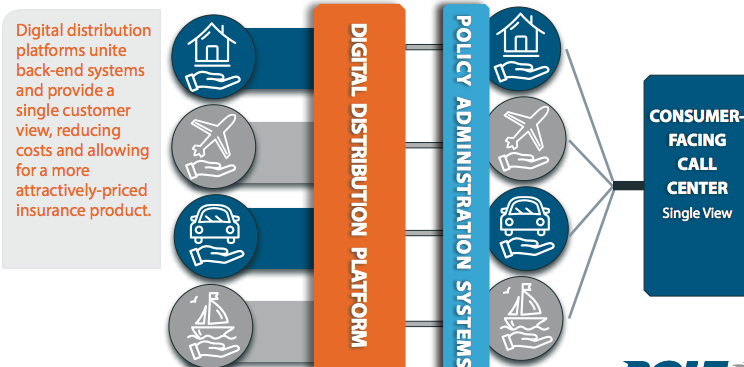
P&C insurance carriers have witnessed a lot of changes in the past decade, but few have been as surprising as the shift of power currently taking place across the industry. According to Dennis Chookaszian, the former CEO and chair of CNA, carriers maintain only 40% of profits today, representing a drop of 20 to 25 points from the 1960s. An equal share now goes to the distribution system, as carriers line up to acquire and maintain more customers. What’s behind this shift in profitability can’t be summed up in a single word, but increasing competition, new market entrants, improving technology, changing customer expectations and continued consumer price sensitivity all play a role. To remain competitive, carriers will need to gain more control over distribution, a goal that even Chookaszian admits will not be easy to achieve. Why the Power-Shift Toward Distribution In the mid-part of the last decade, insurance carriers required two primary competencies to operate: data and capital. Because neither was easy to acquire, competition was less robust, and incumbent carriers found greater profitability, taking in roughly two-thirds of insurance transaction profits. Today, data is everywhere, and through the use of analytics, simpler than ever to understand and use. Capital is also easier to acquire, as is evidenced by the growing number of insurtech players in the industry. According to Willis Towers Watson, $2.3 billion was invested in new insurance tech companies in 2017. According to Chookaszian, the core competency for insurers now lies in distribution and control of the customer. “It’s become so competitive that the carriers basically are always out looking for new accounts,” Chookaszian says. That means higher commissions are paid to agents as carriers battle it out for market share, resulting in shrinking margins. "Given the shift in profitability to distribution, the carriers that will be better off will try to regain some control over distribution,” Chookaszian says. Admittedly, that is not an easy thing to do. The agent enterprise is part and parcel of most insurance operations. Directly selling insurance to consumers will require insurers to set up their own distribution systems, while still supporting their vast networks of independent or captive agent forces. See also: The Future of P&C Distribution   Distribution Goes Digital When Benjamin Franklin started the first successful U.S.-based insurance company in 1752, he was dealing with a localized Philadelphia population, but, by the end of the 18th century, citizens were moving westward, making it necessary for insurers to expand their distribution networks. The Hartford made the first foray into direct distribution by offering insurance through the mail, but few consumers of the time were willing to give up the personal services of an agent when it came to purchasing something as critical as insurance. Carriers of the time faced a similar dilemma as carriers do today: how to acquire customers in a changing marketplace. According to the J.D. Power 2018 US. Insurance Shopping Study, insurers are aggressively courting customers with new options and amenities as auto insurance rates remain stagnant and the number of consumers seeking coverage declines. "We’re entering an era of consumer-centric insurance that will likely be marked by a surge in new digital offerings and serious efforts by insurers to improve the auto insurance shopping experience,” says Tom Super, director of the property and casualty insurance practice at J.D. Power. This shift is happening across all lines of coverage, even small commercial. While citizens on the new 17th-century frontier may have been hesitant to buy coverage without the guidance of an agent, many 21st-century buyers have no such qualms. Nearly half of consumers responding to a survey conducted by Clearsurance said that they would purchase an insurance policy online, while 65% believe this will be the primary channel for purchasing coverage within the next five years. According to research conducted by Accenture, consumers are open to a number of new possibilities when it comes to buying the policies they need: Power in the form of profits may have shifted to distribution, but consumers are making a power play of their own, demanding greater service and amenities and taking their business to the carrier most capable of meeting preferences and price points. In a world of shifting power, creating an active, online distribution channel puts more of the profit back into the carrier’s bottom line and allows it to attract more customers in three distinct ways. Cutting Transaction Costs According to a report from the Geneva Association, the leading international insurance think tank for strategically important insurance and risk management issues, 40% of P&C premiums are absorbed by transaction costs, leading to inflated policy pricing that drives away potential customers. PwC pegs distribution as a heavy culprit, reporting that 30% of the cost of an insurance product is eaten up in distribution. On the other hand, Bain predicts that insurers could cut the cost of acquisition by as much as 43% through digitalization. Underwriting expenses could drop as much as 53%. Reducing these costs allows insurers to present a more attractively priced product to consumers, an important consideration given that 50% of customers base their loyalty with an insurer on price. To understand how costs are reduced through digital distribution, it helps to understand how a leading digital distribution platform works to raise efficiency. According to PwC, up to 80% of the underwriting process can be consumed by administrative tasks that require manual workarounds, such as re-entering information into multiple systems. Much of this re-inputting of data is due to the siloed nature of insurers’ administration systems. Digital distribution platforms create a layer between the front-end online storefront, where customers enter application data, and the back-end systems used to store information. As consumers enter their personal details into the online application, all back-end systems are populated automatically, eliminating the need for manual work-arounds. Everyone across the organization has the same view of the customer and access to any information that has been provided. Digital platforms are also masters of straight-through processing, automating the quote-to-issue lifecycle and reducing the need for manual underwriting. By automatically quoting, binding and issuing routine policies, insurers reduce costs and also provide a more “informed basis for pricing and loss evaluation,” according to PwC. As costs drop, insurers are also able to more competitively price insurance coverage. Lower prices win more customers allowing insurers to take back some of the profitability of distribution. Improving Customer Experiences When it comes to insurer-insured relationships, there is a gap between what consumers want and what insurers provide. Consumers rate the following points as very important aspects of the insurance buying experience:
  • Clear and easy information on policies
  • Access to information whenever it is needed
  • Ability to compare rates and switch plans
  • A wide range of services
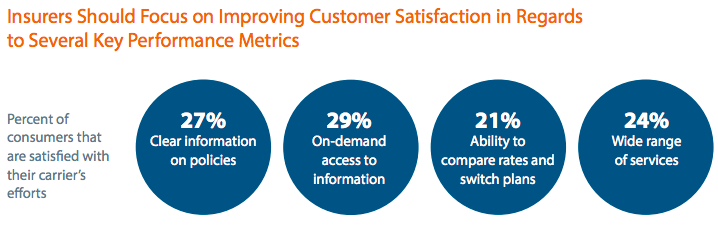
But few consumers agree their insurer is meeting these expectations: 27% see clear and easy information on policies 29% report access to information whenever they need it 21% say there is the ability to compare rates and switch plans 24% see a wide range of services The customer experience is becoming a key differentiator across the insurance industry. McKinsey reports two to four times higher growth and 30% higher profitability for insurers that provide best-in-class customer service, but here’s the rub. Only the top quartile of carriers fall into this category. Becoming a customer experience leader requires insurers to understand that the separate functions associated with policy sales and distribution appear as a single journey to consumers. They expect to quote, bind and issue multiple policies through a single application, using as many channels as they feel necessary to get the job done. While 80% of consumers touch a digital channel at least once during an insurance transaction, 45% of auto insurance shoppers use multiple channels when making a purchase. They expect to be recognized across these channels, picking up in one where they left off in another. The multiple back-end systems employed by most insurers present a strategic dilemma here, as well as in the area of cost containment. Without transparency between channels, consumers are forced to restart a transaction every time they change their engagement method. “It amounts to a great deal of frustration for the consumer,” says Tom Hammond, president U.S. operations, BOLT. “You start an application online and then call the customer-facing call center, and they can’t see what you did through the online storefront.” Hammond explains that digital distribution needs to be omni-channel distribution, seamlessly integrated with a single view of the customer. It’s the only way to meet consumer experience expectations now and into the future. Thanks to advances in analytics and artificial intelligence, the amount of data that is available to carriers has grown significantly, and consumers expect that information to be leveraged for their benefit. Eighty percent of consumers want personalized offers and pricing from their insurers. Progressive is one of the 22% of carriers currently making strides to offer personalized, real-time digital services, having recently released HomeQuote Explorer. From an app or computer, consumers can enter information once and receive side-by-side comparisons from multiple homeowners insurance providers. According to the company, they leverage a network of home insurers to make sure customers can find the coverage they need at a comfortable price. Oliver Lauer, head of architecture/head of IT innovation at Zurich, believes these collaborative networks are an integral part of the digital future of insurance. “Digital innovation means you have to develop your insurance company to an open and digitally enabled platform that can interface with everybody every time in real time – from customers to brokers, to other insurers, but also to fintechs and insurtechs,” Lauer says. Using a digitally enabled market network, insurers can fill product gaps and even meet customer needs when they don’t have an appetite for the risk. The premise is simple. By offering coverage from other insurers, they maintain the customer relationship and reap the rewards of loyalty. As society changes and consumer needs evolve, the ability to personalize bundled coverage to the needs of the individual will become increasingly important. Consumers are now looking for coverage to mitigate risk in previously unheard-of areas, such as cyber security, identity theft and even activities related to legalized marijuana. When an insurer is unable to provide the coverage a customer needs, it risks forfeiting that relationship, and any other policies bundled with it, to another carrier. But when the carrier takes part in a market network, it can bundle the appropriate coverage from another insurer with its own products, personalizing the coverage to better fit the needs of the customer. See also: Key Strategic Initiatives in P&C   Digital platforms offering market networks also set the stage for insurers to offer ancillary services, such as roadside assistance, that make their insurance products more attractive to consumers. We see this happening with increasing frequency as carriers seek to improve the customer experience and lift their acquisition efforts. DMC Insurance, a provider of commercial transportation insurance solutions, recently announced a partnership with BlackBerry Radar. The venture would provide transportation companies with real-time data on vehicle location, as well as cargo-related information, such as temperature, humidity, door status and load state. Information like this will help companies better manage risk. In the personal lines market, insurers are partnering to offer services that enhance the life of their customers. Allstate’s partnership with OpenBay allows consumers to review repair shops and schedule an appointment from an app. Allianz is helping home owners safeguard properties by partnering with Panasonic on sensors that monitor home functions and report issues. Customers can even schedule repairs through the service. Digital Distribution Benefits All J.D. Power reveals that digital insurers are winning the intense battle for market share in the insurance industry, starting a shift that could help level the profitability field between distributors and carriers. In a recent insurance shopper survey, overall satisfaction was six points higher for digital insurers over those that sell through independent agents. This lead grows to 12 points when compared with carriers with exclusive agents. According to research by IDC, digital succeeds on the strength of its data. The ability to collect and analyze the vast stores of data available through these interactions, including such variables as the time of day the consumer shopped for coverage, the channel the consumer used, and stores of information collected from third-parties as part of the automated application process, provides the key to improved customer service. “By analyzing this data, insurers can understand each customer’s lifestyle, behaviors and preferences in order to engage with them at the right time and place, offer personalized service and offers and more,” says Andy Hirst, vice president of banking solutions, SAP Banking Industry Business Unit. As insurers create omni-channel engagement, they’re strengthening distribution from every angle, giving consumers the option to quote coverage online when it’s most convenient for them, and then buy it right then and there or to seamlessly call an agent to discuss their options and their risk. Customer experience is rapidly becoming the foundation of success in the industry, and digital distribution provides the first link in building that base of core customer satisfaction. By providing consumers with multiple channels of engagement and the ability to meet more of their needs at any time, day or night, carriers are taking back the lead on profitability.

Tom Hammond

Profile picture for user TomHammond

Tom Hammond

Tom Hammond is the chief strategy officer at Confie. He was previously the president of U.S. operations at Bolt Solutions. 

How Work Culture Affects Claims Process

Even beyond the impact culture has on talent acquisition and retention, it can drive better risk management and customer service.

Workplace culture has been a hot business topic for some time, and interest shows no signs of abating. We’ve all heard about some of the “coolest” companies that tout their culture as a true differentiator. For example, tech giants Google and Facebook have been longstanding advocates for a strong company culture and as a result are leading examples of enviable places to work. Others such as billionaire investor Ray Dalio’s firm Bridgewater have embraced a very different version of culture – in his case one focused on “radical transparency” – and have seen similar success. No matter the approach, what these and other forward-thinking companies share is a passion and commitment to a strong workplace culture and its impact on their overall success. Culture has been at the forefront for me since the early days of forming my claims management consulting firm. Over the past 16 years it’s been a top priority as we’ve grown our workforce, and aimed to attract and retain the best talent in the business. As a small business, we see the impact of a strong culture even more. What we’ve honed has helped us not just in forming our identity but also with creating a set of values that drive how we interact with our customers. However, in working with many claim operations over the years, we’ve seen how many are still late to the party when it comes to prioritizing workplace culture. While some are scratching at the surface with remote work opportunities and agile work environments, few have fully embraced culture as an unquestionable tenet. Even beyond the impact it has on talent acquisition and retention, we think it can also serve as a driver for better risk management and customer service results. Workplace Culture – Do We Know It When We See It? As much as we may think we know about workplace culture, maybe we should step back and try to define it. If you Google this term as I did, you might get 10,000 or more results. While there’s no shortage of research on the topic, there are some common themes that are key to building a solid foundation. Shared Purpose Employees like to know that they are doing meaningful work and feel connected to their employer’s reason for being in business. Sharing a common set of values with their employer and understanding how their unique skills fit into the bigger picture are important to employees seeking meaning from their work. Identifying with a greater purpose is often tied closely to feeling successful, which is also highly motivational. Employee Recognition Employees often fail to meet their full potential if their contributions are not regularly appreciated. Employers who take the time to acknowledge good work see increased loyalty among their employees and even improved job performance. In fact, it’s so important that according to social scientist Dan Ariely, whose research covers the drivers of motivation, “When we are acknowledged for our work, we are willing to work harder for less pay.” The challenge for employers is finding the right way to show appreciation, especially since everyone responds differently to varying types of acknowledgement. Workplace Diversity Beyond expanding the talent pool, companies focused on diversity see improved employee performance. With a broad range of life and work experiences reflected, decision making by a diverse group produces better results. A culture that recognizes this and commits to it can truly be more successful. Work Environment Environment is one of the most important aspects of culture. In recent years the focus has been on an open environment to improve collaboration and productivity. In fact, about 70% of U.S. companies now have some type of open floor plan. In addition, flexible schedules have also become more common, as has remote work. Companies that focus on flexibility and the environment in which we work see a more productive and engaged workforce as a result. Personal and Technical Development Employees embrace opportunities to contribute, learn, experiment, and to develop new skills. They want to know they have a clear path to growth within their company, which ensures a strong future. According to Gallup, only four in 10 U.S. employees strongly agree they had opportunities in the last year that allowed them to learn and grow. This clearly needs to be more of a focus for employers as they compete for talent, especially among younger generations. Transparent Communication Fostering a great work culture depends on open and honest communication. Communicating with employees consistently and directly leads to improved levels of trust in their employer. Companies must commit to this as a practice from the highest level throughout the entire organization for it to impact the culture. While the above isn’t by any means comprehensive, it touches on many aspects of a strong workplace culture. When it comes to the insurance industry, and specifically claims operations, we’ve observed over the years where they are committing resources to building a strong culture, and whether it’s been paying off in terms of business results. In fact we recently conducted an informal poll of Disability and Life insurance claims professionals to hear more about trends in their workplaces. For example, several told us that they have flexibility in their schedules and work location, and a majority reported working in an open, “collaborative” office environment. When asked whether they believe these factors impact productivity, more felt flex schedules contributed than work environment. For claim professionals this flexibility to when they work may be even more critical given the level of intensity and burnout that can happen in this field. See also: How IoT May Revolutionize Claims   Looking at additional factors, having consistent and open communication from management was most influential to their level of satisfaction. An engaged team can only serve insurers well as it means commitment to the work and loyalty to the company. If we revisit these themes again from the perspective of claims management, here’s what we believe are the most significant ways culture can have an impact: Shared Purpose For claim analysts, it can be extremely challenging to keep in mind the greater purpose – deadlines and complicated case details can easily supersede that. Are team leaders reminding them of the meaningful work they do? Does the company frequently and publicly cite examples of how customer lives are impacted by the great work that the claim team is doing? In reality, the focus for many is on impersonal metrics built from the command and control environment. While we need hard numbers to gauge productivity, the story of what’s being achieved and why it matters is also important. Employee Recognition Taking time to acknowledge those claims that were particularly well handled and acknowledging the analyst’s efforts is important. Sharing this with others on the team can then serve to motivate them, causing a ripple effect. A team that sees their value is recognized is simply going to focus on delivering their personal best. Workplace Diversity While we often think of race and gender as key aspects of a diverse workforce, what about age? Like the rest of the insurance industry, the graying of the workforce is something to address. Finding ways to attract younger workers and from more diverse backgrounds is necessary to creating a stronger claims operation in the long run. How often do you encounter a Millennial who has figured out how to do something much more efficiently? This “life hack” generation has a lot to offer us in terms of openness to learning new technologies and improving our processes. Likewise, older generations have much to offer in experience and wisdom. Baby Boomers for example are remaining in the workforce longer by delaying retirement, allowing for more opportunities to mentor and collaborate with younger counterparts. Work Environment We all have the co-worker who just can’t dial down the volume meter. Or the colleague who insists on talking to themselves for all to hear. Working in an open environment can make these issues even worse, and for those working on complex claim reviews it can be downright counterproductive. While there are benefits to a collaborative space, claim analysts can be challenged to read and analyze detailed documentation, or have sensitive phone conversations in these environments. Creating a space tailored for critical thinking and quiet is important. Even better, allowing them the flexibility to work from home or set their own hours can encourage productivity and efficiency, and greater job satisfaction overall. Personal and Technical Development There are many organizations that likely have a focus on technical development for their claims teams. However, rounding out this training to include softer skills like communication and empathy for example can also be just as valuable to their ongoing success. After all, what good is it to be able to follow all processes and remain compliant if they can’t effectively communicate with claimants and make key connections? Offering a well-rounded training program that encourages these additional skills can only serve to enhance job performance and satisfaction for analysts. Transparent Communication One of the key components of any engaged workforce is feeling connected with management. When we recently polled claims professionals about several key factors related to their productivity, the level of communication was the item most often given the highest ranking for level of influence. Being consistent and clear in communications is needed with any profession, but especially in occupations like claims where analysts are working independently, and now more often remotely. See also: Getting Culture Right: It Starts at the Top   In Summary Workplace culture is more than just a buzz phrase – there are legitimate and quantifiable reasons a company should prioritize it. For those working in the insurance industry, there are unique challenges to fostering a winning culture - attracting younger workers, keeping up with and leveraging new technologies, and promoting a sense of purpose for their employees to name a few. For those on the front line with claims management, the more engaged and productive they can be, the better the results for not just insurers but their customers.

5 Key Business Lessons From GDPR

GDPR may have (just) been about data, and its protection. But it teaches us all to be visionary, agile, adaptive, trustworthy and pragmatic.

With so much focus on the detail of GDPR, let’s take some time to look at the business lessons from this external change. Whatever the size of your business, the world around you changes, and you need to be able to adapt. Regulation is just one of those key drivers of external change. So, to help us reflect on the business lessons from preparing for GDPR, I’m delighted to welcome back guest blogger William Buist. William mentors and advises business leaders, helping them get greater clarity. So, he is well-placed to lead us through this business-focused review. Over to William to draw out those lessons… Business lessons from GDPR readiness, or not GDPR was on the back-burner, for many businesses, for sometime. At least until recently. But, in the last few weeks, we have seen our in-boxes bulging, with businesses seeking to obtain the approval  they need for their marketing lists. It’s been interesting to watch the different ways in which businesses have approached this. It’s the same set of instructions and requirements from the Information Commissioners Office (ICO). They are not all compliant, but many are. Most lack subtlety, almost all miss some aspects of the reason these regulations are being developed. That’s a symptom of confusion, and it is absolutely normal. I’m not going to rehash the detail of the GDPR (we’ve all had enough of that by now!) I thought it would be interesting to consider what the general learning is, about external change. Learning that businesses can draw from the exercise of becoming compliant with the GDPR. I think there are five key lessons. 1. However early you start, it’s probably too late to do a perfect job Almost by definition, external change pops up only when it’s easy to spot. People are talking about it, and you wonder why you hadn’t heard. By the time you catch up with what is happening, the deadlines seem close. The best thing to do, is to keep your ear to the ground. Your network is probably whispering, about a couple of things, that will affect you in 2019 or 2020 already. If you can spot which ones you need to take action about now, you can be ready and relaxed. (Hint: if you use associates or contractors, take a look at upcoming IR35 changes). Be visionary. See also: What GDPR Means for Insurance Companies   2. You are aiming for a moving target Most external changes, like GDPR, are evolving. They continue to evolve for some time, after the ‘deadlines’, as working practices embed & difficulties are ironed-out. Businesses that thrive, look for the intention behind the change, and think strategically, about how to deliver that intention. Rather than thinking tactically, about the current need. Spend time identifying what your relationship, with the intention of the change will be. How you will express it, embrace it, and champion it? Be agile. 3. There are no experts about the impact on your business, and there may be no experts at all External changes aren’t driven with your business in mind. Nobody has enough experience to be an expert. They are just more, or less, knowledgeable than you are about this change; but always less knowledgeable about your business. Check what other say, seek evidence. One example: “privacy policy” is not mentioned in either of the relevant legal frameworks. Neither the Data Protection Bill, nor the GDPR regulations. Now, I’m of the opinion that a privacy policy/notice may be a sensible way to evidence your policy and processes. But it will not, and cannot, of itself, make you compliant. Rather than experts in the thing that is changing, seek out the experts in the work that you need to do. Hire the best implementors and strategists, before your competitors do. Be adaptive. 4. In the long-term, you will wonder how you managed today External change, that affects all businesses (like the introduction of email, or GDPR) can seem like an imposition. Something to be resisted, but ultimately, advantageous. It’s hard to imagine doing business, with a typing pool and snail mail, yet for many years that was the best we had. GDPR will change the way that businesses do their marketing. The better targeting and stronger trust(*), that will arise in the long-term, will seem like a norm that will make today feel antiquated, even ‘quaint’. (*) The P in GDPR is important. Protecting the data of the people you work with, using it responsibly, and sensibly (and being seen to do so) is how trust develops & thrives. That will take time, and it has to be authentic. Be trustworthy. 5. Just because you can’t see the opportunities, doesn’t mean they aren’t there The world will be different, after all that’s what significant change does. In a different world, opportunities are also different, and far less visible, at least until you ‘get your eye in‘. The best businesses scan the horizon, for things that they can use today, to deliver a better business tomorrow (than it was yesterday). It’s worth spending strategic time, to identify what opportunities might exist, in this new world, and how they might be made visible. The best do this habitually. Habits form from regularity. By making these things conscious, you make it more likely you can see the opportunities, than less. Be pragmatic. GDPR may have (just) been about data, and its protection. But it teaches us all to be visionary, agile, adaptive, trustworthy and pragmatic. See also: How to Avoid Being Bit by GDPR (Part 1)    

Paul Laughlin

Profile picture for user PaulLaughlin

Paul Laughlin

Paul Laughlin is the founder of Laughlin Consultancy, which helps companies generate sustainable value from their customer insight. This includes growing their bottom line, improving customer retention and demonstrating to regulators that they treat customers fairly.

7 Things I Learned at Bold Penguin

After years of being an opinionated outsider, the author's first week as CMO has been an eye-opener about what insurtech is really about.

This is my first week at Bold Penguin... marking the true beginning of my insurtech life. I've followed insurtech for more than three years, writing and speaking on the movement, but my vantage point has always been one of the intrigued outside observer. And while one week does not make you a qualified insurance technology startup guru, here are my first seven insights after diving headfirst into my new role as chief marketing officer at Bold Penguin.

1) Small Business Insurance Is the Holy Grail McKinsey & Company has been referring to the SMB market as one of the "few bright spots" in the property/casualty insurance sector for years now. Why? Because no one owns the small business insurance space. The marketplace is fragmented, and generally speaking the commonly accepted customer experience is poor at best. Yet, done right, small business insurance is a growing and profitable market segment. This is by no means breaking news. That doesn't diminish the fact that no one has small business insurance figured out, (except maybe...), making the SMB market the holy grail of meaningful organic growth for the foreseeable future.

2) There Is No Road Map In case you've never worked for a startup before, there is no road map for success. Insurtech startups are creating solutions that haven't existed before. Look at the work that Chris Cheatham is doing in policy automation at RiskGenius or Mike Albert and Allan Egbert are doing in open APIs at AskKodiak. Quite literally, they're making things up as they go along. ...because they have to. The work lives in uncharted waters. My point is, just as insurtech startups must mature into the greater insurance ecosystem that has existed for more than 400 years, the more traditionally oriented organizations (and individuals) must accept the slightly more haphazard nature of startup companies. Insurance carriers with open-mindedness to the realities of trailblazing startups will position themselves out front as the partners of choice for insurtechs mapping solutions for our industry's most challenging obstacles.

See also: An Insurtech Reality Check  

3) There Is a Race to Remove Friction Research from a McKinsey & Company survey shows a 73% increase in customer satisfaction when customers reported they were pleased with the entire customer journey, not just specific touch points.

Winners and losers of the digital insurance revolution will be determined in the race to remove the most friction from the customer experience.

This doesn't mean removing human agents or blowing up the traditional insurance carrier model. Rather, we must think of insurance as a service and create flow throughout the customer journey. I joined Bold Penguin because it's my belief that their solution will be the foundation upon which many winning agents, brokers and carriers build their unique customer journey. Whether you partner with Bold Penguin or not, make no mistake, the race to remove friction is real and it's happening right now. If your organization is not having serious conversations about the customer journey, you're already losing.

4) It's Time to Ask "What if?" It's time for everyone to start asking "What if?" when it comes to the future of insurance.

  • What if APIs are the future?
  • What if customer experience is all that matters?
  • What if we can't build it ourselves?
  • What if half our agency plant retires in the next five years?
  • What if our carrier partners demand digitization?

Whether you believe these scenarios will come true or not isn't the point. The insurance marketplace is changing rapidly and being prepared for all the "What if?" scenarios possible is the only way to survive... ...because no knows what's actually going to happen.

5) Disruption Is Dead From now on, every time you hear the words "disruption" or "disruptor" come out of a startup's mouth, your insurtech B.S. alarm should leap to life, the blaring sirens and seizure-inducing flashing lights overwhelming your senses while an impenetrable B.S. Protection Barrier envelops your entire body like some scifi force field. Seriously though, disruption is not the answer. Instead, insurtechs should focus on collaboration, facilitation and integration with traditional partners, building on the previous foundation as much as possible and alongside where it does not.

6) Culture, Culture, Culture I've seen first-hand the impact a toxic culture can have on organizational success. We live in a tumultuous time for workplace culture. According to the American Psychology Association, the workplace continues to be a leading cause of stress (with 61% of Americans listing work as a significant stress factor). We're under more pressure to spend more time, to get more done every single day. Work-life balance has become a cliche joke. While I believe in hard work, giving more of yourself than is asked in the job description and just kicking ass in general, organizational culture must be a fit to achieve our goals of world domination. Here are three aspects of insurtech culture vital to success:

  1. Always put staff satisfaction first. An inspired team believes, an uninspired team blames.
  2. Never blame the customer. Period. Own your outcomes. The customer may not always be right, but the customer is never wrong.
  3. Don't take yourself too seriously. As an old mentor used to tell me, "Everybody ?s."

I'm sure there are more. But these were the three most obvious to me after spending time at the Bold Penguin headquarters this week.

7) Your Story Matters Your story matters as much as your product. It doesn't matter how amazing, revolutionary or game-changing your product or solution is, if your story doesn't make sense, if people can't connect the dots between your solution and how it benefits them and their organization, your product essentially doesn't exist. This is something we need to do better at Bold Penguin. We're not amazing at telling our story today. We're going to change that. One of many reasons I joined Bold Penguin was that the whole story had yet to be told. I feel like I've found a gigantic diamond just lying there on the sidewalk. And while everyone else walks past, oblivious to the treasure they've just nonchalantly stepped over, to the trained eye all it takes is a craftsman-like approach to telling the story of what Bold Penguin can do for insurance agents, brokers and carriers to unlock industry defining value.

But Bold Penguin isn't alone. Wait until you hear about what Joseph D'Souza is doing at ProNavigator, or Jason Keck at Broker Buddha, or Phil Edmundson at Corvus Insurance. Having a great solution is the barrier to entry. For anyone to care about your company, you must to be able to tell your story.

See also: Innovation: ‘Where Do We Start?’  

The Rub According to the most recent CIAB Market Study, "Driving organic growth, hiring and recruiting talent and enhancing the customer experience remain top organizational priorities" for the U.S.'s top insurance brokerages. With 80% of CIAB's responding agents and brokers listing “driving organic growth” as a top priority for 2018, it's exciting to be part of a company working to solve organic growth concerns, not through disruption but through collaboration, facilitation and integration.

You can find the article originally published here on LinkedIn. Click here to learn more about Bold Penguin.

Awareness: The Best Insurance Policy

Insurers should support organizations whose mission is to save lives by teaching life-saving techniques. Be champions of change.

Awareness is the best insurance policy. It saves costs by saving lives. It is as important to the fate of the insurance industry as it is to fate of the entire nation. The awareness I refer to comes from recognizing the risks we face and the ways we can solve them, starting with the one thing that is both portable and invaluable: education. The more educated a person is, in terms of his or her ability to perform a life-saving procedure such as CPR, the safer everyone will be. Put another way, the education of one translates into economic rewards for many—from fewer hospitalizations and lower medical fees to more affordable health insurance and better options in general. Or: Sometimes, the most practical skills are the most profitable. CPR is such a skill, which not only save lives but strengthens communities. For those communities most in need of help, where first responders are too far away to be the first ones on the scene, the person who knows CPR is the man or woman who can save a life. Compare that scenario with the alternative, where an ambulance belatedly arrives and the patient hovers between life and death. Picture that patient in a hospital, unable to breathe without a ventilator and unresponsive to the simplest gestures. Whether that patient is rich or poor is no matter, not when the richness of life itself vanishes and medical bills are a matter for insurers to pay or to decline to cover altogether. If insurers want to avoid that scenario, they should invest in what works. They should support organizations whose mission is to save lives by teaching life-saving techniques. See also: A Road Map for Health Insurance   According to Mackenzie Thompson of National Health Care Provider Solutions (NHCPS): “Interest in learning how to perform CPR is a global initiative. From Africa to the Americas, every village or township needs to be empowered with life-saving knowledge. In fact, more people from the U.S. access our online certification courses on CPR than any other nation. If saving lives saves insurers money, all the better.” I agree with that statement, as it is neither too complex to achieve nor too controversial to accomplish. In other words, teaching CPR does not involve creating or maintaining huge bureaucracies. It does not involve legislation that divides the public or strains people’s finances. It does not take too much time to practice or too many practitioners to attract supporters. Do not underestimate, also, the power of goodwill. Which is to say the insurance industry has everything to gain—and nothing to lose—by popularizing what is good for its beneficiaries and a benefit to itself: life. The healthier people are, the less costly it is (or should be) to insure them. The happier they will then be, too, because they are alive and well. If insurers want to see the ROI on CPR, they should look to the individuals who owe their lives to this procedure. They should look to promote CPR in every county, city and state. They should look at themselves as champions of change.

Workplace Violence: Assessment, Response

With a deeper understanding, organizations can significantly reduce incidents against their workers.

Workplace violence is a daily threat to workers in many industries. Aside from mass shootings, which grab headlines, more than 2 million workers are victims of violence every year. The issue is a challenge for employers striving to maintain a safe working environment for their employees. By understanding the scope of the problem, the underlying reasons for violence and the types of violence that threaten specific industries and workplaces, organizations can make a significant impact on reducing incidents against their workers. During a recent “Out Front Ideas with Kimberly and Mark” webinar, we had two prominent experts join us to discuss this very challenging issue:
  • Bub Durand, practice leader of medical group support services for Kaiser Permanente’s Northern California region
  • George Vergolias, PsyD, vice president and medical director for R3 Continuum
Scope of the Problem OSHA defines violence as any act or threat of physical violence, harassment, intimidation or other threatening disruptive behavior that occurs at the work site. That includes everything from threats and verbal abuse to physical assaults and even homicide. Many employers, however, are wary of even discussing the issue out of concern that people will view their particular companies as being overly violent. In fact, several potential speakers in retail and other industries we approached to join our panel declined for this very reason. Despite their reluctance, we know that the workplace has increasingly become the site of violence, especially in certain industries. Healthcare Healthcare is the industry that generates more attention than any other with regard to violence – and with good reason. The most recent government statistics show there are 7.8 cases of serious violence per 10,000 employees, which far exceeds any other industry, and that number is likely much lower than the reality. Many healthcare facilities, especially in high-risk areas such as emergency departments and Level I trauma centers, are routinely the sites of violent outbursts. Patients or their families attack providers all too frequently. Many of these workers have come to believe violence is just part of the job. Unfortunately, those in a position to change this often foster that culture. We may soon see an increase in the numbers of incidents reported, due to mandates for increased reporting, especially in California. Schools Mass shootings at schools have been getting lots of attention. However, not talked about is the fact that schools are increasingly the site of daily violence or threats by students against teachers and staff. For example, one of the nation’s largest school districts reported a 10% increase in violence-related claims in the past five years. With incurred losses of $19 million, these claims represented 15% of the total and 12% of the system’s incurred losses. The numbers do not include many of the threats and harassment incidents, which often go unreported. One reason for the increased number of violent incidents reported in schools may be the increased awareness of the issue and the potential for remedies, both legal and administrative. Another is the implementation of zero-tolerance policies that require or strongly recommend reporting. One more is the increase in kids acting on their emotions, more so than they did in past years. Overall, workplaces have seen an uptick in homicide rates in recent years, even though the rate in the general population has decreased. Some experts speculate that may be due to increased stresses facing workers, such as financial pressures. Social media may play a role in increased violence in the workplace, because it seems to empower some people to act in ways they normally would not. This sometimes spills over into real-world, face-to-face situations. On a positive note, efforts to reduce violence in the workplace are paying off. While homicides among government employees increased 30% between 2003 and 2013, the rate decreased 30% in the private sector. See also: Broader Approach to Workplace Violence   Types of Violence Developing violence-prevention programs requires knowing the type(s) of violence to determine the best approach. For example, gender may be part of the equation. Men are more likely to be killed at work during robberies, especially in retail establishments, while women are more likely to be victims of domestic violence. Domestic violence is one category that is often not adequately addressed in the workplace. Many employers believe that, because the potential perpetrator is not an employee, he is not a threat to the workplace. Statistically, it is a very real problem that should be considered and included in violence prevention plans. In fact, violence can be initiated internally or externally. It may be started by an employee within the company, or externally by a customer, former employee, vendor or someone connected with an employee. There are also emotional vs. predatory incidents of violence. Knowing what drives each incident category is important to help prevent it.
  • Emotional violence generally occurs as a reaction to a threat or fear. An example would be two boys ready to duke it out in school. Neither actually wants to fight, but they also do not want to be humiliated, so they pretend they are ready. Diffusing this situation can be done by intervening and stopping both of them equally.
  • Predatory violence involves forethought, rather than being reactionary. A sniper is an example of predatory violence. Preventing these situations is much more complex.
Temporary States vs. Emotional Traits Some attacks occur because the person is temporarily in a highly emotional state. It could be an emotional reaction, a psychotic episode or a drug-induced state. A permanent trait, on the other hand, means the person has a personality factor that is driving him to act in a demeaning or abusive manner. Those traits are more consistent and predictable over time. An example of someone in a temporary state would be a father who has just been told his wife was killed and his child is in surgery following an auto accident, and he speaks very little English. His inability to fully communicate, and his efforts to see his son in the emergency room, could easily lead to a violent outburst. Security personnel might be inclined to handcuff the man, per protocol. However, such a situation can be diffused by understanding why he is acting the way he is and getting a language interpreter to speak with him calmly. It is important to understand the context of the violence and not assign permanent traits to someone who is only in a temporary state. That can sometimes be tricky, especially if a zero-tolerance policy is in effect and mandates that security personnel handcuff any violent perpetrator. If someone is acting out in hostility, especially if it is atypical behavior for that person, asking questions can help prevent an incident. This can be especially effective in the case of students at school; pulling the person aside to find out what is driving his actions is often effective. Assessing the Risk There are many ways to determine the types and levels of risk to an organization.
  • Traditional assessment. One approach includes a traditional security risk assessment of the grounds, the physical security environment and the security practices and policies, using specific metrics and historical performance of law enforcement and risks in the local community as factors.
  • High-risk area assessment. As Bob explained, a new California law addressing workplace violence in healthcare has led Kaiser Permanente to conduct additional assessments of its facilities. One involves looking at high-risk areas, such as emergency rooms. The type of risks present there could include family members worried about patients who have been brought in, or patients left waiting because their injuries are not life-threatening, and they become impatient and agitated. These assessments look at the safety and physical security practices along with engineering controls.
  • Administrative and workplace controls. These focus on ways to distinguish employees from visitors. Kaiser Permanente, for example, requires workers to wear ID security badges from the waist up.
  • Employees’ knowledge. Part of assessing risk is to determine whether staff members know what to do at the first sign of a threat; do they know the security code to call, and what to expect as a response? Employees also are assessed to make sure they understand they may sometimes have to call in outside law enforcement and must know how to do that.
  • Physical layouts. A patient who presents a danger to himself and is brought in involuntarily needs to be placed in a safe room. The assessment would look for any dangerous objects in the area the person could use to injure himself. Staff members are quizzed to ensure they understand what needs to be removed from such an area.
  • Remote worker assessment. Many healthcare or hospice workers go to an offsite home or other location. Because the risks are often unknown in those environments, employees need to understand what to do. For example, the worker could ask whether there are any firearms in the home.
It is also important to assess both safety and security because they are different. Security would include a door in a particular location of the facility that serves as an exit, that visitors cannot enter. However, a worker who props the door open, even briefly, defeats the purpose. Employers need to promote a culture of safety within their organizations, as well enhancing security. See also: New Idea for Active Shooter Incidents   Training The best workplace violence policies mean nothing if people are not trained on them. Employees need to clearly understand what to do in a given situation. Training should be conducted at least annually and with any new hires, and employees should be given competence testing regularly. Staff members need to be clear on the expectations of security personnel or they increase their own risk of becoming victims of violence. Proper training also improves legal defensibility. An important point to emphasize in training is to examine the threats to each particular work site and each specific area of a work site. While the same policy may apply, there may be different priorities depending on the risks and the employees. A one-size-fits-all approach should be avoided. It is also important for the trainer to understand what the policy says before starting the training. A zero-tolerance policy is different from others. Unfortunately, some companies seek training before a policy is fully developed. In addition to training staff on policies, management must adhere to it. Otherwise, they risk creating a toxic work environment if someone reports a concern that is ignored. The trainer needs an adequate amount of time to perform effective training. It is imperative to make sure employees fully understand the policies and procedures. Threat Responses There are a variety of ways for employees to mitigate violent threats in the workplace:
  • Be aware. Being aware of the surroundings, how the worker is feeling and how the other person is feeling is important. The other person is likely feeling agitated, so the worker must be able to stay composed.
  • Understand/do not judge. Where possible, engaging the person can prevent a violent incident. Workers can try to find something they like or have in common with the person.
  • Explain the consequences and alternatives. Angry people are not thinking clearly. Nor are they thinking about how actions will affect their lives or families. Calmly explaining the ramifications can help.
  • Change the tone of voice. Speaking calmly to an agitated person may help reduce his anxiety.
  • Avoid provoking. Telling the person to “just calm down” could make him more angry.
The goal is to help redirect the person so he slows down and begins to think more clearly.

Kimberly George

Profile picture for user KimberlyGeorge

Kimberly George

Kimberly George is a senior vice president, senior healthcare adviser at Sedgwick. She will explore and work to improve Sedgwick’s understanding of how healthcare reform affects its business models and product and service offerings.

Long-Awaited Ruling in King v. CompPartners

The California Supreme Court ruled in favor of a utilization review (UR) physician accused of malpractice.

The long-awaited decision by the California Supreme Court in King v. CompPartners (2018) S232197 is finally out. In it, the court unanimously held, through a majority and two concurring opinions, that a claim for malpractice against a utilization review (UR) physician for injuries arising from a review decision for the treatment of a compensable injury could not be maintained under the workers’ compensation system and is barred by exclusive remedy. The case will be extensively analyzed by all participants in the workers’ compensation system. This will include parsing of various comments in the two concurring opinions regarding whether the UR process is performing up to expectations. As noted by Associate Justice Goodwin Liu in his concurring opinion, “The legislature may wish to examine whether the existing safeguards provide sufficient incentives for competent and careful utilization review.” The other concurring opinion, by Associate Justice Mariano-Florentino Cuéllar, stated, “Even now, those safeguards and remedies may not be set at optimal levels, and the legislature may find it makes sense to change them.” It is difficult to find a point in time where a thorough analysis of the system is contemporaneous with the judicial review of it. Such is the case here. The utilization review events that caused this case to be brought occurred in 2013. Given that this case was dealing with a review of prescription drugs, it is important to note that “safeguards and remedies” now include the Medical Treatment Utilization Schedule Formulary. As stated in the formulary, “ For injuries occurring prior to Jan. 1, 2018, the MTUS Drug Formulary should be phased in to ensure that injured workers who are receiving drug treatment are not harmed by an abrupt change to the course of treatment. The physician is responsible for requesting a medically appropriate and safe course of treatment for the injured worker in accordance with the MTUS, which may include use of a non-exempt drug or unlisted drug, where that is necessary for the injured worker’s condition or necessary for safe weaning, tapering or transition to a different drug.” [8 CCR 9792.27.3(b)(1)] See also: Where the Oklahoma Court Went Wrong   This particular regulation also states, “Previously approved drug treatment shall not be terminated or denied except as may be allowed by the MTUS and in accordance with applicable utilization review and independent medical review regulations.” [8 CCR 9792.27.3(b)(4)] In addition, Senate Bill 1160 (Mendoza) requires UR processes to be accredited by July 1, 2018. The accrediting agency is URAC, although the Division of Workers’ Compensation has the authority to add requirements for certification. The purpose of accreditation is to have an independent, nonprofit entity “…certify that the utilization review process meets specified criteria, including, but not limited to, timeliness in issuing a utilization review decision, the scope of medical material used in issuing a utilization review decision, peer-to-peer consultation, internal appeal procedure and requiring a policy preventing financial incentives to doctors and other providers based on the utilization review decision.” [Labor Code Sec. 4610(g)(4)] Much has happened to the system that was under review by the court in King. To improve on this progress, we need to understand what has been done already to provide more safeguards and remedies for injured workers while being faithful to the “grand bargain” that is workers’ compensation. This cannot be done by turning back the clock.

Mark Webb

Profile picture for user MarkWebb

Mark Webb

Mark Webb is owner of Proposition 23 Advisors, a consulting firm specializing in workers’ compensation best practices and governance, risk and compliance (GRC) programs for businesses.

2 Ways to Refocus the Goals of Innovation

sixthings

I'll be quick this week because I'm a bit out of touch and more than a little tired, having spent the past three days driving my younger daughter's household goods from home in Northern California to Washington, DC, where she just started law school and moved into an apartment. (Sunday was the big day—1,250 miles—for those keeping score at home.)

I could tell you a lot about the history of Rome, having spent almost the entire trip listening to a podcast on the subject. Instead, I'll point you to two articles that surfaced last week and that underscore themes that I believe are crucial.

The first article, on "business process elimination" (as opposed to business process outsourcing), reminds me of a line from my old friend and colleague, Gordon Bell, who developed the first minicomputer back in the 1970s. He said that "the most reliable part of a computer is the one you leave out." Peter Drucker stated the principle more generally and famously when he said, "There is nothing so useless as doing efficiently that which should not be done at all."

We in insurance need to keep that principle in mind as we use technology to become more efficient. There are many things we should simply stop doing. No amount of effort should be spent on using fax machines more efficiently, for instance. They, and many other insurance anachronisms, need to just disappear.

The second article is a dramatic story about a drone saving a woman who was drowning 230 feet offshore in Spain. It would have been tough for a lifeguard to fight through the surf and reach her in time—but a drone got there. It dropped a life vest that inflated on impact, and she managed to grab hold and save herself. The drone kept watch on the woman and some friends, who were also struggling, until the lifeguards could get there.

That sort of story is worth keeping an eye on because, while a lot of the focus thus far for drones has been on their use in assessing damage following home fires or natural disasters, drones can also prevent a lot of injuries and deaths. The International Association of Certified Home Inspectors, for instance, reports that 164,000 inspectors fall off ladders just in the U.S. each year, and that 300 die. Imagine how many injuries and deaths can be prevented as drones replace ladders.

Then imagine all the other things that we as an industry can use technology to do if we move our focus past paying people after bad things happen and work to prevent those bad things from ever happening.

Have a great week.

Paul Carroll
Editor-in-Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.