Download

Sleep Apnea's Risk for Younger Women

A cross-disciplinary study using digital health data may have serious implications for mortality from sleep apnea -- and for insurers seeking to underwrite these risks.

Woman sleeping

Do age, gender and other risk factors influence sleep apnea?

Through a cross-disciplinary study, RGA investigators used digital health data (DHD) to reveal previously under-recognized relationships. The discovery may have serious implications for mortality from this common impairment -- and for insurers seeking to underwrite these risks.

Sleep apnea is a chronic condition in which individuals' breathing stops and restarts repeatedly when asleep, preventing the body from getting enough oxygen. The condition has a significant effect on the individual's quality of life, general health and mortality.

Sleep apnea is also on the rise in many developed countries. An estimated 22 to 29 million Americans -- about 12% of the adult population -- suffer from sleep apnea, according to the American Academy of Sleep Medicine. That's up from estimates of 3% to 7% as recently as 2008, yet the American Sleep Apnea Association suggests the condition may be underdiagnosed.

Is it possible clinicians may not recognize the right risk factors? In advertisements and popular culture, after all, the typical sleep apnea sufferer is often portrayed as a middle-aged man. What if that is not the case?

RGA data scientists, actuaries, medical directors and underwriters sought to find out using a unique store of digital health data. RGA has a well-established database containing prescription medication histories, medical billing histories and death information for millions of individuals. This dataset was used to build a multivariate survival risk model, allowing RGA experts to simultaneously analyze and compare multiple risk factors of sleep apnea mortality. Investigators sought to understand if, and how, mortality rates differ between women and men, across different age groups, weight classes and other conditions.

The model uncovered four variables that can most influence sleep apnea risk: age, severity of underlying conditions, gender and body mass index (BMI). We also used an internal tool, Digital Health Data Risk Scoring, to account for the severity of other medical conditions a person might have. Obesity in this analysis was a qualitative indicator if a person has class 3 obesity or worse. After accounting for all those considerations, younger individuals with sleep apnea have the largest risk factor for mortality.

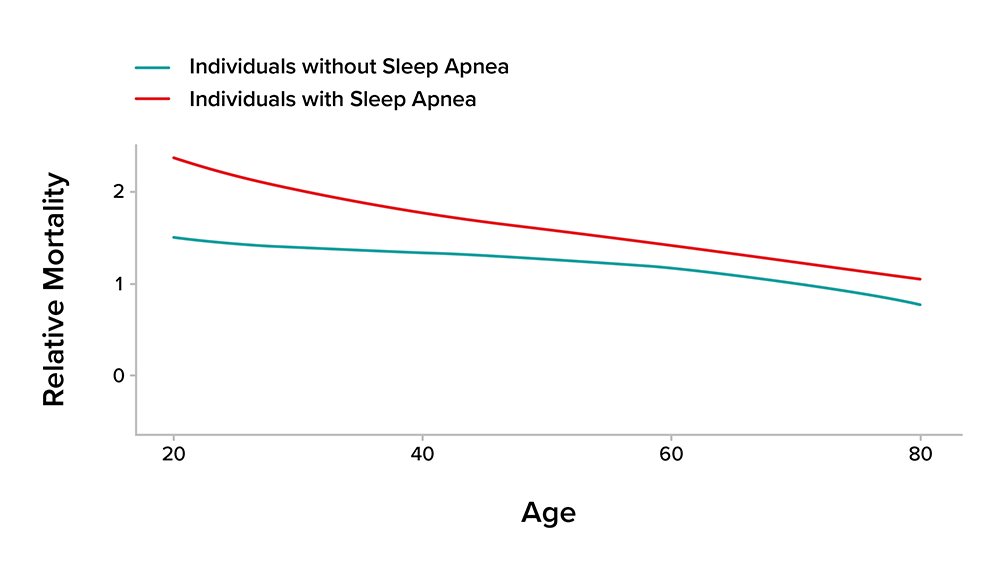
Figure 1: Relative Mortality of Individuals With and Without Sleep Apnea

Relative Mortality of Individuals with and without Sleep Apnea

Note: This graph uses a subset of individuals having higher obesity and a history of using more severe drugs, but graphs using different subsets show a similar pattern with respect to age.

When normalizing for factors (such as obesity or gender), the multivariate survival model in Figure 1 reveals the importance of age as a risk factor in people who have sleep apnea: Relative risk for younger individuals is higher and for older individuals is lower.

See also: Huge Opportunity in Disability Insurance

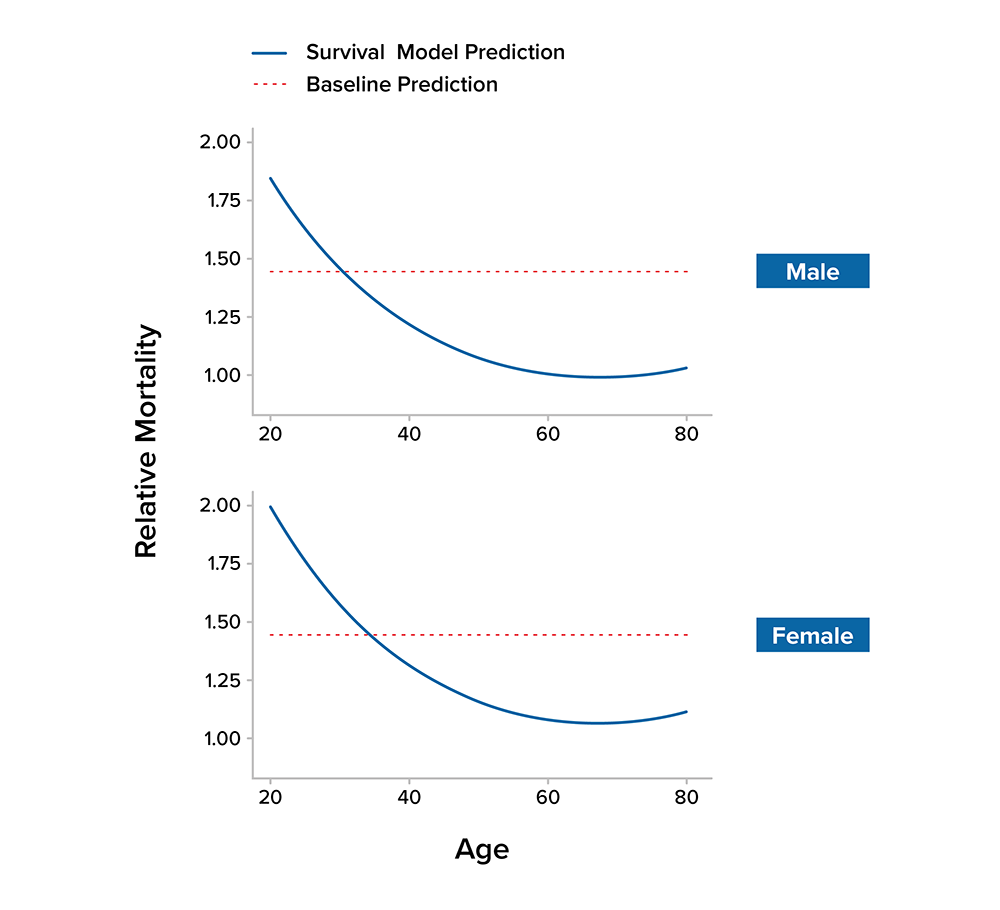
Figure 2: Relative Mortality of Male and Female Individuals with Sleep Apnea
Relative Mortality of Male and Female Individuals with Sleep Apnea

In Figure 2, overall sleep apnea mortality (dotted line) is compared with the survival model prediction among obese males and females with sleep apnea. While gender is a less significant risk factor than age, it is important to note that the relative risk for younger females is higher than for younger males.

Summary

While much of the mortality attributed to sleep apnea is believed to be due to co-morbid conditions, RGA's modeling exercise shows that age is the most significant risk factor. The findings can guide and inform underwriting decisions when assessing individuals with sleep apnea moving forward -- a risk-averse approach is recommended.


Anthony Woods

Profile picture for user AnthonyWoods

Anthony Woods

Anthony Woods is lead data scientist for RGA’s Global Research & Data Analytics (GRDA) team, He leads a group of data scientists in applying statistical and machine learning models for RGA and RGA’s clients. He also leads RGA’s data science effort to develop predictive mortality models using prescription drug history.

He joined RGA in 2015, with 30 years of experience in statistical modeling. His career includes serving as an early member of the data mining department of Enterprise Holdings, where his group applied models to fleet planning, rental demand forecasts, marketing and customer service. Woods has also performed operations research for the U.S. Army and taught in the math department of the University of Missouri.

Woods received his Ph.D. in statistics from Purdue University and is a member of the American Statistical Association and the Institute of Mathematical Statistics.

Consumer Trends Signal Change in P&C

New research shows how COVID has moved insurance from seeing change on the horizon to feeling the impact of customer change in the decision-making process.

Woman carrying boxes

Life is big. Customer choices are complex. When life changes for most of the population, the impact ripples across most industries. Over the past two years, insurance has moved from seeing the effects of change on the horizon to feeling the impact of customer change in the decision-making process. COVID has been a powerful catalyst for change in two areas that deeply affect P&C insurers: housing and transportation.

For instance, population migration is now an insurance concern that affects P&C. According to the U-Haul Growth Index, the top five states for growth due to migration are Texas, Florida, Tennessee, South Carolina and Arizona — all Southern states where job opportunities abound, the cost of living is lower and taxes are, in general, more friendly. Work-from-home and occupational trends have made it easier for people to move. Some insurers struggle in these states, especially in Florida, where risk is high and litigation is common. For those regions, such as California and Illinois, with a population downturn, every move means a loss of premium. Overall housing trends are even more volatile due to rising real estate costs and fewer homes for sale. Property values continue to increase, with the average increase last year at 12% but with some states reporting 15% to 28% increases. Renting is on the rise (see Figure 1), and home-sharing on an online platform is skyrocketing. How will insurers handle the volatility? How will insurance technology help meet the demand for new products and services and better underwriting to drive growth and profitability?

In mobility, the story is different, but the volatility isn’t. Automobile use is down and will not return to pre-pandemic levels any time soon, due to today’s new work-from-home culture. How people live their daily lives has shifted, with more goods and services delivered to their homes, including groceries, take-out, medicine and clothing, resulting in fewer trips. But then, other types of trips may increase, such as camping, going to the park, hiking and road trips. The nature of personal risk for automobiles is changing.

In addition, the automotive sector is facing some real issues that may affect insurers. Chip shortages depleted car inventories, which raised the overall price of both new and used vehicles. Automotive debt is climbing. The loan default rate is expected to climb. The cost of gas and inflation are high. Consumers will be looking for any means to regulate or lower their premiums, including the use of telematic pricing. This fits with what Majesco has found in our proprietary research.

Majesco’s 2022 Consumer Research report, Your Insurance Customers: A Crystal Ball of Big Changes in a Small Window of Time, sheds light on the details of consumer trends that are affecting insurance. In today’s blog, we are taking a close look at some of the most relevant trends in housing and transportation — trends that will affect P&C insurance products, services and customer experiences that can adapt to consumer volatility. We will look closely at:

  • Home- and rental-related activities, insurance products, value-added services and trends in customer experience.
  • Auto insurance activities and products, value-added services, relevant purchase channels and the desire for new methods of pricing and claims management.

Population on the move — Home- and rental-related activities

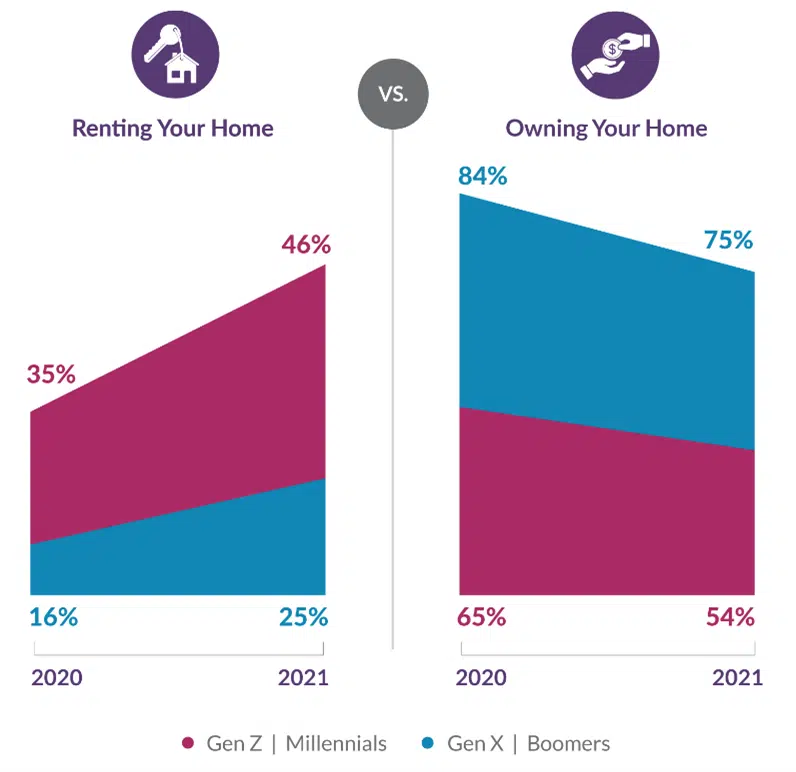
Gen Z and Millennials’ home ownership declined 11 percentage points as compared with the start of 2020 (Figure 1). Gen X and Boomers had a similar decline of nine percentage points. This is undoubtedly a reflection of COVID’s impact on many people’s financial conditions due to job losses, the “Great Resignation,” people moving to other locals and renting instead of buying due to challenges of limited housing, and many Gen Z and Millennials moving back home. 

Whether owning or renting, 33% of consumers invested in their home environment by setting up a work-from-home space, remodeling or renovating or setting up a home gym, according to McKinsey research, a response to the population’s increase in time spent at home, which rose to 62% in 2020 from 50% in 2019. This reflects increased investment in the home or other assets that may need additional coverage, but have insurers assessed this opportunity?   

Figure 1: Rates of home ownership vs. renting
Rates of home ownership vs. renting

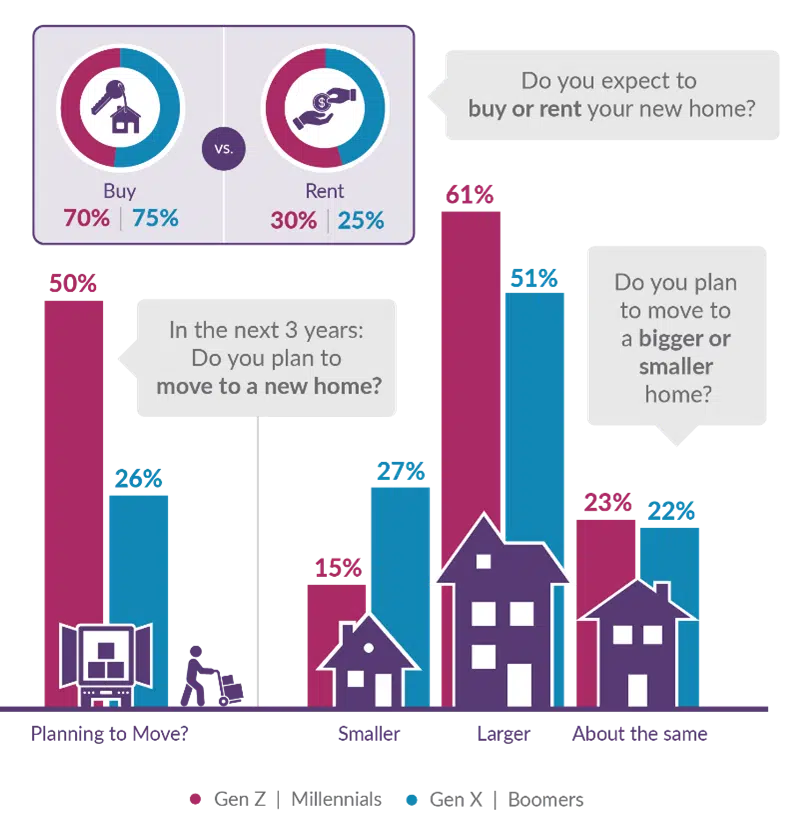
50% of Gen Z and Millennials plan to move to a new home within the next three years, with 70% buying and 30% renting. With 61% of these young movers expecting to have a larger home, there is a huge market opportunity for those who can connect with them when and where they want. But the choices about where they buy will likely be different, given the transient nature of this generation and the expectation of working from home. (Figure 2)

Figure 2: Expectations for a new home in the next 3 years
Expectations for a new home in the next 3 years

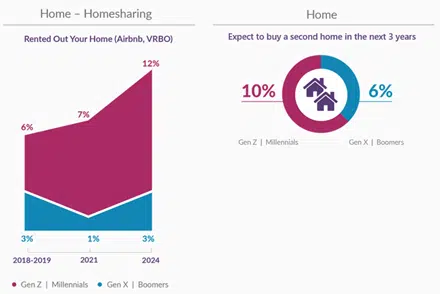
Adding to the Gen Z and Millennial expectations, they are four times more likely to rent their home on a home-sharing platform in the next three years, adding risk complexity and multi-use complexity to their insurance needs. The number using their properties, particularly second homes, for home-sharing will likely continue to increase to provide alternative income streams to address the financial challenges of high inflation. 10% anticipate buying a second home, creating an additional opportunity to expand the customer relationship and drive revenue growth. (Figure 3)

Figure 3: Home-sharing trends and expectations for purchasing a second home
Homesharing trends and expectations for purchasing a second home

Representing still further market opportunities, Gen Z and Millennials are clear-cut leaders in the use of connected/smart home devices like thermostats, smoke/CO detectors, video doorbells and home security devices/services, outpacing Gen X and Boomers (Figure 4). With this usage comes new expectations on how the devices could be used to enhance insurance coverage, address lifestyle needs and provide other value-added services, likely shifting their alliance to insurers who can meet these expectations. A great example is the use of these devices to help the elderly live more safely in their homes by providing monitoring for falls, alerts for taking medicines or doctor appointments and much more. The possibilities are tremendous but require outside-the-box thinking to leverage the technology to meet changing lifestyle needs.

See also: Homeowners, Renters Are Overlooking Risks

Figure 4: Historical and predicted gaps in smart home device usage between Gen Z/Millennials and Gen X/Boomers
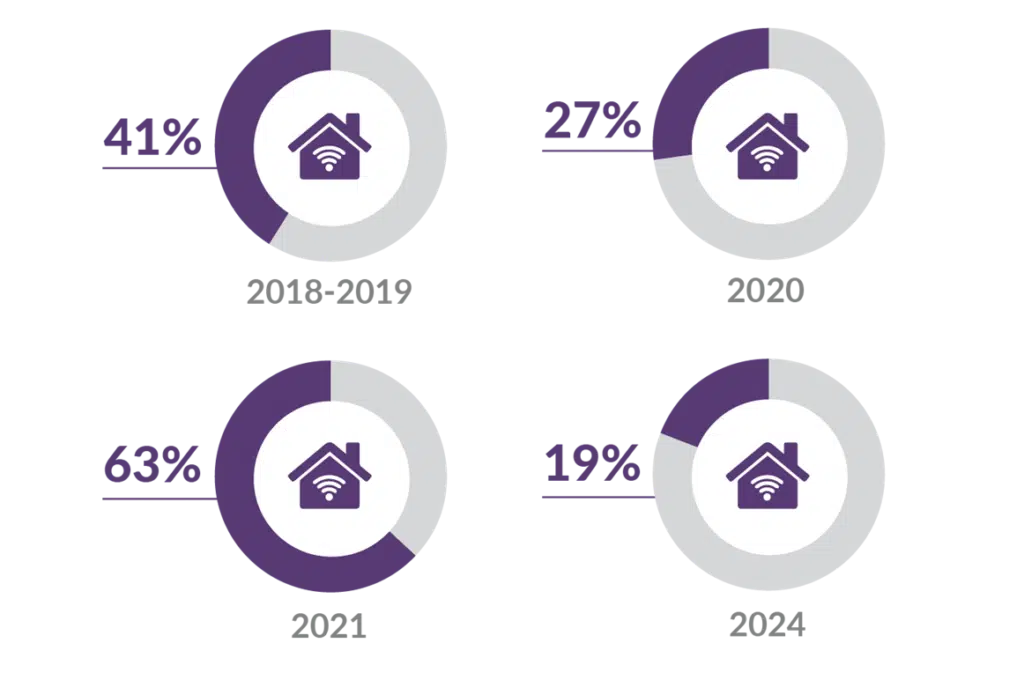
Historical and predicted gaps in smart home device usage between Gen Z/Millennials and Gen X/Boomers

The shifting need for homeowners and rental insurance

When comparing past results with this year for ownership of either homeowners or renter insurance, there was a sizable drop in 2021 within both generational segments, as seen in Figure 5. Gen Z and Millennials anticipate increased home ownership, which offers further market growth opportunities. The key is to anticipate their needs with the right products at the right time in the right channel. For those with existing relationships through rental insurance, the experience will be a key factor in whether they look to those insurers for homeowners insurance. Capturing the customer early in their life and understanding their lifestyle needs and changes creates tremendous opportunity to grow with them as they adapt to changes in their lives. 

Figure 5: Households with home or renter insurance
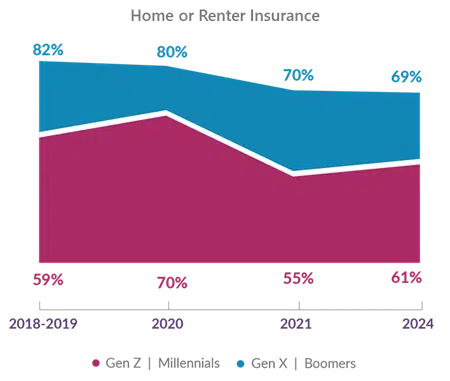
Households with home or renter insurance

The growing desire for value-added services to make life easier

Insurers offering value-added services in addition to the basic risk product will be more successful in capturing and retaining both generational segments as reflected in Figure 6. Value-added services that help manage prevention and recovery are the top areas of interest.  

Both generations are likely to use sensors and alerts for preventing or mitigating losses from fires, carbon monoxide, water leaks or severe weather. Concierge services generate strong interest in both generations. However, Gen Z and Millennials’ interest reflects a generational shift, where they seek services to help them in their daily lives – like food and grocery delivery, Amazon delivery and mobile dog grooming.  

Approximately 62% of Gen X and Boomers and 81% of Gen Z and Millennials are interested in home monitoring for the elderly and children. Some innovative insurers have begun experimenting with this to be prepared for the massive number of aging adults expected in the next 10 to 20 years. 

The sky is the limit when thinking about value-added services. They are low-hanging fruit that provide personalized, regular customer engagement that extends the value of the insurance risk product. In today’s world, customers look at the combination of the risk product, customer experience and value-added services as the product.  

Figure 6: Interest in home or renter insurance value-added services
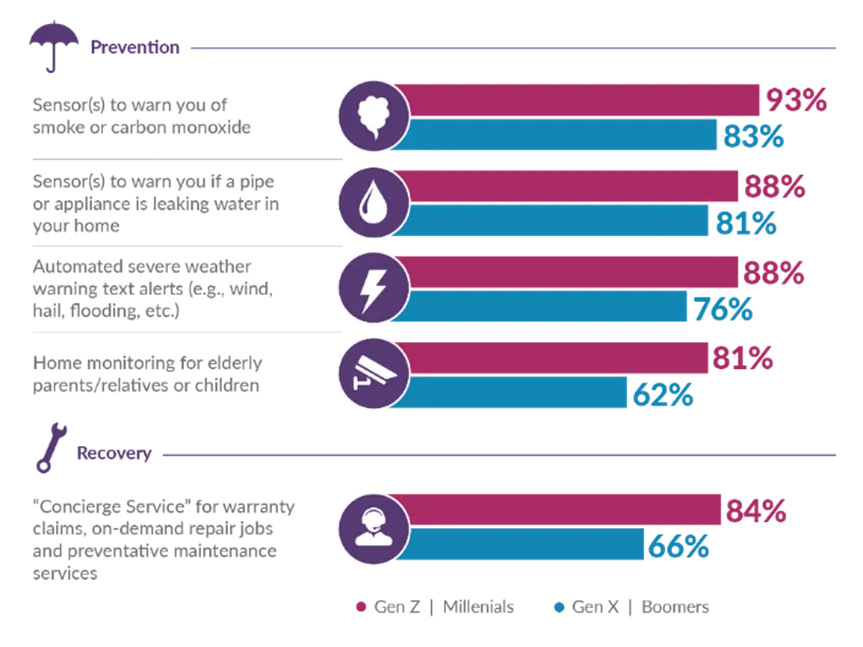
Interest in home or renter insurance value-added services

Claims made easy — the generations agree that digital claims experience wins out

There is strong agreement among the generational segments regarding claims options. The ease and convenience of submitting a claim with a photo of the damage via a smartphone app to using weather and location data to automatically submit a claim is exceptionally high, at 77% to 89%. Taking convenience one step further, customers would like insurers to solicit repair bids from approved contractors on their behalf, by 86% to 88%. For those who want home-sharing on-demand insurance, the importance of the ease of turning on and off the insurance is also very high, at 81% to 90% (Figure 7).

These results highlight a key customer experience demand -- making customers’ lives easier with digital solutions that enhance the relationship, particularly during the claims process -- insurance’s moment of truth.

Figure 7: Interest in ways to activate the claims or coverage process
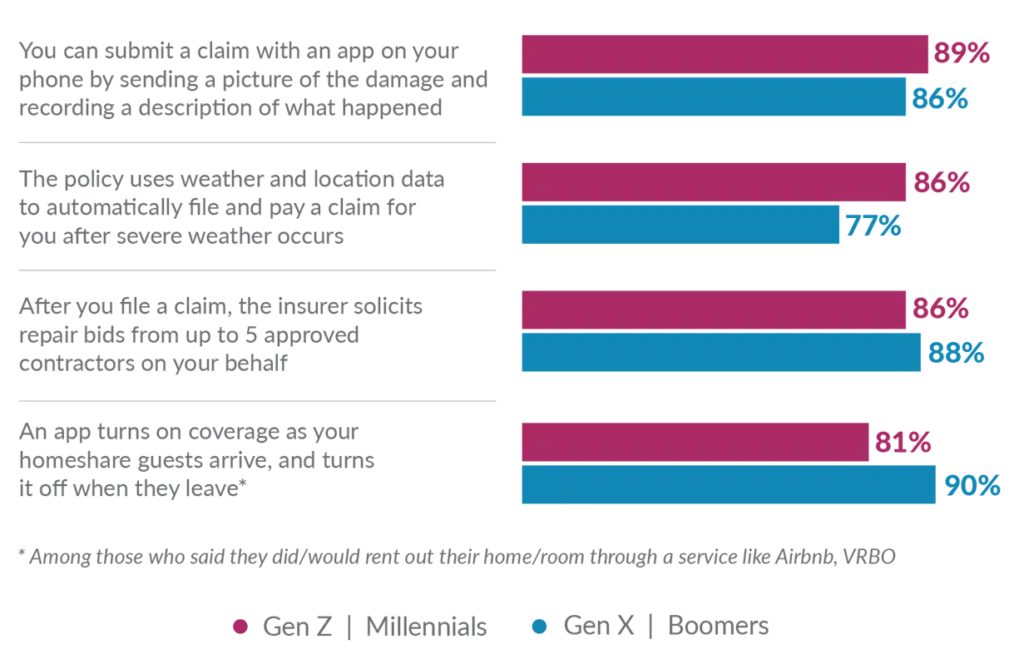
Interest in ways to activate the claims or coverage process

“Bring on the embedded options” — Purchase channel preferences for homeowners and renters insurance

A solid risk product teamed with useful value-added services and customer experience is not enough to stack the odds in an insurer’s favor. The final key component is making it easy for customers to purchase when, where and how they want. Both generational segments strongly agree that traditional insurance company and agent channels continue to deliver the best purchase experience for home and renter insurance, as reflected in Figure 8.

However, Gen Z and Millennials are very open to buying insurance through another channel, such as part of the home-buying or renting process, whether through their bank or credit union, mortgage company or rental leasing company. There is very high interest in having the renter insurance included in the monthly rental fee (86% of Gen Z and Millennials and 76% of Gen X and Boomers). High-tech options like Amazon and Google have a strong interest from the younger generation.

The bottom line is that customers are increasingly moving away from the traditional siloed, separate purchase of insurance to one that is offered or embedded at the time of purchase or renting. This is a major distribution channel shift that will require new partnerships and relationships to meet customers on their terms. For an in-depth overview of today’s channel spectrum, read Majesco’s latest thought-leadership report, Distribution Management: Connecting the Dots to Build Future Market Success.

Figure 8: Interest in home or renter insurance purchase channels
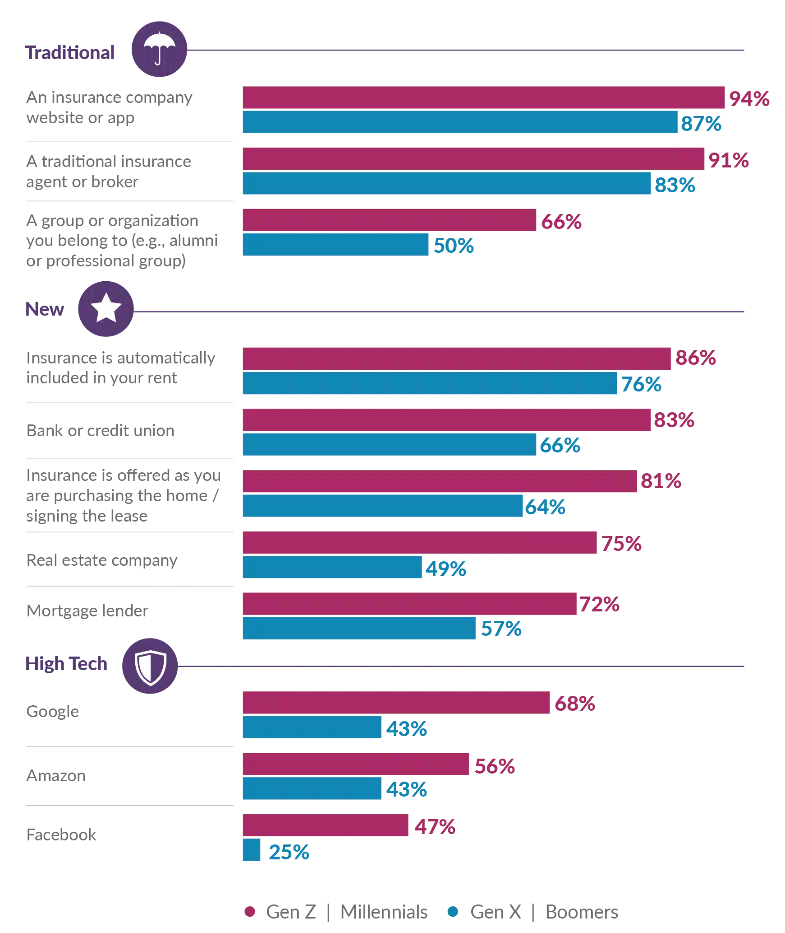
Interest in home or renter insurance purchase channels

Auto Insurance

Auto insurance need in decline?  Let’s take a deep dive into what is going on.

Ownership of auto insurance remains consistently high, but both generational segments expect to see a slight decline of five to six percentage points in the next three years (Figure 9). This decline could suggest a shift to the use of embedded insurance in the purchase or lease of a car, eliminating the need to purchase auto insurance or the elimination of vehicles, given that more people are working from home and given the continued high cost of purchasing, maintaining and using a vehicle.

Figure 9: Households with auto insurance
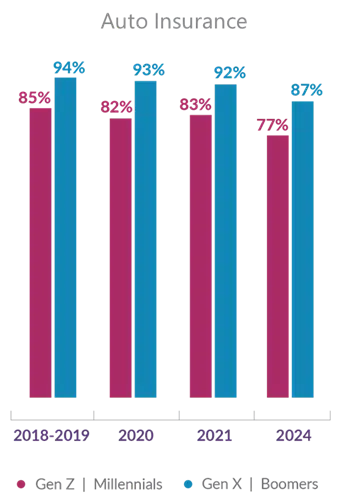
Households with auto insurance

“Show me the data” — Value-added services for auto insurance include info to make life easier

Gen Z and Millennials are very interested in services that provide real-time information on driving safety and performance, keeping their vehicle safe and maintained, maintaining license and registration renewals and knowing the market value of their vehicle (Figure 10). For both generational groups, these value-added services offer new value beyond the auto risk product to drive satisfaction, reduce risk and retain customers. They help customers manage their lives and the assets around them more effectively. 

Figure 10: Interest in auto insurance value-added services
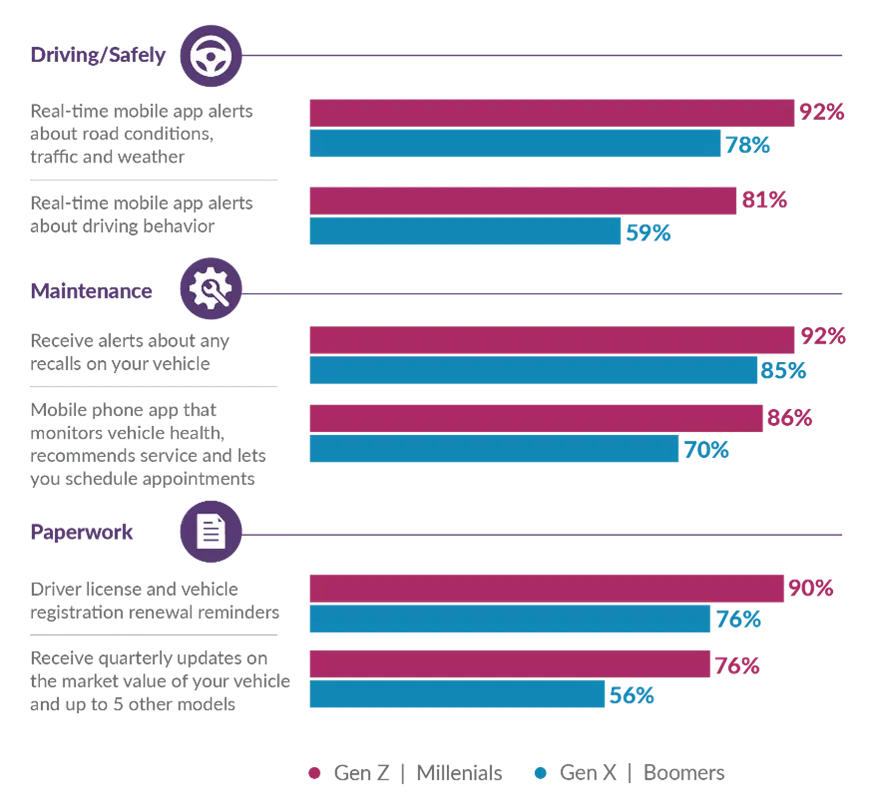
Interest in auto insurance value-added services

Trust and Convenience — the customer experience within auto insurance purchase channels

Traditional channels, including insurer websites or apps and agents, are overwhelmingly the preferred method of purchase for both generational segments (Figure 11). However, among other traditional channels, such as purchasing from a dealership or through another organization, the older generation’s interest drops as much as 23 percentage points compared with the younger generation.  

This trend continues when looking at the new and “high-tech” channels, where there are huge gaps (up to 25 percentage points) between the younger and older generations.

Consistently, the Gen Z and Millennial segment is broadly open to all channels. This highlights the need for insurers to offer and partner with other entities to meet them where and when they want to purchase insurance, moving into a multi-channel world. Gen X and Boomers are still comfortable with traditional channels. Do insurers understand the nuances of channel preference?  

While Gen Z and Millennials see the value of traditional channels, they are more focused on convenience and trust, which is why they are open to other new or high-tech channels. Their experience and trust with companies like Google and Amazon meet both their needs. Insurers that offer or embed insurance at the point of sale directly, or with partners, will transform the purchase process to one that is convenient, seamless and quick. The bottom line…partnerships with other entities are increasingly crucial to not only retain but grow the auto insurance business by addressing how consumers are shifting where and from whom auto insurance is bought. 

Figure 11: Interest in auto insurance purchase channels
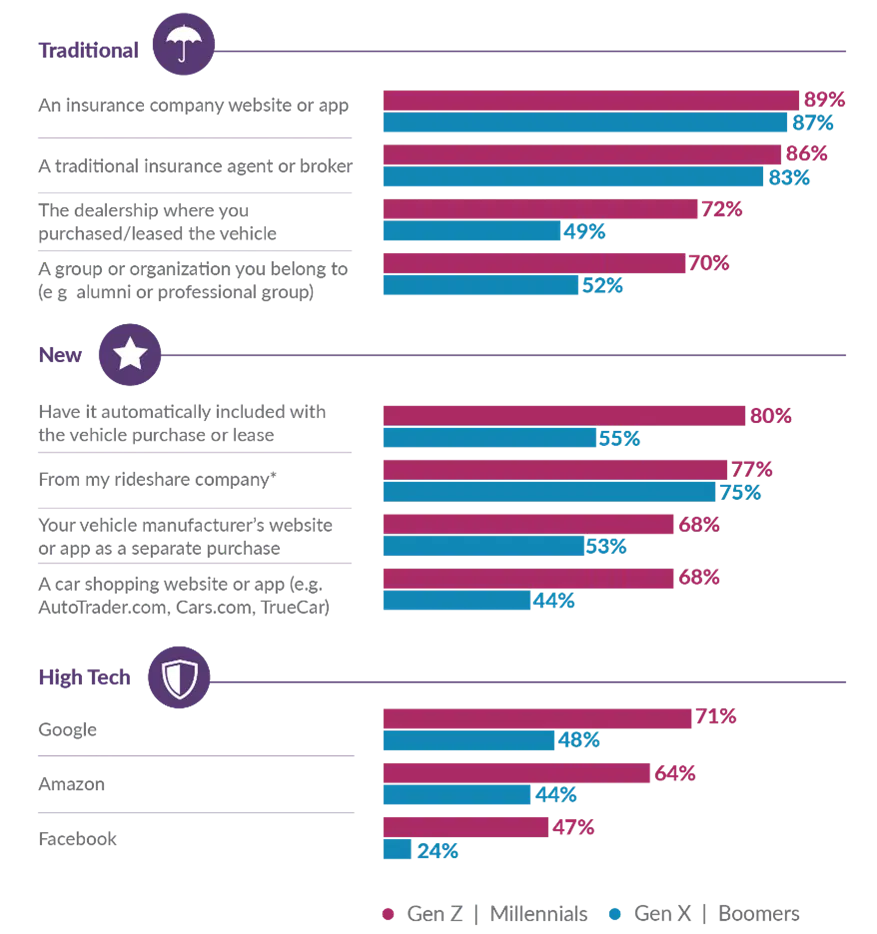
Interest in auto insurance purchase channels

Strong, growing interest in alternative pricing

As we stated at the outset, both generations are open to a wide range of pricing and claims options (Figure 12).

  • Over 80% would use pricing based on driving behavior and number of miles driven, which accelerated in use during the pandemic. Even monthly rates based on whether the car is parked or driving show a strong interest (over 76%).
  • Both generational groups have a strong interest in app-assisted claims processes. The nuanced difference between Gen X and Boomers reflects a desire for control. In contrast, the younger generation is very interested in parametric or automated claims processes, which once again tie to their desire for digital convenience. 

Regardless, the strong results highlight the growing demand for new pricing and claims options for auto insurance that customers will expect as they consider buying or renewing their insurance. 

Figure 12: Interest in ways to activate and determine the cost of auto insurance
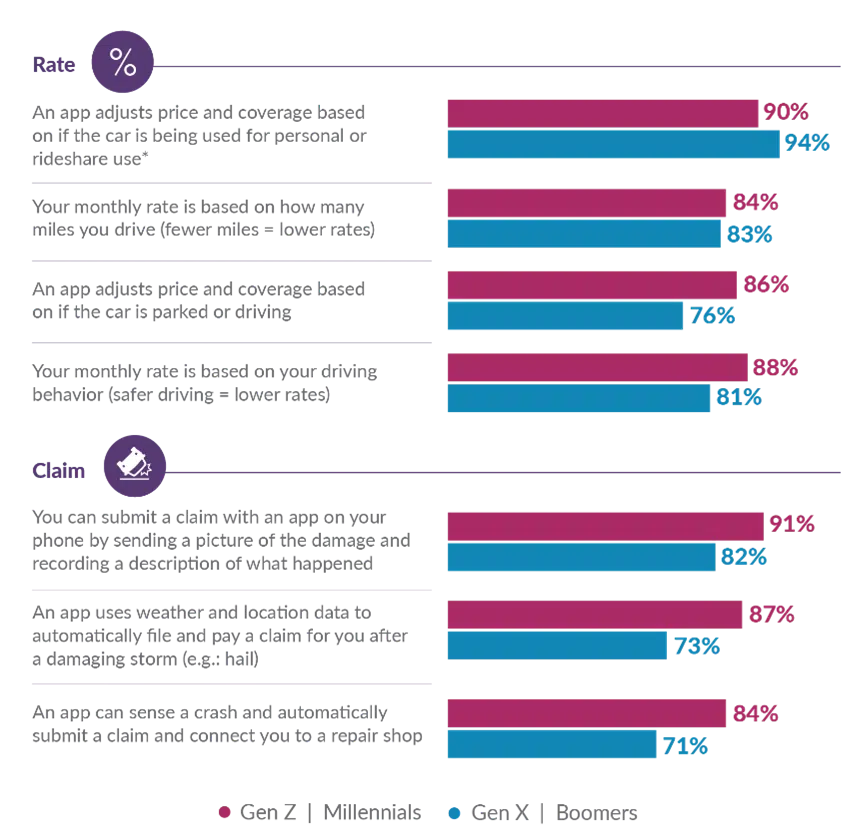
Interest in ways to activate and determine the cost of auto insurance

How to respond?

Today’s insurance process can be difficult, complex and time-consuming. At a high level, what can insurers do to respond to the growing demand for new types of insurance products, services and experiences? How can they reduce the impact of population volatility and increase the opportunity to capitalize on market trends?

For the most part, digital tech and automation will run the future of every business, including insurance. “Pay-as-you-live,” “Protect-as-you-go,” “Buy where, when and how you need it,” “Simplify my life and experience” and “Prevent-as-you-live” technologies and insurance are commanding insurers’ strategic and operational attention. 

In addition, many insurtechs and existing insurer innovations are refocusing to a “buying” over a “selling” approach, through a multi-channel strategy that meets customers where, when and how they want to buy. If distribution channels are easy to use with products that are easy to understand, have value-added services to make their lives easier and provide a great customer experience…then insurance has an opportunity to grow through friction-free, multi-channel distribution.

With the increasing competitive challenges to attract and retain customers, insurers have an opportunity to grow by putting the customer first.

Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Evolution of The Contact Center Experience

The most important contact center metrics are: satisfaction, customer experience, quality assurance and revenue growth -- but the most measured is “call handle time.” Hmmm.

Line of people with headsets on

The term “call centers” is quickly become a relic of the past, and for good reason. Customer service today entails far more than just taking inbound calls; it’s now truly omnichannel. In addition to answering phone calls, today’s contact center experience typically requires agents to have responsibility for responding to online live web chat, text chat, email requests, website contact form submissions and even social media posts.

However, while customers expect to have this flexibility to engage with brands on their terms, phone and voice remain the primary means of customer communications. The State of Contact Center Conversation Intelligence 2022 report by Observe.AI finds that 82% of contact centers engage with customers via the phone. Even as technology becomes more integral and upfront in the equation, people still crave that person-to-person experience.

Yet the rise of our technology-driven, instant-response world — not just in customer service but in literally all aspects of our lives — has conditioned us in ways that have changed expectations about the contact center experience. And these expectations are more nuanced than what most contact centers are measuring, prioritizing and training for.

The Contact Center Experience: Heightened Customer Expectations

Research shows that the top four contact center metrics, in order of importance, are: customer satisfaction, customer experience, quality assurance and revenue growth. Despite this, one of the most measured metrics per agent is “call handle time.”

With an evolving customer expectation to fast-track problem resolutions, focusing on call handle time might, on the surface of things, seem to make sense. But that’s the problem. The metric only scratches the surface of what will improve the key performance indicators (KPIs) contact centers themselves have said are most important.

Today’s customers expect not just faster response rates but faster resolution. They want the issue to be addressed in full on that first contact, without being transferred to someone else or redirected to another department. A Salesforce study found 82% of customers expect to solve complex problems by talking to one person.

In other words, faster resolution doesn’t mean they only want to deal with automated attendants and AI tools. While contact center managers are understandably enthusiastic about the speed, convenience and reduction in human resource costs associated with self-service chatbots and machine learning, these tools and technologies have their limits.

The most loyal customers — the ones who will become your brand’s advocates — are developed through profoundly remarkable customer experiences, and those take a deeper connection. As Chip Bell writes, it requires customer service team members who understand what matters most to their customers and who are constantly looking for ways to create more meaningful, memorable experiences.

Clearly, customers still value the human experience, especially when the humans they’re interacting with have the both the motivation and the skill to make sure their needs are being met. In fact, the Salesforce study shows that 63% of consumers and 76% of B2B buyers expect businesses to know their unique needs and expectations.

Contact Center Management: Missing the Forest for the Trees?

This resurgence and importance of the human aspect in customer service has risen steadily along with the increased adoption of AI and automation. We need people to connect the dots between technology, including sales enablement investments, and what customers want to create a customer-centric culture that is truly dedicated to creating engaging, memorable customer experiences.

AI is often sufficient for addressing the simple problems and helping customers who prefer to go the self-service route. But more and more consumers have now been trained to escalate concerns. They want outcomes, not automated replies, and strategic relationships, not transactional experiences. A lot of companies are talking about “making business more human,” but they’re focused on bringing more and more AI tools into the contact center. And when those tools refer to people as “users” instead of customers, they strip out even more of the human element.

Contact center management needs to take a hard look at what they’re investing in and whether these investments are really delivering on the metrics they say they care about — or something else entirely.

Is that investment in conversational AI about meeting customer needs and solving problems (i.e., call resolution)? Is it about creating loyal customers? Or is it really just about minimizing costs, getting the customer off the phone/chat as quickly as possible and “maximizing ROI,” regardless of whether the problem is truly addressed?

See also: What's After COVID for Call Center Reps?

Contact Center Training Isn’t Adding Up

Most contact centers perceive themselves as more strategic than tactical, monitoring and driving business metrics like customer satisfaction rather than tracking, for example, the number of calls per agent. But do the organizations that are recruiting and training their team members have the same view? Or are they just giving it lip service?

The Observe.AI study found that only 52% of contact center agents consider themselves “very prepared for the future.” Another telling stat: 29% of the contact center agents who consider themselves “very prepared” are actually bottom or average performers.

In the same study, 22% of respondents say their organization “consists of mostly bottom performers,” with some average and some top performers. Only 43% of all respondents say they have mostly top performers.

What this tells us: Companies are increasingly putting themselves at risk of letting down and losing customers and doing irrevocable damage to their brands. “Low performing” contact center agents directly affect the business through low call resolution rates, poor customer satisfaction, poor operational efficiency and low employee satisfaction and engagement. 

Human intervention and solutions are at the root of what customers want. And all the various forms of technology are making it more difficult, not easier, to connect the dots. In too many contact centers, data gathering has become more important than solving problems, being empathetic and listening to uncover needs.

A good example of this is the experience described by one contact center leader we spoke with at Customer Contact Week (CCW) earlier this year. He explained that more than 500 phrases and responses have been recorded into their automated systems and processes. His agents are now listening to three customer calls simultaneously, but they aren’t actually speaking or even actually listening to pinpoint the issue or uncover needs. Instead, they’ve been trained to listen purely for specific words and then press the right button for the right recorded response.

The ideal metric they’re going for is a 0.3-0.5 second response time. “Then the caller doesn’t realize it’s artificial,” he said. The agents will typically hear the word they need to act on within 15-17 words of the customer’s problem statements.

These agents are evaluated purely on how often they press the right button and whether they do it in time. What’s not factored into this equation: actual call resolution or customer satisfaction.

As the leader explained (with enthusiasm), it’s all about driving costs down to under $20/hour per agent. There was no mention of customer satisfaction, solving issues the first time, customer retention or consideration of employee satisfaction and retention.

How to Humanize the Contact Center Experience

Twilio’s 3rd annual State of Personalization Report found that 62% of consumers say brands will lose their loyalty for delivering un-personalized experiences.

Yet our polling of dozens of attendees at CCW each year repeatedly shows that some of the critical skills, actions and strategies that will drive a more personalized customer experience aren’t being addressed. Our most recent polling surfaced three key areas that contact center leaders are struggling with the most:

  1. Agents are not asking enough questions/listening for customer cues about other possible (unstated) needs
  2. Agents are feeling overwhelmed with too many and disconnected tech tools
  3. There is a desire to create more of a true human connection with customers

Training people to press the right button faster isn’t going to create a profoundly remarkable customer experience. It’s also not going to create a personally satisfying and meaningful experience for your employees. If you want to deepen customer loyalty and satisfaction, you have to engage your agents both from a skillset and a mindset perspective.

Agents who view their roles as problem-solvers and value creators — for both the customer and for the business — are going to be more internally motivated and energized to deliver those profoundly remarkable experiences that turn customers into brand advocates. Yet most contact center training ignores this essential piece of the puzzle.

An effective, human-centered development approach emphasizes:

  • The right mindset, which is foundational to achieving the key metrics today’s contact center leaders say are most important
  • The right listening and questioning skills so that agents are not only making the best use of time but also getting problems resolved the first time and making sure value is created from the customer’s perspective.
  • A problem-solving process that focuses on understanding, empathizing with and meeting customer needs head on, and serves as a guidepost for agents to rely on under pressure.

Just as important — and too often overlooked — is the role of the leader. Contact centers need to invest in the development of leaders to create coaching cultures. The Observe.AI study found that 80% of respondents who say they have mostly top-performing contact center agents have a formal coaching program — four times more likely than those that do not.

When we polled contact center leaders at the most recent CCW, “Lack of manager coaching and giving feedback” was one of the top two organizational challenges they said they were facing (along with needing to “improve training effectiveness and ramp-up time”).

The Great Resignation didn’t start with the pandemic; it merely accelerated and crystallized it. The employee perception of organizations caring for their well-being had risen annually over the past decade and then fell off a cliff beginning in early 2020.

And here again, with discussions of “automated coaching,” companies are looking for technology to bail them out. Coaching remains one of the most human, personal and powerful things leaders can do. If your leaders aren’t equipped to coach, they’re not equipped to lead and create a great contact center experience.

Revolutionizing the Contact Center: People + Technology

There’s no question that technology has transformed contact centers and will continue to innovate the way companies interact with their customers. The advances in AI and machine learning have turned many routine and rote requests into quick, self-service transactions. The problem is, many contact centers have left it at that.

The ultimate value of technology is that it should be used to free your agents to be more human and create more of the meaningful, differentiating experiences that matter to your customers. If metrics like customer satisfaction, customer experience and revenue growth truly are as important as you say they are, you have to invest in your people, not just technology.


Randy Leiker

Profile picture for user RandyLeiker

Randy Leiker

Randy Leiker is the vice president of client development at Integrity Solutions. With almost 30 years of experience serving the insurance and financial services industry, Leiker's passion is helping companies manage change. From expansion into new markets for growth to restructuring current operations to better serve clients, the one constant is people. Leiker has helped companies build the processes and procedures for foundational success while creating and implementing training programs to ensure sustained success. 

His consultative approach and experiences as a VP of Sales, Division Manager, and Zone Training Coordinator have helped him engage business owners, market leaders, and industry partners, asking the right questions to determine the true pain point and dream state. 


Why Brokers Have a Leg Up in Insurtech

While insurtechs are struggling, established brokerages have deep industry knowledge and solid businesses from which to build and evolve technology solutions. 

Two men in suits

Insurtechs rose to the forefront of insurance industry news based on their tremendous valuations and self-proclaimed ability to shake up an antiquated, tech-challenged sector. Though many have proven successful, the road to victory was – and still is – filled with significant risk, investor turmoil and the unstable organizational processes that startups are sometimes known for. 

Some Insurtechs Struggling

While insurtechs were touted as the next best thing for the insurance industry and a welcome disruption to a stagnant sector, some companies are struggling. Insurtech darlings have seen their stock price plummet as much as 95%, while others have announced large layoffs.

That’s not all. As Paul Carroll recently wrote at Insurance Thought Leadership, “There is even talk of – perish the thought – down rounds (in which startups will have to raise money at lower valuations than they previously held).”

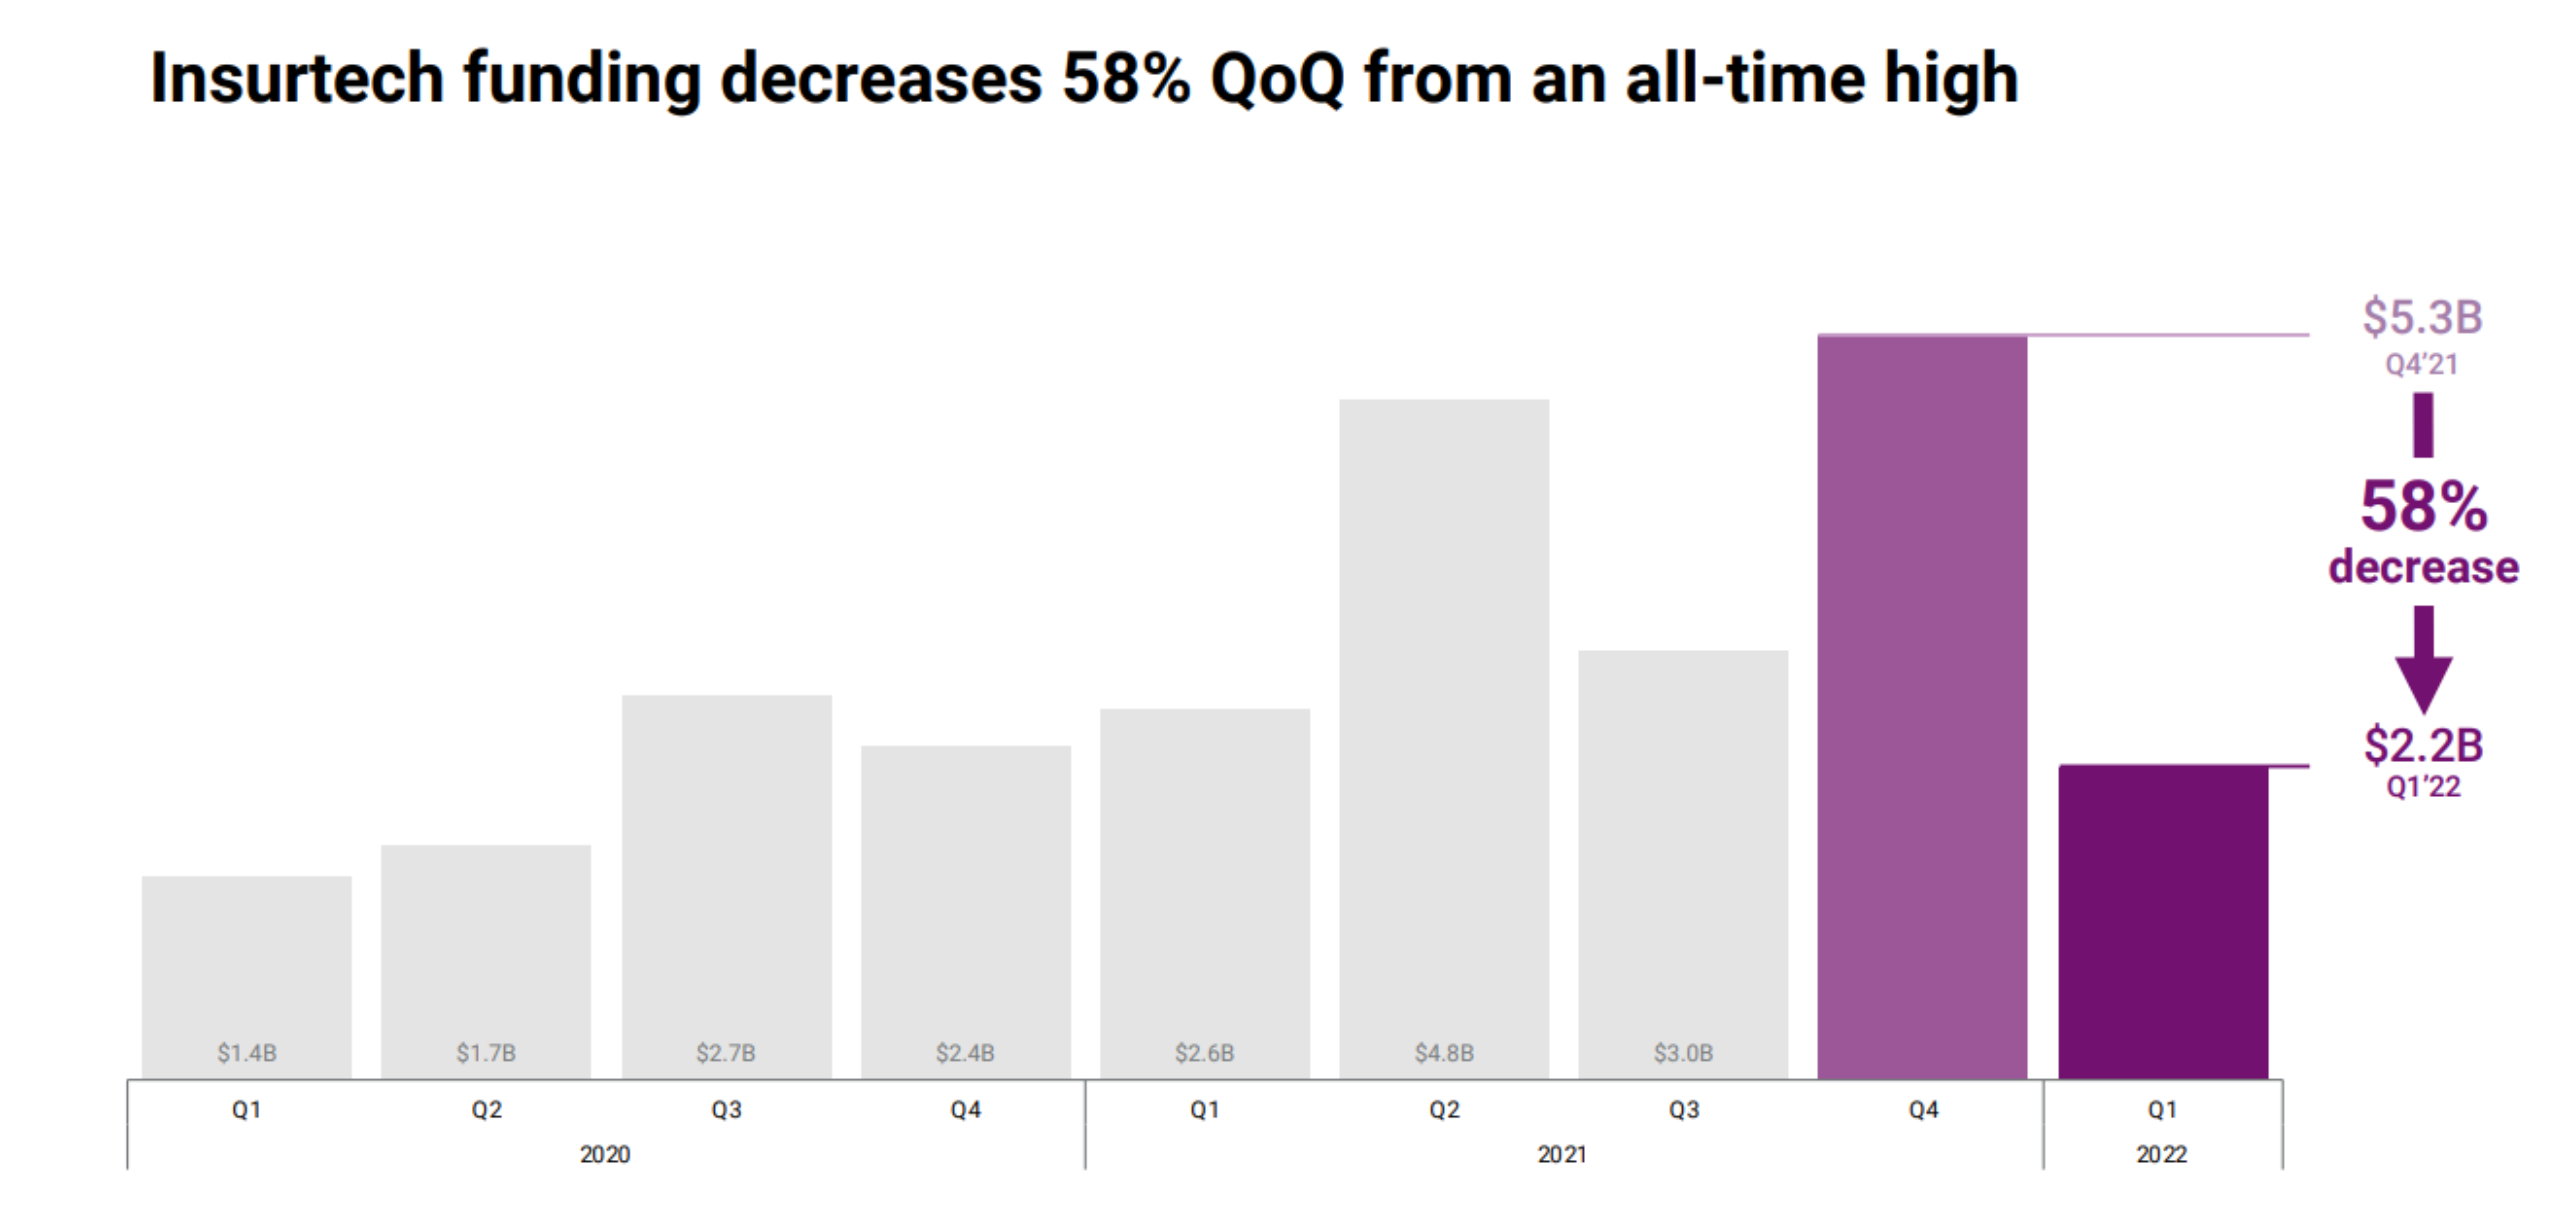
Add to that the fact that insurtech funding is declining from its highs. Following a record in Q4’21, insurtech funding fell 58% in Q1’22 to $2.2 billion, according to CB Insights. This represented a 15% YoY (year-over-year) decline from Q1’21. Q1’22 was also the lowest quarter for funding in almost two years. Meanwhile, insurtech deals remained flat quarter-over-quarter at 143.

Chart showing Insurtech funding decrease

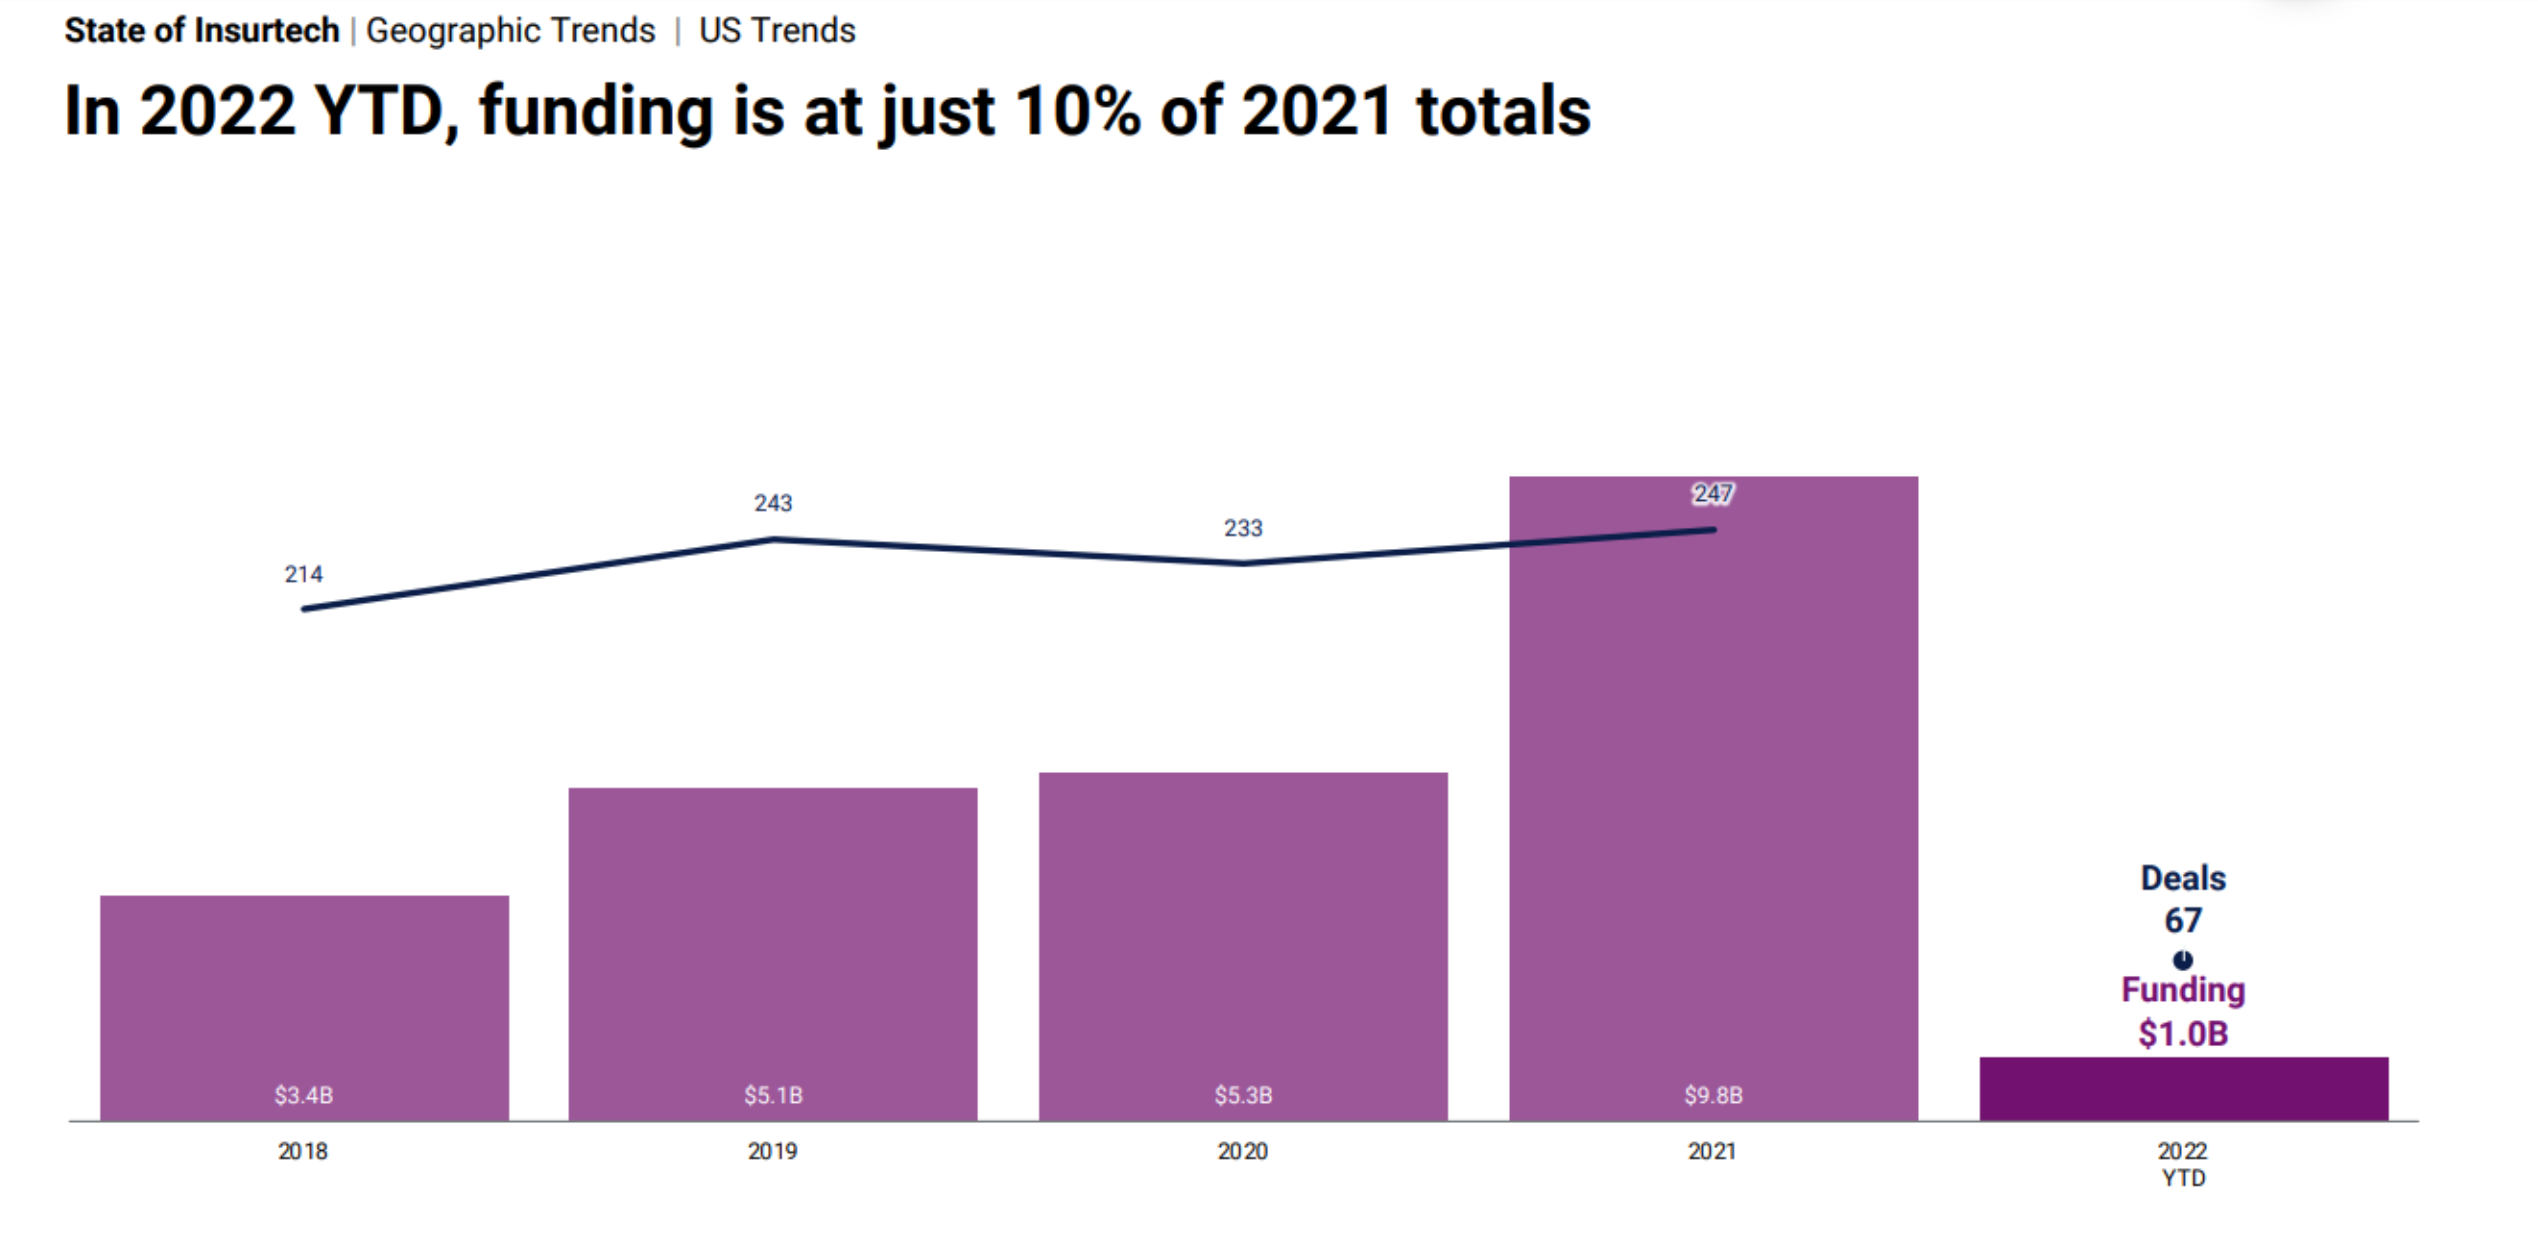
In the U.S., specifically, year-to-date funding of insurtechs is at just 10% of 2021 totals.

Chart showing comparing 2022 funding to other years

See also: Top Brokers' Advantage

Another Option

While the recent news and data regarding insurtechs is not all positive, it doesn’t necessarily mean that the digital revolution in the insurance industry is coming to a halt. Established brokerages and financial firms are providing that by creating tech-driven solutions to meet the needs of today’s consumers. These firms have deep industry knowledge and solid businesses from which to build and evolve technology solutions. 

Companies that have been in the insurance space for decades are launching digital-first, transactional lines services. For example, a carrier recently launched a digital platform offering home and auto insurance with the benefits of choice, efficiency, price transparency and brokerage advice backed by a large personal lines carrier. These initiatives leverage new technology built on the strength of large, knowledgeable and experienced insurance brokers, as opposed to a start-up. 

Established insurance companies are oftentimes better suited to offer tech-driven solutions. For instance, some have access to more than 500 carriers in the U.S. and Canada. Typically, startup competitors have fewer than 10 and struggle to get carrier appointments. A broader foundation ensures stability of market placement for customers. Without that, you have little to work with, and even less to offer clients. 

The future of insurtechs remains an unknown. Many have been acquired and their technology integrated into legacy systems at larger public companies. Others may go by the wayside. Either way, customers now have the ability to choose from tech-based coverage and to receive trusted risk and insurance advice from experienced brokers backed by well-known carriers. This may not be great news for insurtechs, but it is excellent news for insurance buyers.


Bryan Davis

Profile picture for user BryanDavis

Bryan Davis

Bryan Davis serves as president of VIU by HUB, a digital brokerage platform backed and developed by HUB International, the largest personal lines broker in the U.S. 

Davis previously held leadership positions with USAA, Nationwide and AIG.

He is a graduate of Wofford College and has an MBA. He is also credentialed as a ChFC and CPCU. 

Why to Customize Employee Healthcare Plans

Custom health plans allow employers to shop competitively the vendors inside of their health plan, like their pharmacy benefit manager, claims manager and reinsurer.

Doctors showing a patient an x-ray

Employer-sponsored healthcare remains one of the most sought-after employee benefits across America. Unfortunately, rising premiums have made it difficult for many plan participants to continue coverage. According to Willis Towers Watson, employers can expect health coverage costs to jump at least 5% to 9% over the next year. Randa Deaton of Purchaser Business Group on Health predicts a 10% to 12% increase.

Why does this larger-than-usual jump matter? According to Axios, this latest ballooning cost is expected to be passed down to nearly half of Americans who currently receive coverage through their employer. Rising costs of employer-sponsored healthcare premiums have forced many companies to reduce benefits, lower contributions or eliminate health plans altogether. 

Much uncertainty remains concerning how much more and for how long premiums will rise. In the meantime, it is important for employers to understand the severity of these increases and what they can do to reduce costs while maintaining quality benefits.

Rising Premiums - Why?

According to Mercer’s 2021 National Survey of Employer-Sponsored Health Plans, the average per-employee cost of employer-sponsored health insurance increased 6.3% in 2021. 

Many employers have chosen to pass on these costs to their workers, resulting in a high degree of scrutiny. Employers struggle to maintain an affordable healthcare plan that is accessible to everyone while facing rising cost pressures. Finding a solution to these rising costs is critical to retaining talent, reducing turnover and maintaining morale. 

Healthcare costs in the U.S. have risen dramatically over the past several decades. In fact, a study by the Kaiser Family Foundation (KFF) and the Peterson Center on Healthcare found that, when adjusted for inflation, healthcare spending increased nearly $1 trillion from 2009 to 2019. The study showed that healthcare spending in 2019 was nearly $3.8 trillion, or approximately $11,582 per person. These costs are expected to reach $6.2 trillion, or around $18,000 per person, by 2028.

What exactly is causing this rapid rise in employer-sponsored healthcare costs? A combination of factors is at play. Inflation is a leading cause. Health spending and medical care costs typically outpace growth in the rest of the economy. Moreover, healthcare expenses represent a large share of gross domestic product, and many families are feeling the pressure as the cost of health services and premiums start to grow at a rate that surpasses their wages.

Increased provider expenses may also be to blame. Currently, hospitals and healthcare providers are well-positioned to demand higher prices. A recent report by the Center for Studying Health System Change found partnerships and mergers between insurers and medical providers to be one of the most prominent trends in the country’s healthcare system. Lower individual market competition has put insurers and providers in a position where, without opposition, they can drive up healthcare service prices. 

The COVID-19 pandemic has also played a critical role in rising premiums. Throughout much of 2020 and into 2021, many states were shut down to prevent the spread of the coronavirus, preventing many individuals from receiving the care they would normally receive otherwise. Now that the country is open again, consumers’ use of healthcare services continues to rise as more people schedule the care that they deferred during the pandemic. 

See also: How Synthetic Data Aids in Healthcare

Customized Healthcare Plan Solutions

As healthcare premiums continue to rise, many employers are left unsure of how to keep coverage expenses manageable. Most businesses do their best to avoid passing on increased costs to employees but may feel compelled to cut back on benefits or reduce contributions to make up for rising premiums. Many employers are turning to customized healthcare solutions to maintain quality benefits for their workforce while finding opportunities to increase insurance premium savings. 

Custom health plans allow employers to shop competitively the vendors inside of their health plan, like their pharmacy benefit manager, claims manager and reinsurer. This results in cost savings compared with typical off-the-shelf health plans from insurance carriers while maintaining the same quality of coverage. 

As an example, prescription spending accounts for 27% of a plan’s overall claims on average, according to Milliman. Inputting a more efficient pharmacy benefit manager often results in a 50% reduction in overall Rx spending without restricting access to pharmacies or prescriptions for members. These savings are substantial for businesses looking to find ways to reduce healthcare costs and improve benefits. 

Another major benefit with custom plans is they can be built onto all the major national networks: Blues, United, Cigna, Aetna and Humana. So, these plans have no sacrifice to doctors or facilities for employees and their dependents. With flat monthly premiums, they also have the same cashflow predictability as off-the-shelf retail health plans. 

By enrolling in a customized healthcare solution, businesses can gain more control over the selection of their healthcare plan and can choose a policy that better fits their employees’ unique needs. Customized healthcare plan designs can also result in significant savings for employers without the need to reduce employee benefits or employer contributions. This type of solution can be a win-win for both employers and employees in the long term.


Eric Calciano

Profile picture for user EricCalciano

Eric Calciano

Eric Calciano is a partner at New City Insurance.

He specializes in building custom health plans to reduce costs for employers while improving benefits for employees and their families.

The Soaring Cost of Insurance Fraud

Fraud exceeds $300 billion a year in the U.S., nearly four times the previous official estimate, in 1995, partly because the internet allows new forms of cheating. 

Image
The Soaring Costs of Insurance Fraud

While we all know that insurance fraud is a massive problem, we now know just how massive: more than $300 billion-a-year massive, just in the U.S.

That figure comes from the Coalition Against Insurance Fraud, whose estimate would mean that fraud costs each person in the U.S. some $930 a year and the average family some $3,750. The estimate is nearly four times as high as the group's previous estimate, in 1995, of $80 billion of fraud a year in the U.S. -- largely because of inflation and because the coalition looked at more types of fraud this time around, but also because the internet has allowed for new forms of cheating. 

“We updated our study because regulators of insurance need to know this information, as do legislators in Washington, DC, and in our state capitals all across America,” said Matthew Smith, the coalition’s executive director. He said the goal is to put a target on fraud, so that, the next time the group produces an estimate, the number will have fallen. “There’s no reason it shouldn’t,” he said. 

Life insurance registered the most fraud, at roughly $75 billion a year. Next was Medicare/Medicaid, at nearly $70 billion, followed by property/casualty ($45 billion) and healthcare and workers' comp (about $34 billion each). The report says that roughly $25 billion of the workers' comp fraud occurs via false claims, while some $9 billion is because of falsification that leads to underpayment of premiums. Auto theft -- which was not included in P&C -- totaled $7.4 billion a year. 

The coalition singled out the internet as a significant enabler of fraud since it last did a comprehensive estimate of industrywide fraud. 

“In 1995, that little thing we call the internet was only about four years old,” Smith said. “We all know the internet has revolutionized every aspect of life, but it also opened new areas and avenues for insurance fraud.”

The internet, and a host of related technology advances, should also, in my view, make it easier to spot fraud. We've all seen how people making fraudulent claims against workers' comp have been caught through posts on social media showing them playing golf, skiing or doing something else that shouldn't have been possible, given the extent of their "injury." Big data and the ability to analyze it have made it easier to spot doctors generating such high volumes of "treatments" that they likely are in league with fraudsters. Sensors in cars will increasingly tell us what happened in an accident -- and what didn't happen. And so on.

Fraud will always be a cat-and-mouse game. Yes, the bad guys have gained an advantage because the internet has expanded their reach. But technological advances, including the internet, give the good guys a lot of new tools, too -- if we use them.

Here's hoping the next report by the coalition does, in fact, show that the good guys have managed to fight back powerfully.

Cheers,

Paul

P.S. I'm drawing my numbers for the report from two news articles, here and here. I'd obviously use the report itself, but as of Monday evening, as I write this, the page on the coalition website where the report is supposed to be returns an error message when I click on it. Here is the link to that page, on the assumption that the coalition will soon fix the error.  

Is Blockchain Still on Track?

With B3i declaring bankruptcy, will blockchain/DLT (distributed ledger technologies) ever reach the point of disrupting the industry for the better?

A pattern made with gold hexagons

Keeping aside the details of B3i bankruptcy, why is the uptake in the industry very slow, and is there a real return on investment for many of the current blockchain/DLT industry initiatives?

The short answer is that there are many impediments that need to be resolved for a faster uptake. While it is disconcerting to see a leading innovator, in B3i, leave the arena, the killer applications of blockchain/DLT are still evolving and need some push through advances in the technology, broader education of benefits of a business network-based solution to problems of inefficiencies in the industry, concrete business cases with measurable near-time ROI and executive level support. The one application where the industry could see immediate benefit is an area where the industry may be too conservative to get into: cryptocurrencies.

The Impediments to Adoption

The impediments to adoption can be broadly classified as business and technical. Many of these impediments are being addressed.

Business Impediments

  • Collaboration as opposed to competition

Blockchain/DLT is effective when entities come together and form a business network. Forming a business network requires insurance entities to collaborate with a competitor. While the notion is that this will be for the betterment of the overall industry, for any business capability it is not easily accepted, especially when many businesses are doing relatively well despite all the inefficiencies. The push to collaborate will materialize only when insurtechs truly start disrupting the business processes of the industry. Also missing in the industrywide discussions is that insurance entities can still compete on their own terms while collaborating with their competition. The technology to enable this concept exists.

  • Regulatory framework

Regulators are reviewing blockchain/DLT technologies. Many of them attend conferences that have specific tracks on this topic. However, there is a need for a comprehensive, industrywide framework that is fine-grained enough to the level of a sector and business capability.

  • Compliance to regulations

While the regulatory framework is a work in progress, it is not clear if the compliance posture is satisfactory to regulators as business networks between insurance entities come into existence.

  • Operational risk

The operational risk introduced by new technologies, especially solutions that are distributed across multiple entities of a business network, may be too opaque for insurance entities to jump in headlong.

  • Legal

The legal aspects of some of the features of blockchain/DLT technologies are still being addressed. For example, smart contracts are considered legal contracts in some countries, where they are enforceable. However, there is no clarity on the legality of these in many other countries, so it is not easy to implement these in some cross-border transactions. Even in a jurisdiction that recognizes smart contracts as legal contracts, there is not enough critical mass of use yet for legal aspects to be clarified and precedents established.

  • Insurance for use of blockchain/DLT

There are many well publicized high-profile hacks of smart contracts in production in the public blockchain/DLT arena. While the context of enterprise use is mostly around private and permissioned blockchain/DLT implementations, the issue of hacking smart contracts is still something to be cognizant of, as the business network spans multiple entities and their varied security implementations. Hence there is a need for insurance that covers the risk of using smart contracts. This is an area that is still evolving and needs to mature for entities to be comfortable in using blockchain/DLT technologies.

  • Cultural 

The cultural acceptance of blockchain/DLT technologies and the concomitant implications for an insurance entity is one of the most important impediments for adoption. This barrier to adoption can be bridged with appropriate executive support. But, for this to happen, the real ROI and the benefits of a business network capability must be articulated well. Effective tools for quantitative measures of these benefits are yet to be developed.

  • Business network operating model

Who creates the business network and who runs and governs it? Should I join an effort that my competitor started? Or can I start my own network for some business capabilities and expect my competition to join, provided I am willing to join the networks they initiate? The answers to these questions are critical for increased uptake in the adoption of blockchain/DLT in Insurance. There are some initiatives that industry membership groups have initiated, but how many can an insurance entity join? Is joining many networks depending on business capability scalable from an IT and operations perspective? The answer could be for an entity to create and be part of one network and let technical capabilities around interoperability help the entity participate seamlessly in many other business networks. This capability is still not mature.

  • Public vs private blockchains

This is a topic that needs further discussion in the industry. In the early stages of discussion around the enterprise use of Bitcoin and Ethereum public networks, it became clear that private and permissioned blockchain/DLT technology is the only option for enterprise use cases. This is because of limitations of public networks regarding performance, speed and privacy. Public networks have started addressing these issues, but the extent to which the industry will accept the use of public networks for insurance transactions is up for discussion.

See also: Guide to Insurance on Cryptocurrency

Technical impediments

  • Interoperability

The technical solution for blockchain/DLT transactions to seamlessly transcend the different underlying technology implementations is critical to the increased adoption in the insurance industry. The good news is that these technologies are maturing and that there is increased impetus behind making transactions interoperable between networks for multiple industries.

  • Performance

In the near past, as private and permissioned blockchain/DLT technologies were increasingly being evaluated for enterprise use cases, slow performance caused many implementers to pause their efforts. While many of the early platforms have fixed and improved their performance measures, some of the newer platforms still have technical limitations. Also, because there is an increasing focus on the use of public blockchain networks like Ethereum for enterprise use cases, the recent initiative to move Ethereum from proof-of-work consensus mechanism to proof-of-stake should alleviate performance concerns of this well-known public network.

  • Scalability

Scalability of blockchain/DLT private and permissioned networks in terms of large number of participants and their operational base is an issue that is still being ironed out. However, public networks are better suited, and, with Ethereum changing to proof-of-stake very soon, this problem may be alleviated for some enterprise use cases that can be deployed on such public networks.

  • Security and privacy

Blockchain/DLT networks span multiple enterprise boundaries. While the underlying technology is meant to allow secure transactions between inherently untrusted parties, the crossing of enterprise boundaries brings into focus the security posture of the weakest entity in the network. If entities in the network follow guidelines and implement continuous monitoring of adherence to these guidelines, the network could be considered secure. 

Privacy of data and insurance transactions in blockchain/DLT networks could be a concern in two scenarios. In the private business network scenario, insurance entities may deem certain data and transactions to be private and keep them away from competition. Technology does exist for private data and transactions and is maturing. The other scenario is that of transactions on the public networks. Technology for increased privacy of the data is evolving, and clear strategy of an insurance entity to limit public network transactions to those that their privacy policies allow will go a long way in accepting usage of such networks.

  • Governance

The technology for neutral governance of the business network based on blockchain/DLT technologies is maturing. There is increasing need for discussion around a more decentralized way to govern such networks. The rapidly developing technology around DAOs (decentralized autonomous organizations) may be of help. Tools for such a solution need to be developed.

Crypto use cases for the industry

While the industry discussion is focused on use cases that improve the efficiency of insurance transactions across the value chain, there are two applications of blockchain/DLT that the insurance industry should take a deep dive into.

  • The case for an internal coin/token

There is a lot of development and maturity in the realm of coins/tokens. How are these applicable for an insurance entity? One way to test these out is to create an internal coin. Such a coin could be for inter-entity transfer of value. This is especially useful for multi-country insurance entities that transact in inter-entity, multi-national currencies. There is a clear business case and ROI in such a scenario as currency exchanges could be minimized to avoid fees paid to banks.

  • The investment scenario

Insurance entities should also consider investing premium dollars in crypto assets. While these are risky investments, insurance entities invest in risky assets today. Investing in crypto assets can help the insurance entity learn and accept blockchain/DLT technology.

Conclusion

True disruption caused by blockchain/DLT technology of the insurance industry will take a long time. Resolution to many of the impediments and cultural acceptance via increased use of crypto assets will slowly improve adoption. Upstart and smaller insurtechs cannot make an immediate impact on the adoption of blockchain/DLT technologies, as it is a team sport and will require large number of insurance entities willing to participate beyond proofs of concept and pilots and enabling production implementations of  business capabilities.


Chak Kolli

Profile picture for user ChakKolli

Chak Kolli

Chak Kolli is the global chief technology officer for insurance at DXC Technology.

Kolli is responsible for DXC’s global insurance software product and services strategy and vision. He is also responsible for working with DXC’s insurance software clients as they use new and emerging technologies to transform their business. 

Prior to DXC Technology, Kolli led large global initiatives as a senior leader at TCS and AIG.

He has a Ph.D. in computer science from George Washington University.


How Low-Code Can Benefit Life Insurers

Off-the-shelf technology packages rarely produce exactly what an organization needs; with low-code, they can configure solutions to their unique needs.

Person writing code on a computer with a book titled "Python" beside them.

Improving customer experience is the greatest challenge facing the life insurance industry. Social media, the pandemic, technological innovations and e-commerce giants have pushed what it means to deliver fast and customized services that match consumer needs. Life insurers are working to meet these expectations and compete with new market entrants, but legacy technologies create barriers to innovation—including system incompatibilities that slow time-to-market. 

To address these issues, many life insurance companies are implementing low-code applications.

Low-code is an approach to software development that allows any employee to put together software applications to fulfill business needs. It requires a minimal amount of coding knowledge, which makes it easier for non-IT staff to solve business issues and create better experiences.

Key reasons life insurers are embracing the low-code approach

  1. They don’t have to rely on the vendor for changes

Low-code enables an insurer to configure the solution rapidly to bring products to market without the vendor having to change the underlying source code. This approach requires fewer resources, while increasing flexibility and responsiveness to changing conditions because new apps can be brought to market faster. 

  1. Many pre-packaged, static applications from outside vendors can’t be customized to meet organizational needs

Life insurers often rely on third-party vendors to address issues, given the limited bandwidth of internal IT departments. While these vendors might have a solution, they don’t always have the solution to solving the business problem in the exact way the company requires. 

This issue is particularly acute in the insurance industry, because most companies have a host of specific business processes that are unique to their organization. Generic vendor solutions are also often difficult to configure or customize in response to changing business requirements. Low-code applications give a life insurer greater flexibility and make them more responsive to changing regulations, market conditions or competitive pressures. 

  1. Low-code enables life insurers to more easily implement improvements to core systems after initial procurement

It is no secret that the insurance industry is hampered by a proliferation of tedious and repetitive manual processes carried out on idiosyncratic, company-specific systems. This makes insurers a rich source of low-code use cases. 

For example, no two insurers record and store information in the same way. Often, generalized vendor solutions need to create patches or workarounds in order for business processes to work. These types of jury-rigged solutions introduce the risk that data needed for important functions like underwriting decisions or audits could be lost. With a low-code platform, life insurers can easily customize, collect and store crucial information in the correct format without risk.

See also: Breathing Life Into Life Insurance

Wrap-up

Off-the-shelf technology packages rarely produce exactly what an organization needs; with low-code, businesses can more easily configure solutions to their unique needs. Low-code extends the life of core IT technology by enabling easier modification of components to enhance user experience and streamline processes. 


Olivier Lafontaine

Profile picture for user OlivierLafontaine

Olivier Lafontaine

Olivier Lafontaine is the chief product officer at Equisoft.

He has worked in virtually every role in the insurance technology industry, from software developer to product owner, to implementation consultant or program manager. He has experience developing commercial front-end and core insurance software and a proven track record consulting and managing large transformation projects for insurance companies.

Key Innovations for Agricultural Insurance

Insurers can lower operational costs, improve underwriting performance, offer appropriate insurance quotes and more effectively track the facts on the ground.

Rows of growing plants

The daily work of the world's farmers -- from a smallholder's one or two acres/hectares to major agribusinesses -- sustains us all. However, they face myriad challenges, not the least of which is access to agricultural insurance, due to constraints placed on insurance products and the complexity of assessing agricultural risks. Now, thanks to technological innovations, including better methods of crop data collection and agricultural intelligence (AgI) analyses, insurance companies can lower operational costs, improve underwriting performance, offer appropriate insurance quotes and more effectively track the facts on the ground.

Here are just a few ways digitization and other technologies can boost agricultural insurance:

Upgrade data collection

Digital, on-field data collection - with data points including time, location and user stamps - provides insights for effective underwriting and claims management while reducing operational costs.

Technology minimizes human errors and allows complex output, such as damage calculations based on the estimated value of the crops when a damaging event occurs, to be automated and flow seamlessly from the field to the decision-makers' desks, in real time.

These real-time insights improve the efficiency of insurance operations, while creating a structured database of on-field events, making it easier to spot patterns or irregularities that could focus in-person field inspections later.

Streamline quotation

Forget multiple forms and interminable waiting. Digitization at the point of sale smooths the application and quotation process and enhances user buy-in. AgI can be used to create risk models including more accurate quotations in the fields. This can lower premium costs as automation slashes administrative and operational expenses.

See also: Climate Change and Product Liability

Facilitate underwriting

Digitized field data makes it easier to analyze multiple geospatial data sets. Factor in altitude, soil type, climate history, claims history, etc., for a more complete picture of risk patterns. Moreover, the data sets can be used to determine individual risk -- by examining, for example, specific farms and comparing them with equivalent farms in the same region cultivating the same crops. Is one farm employing a different farming method that results in better harvests than the other farm? What are the other variables? These insights can help insurers select "good" risks, the key to achieving a profitable business line.

Optimize monitoring and claims management

Insurers get the critical insights they need to determine immediate and longer-term risk and know where to concentrate their resources using real-time data when tracking remote data sources such as vegetation indices from satellite and weather stations. Perhaps a remote field inspection based on the comparison of data from several insured farms may reveal that one is having issues others aren't experiencing. The insurer can then send someone for an in-person inspection to identify the key variables, whether it's a pest infestation, improper irrigation practices or any impediments to the farmer's success. Answers to these questions and more form the data that will prevent losses for all parties.

Enable farmer education

Lack of understanding by the farming community of the nitty gritty of agricultural insurance is one reason for their inability to access its benefits. For example, parametric insurance, in which payouts to the insured are based on outward or visible guidelines (e.g., level of rainfall) instead of measured and verified damages, may be a hard-to-digest concept for some farmers. Technology can go far in providing insurance education. Imagine a tool that can mimic payout situations to help farmers understand how to apply the parametric insurance concept to their real lives. This will be necessary to win over farmers and increase agricultural insurance's market penetration.

A focus on innovation at the farm and insurance levels can bring significant changes to the state of global agriculture, adding levels of stability to farming that were previously impossible. The more stable the agricultural environment, the easier it will be to maintain stronger supply chains focused on ensuring the world's growing population has enough to eat during these times of extreme climate change.


Arsira Thumaprudti

Profile picture for user ArsiraThumaprudti

Arsira Thumaprudti

Arsira Thumaprudti is the head of business development at Agritask, focusing on applying precision agriculture technologies in the smallholder context. She leads Agritask's business expansion in the public sector across the globe, including governments, multilateral organizations, and NGOs, with keen interest in value chain development and sustainability promotion. 

Thumaprudti has nearly 12 years of experience in finance, strategy and governance, having worked with investment management and advisory services in London and Bangkok. 

She has an MBA from the Wharton School at the University of Pennsylvania and a BA in economics from Harvard University.

Is Cyber Insurance on Brink of Collapse?

An industry that is too important to fail suffered claims of almost $7 billion in 2021 and now looks to take the lead in reducing client risk.

Close up of a computer screen with the word "Security."

The cyber insurance industry, battered by a seemingly unending onslaught of claims, is reaching a breaking point. According to the FBI’s latest Internet Crime Report, cyber-related complaints have increased by more than 180% over the last five years, resulting in $18.7 billion in losses. Last year, some carriers ended up paying out more in claims than they received from premiums. As a result, the industry is now demanding that customers reduce their exposure or face steep price increases or quite possibly cancellations. 

In an effort to shore up the industry, some insurance providers are taking a more hands-on approach in an effort to reduce their client’s risk. At the forefront is an attempt to mitigate human error, the crux of the problem. According to a 2021 Data Breach Investigations Report from Verizon, accidental clicks or other mistakes make up 85% of successful hacks. This has led insurers in search of cybersecurity training programs that have been independently verified to actually change human behavior.

No longer optional 

Survival of the cyber insurance industry is paramount. According to the National Cyber Security Alliance, 60% of small to medium-sized businesses (SMBs) fold within six months of a cyberattack. Yet, while SMBs cannot afford to go without cyber insurance, many soon won’t be able to afford the insurance itself.

Business owners and CEOs are feeling the seriousness of the situation when their renewal letters arrive. Premiums – which increased by as much as 300% in 2021, according to a report by Risk Placement Services – are expected to escalate at an even more dramatic pace. At the same time, insurers are adding exclusions and limiting coverage, and some are even exiting the market.   

“For some underwriters, the risk in offering cybersecurity coverage is simply too great at this point,” said Mark Weir, who has spent over 30 years in the insurance industry and is now managing director of LCM Solutions, a Canadian consulting firm. “In spite of the fact that taking risks is their business, insurance is an industry that doesn’t like uncertainty.” 

In the early days of cyber insurance, the one thing guaranteed was hefty profits. Insurance companies were eager to get into the market because demand was high and the perceived risk was low. 

“Initially, companies were offering cyber insurance thinking they would never actually have a claim,” explains Jeremy Harris, CEO of Mindshare IT, a managed service provider offering both IT and cybersecurity services. “Now they find themselves in a sticky situation and are looking for solutions.” 

In the past, almost all incidents were covered regardless of fault. Today, if a company fails to properly train employees or demonstrates poor security hygiene and gets hacked, its claim may be denied, and future access to coverage could be in jeopardy.

See also: Cyber Insurance Market Hardens

Dramatic rise in attacks

The cyber insurance industry may have become a victim of its own success. As insurers began to offer more coverage, businesses may not have felt the need to be as vigilant in their defenses. Often, they would quickly pay ransomware, assuming they would be reimbursed. As a result, cybercriminals had incentives to target companies with cyber insurance policies in place.

Now, with escalating attacks and shrinking coverage, insurers are trying to actuate companies to be more vigorous in reducing risk, including pushing for more stringent employee education on cybersecurity issues.

Many experts feel training is crucial to slow successful phishing breaches, which account for an overwhelming majority of attacks. Phishing, along with vishing (over the phone), smishing (via text) and pharming (visiting fraudulent websites), often leads to the deployment of malicious software, such as ransomware. 

A growing number of new regulations now require a number of industries to add education to their security programs, but some top executives question whether these generic training programs work as advertised.   

“Our view is training that does not impact risky behaviors is a waste of time and money for our clients,” says Kirsten Bay, CEO of Cysurance, which writes policies to protect against privacy breaches, identity theft, system damage and other cybercrimes.

Bay says Cysurance was looking for a training platform that took into account how different personality types perceive and respond to risks, such as an email with a link or attachment. The platform would then target those specific people with consistent, continuing training materials that would evoke a change in actions.  

“For us, the goal is to find proven ways to detect and prevent harm, which then lowers the risk of both a security event for our clients and also a future claim,” Bay explains. 

“I think what you're seeing with the better security training companies out there is that they really focus on the individual’s personality and train them accordingly,” Harris says. “Those that have metrics proving a reduction in potential breaches are rising to the top.”

Personalized behavioral training

Some personalized training programs have demonstrated they greatly reduce the rate of phishing failures. For example, at cyberconIQ, we have found we can cut failures from a national average rate of 15% to 18%, to less than 2% after just 30 days. We use a 40-question assessment, akin to a Myers-Briggs personality test, to assess the susceptibility of each employee. Then, we use machine learning to develop a customized approach for each, to correct key motivating factors that drive underlying online behavior and measurably lower their vulnerability to fraud.  

“What we look for is to develop a ‘culture of compliance,” Weir remarked. “However, what helps one person, may not be helpful to another. So, this idea of first evaluating the psychology of the individual and then educating that person based on their natural propensity is a game-changer. I think it is going to be what keeps the cyber insurance industry afloat.” 

By partnering with a cyber training company that provides verified proof of reducing claims, insurance companies can greatly minimize their risks and therefore reduce the costs of their coverages. 

“I give a lot of credit to those insurance companies who are smart enough to realize they have to help their clients mitigate risk,” Harris concludes. “It’s for the good of these small companies as well as the overall health of the cyber insurance industry.”


James Norrie

Profile picture for user JamesNorrie

James Norrie

Dr. James Norrie is the founder and CEO of cyberconIQ.

Norrie has more than 30 years of experience in business management, psychology and the cybersecurity industry.

He was the founding dean of the Graham School of Business at York College of Pennsylvania and is currently a tenured faculty member at the school.