Download

Is Hurricane Ian a Turning Point?

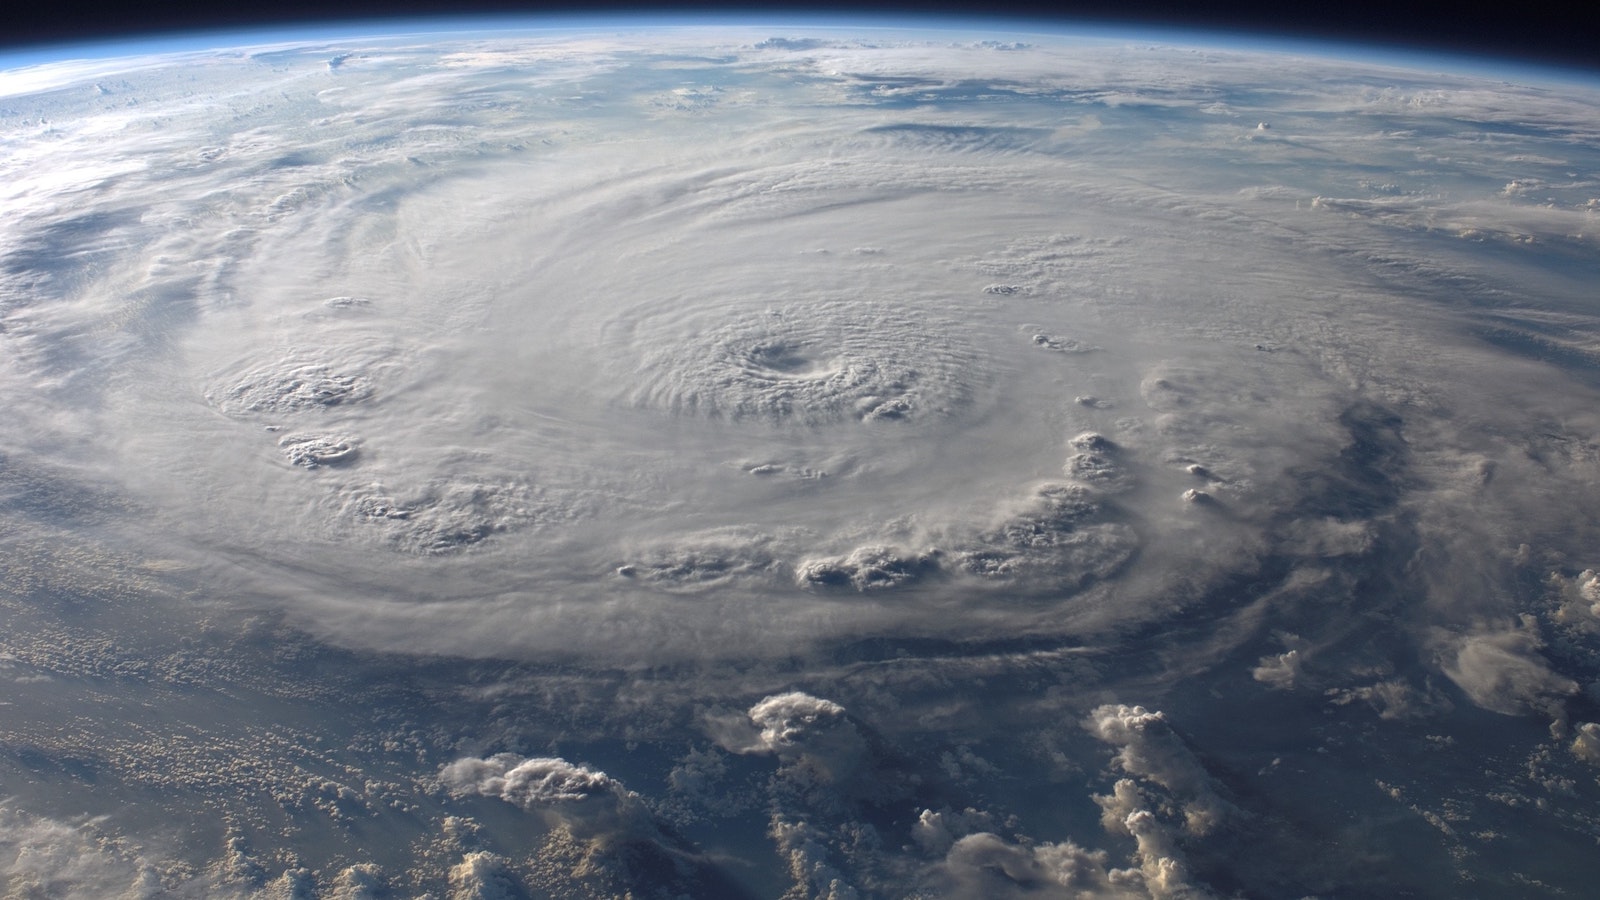
Although it will take time to sort through the wreckage of Hurricane Ian, it already seems clear it will mark a turning point in how we prepare for such mammoth storms.

Image
Truck in hurricane

Although it will take weeks and months to sort through the wreckage of Hurricane Ian, as the insurance industry helps the victims recover as best we can, one thing already seems clear, and it should finally mark a turning point in how we prepare for such mammoth storms. 

Ian makes it increasingly hard to deny that climate change is dangerous in the here and now. People will still argue about just how severe the effects will be in 2035 or 2050 or 2100 and will debate how much we should spend now to avoid those problems. But the climate-related acceleration of Ian into such a massive hurricane will force more people, even now, to confront hard choices about where they live, because more such behemoths are surely coming. And insurers will need to adapt.

The National Hurricane Center defines any storm whose winds increase by 35mph in 24 hours as a rapidly intensifying storm, and Hurricane Ian's winds accelerated 67% in 22 hours. (This article doesn't specify just how much that percentage meant in miles per hour, but, given that Hurricane Ian's winds hit 150mph right before landfall, the increase was somewhere around 60mph in less than a day.) 

The conditions that led up to that increase -- which were so noticeable forecasters called attention to them days ahead of time -- all relate to climate. In particular, the temperature of the water that Ian was crossing right before landfall was 1.8 degrees Fahrenheit hotter than normal, and that extra heat fed the intensity of the storm.

More generally, higher temperatures now reach deeper into the water, so hurricanes may no longer lose power as they suck up water from below the surface, where it used to be markedly cooler. Hotter air can hold more moisture, so hurricanes now can carry and then dump far more rain -- and water, not wind, causes most of the destruction in a hurricane. For good measure, larger hurricanes such as Ian are generally moving more slowly than in the past, so storms can hover and dump unimaginable amounts of rain -- as Hurricane Harvey did in 2017, unloading more than 60 inches of rain in some areas around Houston. 

What comes next will surely be chaos, even more than in the aftermath of most hurricanes -- and, despite all the attention to Florida, let's spare a thought for those in South Carolina who were hit as Hurricane Ian made landfall a second time, and for those in Puerto Rico, which was devastated by Hurricane Fiona, having never fully recovered from Hurricane Maria five years ago. 

The reason for the chaos is that Florida's homeowners market is dysfunctional. It accounted for 76% of all homeowners insurance lawsuits in the U.S. in 2021. Partly as a result, rates are about twice as high as the national average. Hundreds of thousands of people have lost insurance, either because the carriers won't write policies for them or because they can't afford the rates. 

But I'm hoping that we've passed a tipping point on climate denial and that some order will emerge from the chaos. 

Maybe some people will decide to take their insurance settlements and not rebuild in an area that is vulnerable to increasingly violent storms. Maybe many others will focus on increasing resilience to storms as they rebuild. 

Maybe many people, both in Florida and around the world, will have a "there but for the grace of God go I" moment and think about how they can fortify their homes before they face a disaster related to climate change. 

Maybe carriers and agents and brokers can offer guidance that steers clients away from risks and toward resilience.

Maybe the federal government, state governments and insurers can have a much-needed dialogue about who should bear the risk of catastrophes related to climate change -- based on the notion that we all obviously want to help the victims but that we also want to steer people toward safety and relieve some of the burdens of recovery, when some people, insurers or governments have to shell out an awful lot of money.

Or maybe not, of course.

Often, it seems, we have to undergo many "tipping points" before we finally get to the one that truly changes behaviors. But I, for one, hope Hurricane Ian can change a lot of minds.

Cheers,

Paul  


An Interview with Megan Roche Pilcher

Historically, automation and flexibility have been at opposite ends of a spectrum: The more you automate something, the less flexibility you have. But it doesn't have to be that way.

An Interview with Megan Pilcher

Megan Pilcher

Historically, automation and flexibility have been at opposite ends of a spectrum: The more you automate something, the less flexibility you have. But it doesn't have to be that way.

As Megan Roche Pilcher, SVP and insurance go-to-market leader at IntellectAI, explains, AI has progressed to the point that it can automate significant chunks of underwriting. It can eliminate the keying and rekeying that traditionally happened as a submission went through a series of steps that might eventually result in a proposal and bound policy. At the same time, AI can pull together third-party data to enhance what's in the submission and can steer underwriters toward key issues, while enhancing collaboration with others in the enterprise who've dealt with those issues before. That automation enhances flexibility by freeing underwriters to do the important work that only they can do. 

The flexibility is especially important in the insurance line that is our focus this month: cyber. It is changing so rapidly and unpredictably that we all have to stay our toes.


ITL:

IntellectAI is working with a lot of innovative MGAs and specialty carriers in the cyber insurance space. How are you—and they—seeing the market develop?

Megan Roche Pilcher:

There's a ton of opportunity for growth, and the cyber market is changing rapidly. Carriers and MGAs have to be able to respond quickly and appropriately with terms and conditions and pricing, to make sure they're providing the right coverage at the right premium for the accurate exposure.

Historically, the more flexible and responsive to the market carriers needed to be, the more they relied on manual processes to make this happen. People don't automatically think of insurance automation and flexibility together because of past experiences with old monolithic systems. But that's changed.

Underwriting discipline is critical—and automation can help. Technology using artificial intelligence and natural language processing is now available, removing much of the keying and rekeying of data, enabling carriers to home in on the risks they want to write and can win. With automation, underwriters can devote their attention to understanding how an organization uses and stores data, and properly assessing an organization's security posture. An underwriter needs time to really understand a risk's cyber exposure in order to adequately underwrite it. Technology can create this capacity.

ITL:

Can you paint a picture for us of how automation helps?

Roche Pilcher:

Often, current state looks like this: A risk comes in the door, and someone has to enter the account name, effective date, who the agent or broker is, the lines of business and so on into a tool for account clearance. Then, someone else will key in all of the same information, plus all of the exposure info, limits and deductibles, to rate the risk. A proposal has to be created...which usually means rekeying the same info into a Word document...updating it again if the account is bound. Finally, when the policy is issued, it often gets keyed into another system. Besides being heinously inefficient, all the rekeying impacts service to the agent, and is ripe for data inaccuracy.

Now let me tell you about the Utopia that we have enabled with technology. When a submission comes in the door it is automatically ingested and all of the relevant account, rating, and exposure information is extracted. AI is used, and knockout rules are applied to immediately decline submissions that are outside the insurer's appetite. This way no underwriter time is wasted on risks you have zero appetite for.

Then, we can run business rules against the extracted data to identify the remaining submissions that best meet the insurer’s target market.

ITL:

You're on a roll. Please keep going.

Roche Pilcher:

Now the underwriter enters the picture. They open their underwriting workbench and new submissions having the greatest chance of winning appear at the top. The underwriter clicks on the account and not only can they see all of the information in the applications, loss runs, and attachments but there is also risk score to indicate the network security and hardened control present in the organization. AI and third-party data enrich the submission information, highlighting exposures they might want to pay special attention to or ask the agent about.

Automation promotes collaboration, too. In manual processes, a lot of information just sits on an individual's desktop in Excel or a Word document. In our underwriting workbench, we have a tool that lets you look at "accounts like mine." It pulls up risks similar to the one you're looking at that have already been quoted, so you can gain from the experience of other underwriters in the organization. You can see how they’ve crafted insurance programs and what kind of pricing they've used.

With the click of a button, the risk is rated, and the underwriter can price the account and document as they go. The underwriting workbench identifies any places where the underwriter's authority has been exceeded and an automated referral process kicks in.

You can have all these very fluid business rules to make sure there's collaboration on the risks that require it. With one more click, a proposal is generated and emailed to the agent or broker.

ITL:

I imagine the reduction in drudgery could make underwriting jobs a lot more appealing to younger folks and help address the sorts of staffing issues that many companies are facing.

Roche Pilcher:

Definitely. Data entry isn't typically a coveted career path. That said, automation doesn't mean getting rid of people. What it does mean, is focusing people on meaningful and rewarding work, as well as revenue generating activities. Automation allows companies to focus on building a true underwriting career path that develops skills and a culture that allows them to retain talent.

There's a culture shift, too, as Gen Z enters the workforce. Their productivity is directly related to technology. They expect the latest tools and technology to do their jobs. Not manual workflows and Excel spreadsheets. They want to be developed and they want to grow.

ITL:

Final question: While you're focused on improving the underwriting process, how would you summarize the outlook for the market for cyber insurance?

Roche Pilcher:

Although Cyber insurance has been in the market for 20 years, there is now a heightened awareness of cyber risk especially with the looming threat of ransomware attacks. Cyber exposure has gone up. Frequency has gone up. Severity has gone up. So, you've got more opportunities in the marketplace. And companies are shopping to find the right balance of the coverage they need at a premium they are willing to pay.

Insurers really need to understand and think about where they want to play in the space of this opportunity.

In times of rapid growth, underwriting discipline is key. But underwriting discipline doesn't mean you have to go slower. Underwriting discipline means really focusing underwriters on the right risks and the right activities. Leveraging technology like artificial intelligence is becoming table stakes.

ITL:

Thanks, Megan.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

A Road Map to Insurtech Distribution

When it comes to insurance, customers trust people more than tech. Customers want a credible human partner throughout the buying process.

Person holding pen and paper

Despite strong investment in recent years, many direct-to-consumer (D2C) insurtechs aren't seeing the adoption they expected. One underlying cause: lack of customer trust.

When it comes to insurance, customers trust people more than tech. Buying insurance is a major decision, and customers want a credible human partner throughout the process.

To earn customers’ trust and scale distribution, it’s time to look for long-term solutions. Here, I’ll share my three-step road map to help insurtechs build trust and reach more customers.

Step 1: Partner With Independent Agents

I talk a lot about the power of independent agent partnerships. That’s because insurtechs have a genuine trust problem – and agents could be the key to overcoming it. 

Agents provide a human touch and industry know-how that tech can’t replace. 

When agents have face time and interact directly with customers, there’s a back-and-forth dynamic that builds rapport. That rapport builds a relationship. These relationships usher in trust, and customers trust their agent to deliver guidance that actually meets their needs.

In each conversation, agents can use their inside knowledge to deliver insights. They can even enlighten customers about things they don’t even realize they don’t know. For example, an agent could assess a customer’s wildfire risk before a consultation. Then, they could reassure customers about their insurance concerns – and ask follow-up questions about things the customer might not have mentioned.

With agents as partners, insurtechs can put a face to their brand name. The benefit: Through agents, insurtechs can build a foundation of trust with each customer, making it easier to win adoption across markets and retain business. 

Step 2: Get the Right Back-End Tech

Insurtech-agent partnerships are a two-way street. Agents can build and maintain customer trust – but only if they have the right tools.

Insurtechs can leverage their prowess to provide specialized back-end tech. The key here is to understand agents’ pain points. This way, each tool can actually meet their needs. 

The right back-end tech helps agents get better at the things they’re already good at. Tech-powered agents can pull from extensive historical and demographic data to deliver better guidance -- faster. With the time they save, agents can focus on customer conversations and provide personalized guidance at scale.

My suggestions on back-end tools insurtechs should invest in:

  • Quoting and binding tools. In minutes, agents can help their customers find personalized coverage based on location and demographic data.
  • Policy-writing software. Faster policy-writing helps agents reduce their customers’ coverage gaps.
  • Customer support tech. When agents aren’t available, a tech-enabled support team can answer policy questions fast.

Something to remember: Insurtechs don’t have to reinvent the wheel. Proprietary tech can play well alongside third-party software. With a few smart investments, insurtechs can tap into a ready-made knowledge base and quickly give agents the tech they need.

Step 3: Educate Customers About the Industry

Customers rarely understand everything about their insurance policy, much less the industry. But insurtechs can change that. By educating customers about insurance matters, insurtechs can empower them to make confident policy decisions.

There’s a clear business benefit, too: Education builds trust. An educational dynamic is collaborative – it helps customers feel like valuable partners. Educated customers are more apt to trust insurtechs to provide the right coverage. The reward: better customer loyalty.

See also: Insurtechs' Role in Transformation

Agents play an important role in the education process. When helpful resources come from a trusted agent (rather than an anonymous brand), customers are more likely to recognize the value and engage with the material.

Insurtechs and agents can educate customers about things such as:

  • Financial literacy. When customers know the financial basics, they can make smarter coverage choices.
  • Lines of business. Customers need to understand the coverage they have – and the coverage they might need.
  • Industry jargon. Once customers grasp complex terms, they’ll know how to ask the right policy questions. 
  • Local insurance news. Customers should understand how market dynamics affect their coverage.

Insurtechs can use digital tools to boost their educational efforts.

The Future of Insurtech Depends on Trust

Like many tech spaces right now, insurtechs are going through a shakeup because of plummeting valuations. To steady the waters, insurtechs have to prove they can deliver on their promises.

A new-and-improved distribution model can help. With the right approach, insurtechs can partner with agents to restore customers’ trust. The result: a model that keeps insurtechs competitive for the long haul.


Deb Franklin

Profile picture for user DebFranklin

Deb Franklin

Deb Franklin is the co-CEO of PEAK6 Insurtech, the insurance operations and technology subsidiary of PEAK6.

The company's first tech-based solution was developed in 1997 to optimize options trading, and, over the past two decades, the same formula has been used across a range of industries, asset classes and business stages. Today, PEAK6 seeks transformational opportunities to provide capital and strategic support to entrepreneurs and forward-thinking businesses, helping to unlock potential and activate what is into what ought to be.
 

How to Lift Profitability in Tough Times

Demand for commercial insurance is on the rise, but profitability remains elusive. Algorithmic data is the key to greater, granular insight into risks and prices.

Arrows on a road pointing fowards

While demand for commercial insurance is rising, profitability remains elusive for many insurers. A confluence of factors, including inflation, increased liability losses, climate change and gaps in market segmentation, are shrinking profit margins.

However, some market leaders in the industry outperform the competition by using an insurer’s greatest asset — data, both their own internal data and data from outside sources, to learn more about the exposures (e.g., people, physical assets, businesses) they are insuring. Embracing the most advanced data capabilities and deploying a surgical approach to assess and price risks improve performance.

The Trajectory

Industry experts see some reasons for optimism in the commercial insurance market — credit rating agency AM Best upgraded its 2022 commercial-lines market segment outlook to stable from negative for key segments, including commercial property insurance. However, in the near term, the industry faces several challenges related to profitability, including asset and social inflation, rising catastrophe losses and climate change.

Physical Damage Inflation. A spike in demand for goods over the past several years coupled with supply chain issues persisting throughout the pandemic has contributed to inflation rates not experienced for over 40 years. Replacement costs for vehicles and property are increasing as building materials and auto parts become more expensive. Additionally, a lack of available skilled labor to make the repairs contributes to the rising claims costs.

For example, auto repair costs rose 8% in July compared with a year earlier, and the price of auto parts and equipment rose 14%, according to the U.S. Bureau of Labor Statistics.

Labor Shortages. The American Trucking Association estimates the industry is short 80,000 drivers, a number that will double to 160,000 by 2030. An aging workforce and declining interest in truck driving are responsible. Many organizations have lowered driver application standards, which means that drivers with shorter (and riskier) driving records are entering the industry. Additionally, newer employees are more likely to have accidents on the road.

Liability Losses. While there was a slight reprieve for auto insurers during the height of the pandemic (when we experienced an abrupt drop in miles driven), lawsuits are back to increasing — as are the jury awards — as the nation begins to return to normal.

The average verdict size for truck accidents increased 1,000% over the last 10 years. As a result, emboldened plaintiffs’ attorneys are more likely to take the case to trial, extending case durations and raising costs for the insurer to defend a claim. Juries tend to favor the plaintiff on negligence claims.

Climate Change. The growing severity and frequency of natural disasters pose serious risks across the commercial property insurance market. After all, these catastrophes often leave behind severe property damage and associated losses.

Catastrophic losses from wildfires, hurricanes and other natural disasters attributable to climate change exacerbate inflation. In 2021, the National Oceanic and Atmospheric Administration (NOAA) recorded 20 weather and climate disasters in the U.S., each exceeding $1 billion, for a total price tag of $145 billion. Climate experts predict the frequency and severity of natural disasters will increase, affecting commercial insurance premiums.

See also: 4 Stages of Dominance in Performance

Lack of Data. The pricing of risks depends on the ability to collect accurate exposure details.

Early adopters in the market are gaining a segmentation advantage by using data to cherry-pick the premium risks and pricing those risks at a discount. They leave what they don’t want to the broader market.

With the broader market getting “adverse selected” and “out-segmented,” the quality of their portfolios is degrading. As a result, these carriers continue to write risks at an increasingly unprofitable rate in the face of other macroeconomic conditions already challenging their business — creating a profitability conundrum for commercial insurers.

Broad-Based and Surgical

Identifying specific segments in your commercial insurance lines with different risk characteristics is critical to improve profitability. Unfortunately, most carriers do not have sufficient data to identify granular segmentation.

Instead, insurers are left with little choice but to raise base rates, using a one-size-fits-all approach to pricing segmentation. They fail to make more segmented changes — treating the symptom, not the problem.

Imagine two apartment buildings with about the same number of residents and in roughly the same location. While they are nearly identical, one building is riskier to insure for nonweather-related damage. What’s the difference?

Typically, insurers treated every building similarly, using occupancy rates or geographic data to assess commercial property risk. The difference in the buildings comes down to having insight into the building occupants’ contribution to loss costs. Property and geographic conditions may vary over time, but the occupants of an apartment building fluctuate from year to year. Although the occupants of insured property are related to claims performance directly, premiums do not reflect the exposure, leading to a misalignment of the actual losses incurred and the expected losses.

As the example demonstrates, a broad-based approach toward raising the overall rate will not solve the underlying problems — the risk the occupants of each building present. To offer more competitive rates to the premium-priced risks, insurers must use a balanced approach of raising rates while also focusing on improving pricing granularity. Otherwise, your competition will still offer a lower price because they have the segmentation capability to assess the risks more completely.

Anecdotal Versus Algorithmic Data

To gain greater insight into risks and prices at a more granular level, insurers must use data to automate their processes. The benefits include:

  • Increased efficiency,
  • Accurate pricing,
  • Improved customer experience and
  • Reduction of overhead costs.

For example, a construction contractor looks at two insurers for a commercial policy. One uses an algorithm to obtain data systemically, while the other needs to involve an underwriter reliant on anecdotal data.

The algorithm produces a quote in less than 10 minutes, while the quote from the other carrier takes much longer. Even if the price from the algorithm is higher than the other carrier’s rates, customers still may choose the algorithmic quote over the other carrier because it takes less time — so it’s easier for them. Ultimately, ease of doing business often trumps rate.

In commercial auto insurance, increasingly available credit-based driver information, vehicle history data and court violation data enables insurers to create highly sophisticated rating processes that produce more accurate pricing and decision-making in a fraction of the time required of desk underwriters. The algorithm reduces expenses and improves rating granularity and accuracy, leading to increased profitability.

Road to Profitability

As the market leaders are demonstrating, the potential benefits of data — increased premiums, reduced expense ratios, shortened quote times leading to greater ease of doing business and improved risk assessment, among others — can give carriers a substantial edge in a challenging industry.

We Need to Care for the Caregivers

One in four Americans is caring for a loved one with a debilitating illness or other special needs. COVID-19 amplified the problem, and it will continue to grow. 

Grandparent with two young children

The latest census shows that the number of Americans over 65 has increased 34% over the last decade. Thanks to COVID-19, the economy and various other factors, more and more of this demographic are choosing to age at home. While some thrive, many have physical and mental health challenges that burden those who care for them.

My Story

I experienced the challenge of caring for a loved one with a debilitating illness when my mother-in-law was diagnosed with stage four lymphoma. My wife and I decided to care for her ourselves, allowing her to remain in familiar surroundings. While the care was a labor of love, we had to give so much of ourselves that it felt as if our lives were crumbling down around us. In many ways, they were.

Searching for hope, I stumbled across a self-assessment tool designed by researchers at the University of Wisconsin. I took it, thinking it would probably just recommend I place my mother-in-law in hospice care. Imagine my surprise when it advised marriage counseling because my risk factor for burnout was the toll caregiving was having on my marriage. The researchers identified a church just three blocks from our house that offered free family counseling sessions on Saturday mornings. The relatively simple, free solution gave us the strength to provide my mother-in-law with the care she needed while preserving our sanity and our marriage.

My family is not alone in this experience. One in four Americans is caring for a loved one with a debilitating illness or other special needs. COVID-19 amplified the problem. People were afraid to leave their loved ones, especially the elderly, in congregate living settings, such as nursing homes or assisted living facilities.

As an entrepreneur, I saw an opportunity for more people to benefit from the solution I found via the university online tool. In developing a solution, my goal was to get to the root cause of caregiver burnout rather than providing temporary relief.

During the development of the TCARE solution, it became clear that support for caregivers is usually discussed in the insurance industry in terms of providing homecare, respite care or placement in a facility. The hundreds of primary caregivers we've interviewed also tend to think about support that way because they usually don't know what other options are available. However, a care receiver can often benefit from staying in their home longer and being in close contact with loved ones and familiar surroundings.

See also: Solving Life Insurance Coverage Gap

Solving the root problem of addressing caregiver burnout offers tremendous benefits for both the care receiver and the caregiver, and the caregiver doesn't feel as if they're letting their loved one down. While the lives of caregivers may be significantly altered, with the right support they don't have to feel as if they're being destroyed.

Addressing Insurers' Needs

To fully assess caregivers' needs, we created a motivational interview process. We identified that working with insurance companies would help us reach the most people in the most productive way. Partnering with organizations like RGAX, we were able to explore how preventing caregiver burnout would allow insurers to improve their cost structure by decreasing use of long-term care and delaying placement in a nursing home or assisted-living facility.

We didn't want to increase the burden on case managers, as they already have enough on their plates. So, once we know who the primary caregiver is, we partner with insurers to do outreach, letting customers know they're eligible to use the TCARE service at no cost to them. If they agree, we conduct a roughly 25-minute interview that gets to the root cause of burnout and assigns a score to the individual's risk. In collaboration with TCARE's AI and machine learning technology, the TCARE specialist will create a care plan and identify interventions and local and virtual resources, many available at no cost.

See also: The Doctor Is in Your Device

After the initial counseling session, caregivers are sent weekly automated text messages to see if there has been a change in their caregiving situation. If there has, our system alerts the TCARE specialist to reach out to the caregiver and adjust the care plan as needed. These alerts facilitate crisis prevention rather than crisis intervention. 

Real World/Real Problems

One client, for instance, was struggling to provide the care her mother needed as she suffered from dementia. She was taking considerable time off work to provide for her mother's basic needs, which was taking a toll on her career. When she was laid off, and family financial resources grew strained, she reached out to a TCARE specialist, who let her know that Medicare could help her pay for some of her mother's basic needs. The specialist set her up with weekly food deliveries and transportation services to help get her mother to and from her weekly appointments.

Another example is a woman whose husband died by suicide, leaving her to care, alone, for their child with special needs. The day-to-day struggle became overwhelming, and she started having suicidal thoughts herself. When she reached out to TCARE, the 25-minute interview became a two-hour conversation. She was in the red zone and needed someone to talk to. After taking care of the woman's immediate mental health needs, the specialist set her up with respite services, which include overnight services, so that she could have the time she needed for self-care. The specialist connects with her regularly to make sure she is stable and finding time to take care of herself.

A Problem That Demands a Solution

With more people living longer, the number of those caring for a loved one with special needs will likely increase. The caregivers will need all the care we can give them. 


Ali Ahmadi

Profile picture for user AliAhmadi

Ali Ahmadi

Ali Ahmadi is the CEO/co-Founder of TCARE, a venture-backed tool that uses predictive analytics to prevent burnout among family caregivers.

He is a three-time veteran of venture-backed tech startups, with more than $15 million raised in institutional capital, and has over 16 years of business development experience in various industries, including power/energy, aerospace and military/government.

October ITL Focus: Cyber Threats

ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.

This month, we're focusing on Cyber Threats

cyber threats banner
Copy
 

FROM THE EDITOR 

The cyber insurance market is full of good news and bad news, good news and bad news, good news and bad news.

Let's start with the good news.

Targets are getting smarter about how to defend themselves. That's by far the biggest bit of good news. The improved defense is partly because employees are being trained to avoid phishing and other types of attacks. There is also a shift in focus away from relying on fire walls -- which aim to keep hackers outside the perimeter of IT systems but seemingly can all be breached if a hacker is determined enough, at which point the hacker has free rein. Instead, companies are adopting what's referred to as "trust no one" approach. That means that even someone who has presented credentials and is inside a firewall is assumed to be a potential danger and is continually challenged to authenticate himself. Defense has, in fact, improved to the point that the Ukrainians, in particular, and the world, in general, have blunted a wave of hacking attempts by Russians following the invasion of Ukraine in February.

Governments have begun to see cyber attacks as threats to national security, not just issues for the private sector, and are beginning to help. Among other things, they've figured out ways to track and recover the cryptocurrencies that are hackers' favored mechanism for ransom payments. Removing the anonymity should act as a deterrent.

As companies take the cyber threat more seriously, they are also protecting themselves by buying much more cyber insurance.

The insurance industry is leaning into the need by lining up much more capital to back cyber insurance and by helping customers better protect themselves.

Now for the bad news:

Hackers are getting smarter, too, and they are relentless in the face of a massive opportunity to enrich themselves.

In other words: no rest for the weary.

Cheers,
Paul


Historically, automation and flexibility have been at opposite ends of a spectrum: The more you automate something, the less flexibility you have. But it doesn't have to be that way.

As Megan Roche Pilcher, SVP and insurance go-to-market leader at IntellectAI, explains, AI has progressed to the point that it can automate significant chunks of underwriting. It can eliminate the keying and rekeying that traditionally happened as a submission went through a series of steps that might eventually result in a proposal and bound policy. At the same time, AI can pull together third-party data to enhance what's in the submission and can steer underwriters toward key issues, while enhancing collaboration with others in the enterprise who've dealt with those issues before. That automation enhances flexibility by freeing underwriters to do the important work that only they can do.

The flexibility is especially important in the insurance line that is our focus this month: cyber. It is changing so rapidly and unpredictably that we all have to stay our toes.

Read the Full Interview

"Historically, the more flexible and responsive to the market carriers needed to be, the more they relied on manual processes to make this happen. People don’t automatically think of insurance automation and flexibility together because of past experiences with old, monolithic systems. But that’s changed." 

—Megan Roche Pilcher
Read the Full Interview
 

READ MORE


Is Cyber Insurance on Brink
of Collapse?

An industry that is too important to fail suffered claims of almost $7 billion in 2021 and now looks to take the lead in reducing client risk.

Read More

The Cyber Insurance Market Hardens

While the cyber market improved significantly in 2021, increases to prior-year reserves may cause a drag on earnings, and the Russian invasion of Ukraine creates uncertainty.

Read More

The Challenge of Quantum Resilience

Quantum computing, in the wrong hands, could create a multitude of digital risks, including advanced cyberattacks -- a significant problem for the insurance industry.

Read More

The Weak Point in Cyber
Security

The best place to start is by securing a well-known defensive weak point: privileged access that has administrator-level powers.

Read More

Coping With Insider and Outsider Fraud

Recent macroeconomic events involving supply chain slowdowns, flexible work arrangements and rising inflation have paved the way for a possible uptick in crime.

Read More

WINNING STRATEGIES TO TRANSFORM COMMERCIAL UNDERWRITING FOR INSURANCE CARRIERS, MGAS AND BROKERS: AI ADOPTION IN INSURANCE

Sponsored by IntellectAI

As the insurance industry continues to transform, insurance carriers are finding success without having to solve a complex set of problems in their transformation. With the right technology in place, today’s insurance carriers, MGAs and brokers can transform commercial underwriting to make it simple and insightful.

View Webinar


FEATURED THOUGHT LEADERS


This Month Sponsored by: Intellect AI

IntellectAI is a suite of contemporary artificial intelligence products and data insights triangulated from thousands of sources for commercial underwriting offered through Intellect Design.  The IntellectAI products take a strategic approach to tackling the biggest challenges for the industry. We are a proven leader in Data First Strategy for commercial underwriting.  

Our underlying technology powers sophistication with simplicity ensuring an engaging and insightful user journey. Our AI cloud native products are known to address the most complex business objectives with the highest accuracy of outcome. Our skilled technical experts and data scientists seamlessly augment our customer teams to accelerate their transformation journey easily adapting as business models and technology evolves. www.intellectai.com


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

How to Prepare for Catastrophe Claims

By improving weather modeling and assessing past catastrophes, insurers can use predictive analytics to provide better support to customers during difficult times. 

Photo of a hurricane

Climate change is affecting almost everyone in every region throughout the world. Whether it’s hurricanes off the Atlantic coast, flooding in Louisiana, hailstorms and tornadoes in the Midwest or wildfires in the West, climate change is forcing insurers to re-examine how they prepare for and support catastrophe claims.

Recent reports from the National Oceanic and Atmospheric Administration (NOAA) predict with 70% accuracy that the hurricanes that hit the U.S. this year will be major ones – category 3, 4 or 5, with winds of 111 mph or higher. (Hurricane Ian is currently expected to be a Category 4 hurricane when it hits the Gulf Coast of Florida this week.) The intense storms present multiple challenges for insurers, including how to manage the rising number of catastrophe claims. 

For insurance companies to provide the support that their customers need, it’s critical to leverage technologies that improve weather modeling. This helps insurers adapt to weather-related catastrophes and improve how they make decisions. By improving weather modeling and analyzing data and damage from past weather catastrophes, insurers can provide better support (both virtually and in-person) to customers during difficult times. 

Leveraging predictive analytics

One form of technology that insurers are using to improve the claims process is predictive analytics. Predictive analytics analyze and interpret vast amounts of data to help predict outcomes so insurers can help customers make changes in advance to mitigate risk. Leveraging predictive analytics helps insurers rethink their business models to innovate, improve business processes and enhance customer experiences. The industry is already moving in this direction as 53% of risk businesses are using predictive analytics for pricing and product innovation.

See also: Top 2022 Global Business Risks

For insurers to streamline their business processes and provide better support to their customers, consider the following three strategies. 

1) Build a system that can quickly scale and mobilize your team

In many cases, we know when a hurricane or severe storm is going to hit. Insurance companies must be prepared to ramp up support activities on a massive scale in a short time. This means having plans in place to mobilize teams and service providers. By incorporating predictive analytics into the planning process, insurers can determine how many field support experts are needed, where to send them and what resources they need.

During a recent hurricane season, we already had a plan in place, working on behalf of multiple insurers. Claims adjusters were equipped with computers, augmented reality and virtual inspection tools to speed up inspections and processing. We supported thousands of claims across hundreds of miles of devastated towns, which included deploying teams to the hardest-hit areas. 

2) Plan for feet on the ground and logistical support

When hundreds of people enter a region that has been devastated by a natural disaster, logistical support becomes crucial. When developing a blueprint for on-site support, consider the following areas of need:

  • Are adjusters trained in specific areas such as coastal or mountain regions? Do they have experience dealing with hurricanes, tornadoes or earthquakes?
  • Is your internal IT team equipped to support a massive amount of data collection and analysis in real time?
  • Are there enough generators, vehicles, food/water and places to stay for field support teams? For example, during one extreme weather event, we had an extra 150 to 200 people at headquarters on standby to support the extra 400 people we had on-site.

Training programs that are continually updated with the latest analysis of recent disasters help hone support programs. As weather-related catastrophes continue to increase, it’s important to make sure that insurers are prepared for multiple disasters simultaneously. 

3) Equip your team with advanced IT support

Predictive analytics can alert local authorities as to where the areas of devastation will be, when to evacuate and what areas to avoid. The supporting technology applications that insurers use on the ground and back in the office to provide the information needed to support customers is vital. 

Prioritize regularly updating guidelines for all teams based on new experiences when supporting customers following natural disasters. For instance, we use inspection tools so our claims adjusters can take photos and upload them while in the field to expediate processing. Similarly, using cost-estimate platforms, which are based on data run through predictive analytics programs, means adjusters can give estimates on payment information to customers in real time. This promotes efficiency and helps provide emotional support to customers who are concerned about how long it will take to repair their house or vehicle. 

A new form of technology that we’re using frequently is virtual inspections. This self-service tool helps alleviate the burden on local agents as well as in smaller communities that are far away from where the event (hurricane, tornado, etc.) occurred. While there might be less damage in a town 500 miles away from the impact area, those communities need support. Having customers upload images or show damage via a camera in real time means an agent who is stationed at headquarters can view the damage and help support customers. 

One example is the winter storm that covered Texas in mid-February 2021, where hundreds of thousands of insurance claims were filed for home and property damage. To effectively organize and assess the claims process, we stepped in to help insurers respond.

With claims from the state estimated to cost between $10 billion and $20 billion, multiple stakeholders were overwhelmed, including insurance companies, supply chains and providers. We enabled customers to use mobile applications on their phones and mobile devices to upload photos and 3D models to provide more detail of the claims, resulting in faster claims processing and faster payouts to customers.

Learn from past catastrophes

Leveraging predictive analytics is critical for insurance companies to prepare for increasingly devastating weather-related catastrophes. Learning from each climate catastrophe helps insurers provide better logistical and IT support that reduces the time to mobilize a task force to support customers.

In the end, it’s all about providing customers with the support they need in times of crisis.

An Often-Overlooked Business Interruption Risk

A great many companies don't realize they rely on critical web-service suppliers, but when the technology goes down, business may grind to a halt.

Person typing on a computer

A handful of tech firms ensure the smooth operation of millions of businesses world-wide. A great many companies may not even realize that they rely on these critical web-service suppliers, but when the technology goes down, business may grind to a halt. To compound the problem, some of these background web companies depend on the services of yet others, which creates a complex web of potential contagion. For cyber insurers and their reinsurers, the contingent business interruption (CBI) aggregation risk is enormous.

The companies are the cloud service providers (CSPs) and content delivery networks (CDNs) that make the internet work. They support billions of dollars of commerce and services every day. AWS (Amazon Web Services) is the leading CSP, with about 40% market share and more than one million customers. More than 95% of the Fortune 500 rely on Azure, Microsoft's CSP, at least to a certain extent. Cloudflare is used by about 150,000 clients. Google Cloud Services sits behind Shopify, the e-commerce platform relied upon by about 800,000 merchants in the U.S. alone.

These, along with other CSPs and other service providers, form the backbone of the technology and infrastructure that allows the internet - and therefore the modern economy - to work. When they're operational, they ensure that e-commerce, from online banking to pizza delivery orders, functions effortlessly and almost instantly. Unfortunately, they go down with alarming frequency. Major vendors that suffered at least one outage this year include AWS, Fiserv, Shopify, Azure, Cloudflare, Google Cloud, IBM and Verizon. One service interruption happened because a cable was inadvertently cut. Another occurred when the air conditioning shut down.

See also: Essential Steps for Cyber Insurance

Traditional business interruption (BI) insurance covers losses arising when something the insured does or suffers causes a systems problem that brings normal business to halt. Contingent BI, also known as Dependent BI, is a subclass that protects insureds when something goes wrong at a third-party service provider and their shutdown causes the insured's business to stop in its tracks.

It's a complicated risk to assess at the best of times, but it's made fiendishly more difficult when the third parties are CSPs and CDNs. Worse, because an outage at one of the big players can affect hundreds or thousands of insured firms, the potential aggregation - especially for reinsurers - is gigantic.

Cyber insurers' reactions to the threat naturally vary. Some have lengthened the time the outage must last before coverage kicks in, effectively increasing the self-insured retention. Others have imposed low sub-limits that cap the indemnity payable to a fixed maximum that may be much lower than the insured's actual loss. The third option is to exclude CBI cover for CSPs and CDNs. The fourth and most extreme reaction is to remove DBI coverage altogether.

The widespread reluctance to cover cloud outages and distribution network interruptions is understandable. It is very difficult to gain a clear vision of all clients' true exposure to specific services. It is even more difficult to garner a granular view of the nature of the exposure; the insured can sometimes name their service provider but often don't know the specific service provided or the regional sub-service that delivers it.

Historical data about the services consumed is typically very limited or absent, which leaves insurers unable to model individual risks, let alone the threat of aggregation. And, because the risk lies with third parties, it is impossible to differentiate among insureds based on their systems architecture, infrastructure or controls. As a result, accumulations of exposures, particularly around market-dominating service providers, cannot easily be managed effectively.

There are several strategies to tame these challenges. Foremost is understanding: Downtime policies should cover specific, named services. Secondly, each risk should be underwritten individually. This is a necessity, because not all risks are insurable. Some service providers' reliability is not up to par, and sometimes an insurer must manage its own accumulation. Insureds presenting a higher accumulation risk may face higher premiums or longer downtimes before coverage is triggered. These measures allow downtime insurers to limit accumulation risk. That goes both ways, though, because customers using service suppliers outside those that present the largest accumulations pay less and benefit from shorter self-insured interruptions.

These accumulation management measures are important, but the heart of downtime insurance should be cloud monitoring. Downtime insurers should watch the CSPs and CDNs constantly, in real time, to see their performance and detect dependencies and know about clients' interruptions as soon as they happen. That monitoring allows downtime insurers to offer Cyber CBI insurance products on a parametric basis. When the cloud or network used by a specific customer goes down long enough to trigger a claim, the downtime insurer should tell them. It's simple and efficient and helps the world get back to business as usual with as little disruption as possible.


Yonatan Hatzor

Profile picture for user YonatanHatzor

Yonatan Hatzor

Yonatan Hatzor is a successful entrepreneur.

He co-founded Parametrix in 2018 based on his realization that cloud downtime was a growing, unaddressed risk for businesses. He first built the technology to collect and analyze data, and based on that was able to get the backing of major insurers and to offer a first-of-its-kind cloud downtime insurance product. The new policies earned the trust and backing of the largest global insurers and are protecting hundreds of businesses from the damages of third-party IT failure.

Prior to creating Parametrix, Hatzor built Matter, which developed technology to visualize properties using 3D imagery, to create virtual tours. Three years later, his company was acquired by Treedis.

The Big Aha From InsureTech Connect

Embedded insurance showed up almost everywhere, as executives talked about building APIs to connect seamlessly with partners.

Image
bartender

The theme from last week's InsureTech Connect in Las Vegas crystallized for me when an insurtech executive, sipping on a glass of wine, told me he thought bartenders would make the best insurance agents. 

Think about it for a second. Even leaving aside that people tend to let their guards down after they've had a couple of drinks, bartenders know a lot about the wants and needs of their regular customers. Bartenders also have lots of leeway to offer advice. It tends to be along the lines of "Dump the guy" or "Don't dump the guy," or "Quit the job" or "Don't quit the job," but why couldn't the advice go further? 

Imagine a bartender saying, "You know, a lot of people these days don't carry any personal life insurance or don't carry enough to support their families if they get run over by a truck. Life insurance for somebody your age is a lot cheaper than you think...."

While the idea of bartender-agents is fanciful, the notion brought home to me what I saw as the theme of ITC: embedded insurance. 

That theme showed up throughout the conference, where almost every executive I met with talked about how their company was building application programming interfaces (APIs) to connect seamlessly with partners. Many executives cited examples of embedding insurance offerings in the sales of other products -- offering insurance for an engagement ring while the couple is still at the jeweler's, offering specialized auto insurance that can be purchased with just four taps on a phone when a driver signs on with a ride-sharing company in the U.K., etc. An executive from Credit Karma told me about how the company is using its relationships with its more than 100 million members in the U.S. to engage them about insurance.

While I was at the conference, Next Insurance and Intuit underscored the embedded theme by announcing that small businesses and accountants would be able to buy numerous insurance products without ever leaving the QuickBooks ecosystem, in which they spend so much time thinking about financial considerations. This follows Next's announcement with Amazon a year ago, where Amazon is offering product liability insurance to the massive number of small businesses that sell products through it. (I continue to think that relationship could spread and have a major effect on insurance, as I wrote here.)

The recent examples build on others that have drawn attention in the past couple of years, such as the ability to sell renter's insurance as part of the process of renting the apartment, the increased availability of warranties when someone buys a phone or other expensive device and, of course, the continued success of Exhibit A for embedded insurance: travel insurance. 

It seems to me that one of the shibboleths of the insurance industry is being turned on its head. We've all been told that insurance is sold, not bought. Increasingly, though, insurance will be bought, not sold -- at least if companies can position themselves in the middle of the purchase of something that triggers a thought about the need for insurance.

Cheers,

Paul
P.S. If you'd like to read more about embedded insurance, I'd recommend these articles that we've published over the past year or so:

Embedded Insurance: The Hot New Topic

Embedded Insurance Reaches Tipping Point

The Recipe for Embedded Insurance

Embedded Insurance -- Both Old and New

How Dark Data Can Shed Light on Risk

Understanding your dark data can reveal insights into customers and employees, the quality of your assets and manufacturing and the risks your brand faces on social media.

photo showing network technology data

There’s not a company on the planet that isn’t generating and collecting data in some way. Today alone, the world will generate trillions upon trillions of bits of information. But there’s a problem with gathering all that data: It’s way too much for companies and their chief data officers (CDOs) to handle — and way too much for people to comprehend.

Much of what’s collected is called dark data, information that’s collected but never used. In our experience, dark data makes up most of the information companies collect. Unstructured data — videos, images, emails and other points that can’t be inserted into a spreadsheet — falls into this category, but businesses also collect a lot of information that for one reason or another never gets analyzed.

What’s exciting is that while a lot of valuable data is considered dark, when brought to light it can reveal real insights into the wants and needs of your organization, including around your customers and employees, the quality of your assets and manufacturing and the risks your brand faces on social media.

More dark data ahead

CDOs need to get a handle on their dark data now, as their companies are gathering increasing amounts of information every day. Businesses are putting data-collecting sensors on pretty much everything — industrial equipment, agricultural fields, office building walls and people’s wrists. They’re using drones to measure climate impacts and snap pictures of assets, while artificial intelligence (AI) technology is finding data points in minutes rather than the days, weeks or years it used to take to uncover.

While companies don’t need to analyze every number or statistic that comes their way, they also shouldn’t continue keeping all this data in the dark.

A lot of this is potentially valuable information that can be used to increase productivity and boost growth. And not knowing what’s there can pose significant risks.

Say a utility has sensors on its equipment to detect gas leaks, and a safety incident occurs. Now suppose that there was information hidden in the dark data those sensors collected that could have been used to predict and prevent the incident, but the utility never looked at that data. Having the data available but unused could bring lawsuits or a public relations nightmare.

Or take a bank dealing with a fraud case. An analysis of its dark data might have revealed red flags that would have prevented the breach. Worse, regulators — who now have a much better understanding of the data companies collect — might be unimpressed with a bank defending itself with, “How could we have known that was coming?” Regulators expect businesses to use all the tools they have to prevent fraud and generally crack down if they see something that a company missed.

How can companies make their data more visible? Here are some ideas:

Get a handle on all your information

  • Know what’s being gathered and where it’s being stored.
  • Then decide whether it’s useful to the business or not.

Understand your risks

  • Start by identifying the risks in your business that require you to take action to address. Risks could include becoming more compliant with certain industry regulations, fixing holes in your cybersecurity defenses or better understanding when equipment might break down.
  • Once you know the risks and what actions you must take to fix them, start identifying what kind of dark data will help. 

Use AI tools to parse data

  • Use artificial intelligence tools that can identify patterns in photos, detect irregularities in sensor data and uncover other hard-to-find insights. A lot of data, whether it’s images, weather patterns or vibrations, can’t be interpreted by the average person. The volume of information will be overwhelming, and humans won’t be able to understand all of the anomalies in the information.

Get excited about data

  • Understand how data can elevate business performance. Business leaders should take a keen interest in all kinds of data, not just what they can see in front of them. 
  • Create data lakes where structured and unstructured information gets stored. 

The more data that your company can analyze, the better decisions you’ll make. While it’s important to not get overloaded with information — keep going back to your business objectives and the risks you’re accounting for to determine what to observe — you should still be aware of what you’re collecting.

As companies become even more data-focused, and as new tools emerge to help people analyze their unstructured information, it’s only a matter of time before your dark data gets out in the open. The companies that use their data to their advantage can be the ones that get ahead.

This article first appeared on PwC's website here.


Matt Labovich

Profile picture for user MattLabovich

Matt Labovich

Matt Labovich leads PwC's Analytics Insights practice.

The team delivers integrated data strategies — data platform implementation and governance, visualization capabilities and advanced data science and automation services.