Download

How Gen AI Will Revolutionize Claims

In workers’ comp, generative AI can transform claims management by improving accuracy, enhancing documentation and, freeing adjusters to focus more on the injured workers.

An artist’s illustration of artificial intelligence (AI).

According to a recent report, 38% of insurance CEOs are embarking on generative AI initiatives, and 34% of surveyed companies have already incorporated this technology into existing workflows. While the rapid development of large language models leaves room for discoveries, this survey and others present a clear picture of generative AI’s potential value for the insurance industry.

In workers’ compensation, generative AI has the power to transform claims management by improving decision-making accuracy, enhancing documentation and, most importantly, freeing time for adjusters to focus on helping injured workers get the care they need quickly. This will ultimately accelerate return to work and protect an employer’s brand. Generative AI can equip staff with more robust data, leading to enhanced predictive models to optimize and reduce emerging risks. 

Let’s explore where generative AI makes the greatest impact in claims management and how AI-friendly workplaces can augment human insights and empower claims professionals to work at their highest professional standard. 

See also: The Dawn of Gen AI In Insurance

Revolutionizing Efficiency

A chief insight of the report is the belief held by nearly 80% of respondents that generative AI will significantly increase operational and process efficiencies. This capability stems from the power of large language models (LLMs) to digest vast amounts of information, detect patterns often hidden to the human eye and generate insights and reports. As adjuster workloads have historically been composed of manual processes, the power of generative AI to streamline claims processing represents the transformation of an entire industry. 

When adjusters receive a claim, the information found in the accompanying medical records tells a story that will determine the direction of the claim and the resulting next steps. In current cases, generative AI tools can read and digest this complex medical information, produce concise summaries of key highlights and propose actions. This utility is taken one step further by the power of LLMs to extract unstructured data from medical documents for quick updates on claims management platforms. This helps ensure that all stakeholders are apprised of the status of the current claim. In addition, adjusters can leverage generative AI’s rapid processing capabilities to answer queries in context, sidestepping searching what could be copious amounts of documents for answers. 

The efficiencies realized from incorporating generative AI tools into claims workflows translate into time savings, increased productivity and more accurate decision-making. By automating repetitive tasks, professionals can focus on more complex cases, enhance customer service and satisfaction and ultimately improve injured worker outcomes. 

Improving Outcomes 

When adjusters automate and streamline high-volume, manual claims processing tasks with generative AI, they can devote additional time to strategic work, such as directly engaging with injured workers, conducting comprehensive investigations and delivering personalized assistance throughout the claims journey. These personalized interactions and faster claims processing times enable injured workers to be quickly connected with care resources and embark on their recovery journey. In addition, by leveraging generative AI’s power to derive insights from medical documentation, adjusters can equip clinicians and insurers with pertinent information about workers’ injuries and health history, further removing communication silos between key stakeholders on workers’ care teams. 

Experiencing delays in getting an appointment and navigating insurance processes are common challenges many encounter within the U.S. healthcare system. For injured workers who may be unfamiliar with the workers’ compensation process, these poor experiences can easily be compounded, leading to fragmented care and delayed recovery. By accelerating claims processing and streamlining communications, generative AI places injured workers at the center of the claims journey and influences better experiences, enhanced care outcomes and faster return to work.

See also: How Gen AI Changes Everything in 2024

Transforming the Role of Claims Adjuster   

Generative AI not only has the power to transform injured worker outcomes but can also revamp and expand the role of the adjuster. As adjusters leverage advanced technology to equip injured workers with care, these professionals are empowered to understand their role as more than just processing documents; they can effect real change in the lives of injured workers. Over the next five years, as adjusters increasingly rely on generative AI to handle routine tasks and streamline processes, we will see the role of the adjuster focus on highe-value tasks such as strategic decision-making and customer relationship management. 

To support adjusters’ evolving role, third-party administrators (TPAs) and insurers will be called to prioritize generative AI training and education to ensure the effective use of these tools. Learning models such as hands-on workshops, online courses and continuous skill development programs will enhance understanding and proficiency in using AI for claims management. The key to promoting AI best practices is highlighting the importance of using AI as a supportive function rather than a worker replacement. This perspective, known as “augmented AI," refers to using AI technologies to enhance human capabilities rather than replace them entirely. While AI has the benefit of streamlining processes and providing actionable insights, human oversight and empathy remain critical to claiming success. 

Considerations and Looking Ahead

As with any new process or implementation, TPAs and insurance leaders can expect to encounter challenges with integrating generative AI into claims processing workflows. These challenges include data privacy concerns, ensuring the accuracy and reliability of AI-generated insights, employee resistance to change and regulatory compliance considerations. Leaders can navigate these obstacles by investing in robust data security measures, providing comprehensive training and support, collaborating with regulators to ensure compliance and, most importantly, proactively addressing concerns. 

The future is bright for generative AI in claims management, and we can expect long-term uses to include automation of the entire claims processing cycle. While industry-leading TPAs are already revolutionizing efficiency in medical document review, future iterations may further automate claims processing tasks, learn from past claims to generate new information, enhance fraud detection and improve customer service through AI-powered chatbots. 


Jeff Gurtcheff

Profile picture for user JeffGurtcheff

Jeff Gurtcheff

Jeff Gurtcheff is CorVel's chief claims officer. 

He has more than 30 years of experience in the industry, spanning the third-party administrator space, independent insurance and the carrier market.

Gurtcheff received his bachelor's in business administration/finance from the University of Iowa.

Gamify Data Management for Clear Business Insights

Many agents wonder why they should triple check if data fields are filled in correctly. This is where gamification kicks in.

An artist’s illustration of artificial intelligence (AI)

Have you ever found yourself hastily typing during a client call, trying to complete the system’s mandatory data fields and bypassing fields to save time? You might find yourself thinking, “I’ll go back and fill that out later.” But when this happens repeatedly and across the entire agency, it can lead to a data cleanliness issue.  

A study by IBM reports businesses can lose up to 20% in revenue for poor data quality. Simply put, better data quality can influence every part of an agency’s business, from client retention to overall growth. 

A data management plan is the systematic and strategic handling of large amounts of data that agencies generate, collect and process in their operations.

The benefits of a successful data management plan can include:   

  • Clear visibility into cross-selling opportunities.
  • Renewal improvement with auto-delivered information.
  • Insights to improve client retention.
  • Improvement in attractiveness as a potential acquisition.

Investing in a data management plan ensures that agencies can harness the full potential of their data, turning it into a powerful asset for informed decision-making and strategic growth. 

With gamification, agencies open the door to a fun and collaborative learning environment that benefits everyone.    

Understand the reasoning behind the game 

It’s understandable to push data management aside for another day. Some agents may ask why they should take that extra minute at the end of a client call to triple check if data fields are filled in correctly. It’s a fair question.  

This is where gamification kicks in. Gamification incorporates game-design elements and principles into non-game contexts to enhance user engagement, motivation and participation. This concept can be applied to a data management strategy to help keep data clean and foster a culture of accountability.  

Get everyone ready to play by first showing the necessity of data management. Ditch the Power Point presentation and instead amp up opportunities for Q&A, use fun GIFs to make a point or post interactive polls to gauge feedback and keep everyone engaged. 

Clear and transparent information will break down barriers. Once the team understands the importance of data cleanliness, dig in to understand exactly how data mistakes happen in the first place.

See also: 'Data as a Product' Strategy  

Uncover data challenges and turn solutions into wins

Data management challenges often arise from simple human circumstances, such as time constraints and misunderstandings, rather than intentional negligence. The term "field hijacking" refers to incorrect data entered into a mandatory field just to bypass requirements. An example of this includes entering “9999” as a legitimate SIC Code—meaning non-classifiable—rather than taking the time to find the correct SIC classification. Other examples are purely mistakes, such as keying in the wrong ZIP code or falling victim to the commonly known "fat thumb problem," accidentally hitting the space bar and creating a blank character in a field.  

Understanding the challenges up front will help staff know what to look for. They will also be better positioned to motivate coworkers and win rewards throughout the game. 

Organize teams and stay competitive     

The good news is that bad habits can be broken. 

To create the shift in approach and stay focused on gamification, incorporate game updates in company-wide meetings and showcase clear outcomes as data management improves. Within the updates, focus on three key pillars of strategy to keep messaging consistent and then repeat these pillars over and over again in messaging throughout the gamification process. The pillars can be simple, such as “achieving data accuracy,” “trustable reporting” or “integration-ready data.” Granular objectives for each pillar can be further annotated to help drive action.

After the three pillars have been established, develop a framework tailored to your data management needs by defining goals, rules, rewards and feedback mechanisms. Pick a fun name to brand the initiative, like "Datapalooza,” then create teams or appoint individual stewards. For example, create a team around each of your account executives. Each team will be tasked with initiatives catered to your data management framework, like removing blank spaces and filling in required fields. 

Track progress and share rewards 

Throughout the gamified data management process, use a data analytics tool to track progress and reward staff accordingly. A platform designed specifically for data management will make the process a breeze, with one easy-to-view dashboard. Through this software, you can pull weekly reports to check on team status, view areas for improvement and create visually appealing presentations to share during company-wide meetings.   

Continue to provide incentives to staff by offering rewards for team winners. Free lunches or Amazon gift cards inject healthy competition into the process, making data cleanup a quick weekly ritual rather than a daunting task. Engagement and accountability will naturally rise when infusing gamification into the data cleaning process. Keep the gamification elements fresh and exciting and regularly update challenges and rewards based on user feedback and performance data. 

See also: How External Data Is Revolutionizing Underwriting

A continuous process to keep momentum 

One-and-done training sessions usually fall flat. Implementing a continuous process with motivational incentives will give employees a better understanding of the importance of clean data. Keep up the conversation through lunch and learns and promote progress frequently through multiple internal channels. 

Don’t kick data management down the road. Valuable insights are guaranteed to drive business growth.   

Why Touchless Claims Is a Must-Have in 2024

Enhanced customer experience, cost reduction, fraud prevention, improved accuracy and scalability make it a compelling choice for the industry. 

Lights Streaks in Close-up Shot

The insurance industry, traditionally known for slow adoption of technology, is on the brink of a transformation. Touchless claims processing, once a futuristic concept, is rapidly becoming a necessity. 

As we move further into 2024, the demand for efficient, customer-centric solutions has never been greater. Touchless claims processing promises to revolutionize the insurance sector by enhancing efficiency, reducing costs and significantly improving customer satisfaction. This blog explores why touchless claims processing is a must-have for the insurance industry in 2024 and beyond.

The Evolution of Insurance Claims Processing

Historically, insurance claims processing has been labor-intensive and time-consuming. Customers often faced long wait times, extensive paperwork and numerous touchpoints with various agents. This approach not only led to customer dissatisfaction but also increased operational costs for insurers. The advent of digital technologies has paved the way for a more streamlined approach, but the full potential of automation is realized with touchless claims processing.

See also: Digital Revolution Reaches Underwriting

What Is Touchless Claims Processing?

Touchless claims processing leverages advanced technologies such as artificial intelligence (AI), machine learning (ML) and robotic process automation (RPA) to handle claims with minimal human intervention. From the initial claim submission to the final settlement, each step can be automated, ensuring a seamless and swift experience for the customer.

Key Components of Touchless Claims Processing:

  1. AI and Machine Learning: These technologies are used to analyze data, predict claim outcomes and identify potential fraud.
  2. Robotic Process Automation (RPA): RPA handles repetitive tasks such as data entry, validation and communication.
  3. Natural Language Processing (NLP): NLP enables systems to understand and process human language, facilitating customer interactions and documentation.
  4. Digital Self-Service Portals: These portals allow customers to submit claims, track their status and communicate with insurers without human intervention.

Benefits of Touchless Claims Processing

1. Enhanced Customer Experience

In today's fast-paced world, customers expect quick and hassle-free service. Touchless claims processing meets these expectations by significantly reducing the time taken to process claims. Customers can submit claims through user-friendly digital portals and receive real-time updates on their claim status. This transparency and efficiency lead to higher customer satisfaction and loyalty.

2. Cost Reduction

Automating the claims process reduces the need for manual labor, which in turn cuts down on operational costs. Insurers can reallocate resources to other critical areas, such as customer service and product development. Moreover, automation minimizes errors, reducing the costs associated with claim rework and corrections.

3. Fraud Detection and Prevention

Fraudulent claims are a significant concern for insurers, leading to substantial financial losses. Touchless claims processing employs AI and ML algorithms to detect anomalies and patterns indicative of fraud. By identifying fraudulent claims early in the process, insurers can mitigate losses and ensure that genuine claims are processed swiftly.

4. Improved Accuracy and Consistency

Human errors are inevitable in manual claims processing. Automated systems, however, ensure that claims are processed with high accuracy and consistency. This not only speeds up the process but enhances the reliability of the service provided.

5. Scalability

As the volume of insurance claims fluctuates, touchless claims processing systems can easily scale up or down without compromising efficiency. This flexibility is crucial for insurers to handle peak periods without delays or increased costs.

See also: Commercial Insurance's Digital Revolution

The Role of Data in Touchless Claims Processing

Data is at the heart of touchless claims processing. The vast amounts of data generated and collected by insurers provide the foundation for AI and ML algorithms. These algorithms analyze historical claim data to predict outcomes, identify fraud and optimize the claims process. Additionally, real-time data from IoT devices, telematics and other sources enhance the accuracy and efficiency of the system.

Data Integration and Management

To fully leverage the benefits of touchless claims processing, insurers must invest in robust data integration and management systems. This includes ensuring data quality, consistency and security. By integrating data from various sources, insurers can gain a comprehensive view of each claim and make informed decisions quickly.

Challenges and Considerations

While the benefits of touchless claims processing are clear, insurers must navigate several challenges to implement this technology successfully.

1. Data Privacy and Security

Handling sensitive customer data requires stringent data privacy and security measures. Insurers must comply with regulations such as GDPR and CCPA to protect customer information and maintain trust.

2. Change Management

Shifting to touchless claims processing involves significant changes in workflows and employee roles. Insurers must manage this transition carefully, providing training and support to ensure a smooth implementation.

3. Technology Integration

Integrating touchless claims processing with existing systems can be complex. Insurers need to ensure that new technologies are compatible with legacy systems to avoid disruptions in service.

4. Customer Adaptation

While digital portals and automated systems offer convenience, some customers may be hesitant to adopt these new technologies. Insurers must provide clear communication and support to help customers adapt to the new processes.

See also: A Reality Check for Generative AI

The Future of Touchless Claims Processing

As technology continues to evolve, the capabilities of touchless claims processing will expand. Advanced AI algorithms, blockchain technology and enhanced data analytics will drive even greater efficiencies and accuracy in claims processing. The integration of these technologies will enable insurers to offer hyper-personalized services, enhancing the customer experience.

Conclusion

Touchless claims processing is no longer a luxury but a necessity for insurers aiming to stay competitive in 2024 and beyond. The benefits of enhanced customer experience, cost reduction, fraud prevention, improved accuracy and scalability make it a compelling choice for the industry. However, successful implementation requires careful consideration of data management, privacy, security and change management. By embracing touchless claims processing, insurers can revolutionize their operations, meet evolving customer expectations and secure a competitive edge.

The insurance landscape is changing rapidly, and touchless claims processing stands at the forefront of this transformation. Insurers that invest in and adopt this technology will be well-positioned to lead the industry, providing unparalleled service and efficiency to their customers.

Litigation Risks in 2024 and Beyond

Litigation risk looms large over the insurance industry, driven by digital transformation, more complex insurance products and heightened regulatory scrutiny.

Businessman Signing a Document

In the fast-paced world of insurance, where innovation and technology drive industry evolution, one critical aspect often overlooked is the looming threat of litigation. As insurers and innovators strive to stay ahead of the curve, understanding and mitigating litigation risk is paramount. In 2024, with the ever-increasing complexity of insurance products and the growing influence of digital technologies, the landscape of litigation risk is evolving rapidly. This blog delves into why litigation risk should be a top priority for every insurer and innovator in 2024, and what steps can be taken to navigate this challenging terrain.

The Changing Face of Litigation Risk

The insurance industry is no stranger to litigation. From coverage disputes to regulatory challenges, insurers face a myriad of legal hurdles that can significantly affect their bottom line and reputation. However, in 2024, the nature of litigation risk has undergone a dramatic shift, driven by several key factors:

1. Digital Transformation

The widespread adoption of digital technologies has revolutionized the insurance industry, offering new opportunities for efficiency and customer engagement. However, this digital transformation has also introduced new risks, such as cybersecurity breaches and data privacy concerns, which can result in costly litigation.

2. Complexity of Insurance Products

As insurers strive to differentiate themselves, they are developing increasingly complex insurance products tailored to specific customer needs. While these products offer greater customization and coverage options, they also raise the potential for disputes over policy interpretation and coverage limits.

3. Regulatory Scrutiny

Regulators are keeping a close eye on the insurance industry, particularly concerning consumer protection and compliance with evolving regulations. Insurers must navigate a complex web of state and federal laws, as well as industry guidelines, to avoid regulatory enforcement actions and associated litigation.

See also: A Tipping Point for P&C Litigation

Understanding Litigation Risk

To effectively manage litigation risk, insurers and innovators must first understand its various sources and potential consequences:

1. Policyholder Disputes

Policyholders may file lawsuits alleging breach of contract, bad faith denial of claims or other violations of their rights under the insurance policy. 

2. Third-Party Claims

Insurers may face lawsuits from third parties, such as injured parties in auto accidents or property damage claims. These claims often involve complex liability issues and can result in significant financial exposure.

3. Regulatory Actions

Regulatory agencies may initiate enforcement actions against insurers for violations of consumer protection laws, unfair claims practices or failure to comply with regulatory requirements. These actions can lead to fines, penalties and reputational damage.

4. Data Privacy and Cybersecurity Breaches

With the increasing reliance on digital technologies, insurers are vulnerable to data breaches and cyberattacks. Failure to protect sensitive customer information can result in litigation, regulatory fines and damage to the insurer's brand.

See also: The Plaintiff Bar Is Winning in AI

Mitigating Litigation Risk

While litigation risk cannot be eliminated entirely, insurers and innovators can mitigate its impact:

1. Robust Compliance Programs

Developing and implementing comprehensive compliance programs is essential for ensuring adherence to regulatory requirements and industry standards. This includes regular training for employees, monitoring of regulatory developments and internal controls to detect and prevent compliance violations.

2. Clear and Transparent Communication

Transparent communication with policyholders and other stakeholders is crucial for mitigating disputes and building trust. Insurers should provide clear explanations of policy terms and coverage limits, as well as timely updates on claim status and resolution.

3. Investment in Technology and Security

Investing in advanced cybersecurity measures and data protection technologies can help insurers safeguard sensitive customer information and mitigate the risk of data breaches. This includes encryption, multi-factor authentication and regular security audits to identify and address vulnerabilities.

4. Alternative Dispute Resolution

Using alternative dispute resolution mechanisms, such as mediation and arbitration, can help insurers resolve disputes more efficiently and cost-effectively than traditional litigation. These methods offer greater flexibility and opportunities for collaborative problem-solving.

5. Continuous Monitoring and Risk Assessment

Regular monitoring of litigation trends, regulatory developments and emerging risks is essential for staying ahead of potential threats. Insurers should conduct thorough risk assessments to identify areas of vulnerability and address them.

The Future of Litigation Risk Management

As insurers and innovators continue to adapt to the evolving insurance landscape, effective litigation risk management will remain a critical priority. By embracing technology, enhancing compliance efforts and fostering transparent communication, insurers can navigate the complexities of litigation risk and position themselves for long-term success in 2024 and beyond.

Conclusion

In 2024, litigation risk looms large over the insurance industry, driven by factors such as digital transformation, complexity of insurance products and regulatory scrutiny. Insurers and innovators must address this risk by understanding its sources, implementing robust risk management strategies and staying vigilant in monitoring emerging threats. By mitigating litigation risk, insurers can protect their bottom line, safeguard their reputation and maintain the trust and confidence of their policyholders and stakeholders.

In the dynamic and competitive landscape of 2024, effective litigation risk management is not just a necessity – it's a strategic imperative for every insurer and innovator aiming to thrive in the digital age.

The Gen AI Effect on Insurance

By embracing personalization, technology, prevention, ethical considerations, and collaboration, insurers can position themselves for long-term success.

An artist’s illustration of artificial intelligence (AI)

In the ever-evolving world of insurance, a new generation is poised to shake up the industry like never before. Generation AI, born into a digital age, is driving transformation in how insurance is perceived, accessed, and used. 

Let’s delve into the profound impact this generation is having on the insurance industry.

See also: Re-Imagining the Actuary in the Gen AI Era

  1. Personalization: Gen AI craves personalization in every aspect of their lives, and insurance is no exception. Traditional, one-size-fits-all policies are becoming obsolete as Gen AI demands tailored insurance solutions that align with their unique lifestyles and needs. Through the power of AI and big data analytics, insurers can offer hyper-personalized policies that cater to individual preferences, behaviors, and risk profiles. Whether because of usage-based auto insurance, pay-as-you-go health coverage, or customized home insurance packages, Gen AI is driving a shift toward personalized insurance experiences that resonate on a deeper level.
  2. Tech-Driven Accessibility: Gen AI is a generation that lives and breathes technology. They expect seamless digital experiences and instant access to information, and the insurance industry is adapting accordingly. From AI-powered chatbots that provide instant assistance to mobile apps that allow for on-the-go policy management, insurers are harnessing technology to meet the evolving needs of Gen AI. The days of lengthy paperwork and tedious phone calls are fading away, replaced by intuitive digital platforms that empower customers to interact with their insurance providers any time, anywhere. This enhanced accessibility not only improves customer satisfaction but also fosters greater transparency and trust within the industry.
  3. Prevention Over Remediation: Unlike previous generations, Gen AI places a strong emphasis on prevention rather than remediation. With advancements in IoT (Internet of Things) technology, insurers can offer innovative solutions that help prevent losses. From smart home devices that detect potential hazards to wearable technology that promotes healthier lifestyles, Gen AI is driving a paradigm shift toward insurance policies that reward risk management. By embracing prevention-centric approaches, insurers can not only reduce claims costs but also foster a culture of empowerment and responsibility among policyholders.
  4. Ethical and Environmental Considerations: Gen AI is deeply passionate about social and environmental issues, and they expect the companies they engage with to share their values. In response, insurers are increasingly incorporating ethical and environmental considerations into their business practices. From offering sustainable insurance products that support eco-friendly initiatives to promoting diversity and inclusion within their organizations, insurers are aligning themselves with the values of Gen AI. By demonstrating a commitment to corporate social responsibility, insurers not only attract younger customers but also contribute to positive societal change, earning them goodwill and loyalty in the process.
  5. Collaborative Ecosystems: In the age of connectedness, Gen AI thrives on collaboration and community-driven solutions. Recognizing this trend, insurers are forming strategic partnerships and ecosystems that offer holistic solutions beyond traditional insurance products. Whether it’s teaming up with tech companies to develop innovative insurtech solutions or partnering with healthcare providers to promote wellness initiatives, insurers are embracing a collaborative mindset that extends beyond their core business. By leveraging the collective expertise of diverse stakeholders, insurers can deliver comprehensive solutions that address the evolving needs of Gen AI and foster a sense of belonging within their customer base.

See also: The Dawn of Gen AI In Insurance

The Gen AI effect is not just a passing trend; it’s a seismic shift that is reshaping the insurance landscape for the better. By embracing personalization, technology, prevention, ethical considerations, and collaboration, insurers can adapt to the changing preferences and expectations of Gen AI and position themselves for long-term success. The insurance industry is undergoing a profound transformation, and Gen AI is leading the charge toward a future where insurance is not just a safety net but a catalyst for positive change in society. Embrace the Gen AI revolution, or risk being left behind in the dust of outdated practices and antiquated ideologies. The choice is yours, but the consequences are clear.

Time to Modernize Your Mainframe

Mainframe modernization can let incumbents turn the tables on newcomers by taking full advantage of new approaches while leveraging their historical strengths.

Man Walking on White Platform

In today’s rapidly evolving insurance sector, industry leaders are increasingly discussing the potential of technologies such as generative AI, big data and digital twins. However, success will come most readily to leaders who put mainframe modernization at the heart of their digital transformation strategy. This can let incumbent insurance organizations turn the tables on newcomers by taking full advantage of new approaches while leveraging their historical strengths and dominance.

Are mainframes still relevant? 

Large organizations like banks, insurance companies and communication service providers turned to mainframes decades ago for their undeniable virtues. Mainframes offered high processing power, reliability and security. 

The fact that mainframes are still at the core of IT systems of some of the largest insurers is a testament to their utility. Yet, the challenges of mainframe technology, such as its inflexibility and high operating and licensing costs, are now increasingly apparent, pushing a shift toward more modern solutions.

Operating and scaling mainframes is costly, with providers raising fees to offset a shrinking customer base. A critical issue is the dwindling pool of mainframe expertise, as most mainframe experts are nearing retirement or are already retired. Few young tech professionals are interested in mainframes and supporting technologies such as COBOL, Natural, IDMS, PL1, EGL, ADS or Assembler that are gradually disappearing from universities’ curricula.

Open the door to agility and cost savings 

Many insurance providers are considering moving away from mainframes, recognizing the downsides. Nevertheless, the real motivation of visionary leaders is the advantages of modernized technology and the innovation potential it unlocks. Starting the modernization journey focusing on achieving agility, rather than avoiding calamity, positions companies to set the pace for industry growth. 

To improve performance and efficiency, integrating new technologies into modernized systems is crucial. Unlike mainframes, modern systems easily integrate with the latest technologies and practices. Among other advantages, this shift allows migration to the cloud for increased elasticity, horizontal scalability and reliability. Moreover, server-less approaches and microservices become viable options, meeting today’s customer demands for real-time processing and personalization.  

Modernized mainframes also allow for a smoother, faster data flow within various systems, enabling advanced data analytics. Just as important, modernization supports secure data transfer between institutions, aligning with emerging regulatory requirements and open finance. This greater interoperability creates a foundation for new ecosystems based on collaboration and partnerships, expanding customer reach. 

See also: The Threat From Quantum Computing

How about the ROI?

Long-term cost savings typically surpass the initial costs of modernization. Insurance providers see an immediate reduction in the maintenance and license costs associated with mainframes. The cloud’s pay-as-you-go pricing model can further amplify savings, allowing companies to redirect funds from routine operations to innovation. The cloud's near-infinite scalability makes it easy to add compute instances, simplifying planning.

Modern IT practices, like DevOps, flourish within organizations that rely on modern systems. Teams adopting these practices work faster and with greater agility. They accelerate development cycles and time to market for new features, products and services. Young professionals seek out organizations with future-ready IT infrastructures. As a result, many insurance companies find that moving to modern systems and practices enhances their ability to attract top talent. 

Insurance giant automates modernization 

Let’s look at a real-world example. A multinational insurance company with a broad range of products found that its legacy mainframe systems hampered its digital transformation goals. High operating costs and a shortage of people with mainframe skills added to the drag. The company decided to modernize its mainframes, shifting away from COBOL and other legacy approaches to a modern platform. 

The company accelerated its journey by using automation to drive modernization's traditionally slow refactoring and testing phases. A 100% automated process enabled the company to transform legacy source code and data to modern standards, primarily Java. The process opened the door to the cloud while simplifying and accelerating development cycles. Perhaps most importantly, the company now relies on a more agile, open and interoperable infrastructure, giving the company the ability to keep pace in a rapidly changing insurance landscape. This modernization approach also enabled significant cost savings and addressed the challenge of finding and hiring mainframe experts.  

See also: Why Every Insurer Needs a Modern CRM

Start smart and modernize fast

Mainframe modernization has historically been a daunting undertaking. However, as seen in hundreds of successful projects, a fully automated process, a well-planned roadmap and experienced partners can accelerate the process dramatically and minimize the risk and cost. Once completed, modernization allows organizations to reap all the benefits of today’s leading IT practices, to innovate with fewer constraints and to stay competitive in the insurance industry. Soon enough, we will be able to see who managed to make the shift.


Scott Silk

Profile picture for user ScottSilk

Scott Silk

Scott Silk is chairman and CEO of Astadia, acquired by Amdocs in November 2023.

He was previously chairman and CEO of SeeWhy, acquired by SAP in 2014. Prior to SeeWhy, Silk was president and CEO of Action Engine, an on-device portal company. Before that, Silk served as senior vice president and general manager of ePresence, a provider of security and identity management solutions. Prior to ePresence, Silk served as president of North American operations and vice president of worldwide marketing for Gentia Software.

The Power of the ‘Longevity Economy’

Paul Carroll, editor-in-chief of Insurance Thought Leadership, recently sat down with Scott Frisch, EVP and chief operating officer at AARP, to discuss the power of what AARP has labeled the longevity economy. 

aarp interview

While advertisers focus on 18- to 34-year-olds, the over-50 cohort in the U.S. accounts for $8.3 trillion of economic activity—about half that of all of China. 

Paul Carroll, editor-in-chief of Insurance Thought Leadership, recently sat down with Scott Frisch, EVP and chief operating officer at AARP, to discuss the power of what AARP has labeled the longevity economy. Frisch explained how companies can position themselves to take advantage of the over-50s’ buying power—and how the insurance industry can draw on their work experience at a time when the need for talent is so great. 


Paul Carroll

I'm intrigued by your idea of the longevity economy—and not just because I'm part of that over-50 group you guys spend so much time working with. It just seems like a really interesting way to slice and dice the world. I live in California, where officials often brag about being the fifth-largest economy in the world if it were treated as a separate nation, but the over-50 group in the U.S. is an even more remarkable economic power. 

Scott Frisch

The  mission of AARP is to empower people to choose how they live as they age. Part of that mission is about getting the marketplace to think about this massive audience that we have in this country and, quite frankly, now the globe. 

In the U.S., we have over 115 million people, give or take, over the age of 50. We've always tried to push the marketplace to think about that group in terms of products and services, as one example of helping people over the age of 50. But a number of years ago, we decided to actually try to quantify what the economic impact is of this massive pool of people in this country. We commissioned a study along with another group and found that the direct and indirect economic impact of this audience is roughly $8.3 trillion a year.

That number is staggering. It’s about half the GDP of China.

We all read about how advertisers will focus on the 18- to 34-year-olds, and that’s done for a reason. But the point of this study on the longevity economy is to point out that the 50-plus audience has huge buying power.

Focusing on the longevity economy has let us help other organizations wanting to focus on the 50-plus. I’ll give you an example. 

Around 2015, we launched the AARP Innovation Fund, a venture fund that focused on products and services for the 50-plus, related to aging in place, access to healthcare and preventative health care. We had a very hard time finding companies to invest in within those three criteria that were looking at the 50-plus. A lot of folks said, “Wow, I never would have thought about doing this.”

Now fast-forward to today. The concept of age tech is becoming almost ubiquitous. I would guess that in any given month my team gets four or five calls from other venture funds focused on the same space. The venture space is recognizing that this population of 115 million people, plus or minus, has a huge impact on our economy, not to mention globally, and is driving capital and therefore more products and more services.

So it's been a wonderful journey to go from coming up with this concept to seeing the marketplace adopt it. 

Paul Carroll

I've always found it interesting that AARP started, basically, with an insurance product. Your founder, back in the ‘50s, had a vision for teachers and how they should be able to age after they retired. She was the first woman to be a high school principal in California and was focused on them. The first thing she organized was a group health insurance product. 

It seems to me that there are just massive opportunities: long-term care, a lot of things with wealth management, certainly healthcare and so on. So it seems to me that my audience in insurance really ought to be thinking in terms of the longevity economy. 

Scott Frisch

You're spot on. In 1958, Dr. Ethel Percy Andrus founded AARP because she went to visit one of her teachers after the teacher retired and found her living in a chicken coop behind a house. That was the impetus. And the first thing she did was find group health insurance for retired teachers. 

Fast-forward 65 years and look at what is in the marketplace today. Think about Medicare Advantage, Medicare Supplement and Medigap, of which we have all three here at AARP. Think about the life insurance marketplace, how that's changed. We have property and casualty insurance focused on the 50-plus. With all these things we put our name on—whether working with United Healthcare, New York Life, Barclays, you name it—we try to have something of value that our audience couldn't otherwise get in the marketplace.

Going from that one incident in 1958 to today is just a phenomenal story.

Paul Carroll

Let me ask you about the flip side of the buying power of this group you're talking about, because one of the big things that people worry about in insurance is the talent gap. Insurance isn’t seen as a very sexy industry, so your kids and mine aren't necessarily thinking about going into it, and there are a lot of people who are retiring. I've seen numbers saying as many as 400,000 people will leave the insurance industry by 2026 out of a population of about 3 million in the U.S. And it seems to me that this over-50 cohort, over-65 cohort, over-70 cohort has an awful lot of talent. 

These days, with Zoom calls and remote work and that sort of thing, there's a lot that probably could be done to keep that talent in the industry and continue more or less uninterrupted even though there are going to be all these people leaving. I’m curious to hear how you're thinking about keeping people in the workforce, not 40 hours a week, necessarily, but maybe 20 or 30.

Scott Frisch

I don’t think the insurance industry is alone. I'm a CPA—although not practicing, obviously—and I think the public accounting industry isn’t much different. It's getting harder and harder to keep people in certain industries. 

But the over-50 group may want to continue working for a variety of reasons. They may want to be part of something bigger, something that gives them an emotional lift. They may do it for financial reasons. They may do it because they enjoy the social aspect of work.

AARP has been challenging myths about older workers for years—that they aren’t as engaged, that they don’t have the technology skills—because age discrimination in the workplace is based on those myths. Study after study debunks them. Older workers provide things like mentorship, institutional knowledge and experience. Having gone through a variety of experiences throughout  their careers, whatever it may have been, makes them better prepared to deal with an issue that's happening today.

When we about diversity in the workforce, age should be part of that.

Businesses need to think: How do I retain the older population in the workforce? That requires some flexibility. Technology, with Zoom and Microsoft Teams, has helped tremendously. At AARP, we offer 80 hours of caregiving leave fully paid per year for every employee, which about 45% of our people use. That's a tremendous offering that really doesn't cost that much, and supporting a multi-generation workforce is a big deal. It adds to the vibrancy of a company, the vibrancy of your workforce.

Paul Carroll

Those of us who type for a living have it easier than people who do more manual labor once we get older, but I’m certainly encouraged, in general, about the flexibility being offered in the workplace. 

Scott Frisch

COVID was awful on so many levels, but there were some silver linings, the flexibility issue being one of them. I also think it got all of us used to using Zoom or FaceTime or whatever and closed the digital divide, so the myth about older people lacking technology skills is fading.

Paul Carroll

This is great. I appreciate your taking the time. The over-50 cohort is massive as a buying group and as a source of talent, so I hope the insurance industry leans into your work on the longevity economy.


For the full conversation between Paul Carroll and Scott Frisch, click HERE.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Beyond the Hype on Embedded Insurance

Proponents rave that embedded insurance benefits the insurer, third parties and customers, but we should temper the hype--without spoiling the enthusiasm.

Person holding stylus and mouse

The insurance industry is renowned for its ability to remain emotionally unaffected by hype and respond cautiously to it. With trading in risk as the core business, the insurance industry has evolved through several centuries, catering to the risk needs of the changing geopolitical, economic and technological landscapes. This inherent risk mindset has made the industry immune to being excited about any trigger or responding to it without a qualified assessment. However, a technology-driven startup boom in the last decade is changing the paradigm. These startups strive to gain attention by trumpeting their capabilities and offerings. For example, propositions such as on-demand, parametric and embedded insurance have been grabbing enormous column inches of insurance literature.

We are here to discuss embedded insurance. In the past, only large insurance companies and third-party brands had the privilege of partnering to sell embedded insurance policies. The simultaneous growth and adoption of several technologies has democratized the eligibility criteria and made it easier for anyone to partner, thus ushering in the new era of embedded insurance 2.0 (EI 2.0). 

Now, we can seamlessly integrate granularized and tailor-made insurance coverage into the primary purchase process of a product or service, positioning it as an add-on component or an integrated feature, rather than treating it as a discretionary choice that follows a primary purchase. Embedding helps to prevent traditional decision fatigue and hesitation when purchasing insurance coverage. 

Every piece of literature on EI 2.0 raves about how it is beneficial for the insurer, third parties and customers. This article aims to temper hype with words of caution, without intending to spoil the enthusiasm.

On the hype

The core concept of embedded insurance, which is to sell insurance coverage when a customer purchases a different product or service, is not new. Insurance companies have experience selling their policies through affinity relationships, trade associations and other partnerships. They sell insurance policies when a customer buys a car, mobile phone or a flight ticket or obtains a mortgage loan from their authorized partners. 

However, the old process was fraught with manual handovers and friction points; it did not work as seamlessly as customers wanted. 

The world is a different place now. The growth and proliferation of a constellation of technologies, such as application programming interfaces (APIs), cloud computing, infrastructure platforms, mobile wallets, security technologies and payment applications, has led to broader industry movements like open insurance. This has catalyzed the supply-side development of EI 2.0.

The demand side is empowered by the generational shift in consumer demography, changing consumption dynamics and increasing technologically savvy consumers. This near synchrony between supply and demand allowed insurers to experiment with product innovation by granularizing the coverage and innovatively integrating it within the purchase process of a third-party product or service. The outcome is the unobtrusive positioning of tailored insurance coverage at the right moment in the customer journey of the primary product or service.

There are two prominent indicators of hype in any technology or concept that can be identified with plain eyes: the mushrooming of many startups concentrating on a space in the short term, and the volumes of literature proselytizing its virtues as the best thing since sliced bread. A cursory search of EI 2.0's benefit glossary will leave both checkboxes marked in bold. The results you might get will be replete with phrases like brand expansion, convenience purchase, enhanced experience, financial inclusion, market development, new revenue stream, personalized coverage, protection gap and reduced acquisition cost. Whether you are an insurance company or a consumer thinking about experimenting with EI 2.0, you must ignore the din and exercise caution.

If you are an insurer

The earlier version of embedded insurance achieved two significant things for you: completing the sales process of already commoditized products and facilitating lead generation and early application processing for non-commoditized products that needed individual risk assessment. With EI 2.0, you could achieve much more, but it depends on how you prioritize the overall new proposition.
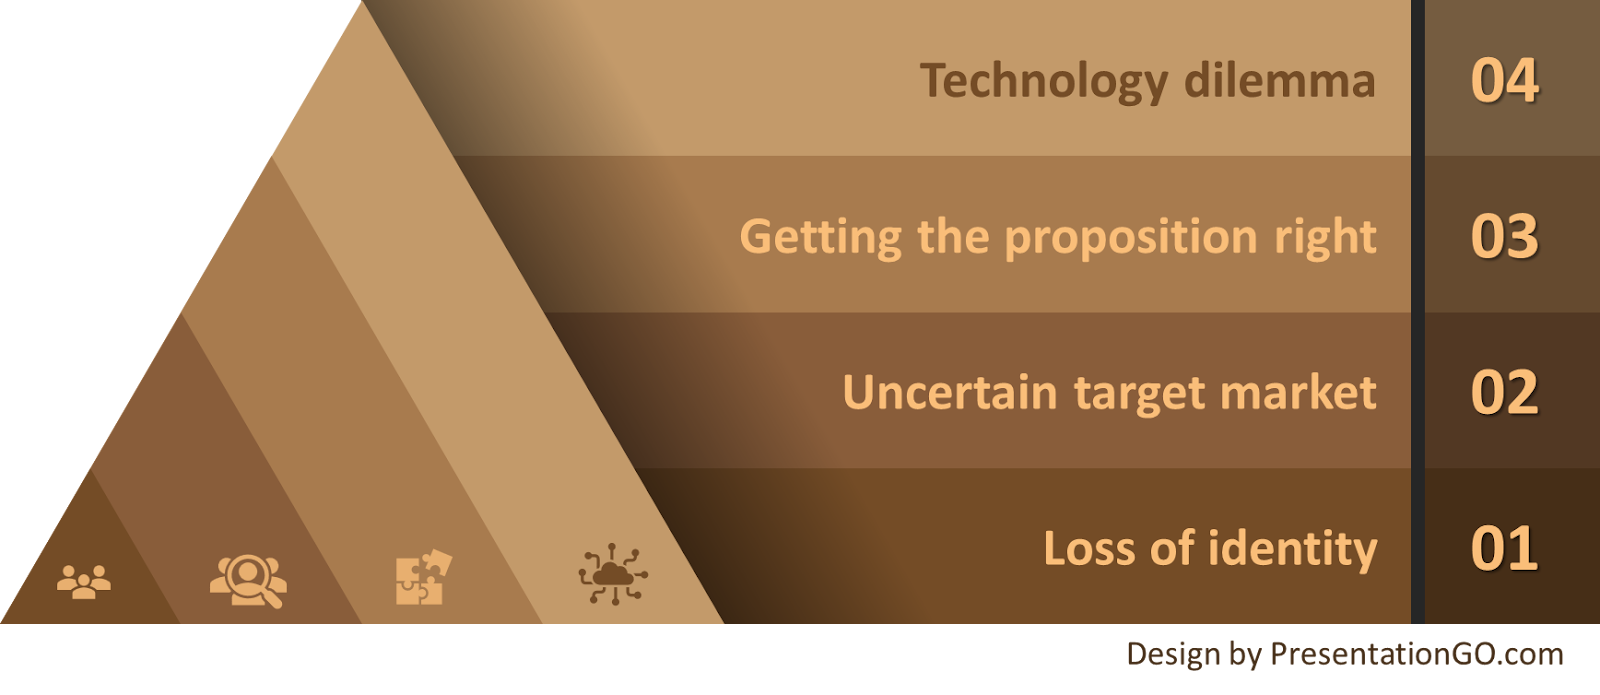
Figure 1: What you should contemplate as an insurer

See also: What's Next for Embedded Insurance?

Loss of identity

The product or service that customers buy is the primary transaction on which insurance piggybacks. The customer does the research to choose the third-party brand from various options, and the brand in turn owns the customer. You are merely leveraging the third-party brand to secure a share of their customer base. You are dependent on your partner, not the other way around. The third-party distributor holds an undeniable dominant position in this relationship and captures the maximum eye-share, mindshare and wallet-share. 

It is likely that your partner may dictate the service standards you should provide to their customers. This puts you in a servile and vulnerable position, susceptible to replacement based on the partner's convenience. It is also possible that all your good work, rather than improving your brand or recall value, enriches your partner's goodwill.

EI 2.0 abstracts the insurance coverage selection as a checkbox on the screen, or worse, as an invisible or inbuilt feature of the primary product or service. If you are a startup seeking to establish a presence in the insurance industry, you may be able to adapt to this inconspicuous existence. If you are an established player, you may tolerate it when embedded insurance holds an insignificant percentage of your portfolio, or if you are using it as the tip of the spear to attract customers. On the other hand, if you want to establish a strong presence in the embedded space, indistinct positioning could result in a significant dilution of your brand and a loss of identity. 

This deconstructs the insurance product beyond its commoditization and converts it into a transaction. Such "transactionalization" eliminates the buyer's decision-making process and exposes insurance purchases to third-party behavior steering.

Uncertain target market

The hype period projections for the total addressable market (TAM), serviceable addressable market (SAM) and serviceable obtainable market (SOM) for any technology or concept are exaggerated. The realistic values will always be much lower. 

Digitalization, the foundation on which the premise of EI 2.0 rests, has lowered the entry barrier for participants, birthed new substitutes, changed consumer preferences and increased their bargaining power. This has led to a reduction in profits, and in a partnership where you are only a secondary player, you may find yourself with less money on the table. Furthermore, given that EI 2.0 represents contextualization, personalization and granularity in risk cover, the premium for these bite-sized products is likely to be lower. 

The early technology-led startups have so far focused only on experience-driven topline growth. Operating on thin margins will deprive you of any opportunity to face adverse claim experiences. Consecutive years of underwriting losses could derail your determination to stay on track with your EI 2.0 journey.

In recent years, many new business models, such as platform-based ecosystems, collaborative consumption models, q-commerce platforms and gig-working models, have emerged. The protection requirements of these customer segments are unique. To meet their needs, you must be creative and astute in designing protection covers, even in the absence of any reliable claim experience history. 

Every EI 2.0 proposition revolves around catering to the tech-savvy younger generations and tailoring risk cover to their purchase patterns, preferences and financial means. However, the younger generation faces challenges, such as income disparities, education debt, the cost-of-living crisis and lofty intergenerational inequality. This economic trend could upend your strategy of using embedded propositions to catch them young and position high-value conventional products as they grow and stabilize.

By catering to this socio-economic group, you are targeting the bottom of the pyramid, recognized for its low price and low margin. To make sustainable profits in this market, you may need your partners to sell insurance coverage in large volumes, which could be beyond their capacity. If selling insurance coverage in large volumes proves to be unfeasible, you may need to increase the margins by either increasing the rate per unit of risk or implementing the widely debated price optimization practices, the success of which is difficult to calculate. 

Insurance is considered a normal good in economics, whose demand increases as consumers’ incomes rise and decreases as consumers’ incomes fall. However, it exhibits varying degrees of income elasticity depending on the type of insurance. Some products, such as health, auto and home insurance, are income-inelastic, whereas others, such as life and travel insurance, are income-elastic. Broadly speaking, when income levels increase, customers may start looking for value and may prefer fewer iterative insurance purchases. They could stop buying granular coverage pieces and opt for comprehensive coverage.

Your inconspicuous presence in the EI 2.0 partnership does not provide you with any recall value among your target customer segment: the less affluent younger generations. As these customers progress in their lives, your previous acquaintances will not be valuable if you wish to leverage them for the sale of other conventional policies.

See also: A New Approach to Embedded Insurance

Getting the proposition right

Before delving into identifying the right proposition, you need to gauge your commitment quotient. Ask yourself if your plan is merely to play with the concept of EI 2.0 for the short term, to reenact your current, manually intensive embedded insurance onboarding process in the digital landscape, or to consider it with all seriousness for the long term. 

If you are serious, you must develop a well-thought-out philosophy on how you are going to pursue EI 2.0. Do you want to test with a small number of partners and products, or do you want to embark on a long-term strategy to broaden your reach across multiple partners and products? Are you going to embed products from your existing portfolio or create innovative ones that cater to the needs of each customer segment? Do you want to take the traditional rigid approach or a fluid approach for product creation?

A rigid approach is where you work with your partner to identify their requirements, create products from scratch and freeze them. A fluid approach is where you already have the coverage deconstructed, unbundled and granularized. For the launch, you can either adopt a template-based approach, which involves creating pre-configured coverage bundles designed for predefined customer segments, or you can adopt an à la carte approach, which allows partners to customize the coverage to their unique requirements, thereby reducing the design-to-deployment time. 

For innovative product creation, the most important thing you need is a fresh pair of eyes to see across the spectrum of interactions that a consumer might have with a product or service to find opportunities. While developing your proposition, you need to check if, by any means, you are disrupting your current product-distribution-customer equilibrium.

Creating an innovative coverage is just one part of the success equation of EI 2.0. You should also consider other factors, such as how the cover is positioned in the purchase process, how customers are onboarded, including risk underwriting, the cost at which the coverage is offered and the smoothness of all post-sale services. 

Insurance policies that are simple, pre-underwritten, meant for risks related to fortuitous losses, providing episodic or short-term covers and necessitating just a single payment of premium would follow an optimal pathway to onboarding as they could be sold as part of the primary purchase transaction itself. In contrast, if the products require individual risk underwriting, they may need to follow the traditional approach by integrating the insurance purchase process into the primary purchase journey and enticing interested consumers to reach out for completion. Given the way insurance is bundled and the limited time for completing the purchase, you should aim to ask fewer questions to assess the risk.

You must be aware that, in the past, there have been several instances where third parties and intermediaries have been involved in the mis-sale of insurance policies, driven by the urge to increase their revenue. This could lead to the suppression of material information and exacerbate information asymmetry. To prevent any such eventuality, it is essential that you exercise utmost caution while choosing your partner, designing the embedded risk coverage and implementing the risk selection process.

Traditionally, embedded insurance propositions focused only on lead generation and customer acquisition. With EI 2.0, the insurance purchase and customer acquisition processes become frictionless. As customers get used to this convenience, their logical expectation is for you to make other services, including claims, resonate at the same level of ease and comfort. 

For simple monoline policies with a single trigger for insurance coverage, you may also explore designing parametric contracts for claim settlement. Parametric contracts will be well-suited for faster resolution of low-value embedded policy claims because they do not require a lot of evidence for a complicated adjudication and approval process.

Technology dilemma

You must be aware that the growth and proliferation of new technologies drive EI 2.0. However, how you respond to this fact depends on whether you are a startup or an incumbent. If you are a startup, having zero-legacy technology burden is a big advantage. In contrast, if you are an incumbent working on legacy infrastructure with disparate systems and technologies, you might be wondering how to meet EI 2.0 requirements. Will a temporary fix do the trick, or is an expensive, broad-based approach that involves modernizing your legacy baggage required?

You know well that embracing new technologies, digitalization and giving your application landscape a total makeover are no longer options that you can ignore. These have become prerequisites for engaging with your customers, whether you choose to pursue the embedded insurance road or not. However, you still need to conduct a cost-benefit analysis, considering the expenses for EI 2.0 deployments relative to your philosophy toward them. Given that most embedded contracts are small-ticket items, the revenue stream and profits are likely to be limited. Your calculations should determine whether short-term experiments can justify the cost, or if several long-term engagements are required to recover it.

To launch EI 2.0 propositions, you must invest in a policy administration system that is adaptable, robust, cloud-based and built on open standards and that supports microservices. Low-code platforms will provide you with the flexibility to quickly adapt to the changing needs of the market and configure products rapidly. It would be ideal if your policy administration system was capable of handling claims functions.

If you fail to sustain your initial enthusiasm for launching embedded insurance, your technology investments may turn into shelfware or abandoned software, thereby contributing to your growing technology debt. To avoid "sitting on the shelf," you must engage in prior soul-searching to measure your commitment quotient and conduct a realistic market assessment.

See also: Embedded Insurance Is Made for SMBs

If you are a consumer

When compared with the process friction you might have faced while purchasing conventional insurance, the ease of buying insurance through embedded arrangements could be enticing. However, you must be aware that the insurance policy sales process is historically known for mis-selling practices such as misrepresentation, non-disclosure, pressure selling, churning, unsuitable recommendations, overstating benefits and undisclosed fees. 

The terms and conditions of insurance policies are full of jargon and are notorious for being difficult to understand. Currently, the technology-dominated EI 2.0 environment lacks a clear definition of the permissible types of insurance coverage unbundling and rebundling. You must consciously avoid being beguiled and clearly understand the nature of the coverage you are purchasing.
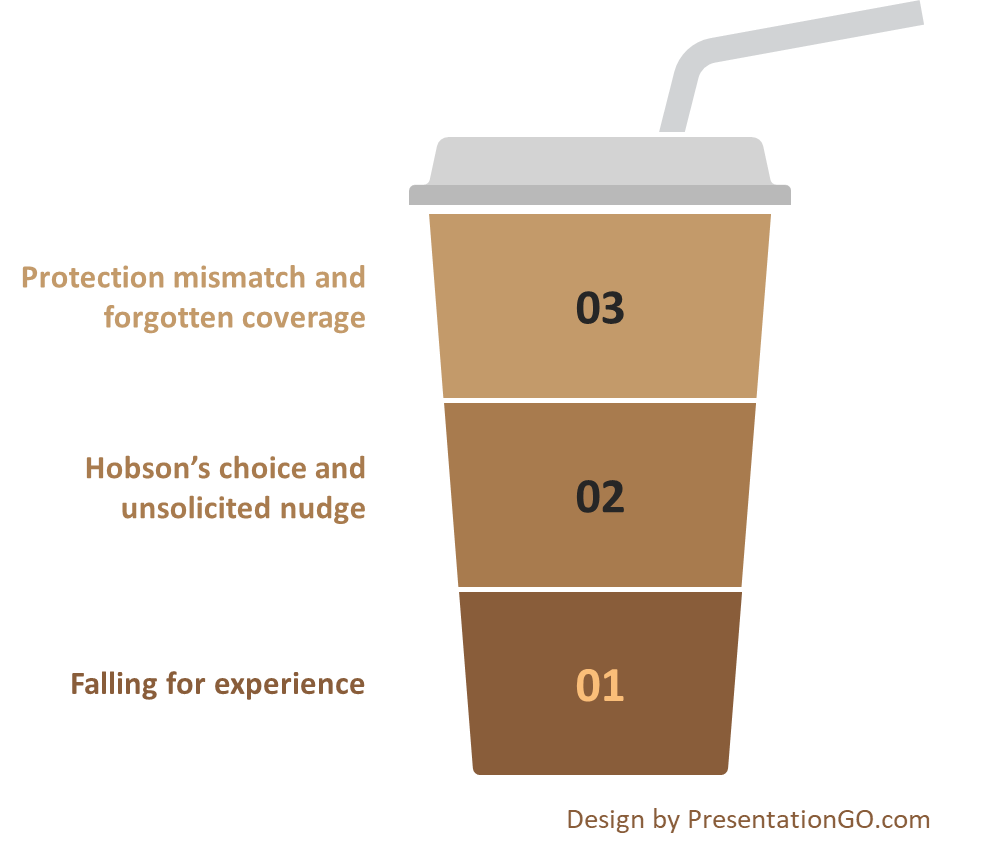
Figure 2: What you must watch out for as a consumer.

EI 2.0 revolves around you and your desire for experience. While you are immersed in the captivating purchase experience of the primary product, insurance coverage is offered to you as a "convenience-wrapped" parcel. EI 2.0 eliminates the need for you to initiate a separate process for purchasing insurance coverage after completing the primary purchase. You will benefit from the default insurance proposition of EI 2.0 if the coverage is custom-designed with the utmost care and if the default option is optimal in terms of design and cost. If trust is not maintained, you may end up paying an experience premium for coverage that you may or may not need. 

Despite prioritizing experience as the most important performance measure, you must be vigilant that transparency, suitability and ethical practices are not compromised. If you go with the flow without understanding the coverage and its suitability for you, the terms and conditions may hurt you later, and you will have only your compromised rationality to blame.

Falling for experience

An embedded insurance proposition involves an inherent contractual agreement between the primary product or service provider and the insurer whose coverage is embedded. This means that when you buy the primary product, if you opt to purchase embedded coverage, you are limited to the specific insurance company providing that coverage. You do not have the choice to compare it with other products available on the market and select better coverage from a different insurer of your choice to bundle into the primary purchase. Even if you have the freedom to opt out of the embedded coverage and purchase one from the open market, it's possible that you won't find comparable custom-made coverage. This could become Hobson’s choice for you.

Ever since behavioral economics gained global attention, nudges and behavior steering have become corporate zeitgeist. When applied ethically, the principles of nudge can significantly benefit you. However, nudging can become evil if the sole intention of the insurer or third party is to manipulate you digitally into purchasing insurance coverage without assessing your actual need or suitability for the coverage. Any method that exploits your emotional state or irrationality constitutes a violation of your autonomy. Therefore, it is crucial to persistently seek full disclosure and transparency of the terms of the insurance contract.

See also: Driving Growth Via Embedded Insurance

Protection mismatch and forgotten coverage

There is one very special aspect about EI 2.0: It bundles appropriate coverage with the product or service you are purchasing, thereby informing you of any potential risks associated with it. However, you should be aware that, in most cases, EI 2.0 bundles granularized and custom-designed coverage rather than comprehensive coverage. It will compensate you only for named perils, not all perils. 

Because the insurance coverage is closely bundled with the primary purchase, any conscious effort from you to purchase the insurance coverage is muted. This disengagement may lead you to mistakenly believe that you have purchased full protection when, in fact, you have not, and thus neglect to seek alternative full protection options. This false sense of security could leave you either partially covered or uncovered.

The other side of this dilemma is the possibility of being overinsured. As a consumer purchasing various products and services, you may also choose to buy embedded insurance coverage as part of the respective purchase journeys. If these different policies include extra coverage and frills, you may wind up with overlapping protection in certain areas. 

Another downside of making a disengaged insurance purchase is that when a loss occurs, you may forget that you are covered for it. While this may not be problematic for short-term episodic coverage, it could pose challenges for long-term coverage if insurance companies fail to continuously engage with and inform you.

End note

The EI 2.0 story is yet to cross the chasm, inviting active participation from the early majority. The success of EI 2.0 does not depend solely on a few enthusiastic startups celebrating it; rather, it hinges on a significant number of incumbent insurance companies joining the party. Insurance giants have so far taken a measured approach. To entice them, EI 2.0 must go beyond focusing solely on product innovation and experience, and instead emphasize equitable value for all parties involved, including insurers, third parties, and consumers. 

Regulations are not explicit regarding the permitted ways in which insurance, a highly regulated financial instrument, could be integrated with a less regulated product or service in a digital setting. Regulatory guidance and oversight must adapt to accommodate all potential forms that embedded insurance could take.

Despite efforts to make it appealing, at its core, insurance remains a boring business focused on numbers, and its seriousness cannot be diluted. Amid all the excitement, insurance companies and third parties must not overlook the importance of transparency to consumers regarding embedded insurance coverage and its terms and conditions. 

Insurance is a contractual agreement, and no amount of innovative packaging and positioning can make it become a candy at the payment counter.


The Next Evolution in Customer Quoting

Quoting has historically been tedious and time-consuming, but a new approach can greatly simplify the process. What is it? Texting. 

Black and Gray Laptop Computer on Writing Desk

The quoting process can be incredibly tedious and time-consuming. Traditionally, the process has been facilitated through phone calls, emails and face-to-face meetings. Digital transformation across the industry has shifted companies’ strategies toward digital platforms such as online portals, mobile apps, video conferencing and even AI-powered chatbots. 

Although these communication channels make client outreach easier, time constraints and customers’ increasing expectations of quick and personalized services still challenge agents. The industry needs to keep innovating. 

To that end, there is a new quoting channel that resonates more with clients and will elevate any agent’s quoting process: texting. Some may ask, “Why texting? And how can it enhance the quoting process?" 

Let's dive into what makes texting an indispensable tool for the insurance quoting process.

See also: Customer Success Is Key, but Where to Start?

Everyone Texts

People love to text, and text messaging (SMS) is the most used data service in the world. Texting is extremely user-friendly, and people in every age range -- not just in younger generations -- show interest in engaging with businesses through messaging. In fact, text messaging is preferred three to eight times more than face-to-face communication across all generations.

An Instant and Convenient Touchpoint

Customers crave quick responses and convenience during the quoting process, and texting is the key to those needs. Texting allows for instant and real-time communication. In fact, the response rate for text messages (45%) is significantly higher than the response rate for email messages (6%). By incorporating texting as a communication channel within a management system, quotes can be delivered instantly to clients, and questions or concerns can be swiftly resolved any time, anywhere. In the process, agents save time from manual communication outreach so they can focus on what they do best: being a trusted adviser and providing valuable service to their clients. 

A Personalized and Accessible Experience

Insurance is a personal service for insureds, so communication during the entire policy lifecycle should feel like a one-on-one experience. By implementing texting into the quoting process, insurance professionals can tailor their responses to the unique needs and preferences of each client. Texting with customers closely resembles their daily conversations and creates a familiar, personalized form of service.  

Because texting doesn't require any special software or technological prowess, it is an inclusive channel for all customers and insurance agents and offers a level of accessibility that other communication channels don’t necessarily have. The easy accessibility is also enticing to prospects and customers who want to receive their quote information quickly and on their personal device. Sales prospects who are sent text messages convert at a rate 40% higher than those who are not sent any text messages. Not only can agents offer a touchpoint that everyone can use, but texting also drives potential leads to build their book of business.

See also: Commercial Insurance's Digital Revolution

One Place to Record and Track Information

Being able to track and refer to a client’s record in one place enables agents to get a full picture of the client's history to best support their needs. Integrating texting into the insurance quoting process enables agencies to keep detailed records of all exchanges between the agent and the client. It also allows for automatic updates of client communication records after each interaction, reducing the need for manual data entry and minimizing human errors. As a result, agents can easily refer to these records, which improves their efficiency and enhances the customer experience.

The future of quoting is texting. This channel is the next innovative way for consumers to shop for their insurance and help agents better interact with their clients. Investing in integrated texting technology will help insurance professionals connect with the increasingly texting-savvy insurance shoppers of today, and ultimately win more business.

Reimagining Long-Term Care

As the population ages, more people need long-term care, but insurers are backing away from the market. There is a gap that needs to be filled. 

Woman Checking Blood Pressure of a Man

The average lifespan has increased by almost three decades since the 1950s. However, "health span" has not followed the trajectory, largely due to chronic conditions affecting aging populations and their quality of life. In the U.S., for example, the demographic of those aged 65 and over is projected to reach 20% of the population by 2030, and 70% of them are estimated to require long-term care at some point. 

While Medicaid, a government program, can help to cover LTC costs, eligibility often requires individuals to redeem their assets and spend down most of their cash. This creates a financial burden for the elderly and their families and limits access to basic care. On the other hand, LTC insurers are facing challenges because of the rise in the number of claims (indemnity, reimbursement etc.), increase in capital risk due to increased cost of care associated with inflation, shortage of skilled caregivers and long cycle time for state filings for rate increases. So insurers are limiting their services to in-force policies and not underwriting new business.

The gap in care needs to be looked at by society, government, providers and insurers, and early diagnostics need to be leveraged to devise interventions to address age-related multimorbidity, such as dementia, Alzheimer's, chronic kidney disease (CKD) and frailty.

See also: The Crisis in Long-Term Care

LTC Challenges - Different Perspectives

For insureds and their families, financial stress is exacerbated by long claims processes and the resulting payment delays for monthly services such as home health aide services; higher premiums; and limited or no early detection or diagnostics services for multimorbidity conditions. 

On the other hand, insurers are facing fraud, waste and abuse (FWA) challenges such as claimants misrepresenting impairments to satisfy eligibility, providers billing for services not rendered, increased claim payouts and underestimated cost of care, resulting in capital risk.

From the caregiver perspective, the cognitive declines among patients increase stress, especially when detected late. 

These realities underscore the complexity of the care ecosystem and the need for innovative approaches to early detection of multimorbidity conditions. Such approaches would reduce the cost of care, increase health span and promote elderly independence.

New Pathways 

With recent advancements in Alzheimer’s disease pathology, researchers estimate that up to 40% of dementia risk is attributable to 12 modifiable risk factors such as hypertension, obesity and physical inactivity. These factors, along with social determinants of health (SDOH) and non-modifiable risk factors, provide a means to identify the segments at risk, through machine learning algorithms.

Primary care providers can recommend or refer this segment for digital cognitive assessments such as speech analysis to determine the high-risk class. Those in danger could then undergo brain imaging or FDG-PET scanning; digital biomarkers would help to determine the deposits of amyloid proteins, if any, allowing for early detection and appropriate intervention to delay the onset.

LTC insurers providing benefit coverage for such scenarios will help to delay the condition and, thus, potential claims and reduce the financial burden for insureds. Also, digitization would enable straight-through processing for claims for recurring monthly services.

Digital twins for the aging, plausible digital copies (base on real-time physiological, medical data) of elderly people, can help to maintain a high quality of life. Connected homes (using environment/IoT data) can help prevent trips/falls, predict the onset or worsening of illness at an early stage and enable elderly to remain in their own homes.

See also: The Future of Caregiving

Empower the Future of Aging

An interagency coordinating committee (ICC) on healthy aging, chaired by the Administration of Community Living (ACL), has set a strategic framework focused on four overarching domains: age-friendly communities, coordinated housing and supportive services, increased access to long-term care services and aligned healthcare and supportive services.

LTC insurers, along with ecosystem participants such as regulators, primary care providers, specialists, community, facilities and care givers, play a vital role in realizing the vision of person-centered care, early detection and prevention services for healthy aging and independence.


Prathap Gokul

Profile picture for user PrathapGokul

Prathap Gokul

Prathap Gokul is head of insurance data and analytics with the data and analytics group in TCS’s banking, financial services and insurance (BFSI) business unit.

He has over 25 years of industry experience in commercial and personal insurance, life and retirement, and corporate functions.