Download

Farmers Face Growing Pollution Liability Risks

Agricultural practices designed to boost crop yields increasingly expose farmers to pollution liability risks requiring specialized insurance solutions.

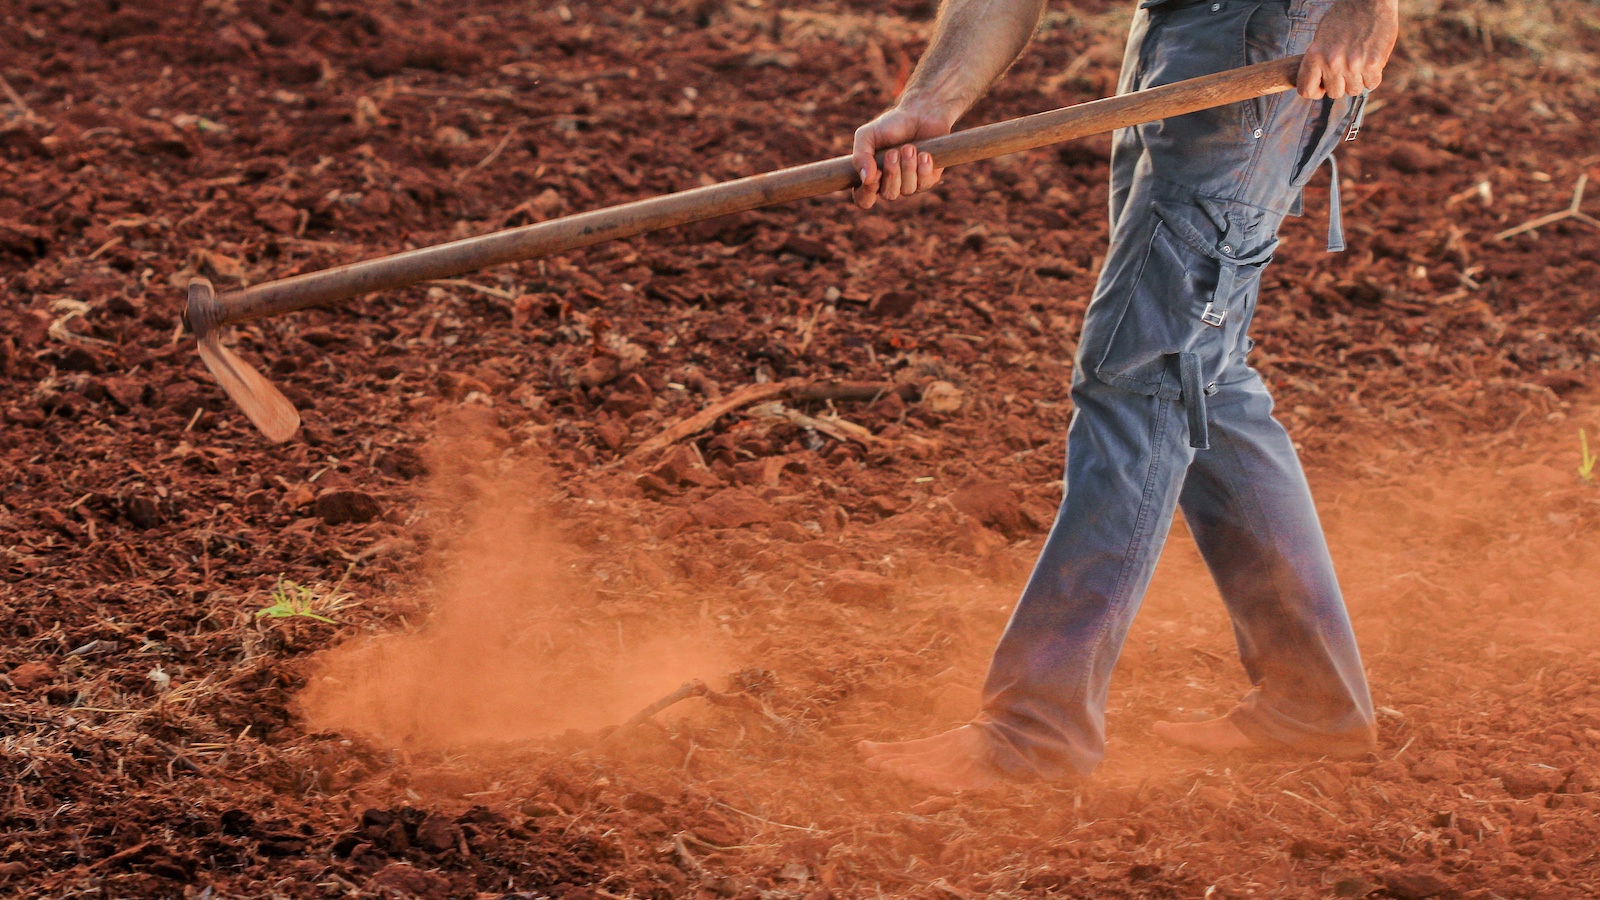
Man Holding Hoe In Dusty Field

Fertilizers and pesticides have increased crop yields for centuries, but they also create broader problems that increase pollution liability risks for farmers. Legislative and legal developments in the past several decades have led to unfortunate consequences: agricultural runoff is polluting rivers and oceans, and farmers and agribusinesses are exposed to environmental liability from everyday activities that were intended only to improve food production. Retail insurance agents can play an important role in advising agribusiness clients on loss prevention practices and working with wholesale specialists to develop tailored risk transfer solutions for agriculture risks.

Risks from agricultural runoff

Irrigation and precipitation cause runoff from fields and pastures, taking on chemicals and animal waste. Eventually, this runoff finds its way into streams and rivers, and drains into oceans. The runoff can cause algal blooms that spawn low-oxygen spots and disrupt marine ecosystems.

An analysis by North Carolina State University found a complex chain of effects from the addition of nitrogen and phosphorus – common ingredients in fertilizers. Published in the Biological Review, the analysis "combined the results of 184 studies drawn from 885 individual experiments around the globe that investigated the effects of adding nitrogen and phosphorus, the main components of fertilizer, in streams and rivers. While the analysis only included studies where scientists added nitrogen and phosphorus experimentally, nitrogen and phosphorus pollution can run off from farms into streams, lakes, and rivers – as well as from wastewater discharge. At high levels, fertilizer pollution can cause harmful algal blooms and can lead to fish kills."

A prime example of these consequences is the "dead zone" in the Gulf of Mexico. The Science Education Resource Center at Carleton College says it "is primarily a result of runoff of nutrients from fertilizers and manure applied to agricultural land in the Mississippi River basin. Runoff from farms carries nutrients with the water as it drains to the Mississippi River, which ultimately flows to the Gulf of Mexico. If the number of nutrients reaching the Gulf of Mexico can be reduced, then the dead zone will begin to shrink."

The National Oceanic and Atmospheric Administration (NOAA) has studied the dead zone since 1985 and notes it varies in size. In Aug. 2024, NOAA estimated the Gulf of Mexico dead zone was more than 6,700 square miles – about the size of the state of New Jersey. Subsequently, the Hypoxia Task Force formed in 1997. Led by the U.S. Environmental Protection Agency and consisting of five federal agencies and 12 states, it has been working to implement policies and regulations to reduce the size of the zone.

Initiatives include:

  • Better management of nutrient application can reduce nutrient runoff to streams.
  • Planting of certain grasses, grains or clovers, called cover crops can recycle excess nutrients and reduce soil erosion, keeping nutrients out of surface waterways.
  • Reducing how often fields are tilled reduces erosion and soil compaction, builds soil organic matter, and reduces runoff.
  • Keeping animals and their waste out of streams, rivers, and lakes keep nitrogen and phosphorus out of the water and restores stream banks.
  • Reducing nutrient loadings that drain from agricultural fields helps prevent degradation of the water in local streams and lakes.
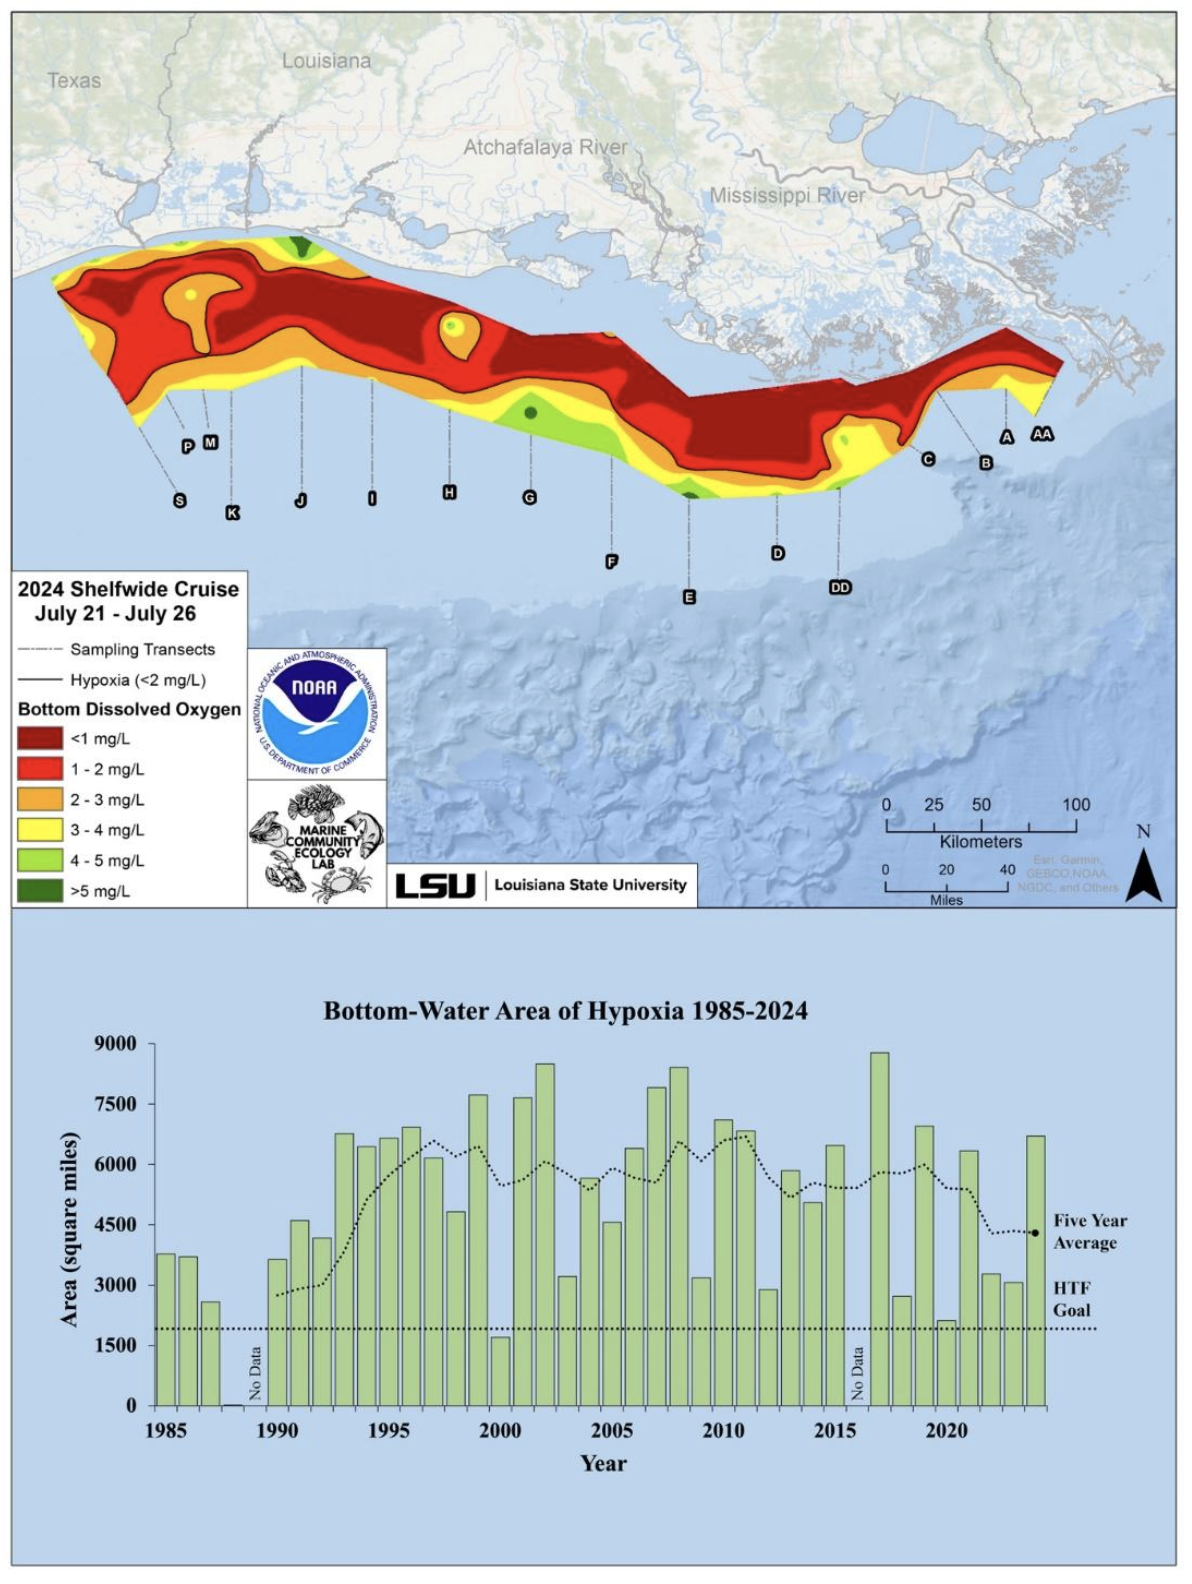
Two Graphics: 2024 Shelfwide Cruise July 21 - July 26, Bottom-Water Area of Hypoxia 1985-2024

Source: NOAA/Louisiana Universities Marine Consortium/Louisiana State University

Waste minimization and pollution risks

An analysis of United Nations' Food and Agriculture Organization data shows that global meat production quintupled from 1961 to 2023. More than 360 million tons of meat are produced worldwide from various kinds of livestock. Managing the waste produced by the livestock required to fulfill global demand is an enormous challenge.

Since 1976, when the Resource Conservation and Recovery Act (RCRA) was enacted, the U.S. has sought to address the increasing volume of municipal and industrial waste. The 1984 passage of Hazardous and Solid Waste Amendments to RCRA "required phasing out land disposal of hazardous waste, corrective action for releases and waste minimization. Waste minimization refers to the use of source reduction and/or environmentally sound recycling methods prior to treating or disposing of hazardous wastes," according to the U.S. Environmental Protection Agency.

In recent years, additional legislation has extended to the agricultural efforts of farmlands that have the continuing potential to pollute and harm the very land on which they reside, in addition to the surrounding environment, groundwater and wildlife that share these spaces. The National Resources Defense Council defines agricultural pollution as "the contamination we release into the environment as a by-product of growing and raising livestock, food crops, animal feed, and biofuel crops."

Protecting farmers' right to farm, not pollute

State and federal court decisions in agricultural pollution cases have consistently found in favor of protecting the environment and adjacent lands. Courts have generally ruled the right to farm does not grant a right to pollute. Commonly, courts levying fines have issued findings of negligence, nuisance and trespassing related to the storage, hauling, treatment and disposal of waste of all kinds.

In 2014, the Wisconsin Supreme Court ruled that "manure applied to fertilize a field in the usual course of a farming business was transformed into a 'pollutant' when it seeped into adjoining neighbors' wells. As such, the Court ruled that a 'pollution exclusion' clause in the farmer's insurance policy eliminated the insurer's duty to defend in lawsuits seeking damage for the contaminated wells."

In the underlying case, the court noted the farmer used "manure from his dairy cows as fertilizer for his fields pursuant to a nutrient management plan prepared by a certified crop agronomist and approved by the Washington County Land and Water Conservation Division. Several months later, the Wisconsin Department of Natural Resources notified the farmer that the manure had polluted a local aquifer and contaminated neighboring water wells. The well owners demanded compensation, and the farmer sought coverage from his insurer under his farm owners' policy."

The insurer sought a declaratory judgment that it had no duty to defend or indemnify the farmer because "manure was a 'pollutant' subject to exclusion under the policy. The circuit court agreed with the insurer, finding that the pollution exclusion in the policy applied to exclude coverage for damage caused by the application of manure because 'a reasonable person in the position of the (farmer) would understand cow manure to be a waste,'" the state supreme court ruled.

Mitigating pollution liability

Farmers today face many difficult issues, from the effect of climate change and weather volatility to the continued urbanization of rural areas, to how to manage runoff and waste. What can farmers do with all the manure as their operation grows? How can farmers protect themselves from pollution laws even when they've done their best to alleviate the problem?

Fortunately, tailored pollution insurance solutions are available to retail agents and brokers to help curtail the potential effect of exposures and liability confronted by their clients, today's farmers and agricultural community. Some insurance options include:

  • Sudden & Accidental (Time Element) Insurance. This typically covers sudden pollution incidents that happen on an insured's land. Incidents typically need to be found in about three days and reported to the insurance carrier within two weeks. It must begin and end in a certain timeframe and is meant to exclude true gradual pollution damage claims that occur accidentally over months or years. Gradual damage tends to be the most costly, hence why Sudden & Accidental pollution coverage for agriculture risks is so inexpensive.
  • Pollution Legal Liability (PLL). This is a risk management tool for property owners that is typically designed to address premises pollution exposures. This claims-made coverage, in our experience, consistently manages the on- and off-site cleanup/remediation expenses; third-party bodily injury and property damage; and defense expenses associated with industries including the agricultural sector. However, because it is an expanded gradual coverage compared to sudden and accidental, it comes with a much higher price tag.
  • Transportation Pollution Liability. This type of cargo pollution insurance generally covers pollution conditions caused during transportation, loading or unloading, and sometimes mis-delivery of this cargo including waste such as manure, or a product such as fertilizer.
  • Non-Owned Disposal Site Liability (NODS) typically covers disposal of waste to a non-owned disposal facility. RCRA provides for joint and several liability for waste generators, meaning a farmer that uses a non-owned disposal facility can still be deemed a potentially responsible party for cleanup and remediation by the EPA. NODS coverage exists to indemnify insureds in this situation.

The key to helping protect the agricultural community from potential pollution conditions starts with the careful understanding of the client's workplace, practices and processes. A one-size-fits-all solution may not take into account the specifics involved in an insured's work and daily practices. Other solutions include the tailoring and blending of various policy forms to create an a la carte coverage form that is designed to help cover the specific pollution conditions of this unique marketplace.
Gen AI Sprouts Ears and a Mouth

A new generation of Apple AirPods enables AI applications that will improve insurers' customer service.

Image
ai robot with headphones

Perhaps the most convoluted conversation I've ever had occurred when my wife and I visited a tiny winery in Tuscany in the late 1990s. The winery was tucked into the stone city wall of Montepulciano, on a street barely wide enough for pedestrians, let alone our rental car. There was no sign above the tiny door, just the street number a sommelier had written down for us. An elderly man answered the door... but spoke no English, while we spoke no Italian. 

We experimented and found he understood Spanish, which both my wife and I spoke because we had recently lived in Mexico. In addition, he spoke French, which I still mostly understood from three years in Brussels. So Kim and I would ask a question in Spanish, which he translated in his head into Italian. He responded in French, which, after some fumbling, I'd translate into English. And away we went — English to Spanish to Italian to French and back to English. We learned he was a sixth-generation wine maker, heard about and tasted his wines and purchased two dozen wonderful bottles.

An announcement last week from Apple will let us use AI to cut right to the chase: translating from any language to any other language in real time and via voice, not just text. The new AirPods won't guarantee you the wonderful morning that Kim and I spent with the charming Italian winemaker but will help the insurance industry with customer service. 

The headline of the New York Times review of the Apple announcement pretty much says it all: "The New AirPods Can Translate Languages in Your Ears. This Is Profound."

The reviewer describes the AirPods as "the strongest example I had seen of AI technology working in a seamless, practical way that could be beneficial for lots of people. Children of immigrants who prefer to speak their native tongue may have an easier time communicating. Travelers visiting foreign countries may better understand cabdrivers, hotel staff and airline employees."

While the reviewer focuses on general use, not insurance, it's easy to see how the AirPods could help agents, brokers, customer service representatives and claims agents assist customers whose native language isn't English. And, while the natural tendency in the U.S. is to think about English-Spanish translation, the AirPods will, in time, be able to translate hundreds of languages into English or any other language. All you need is a set of AirPods for yourself and one to lend a client, and you can converse, with only about a one-second lag between the time you say something and when the other person hears the translation.

Translation apps of one sort or another have been available for a decade, but they've been clumsy. Some translated speech into text, which you had to then read or have the other person read, and you typically had to put your phone or other device in front of your mouth or of the person you were conversing with. The new AirPods have voice output, not only text, but mask ambient noise so well that they can be used as part of a normal conversation, some feet apart or over the phone. 

Improvements from the large language models (LLMs) used in generative AI also make the translations much more accurate than they have been, because LLMs can grasp the whole context of a conversation and not just translate individual words — which can lead to the sorts of mistakes all too familiar to anyone who's ever learned a new language. (I once got caught in a rainstorm in Mexico and, walking into the office dripping wet, told my assistant, "Estoy muy morado," when I meant to say, "Estoy muy mojado." Instead of saying, 'I'm really wet," I said, "I'm really purple." He laughed and laughed and laughed.) Individual words can matter a lot in insurance conversations and contracts, so doublechecking will always be required at some level, but the Times reviewer said his review of the transcript of a long conversation with a Spanish speaker found only tiny errors, such as whether a noun should have been translated as masculine or feminine. 

We've seen some duds among the bold attempts to embed AI in objects in the past — we're marking the 10-year anniversary of the cancellation of Google Glass, and the maker of the much-hyped Humane AI pin was sold for pennies on the dollar earlier this year — but, within a couple of years, the new AirPods should be a powerful tool for all kinds of individuals and businesses, including in insurance.

Estoy muy cierto.

Salud,

Pablo

Vehicle Literacy: Let’s Talk About Cars          

Despite having VIN data, auto insurance companies remain surprisingly illiterate about the cars they insure. There's no excuse.

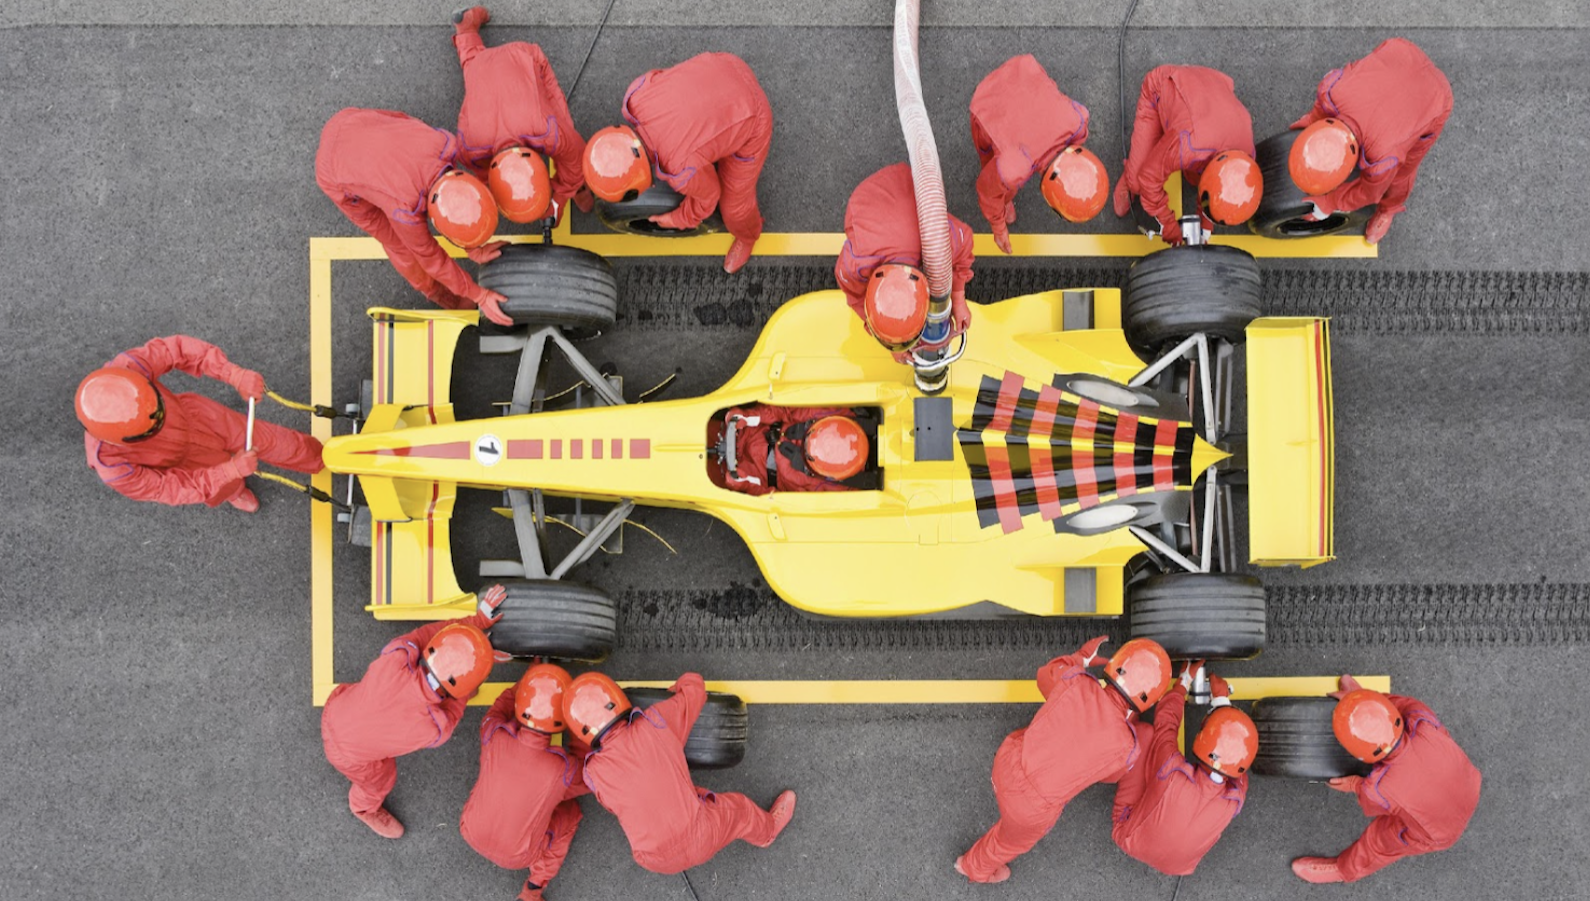
Overhead picture of fourteen individuals in red suits working on the same yellow race car vehicle

Sometimes a picture says it all. The stock photo above shows 14 individuals working on the same vehicle and focusing on separate things. None of them knows everything the others have seen. None knows everything about the car. None necessarily documents anything they just did. They just complete a task — none talking to each other.

Sounds like every auto insurance company I have visited in the last 25 years — no exceptions.

Marketing, advertising, agency, distribution, acquisition, rate/quote/bind, service, claims, etc.: We all know those are about a car, just not exactly which car and what's inside it.

Back to the picture above: No one even counted #15, the person in the driver's seat.

That's what I'm talking about: We ignore our customer.

Worse, we blame them for not knowing their car, and we ask them car questions all the time.

It's not like we don't ignore everyone else in the insurance value chain, but not knowing the customer's car when we talk about their car with the customer seems like an epic ball drop.

We ask them all sorts of things about their car that we could just look up ourselves most of the time. Not because we are mean but because we lack basic information to communicate in a literate way about specific car features and values across our many insurance transactions.

How much empathy do we show when we use customers to do our legwork? Do we save them time? Do we add value by bringing knowledge they might expect from us? Do we show respect for their own lack of car literacy — they are just the driver. Do we serve up delight and satisfaction? Do each of us even know the features and values on our own cars? Maybe for a recent purchase with a window sticker handy, but that used car we bought second hand five years ago from a neighborhood lot with the yellow paint on the windshield that said "Sale $5,899" — of course we don't.

Face it: Nobody carries around their owners' manual. Even if they did, it doesn't say if the exterior paint is clear-coated metallic finished or just regular paint. Who really knows where the advanced driver assistance sensors are on a car — bumper, side mirror, main windshield, front grill, or multiple fused sensors, etc.? These are the clues needed for knowing you have a $5,000 windshield when a "rock from road" claim occurs versus a $500 version. This detail is how the windshield repair truck driver knows what to deliver, and what tips them off that you may need in-shop calibration.

We know that vehicles might have automatic emergency braking (AEB), but for the current car of the conversational moment, is it installed on this car? The answer is binary, yes or no, but our frame of reference is wonky… most cars on the road can't possibly have AEB. The average age of cars on the road is over 12 years old, and forward AEB technology was only entering the new car fleet sporadically about 10 years ago. Rearward AEB is even newer.

Even the new car on the lot for the new policy being issued today - is AEB there or not? While there are plans to make it a standard feature on all cars someday (like a backup camera since May 2018 in the U.S.), there are more unknowns than not, certainly if you ask the customer.

That's what I mean when I say the auto insurance industry is illiterate when it comes to cars.

Not about car insurance, but about the cars themselves.

We talk about average cars, typical cars, new cars, and features available on some cars — some available standard, some optionally available. Seldom do we talk about a specific car with specifics. 

This, even though we can just look it up. 

We have the data we already require in some policy system somewhere or in a quote flow or a claim. Literally, we can just look it up, or better still, pre-fill all our questions with the accurate manufacturer answers. So can everyone.

We struggle with "as built" and "your vehicle," but every single policy for each specific vehicle is identified by its VIN (vehicle identification number), a unique serial number assigned by the manufacturer and labeled in many ways and places on modern vehicles, including registration.

For industry veterans, there was a time long ago when there was no standard VIN (before 1981). And for many of us raised without smartphones (first iPhone was 2007) or perhaps even before the internet (World Wide Web publicly available in 1993), there are decades of model years of vehicles without electronic data that describes them deeply. But for the last decade for sure, seeing a VIN on the internet with price, features, dealer location, and window sticker details is how we shopped for our vehicle, and how we compare features and values every day.

It's time we bring to work what we have in our pockets… easy, accurate, specific details about any VIN on the street, especially the last 100 million vehicles made and sold in the U.S.

I pick on these 100 million as the NEW FLEET: the ones with all the gadgets, sensors, and a variety of possible power trains (old-fashioned internal combustion engines, mixed breed hybrids, and full-on electric vehicles). These 100 million are all model years since 2019, when being online was table stakes for car sales dealers, and a new listing had VIN and window sticker as minimal evidence that a new car was built in a certain way with a certain color and certain features for a certain advertised manufacturer suggested retail price (a base MSRP) with complete disclosure of any destination and delivery fees as well as any optional equipment installed costs to give a total MSRP.

Sure, in the real world, any manufacturer can change their base MSRP, destination and delivery fees, and option prices at any time — that they do. These updates flow onto the dealer lots and websites just like they have gone to dealerships since the very first window sticker back in the 1950s. The car sold yesterday had its window sticker, and the changes that apply today can usually be relied on to be on today's window sticker.

That sticker for a new vehicle is still there when that new car is driven off the lot on the way to its new home by its new driver. For "new fleet" used cars sold, the internet listings of its first listing have that same data. In fact, all new listings for the 100 million "new fleet" vehicles are living in a repository you can see from your smartphone right now. Most also have full "as built" manufacturers build sheet data already appended.

Show a little empathy, save a lot of time, save a lot of money. Talk isn't cheap. Neither is rework.

Let your staff and customers use the data on hand to have specific, accurate, and literate car conversations. This same data can be used to shop for replacements "just like your car" with literally no questions required to be asked. Not for shoppers, customers, agents, underwriters, actuaries, customer service people, co-workers, claims adjustors, repairers, salvage, recovery, vendors, banks, or lenders, just to name a few.

Moving from the general idea of a car to the specific "as built" details of your car is the current and future of what car literacy should look like.

AI May Break the Gartner Hype Cycle

P&C insurers are embracing AI despite regulatory headwinds, potentially letting the technology blast through the intermediate stages of the Gartner Hype Cycle timeline.

Artificial intelligence face against purple lights emanating outward

As we live in an era of technological boom, it is increasingly difficult to separate hype from reality. With so many breakthroughs in medicine, space exploration and even autonomous driving, it is not advisable to bet against even the boldest of efforts. So, perhaps humans will indeed live on Mars one day. In recent times, the naysaying against hype is generally about the when it will happen, less about the if it will happen.

The P&C insurance space has seen its share of hyped concepts like blockchain and virtual reality but none as much as the recent exuberance for AI. And for good reason. Insurance practices are largely about information gathering and validation, whether for underwriting, claims or risk management. Actuarial mathematical sciences are applied for trending and pricing. Internal functions and external processes are just a few ways to describe insurance at-a-glance. All of which may benefit from AI tools and agents near-term and into the future. Insurance talent shortages, high costs of insurance for consumers and businesses, changing risks, demand for loss prediction and prevention are just some of the bigger challenges in which AI may come to the rescue.

The Gartner Hype Cycle

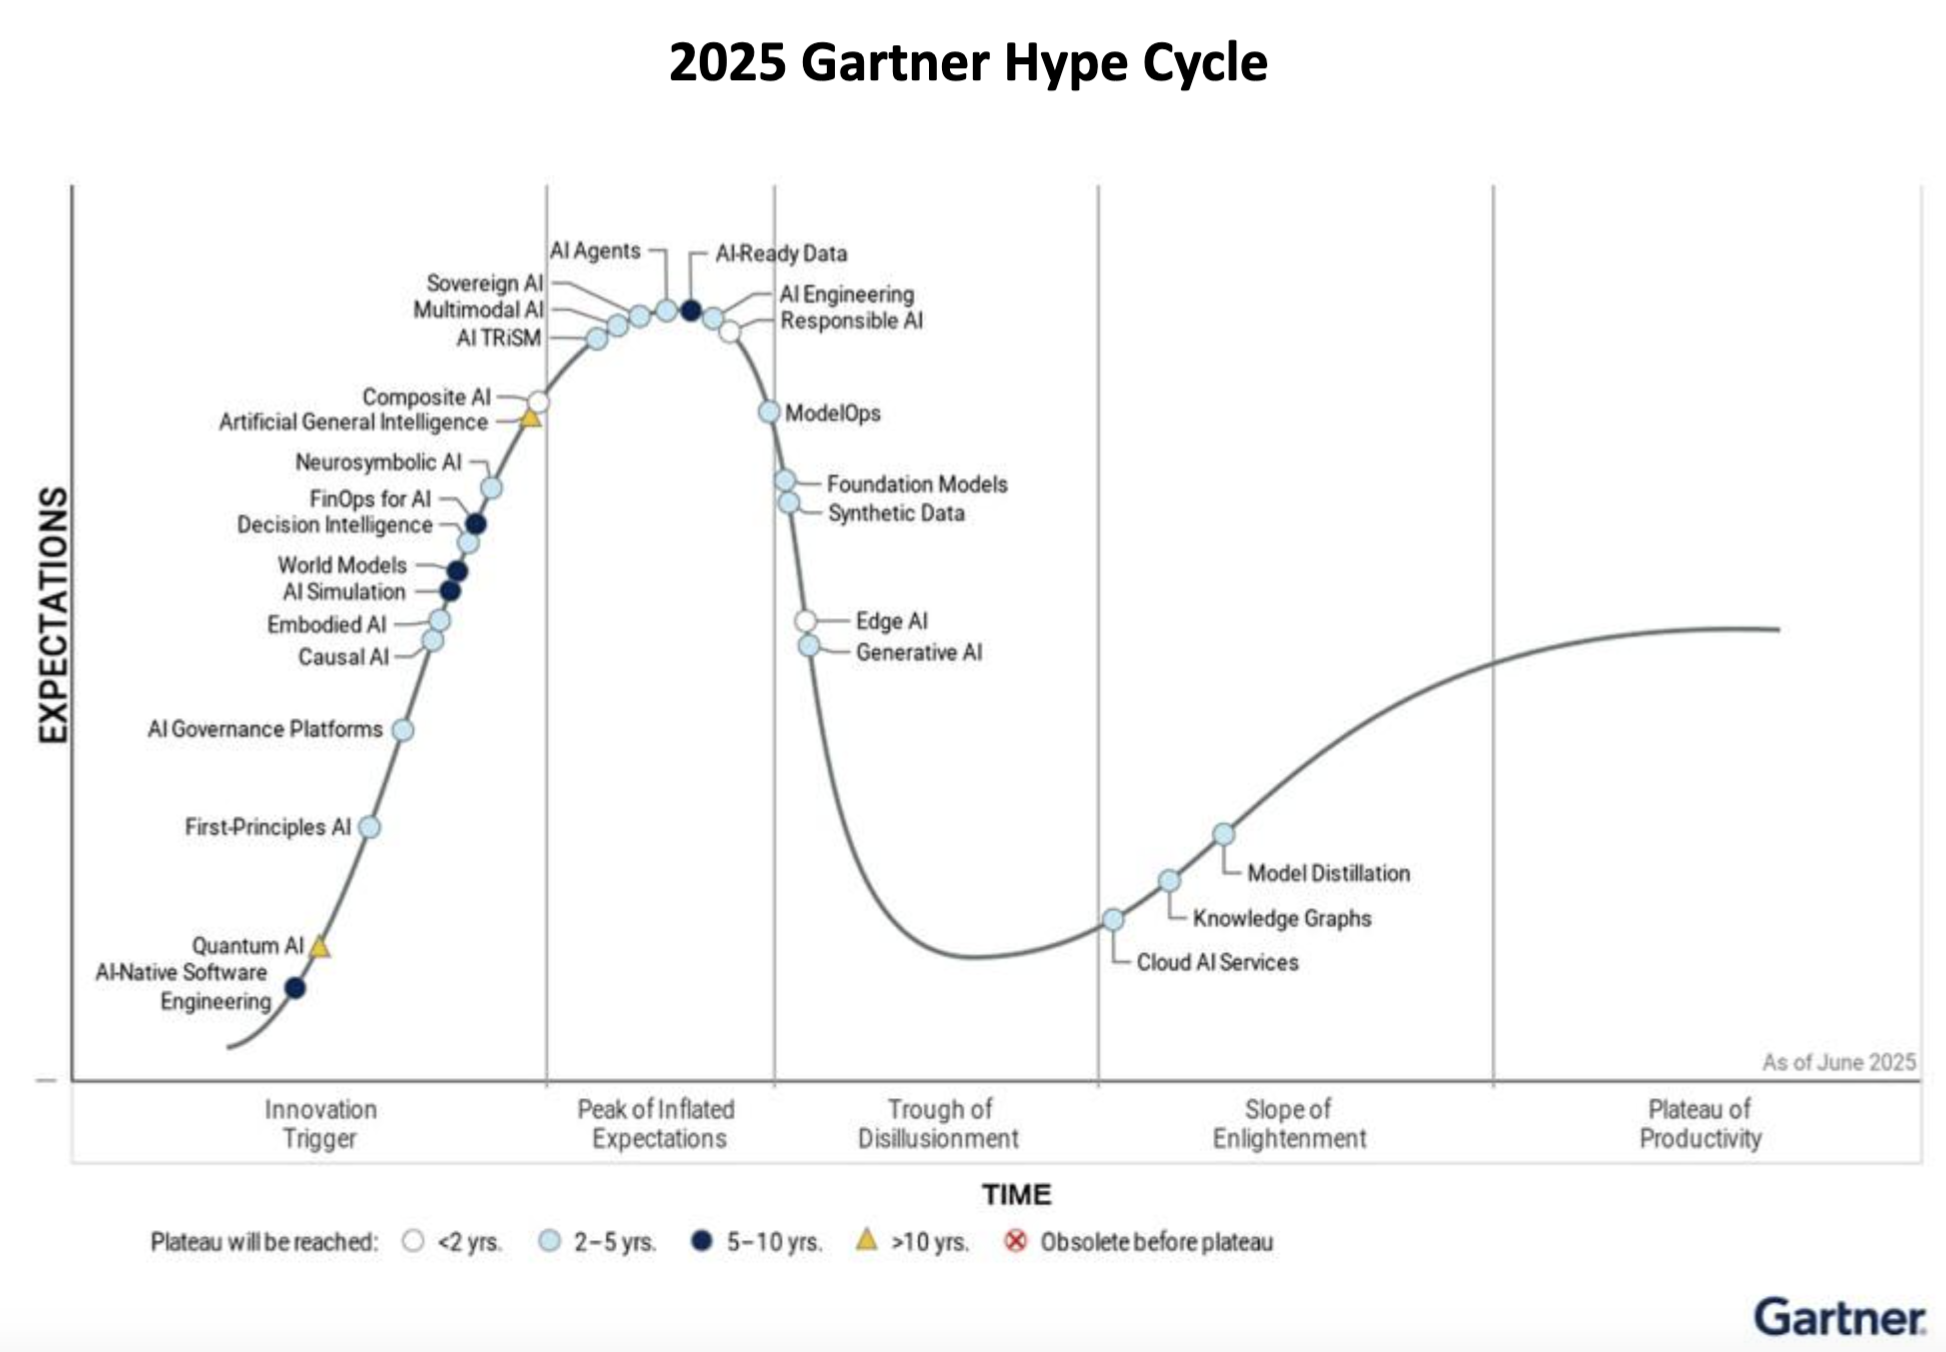
Most of us are familiar with the Gartner Hype Cycle, a visual model that illustrates the maturity, adoption, and social application of a new technology, charting its progression through five key phases. It provides a framework to guide technology investments by showing when a technology's actual value becomes clearer, helping organizations reduce risks and make informed decisions about when to adopt emerging technologies. As valuable as it has been, the arrival of AI technologies may challenge its relevancy.

References to AI and related application are impossible to avoid, which could lead many of us to conclude that we have moved from the Peak of Inflated Expectations and are approaching the dreaded Trough of Disillusionment in the Gartner Hype Cycle (see below).

Indeed, edge AI and generative AI have just barely entered this phase in Gartner's 2025 report.

Gartner Hype Cycle

However, it is our contention that many other uses of AI – including AI agents and decision intelligence, in insurance and beyond – could defy the history of new technologies and collapse the model, skipping right over or compressing the trough and moving straight on to the Slope of Enlightenment and the Plateau of Productivity.

This is not to say that AI adoption – we could call it commercialization at scale – is not without plenty of headwinds. Regulators and lawmakers are expressing ethical and data privacy concerns. Labor unions, service, and information workers are concerned about employment security. Insurance carrier adoption for all new technology is often quite slow, and AI is demonstrating the highest scrutiny ever. Data privacy, legal exposure and brand protection are front of mind among insurers. As legitimate as these concerns may be, collectively, they underscore the huge potential for disruption that these technologies represent.

The insurance industry is among the earliest adopters of AI, although the use cases are still somewhat basic and not yet delivering material returns. But we caution carriers not to allow these early experiences to discourage greater investment and research – the potential returns cannot be ignored, and moreover neither can the competitive market advantages.

International Insurance Society Report Identifies the Rapid Rise of AI

The International Insurance Society, which is affiliated with The Institutes, collaborated with The Institutes along with several affiliates, including the Insurance Information Institute, Insurance Thought Leadership, and Pacific Insurance Conference, on this survey.

According to their just released report, in 2025, artificial intelligence (AI) has emerged as the single most important priority among industry executives, surpassing inflation for the first time in recent years. Two-thirds of executives now place AI at the top of their technology and innovation agendas, representing a steady climb from just 17% in 2021. This accelerated focus is driven by the growing realization that AI can streamline operations, enhance data analytics, and open avenues for product innovation, all of which are seen as critical for staying competitive in an evolving business landscape.

One executive described the benefits of AI to their bottom line: "These tools enhance forecasting capabilities by allowing for deeper insights into trends and potential future risks. By empowering themselves with robust analytics, organizations can improve their strategic planning and risk management efforts, ultimately driving better business outcomes."

P&C Observations on AI Adoption

The following is a snapshot of what we are seeing and hearing from carriers and others:

• Insurers are embracing the concepts of AI to benefit in several areas, including risk selection, underwriting, operational efficiency, and cost management. Claims and underwriting tend to be the most often cited insurance use areas

• C-suites are promoting and setting mandates to advance AI agendas with a "let's not get left behind" mantra

• The variety and number of use cases for nearly every insurance function from product development to distribution and service are remarkable and optimistic

• Internal insurance carrier governance panels tend to narrow, halt and perhaps appropriately stall expansion of use cases due to data security and privacy, legal, and reputational harm risks, along with anticipated future regulatory controls

• AI for insurance encompasses a wide range of types and usage, including computer vision, generative, conversational (chatbots), agentic, and predictive

• Document review and summarization is a particular and popular use, e.g., medical records, demand packages, and legal documents

• Other areas of use include risk section, CAT modeling, claim case escalation, visual damage evaluation tools, reserving, insurance sales, and numerous internal processing functions

• Carriers are mixed in terms of buy vs. build, with most doing both by partnering with AI solutions firms and building proprietary solutions

• There is an abundance of "AI solution" providers with .ai in their URL or otherwise in marketing material, making it extremely difficult to distinguish

• Insurers are highly protective when contracting with vendors and providers, focused on data security and privacy and buckle down on AI usage, data access and related items

• Demands on people, including AI knowledge, skills and capabilities, are understated when it comes to change management

Regulators and AI

The National Association of Insurance Commissioners (NAIC) has introduced model guidance and regulations for the use of artificial intelligence systems by insurers, which have been adopted by 24 states (see NAIC Model and NAIC Model Adoption Map).

The April 2025 Genpact Consumer AI Study reveals that  a majority (55%) of U.S. adult respondents feel neutral about their insurance companies using AI, and 25% view it negatively. However, when AI delivers tangible benefits – such as faster and more accurate claims processing, customized quotes, and improved customer service – customer acceptance increases significantly. The findings emphasize an opportunity for insurers to shift perception and build preference and trust with their customers.

"As insurers embrace AI to enhance operations or customer experience, they must ensure that every interaction – whether human-led or AI-powered – meets or exceeds customer expectations," said Adil Ilyas, global business leader for insurance at Genpact. "This research highlights AI's potential to transform insurance, but also the need for insurers to close experience gaps and communicate transparently to build trust and loyalty."

Recommendations for P&C Industry Leaders

Prioritize governance and model risk management now. Regulators and plaintiffs are focused here — being proactive protects both customers and the balance sheet.

Focus first on high-value, low-risk gen-AI deployments (internal productivity, document summarization, FNOL assistance) while building the data and MLOps backbone.

Treat vendors and foundation models as concentration risk — strengthen contractual, privacy and incident response clauses.

Measure outcomes, not just outputs — track bias metrics, appeal reversal rates, customer satisfaction and financial key performance indicators (KPIs)

Plan for regulatory change — assume more granular supervisory questions and state/federal enforcement in the short term.

Disclosure and Transparency

We employed ChatGPT to gather some of the facts for this article, which itself is validation of our premise that AI is becoming pervasive and is too valuable to ignore for certain tasks. We believe that any published work should include an AI disclosure statement. When used in conjunction with the author's own experience, informed insights, common sense, and ethical judgement, it feels like AI could help make it an exciting future.

Even though insurance AI hype exceeds measurable uplift at the moment, it is our view that AI is not just another technology bubble. AI in insurance holds tremendous potential to ultimately solve the many worsening gaps and challenges in the insurance model.

Waiting for regulatory clarity or delaying to completely de-risk AI may prove to be a detrimental path with first movers having an insurmountable advantage.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.

Flood Risk Solutions From Across the Pond

Growing flood risks challenge U.S. cities with low insurance adoption; the U.K.'s technology-driven approach to resilience offers a solution.

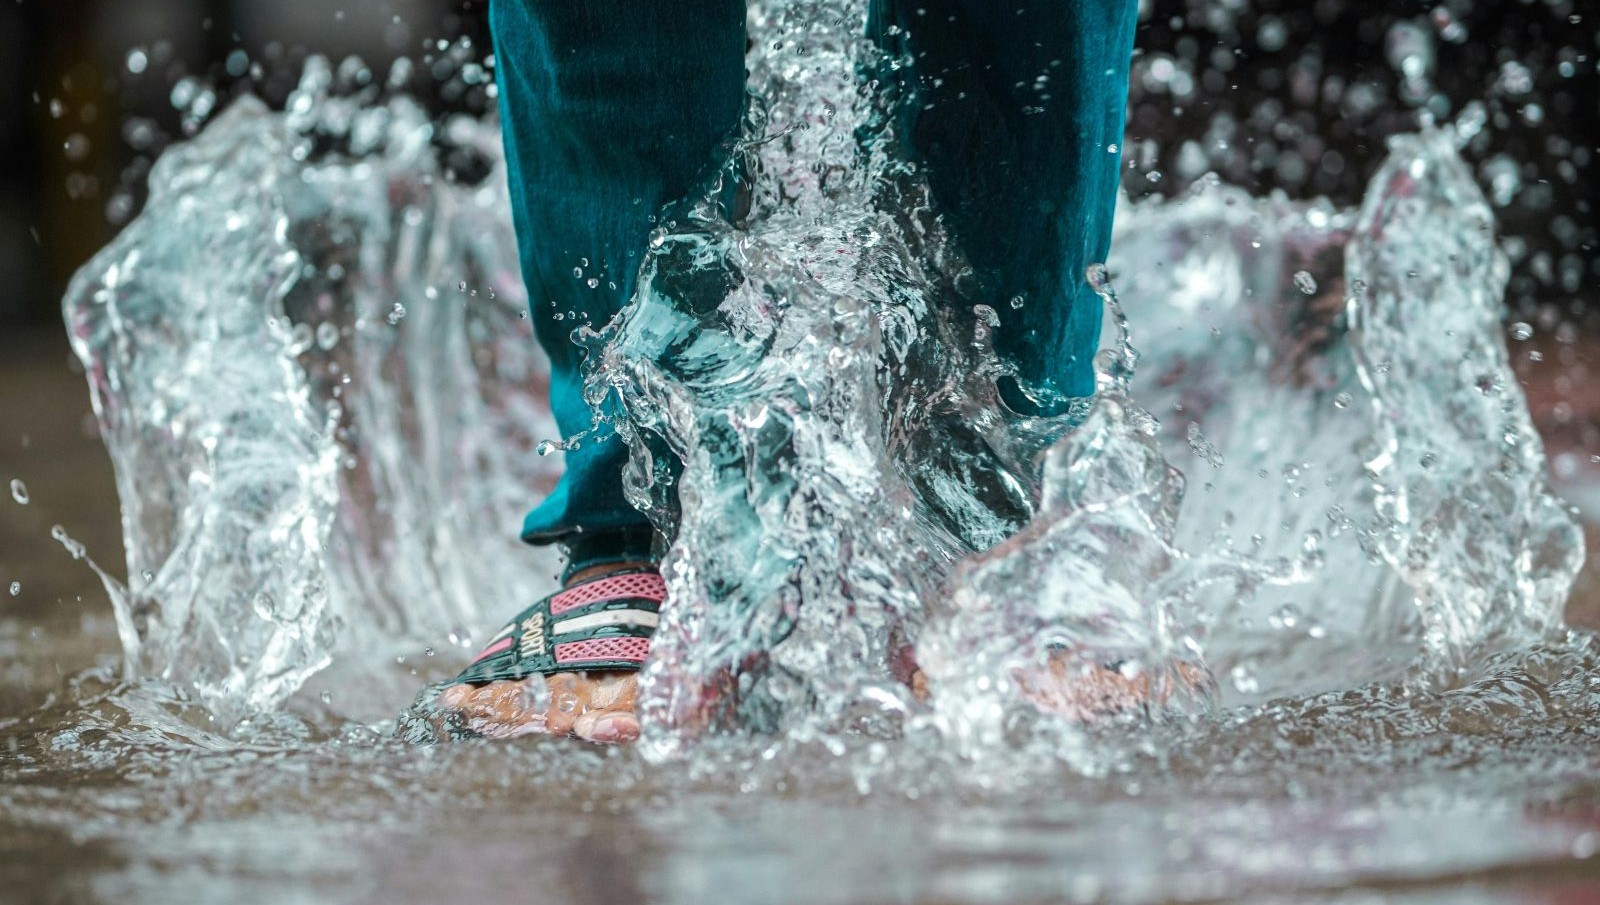
Person in long pants with shoes on standing in a large puddle with water splashing up around them

Flooding is a hot topic at Climate Week NYC, as the risk of major flood events grows more frequent and destructive in the U.S., with insurance being a prevailing issue and leaders under increasing pressure to shift from reactive disaster response to proactive resilience.

In this article, I explore how U.S. risk professionals, as well as other leaders at Climate Week NYC and beyond, can learn from the U.K. in building both short- and long-term resilience.

High flood risk – low insurance uptake

Flood insurance in the U.S. is primarily offered through the National Flood Insurance Program (NFIP), run by FEMA, with some support from a small but growing private market. Homeowners, renters, and businesses in more than 20,000 participating communities can purchase coverage, whether they live in high- or low-risk flood zones.

For those in federally designated high-risk areas with a government-backed mortgage, flood insurance is often mandatory. However, uptake remains low in many other regions where flooding is still a real threat.

The majority of businesses (56%, according to a survey by Chubb) do not buy flood insurance, as they assume it is included in their commercial property policy. Many households also mistakenly believe their standard homeowners insurance covers flood damage, leaving them financially vulnerable after disasters.

Proven solutions from the U.K.

At Previsico, we have seen how the increase in flood risk has been driven by the complex dynamics of climate change, rapid urbanization, and aging infrastructure, and we are keen to share the solutions that have proved most effective in the U.K.

In the U.K., which has spent decades navigating flood risk in densely populated, flood-prone areas, we now have a proven model for integrated flood resilience with a multi-layered approach that brings together technology, tools, and stakeholders.

By sharing insights, we have been able to reduce damage, protect communities, and lower economic losses. We are also able to unlock faster, fairer recovery, and provide incentives for smarter risk management, with actionable insights.

Building flood risk into decision making

The U.K. now has both national and local policies that require developers to assess flood risk before construction, especially in flood-prone areas. Where development does proceed, it must meet strict resilience criteria, such as raised floor levels, permeable surfaces, and built-in flood defenses.

U.S. cities can benefit from this approach by embedding flood risk awareness into zoning laws, building codes, and design standards. While some U.S. cities are already doing this, the U.S. lacks a coordinated federal strategy, unlike the U.K., resulting in a more fragmented approach.

Avoiding development in high-risk areas is critical, but so is preparing new infrastructure for a wetter future. This includes climate-forward planning that accounts for future flood risk, not just historical patterns.

Enhanced building codes, requiring features like elevated electrical systems, water-resistant materials, and flood barriers, can dramatically reduce damage. Meanwhile, integrating green infrastructure, such as swales, rain gardens, and green roofs, helps to manage stormwater and ease pressure on city drainage networks.

Technology is changing the game

Early warning systems have emerged as one of the most important innovations in managing flood risk across the U.K. Forecasting is critical, particularly for storm water flooding, which is both the most common and the most difficult to predict. These systems can offer warnings up to 48 hours in advance, allowing time for vital preparations and risk mitigation. 

Accurate flood forecasting relies on highly detailed, real-time data. The most effective solutions integrate high-resolution weather forecasts, detailed topographic mapping, and advanced hydrodynamic modeling to simulate flood scenarios and predict potential impacts.

This level of precision enables targeted alerts to be sent to residents, businesses, first responders, and city officials, giving communities time to move vehicles, safeguard property, or evacuate. Lack of warning was a major issue in the recent Texas floods, which, according to AccuWeather, led to an estimated $18-22 billion of losses, capturing both direct and indirect losses, very little of which was insured.

Speed and accuracy are critical

For insurers, access to precise, real-time flood forecasting enables the delivery of alerts to policyholders, helping reduce damage and, in some cases, prevent claims altogether.

This level of accuracy is especially powerful when paired with parametric insurance. This is where location-specific data triggers automated payouts with no lengthy loss assessments. Funds provide immediate support when it matters most, such as for relocating equipment, installing flood barriers, or coordinating community evacuations.

In contrast, many people in the U.S. still rely on systems that provide alerts only after water levels rise or drainage systems are overwhelmed. By adopting predictive, hyper-local forecasting technologies, like those used in the U.K., and integrating them with parametric insurance models, U.S. cities can move from crisis response to proactive risk management.

Collaboration makes it possible

Flood resilience in the U.K. is underpinned by cross-sector collaboration, where national agencies, local governments, insurers, water companies, researchers, and community groups all play a role in managing flood risk. This holistic model results in smarter, more coordinated flood planning and response.

The U.S. can replicate this by forging partnerships with tech firms, insurers, and grassroots organizations. For example, urban planners can collaborate with climate scientists to model future risks, while insurers can provide incentives or solutions for flood-resilience and preparedness.

In the U.K., insurers are increasingly embedded in the resilience conversation, supporting initiatives like risk-reduction incentives. For U.S. insurance markets, this kind of collaboration presents a path to shared accountability, stronger risk models, and lower payouts.

A way to fast-track U.S. flood resilience

Flood resilience isn't just about building higher walls, it's about predicting risk, planning smarter, and acting earlier. U.S. cities, many of which are facing new or worsening flood threats--including New York, which has suffered greatly in recent years--can benefit hugely from this model of integrated, technology-driven resilience.

By investing in real-time flood forecasting, embedding flood risk in planning and construction, and promoting multi-stakeholder collaboration, the U.S. can not only better protect communities but also foster greater trust among governments, insurers, and the public.


Jonathan Jackson

Profile picture for user JonathanJackson

Jonathan Jackson

Jonathan Jackson is CEO at Previsico.

He has built three businesses to valuations totaling £40 million in the technology and telecom sector, including launching the U.K.’s longest-running B2B internet business.

A Powerful Chain Reaction: The Financial and Operational Impact of GenAI and Agentic AI Across the Insurance Value Chain

Explore how GenAI and Agentic AI are transforming insurance, driving financial gains, operational efficiency, and customer value across the entire insurance value chain. Download now.

ai robot hand


unleash ai

AI is no longer a future promise – it’s a present reality reshaping the insurance industry. This new Majesco report explores how insurers can move beyond pilots to enterprise-wide transformation. Discover practical uses cases, proven financial outcomes, and strategies that unlock efficiency, reduce costs, and elevate customer experiences. This report is your roadmap to harnessing GenAI and Agentic AI to create lasting competitive advantage. Download now to see how insurers are turning innovation into measurable impact.

Read Now


Sponsored by ITL Partner: Majesco


ITL Partner: Majesco

Profile picture for user majescopartner

ITL Partner: Majesco

Majesco isn’t just riding the AI wave — we’re leading it across the P&C, L&AH, and Pension & Retirement markets. Born in the cloud and built with an AI-native vision, we’ve reimagined the insurance and pension core as an intelligent platform that enables insurers and retirement providers to move faster, see farther, and operate smarter. As leaders in intelligent SaaS, we embed AI and Agentic AI across our portfolio of core, underwriting, loss control, distribution, digital, and pension & retirement administration solutions — empowering customers with real-time insights, optimized operations, and measurable business outcomes.


Everything we build is designed to strip away complexity so our clients can focus on what matters most: delivering exceptional products, experiences, and long-term financial security for policyholders and plan participants. In a world of constant change, our native-cloud SaaS platform gives insurers, MGAs, and pension & retirement providers the agility to adapt to evolving risk, regulation, and market expectations, modernize operating models, and accelerate innovation at scale. With 1,400+ implementations and more than 375 customers worldwide, Majesco is the AI-native solution trusted to power the future of insurance and pension & retirement. Break free from the past and build what’s next at www.majesco.com


Additional Resources

The Second Half of Agentic AI

Read More

The Insurance Alignment Gap: Where Insurer Priorities and Customer Protection Needs Converge…and Diverge

Read More

Operational Value and Impact of GenAI and Agentic AI

Read More

Reimagining Insurance for a More Resilient Future

Read More

State of Core Solutions Transition: Which Tech Priorities Are Being Carried Out?

Read More

Smarter life underwriting through patented automation

Munich Re’s alitheia platform helps life insurance carriers automate underwriting with patented AI and natural language processing—delivering faster, more accurate decisions through flexible, modular integration.

rowing

Smarter life underwriting through patented automation

In an industry where precision and speed are paramount, underwriting has long been a balancing act between risk accuracy and operational efficiency. But with the expansion of alitheia, a rapid risk assessment platform from Munich Re Life US, carriers now have more flexibility than ever to automate without compromise.

In a landscape where underwriting must evolve to meet rising consumer expectations and the drive toward automation, alitheia stands as a beacon of what’s possible when data science, machine learning, and Munich Re’s deep risk expertise converge.

Modular flexibility meets strategic integration

alitheia offers a modular platform that supports a wide range of risk assessment capabilities. Carriers can adopt it as a full end-to-end solution or integrate specific components – such as predictive models, configurable rules engines, and underwriter workbenches – into their existing systems.

Carriers have seen instant offer rates climb to 50%, tripling industry averages. And with decisions made within 48 hours in 75% of cases, the platform is setting new benchmarks for underwriting speed and accuracy. [1]

Patented innovations that power smarter automation

Backing these capabilities are newly awarded U.S. patents for proprietary methods that optimize the sequence of underwriting requirements and interpret free-form text using advanced natural language processing (NLP). These innovations help carriers streamline workflows, reduce costs, and accelerate decision-making, while maintaining rigorous risk standards.

From bee stings to breakthroughs: Natural language processing that understands context

One of the most compelling aspects of alitheia is its ability to parse and contextualize free-text responses in insurance applications. In traditional systems, benign entries like “I stubbed my toe” could trigger manual reviews, slowing down the process. alitheia’s natural language processing engine maps such responses to a medical ontology, enabling instant decisions for non-medically significant disclosures.

This capability can increase the number of cases processed instantly by an additional 3-5%, reducing reliance on full underwriting and improving applicant experience. [1]

John Hancock puts alitheia to work

John Hancock’s collaboration with Munich Re demonstrates how alitheia can be tailored to a carrier’s unique underwriting philosophy. By leveraging automated EHR assessments and proprietary models, John Hancock is focused on enhancing the buying experience for consumers and agents, as well as greater efficiency for their underwriters, with the goal of delivering faster turnaround times. [2]

Learn more about modernizing with alitheia

Discover how alitheia’s patented technology and modular architecture can support life insurance underwriting. Whether a comprehensive solution or targeted enhancements are needed, alitheia delivers the flexibility and power to help carriers achieve their automation goals.

Learn More


Sponsored by ITL Partner: Munich Re


[1] Based on carrier experience. Results may vary.

[2] John Hancock Disclosures:
Policy issuance is not guaranteed as any life insurance purchase is subject to completion of an application, including health questions, and underwriting approval. John Hancock may obtain additional information, including medical records, to evaluate the application for insurance; and after the policy is issued, to identify any misrepresentation in the application.
Insurance products are issued by: John Hancock Life Insurance Company (U.S.A.), Boston, MA 02116 (not licensed in New York) and John Hancock Life Insurance Company of New York, Valhalla, NY 10595. MLINY091525144-1


ITL Partner: Munich Re

Profile picture for user MunichRepartner

ITL Partner: Munich Re

Munich Re Life US, a subsidiary of Munich Re Group, is a leading US reinsurer with a significant market presence and extensive technical depth in all areas of life and disability reinsurance. Beyond vast reinsurance capacity and unrivaled risk expertise, the company is recognized as an innovator in digital transformation and aims to guide carriers through the changing industry landscape with dynamic solutions insightfully designed to grow and support their business. Munich Re Life US also offers tailored financial reinsurance solutions to help life and disability insurance carriers manage organic growth and capital efficiency as well as M&A support to help achieve transaction success. Established in 1959, Munich Re Life US boasts A+ and AA ratings from A.M. Best Company and Standards & Poors respectively, and serves US clients from its locations in New York and Atlanta.


Additional Resources

Drug deaths a concern for life carriers

A 25% increase in substance abuse death rates in the college-educated population is a particularly worrying trend for the life insurance industry.

Read More

EHRs transform life underwriting

Our extensive study confirms the value of electronic health records (EHRs) across life underwriting use cases.

Read More

Life insurance fraud trends

Munich Re’s survey reveals which types of fraud have been on the rise for U.S. life insurers in recent years.

Read More

Recent patterns in cancer claims

Cancer is the most common cause of death for the life insurance population. Munich Re analyzes recent trends.

Read More

The digital future of life insurance

Leverage emerging technologies to improve operational efficiency, enhance underwriting processes, and expand insurance accessibility.

Read More

Hidden Risks in Teen Cellphone Bans

Increasing school cellphone bans create liability exposures that insurance professionals must help clients navigate carefully.

Overhead view of a person holding a black phone in their hand

As classes start this fall, parents across the country are surprised to see some school districts are doubling down on their cellphone policies. Similarly, other organizations that serve youth—such as camps, houses of worship and recreation programs—also are implementing stricter cellphone bans in an attempt to help young people focus.

While insurance agents and brokers shouldn't be involved in making these kinds of decisions for organizations, they can advise their clients as to potential risks inherent in a blanket cellphone ban. Certain issues might pose a challenge.

Phone damage

Schools and other organizations have become creative in how they keep kids away from their phones, from designated storage areas such as classroom caddies to requiring phones be kept in their lockers.

Damaging or losing phones is a very tangible risk—and a policy gap—when organizations elect to take them away from the students for a short time. A new smartphone can cost anywhere from $500-$1,200. Multiply that by dozens of students' phones lost or damaged in a given month, and it can be a budget breaker.

Of course, not all phone storage methods are equal. Asking students to dump their phones in a common caddy at the beginning of class or an event can easily lead to cracked screens, spills and students accidentally taking home the wrong phone. One potential way to manage that risk is to designate a specific, numbered spot for each teen's phone.

Medical situations

Young people who have diabetes or other chronic health conditions may use their phones to monitor their blood sugar levels, food intake or other important information. If an organization attempts to take their phone away from them, it could not only cause a potential health emergency but also could lead to a costly lawsuit because of negligence.

Any policy banning cellphones must make an exception for medical situations. Otherwise, the organization may be exposed to major liability if an incident occurs.

Emergencies

One nuanced risk area—especially in schools—is how cellphone access plays out during emergencies. On the one hand, having a cellphone can be incredibly helpful. Teens may use their devices to report an incident, contact emergency services or communicate with loved ones. In some cases, student cellphone calls during active shooter situations have made the difference between life and death.

However, cellphones can also be harmful in emergency scenarios. Widespread use during a crisis may:

  • Spread misinformation and panic, especially through social media.
  • Jam cellphone towers, potentially disrupting communication for emergency responders.
  • Accelerate the arrival of parents and community members, which can complicate evacuation or lockdown procedures.

Organizations must weigh these risks carefully. A well-crafted policy should strike a balance, ensuring teens can access their phones when truly needed, while minimizing the potential for unintended consequences.

The DONUT approach

Risk management of a cellphone ban all ties back to policy. If an organization wants to safeguard itself against potential insurance claims or complaints, it should work with its attorney to develop a solid policy to back it up.

It can be helpful to use the acronym DONUT as a guiding principle:

  • D – Development – The first step in developing a clear policy is taking the time to include all stakeholders who will be affected. It's important to frame the potential new policy in a positive way, showing how it can ultimately increase test scores and decrease bullying.
  • O – Opportunity – Organizations need to give all people an opportunity to offer input into the intricacies of the policy. This includes both the people who will be enforcing the ban (such as staff members or volunteer leaders) and the teenagers themselves.
  • N – Notice – It's always a good idea to give the young people of an organization proper notice about a cellphone ban—through a medium they actually use. In other words, group texts and social media posts are more likely to get through to their intended audience than paper letters and emails.
  • U – Uniformity – The teens of an organization shouldn't be the only ones whose cellphone use is limited. How would it look, for example, if a camp forbade cellphones, but the camp counselors were always on their phones. Adults should be setting a good example by putting away their devices, as well.
  • T – Timeliness – Once the cellphone ban goes into effect, enforcement should be consistent and timely. Staff members need to implement consequences at the time of the infraction—not a day or two later.

Depending on an organization's previous rules regarding cellphones, making changes could trigger some culture shock. Therefore, it may be best to try a phased approach. For example, rather than requiring all youth to set their phones aside at the start of an activity, class or camp, organizations may instead ask that they keep the phones on "silent." They're more likely to get buy-in if they ask for small changes at the beginning.

While cellphones can create risk surrounding teenagers, so, too, can cellphone policies. That's why it's important that organizations perform enough research ahead of time to anticipate potential problems.


Sharon Orr

Profile picture for user SharonOrr

Sharon Orr

Sharon Orr is director – risk control, education for Church Mutual Insurance and has been with the organization for almost 20 years. She has worked in the safety field for more than 25 years, including time with U.S. Army 513th Military Intelligence Brigade and loss prevention and asset protection for Fortune 500 companies. 

What Robotaxis Mean for Auto Insurance

Momentum for robotaxis is starting to make clear how companies will divide up the hardware, software and operational work — and how insurers must adapt.

Image
robotaxi future cars

Recent announcements of two new robotaxi services in the U.S., together with a robotaxi-related surge in Tesla stock, seem to be raising lots of questions about how quickly autonomous vehicles (AVs) will become a major factor on our streets and about what they will mean for auto insurers.

Once you understand the "stack," to use the Silicon Valley term for the layers of hardware, software and operational service that make up a robotaxi service, the implications start to become clear.

So let's have a look. 

The reason for the recent surge of interest in robotaxis stems in part from last week's announcements by Amazon and May Mobility. Amazon said its toasterlike Zoox AVs will start operating in Las Vegas, while May Mobility said it will start offering rides in Atlanta in its autonomous vans, which will be offered to those who hail a ride through Lyft. 

In addition, Tesla fans are out in force again, boosting the stock with claims such as that the company will be able to remove safety drivers from its robotaxis imminently and can thus have thousands of the vehicles operating fully autonomously by the end of the year. 

As backdrop, there was a highly publicized report from Goldman Sachs in June that says fully autonomous robotaxis will be generating $5 billion of revenue in the U.S. by 2030. That's a lot of robotaxi rides.

I'd urge some caution on the pace. Zoox is just offering rides between five points in Las Vegas. May Mobility is operating only in a section of Atlanta, with what the CEO calls “a few hands’ worth of vehicles” and with safety drivers behind the wheel. Tesla is operating perhaps three dozen cars in Austin, Texas, all with safety drivers, and, while CEO Elon Musk said earlier this year that millions of autonomous Teslas will be on the road by the second half of next year, his projections have been wildly overoptimistic for a decade now. 

Still, robotaxis seem to finally be on a clear glide path toward widespread adoption. 

Google's Waymo says it has 2,000 AVs on the road in Phoenix, San Francisco, Los Angeles, Austin, and Atlanta, completing hundreds of thousands of paid rides per week. Waymo plans to keep steadily increasing the number of cities it serves. Wired magazine says that, "in China, WeRide, Baidu’s Apollo Go, and Pony.ai are all running robotaxis in multiple cities; WeRide has started operations in Abu Dhabi, too." Regulators in Beijing and Shenzhen are allowing the robotaxis to operate without safety drivers, and Abu Dhabi encourages AVs in special zones. So, while Europe is moving somewhat slowly, there is plenty of international competition to keep up the pressure for improvements in the technology and for deployment. 

What does this all mean for auto insurance?

Let's look at the stack. It's dividing up into the hardware (the car), the software (the artificial intelligence that operates the car) and the operator (the company that will keep the cars recharged, positioned so they can get to passengers quickly, cleaned, and so on). 

Insurers could have a role at any of those tiers but will likely have little to do with the software. In any case, any insurance will be commercial. Personal insurance won't be a factor for the simple reason that people don't need to insure their driving if they aren't driving. 

The hardware

For a time, General Motors tried to take on all three layers in the stack. It made the cars that used the AI developed by its Cruise subsidiary, which also operated a robotaxi service. But GM shut Cruise down last year and is focusing on incorporating its AI into existing lines of vehicles. Tesla is also trying to handle all three layers, while offering insurance, to boot, but as I've said several times now (including here), I don't think Tesla can pull it off. Musk is just using cameras as sensors, while others are using radar and LIDAR, as well. Musk does have better access to certain kinds of data than other robotaxi companies because he has cameras in every car and has so many Teslas on the road, but I don't see how having better maps can cover for the lack of real-time data from sensors that are more sophisticated than cameras. Tesla may eventually have usable technology, but Musk is years behind Waymo, and I think he'll stay there. 

If Musk does succeed with his grandest vision, he would introduce an opportunity for personal auto insurance in the robotaxi world. That's because he has said individual owners will be able to upgrade their software with Tesla's latest AI capabilities and make their cars available as part of a robotaxi fleet that Tesla would coordinate. Owners would presumably be responsible for the upkeep of their cars, so they might buy insurance to cover their liability.

But if I'm right that Tesla will be a minor player in robotaxis for the foreseeable future, then the hardware is a separate layer. It splits into two pieces: the manufacturing and the ownership. 

The role of insurance in manufacturing will be what it's always been. Car makers will have to worry about product liability and could purchase insurance, but the behemoths that do that sort of work will likely self-insure. 

Ownership could be a different question. Just about nobody wants to own assets these days. Everybody wants to be an asset-light company like AirBnB and not have to commit the hundreds of billions of dollars that robotaxis will cost. So it's not clear yet who will own the vehicles. If, as I suspect, huge companies — perhaps formed just for the purpose — own the cars, they'll likely self-insure. If not, there could be opportunities for commercial insurers.

The software

The AI is where the magic happens, and the work is so expensive that it is either being done by huge companies now or by startups that will surely be acquired by massive companies. So, yes, this layer will surely be self-insured. There's room for commercial insurance on, say, theft of business secrets but not for personal auto insurers.

The operators

Who will own this layer isn't quite clear yet. Waymo, for instance, is operating its own network at the moment, and that makes total sense at this stage of the technology. Waymo needs to have people in-house available when one of its vehicles runs into a problem, both to smooth over issues for paying customers and to learn where problems are, so the underlying AI can continually be improved. But Waymo and others won't always have to own the whole operating process.

Yes, Waymo will need to always be running the AI in its cars, but that doesn't mean it will have to handle the dispatching, the recharging, the cleaning and so on, and there could be opportunities for insurance there. 

I suspect the dispatching will be handled by big companies. Uber and Lyft have been doing a nice job of positioning themselves as partners to AV companies. Google could also muscle its way into dispatching through its maps — if you're asking about a destination, Google could easily offer you a ride. So there could be an interesting battle here (perhaps with antitrust implications for Google), but I don't think it will matter to insurers because the winners will self-insure against any customer issues.

The rest of the operations, though, could create opportunities for commercial insurers. The cleaning and recharging could well be handled by smaller companies, perhaps different ones in different cities, and they could well want to lay off some of the risk of dealing with customers, who can have any number of hard-to-predict problems. 

But, again, no luck for personal auto insurance.

As I've said, there are plenty of reasons to think that some of the claims about robotaxis are hyperbole, but if Goldman Sachs is even close to right that robotaxis will be generating $5 billion in revenue by 2030, vs. my back-of-the-envelope calculation of maybe $100 million this year, then we're on an exponential curve. And as all those companies that didn't come to grips with the pace of Moore's law have learned over the past few decades, exponential change can sneak up on you really fast. It's always wise to be thinking ahead.

Cheers,

Paul 

P.S. If you really want to think ahead, imagine what cities will look like if there is the sort of takeover by robotaxis envisioned in this article at Vox: "A self-driving car traffic jam is coming for US cities." 

The underlying changes will be deceptively simple. Parking garages, which take up as much as 40% of the space in some cities, will pretty much disappear. So will curbside parking. But the number of cars on the road will increase drastically. 

When you go from there, though, there could be all sorts of effects. Maybe apartment buildings replace the parking garages, and the additional housing makes cities less expensive and draws more people. Maybe having even more people in cities facilitates time in the office and leads to more office buildings, too. Maybe restaurants and other small businesses benefit greatly from increased foot traffic... or maybe they don't, because robotaxis are taking people straight to their destinations, so they aren't walking and window shopping. And maybe robotaxis make it easier to live in suburbs and exurbs, so city populations actually diminish and people work at home more.  

The good news is that cities won't change nearly as fast as the car fleet does. It takes a lot longer to tear down and replace a parking garage or rip up city streets than it does to beam a software update to a car. 

But I still find this kind of thing interesting to ponder and thought you might, too. 

AI Can Power Personalized Life Insurance Quotes

Life insurers can replace generic quotes with AI-powered personalized proposals that address individual customer circumstances and needs.

An artist’s illustration of artificial intelligence

Life insurance quotes typically feel like form letters. That's because most insurers still use off-the-shelf policy administration software that prioritizes core functions like policy issuance, billing, and claims processing. The proposal generation component receives minimal attention during system development, so it fails to address individual customer circumstances and preferences.

Here's the difference between a traditional proposal and the sort made possible by today's AI:

Traditional Proposal: 

"Dear Customer, thank you for considering ABC Life Insurance. We are pleased to offer you a life insurance plan with standard coverage options at competitive rates."

AI-powered Proposal: 

"Dear Sarah, we understand your priority is protecting your family's future while keeping monthly expenses manageable. Based on your age, health profile, and financial goals, we've designed a tailored plan that secures your children's education and mortgage while giving you flexibility for future needs."

When potential policyholders receive standardized proposals, a significant disconnect emerges between customer expectations and actual delivery. Standardized proposals position insurance companies as outdated in an era where personalization has become standard across industries. Trust erodes when initial quotes fail to acknowledge a customer's specific financial situation or coverage needs.

That's why insurance companies should prioritize implementing life insurance policy administration software that generates personalized proposals and quotes.

Smart Proposal Generators in Policy Administration Systems

AI-powered proposal generators in policy administration systems mark a new era in insurance technology. These advanced platforms leverage artificial intelligence and automation capabilities to streamline personalized proposal creation for customers, unlike their traditional counterparts.

AI proposal generators consist of four essential components that work together to streamline quote distribution:

  • Automated Data Capture – These generators enable life insurance policy administration software to pull insured details directly from multiple sources, including applications, CRM records, and third-party databases. This eliminates manual data entry and ensures information accuracy across all proposal documents.
  • Instant Formatting Capabilities – AI maintains brand standards while following carrier-specific requirements. Templates automatically adjust based on product types and regulatory guidelines without compromising visual consistency.
  • Real-Time Validation – Built-in validation mechanisms flag missing information before client presentation. This prevents incomplete proposals from reaching potential policyholders and reduces back-and-forth communication.
  • Comparison Views – The system analyzes pricing and coverage differences across multiple carriers, presenting unified comparisons that help customers make informed decisions.

Insurance companies benefit significantly from implementing life insurance policy administration systems equipped with AI-powered proposal generator systems. Quote processing time drops from minutes to seconds when multiple carrier quotes require conversion into client-ready proposals. These capabilities enable underwriters and insurance managers to focus on advisory services instead of administrative tasks.

These systems eliminate repetitive data entry tasks while ensuring faster customer responses. When clients receive accurate proposals quickly, insurer professionalism increases, and trust builds more effectively throughout the customer relationship.

How AI Proposal Generators Modernize Proposal and Quote Distribution

AI-powered proposal generators in life insurance policy administration systems work as smart workflow engines that change how insurers deliver tailored quotes. These tools create a simplified path from customer data intake to final delivery.

  1. Customer Details Intake and Data Preparation: AI systems collect and normalize client information automatically from multiple sources, including forms, emails, and CRM records. This first step removes manual data entry and reduces errors while creating clean, well-laid-out information for processing.
  2. Product Configuration and Pricing: The AI models analyze customer data against available products and calculate premiums using dynamic pricing models. The system creates accurate quotes based on business logic and pricing structures quickly. Complex scenarios like volume pricing or custom tiers are handled seamlessly.
  3. Content Generation and Personalization: The AI models enable life insurance policy administration systems to create targeted proposals by adding relevant sections based on the client's type and requirements. Product features, case studies, and testimonials are recommended by the system while brand consistency stays intact across all documents.
  4. Compliance and Risk Controls: Built-in compliance features ensure all proposals generated by life insurance policy administration software meet regulatory standards and internal guidelines. The AI models confirm eligibility criteria and verify that proposals follow jurisdiction-specific requirements before moving forward.
  5. Workflow Automation, Approvals, and Omnichannel Distribution: The system routes proposals through approval workflows, tracks engagement metrics, and delivers documents through email, messaging platforms, or client portals. This complete automation supports scalable proposal generation operations while life insurers retain control of quality. A recent insurtech survey cites that the worldwide insurance automation investment market is projected to touch 1.3 billion USD by 2031.
Key Challenges Resolved by AI Proposal Generators in Policy Administration Systems

Modern technology has solved many problems that come with manual proposal generation. AI-powered life insurance policy software tackles these age-old challenges head-on.

  1. Accelerated Proposal Creation: Traditional proposal development requires weeks of coordination between underwriters, agents, and administrative staff. AI-powered systems complete this entire process within seconds. Insurance agents can eliminate intensive proposal data compilation tasks and paperwork. Teams can focus on client consultation and relationship building rather than administrative processing. The speed improvement proves substantial when measured against manual methods. Where traditional systems require multiple touchpoints and approval cycles, AI handles data analysis, pricing calculations, and document generation simultaneously.
  2. Enhanced Accuracy Through Automated Validation: Human errors frequently occur during manual calculation processes and data interpretation stages. AI systems perform continuous data cross-checks and pattern recognition to identify discrepancies before proposal finalization. The technology flags inconsistencies in premium calculations and coverage recommendations that manual review might overlook. Automated validation mechanisms ensure that customer data aligns with product eligibility criteria and pricing models. This eliminates calculation errors that damage insurer credibility and customer trust.
  3. Streamlined Compliance Management: Regulatory requirements vary across jurisdictions and product lines, creating compliance complexity for insurance companies. AI-powered policy administration systems automatically verify regulatory standards and internal guidelines during proposal generation. The technology recognizes compliance obligations specific to different markets without relying on manual checklists or institutional knowledge. Built-in compliance features ensure proposals meet all necessary regulatory standards before client presentation. This eliminates the risk of legal penalties and extensive compliance evaluations.
  4. Scalable Operations Management: Massive enrollment periods and periodical fluctuations challenge traditional proposal generation processes. AI systems process multiple applications simultaneously without requiring additional staffing resources. Insurance companies handle proposal volume spikes efficiently while maintaining consistent service quality. The technology scales proposal generation capacity based on actual demand rather than fixed resource allocation. This enables insurers to respond to market opportunities without operational constraints.
Final Words

AI-driven proposal generators are transforming policy administration systems used by insurance firms. These tools solve long-standing problems with traditional systems and streamline generic, time-consuming processes into customized workflows. Insurance companies can now offer tailored quotes that match each customer's specific needs instead of generic proposals.

The benefits go well beyond customization. Agents used to spend hours creating proposals manually, which led to errors and inconsistencies. These intelligent systems now handle everything automatically - from collecting data to delivering the final product - while meeting accuracy and compliance standards. This change lets insurance professionals build better client relationships instead of getting bogged down with paperwork.