Sanity Prevails on Award of TTD
An appeals court reversed a puzzling W.C.A.B. decision that awarded temporary total disability benefits beyond five years from the date of injury,
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Richard (Jake) M. Jacobsmeyer is a partner in the law firm of Shaw, Jacobsmeyer, Crain and Claffey, a statewide workers' compensation defense firm with seven offices in California. A certified specialist in workers' compensation since 1981, he has more than 18 years' experience representing injured workers, employers and insurance carriers before California's Workers' Compensation Appeals Board.
One of the first employer concerns has to be preventing and responding to employee injuries when a disaster occurs.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Kimberly George is a senior vice president, senior healthcare adviser at Sedgwick. She will explore and work to improve Sedgwick’s understanding of how healthcare reform affects its business models and product and service offerings.
Mark Walls is the vice president, client engagement, at Safety National.
He is also the founder of the Work Comp Analysis Group on LinkedIn, which is the largest discussion community dedicated to workers' compensation issues.
The accident in which an Uber driverless car hit and killed a pedestrian Sunday night in Tempe, AZ, got us talking about how innovation should progress in a risky world. We worry that Uber hasn’t always been as careful as, say, Google/Waymo and GM/Cruise in testing its autonomous technology. An investigation will tell the tale soon enough in this particular instance (one of the advantages of all those sensors on driverless cars), but we’ll still be left wrestling with a world in which innovating can place people at risk, but in which not innovating might even be more dangerous. We can’t just sit still in a world where 1.25 million people die in traffic fatalities each year.
Our CEO, Wayne Allen, took up the pen to address the role we intend to play on innovating amid risk:
"I want to be super clear. We at ITL and Innovator’s Edge are going to increasingly take positions about what 'should be.' The rate at which certain technologies are being introduced into the marketplace outpaces the ability of lawmakers and even regulators to keep up, including those in the insurance world. Governmental authorities have jurisdiction over bits and pieces of the technology ecosystem, but it is rare for a single body to have complete authority over all the concerns about privacy, discrimination, consumer safety, etc.
"It is, therefore, incumbent on our industry, the folks who are supposed to manage risks of all kinds, to step forward and lead. Let’s provide innovation at the speed of reason.
"We will never advocate for the tempering innovation for the sake of antiquated processes. No. But we advocate for everyone to cinch up their chin-strap and do what’s right.
"Consider chatbots. If chatbots are as much a commodity as many tell me they are, then anybody could roll them out to a carrier, right? Well, what if it turns out that the data transmitted to a chatbot is personal financial information or personal information about a health condition or relates to an accident and includes health information? Shouldn’t we be asking questions about how secure these chatbots are? How safe is the data being transmitted? Shouldn’t any company integrating chatbot technology in its claims process—or any customer communication, for that matter—verify that the bot and the path through which the information passes meet a standard for privacy?
"What about autonomous vehicles? Should we be surprised if not all autonomous technology is created equal? Could one company’s technology be more secure, more heavily tested, just plain better than another? Are there standards for testing and product rollout that should be implemented? Should we as an industry simply take the position that we will not insure any vehicle (irrespective of the creative ways insurance can and will be built into the experience) that does not meet certain standards? If we do not, I am certain some enterprising politician will roll out a solution that will be the worst possible result, will likely be in line with what some lobbyist representing some corner of some industry wants, will stymie innovation and will be nearly impossible to overturn.
"If you agree with me and want to help provide innovation at the speed of reason, for the benefit of us all, please email me at wallen@innovatorsedge.io. The table stakes need to be known, and they need to be raised."
Have a great week.
Paul Carroll
Editor-in-Chief
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Paul Carroll is the editor-in-chief of Insurance Thought Leadership.
He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.
Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.
Flood and earthquake insurance work well at the macro level, but try to buy a policy, and you see the problems quickly.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Vijay Padmanabhan is vice president of marketing at AIR Worldwide, which provides catastrophe risk modeling solutions that make individuals, businesses and society more resilient.
States take different approaches to choosing workers' comp doctors, but ranking based on outcomes always delivers benefits.
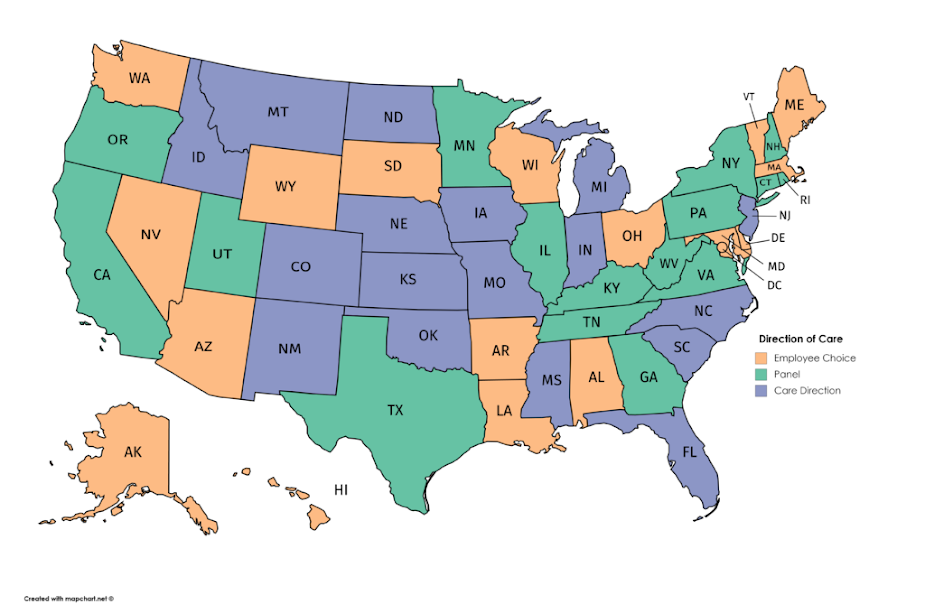
Throughout this series, I have stressed the importance of connecting workers’ comp patients with great doctors at their time of need and how this results in an average of a 10% reduction in claims costs. I’ve also talked about the role of PPOs and EPOs. Next up: outcomes strategies for each jurisdiction. Workers’ compensation is determined state-by-state, requiring any national workers’ comp company to adhere to variations in the laws. Some states provide excellent control over care, while others allow so much choice that it can seem like there is no strategic use for an outcomes-based network. States use three main categories of jurisdictional control: panel (employee has to select from your list of doctors), care direction (you tell the employee who to use) and employee choice (employees choose their doctors on their own). The graphic below provides a visual breakdown of each state’s model:
Despite what you might think, outcomes can play a meaningful role in any of these jurisdictions. Let’s discuss each model in more detail. Panel States In a panel state, employees are required to choose their doctors from a list created by payers or employers. These can range from exclusive provider networks (EPOs) to simple panels. The employee could be mandated to use doctors on the list for the life of an injury (as in the California MPN), or the designated doctor could maintain control for at least a meaningful portion of the claim (e.g., Pennsylvania workplace panels). The important consideration is that the employee can typically select anyone on your list. There is no way to manage around average doctors in your network, so it is in your best interest not to file your entire PPO as your exclusive provider listing. If you do, your overall average outcomes drop to the average across all doctors included, and you will have little recourse if injured workers choose the worst doctors on your list. For this reason, it is critical to stay on top of who’s included. Remove poor performers to ensure that any provider on that list can be trusted at any time. See also: 2018 Workers’ Comp Issues to Watch My best practice recommendation is to “right-size” your EPO by first predicting how many doctors are necessary in each coverage area (typically about a 15-mile radius). Once you know your needs for appropriate coverage, then pull only that number starting with the best and working down the ranking. The tighter you keep participation, the more impact you will see on claims outcomes. A well-constructed model can leverage provider outcome and drive overall claims costs down by 10% or more. The downside of this model is the level of effort required to maintain your list. You should keep inclusion/exclusion criteria documented up front, so you have a structured plan for whom to keep and whom to remove. You also need to check in at least quarterly to remove anyone whose performance has dropped or who has moved or closed his or her practice. Typically, you are handing over a list and letting the employee select a provider. If there is a problem (such as a provider closing the practice and not notifying you), you probably won’t realize you have an issue until you hear from the injured worker’s lawyer. Key strategic driver: Focus on the providers in your listing at all times and keep the list tight. Care Direction States In a care direction state, the insurer or payer maintains the exclusive right to tell the injured worker which doctor to use. The biggest difference over a panel model is that providers can be selected in real time. This makes maintenance a lot easier because you don’t need to “right-size” the network and anticipate needs. What you do need is an integrated view of your networks that includes your scores. In care direction states, it is critical that the search engine your team uses to direct care shows the scores of the doctors. Any time a patient needs a doctor or specialists, you want your team selecting the best available provider proximate to the injured worker — not just the closest one in network. When outcomes as a measure first matured to the point where it was widely adopted, most people focused on using outcomes to select their networks for panel states. However, the care direction model actually has a higher potential ROI because you are always selecting the best provider at the time of need. In a panel state model, when I hand over a list, the average quality of all the doctors on the list will drive the impact on your claims population. In care direction, I am always selecting the best, which drives impact to the quality of your best doctors. In addition, because the scoring updates in real time, you are always making your care decision on the latest information at the time of need, not on the information available when you built your list. Also, your best strategy is to not limit yourself to your existing network. If you are looking for a top neurosurgeon in a rural area, and there are not any good options in your PPO, you should look for a high-scoring doctor outside your network before you send the patient a longer distance to an average doctor in your PPO. As I explained earlier in the series, the outcomes savings will almost always be more than the PPO discount. Key strategic driver: Always go for the best doctors available, keeping your scores integrated with your list. Employee Choice States Many people falsely believe that outcomes-based control strategies cannot work in a state that allows the employee to select whomever they want. This is not true. Soft channeling is a strategy that involves making targeted recommendations throughout the cycle of the claim. For example, selection of the doctors that show up on the workplace poster should be based on the best doctors nearby — not just the closest. Using outcomes scores when creating workplace panels helps encourage good choices without stepping on the rights of the employee. Another strategy for the employee choice model is to integrate scores into your billing workflow. If you see an initial consult from a poor-performing ortho, you have about two weeks before your claimant goes under the knife. If you can operationalize this strategy, you have the opportunity to reach out to the injured worker with a crafted message such as: “We typically recommend a second opinion in cases like yours; there is a great specialist not far from you. Would you like me to set up an appointment?” See also: The State of Workers’ Compensation The point is to not interfere with the injured worker’s choice while taking every opportunity to provide great options for the person to consider. If your scoring model is focused on quality-of-life outcomes such as less time away from work or lower disability rates at the end of care, you are providing a valuable service to that injured worker when you steer the person away from a doctor who has high infection rates and a high incidence of failed surgeries. Certainly, the potential ROI is not as significant as in other states, but you only need a small number of injured workers to choose a better doctor to recoup typical costs of implementing these strategies. Wrapping Up There are methods and strategies to leverage outcomes in all jurisdictions. Some jurisdictions are easier than others, and your ROI and level of effort will vary, but don’t lose sight of why this is important: Better care improves everyone’s outcomes. Better outcomes improve not only the bottom line but also the quality of life for people who get injured on the job. Better care results in happier and more productive employees, fewer costly complications, less legal friction and, ultimately, a better workers’ comp system. Throughout this series of articles, I’ve covered multiple aspects of outcomes-based networks, including important considerations and strategies. These are recommendations and best practices pulled from my experiences. You don’t have to hit a home run every time. If you simply get 5% to 10% of the claims away from bad doctors and into the care of great doctors, you will have significantly better results overall. Please reach out with questions and feel free to comment with ideas for additional articles on the future of workers’ comp. As first published in Claims Journal.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Gregory Moore is the former chief commercial officer of CLARA Analytics, a division of LeanTaaS and a leading predictive analytics company for workers’ compensation.
Prior to joining CLARA Analytics, Moore founded Harbor Health Systems, which he led for 16 years.
Functional silos are optimized for operational efficiency, but, as customer journeys change, are degrading the customer experience.
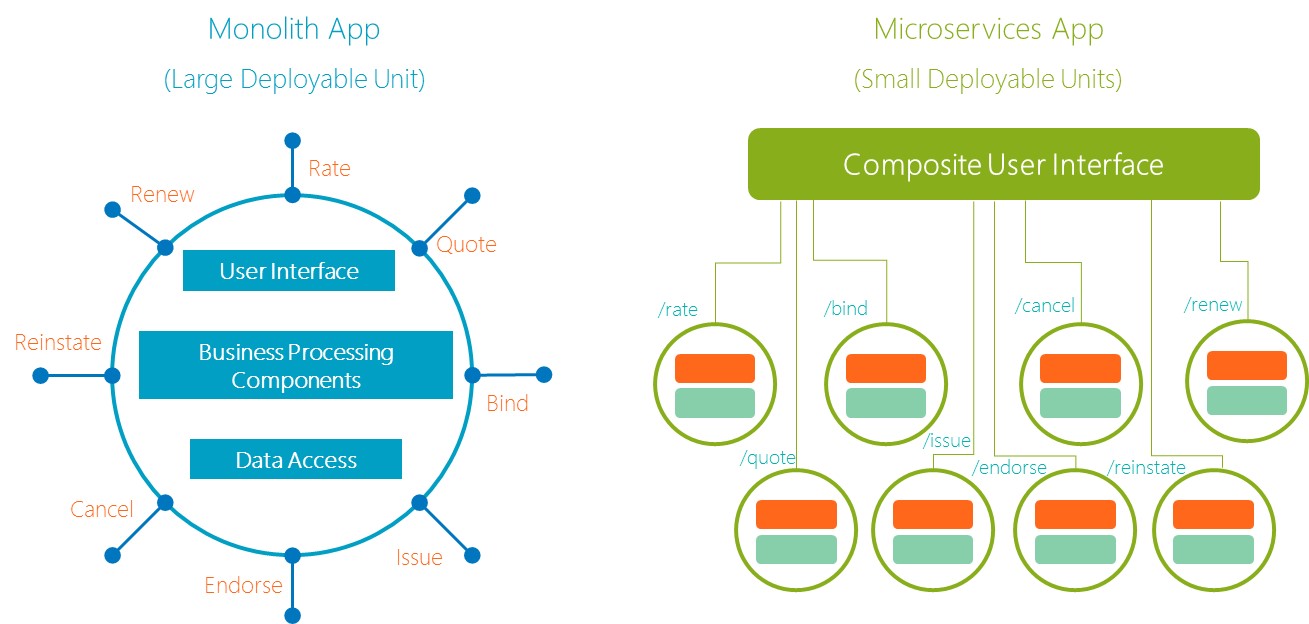
Today’s monolith insurance systems, although partially accessible through APIs, are built as a large deployable monolith unit. This architecture does not easily adapt to the rapid pace of change because the change is to a large-system single codebase and specific localized API. A separate API layer exposed over the single-monolith code base makes it difficult to integrate with ecosystem partners as well as making it extremely complex to orchestrate services across various systems or apps.
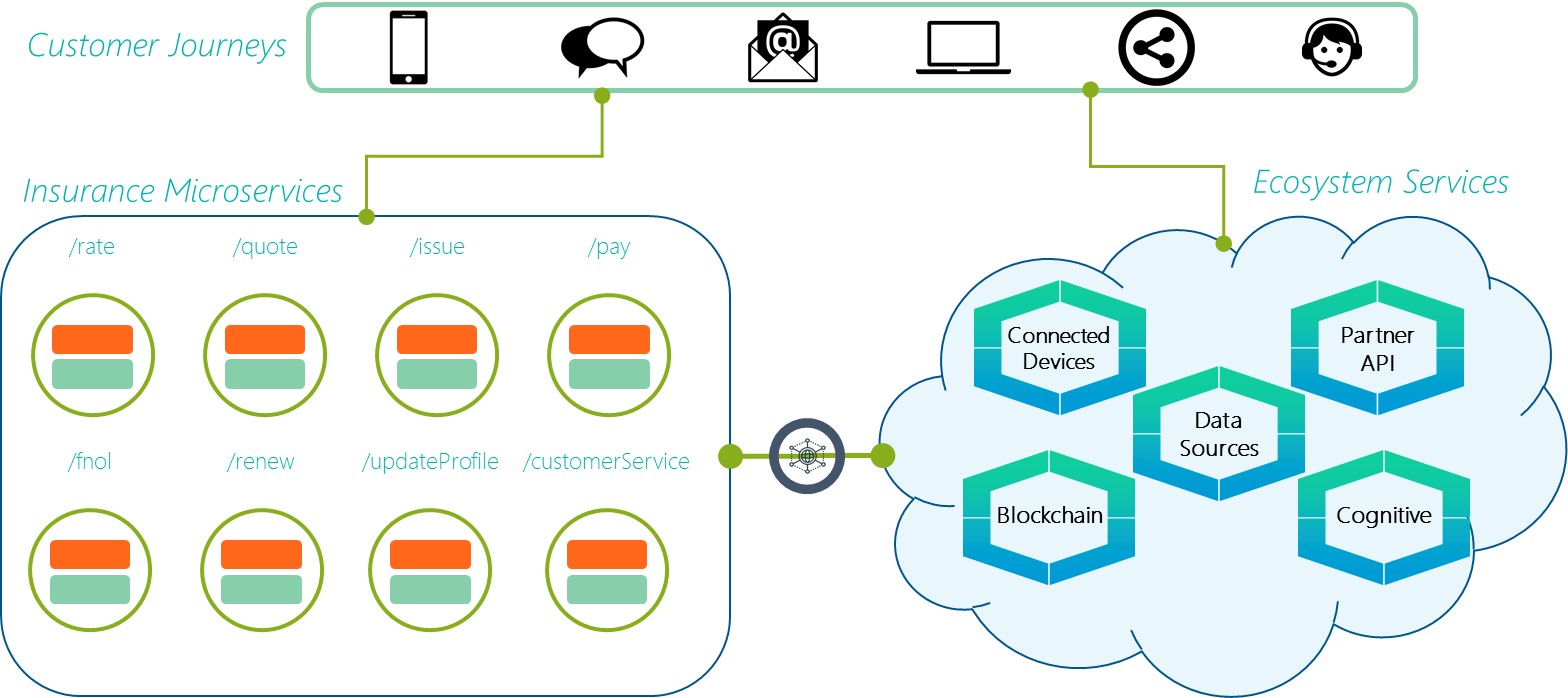
In contrast, a microservices architecture decomposes a large unit into fine-grained single purpose, self-contained and independently deployable business services that enable the ability for rapid change and open the possibility of multiple change deployments daily instead of waiting for the periodic release cycle. Using microservices across various apps, insurers can orchestrate a composite user interface that is a tailor-made customer journey. It can be enhanced quickly based on customer feedback. The graphic below shows how a microservices architecture can assist in the design of a unique customer experience using a product offering and ecosystem. Multiple customer journeys can be assembled by orchestrating functional microservices and ecosystem services available outside the insurer enterprise.
The times are changing. And it is exciting! The ability to leverage powerful microservices architecture to build a new foundation for the digital age of insurance is game-changing. It will enable new business models, new products, refined customer experiences and timely responses to new business needs (in hours and days instead of months and years), and it will help insurers remain relevant and competitive. While microservices is exciting and will accelerate the industry’s ability to innovate, it is not the Holy Grail. The smaller, focused services have many advantages but also create complexity in the orchestration of those services. Employing best practices in designing microservices size and data model sizing is critical. Most importantly, determining the gradual transition to microservices rather than a big-bang approach will help insurers build a platform that can withstand the test of time and constant change to help insurers participate in the digital age and platform economy with agility, innovation and speed.
See also: It’s Time to Accelerate Digital Change
In Part 3, we look forward to covering our views on best practices in introducing and scaling microservices within the world of the monolith IT system environment. We encourage you to read our thought leadership, Cloud Business Platform: The Path to Digital Insurance 2.0, to gain a deeper insight on these topics. Please share your views on this exciting topic in the comments section. We would enjoy hearing your perspective.
This article was written by Manish Shah and Sachin Dhamane.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.
It has become clear that product development can no longer occur in silos, with one function creating products for another function to sell.
"The biggest problem these days is, although everybody is talking about Digitisation and Disruption and are modernising their core systems with huge investments in order to support these new trends, the underlying products are not yet 'digital ready' – even new ones." — Oliver Lauer, former Head of Architecture / Head of IT Innovation at ZurichIn this installment, we start by looking at where innovation is occurring (by insurance line and insurance department) before considering some of the broad trends in product development – from bundling and upselling to diversification and Usage-Based Insurance (UBI). The following stats and perspectives are taken from our Global Trend Map; a full breakdown of our survey respondents, and details of our methodology, are included as part of the full report, which you can download for free at any time. So first up: which departments is product innovation currently coming from? ...
The three highest-scoring departments were Underwriting (with 70% of respondents naming it), Pricing (55%) and Marketing (54%). Other areas that warrant mention were Actuarial (51%) and Distribution (36%). We noted in our earlier post on Marketing & Customer-Centricity that the roots of today’s consumer-led disruption are in the rise and ease-of-use of new distribution channels – so insurers that leave Distribution outside of their product discussions do so at their peril!
See also: Next for Insurtech: Product Diversity
Which insurance lines are driving the greatest degree of product innovation?
In addition to seeing product as department-driven, we also investigated the extent to which it is line-driven. The chart below shows Auto (voted by 56% of respondents), Home (45%) and Health (41%) to be the three lines experiencing the most product innovation (according to carriers taking our survey). This is corroborated anecdotally by the sheer number of in-market IoT products we see across these fields, from in-car telematics through to smart-home controllers and connected-health armbands.
Life and Commercial are relative laggards in this regard, although we do believe there is ample opportunity in both these areas. This may follow the same pattern we identified with IoT (itself an abundant source of product innovation), where we saw platform implementation in Commercial currently trailing but quickly drawing level with other lines (see our earlier post on IoT). Regional trends for this question warrant some high-level comment:
Health is a substantial driver of product development for carriers in Asia-Pacific and Europe. In North America, however, it appears relatively insignificant#smarthome #mhealth #AutonomousVehicles #telematics See where insurance innovation is greatest in the #InsuranceMap: https://t.co/QH8z3aYH7y pic.twitter.com/qj6KKBrUF3
— Insurance Nexus (@InsuranceNexus) July 26, 2017
"The biggest risk the insurance industry faces when it comes to innovation is not taking enough risk. True innovation requires experimentation, which most of the time results in failure. Insurance organisations are built to eliminate failure from their culture. Without failure, you can have no innovation. CEOs demand a positive Return on Investment (ROI), they now need to seek out and understand what it means to have a positive Return on Risk (ROR)." — Steve Anderson, President at The Anderson Network[caption id="attachment_30597" align="alignnone" width="570"]
Human hand pointing at touchscreen in working environment at meeting[/caption]
Key trends in the development of products
It’s clear from this section so far that product development is a strategic priority for a diverse spread of departments and lines. But how are insurers actually going about product development on the ground? Let us now present our trends on a number of product approaches that we identified among our carrier respondents: product diversification, Usage-Based Insurance (UBI) and product bundling/upselling.
"You don’t really have to invent new products in my eyes, you just have to make the existing ones easier and more 'digital native'. Today’s products have been and are still created for non-digitals. And this situation not only makes new customer-facing digital processes complicated, it also makes core replacements and automation more complicated and expensive than necessary." — Oliver Lauer, former Head of Architecture / Head of IT Innovation at Zurichi) Product Diversification The pace of change in the insurance sector is picking up, and many ecosystem players are quickening their iterations both on new and existing products in a bid to stay relevant. 76% of (re)insurers are pursuing product diversification as part of their organisations’ growth strategies… This move towards diversification is not limited to any one kind of insurance market but is driving insurance growth all around the world. It is naturally very important for insurers looking to break into totally new markets, as is the case in many developing economies, where traditional insurance products may be inappropriate for lower-income demographics (microinsurance being a case in point). In mature markets, growth will come primarily from addressing existing demographics with more tailored products to fill in under-penetrated lines and segments; there is also the perennial threat that existing customers, tired of products that are suboptimal, will churn to competitors and new entrants who can offer better-suited ones. Whatever the market conditions, by trialling multiple products, insurers can both broaden their appeal and arrive at optimal products more quickly. ii) Usage-Based Insurance (UBI) The emerging generation of insurance products differ from those that have gone before in several key ways. One is the on-demand or usage-based component of new products – so that, rather than having idle and inflexible policies that subject the policyholder to the Tyranny of Averages, consumers can enjoy insurance-as-a-service. 32% of insurer respondents have a Usage-Based Insurance (UBI) strategy… This trend towards Usage-Based Insurance (UBI) is a global one, and there was no significant regional variation across our three key regions. More information about UBI models can be found in our earlier Internet of Things section and in our section on Europe in the upcoming Regional Profiles. "Most of the innovation in product development will happen where smart connected devices drive new business models based on behavioural data. I particularly expect improvements in pricing. UBI is a bigger game changer than covering events that are not insured today. In any case, there will be a huge need to understand, measure and manage rational and irrational behaviour." — Andreas Staub, Managing Partner at FehrAdvice iii) Product Bundling and Upselling A key trend we have witnessed in other B2C industries, like Amazon and Netflix, is the rise of the recommendation engine. This is not just a core component of the customer experience but also an important enabler of new business, insofar as it lets companies push new products to customers that they are actually likely to want and to find useful. We also see this in insurance, in the form of data-driven product bundling and upselling. 47% of insurers have a strategy to bundle and upsell products based on customer lifestyle analytics… Insurance has always had relatively few customer touchpoints, and even though insurers are now seeking to increase that number, insurance remains a product that is sold rather than bought. Taking full advantage of every selling interaction they have is therefore the surest way for insurers to increase their customers’ lifetime value. Bundling and upselling products is – like diversification – a strategy with strong applications regardless of what sort of insurance market you are operating in. Whether your focus is to chase new customers or to retain existing business, it is better to reap maximum reward on each customer from the outset than to re-engage them (perhaps unsuccessfully) later on. "The cost of customer acquisition is a critical metric for marketing efforts. Lifetime customer value also helps us know how much we should be spending to acquire as well as how we should expand our share of wallet within the products we offer." — Michael Shostak, SVP and Chief Marketing Officer at Economical Insurance See also: Insurance Product Development (Excerpt, Part 3) There are obviously many aspects of product development beyond diversification, UBI and bundling/upselling which we were not able to investigate directly. For this reason, we asked our carrier respondents to indicate additional product-development talking points in open text. Two key points that emerged across their comments were:
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Alexander Cherry leads the research behind Insurance Nexus’ new business ventures, encompassing summits, surveys and industry reports. He is particularly focused on new markets and topics and strives to render market information into a digestible format that bridges the gap between quantitative and qualitative.Alexander Cherry is Head of Content at Buzzmove, a UK-based Insurtech on a mission to take the hassle and inconvenience out of moving home and contents insurance. Before entering the Insurtech sector, Cherry was head of research at Insurance Nexus, supporting a portfolio of insurance events in Europe, North America and East Asia through in-depth industry analysis, trend reports and podcasts.
A programming aphorism says the first 90% of code takes the first 90% of development time—and the remaining 10% of code takes another 90%.
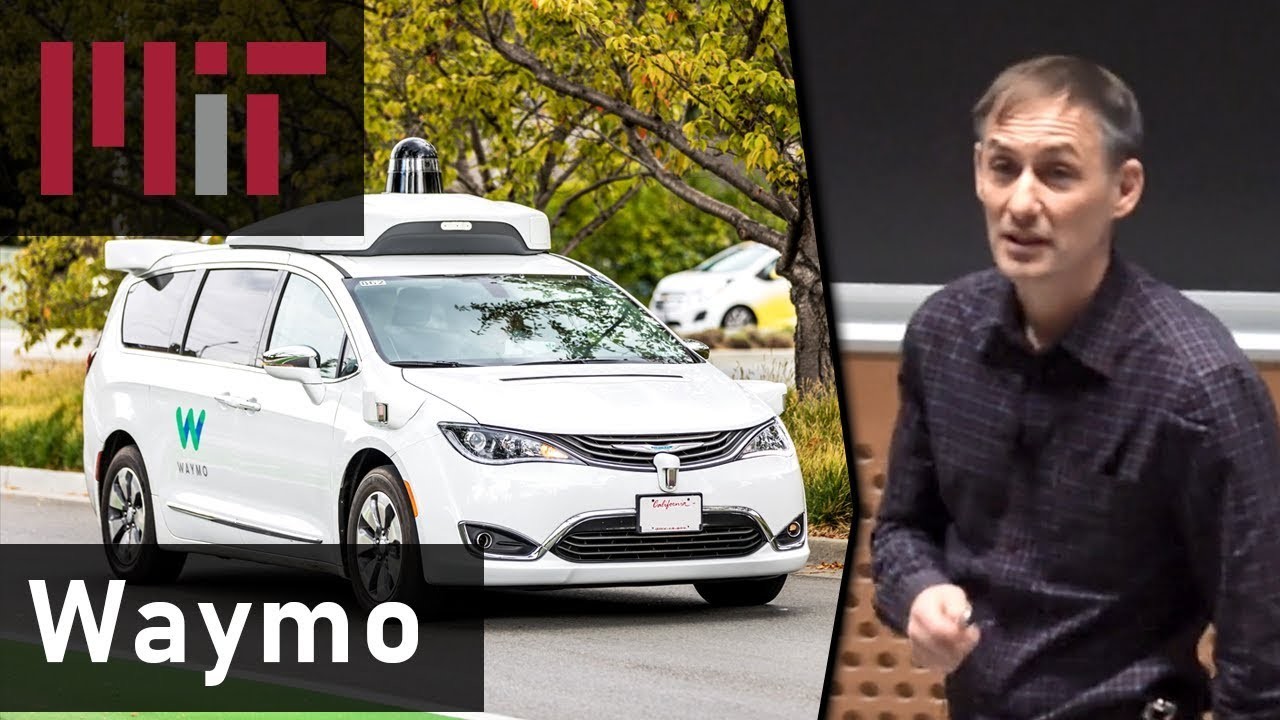
Arnoud’s remarks were given at a guest lecture at Lex Fridman's MIT class on “Deep Learning for Self-Driving Cars.” He offered technical insights on the history of the Waymo program, how it is applying artificial intelligence and deep learning and how it is moving from demo to industrial-strength product.
The Waymo engineer’s lecture goes beyond most Waymo management presentations and press events. He provides vivid details on the complexity of the effort to date and insight on challenges to come—both for Waymo and for those trying to catch up to its pioneering efforts.
Here are 5 takeaways, though I recommend watching the entire presentation.
1. Industrialization requires 10x the effort.
Arnoud emphasized the large amount of work needed to go from a demo that works in a lab to an industrialized product that is safe to put on the road: “You need to 10x the capabilities of your technology. You need to 10x your team size, including finding effective ways for more engineers and more researchers to collaborate. You need to 10x the capabilities of your sensors. You need to 10x the overall quality of the system, including your testing practices.”
2. Deep learning enabled algorithmic breakthroughs.
Arnoud noted that deep learning techniques were much less advanced in 2010 when Google started its work on self-driving cars. But, in the years since, deep learning has advanced to enable algorithmic breakthroughs in several critical areas for autonomous driving, including mapping, perception and scene understanding.
Arnoud gave numerous examples, such as using deep learning to analyze street imagery to extract street names, house numbers, traffic lights and traffic signs. The ability to precompute such data and store them as maps in the car saves precious onboard computing power for real time tasks.
See also: When Will the Driverless Car Arrive?
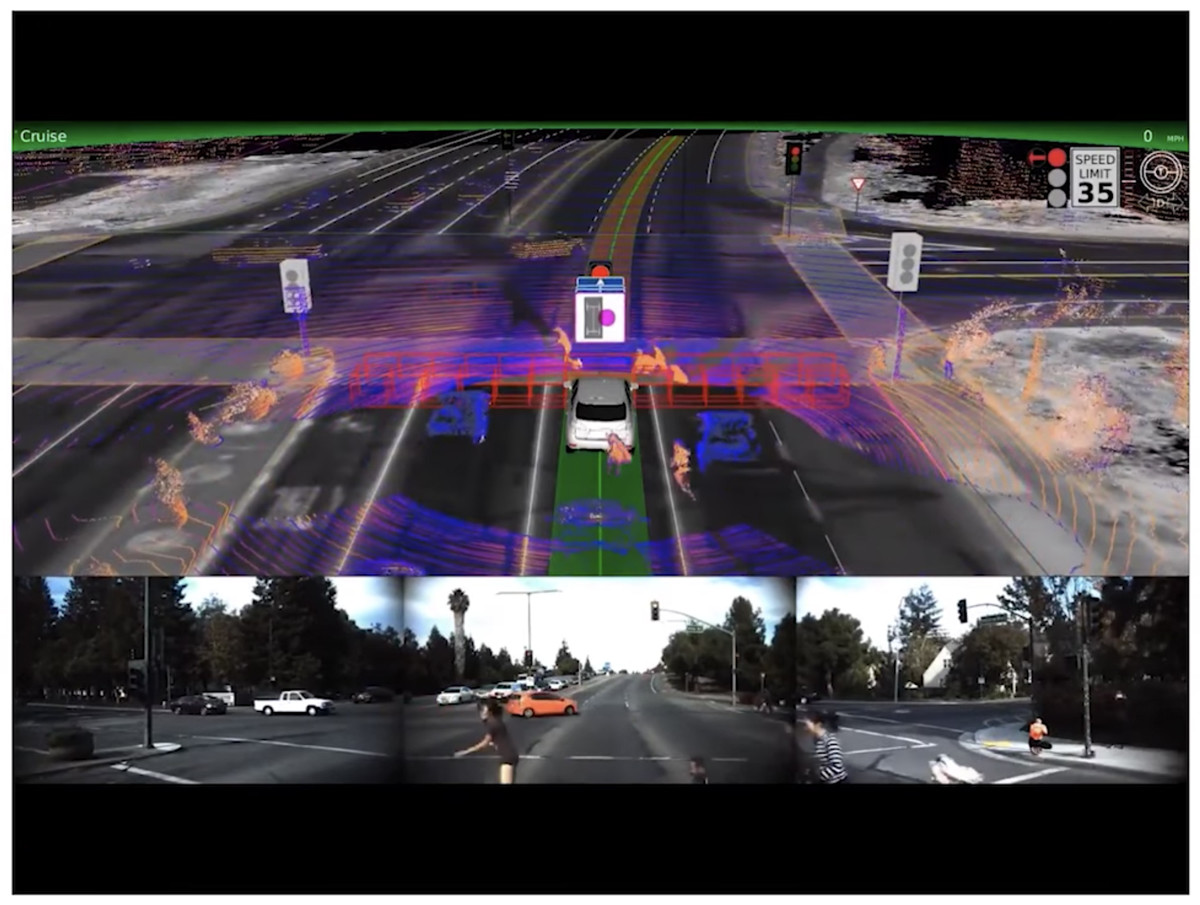
Deep learning is driving breakthroughs in real-time tasks as well, such as analyzing sensor data to identify traffic signals, other vehicles, obstacles, pedestrians, and so on. Deep learning capabilities also help in anticipating possible behavior of other drivers, cyclists and pedestrians, and driving accordingly.
3. Synergy with other Google units is key to Waymo’s progress.
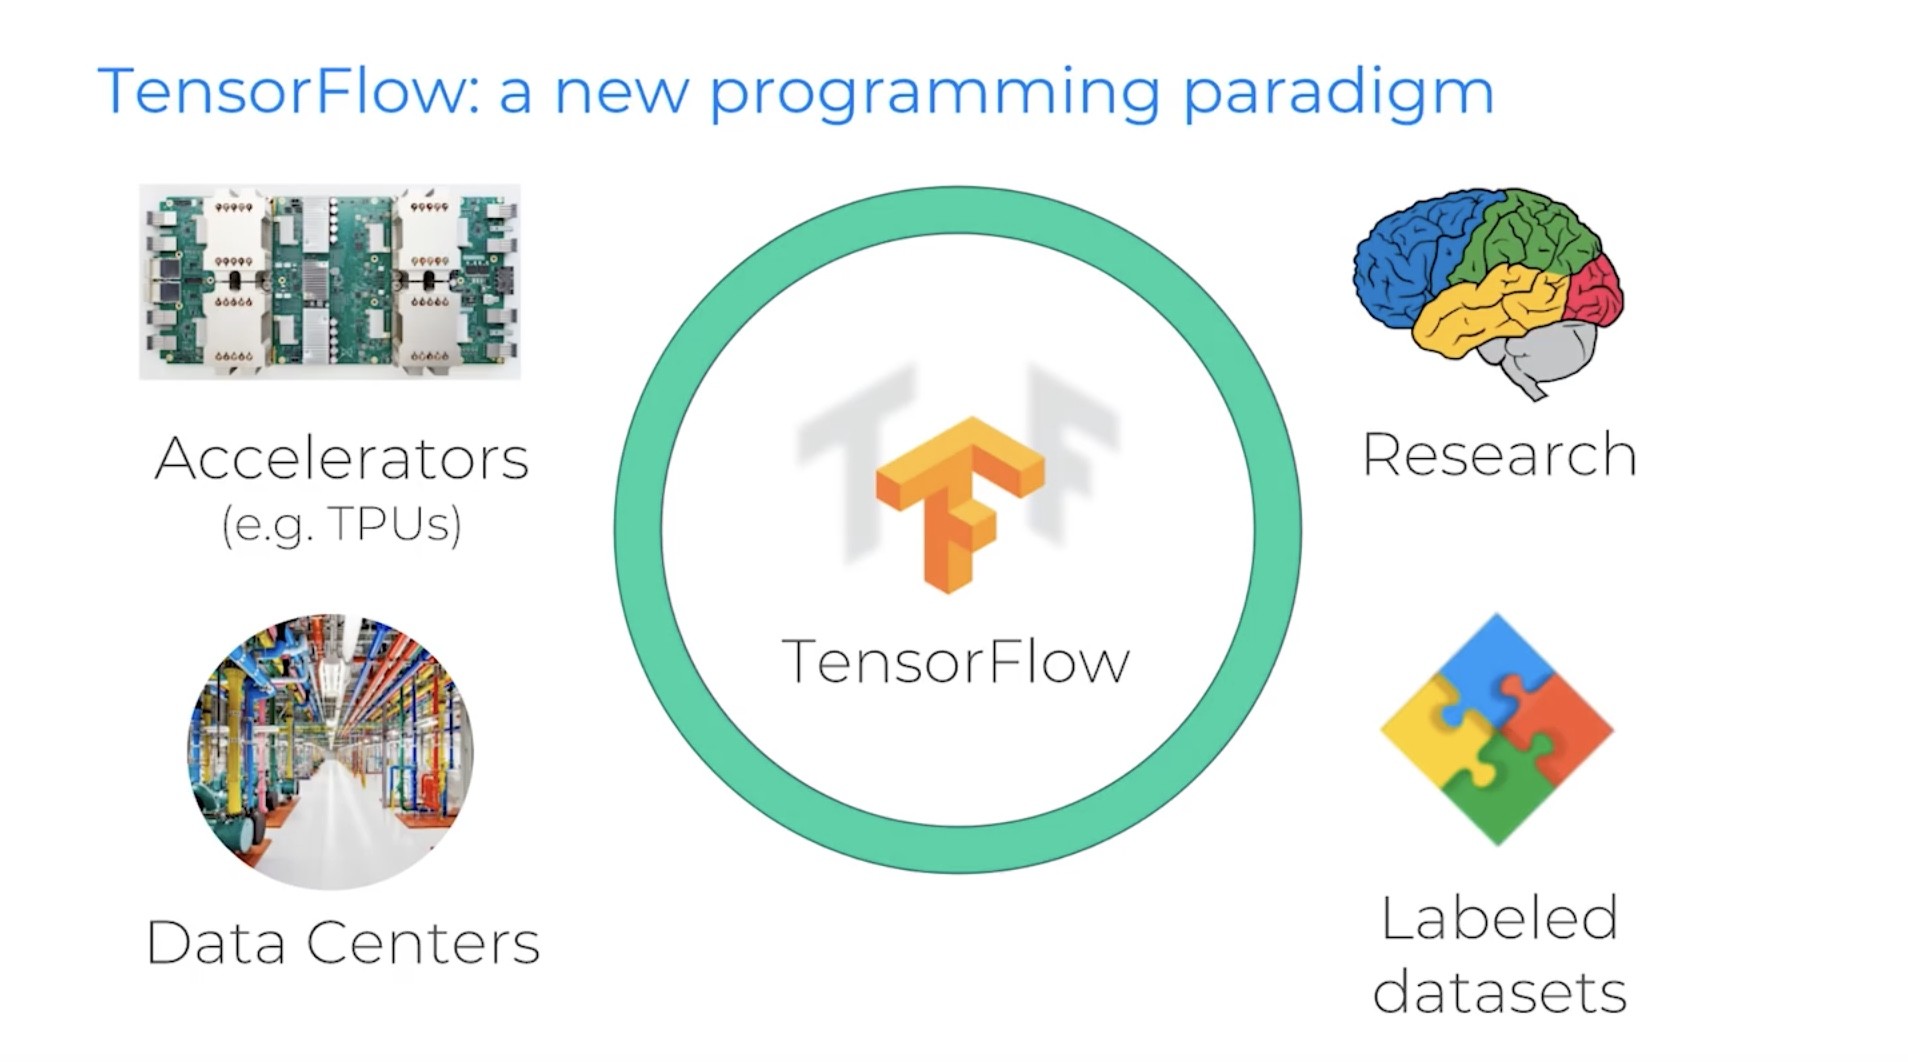
Arnoud acknowledged the importance of Google’s “whole machine learning ecosystem” to Waymo’s progress. This includes the seminal software advances by the Google Brain team and on-going collaboration with other Google teams working on deep learning at scale, such as in vision, speech, natural language processing and maps. The Google ecosystem also provides specialized infrastructure and tools for machine learning. This includes accelerators, data centers, labelled datasets and research that support Google’s TensorFlow programming paradigm.
4. Waymo’s testing program might be its secret sauce.
Arnoud emphasized that however great Waymo’s algorithms, sensors and overall package might be, driverless cars are still complex, embedded, real-time robotic systems that must work safely with imperfect data in an unpredictable world. He highlighted Waymo’s three-prong testing program of real-world driving, simulation and structured testing as key to iterating on and productizing the technology.
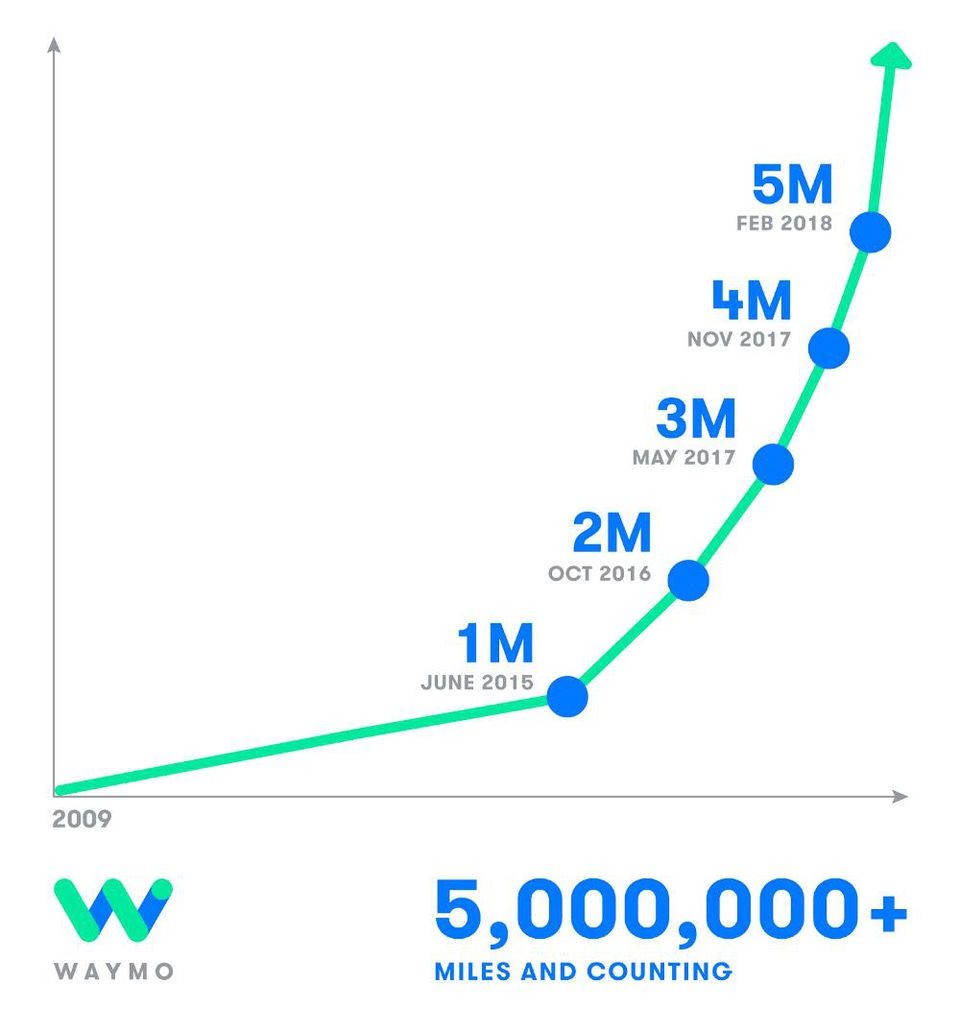
Much is made of the millions public-road miles that Waymo’s cars have driven autonomously. Arnoud described this as the equivalent of about 300 years of human driving experience and 160 times around the globe. Real world driving is critical, he said, but what is more important is the ability to simulate.
Simulation is critical because it allows for Waymo to test each new iteration of software against all previously-driven miles. Even more important is the ability to test against “fuzzed” versions of those millions of miles, such as seeing how the software would handle cars going at slightly different speeds, an extra car, pedestrians crossing in front of the car and so on. Arnoud described Waymo’s simulation-based testing capability as the equivalent of 25,000 virtual cars driving 2.5 billion real and modified miles in 2017.
The third component of Waymo’s testing program is its structured testing program. Arnoud said that there is a “long tail” of driving situations that happen very rarely. Rather than trying to encounter every possibility in real-world driving, Waymo set up a 90-acre mock city at the decommissioned Castle Air Force base where it can test its cars against such edge cases. These tests are then fed into the simulation engine and fuzzed to create variations for more testing.
5. Waymo’s next steps are big (and hard) ones.
Arnoud closed with a discussion of the engineering challenges in front of Waymo. He described two big next steps.
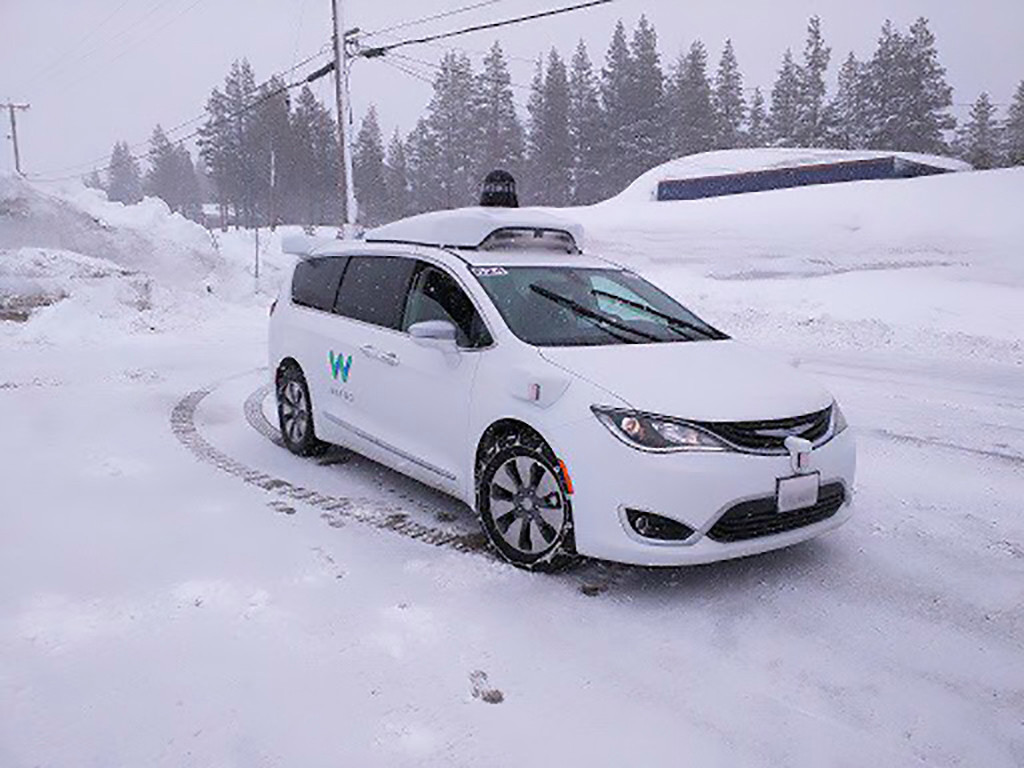
One next step is expanding the “operational design domains” (ODD) of the cars. This includes expanding into “dense urban cores,” such as San Francisco (in which Waymo recently announced it is expanding its testing program). The other ODD was additional weather conditions, such as hard rain, snow and fog. (Waymo CEO John Krafcik recently told an audience that he was “jumping up and down” recently when it snowed 12 inches near Detroit, because it would enable Waymo’s testing in snow.)
See also: 7 Steps for Inventing the Future
The other area of focus was what Arnoud called “semantic understanding.” As an example, he pointed to the chaotic Place de l'Étoile traffic circle around the Arc de Triomphe in Paris. The circle is a meeting point of 12 roads and notoriously difficult to navigate. Arnoud says he has driven it many times without incident, however, and that such situations require a lot more than perception and vehicle operating skills. They require deep understanding of local rules and expectations. They also require constant communication and coordination with other drivers, including signals, gestures and so on. This kind of deep reasoning is key to numerous edge cases and improving the general abilities of driverless cars.
* * *
While Waymo has clearly made tremendous progress towards the driverless future, Arnoud closed his presentation by emphasizing the engineering infrastructure and the complexities of scaling that have to be addressed in order to turn driverless cars into safe production systems.
How far along is Waymo in the last 90% of that industrialization process? Arnoud never said. But, to put a point on the complexities, he showed a closing video of a Waymo car stopped at an intersection as a gaggle of kids bounced on frogger sticks across the street on all sides of the car. Some things are waiting for, he seemed to imply.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Chunka Mui is the co-author of the best-selling Unleashing the Killer App: Digital Strategies for Market Dominance, which in 2005 the Wall Street Journal named one of the five best books on business and the Internet. He also cowrote Billion Dollar Lessons: What You Can Learn from the Most Inexcusable Business Failures of the Last 25 Years and A Brief History of a Perfect Future: Inventing the World We Can Proudly Leave Our Kids by 2050.
Negotiating a workers' comp settlement at a mediation is often better than at the board, but how does that compare with an informal?
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Teddy Snyder mediates workers' compensation cases throughout California through WCMediator.com. An attorney since 1977, she has concentrated on claim settlement for more than 19 years. Her motto is, "Stop fooling around and just settle the case."
As it is every year, March is Ethics Awareness Month for the insurance industry. Click here for my March 2017 article on this, though the poll I cite does not appear to have been updated for recent public opinion about the insurance industry. The CPCU Society usually leads the way on this, and you can get more information here. I wrote about the CPCU code of ethics in an article I called “The 7 Habits of Insurance Professionals.”
Those who view insurance as a career rather than a job probably think of themselves as professionals. As to what specifically constitutes a “professional,” here are some criteria from Ron Horn in an old CPCU text: 7 Characteristics of a Profession
Source: “On Professions, Professionals, and Professional Ethics” by Ronald C. Horn
Based on these criteria, someone CAN be a “professional” in the insurance industry. The biggest stumbling block might be #7 above. Does the typical consumer view, for example, the typical insurance agent as a “professional” akin to their perception of a doctor, attorney, accountant or perhaps clergy member?
The answer is almost certainly a resounding “No”… until their insurance claim is denied. At that time, the plaintiff will almost assuredly try to convince a judge or jury that the agent owed a higher standard of care as a professional in his or her field.
See also: Will Insurance Ever See a ‘Killer App’?
So, how do we begin the process of changing this unprofessional view of our industry, aside from voicing our displeasure with the incessant price-focused shilling that passes for advertising that dominates the media?
The above was largely excerpted from my coming book “When Words Collide: Resolving Insurance Coverage and Claims Disputes.”
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
William C. Wilson, Jr., CPCU, ARM, AIM, AAM is the founder of Insurance Commentary.com. He retired in December 2016 from the Independent Insurance Agents & Brokers of America, where he served as associate vice president of education and research.