3 Ways to Use Data to Optimize Mobile Ads
A “spray-and-pray” approach — blasting your message out to everyone and hoping it will reach someone likely to respond — no longer cuts it.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Gregory Bailey is president and CPO at Denim Social. He was licensed to sell insurance at the age of 20, continued as an agent in the industry for the next nine years and then stepped into the corporate world of insurance.
Disruption has definitely arrived in Europe, and the European market may be marginally ahead of the North American market.
Our discussion on Europe falls into five broad chapters, the first two of which we cover in today's post:
"European carriers have a raft of incoming regulation to implement and prepare for… In addition to the implementation of Solvency II, we can also point to the IAIS’s Insurance Capital Standard (ICS) slated for 2020, the introduction of International Financial Reporting Standards (IFRS) and the transposition into national law of the Insurance Distribution Directive (IDD) in time for 2018." — James Vincent, general manager at Insurance NexusInterest rates and regulation make it imperative for insurers to seek growth and profit opportunities elsewhere. And while there does exist a low-end market opportunity in Europe, this is nowhere near on the scale we see in Asia-Pacific, Africa and LatAm. This means that, in the main, insurers must focus on established demographics and look either for entirely new risk categories or for ways to serve their clients’ existing risks better and more extensively. A key emerging risk area on the commercial side is cybersecurity. This isn’t entirely new as a risk category but looms larger and larger for any company operating with customer data (i.e. every company). Unfortunately, cyber risk is not an easy category of risk to insure, given the wide range of dependencies involved, spanning everything from reputational damage to share-price hits. It is partly for these reasons, Margaris says, that many insurers have been reluctant to jump on the cyber bandwagon, at least for now. Cybersecurity is also an issue that insurers are on the receiving end of, insofar as they steward vast quantities of customer data, all of which must be secured. Consistent with our other regions, a majority of European (re)insurers are very concerned about information security breaches, as we saw in our earlier post on cybersecurity; fortunately, a majority also have mitigation plans and have adjusted their security strategy to reflect the rise of new digital platforms. Beyond exploring completely new risk categories, like cybersecurity, insurers in Europe will find fresh profits by focusing on what they have always done – only better. Retention of existing business is therefore of primary importance, and we did indeed find a high focus on customer loyalty among European insurers in our post on marketing and customerCcentricity. Part of this also involves increasing the lifetime value of customers already on the books, with around half of European respondents indicating that they have a strategy to bundle and upsell products based on customer lifestyle analytics, consistent with our other regions, as we recounted in our section on product development.
"There is an abundance of capital available in the global economy, and right now money is cheap. There is minimal value in continually driving down price and adding further competition to a saturated market place. Putting digital at the core of distribution strategies will allow previously untapped markets to be exploited for a relatively low cost, allowing that capital to be deployed more effectively." — Gareth Eggle, head of insurance at Flint HydeAdditionally, though, growth for European insurers will come from going after new customers in the established demographics, and this will require carriers to better adapt their existing products to the sorts of risks people want to insure against and to offer them at an appropriate price. While this new drive toward customer-centricity will, generally speaking, result in lower premiums (insurance is not a designer item, and less is always more from a price perspective), it also allows greater scale and, ultimately, lower operating costs. If we take the U.K. motor-insurance market as an example, we see that there is plenty of old business to be better served and new business to be won. Charlotte Halkett, speaking from her experience as general manager at telematics provider Insure The Box (Charlotte is now MD of home-line Insurtech Buzzmove), mentions that the cost of motoring in the U.K. is a particular challenge and draws attention to unlimited liability as well as to various government-influenced changes, such as the Odgen Rate, which disproportionately affects younger drivers less-well-placed to front the cost of auto insurance. It is this opportunity – not just to improve driver safety but to bring down the cost of motoring – that Insure The Box is taking full advantage of. By monitoring driver behavior through telematics, the company is able to encourage safer driving behaviors and ultimately guide motorists to lower premiums. We will explore their usage-based insurance (UBI) model in our next post. While Insure The Box forms part of an incumbent insurer’s technology stack through its parent company Aioi Nissay Dowa Insurance Europe, it is unlikely that the new play for personalized, customer-centric insurance will work out solely for the benefit of incumbents. Indeed, the opportunity is already attracting many new market entrants (like insurtechs), which represent a serious threat to legacy insurers’ hitherto cozy models. Margaris gives a high-level explanation as to why insurtechs are such a threat to traditional players: "Consumers will ask themselves why is it so much cheaper with an insurtech company and why does it cost so much at the insurer’s end? So there will increasingly be a margin pressure. The example I often present: If somebody gives the milk away for free, will you go to the deli and pay $1? You’ll say, I get it free there. I want to stay with you, but I’m not going to pay you a dollar for it. And that’s what fintech/insurtech does, it piles on margin pressure." Even if insurers can get the price of their products down, Margaris still believes insurtechs have an edge due to their stronger customer credentials. "If insurtech companies provide solutions that feel very personalized, customized to the user’s needs, people will feel like what their insurance company is offering is so old-fashioned," he says. "So there will be dissatisfaction with the incumbent services that they’re getting, and of course pressure not to pay up for that." Much of the difference between old-fashioned and newfangled comes down to the user interface. In this regard, Margaris compares the old and the new in insurance with the old and the new in software: "If we go back 15 years and look at the user experience with software then – nowadays, you’re left asking, how did people use it? But at that point we thought it was cutting-edge. Now, though, people don’t want to think about what they’ve got to do, everything has to be seamless." Price and personalization (the two Ps) are the two key areas that insurers have to work on as they square up to new market entrants. We will see later on in our Europe profile that insurers’ ability to lower premium prices in fact goes hand in hand with improving personalization – in the sense that more frequent customer touchpoints and interactions provide the very data insurers need to price accurately and to offer the incentive of lower prices still.
"Anyone who believes that business will stay as in the past, will face a so-called 'Kodak' moment and will not survive increasing competition. There is an urgent need to systematically deal with innovation and challenge the current offering or even business model." — Monika Schulze, global head of marketing at Zurich Insurance2. Europe as Early Adopter The trends we have just outlined – falling investment returns and a renewed drive toward customer-centricity – all manifest themselves, in some way or another, in the other markets we examine. But how does Europe compare with other markets? Throughout this report, we have characterized the current disruption sweeping through the insurance industry as being customer-driven. We further identified its roots in the growth of digital outreach and distribution channels, not just in insurance but in the online economy more generally (a case in point being online retail), in the sense that these open up formerly captive markets to fleet-footed digital competitors.
"From IoT in the field to analytics and emerging AI solutions at the back end, European carriers are grasping with both hands everything the technology community has to offer in their bid to win the race for the customer. This promises to be a very exciting period for solution providers!" — Guy Kynaston, commercial director at Insurance NexusEurope is not just a heavily disrupted market but one in which insurers are showing themselves relatively well-equipped to deal with this, compared with our other key regions (this comes, of course, with the caveat that the European market varies substantially from country to country in ways we can only explore here at a relatively high level!). In our post on marketing and customer-centricity, we characterized Europe and Asia-Pacific as exhibiting a marginally more problematic insurer-customer relationship than North America. In Europe’s case, we pointed to the high priority score that it achieved for customer-centricity (56 compared with North America’s 51). Our thesis was that higher customer expectations in the region were driving customer-centricity to the very top of the European priority rankings. In line with our view that changes to distribution are intimately tied up with disruption in insurance, we expected to find a relatively shaken-up distribution landscape in Europe. A few thoughts on this:
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Alexander Cherry leads the research behind Insurance Nexus’ new business ventures, encompassing summits, surveys and industry reports. He is particularly focused on new markets and topics and strives to render market information into a digestible format that bridges the gap between quantitative and qualitative.Alexander Cherry is Head of Content at Buzzmove, a UK-based Insurtech on a mission to take the hassle and inconvenience out of moving home and contents insurance. Before entering the Insurtech sector, Cherry was head of research at Insurance Nexus, supporting a portfolio of insurance events in Europe, North America and East Asia through in-depth industry analysis, trend reports and podcasts.
Insurers that can provide an ecosystem of sensors, monitoring and risk reduction will find businesses are highly receptive.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.
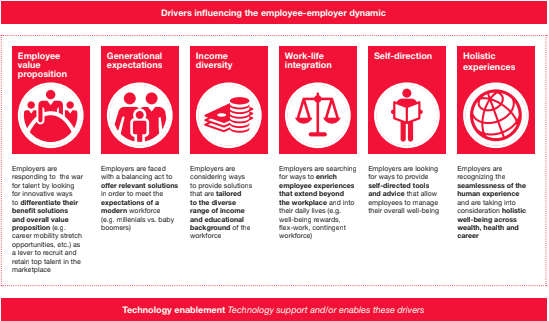
Changes in the employee-employer dynamic are making investments and growth prospects in the group sector more attractive.
Carriers’ initial response has been to drive profitable growth by streamlining their operating models and making incremental investments in technology to upgrade their capabilities. However, employer and employee needs and expectations continue to rise.
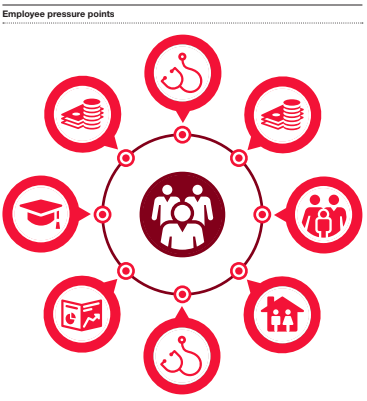
Employers are using innovative benefit solutions to differentiate themselves when recruiting and retaining top talent. Employers recognize that employees no longer have the patience or time for benefit plans that are cumbersome to enroll in and manage. They’re looking for holistic solutions that employees themselves can direct. In addition, employees have different needs based on income diversity and – more so than in recent memory – generational circumstances. Consequently, they’re looking to employers to offer customizable solutions that help them meet their unique needs in a user-friendly fashion, 24/7.
Moving forward, five trends will continue to shape the group insurance market and influence carriers to move beyond incremental investment to fundamentally reposition their business and operating models. These trends will motivate group insurers to provide more measurable value for employers, employees and intermediaries by delivering more integrated products and services and better customer experiences. We also expect to see a) More and more players in adjacent markets such as health, workforce management and wealth to expand into market niches that overlap with group insurance; and b) More venture capital to flow to insurtech solutions that meet the group space’s evolving needs.
Group insurer solutions will take advantage of the convergence of
health-wealth-career management
Consumers are increasingly managing their health, wealth and career decisions in a coordinated way because they all affect the same wallet.
Decisions about health range from ways to maintain fitness to ensure their quality of life (and thus ability earn an income) to selecting the right combination of benefit products to reduce the key risks that could knock them and their families off track for an extended period of time. As people at the higher end of the socioeconomic scale live longer and healthier lives, they’re looking to manage their personal wealth to support their and their families’ financial positions for longer periods of time.
Moreover, as employers compete for top talent, they are increasingly providing benefits and programs that address the concerns their employees have about their and their families’ physical, mental and financial health. Employers are focusing on a) health and return to work programs that contribute to worker productivity and performance, and b) employee development programs.
See also: How to Unlock Group Insurance Market
The confluence of these factors is creating opportunities for group insurers to provide employers with solutions that help them improve their employees’ health, wealth and professional satisfaction. Some carriers are responding by offering more holistic solutions, either by expanding their own product offerings or through partnerships with others in which they can white label products. Other carriers have decided not to expand their own product offerings, but instead focus more on the wealth/ retirement or health. In either case, they’re trying to make their products and services fit with the other benefits employers’ chosen platforms offer.
Group insurers will look to serve more market segments
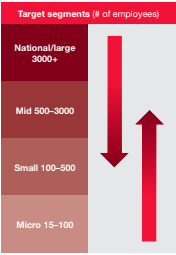
Many group insurers have long focused on certain market segments. For example, some have been dominant in the national account or large case segments and others in the small or mid-case account segments.
Each market segment requires different operating model strengths. But, as employer and employee needs increasingly change, the traditional lines between small, mid, and large account segments are starting to blur.
Group carriers are now rebuilding core capabilities and introducing new ones in order to more profitably serve a broader range of employer segments. Recent M&A activity has resulted in significant new capabilities. For example, the Hartford, which acquired Aetna’s group life and disability business, and Lincoln Financial Group, which acquired Liberty Life, are examples of the priority group players are placing on adding or enhancing capabilities (such as integrated absence management) to serve broader segments of the market.
These moves indicate that the carriers which traditionally have been stronger in the small and mid-markets are building new capabilities and transforming their target operating models in order to serve the unique needs of larger account segments. Moreover, large account carriers are building new capabilities and changing their target operating models in order to standardize and automate their solutions to more profitably serve smaller market segments.
Group insurers will increasingly respond to increased absence management needs, even for down market clients
Absence and leave management services are a core service in the disability market and demand is growing.
There has been a spike in requests by employers for absence and leave services as a result of:
a. The January 1, 2018 New York Paid Family Leave Law, which is the most significant paid leave program in the US;
b. Recent localized laws, such as the Paid Sick Leave Ordinance (PSLO) and Paid Parental Leave Ordinance, have increased the local complexity of employer leave and absence tracking; and
c. Increased cross-selling of disability, FMLA, and voluntary products makes the need for claims/absence integrated services more relevant.
In response to these changes, carriers are increasingly adding absence services and platforms to their repertoire. For those familiar with disability, FMLA, and other products, absence is not new. For those who aren’t, tracking the high number of federal, state, and local laws is a tremendous value-add to their client base. In order to improve customer service, carriers are integrating claims and absence into an “event” experience to radically reduce the burden of correspondence that explains payments and absence rights.
M&A activity and insurtech investment will continue to shape in the group market
Moving upstream and downstream among employer segments requires new capabilities.
The traditional way of doing business will not meet changing employer and employee expectations. As a result, M&A, insurtech investment, and maturing group technology solutions will continue to influence the group market in three ways:
a. In addition to the M&A activity we previously noted, there have been other transactions in the group space, including Meiji’s acquisition of Stancorp and Sumitomo Life’s acquisition of Symetra. Acquisitions like these potentially provide much needed capital investment for group players looking to take advantage of the convergence in the space and the opportunity to profitably expand across traditional market segments. This in turn could raise the bar for existing players, especially in areas where they need i) broker or consultant customers to recommend their products, and ii) to address employer needs to respond the changing employer- employee dynamic.
b. There also have been deals adjacent to group benefits, such as CVS’s acquisition of Aetna and the Amazon, Berkshire and JP Morgan joint venture. These developments may impact more than product solutions, pricing and omni-channel distribution and service; they also could significantly reshape the employer and employee customer experience.
c. Group carriers traditionally have often been reluctant to make significant investments in technology and when they have, they’ve attempted to build new technology solutions in-house. However, with the exponential growth of insurtech and the maturation of group-focused core technology, some carriers are finding it both necessary and easier to acquire new solutions rather than build them. Consequently, group insurers are accelerating their investment in core areas, including enrollment, policy administration, and claims, thereby allowing them to improve in a number of areas from quote to close ratios, and from employee program participation to claims management.
Group insurers will continue to build digital & data architecture and expand analytic capabilities
Artificial intelligence, predictive analytics, behavioral economics,
machine learning, robotic process automation, among other technological developments, represent opportunities for group insurers to better understand, acquire, serve and retain customers in new and more cost effective ways.
Carriers are choosing to invest in new digital capabilities to improve customer and channel segmentation and experience, as well as enhance their ability to acquire and retain the right customers. This helps carriers anticipate employer needs and enables solutions to change as employers do. It also promotes better carrier understand of employees’ broader needs beyond the employer relationship.
Also of note, group insurers have long had a significant amount of data and in recent years have taken advantage of advances in big data, reduced cost of computing power, and commoditized analytic techniques to increase their use of data for decision-making and insight generation. However, many of the advances in data have still not translated to improvements in employee level data across the value chain.
See also: Group Insurance: On the Path to Maturity
New investments in data will help group carriers 1) Improve the data architecture that is critical to improving workflow and customer experiences, 2) Focus on employee level data to better meet the needs of employees – especially in the areas of portability, and 3) Incorporate third-party and unstructured data with employee level data, which will help them be more consultative with employers about the design of responses to employee needs.
Implications
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Jamie Yoder is president and general manager, North America, for Sapiens.
Previously, he was president of Snapsheet, Before Snapsheet, he led the insurance advisory practice at PwC.
Marie Carr is the global growth strategy lead and a partner with PwC's U.S. financial services practice, where she serves numerous Fortune 500 insurance and financial services clients.
Over more than 30 years, her work has helped executive teams leverage market disruption and innovation to create competitive advantage. In addition, she regularly consults to corporate boards on the impacts of social, technological, economic, environmental and political change.
Carr is the insurance sector champion and has overseen the development of numerous PwC insurance thought leadership pieces, including PwC's annual Next in Insurance and Top Insurance Industry Issues reports.
The measurement of NPS is arguably the least important component of a program. What matters is what comes after the measurement.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Jon Picoult is the founder of Watermark Consulting, a customer experience advisory firm specializing in the financial services industry. Picoult has worked with thousands of executives, helping some of the world's foremost brands capitalize on the power of loyalty -- both in the marketplace and in the workplace.
NIH is one of those surprising features of the innovation landscape – the situation where an organization rejects a new idea offered from outside.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
John Bessant holds the chair in innovation and entrepreneurship at the University of Exeter and has visiting appointments at the universities of Erlangen-Nuremburg and Queensland University of Technology.
Industry leaders are starting to leave behind the “fast-follower” mentality, reallocating investments to customer-centricity and differentiation.
Building a digital platform
Although we tend to understand digital transformation and modernization of technology platforms as sequential, multi-year events with multi-million dollar price tags, finite delivery dates and fixed realization periods, true modernization requires a foundational
shift in the organizational culture, operating model, and underlying architecture that enables business flexibility and agility.
Building a digital platform that will take your company into the future — not just respond to current needs — is critical to prolonged success.
Insurers are currently enabling access to data across various domains and dimensions, but the companies going the extra mile to design a futuristic platform architecture are the most likely to benefit in the long term. Future-oriented platform architectures should be able to:
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Jamie Yoder is president and general manager, North America, for Sapiens.
Previously, he was president of Snapsheet, Before Snapsheet, he led the insurance advisory practice at PwC.
Here is a look at the insurance and insurtech trends in the world's seven key regions.
In our forthcoming posts, we will be referring back — on a regional and comparative basis — to the stats presented across our earlier installments on: Industry Challenges, Insurtech Perspectives, Insurer Priorities, Services, Investments & Job Roles, Analytics & AI, Digital Innovation, Internet of Things, Marketing & Customer-Centricity, Distribution, Claims, Fraud, Cybersecurity, Investment Management, Regulation and Product Development. Additionally, we supplement our statistics with perspectives and discussion from a range of local correspondents in each region.
In this post, which introduces our regional profiles, we present a brief preview of each region including key external and internal challenges, as well as insurer priorities. Each preview kicks off with a Top-Trumps-style summary table of key stats (an exhaustive key explaining each measure is included in the full report).
In our Profile on Europe, we draw on the expert opinions of Switzerland-based venture capitalist Spiros Margaris, VC (InsureScan.net, moneymeets & kapilendo), and Charlotte Halkett, former General Manager of Communications at UK-based telematics provider Insure The Box (now MD of Buzzvault at Buzzmove). For all their insights, simply download the full version of the report. Below is a sneak preview of the stats and themes we discuss in the full profile.
"Europe presents us with a potentially gloomy picture, with the on-going issues of low interest rates and weak growth prospects, to which we may add growing regulatory burdens and political uncertainty – especially in the wake of the UK’s Brexit vote. However, we have nonetheless gathered plenty of evidence that incumbents have the tools in place both to come through and to hold their own against new entrants." — Helen Raff, Head of Content at Insurance Nexusi) The External Challenges: Europe In Europe, the top three external challenges facing the insurance industry as a whole follow the global trend we outlined in our earlier post on Industry Challenges: 'Technological advancement', 'Changing customer expectations' and 'Digital channel capabilities'. Looking further down the table, some points of note are the higher position attained by ‘Increased regulation’ and the lower positions of ‘New emerging risks’ and ‘Catastrophe risk’. Compared to some of the other regions we examine, like Africa and Asia-Pacific, Europe is relatively sheltered from natural catastrophes and the associated risks that they bring with them, which possibly explains the lower scores we find for ‘New emerging risks’ and ‘Catastrophe risk’. As for the prominence of the regulatory challenge, we need look no further than the EU’s Solvency II, which came into effect at the start of 2016 and represents the first major shakeup of the landscape since the 1970s. --- ii) The Internal Challenges: Europe Internally, the top challenges are close to the global trend we outlined in our earlier post on Industry Challenges: ‘Lack of innovation capabilities’ and ‘Legacy systems’ take first and second place respectively, with ‘Siloed operations’ edging out ‘Finding and hiring talent’in third place.
--- iii) Insurer Priorities: Europe
These are the priority areas on which European insurers lead our other regions, out of our shortlist of 15 priority areas presented in our earlier post on Insurer Priorities:
"Customer-centricity is an important issue because insurance is a 'trusted good'. To address social values and preferences is important. Customer-centricity means building trust, branding and a business model based on relational values. Not for nothing: Empirical evidence shows that identity is the strongest customer KPI." — Andreas Staub, Manager Partner at FehrAdvice
In our full profile for Europe, we dig deeper into these challenges and priority areas on a more qualitative note, with insights from our two regional contributors, Spiros Margarisand Charlotte Halkett. Key focal points of our discussion include:
"Rising claims costs – both attritional and catastrophic – against a backdrop of low interest rates calls for a new approach to insurance in North America. That the lion’s share of Insurtech deal money has been going to US companies suggests that this change of approach may not be long in coming." — Marsha Irving, Head of Innovation / Commercial Director at Insurance Nexus--- i) The External Challenges: North America
In North America, the top external challenges for the insurance sector as a whole follow the global trend from our earlier post on Industry Challenges, with ‘Technological advancement’ and ‘Changing customer expectations’ taking 1st and 2nd place respectively, except that in 3rd place we find ‘New emerging risks’. In comparison, this comes 4th globally and only makes 6th place in Europe – which, as we indicated in our Europe preview above, likely reflects some parts of the world being more exposed to disasters (and hence concomitant risks) than others. Further down the table, 'Increased competition' moves up a place, knocking 'Increased regulation' down one spot to 7th.
See also: How Is Insurtech Different in Asia?
--- ii) The Internal Challenges: North America
Looking internally, the top challenges reflect the global trend we outlined in our earlier post on Industry Challenges, except that ‘Legacy systems’ wrests the top slot from ‘Lack of innovation capabilities’ (which, by way of comparison, comes first in Europe and Asia-Pacific).
Innovation is, at its heart, customer-driven, and, as part of our Regional Profiles, we compare the insurer-customer relationship in North America with what we find in our other key regions – and this may well explain the different positions ascribed to ‘Lack of innovation capabilities’ in their respective challenge tables. The parallel suggestion is that ‘Legacy systems’ play more of a role in North America, which is another theme our full profile investigates in more depth.
"Legacy systems has long been a core challenge for executives across functions within insurance carriers who are focused on innovation, customer experience and efficiency. Impacting product development, applying analytics, claims modernization, marketing optimization and more, it’s no surprise this is such a top priority for insurers. In the future, I think we’ll see more legacy system upgrades across insurers looking to digitize and streamline operations." —Emma Sheard, Head of Strategy at Insurance Nexus--- iii) Insurer Priorities: North America These are the priority areas on which North American insurers lead our other regions, out of our shortlist of 15 priority areas as presented in our earlier post on Insurer Priorities:
In our full profile for North America, we return to these challenges and priority areas, bouncing them off our two regional contributors, Stephen Applebaum and Matthew Josefowicz. Some of our key points of interest that emerge, and which we discuss in detail, are:
Our exploration of Asia-Pacific brings into play, alongside our statistics, the experience and perspectives of three in-region commentators: Steve Tunstall, CEO at Singapore-based Insurtech start-up Inzsure, João Neiva, Head of Innovation, IT and Business Change at Zurich Topas Life in Indonesia, and HK-based David Piesse, Chairman of IIS Ambassadors &Ambassador Asia Pacific at the International Insurance Society (IIS). What follows is a preview of our Asia-Pacific Profile (full thing here).
--- i) The External Challenges: Asia-Pacific
In Asia-Pacific, the top external challenges facing insurance as a whole follow the global trend familiar from our earlier post on Industry Challenges, with ‘Technological advancement’ and ‘Changing customer expectations’ taking first and second place respectively, except that, as in North America, in third place we find ‘New emerging risks’(by way of comparison, this challenge only makes 6th place in Europe).
One possible explanation for the higher ranking of ‘New emerging risks’ is to be found in the related challenge of ‘Catastrophe risk’ – which also results one place higher in Asia-Pacific than was the global trend.
While natural catastrophes are not emerging risks, in the sense that they have always occurred, their consequences are becoming more multifaceted as a result of the massive growth in urban areas and the rife interconnection of business in today’s globalised economy. This has introduced a new class of accumulation risk which could justifiably be called ‘emerging’.
We know anecdotally that this phenomenon is particularly pronounced in the APAC region, which boasts some of the densest urban and business conglomerations in the world, in and among noted catastrophe zones, and the trend towards urbanisation and megacities is only set to continue.
See also: Insurtech Ecosystem Emerging in Asia
Another detail we notice with the external challenges is the relatively high position attained by ‘Increased competition’ (two places up on the global trend), and we believe this is a natural consequence of the expansion opportunities on offer in the region. As we uncover in the course of our full Regional Profile for Asia-Pacific, this uneasy marriage of high growth and high competition is in many ways APAC’s defining market characteristic: to win is only ever to win big (get the full profile).
"The most significant challenges for insurers in Asia, from an IT perspective are: firstly, moving services to online sales – for agents, brokers, bancassurance and direct to customers; secondly, providing instant and ideally paperless servicing on claims management; and finally, the development of Chinese Insurtech players if they decide to compete outside of their local market." — Ash Shah, Regional CIO and Chief of Staff Property and Casualty at AXA Asia--- ii) The Internal Challenges: Asia-Pacific The internal challenges highlighted by APAC respondents exactly replicate the global trend we staked out in earlier post on Industry Challenges, with a top three constituted by: ‘Lack of innovation capabilities’, ‘Legacy systems’ and ‘Finding and hiring talent’.
--- iii) Insurer Priorities: Asia-Pacific
The following 6 priority areas are those on which insurers in Asia-Pacific lead our other regions, out of our shortlist of 15 priority areas introduced in our earlier post on Insurer Priorities:
"Doing nothing is not an option any longer. The top priority for many CEOs is to acquire the capabilities to deliver true digital innovation that achieves competitive advantage in a very short period of time. Understanding the agile and flexible lean techniques used within the start-up world can help. Analytics, the IoT or mobile are just enablers to ease such transformation." — Sabine VanderLinden, Managing Director at Startupbootcamp
We return to these regional constellation of challenges and priority areas in our full Regional Profile for Asia-Pac, in which we present the direct market testimonies of Steve Tunstall, Joao Neiva and David Piesse. Key areas that we drill down into are:
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Alexander Cherry leads the research behind Insurance Nexus’ new business ventures, encompassing summits, surveys and industry reports. He is particularly focused on new markets and topics and strives to render market information into a digestible format that bridges the gap between quantitative and qualitative.Alexander Cherry is Head of Content at Buzzmove, a UK-based Insurtech on a mission to take the hassle and inconvenience out of moving home and contents insurance. Before entering the Insurtech sector, Cherry was head of research at Insurance Nexus, supporting a portfolio of insurance events in Europe, North America and East Asia through in-depth industry analysis, trend reports and podcasts.
Insurtech must be broken into characteristics that describe a vision, around which some predictions around time-to-value can be made.
Insurtech is a poorly defined term, and as a result is little understood across the industry. At one end of the spectrum it can refer to early stage startup spun out of the world of fintech to focus purely on insurance; at the other end of the spectrum, it can refer to anything remotely innovative around the application of technology within an insurance context. This ambiguity, coupled with a high degree of media attention, has led to confusion and inconsistencies in understanding future value. Typical accepted signs of success, such as a flurry of startup activity in a given sector, higher levels of hiring activity, new inward investment or exit values, are not always good indicators of future value — despite being useful pointers. Furthermore, focusing purely on market-visible startup activity omits equivalent innovation activity underway within insurers, either as part of incubation or greenfield ventures.
Increasingly, we are being asked to help identify the source for future value for a few select concepts being explored within insurtech, specifically around distribution, proposition design and business model formation. Although there is a significant amount of public information available across the market for startup activity, venture activity and exit values, there is a dearth of data available on market traction and customer value. Consequently, in this research, Celent chose to break down insurtech into a set of characteristics that describe a future vision of insurance, around which some predictions around time-to-value could be made. They include attributes like a heightened level of digital engagement, a switch in proposition from purely indemnity toward active loss prevention, a fundamentally different business model and a shift toward a more agile way of working. We refer to these as “insurtech concepts,” and they can be evidenced in both startup ventures and an insurer’s innovation activity, helping to make them universal in their applicability.
See also: How to Embrace Insurtech CultureGiven this inherent market and data collection difficulty at this early stage, we gathered 72 expert predictions of time-to-value for some of these specific insurtech concepts and general preparedness from our innovation leaders panel. The findings from this research have been insightful.
When the insurtech concepts are viewed in their entirety across all lines of business, a number of patterns begin to emerge when evaluating expert predictions for time-to-value. Using these predictions, innovations and new partnerships in distribution are likely to remain the primary focus of insurers for generating value in both the near and medium term. Given the activity already underway around robo advice, aggregators and digital platform partnerships, this observation may come as no surprise. With respect to the proposition, the focus on patterns for continuous engagement also attract a degree of attention (with 92% expecting a significant shift within the next five years), albeit largely focused on existing propositions and models. Experimentation beyond this for the proposition will differ depending on the market segment and product line. It is likely that retail propositions will continue to become more sophisticated in pricing and the use of external data (from sensors or otherwise) for tailoring the price to the end customer, while commercial continues to develop around disaggregation and the formation of alternative distribution, and active loss avoidance. Although the switch to becoming a more virtual organization appears to attract less attention today, Celent believes that the fast pace of AI maturation will provide a more certain path to value in the near term. This sentiment is also being echoed in client conversations we have had as part of the 2018 planning process, as can be seen in Celent’s latest insurance innovation outlook report.
Other highlights include:
Although still at a nascent stage, insurers should prepare to adapt innovation activities to recognize the different expectations for time-to-value between lines of business, while maintaining a strong focus on innovation in distribution regardless, because disruption in this part of the value chain is already clearly signposted.
See also: Key Insurtech Trends to WatchThis report is the first of a two-report series. Part 1 focuses on time-to-value for given insurtech concepts. Part 2 explores how insurance company innovators are approaching insurtech in their ambitions to engage.
You can find the full report here.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
While AI systems can now learn a game and beat champions within hours, generating lots of hype, they are hard to apply to business applications.
While AI systems can now learn a game and beat champions within hours, they are hard to apply to business applications.
MIT Sloan Management Review and Boston Consulting Group surveyed 3,000 business executives and found that while 85% of them thought that AI would provide their companies with a competitive advantage, only 1 in 20 had “extensively” incorporated it into their offerings or processes. The challenge is that implementing AI isn’t as easy as installing software. It requires expertise, vision and information that isn’t easily accessible.
When you look at well-known applications of AI, such as Google’s AlphaGo Zero, you get the impression it is like magic: AI learned the world’s most difficult board game in just three days and beat champions; Nvidia’s AI can generate photorealistic images of people who look like celebrities just by looking at pictures of real ones.
But most business problems can’t be turned into a game; you have more than two players, and there aren’t clear rules. The outcomes of business decisions are rarely clear wins or losses, and there are far too many variables. It is a lot more difficult for businesses to implement AI than it seems.
Today’s AI systems do their best to emulate the functioning of the human brain’s neural networks but do this in a very limited way. They use a technique called deep learning, which adjusts the relationships of computer instructions designed to behave like neurons. To put it simply, you tell an AI exactly what you want it to learn and provide it with clearly labeled examples, and it analyzes the patterns in that data and stores them for future application. The accuracy of its patterns depends on data, so the more examples you give it, the more useful it becomes.
Herein lies a problem. An AI is only as good as the data it receives and is able to interpret it only within the narrow confines of the supplied context. It doesn’t “understand” what it has analyzed, so it is unable to apply its analysis to scenarios in other contexts. And it can’t distinguish causation from correlation. AI is more like an Excel spreadsheet on steroids than like a thinker.
The bigger difficulty in working with this form of AI is that what it has learned remains a mystery: a set of indefinable responses to data. Once a neural network is trained, not even its designer knows exactly how it is doing what it does. As New York University Professor Gary Marcus explains, deep learning systems have millions or even billions of parameters, identifiable to their developers only in terms of their geography within a complex neural network. They are a “black box,” researchers say.
Speaking about the new developments in AlphaGo, Google/DeepMind Chief Executive Demis Hassabis reportedly said, “It doesn’t play like a human, and it doesn’t play like a program. It plays in a third, almost alien, way.”
Businesses can’t afford to have their systems making alien decisions. They face regulatory requirements and reputational concerns and must be able to understand, explain and demonstrate the logic behind each decision they make.
For AI to be more valuable, it needs to be able to look at the big picture and include many more sources of information than the computer systems it is replacing.
See also: Strategist’s Guide to Artificial Intelligence
In inventory management, for example, purchasing decisions are usually made by experienced individuals called buyers, department by department. Their systems show them inventory levels by store, and they use their experience and instincts to place orders. An AI could consolidate data from all departments to see the larger trends — and relate them to socioeconomic data, customer-service inquiries, satellite images of competitors’ parking lots, predictions from the Weather Company and other factors. Many retailers, including Amazon.com, are doing some of these things.
AI is advancing rapidly and will surely make it easier to clean up and integrate data. But business leaders will still need to understand what it really does and create a vision for its use — that is when they will see the big benefits.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Vivek Wadhwa is a fellow at Arthur and Toni Rembe Rock Center for Corporate Governance, Stanford University; director of research at the Center for Entrepreneurship and Research Commercialization at the Pratt School of Engineering, Duke University; and distinguished fellow at Singularity University.