Download

Are You Tapping Your Innovation Energy?

Some of the best concepts, opportunities and solutions find the exit sign faster than they find traction within firms.
The insurance industry is facing seismic and unprecedented shifts on multiple dimensions. From increasing client expectations to new emerging risks, from the emergence of robo-underwriters to the ever-present question regarding the role of traditional channels, insurance carriers have multiple fronts on which to re-think, re-look and address innovation challenges and opportunities. The culture of the insurance sector is changing. The momentum to engage, identify new frontiers of competitive differentiation and execute outcomes has clearly started. As a case in point, Insuretech Connect, the largest insurtech conference had 1,200 participants in 2016, 3,800 in October 2017 and 6,000-plus this year. At events like this, you can feel the incredible energy of insurance professionals, regulators and startups. Insurance organizations are full of insurance professionals with incredible skills and commitment to always go the extra mile. Driven by an entrepreneurial spirit, they seek to reinvent the way things are done and have in many cases always been done. A few trailblazers have challenged their organization’s formal rules and forced habits and have pushed bottom-up innovations within their organizations. Yet other committed insurance folks have been involved in top-down programs that have been created by their companies to capture and execute the next frontier of innovation. We find that, unfortunately, large segments of the workforce do not engage with the innovation process of their employer. We often find that some of the best concepts, opportunities and solutions find the exit sign faster than they find traction within the boundaries of their firm. In some cases, people push for their innovations as side agendas, often driving them as secret agendas where their energies and attention are spent. In other cases, people simply decide that it’s better to pursue the art of the possible outside of the firm. We believe that this is a pity and a waste of positive energies for the existing incumbents. Carriers should embark on building a foundation that creates the conditions and enables mechanisms for promoting the culture of innovation and channeling this energy in a productive direction for the company. We have worked in and with large and international organizations and know well how these complex elephants live and how difficult it is to set formal processes able to promote virtuous circles and orchestrate innovation as a “living, breathing and relevant” process. This issue is big and complex, and there is no magic wand to solve it. We would like to start a discussion on how this issue can be addressed in the insurance sector. The problem as mentioned has many different angles. We decided to start by addressing one aspect of the current state—the silos. Traditional silos are one of the of the killers of insurance innovation. We recently came across situations that speak volumes to the need to consider foundational investment in integration capabilities. We present three myths that often prevent even forward-looking carriers from pursuing well-intentioned innovation strategies. Getting underwriters, risk engineers, marketers, product developers, actuaries, claim handlers and technology folks to break out of traditional silos will need to be a critical first step before any innovation investment or program is considered. See also: How to Get Fit for Innovation   The Myth of the Innovation Mirror A top performer in a line of business at a well-recognized carrier was promoted and placed in the company's innovation group. This leader was a recognized expert in his functional domain and was often sought out for insights on both legacy issues and emerging trends. During a recent meeting, we asked him for his opinions on the issues being faced by a key stakeholder and partner group within the same firm on a business line that, while different, was really close to his business line. Much to our surprise, this leader said, "I have never thought of their business line. I don’t know." We left the meeting with a surprising realization that there are probably many other top performers who excel in their chosen disciplines within well-defined boundaries, yet do not seek to expand the vistas of their exposure or to apply their knowledge to related domains. Their organizations have correctly encouraged their growth and specialization in one domain but have probably never facilitated exchanges between business lines or forced them to go out they comfort zone. We call this the "Myth of the Innovation Mirror," where the images we focus on are constrained by one's own areas of expertise. The Myth of the Signal Catcher A leading U.S. carrier saw the departure of one of its top line leaders. This individual had spent decades building a robust P&L, operating team and client relationships. He had been recognized for his thought leadership and for building teams that pushed the boundaries of what's feasible and valuable for their clients, but he was not directly involved in the innovation program of the company. This company boasted of a well-funded and successful enterprise-wide innovation program, championed by the CEO and supported by divisional leaders. The irony of this departure was that the executive left to pursue an independent entrepreneurial venture because he believed that his ideas and the innovative value proposition would not be implemented by the firm. Despite having a robust and well-managed innovation program, the firm failed to catch the signal that one of their very own was both willing and able and highly motivated to create a future-forward product today. There could be many reasons for this specific departure but we believe that it probably happened because this leader was not formally affiliated with the innovation program. There was no mechanism to watch, catch and act on the weak signals that this leader was sending out, weeks and months ahead of his departure. We believe that this myth of the signal catcher is a serious risk that carriers have to consider and address. Simply creating and operating an innovation program is not adequate and sufficient. Creating the ability and the mechanics to watch, interpret and catch the weak signals coming out of individual and or team efforts is as important if not more important than simply being a scouter of startups, or an inventor of ideas and concepts or an evangelist of the innovations. The Myth of Action Finally, we address the "Myth of Action." A global insurance carrier has innovation centers across key markets. A formalized program exists where leaders and staff resources spend dedicated time getting together and converting their individual ideas and interests to collective outcomes. Some of these centers represent centers of excellence in different domains. In this scenario, we found that an innovation team in one part of the world—while working on a new topic for them—was almost devoid of access to similar concepts and work that had already been pursued halfway around the world. As carriers with a global footprint address innovation outcomes, it will be critical to ensure that action is not mistaken for outcomes. Bridging the distance within and between different centers of innovation is crucial to ensure that the teams do not end up becoming innovation silos unto themselves. The "Myth of Action" arises when innovation champions or leaders assume that presence and permanence are sufficient. We are perfectly aware of the local specificities that make the possibility of simply copying-and-pasting an insurance solution coming from another country a utopian idea. But many ideas can inspire location-specific variations and be tailored to the local needs. While presence across regions and permanence from a mandate perspective are key, we believe that it is more critical to ensure that physically far-removed teams get structured and unstructured opportunities to be exposed to work that peer groups are driving at non-local locations. Researchers have found that proximity is a key driver of organizational effectiveness. Solving for this “distance bridging” will be critical. Simple tactics like designing intentional cross-location collaboration will ensure that exchange of ideas in large and complex organizations can transcend distances. So how can you attack these myths head on and build or mature your innovation practice? We recommend that innovation efforts identify three distinct but connected archetypes for roles/resources working with an innovation focus. We propose the trifecta of Observer, Interpreter and Storyteller. Think of these as hats or lenses, rather than roles or restrictions. Observers are designated to be non-judgmental observers of actions, outcomes and opportunities. With two leading questions of “What do I see?” and “Where do I see?”, Observers play a key role in taking a non-action view and in scouting even where you don’t expect to find anything. Interpreters are driven by two different questions. While the Observer has simply made her observations known, the Interpreter asks, “Why do I see what I see?” and “What does this mean?” These questions are designed to help the Observers dive deeper into the observations they are presented with, but also to rationalize the knowledge and ideas identified. While there might be a temptation to go broad and expand the scope of one's assessment, we believe that focusing on depth and asking increasingly fine-grained questions is more beneficial. Storytellers are the final actors in an innovation practice. We humans are wired for storytelling. From time immemorial, our ancestors have passed on down through generations many a story of heroes, victors and vanquished. We recommend that the Storytellers play their part in the modern version of "tell me a story," and spread the word about the insights that the Interpreters have distilled. The storytellers have to evangelize, inspire and motivate the organization in the adoption of innovation. See also: Key Trends in Innovation (Part 6)   Taken together, the Observer, Interpreter and Storyteller create the much needed and often missing enterprise-scale integration that helps make innovation efforts successful. These archetypes can be introduced and embedded into almost any current innovation program. Their integrated activities will contribute to channel the positive energy in a productive direction for your company. Think of these as calibrations you can do to any currently defined innovation operation, resource or delivery model. Done right and executed consistently, these three roles can help address the three myths, and the risk of innovation teams not living up to the promise of what they can truly deliver. In many ways, the IoT Insurance Observatory (spearheaded by one of the authors of this article) has applied this trifecta of lenses with an extremely narrow scope—the usage of sensors within the insurance sector—targeted at the open market (opposite to the internal focus of the discussion above). This think tank is, first of all, constantly observing and scouting the usage of sensors in different insurance business lines around the globe. Second, it is interpreting best practices and pitfalls for the members, so providing them the most globally relevant IoT insurance knowledge. Last but not least, it has as a core deliverable the storytelling of this knowledge through workshops dedicated one-to-one to each of the organizations that are members. In this way, the Observatory has aggregated almost 50 organizations between North America and Europe and is promoting IoT adoption in the insurance sector. **** We believe carriers can employ these three tactics/rules to mitigate the risks of the three myths. These tactics are part of the solution for the big and complex problem of how to promote virtuous circles and orchestrate innovation. Join our discussion to find additional solutions to catalyze all the positive innovation energy is emerging in the insurance sector. The article was written by Matteo Carbone and Sri Nagarajan.

What Digital Can Do for Disability Claims

For insurers, digital technology offers new ways to manage risk that relies less on face-to-face and traditional clinical assessment.

Healthcare is being transformed by advances in artificial intelligence, virtual reality, machine learning, sensors and other innovative technologies. Practically everybody has a smartphone, making it easier than ever to gather data and consent to third-party access. Unique data insights mean providers can offer people products and services tailored to them individually. For insurers, digital technology offers new ways to manage risk that relies less on face-to-face and traditional clinical assessment; this is why there is so much interest in understanding how innovation might work. Selected comments from four key players in the digital health ecosystem make clear the appeal of putting two and two together. Thomas Lethenborg at Monsenso, a mobile platform for mental health, said, “Digital technology helps an individual move from reactive behavior to being more proactive - and this changes the paradigm in particular with engagement.” It’s a view shared by David Forster of Thrive, a digital interventions app for mental health: “Data drives our understanding of what works best for the individual.” According to Forster, the success of digital technology in clinical settings points to real opportunities in insurance: “It makes it possible to provide policyholders help with illness prevention, early detection and assistance on a personal level.” Ian Prangley, of exercise rehabilitation service TrackActive, continued the theme when he said, “For insurers, digital solutions can drive connectedness, engagement and customer satisfaction while enabling people to self-manage their health. Harnessing data insights and implementing artificial intelligence (AI) is key to achieving this.” See also: Why to Digitize Disability Claims   A comment by Danny Dressler of AIMO, an ecosystem integrating intelligent motion analysis into musculoskeletal care, added further confirmation: “As more and better data is gathered and processed safely, AI offers the most promise to take care of people's health, and fix issues in both healthcare and the life and health insurance sectors.” By using digital means, insurers can create scalable, automated, speedy ways of supporting people when they need help the most. Proponents argue it offers better health outcomes for policyholders that will reduce the costs associated with long disability claims - a win-win for both insurers and consumers. Dressler also said that “technology like ours lets insurers offer customers new solutions such as dynamic pricing and automated claims and even help to prevent claims from happening.” Lethenborg says it represents “an opportunity to ensure the data collected gives holistic insights and analytics that we can use to intervene more rapidly, when help is needed.” But it’s crucial the highest levels of privacy and data protection are guaranteed and operators are in full compliance with regulations. An imperfect balance of privacy with innovation is a deal-breaker for consumers. Forster is clear how delicate this balance is: “We recognize our responsibility to safeguard users’ data, but at the same time information technology empowers people to make choices and participate actively in managing their own health - it puts them in the driving seat for the first time.” For digital solutions to be convincing, research and scientific evidence are needed, but with newly made services, long-term experience is scarce, and a leap of faith is required. Dressler spoke for all in saying, “We maintain strong links to scientific institutions because the general technologies underpinning our solutions emerges from scientific thesis...[This means] we only implement new features or functions after a rigorous validation process, especially because we are asking people to trust us with their health and well-being.” Dealing with high volumes of data is not without risk, particularly when it’s shared with third parties. See also: Digital Innovation in Life Insurance   Prangley has pointed to recent concerns over how sensitive data is being used to highlight the challenges faced, “The key is to anonymize and protect data, and have customers consent to sharing it on the understanding it will be used solely to improve their health.” This insight is driven home by Lethenborg, who said, “Transparency about how the data will be used is essential to building trust.” Digitization has already brought new products and services that have had positive medical and scientific impact. As Prangley said, “Technology has connected people and changed how we relate to each other. There [are] arguments for and against this of course, but in the context of health and wellbeing we believe it’s a great thing.” With mental health and musculoskeletal problems as the leading causes of disability claims in every market, these companies can bring digital solutions and opportunities - and health insurers can also feel great about them.

Are Insurers Ready for Voice Search?

In a world where customers already do research and contact insurers via multiple channels, voice assistants are a natural frontier for marketing.

Who do property and casualty insurance customers turn to when they need help? In the past, answers have included insurance agents, customer helplines and company websites. Today, however, customers are increasingly likely to consult Alexa, Siri or Cortana. As voice assistants gain popularity in homes, in cars and on smartphones, they’re also gaining traction as a marketing tool. Here, we look at the ways in which insurance companies are using voice assistants as part of their marketing and sales strategy, as well as what to expect in the near future. How Voice Assistants Are Changing Marketing Voice assistants commonly come in one of two forms: wireless speakers that can be placed in the home or office, or as built-in tools on smartphones. iPhones and various Android devices have had them for a few years now. In some ways, voice assistants work similarly to visual or text-based tools like smartphone apps and Google search bars. The user asks a question or enters a command, and the device responds to it. Voice assistants like Alexa even offer apps, or “skills,” that work similarly to smartphone apps — except they rely on audio rather than visuals to share information, TechCrunch’s Sarah Perez writes. The audio-based approach changes the ways in which both search results and apps work on voice assistant devices. A text-based Google search, for instance, returns a list of links from which the user can choose. A voice-based search, however, tends to return the single response the AI thinks best fits the user’s query. Some experts praise this option for its speed and flexibility. “Since voice flattens menus, it will make daily tasks far easier to complete,” Jelli CEO Mike Dougherty says. Yet it also puts additional pressure on marketing teams to ensure that their content gets chosen by the various search engines that inform each voice-based device, says Richard Yao, senior associate of strategy and content at IPG Media Lab. Voice assistants haven’t just changed how search results are presented. They have also changed how users launch searches in the first place, says More Visibility’s Jill Goldstein. While text-based searches tend to focus on two or three keywords, voice-based searches use full, natural-language sentences. These often start with question words like “what,” “how” or “when.” See also: Insurtech Starts With ‘I’ but Needs ‘We’   These questions give marketers insight into where shoppers are in their buying journey and how best to meet their needs — but only if marketing teams are collecting and using this information, says Tyler Riddell, vice president of marketing for eSUB Construction Software. Not only are marketing teams learning to adapt to the differences between audio and visual, but they’re also learning how to adapt to a search tool that adapts itself. Because voice assistants use artificial intelligence and machine learning, they can adapt to changes in search terms, says Gartner analyst Ranjit Atwal. The onboard AI is designed to learn over time, gaining a better sense of how users frame their queries and the sort of information they may be looking for. ‘Alexa, Find Me Auto Insurance’: The Rising Demand for Voice Search Based on recent sales trends, 55% of U.S. households are expected to have a smart home speaker, with voice assistance enabled, in their houses by the end of 2019, Dara Treseder at Adweek reports. Voice assistants are also a mainstay of many smartphones, from Apple’s Siri to Google’s voice search option triggered by saying, “OK, Google.” Insurance customers increasingly prefer to include digital channels in their search for property and casualty insurance. With voice assistants occupying millions of smartphones and a wide range of other devices, customers increasingly prefer to rely on these tools, as well. Nearly half (46%) of insurance customers already use voice search tools at least once per day, according to Shane Closser at Property Casualty 360. One in four want their voice assistants to be able to give them more information on insurance agents and products. One in three wanted to use voice assistants to book appointments with a particular insurance agent. Service-based companies that offer “highly complex and highly personal” services are uniquely suited to thrive in the voice search era, says Adweek’s Julia Stead. While Stead focuses on travel, finance and healthcare, her analysis applies to P&C insurers, as well, because these companies also offer services that have long been accessed via voice (phone), are tailored to the needs of each customer and often require access at odd locations or hours. And while the conversation about tech innovation often focuses on younger users, voice assistants are increasingly popular with older insurance customers. See also: Future of Insurance Looks Very Different   Lauryn Chamberlain at GeoMarketing.com says that 37% of consumers age 50 and older say they use a voice assistant, often because simply speaking to a smart speaker or phone is easier than tapping, swiping or reducing a question to its key search terms. In other words, older users can think of their voice assistants as a helpful background entity rather than as a device. In short, voice assistants are cutting across demographics. They’re entering more homes and workspaces. And insurance customers want to use them to secure coverage. How P&C Insurers Are Incorporating Voice Into Their Marketing Several insurance companies are already experimenting with voice assistant tools as part of their own marketing process, according to Danni Santana at Digital Insurance. For instance, Nationwide, Liberty Mutual (and subsidiary SafeCo) and Farmers have all launched Amazon Echo Skills. Progressive, meanwhile, joined Google Home in March 2017, the first insurance carrier to do so, according to Rachel Brown at Mobile Marketer. Other insurance companies have experimented with different approaches. Amica Mutual Insurance, for example, launched an Alexa skill that doesn’t connect users to their individual accounts. Rather, it offers information in more than a dozen categories to help users better understand billing, discounts, storm preparation and more. With the development of Alexa skills and similar tools, brands are thinking about how a voice assistant’s sound affects their brand development, says Jennifer Harvey, VP of branding and communications at Bynder. The choice of voice tone, pitch and speed can all send a powerful message about an insurer’s brand and culture, whether it’s reassuring, serious, cheerful or anything in between. One of the big opportunities for insurance companies and voice assistants is access. Currently, voice assistants can take on many simple tasks but can’t always handle a transaction as complex as ensuring a customer receives the right home or auto coverage for their needs. Yet developments in AI and voice recognition indicate this may change. “Alexa is already capable of placing a complicated pizza order,” says Inbal Lavi, CEO of Webpals Group, “underscoring that voice assistants will act as more than middlemen.” For now, however, even the digital middleman approach can benefit potential and current P&C insurance customers and the companies that serve them. “We want to enable easy access for our customers,” says Alexander Bernert, head of brand management at Zurich Insurance. “Consumers do not necessarily think of taking out disability insurance between 9 am and 5 pm, but maybe even shortly before midnight.” It can be tough to reach an insurance agent shortly before midnight. But a voice assistant can find one, provide information and even schedule an appointment — making it easier for potential customers to turn into actual purchasers. In a world where insurance customers already do research and contact insurers via multiple channels, voice assistants are a natural frontier for insurance marketing.

Tom Hammond

Profile picture for user TomHammond

Tom Hammond

Tom Hammond is the chief strategy officer at Confie. He was previously the president of U.S. operations at Bolt Solutions. 

Faulty Math Behind Over-Treatment

A recent recommendation to start colonoscopies at age 45 shows why the U.S. suffers from over-treatment and worse outcomes.

The American Cancer Society (ACS) recently decided that, because the rate of colon cancer has increased by an “alarming” 22% in the 45-to-49-year old cohort this century, colon screenings should start at age 45. This is a very instructive decision, though not because it is a good idea. Rather, it’s instructive because it’s a “teachable moment” about why Americans suffer from over-diagnosis and over-treatment so much more than people in other modern economies, with worse outcomes to show for it. One reason is the failure of our medical and public health community to understand the difference between relative risk and absolute risk. On one hand, a smoker might have a relative risk of heart attacks that is only a few times greater than the risk for nonsmokers. However, with Americans suffering 400,000 heart attacks a year, many of us do whatever we can to avoid small increases in relative risk of a heart attack because the absolute risk is so great. On the other hand, suppose the relative risk of an unsafe airline is 10 times the risk of a safe airline. But with about three crashes a year (in a very bad year) over the course of 30 million flights, even a whopping tenfold increase in relative risk would bring your absolute risk of crashing up to a trivial 1-in-a-million. Here at Quizzify, we’d still opt for the unsafe airline if it has more legroom and a better mileage program. See also: A Road Map for Health Insurance And that brings us to exactly what the American Cancer Society miscommunicated…with a disturbing twist, as you’ll see below. This “alarming” 22% increase in relative risk over the course of this century translates into an increase in the absolute rate of colon cancer in the <50 cohort from 0.006% to 0.007%. Yes, 0.001 percentage point more of the <50 population in this country will get colon cancer now than 18 years ago. Further, suppose half of that 0.007% had a family history (or some other major risk factor) and would be advised by their doctor to get screened regardless of guidelines for the average person. That leaves roughly 0.0035% of the 45- to 49-year-old population who could possibly benefit from a random screen. That’s not much different from your lifetime odds of getting struck by lightning. And a screen is far from a lifesaver, in general. Quite the contrary, statistically speaking it is likely to find the slow-growing tumors while missing the more aggressive, faster-growing tumors that begin between screens. Screening is not a surefire way to detect cancer, by any means. The Disturbing Twist: The Hazards of Screening That trivial benefit must be weighed against the nontrivial harms. The risk of a complication, such as a perforation, is estimated at between 1.6% and 1.8%. In all fairness to the ACS, it isn't insisting that the screen be done via a colonoscopy, though the non-invasive screens have such high positive/inconclusive test rates that they often lead to colonoscopies. That makes the rate of complications about 3,000 times the odds of having your life saved by early diagnosis of colon cancer. See also: How Telehealth Changes Senior Care Of course, the worst complication is death, and the mortality rate from colonoscopies (0.02%) appears to be, on its face, much higher than the rate of lives that would be saved. However, in all fairness, the mortality rate, like the complication rate, in general, increases with advancing age. Hence maybe the mortality rate in the 45- to 50-year-old cohort isn’t any higher than — and might even be slightly lower than — the rate at which early detection will save lives. So what’s an employer to do? We’d say, stay on the sidelines. Let employees work this one out for themselves, with their doctors. Or show them this post. But don’t encourage them to run out and get screened on the basis of a recommendation that is at best controversial and at worst harmful.

Digital Survival Tools for Agents

Agents and brokers need to consider three things: multi-generational marketing, administration tools and digital strategy.

Whether the majority of your business is online or in-office, it is crucial for you to have the right tools to help you capitalize on the insurance market and get ahead of the competition in a changing landscape. It does not matter what type of insurance you are selling, whether it’s employee benefits, life insurance, group insurance, voluntary benefits or property and casualty. While your role may not be directly affected by things like legacy system transformation, robotics and big data, there will be ripple effects. Besides obtaining new clients, presenting renewals and marketing, changes in regulation and advances in technology are all things that agents will have to contend with. Here are three elements that savvy agents and brokers will want to consider. Multi-generational marketing Global populations are now categorized (albeit loosely) into four categories: Baby Boomers, Generation X, Millennials and Generation Z. Although Baby Boomers are still the largest population, the U.S. Census Bureau predicts Millennials will outnumber Boomers by 2019. These differentiated markets make targeting sales much more difficult. Fortunately, there are online tools that can support you. The trick here is diversifying your presence. Ensure that you have a presence on multiple channels so that you are able to meet your customers where they are. See also: 10 Essential Actions for Digital Success   Update your agency website with a live chat feature, and ensure it is easy to contact you online. Examine whether it makes sense to use Twitter, Facebook or Instagram. If you do, you’ll need a strong content strategy that provides real value to pull in visiting prospects. Don’t just surf the web, observe the web. Set up Google alerts and analytics and Hootsuite streams to follow partners and competitors. Watching for trends will keep you ahead of the game. Administration tools A strong agency management system can provide you with everything you need to support your customer lifecycle. When looking for the right one for you, think about CRM and marketing automation. Determine what will make it easier for you to track leads, nurture prospects, close deals and obtain commissions. Once you’ve sold a policy, a high-quality microphone and webcam will enhance consistent communication with customers remotely on Skype, WebEx, GooglePlus Hangouts or even Facebook. Get comfortable with automation As you get comfortable with a new and diversified way of connecting with your customers, you’ll want to consider that insurance carriers are doing the same thing. Accenture’s Technology Vision 2018 report revealed 82% of insurance carriers agreed that their organizations must innovate faster just to stay competitive. In a world where customers are shopping around for options and prices all the time, retention itself becomes a valuable commodity. Help carriers help you by learning what tools their new systems have to offer so you tap into all the resources available. Do your insurance companies offer broker portals? Do they offer online quoting capability for immediate results? Can you generate a proposal or immediately sell a policy? Can you offer that functionality on your own website? The carriers that invest in your success by improving sales, underwriting and admin functions for quicker turnarounds and smooth renewals are doing themselves a favor, too. See also: Agents Must Become ‘Discussion Partners’   Think strategy As you determine the best way to move forward, sit down with others on your team, start a Google doc and plan your strategy for the year ahead. As Yogi Berra wisely said, “If you don’t know where you’re going, you might not get there.” What free tools will you use? Which ones will you invest money in? How will you track progress to determine ROI? What tools are working for you? The best agents and brokers will be nimble enough to exploit the tools available to them and prepare for new ones as they arrive. The sooner you start, the more likely you’ll find yourself ahead of the digital curve.

Insurers: Start Boosting Your 'AIQ'

Insurers need a much higher artificial intelligence quotient (AIQ), but they face a crucial talent gap among employees.

||||
In this blog series, we explore what benefits insurers would gain if they start boosting what we call the Artificial Intelligence Quotient (AIQ), and give an overview of why and how insurers should leverage technology, data and people to get started. Perhaps some of you remember when an IBM computer called “Deep Blue” defeated world chess champion Garry Kasparov, in 1997. Twenty years later, he said:
“Human plus machine isn’t the future, it’s the present; Don’t fear intelligent machines, work with them.”
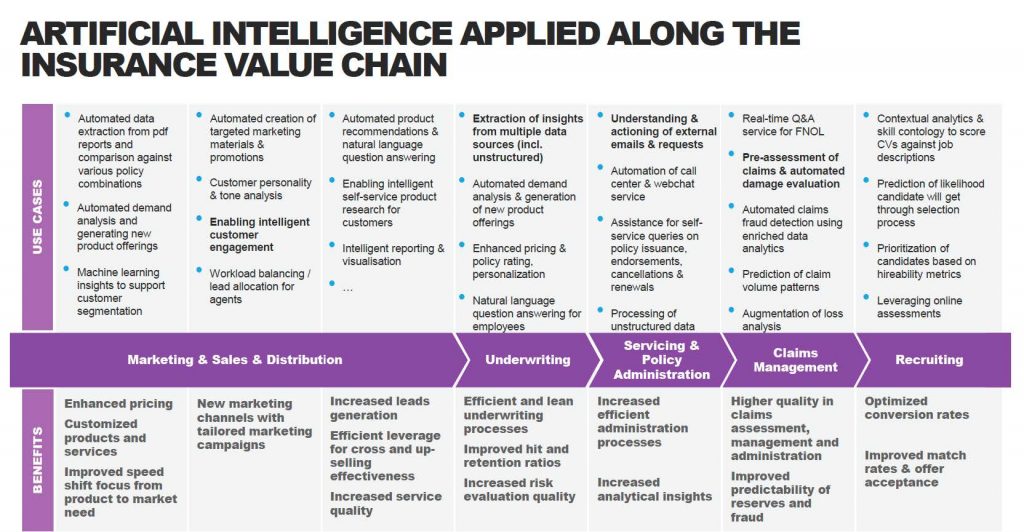
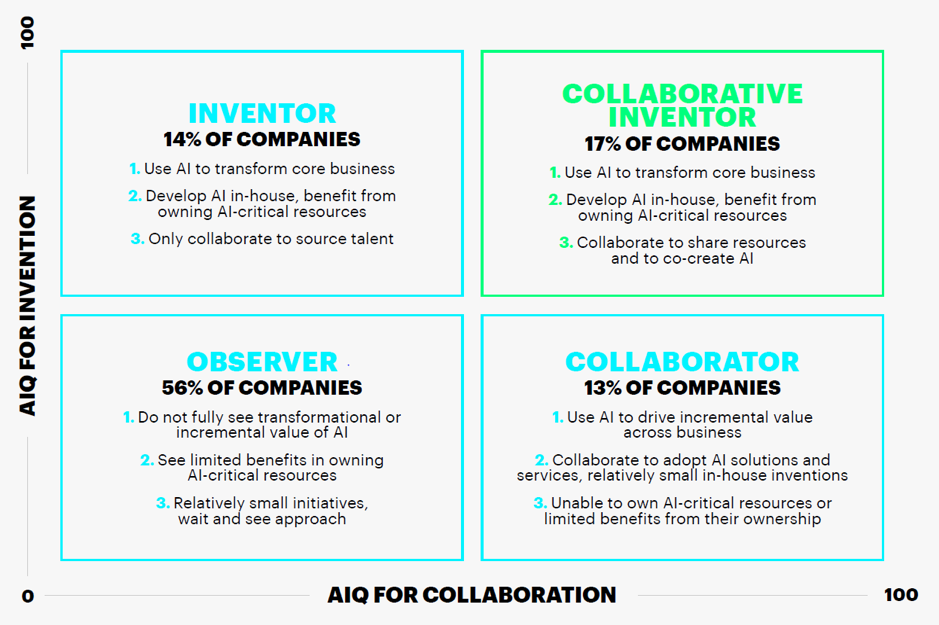
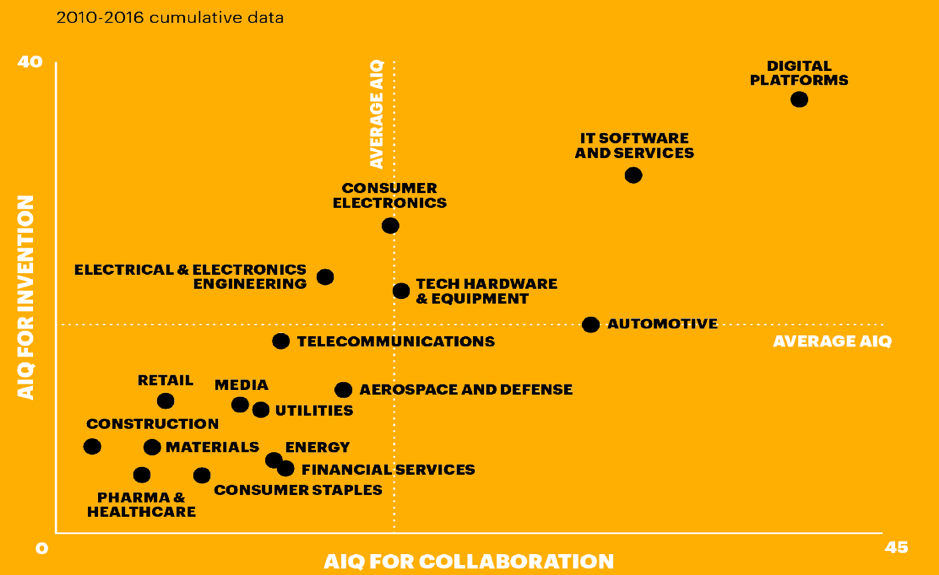
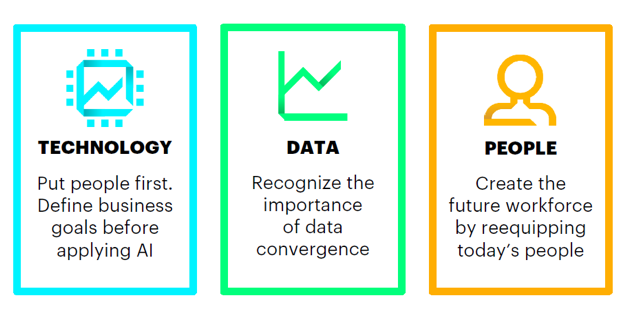
Please note, he says “plus” not “versus” or “against.” I believe he is right – there is actually an optimistic story of unlocked potential. When AI was enlisted to detect breast cancer A team of Harvard pathologists recently showed how some commentators on the future of artificial intelligence – who either wax enthusiastic about the productivity gains or predict the elimination of jobs – are missing the most important point. The doctors created an AI-based technique to identify breast cancer cells. It did well, scoring 92% accuracy, but still fell short of human pathologists, who typically achieve precision rates of around 96%. The biggest surprise came when humans and AI combined forces. Together, they accurately identified 99.5% of cancerous biopsies. Much like Kasparov, I believe this is how AI will realize its fullest potential—when human ingenuity and intelligent machines combine synergistically to deliver more than either can on its own. How does this relate to Insurance? There are numerous use cases of AI that can be applied along the insurance value chain, such as enhanced pricing, customized products and services, efficient underwriting and claims administration processes. Sales & Distribution — Employing machine learning insights to support customer segmentation could lead to benefits such as customized products and services and increased sales. Underwriting & Risk Management — The extraction of insights from multiple data sources can lead to improved risk evaluation quality and, hence, better pricing. Servicing — using machine learning to handle external emails and requests can lead to an increased efficiency in administration processes. Claims — The pre-assessment of claims and automated damage evaluation leads to higher quality and accuracy in claims assessment, management and administration and, hence, to cost savings. Recruiting — Leveraging contextual analytics and skills-based ontology to score resumes against job descriptions leads to an optimized conversion rate. There are many benefits for insurers – more efficiency, better pricing, customized products and services. AI will deliver efficiencies, but its greatest benefit will be to drive growth. Especially when it’s used primarily to augment the capabilities of humans. Artificial intelligence is set to play a major role in insurance, not only by improving efficiencies but by significantly enhancing the customer experience, boosting innovation and opening up new sources of growth. Accenture conducted an econometric analysis that forecasts that insurers that invest in AI and human-machine collaboration at the same rate as top-performing businesses could not only profit from becoming a more efficient company but also boost their revenue by an average 17% by 2022. But the research revealed that, while executives expect AI to completely transform insurance, they believe only 25% of their employees are ready to work with intelligent technologies. See also: 3 Steps to Demystify Artificial Intelligence   Insurers acknowledge AI’s importance and its transformative potential. They admit their people are critical to the success of their AI initiatives, and the growing skills gap is the key factor influencing their workforce strategy, but only 4% plan to significantly increase their investment in reskilling programs over the next three years. So, there is a major disconnect in insurers’ approach to AI. Time to Boost Your AIQ To help insurers take the next steps toward investing in AI, we created two indexes to see what is working. We studied both the FORTUNE Global 100 and what we call the “Intelligent Global 100” – these are pioneers in the development of AI technologies and applications – for the period between 2010 and 2016. For those 200 companies, we looked at both their in-house focus (their AIQ for invention) and their outside focus (AIQ for collaboration). Both are essential. Organizations with a high AIQ invest significantly in their in-house AI capabilities and collaborate externally. Yet our analysis revealed that fewer than 20% score well on both indexes — those companies we call “collaborative inventors” (who balance in-house innovation with external collaboration) — while 56% were weak on both. Not surprisingly, financial services (as you can see in the lower left quadrant) currently has one of the weakest scores on this matrix. How do you build your AIQ? There are three key ingredients to building a high AIQ: Insurers need to own some of the technology (but define business goals before applying AI), some of the data (recognize the importance of data convergence) and some of the talent (create the future workforce; start reskilling your staff). And they will also need to be deeply involved in a broader ecosystem. You need to work at all three, both in-house and collaboratively, to achieve success. Business leaders need to evaluate how they invest in technology, data and people. To start, they need to ask themselves the following tough questions: Technology:
  • Does your AI amplify the skills of your people?
  • Are you integrating your AI with internal and external systems?
  • Does owning your own AI differentiate you in the market?
Data:
  • Have you partnered with companies that can monetize your data?
  • Can you integrate data with your legacy systems?
  • Do you practice responsible AI?
People:
  • Can you reskill your workforce to stay ahead of automation?
  • Do you offer continuous on-the-job training?
  • Can your leaders manage diverse teams?
Finding honest answers to these questions and taking the next steps forward matters, as they are the basis for leveraging the full potential of AI. Before embarking on this transformational journey and to answer all these questions, it makes sense to first develop a cross-enterprise AI strategy to clarify strategic goals – the whys, the hows and the whats of the business model. As we have seen, the majority of insurance executives believe human-machine collaboration is important if they are to achieve their strategic objectives. Because the workforce is a critical enabler of any AI strategy, insurers need to develop a workforce that is equipped and willing to work at a higher level in collaboration with intelligent machines. Insurers, in my view, cannot afford to wait until the future is clear and predictable, but need to start now. There is a choice that insurers need to make. Which company do they want to be? The one that has strategically leveraged intelligent technology, data and upskilled its people – or the one that has not? Transforming the workforce to collaborate effectively with AI won’t be easy or quick, but it is essential if the potential of artificial intelligence is to be realized. The time to start is now. See also: Strategist’s Guide to Artificial Intelligence   As mentioned at the beginning, the use cases for the application of AI along the insurance value chain are numerous, and I will explore some in my next posts. This series is structured to answer a number of key questions:
  • How can you boost your AIQ in sales and distribution?
  • How can you boost your AIQ in underwriting and risk management?
  • How can you boost your AIQ in claims management?
  • How can you boost your AIQ in client services and policy administration?
  • What steps should you take to create the insurance workforce of the future needed to become an AI-driven company?
To learn more about how to raise your organization’s AIQ, download the report: Boost your AIQ. You can find the article originally published at Accenture.

Whole New World for Customer Contact

Some individuals still want to receive information in the traditional ways, but the tide is turning, and insurers must catch up with customers.

Common things we hear these days: “If you really want to reach me, text me.” “Send that file to me via Slack.” “I live on Facebook, so send me a message on Facebook Messenger.”

We also observe that many people never answer voicemail, virtually ignore emails and throw away mail without even looking at it.

These are samplings of the communication patterns that are evolving in our society today. Meanwhile, how do we in the insurance industry communicate with our policyholders, agents, claimants and others? Email, phone calls and documents in the mail predominate. Web portals are also common. Some of the newer options for interaction are not on the radar of most insurers. Now, there are certainly individuals who still want to receive information in the traditional ways, and there will continue to be a need for these options, but the tide is turning.

See also: The Missing Piece for Customer Experience  

SMA has been investigating some new communication options and their implications for insurers. Our new research report, Advanced Customer Communications in the Digital Age: New Options for Insurers, explores how communications have evolved, how the insurance industry is using these options (or not), example use cases and what it all means in the context of an omni-channel environment.

Some of the new(er) forms of communication that have been gaining adoption and setting new expectations for customers include:

  • SMS texting and online chat: Although it is difficult to classify these as “new,” the insurance industry still has very little use of the technologies outside of the enterprise.
  • Messaging and collaboration platforms: These have been proliferating over the past decade or so, with tools like Skype, Facebook Messenger, Slack, Zoom and many others gaining large followings.
  • Voice assistants and chatbots: As voice and AI technologies have leapt forward, the opportunities to leverage AI-driven chatbots and voice assistants has increased dramatically. Much experimentation is underway in insurance.
  • Smart documents: Documents in many forms will continue to play a major role in communicating information to prospects, producers and policyholders. Rethinking those documents from a customer perspective and making them interactive and parametric provide great opportunities for the industry.
  • Augmented/virtual reality: Although a bit further out in terms of adoption and implications for insurance, there are already pilots and projects underway in the industry.
See also: How Customers Buy… and Why They Don’t  

The way the world communicates is rapidly changing, and everyone has their favorite options. Insurers would be wise to consider these in their customer journey and omni-channel strategies and plans.


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.

Bringing Dreams to Life

It's exciting to see companies bring to life the sorts of dreams that many of us have been describing for years now.

sixthings

Greetings from Las Vegas, where we've gathered for the third InsureTech Connect with 6,000 or so of our closest friends. That's about twice as many attendees as last year, which was twice as many as the first year. Exponential growth is good, right? And the group now represents what a venture capitalist might call a "full stack" -- all types of companies, investors, startups, technologies, countries, you-name-it are represented here.

It's exciting to see companies bring to life the sorts of dreams that many of us have been describing for years now. For example, I met with Cover Genius, which takes an API-based (as in, application programming interface) view of the world that enables a model I've described as "Do you want fries with that?" The startup offers digital versions of insurance products that e-commerce companies can bundle into their offerings, generating savings on costs of sales that can be shared with customers. The first big success has been with rental-car insurance that travel sites can offer when someone makes a booking. The price from Cover Genius is much lower than what you'd be quoted at the rental car counter. And I believe that Cover Genius is just scratching the surface. As insurance products become APIs that can fit into any digital product or service and any sales process, the lower prices and ease of purchase will have customers ordering lots of "meal deals."

I was also struck by the work at Parsyl, which is just coming out of stealth mode with an ingenious application of the Internet of Things that reifies another of my big themes: that insurance should increasingly be about preventing the bad stuff from happening in the first place. Parsyl, which has formed a partnership with AXA XL, has developed sophisticated, reusable sensors that can be placed in shipments to make sure they stay within certain important ranges, such as temperature in the case of a load of fish. The sensors don't just trigger an insurance payment if there is a problem, as current, simple sensors can, but can signal when an indicator is heading out of range, so that someone might be able to intervene. In any case, the sensors record when and where a problem occurred, so responsibility can be assigned quickly and accurately and so steps can be taken to prevent a recurrence. 

I found reason to be optimistic because of a workshop that our own Guy Fraker, ITL's chief innovation officer, ran for some 60 executives from incumbents that are trying to figure out how to set up innovation programs. He took the group through some exercises that showed them that they could quickly generate lots of hypotheses for potentially important innovations and assured them, "You only need four or five people to drive innovation. You don't need 100. This is not Big Pharma R&D."

The cherry on top was that a representative from a major auto maker told the group that he was looking to break out the insurance piece that goes into the monthly price for his vehicle subscription program  -- people who "subscribe" are basically leasing a car but for an indefinite period longer than 30 days and can pick and choose among a certain set of vehicles, such as a sports car line. These subscription programs are growing fast at any number of auto makers, so why wouldn't others be interested in breaking out the insurance piece, offloading the risk and making the monthly price for the car at least look lower? Why couldn't some enterprising company come along with a white label product, expressed as an API that could fit into the processes of all these car makers? You could almost hear the wheels turning in people's heads as they thought through the possibilities. 

Maybe someone will announce such a product at next year's ITC. Or, why wait until then? 

Have a thought-provoking week. 

Paul Carroll
Editor-in-Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Engaging Employees: Key to Success

No matter the size of your company or the lines you deal in, having an engaged team makes all the difference.

After three decades working in this competitive industry, I have come to understand the very significant role that employee engagement plays in the success of any insurance company. No matter the size of your company or the lines you deal in, having an engaged team makes all the difference.

I have seen this in action, first-hand, as the CEO of IAT Insurance Group. When I joined the company four years ago, IAT’s underwriting results were underperforming. For the last three years, however, we have turned an underwriting profit.

What changed? In part, this came about by refocusing the company on underwriting discipline and restructuring key operations. I firmly believe, however, that it is also due in large part to a renewed emphasis we have placed, company-wide, on fostering employee engagement. We could not have achieved such an immediate turnaround in results without the input of our employees.

A focused program of specific, concrete actions key to employee engagement

Employees are savvy. They know when management is all talk. This is especially true when it comes to employee engagement. Insurance companies must take concrete actions that are more than just motivational poster slogans to foster a positive — and profitable — working environment.

See also: Employee Wellness Plans’ Code of Conduct  

This is why we have engaged in a focused program over the past four years with specific tactics to foster an employee culture that creates productivity and growth. This includes:

  • Getting everyone on the same team. IAT has grown through a series of mergers and acquisitions, with many business units operating under their original names and branding. That led to a fracturing of IAT’s internal identity as one company. One of our first initiatives when I joined IAT was to bring all the units together under one IAT umbrella. That put everyone on the same team, pulling together in one direction.
  • Establishing a unified internal “brand.” It was one thing to unify IAT’s disparate business units under one umbrella on paper. It’s quite another to have employees actually feel like one. To help build culture, we established an internal brand that we call “A Family of Answers” to help all employees, at every level, identify as one company with one mission. At IAT we provide answers to each other, our customers and the community. This core identity reflects our company values and unites us.
  • Investing in technology that connects employees. IAT has offices throughout the U.S., which makes operating as a unified team difficult. To foster connections, we have invested heavily in technology that effortlessly links our employees together. We make extensive use of videoconferencing, for example, and for more than just big meetings. Instead of picking up the phone to talk to a colleague from another office, we turn on our desktop video cameras to have that conversation. The company also launched a state-of-the-art Sharepoint-powered intranet, called IAT Connect, that lets all employees access the latest corporate information as well as collaborate on projects.
  • Fostering real openness and transparency. Companies make better decisions when more people weigh in, and engaged employees are more likely to share feedback and ask questions. To encourage more people to contribute, we hold quarterly all-employee webcasts to provide an update on the company and key projects. More importantly, however, we solicit and answer employee questions. We give employees the option to ask their question live during the meeting or submit it anonymously. We make sure every question is answered. If we run out of time during the meeting, we answer remaining questions on IAT Connect. The company benefits from the thoughtful inquiries and insight of our employees, and, at the same time, we are building transparency and trust.
  • Acting on employee feedback. Encouraging employee feedback is one thing, but it will not help engagement if nothing changes in light of that feedback. We make a point of listening to employees — and then acting. For example, during one of our quarterly webcasts, an employee asked if a year-end performance bonus could be distributed before Black Friday instead of in December so employees could take advantage of sales. The executive team discussed it, and the change was made.
  • Encouraging community engagement. Giving back to the community is the right thing to do. It also aligns with our core values and goes a long way toward building a culture of engagement. We provide a company match for employees’ contributions to charities, paid time off for volunteering and a companywide week focused on community service and charity called Giving Week.
  • Investing in training and career development. Investing in our employees’ success is a win/win. We launched IAT University last year to provide free access to an array of courses, from technical skills training to leadership development.
  • Formalizing employee recognition programs. We introduced two programs to provide more opportunities for employees to be recognized and financially rewarded for outstanding customer service and performance.
  • Moving to a pay-for-performance system. Money is not the only motivating factor for employees — but it is an important one. IAT always had a generous bonus program, but all employees were largely treated the same, despite their performance, and a majority of staff found this de-motivating. Based on employee feedback, we moved to a pay-for-performance compensation system that encourages productive employees who contribute to the company and its profitability. The system works and is very generous. In 2017, based on the company’s success, 94% of IAT employees earned a bonus, and the total bonus pool was up more than 14% over the year before.

Measure and benchmark to ensure employee engagement goals are met

Even with concrete actions, no program to increase employee engagement could be considered a success without hard data to back it up. Yes, IAT began turning an underwriting profit three years ago and has continued to do so, but we wanted more direct proof our initiatives were having an impact on the work culture at our company. So, for the last three years we have commissioned well-known corporate leadership consultant Kevin Kruse to conduct an employee engagement survey. Each year’s results have shown marked improvement.

The 2018 findings are particularly noteworthy:

  • An 87% participation rate
  • Overall engagement score of 4.13 out of 5 (up from 3.87 in 2017)
  • Engaged-to-disengaged ratio of 26:1 (an improvement over 12:1 in 2017). The ratio puts IAT in the top 10% of companies surveyed by Kruse

The metrics are gratifying proof that our collective hard work and the company’s investment of time and money into employee engagement have paid real dividends.

See also: 4 Good Ways to Welcome Employees  

Invest in your employees, and they will pay it back, with interest

Peter Kellogg, our owner, has always said, “Take care of your people, and they will take care of the business.” Any company wanting an edge in today’s competitive marketplace would be wise to take a good, hard look at what it does around employee engagement, and make any and all necessary changes accordingly.

How to Repair Car Insurance Policies

The current system is economically unsustainable and morally unforgivable, requiring cleanup from insurers and better clarity from lawyers.

Car insurance is, to borrow the title of a book by Ralph Nader, unsafe at any speed. It is a gruesome fact, indeed, as the annual number of automotive fatalities is too large to be an abstraction and too sizable to be a purely academic matter. Maybe the reform the insurance industry needs—and the safety every driver deserves—comes from without rather than within; maybe those who advocate safety, and agitate (peacefully) for change, are the very advocates who do this for a living; lawyers who specialize in representing car accident victims. Where there is no room for doubt—where there is no roadway for leeway and no acceptance of maybe as an answer—concerns the status quo. The current system is economically unsustainable and morally unforgivable, a pileup of a disaster that requires cleanup from insurers and better clarity from most lawyers. That is, if we want to lower costs and lessen risk, we must inform drivers of their rights and, pardon the series of automotive metaphors, dissuade insurers from making yet another wrong turn. According to John K. Zaid, a Houston-based lawyer, companies should invite attorneys to speak to their respective workers about car and road safety. Insurers should join this conversation, too, because it is in their interest to make personal safety a professional priority. See also: The Sharing Economy and Auto Insurance   Far from being an adversarial process, these seminars can unite lawyers and insurers. The two share most of, if not all, the same goals—including an emphasis on education, so drivers can be more aware of the dangers they face and automobile manufacturers can produce less dangerous cars, so everyone can profit from fewer risks and more benefits. Lawyers can give voice to these issues—they already do, when entering a courtroom or issuing opening and closing remarks to a jury. They can be, and are, a voice of reason. They nonetheless need insurers to convert these voices into a chorus of rhythm and harmony; in which safety is a universal mission; in which life is too precious a commodity for talk about compromise; in which product liability compromises the health of many and the lives—and livelihoods—of millions; in which the way some corporations do business is an increasingly surefire way for companies to go out of business. Let this chorus be as diverse as possible, resonating in every city, county and state. Let it echo in the corridors of power and reverberate among the powerful. Let it be a call to action by lawyers and insurers alike, because we cannot afford to read more statistics without seeing the faces behind the numbers: young and old, rich and poor, parents and grandparents, friends and neighbors. See also: Beginning of the End for Car Insurance?   We cannot afford a policy of indifference, whose premiums we can neither permit nor attempt to pay. We can, however, save lives through a partnership of protection. We can do so—we must do so—before car accidents become too commonplace to be cause for concern. The consequences are too important to look or feel inconsequential.