Download

How to Approach the Future of Work

The workers’ comp industry must attract and retain top talent while responding to evolving work cultures.

The workplace is evolving, to the point that many people have no actual "place" from which to work. Some do their jobs remotely, while others work from locations such as their cars, if they are part of the gig economy. While we often think about technology and automation as driving influences for the future of work, people are a critical part of the equation. The workers’ compensation industry will be an exciting place to be, as long as we can meet the challenges of attracting and retaining top talent and responding to evolving work cultures. An esteemed panel of workers’ compensation thought leaders were on hand to help us address these issues during our most recent Out Front Ideas with Kimberly and Mark webinar:
  • Lisa Corless, president and CEO of Accident Fund Group
  • Artemis Emslie, founder, AGM Holdings, former CEO, myMtrixx
  • Faith Mason, corporate manager, workers’ compensation, at Comcast NBC Universal
  • Marijo Storment, CEO of Paradigm Complex Care Solutions
Talent Attraction and Retention The workers’ compensation industry is facing high turnover as aging baby boomers set their sights on retirement. Finding people to replace them can be a challenge, especially in our industry, which younger people may view as behind the times. Savvier companies are overcoming this challenge by focusing on technology — not to replace people but to attract those who have spent their lives using it. The "human touch" will always be needed in workers’ compensation to meet the needs of customers, especially cognitive skills. But many repetitive tasks can now be performed through automation, artificial intelligence (AI) and robotics. Successful integration of these newer technologies into our workflows depends on a strong human partnership. Accident Fund Group has addressed the issue by making "People First" one of its strategic pillars. The company strongly promotes a work/life balance and uses this to reach out to younger talent. The company works with colleges and high schools in communities throughout the country to let these students know about the many opportunities. For example, the company shares the ways it uses robots and AI. It has also conducted hackathons around Alexa and other digital assistants. These innovations attract these younger people to our industry, where they later learn of the many areas in which they can work. Reaching out to students is also a good way to attract more nurses, who have become increasingly important in managing workers’ compensation claims but who are in high demand throughout the economy. One speaker said that there will be more jobs for registered nurses as of 2022 than any other profession in the U.S. Many nursing school graduates are not even aware of the opportunities in workers’ compensation. Companies are working with colleges to add courses on case management. Retaining nurses is also vital. The job of a case manager has become more difficult over the years due to the increased severity of claims, privacy and security measures, and the wide variety of service-level agreements. See also: Workers’ Comp Issues to Watch in 2019   Paradigm strives to provide a fun, supportive working environment. Making its workers feel valued through mentoring programs and high-performing support groups is key. The company actually has found that, by treating employees well, they become a primary source of referrals for new workers. A high value on soft skills has changed the way many companies seek talent. Rather than looking for people who have experience in the industry, companies may seek those who are empathetic and highly communicative. As one speaker told us, you can train an adjuster to be proficient in adjudicating a claim, but it is harder to teach soft skills. Training and Development Bringing new hires into an organization with the intent of retaining them for many years involves much more than just training them on certain tasks. It includes integrating them into the culture of the organization so that they truly feel engaged in it. Some refer to this idea as organizational health, meaning the connection and communication felt among workers and their colleagues. Ideally, employees should have their personal and professional goals aligned with the corporate strategy to allow both the employee and the organization to grow and evolve. The process of truly engaging workers begins the first day of employment. Employees need to understand the purpose of the organization and how their contributions fit into the big picture. They need to understand, not only what the expectations of them are, but what they can expect from the organization. That attitude fosters transparency and communication – two very important aspects of a thriving company. One way to develop future leaders is by allowing employees to grow and expand professionally and personally. Sedgwick, for example, has a program where employees can nominate themselves into a leadership program. Those accepted spend one year training in many parts of the organization. They work with mentors and sponsors and receive career coaching. They are exposed to many areas and products so that they are not pegged as specialists focused on only a single area. Part of the training helps them further develop those important soft skills. At the end of the year, they work on some of the company’s largest, complex programs. Workers who deal with customers throughout the day do very well with resilience training. No matter how intrinsically strong someone is, getting yelled at for eight hours a day can take a toll. Companies that want to help their customer service professionals stay with the organization spend resources helping them to better deal with negative experiences. Employee Experience and Engagement Making employees feel supported and engaged with the organization not only helps retain them, it also is important if they become injured. Injured workers who are fully engaged in their recovery and the return-to-work process experience better outcomes and reduced costs for their employers/payers. Using an advocacy-based care model keeps that employee connected and on the right track for a swift recovery. Comcast NBC Universal, for example, has a program that ensures injured workers are supported from the beginning all the way through the recovery – even if their workers’ compensation claim is denied. The company provides resources to assess the worker’s condition and, if it is a mental-mental claim, for example, determines if it is compensable. If it is not, the company sends the employee to short-term disability and provides notice to the vendor to make the process seamless. The idea is for the employee to feel cared for and not experience a major disruption. Comcast NBC Universal calls the approach the "happy path." Making remote workers feel engaged and connected can be a challenge. Paradigm seeks ways to establish constant connections among employees. Through mentoring, highly engaged small groups, an internal newsletter and other programs, the company finds ways to bring workers into the company fold, even if they are not physically together. There is even a software platform where workers can give one another accolades and celebrate birthdays. One aspect of helping employees feel engaged is to ensure they feel safe; that is, safe to make suggestions and provide input that may not be exactly what the "suits" want to hear. Our speakers told us that allowing and encouraging honest feedback helps both the worker and the organization as a whole. Employees can draw attention to processes and tools that may not be working as well as they could. That allows change and evolution to occur. Artemis Emslie related a program that allowed the organization as a whole to set goals and have individuals and teams come up with strategies to affect the goals. Workers, she said, often come up with ideas of one or two things to do differently that will help the company realize its goals. See also: Culture Side of Digital Transformation   Culture We often hear about the culture of an organization. Our speakers described it as something you can feel when you walk into a company. An open, positive culture is one where people are engaged with one another, obviously happy to be there and focused on the customer.. The general feeling is one of an accepting environment. One way to ensure a company’s culture continues to be positive is by focusing on diversity and inclusion. More than an initiative, they are a mindset, a way of thinking and behaving. Studies have repeatedly shown that this mindset results in growth and innovation. While both diversity and inclusion are necessary to improve a company’s culture, they are not the same. Diversity refers to the differences in people – not only gender and race but sexual orientation, a disability, ADHD, diversity of thought – anything that makes one person different from another. The term ”inclusion” refers to creating a safe environment where every person feels honored and appreciated. Some companies foster inclusion by inviting diverse groups of people to meetings, such as high-ranking personnel along with lower-level employees. Each person’s opinions are encouraged and supported. If everyone in a meeting likes a particular idea, the lone person who does not should feel safe to express his or her thoughts without fear. The idea of work/life balance is one aspect of culture that sometimes causes confusion. As Emslie explained, it does not necessarily mean every single day has the exact balance of work and personal activities. Instead, it can be viewed holistically. Ultimately, it means having priorities straight and taking care of both adequately. For more information on this important subject, you can view information from a recent Future of Work event produced by the Alliance of Women in Workers’ Compensation, held adjacent to the 2019 Workers’ Compensation Research Institute’s Annual Conference in Phoenix. Information about the Alliance and notices of its coming events can be found here.

Kimberly George

Profile picture for user KimberlyGeorge

Kimberly George

Kimberly George is a senior vice president, senior healthcare adviser at Sedgwick. She will explore and work to improve Sedgwick’s understanding of how healthcare reform affects its business models and product and service offerings.

3 Keys for Building Women Leaders

To drive innovation, the industry needs to draw on the power of diversity and inclusiveness.

||
As the insurance industry continues to evolve in response to disruption, it’s imperative that insurers embrace innovation to achieve growth and market leadership. The capacity to innovate drives the business models of tomorrow, as well as the investor perceptions of today. Already, ratings agency AM Best has announced plans to score and assess carriers based on their ability to innovate. To truly drive innovation and stay relevant in today’s rapidly changing world, insurance leaders cannot afford to overlook the power of diversity and inclusiveness (D&I) in thinking, experiences, ideas, backgrounds and abilities. Studies show that diverse teams outperform homogeneous teams when led inclusively and that firms deliver better financial results when they have women on their corporate boards and in the C-suite. So, in today’s Transformative Age, why is it taking so long for women to belong equally? To foster an environment for the industry’s future leaders to thrive, it takes effort, backed by accountability and active participation from everyone — not just women. We’ve outlined three ways to build the next generation of women leaders in insurance: 1. Improve recruitment and hiring Today’s college graduates are surrounded by diversity, and they expect to enter workplaces that embody those same values. For the insurance industry to attract new employees who have the creative, technology and customer skills needed to build the insurance workplace of the future, insurance companies must demonstrate their commitment to diversity, as manifested throughout the formal recruitment process, as well as leveraging personal relationships. Insurers should consider how to recruit more women with backgrounds in science, technology, engineering and mathematics (STEM). While actuaries have always needed mathematics and statistics, just about every aspect of insurance is being transformed by digital technologies, artificial intelligence (AI) and other computing-intensive business processes. It is also important that insurers recruit liberal arts majors for areas like underwriting. These graduates possess the necessary skills for sales, relationship management and creation of business solutions. The ability to reason and philosophize will be even more critical in the digital age, as more repetitive tasks shift to AI. See also: Survival Guide for Women in Insurtech   At the same time, insurance companies must drive accountability for D&I initiatives by removing unconscious biases from the recruitment process, recruiting balanced teams and hiring women from diverse backgrounds, skill sets and experiences. A way to enact this is to ensure there are diverse slates of both interviewers and interviewees, as well as holding leadership teams accountable for their team’s D&I profiles. 2. Sponsor and mentor women to support career progression and improve retention Mentors provide advice and counseling throughout one’s career, while sponsors are on-the-job allies who state the case for one’s promotion or participation on a high-profile project. Women joining the insurance field need both mentors and sponsors — and both roles need to be embraced by men and women. Employees may be able to find mentors and sponsors through their own networking efforts, but organizations should also foster connections through team-building workshops and other methods. Executives should be held accountable for their strong commitment to D&I by measuring results, such as the retention levels and career achievements for women and other underrepresented groups within their spheres of influence. Only through metrics-based accountability will D&I achieve a sustainable impact. 3. Clear away barriers preventing the ascent of women executives While progress has been made, women are still severely underrepresented in insurance leadership roles. Although women represent more than half of the insurance workforce, they hold fewer than one-fifth of board seats and only about one-tenth of insider officer positions and top officer positions such as CEO, COO and CFO. Based on this evidence, we can see that the pipeline for women executive talent is being artificially blocked. In response, insurance companies need to work for greater diversity in succession planning and to prepare women for these kinds of roles. To ensure that women can rise on their merits and in accordance with the requirements of the job, succession planning has three key areas for improvement:
  • Preference. Counteract the bias for search teams to promote people who look just like them.
  • Tradition. Break the pattern of hiring leaders with the same background and profile as previous leaders.
  • Requirements. Promote and appoint leaders based on the specific skill sets of what the leadership role requires for the success of the company.
As top executives support and prepare the right individuals for the right roles, more women will rise to the occasion to join the leadership ranks with more opportunities, as well as the knowledge that they are welcome. See also: The Right Way to Tackle Gender Bias   D&I is critical for driving innovation and a competitive advantage for insurers in today’s transformative age. By welcoming a wider range of skills and viewpoints, D&I represents an essential component of the evolving business model in insurance. As part of their broader D&I initiatives, insurance companies must take steps to improve gender parity. Starting from the top, business leaders throughout the insurance organization should be held accountable for recruiting and hiring women, sponsoring and mentoring women, retaining and promoting women and clearing away obstacles to leadership roles. Yet D&I is not just a matter for top executives. We all have to ask ourselves: “Who am I mentoring? Who am I sponsoring? Who am I pulling up?” Answers to those questions will become increasingly important for the success of individuals, teams and organizations throughout the insurance ecosystem. By thinking, challenging and engaging differently, we can build a better working world where women belong as much as men do. What actions will you take to make sure that #SheBelongs? The views reflected in this article are those of the authors and do not necessarily reflect the views of Ernst & Young LLP or other members of the global EY organization.

Gail McGiffin

Profile picture for user GailMcgiffin

Gail McGiffin

Gail McGiffin is a principal in EY’s insurance practice and leads the underwriting, product, policy and billing offerings. Prior to joining EY, McGiffin was the chief information officer at ProSight Specialty Insurance.

Maybe the Innovation Glass is Half Full?

sixthings

After attending the OnRamp conference in Minneapolis last week, I come away more optimistic about innovation in insurance than I've been in some time. 

That feeling began with the keynote panel I moderated with Allianz Life CEO Walter White and Securian Financial CEO Chris Hilger, who laid out a compelling vision. Rather than thinking about using technology to automate jobs or cut expenses, they see ways to make their financial advisers better, more-informed coaches. They also envision extending the benefits of the advice to those many who otherwise couldn't afford financial counsel, because the high cost structure makes fees prohibitive. (At ITL, we use the word "centaur" to describe employees who, like the mythical creatures, have combined with machines to be more powerful than people alone would be.)

A later panel laid out a new vision of segmentation. While the traditional focus has been on defining segments for marketing purposes, panelists recommended using the techniques to categorize people for different customer experiences. At the moment, companies strain to win customers by demonstrating great understanding of their situations and needs, then do one of two things: 1) dump them into a generic onboarding process that immediately undercuts any claims of trust; or 2) strive (and fail) to deliver a unique experience for each person. Sophisticated segmentation of customers could deliver considerable personalization of the customer journey at a reasonable cost. 

(ITL CEO Wayne Allen contributes a related thought from the Sitkins Network conference where he spoke last week. He said the suggestion was to move away from thinking about customer-centricity and toward empathy. In other words, don't just make the customer the center of your efforts; do everything you can to put yourself in that customer's shoes and understand what he or she feels, then do what the customer—not the company—needs.) 

Still another OnRamp panelist described an opportunity with micro businesses—ones that range from a sole proprietor up to four employees. While many have seen potential in small and medium-sized businesses, I hadn't yet heard such a clear argument for products and services that can be provided digitally, at low cost, with little friction, while fitting in with personal financial services that the buyer wants and may already receive.

The array of clever ideas behind some startups also struck me. For instance, while I've been hearing about telematics in cars for decades, I'd never thought about motorcycles until Marina Mann introduced herself and her company, EatSleepRide. She has tracked 20 million kilometers of motorcycle rides and is rolling out services that not only rate the risk of the rider but offer real-time advice to the rider about signs of fatigue, dangers that may lie ahead, etc. 

There was even a startup, Owl Cam, that may let me resolve a pet peeve that has been bugging me for the, oh, 45 years I've been driving. 

The background: I often offer a running commentary about other drivers, a habit I picked up from my father and, sorry to say, seem to have passed on to my daughters. I get especially annoyed when someone tailgates me in the left lane even though traffic in front of me means I have nowhere to go—these geniuses seem to think they can push safe drivers out of the way by creating dangerous situations—but I'll also complain if someone cuts me off, if someone seems to think he's playing Fast and Furious, etc. I've always wanted some way to document the crazy driving to help get idiots off the road (and, yeah, vent my spleen a bit) but never had the means. Until now.

Owl Cam sets up a two-way camera on the dashboard that captures both the interior and the road. The main purposes are to record a thief, a vandal or a car that hits yours while you're not in it, and to help resolve claims quickly if you're in an accident. But the feature that I covet is the one that lets you keep the past 10 seconds from the forward-facing camera by just saying, "Hey, presto." Now, if the police set up some way for concerned citizens to share video, and if Owl Cam figures out some way to capture the license plates of those tailgaters, we'll be in business. 

This insurance innovation thing may have a future!

Cheers,

Paul Carroll
Editor in Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Growing Demand for Digital Self-Service

Knowing which technologies to use and how to use them will improve customer satisfaction, retention and growth.

|||||
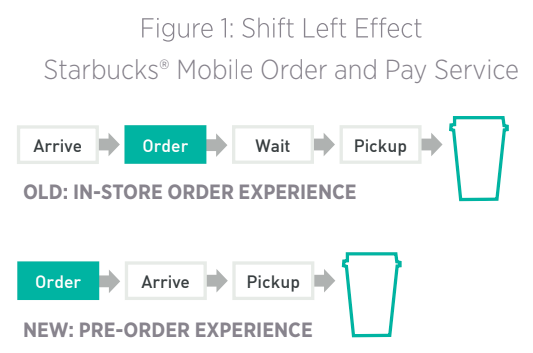
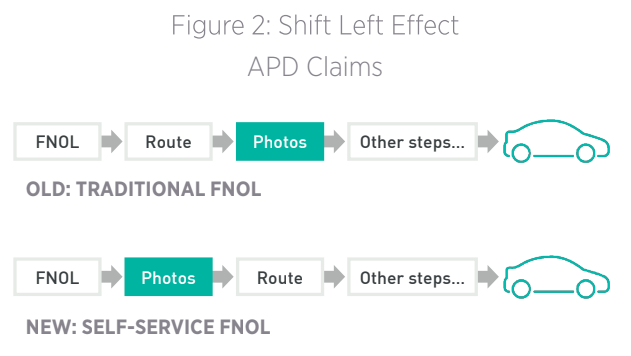
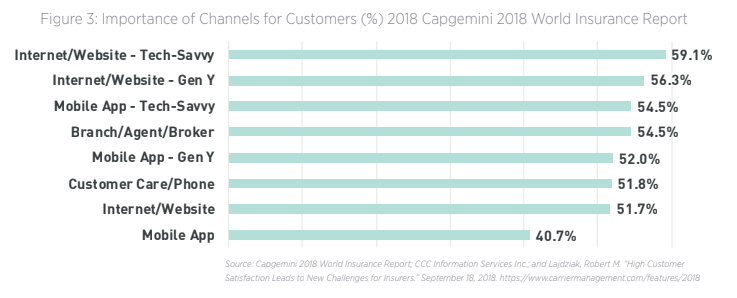
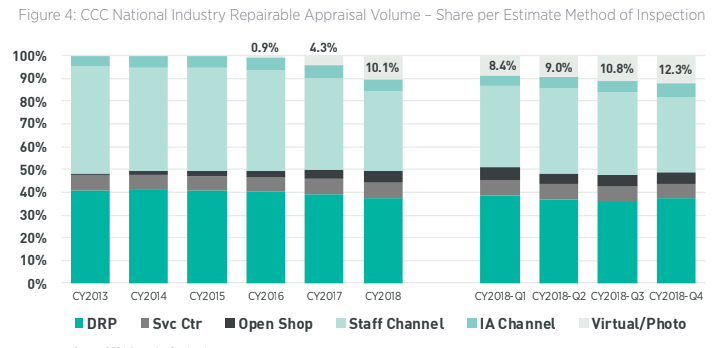
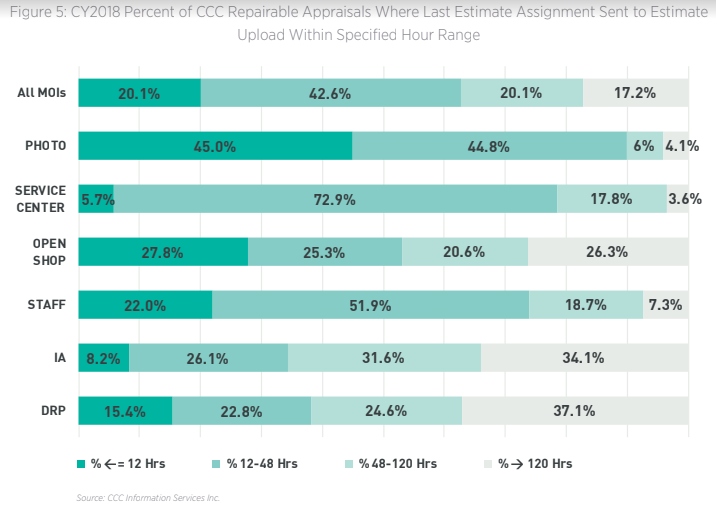
Technology is bringing change to nearly every part of our lives. Platforms like Amazon have created expectations among consumers that they shouldn’t have to send the same information to multiple parties across different methods – digital and mobile technology should make the process seamless and should be personalized. And, companies like Starbucks have innovated their business processes through a Left Shift (see Figure 1 below), creating more choice and loyalty, better cycle time and ability to know more about their customers through their digital engagements. For our industry this personalization, convenience and level of service have become expected by consumers, regardless of who they are insured with, what vehicle they drive and what the characteristics of their accident were. Through new capabilities such as self-service claims, the consumer no longer waits days for an estimator to take photos; the extent of damage is knowable at first notice of loss (FNOL), and vehicle damage photos facilitate speedier decisions to be made about the claim (see Figure 2). Customer retention is a huge benefit gained from improving digital channel experiences, yet there are additional benefits that help insurance carriers with their loss adjustment expenses (see Figure 3). For example, the J.D. Power 2017 Auto Insurance Study found that customers who set up an account online with their insurer are two times as likely to submit incident photos through an app and receive digital updates and three times more likely to report first notice of loss online. However, the overall percent of customers willing to report their first notice of loss is low, with 9% in J.D. Power’s 2017 survey growing only to 11% in their 2018 survey. But the same survey data also showed 65% of customers received digital status updates for an auto claim, and 42% submitted their own photos. See also: Transforming Claims for the Digital Era   Virtual auto claims handling via integrated smartphone technology has emerged as a key competency that consumers not only want and expect, but the technology also removes significant cost from the claims process by “…essentially eliminating the first half of the work. [The insurer doesn’t] have to get the car to the human or the human to the car.” Analysis of vehicle appraisals generated annually shows a shift among insurance carriers and their customers to new and different methods of vehicle inspection such as virtual or photo inspections and away from insurance staff appraisers inspecting the vehicle in the field or in a drive-in facility (see Figure 4). A comparison of claim cycle times reveals the number of days from the last estimate assignment to the date the initial estimate of record is completed is lowest for those appraisals with a photo estimate method of inspection, and photo inspections have the highest percent of appraisals where the last estimate assignment to date of estimate complete is less than or equal to 12 hours (see Figure 5). The streamlined appraisal process also sets the stage for a streamlined repair process – where within the same app the customer can view the estimate of record produced from the vehicle photos, then choose a repair facility to fix the vehicle and even schedule the appointment with that shop. Photo estimating coupled with online claims communication and scheduling saves consumers time they may traditionally have spent driving around to multiple shops to get estimates or waiting for an insurance adjuster to show up at their home or work, ultimately ending up with a paper copy of the estimate and maybe a check, only to then have to decide where to get the car repaired and schedule the repair. With online shop scheduling available as a "next step," the customer can select the repairer based on proximity, DRP program participation, on-line reviews, customer referrals or availability of OE certification, essentially enabling the overall experience to occur on a single platform in a personalized manner – not too different from what consumers experience on Amazon today. Insurance companies and repairers that adopt a single platform can enable consumers to efficiently process their claim, schedule the repair and ultimately deliver an experience more in-line with modern expectations. Self-service claims and repair scheduling capabilities via digital devices are just two examples of how our industry is using technology to "shift-left" – providing customers with enhanced self-service capabilities via technology that ensures the same or better customer service and engagement. See also: Survival of the Fittest in the Digital Age   Technology such as mobile, AI and IOT will increasingly play a key role in a company’s ability to quickly assess and respond to consumer feedback and other information on market conditions. Knowing which technologies to use and knowing how to use them to cater the claims and vehicle repair experience to each distinct customer will lead to higher customer satisfaction, retention and growth.

Susanna Gotsch

Profile picture for user SusannaGotsch

Susanna Gotsch

Susanna Gotsch is director, industry analyst at CCC Intelligent Solutions. She has been with CCC since July 1992. Gotsch brings 20-plus years of experience within the automotive claims industry.

Role of Unstructured Data in AI

Unstructured data will not only improve accuracy but achieve fundamentally new ways of thinking, communicating and using information.

The process of making artificial intelligence (AI) systems interact more like humans makes some people uncomfortable, but AI is not about replacing humans. In reality, it is much more about removing the robot from humans. A big part of AI’s value lies in automating manual processes and analyzing vast amounts of data quickly so that humans are free to accomplish higher-order tasks that require reason and judgment. To get to this point, however, AI systems must be able to communicate with users and analyze natural forms of data (aka unstructured data) — all of the free-flowing stuff that is unable to be packaged in a neat way, things like voice, images and text. Unstructured data is vital to the development of an AI system. The better an AI system communicates with users, the more it can learn on its own and, therefore, the more efficient it will be. This is important because if an AI system requires a user to interact only in a structured format, its components are dramatically limited. For AI to be successful, it has to make sense out of messy information. In this context, let’s dive deeper into how unstructured data comes into play. The Challenges of Unstructured Data In the human world, you and I do not speak by protocol when we carry on a conversation. We say whatever pops into our heads, in some configuration that may or may not follow convention. We use slang, incorporate sarcasm and crack jokes. It is not natural for us to organize our everyday language and the information we wish to convey into neat columns and rows. Speech is natively unstructured. If you’ve ever interacted with Amazon’s Alexa, you know that, while the Echo system has generally become quite proficient at understanding free-form commands, the lack of a defined protocol can sometimes cause problems — or at least humorous responses when Alexa attempts to answer queries that don’t fit the mold. Amazon has poured massive resources and millions of dollars into creating and perpetually refining the algorithms that enable this humanlike voice to respond to commands, but, as adept as Echo has become at deciphering free-flowing language, Alexa still has flaws. See also: 5 Key Effects From AI and Data Science   The Alexa example highlights the complexity of one type of unstructured data. An AI system’s ability to process and create a numerical equivalent to text is also a tall order, especially when you consider nuance and the importance of context. And imagine a machine trying to “understand” what is happening in that picture from your family vacation or an image in an art history textbook covering Impressionism. The complications associated with processing unstructured data are perhaps the biggest obstacles for AI in the enterprise. Yet, they are not insurmountable. The Importance of Expertise Unstructured data is inherently noisy. As such, it requires substantial expertise to cut through and tease out patterns, then develop models that recognize those patterns. Data scientists are pushing aggressively to improve AI systems, and the biggest successes underscore that human instinct and experience are required. This usually happens when a team is focused on a very narrow application of AI. Let’s look at the workers’ compensation claims process as an example. Teams of data scientists with a deep knowledge of claims can create predictive models based on key indicators they spot. They incorporate unstructured data such as diagnostics, drug information and claim notes. In doing so, the AI system assesses early indicators and determines that a certain claim might be denied. It can then provide an alert to users. A claims representative can figure out how to intervene and give a particular claim more care to prevent the claimant’s attorney from getting involved (typically, denied claims wind up involving an attorney, which gets very expensive and takes a long time to resolve). In this case, it is easy to see how the AI system provides assistance to its users, and there is also a tremendous boost in accuracy when that unstructured data is incorporated versus relying on structural data alone. There is a gold mine of information and insight in the unstructured data (e.g., information about comorbidities) that just doesn’t find its way into structured data consistently. With each additional piece of information, the AI system gets smarter, and results improve. This translates to greater efficiency and lower claims costs. This is just one example of one benefit from incorporating unstructured data into an enterprise AI system. It takes time and diligence to crack the code, but the payoff is gaining a level of insight that has never been possible before — and getting it in a matter of minutes or hours compared with days or weeks. Unstructured Data Is the Key Every AI system needs to interact with users in a natural way. Organizations must have a sharp focus on this. In fact, there is a huge gap in a company’s offering if unstructured data analysis is not part of the road map. See also: Next Step: Merging Big Data and AI   While unstructured data is challenging, Amazon, Google, Apple and others have opened a lot of opportunities for AI applications. We can take these advances and apply them to enterprise applications where they have an enormous impact. By taking the time to apply expertise and sound data science, we can make breakthroughs. We will not only improve accuracy in data analysis through unstructured data but also achieve fundamentally new ways of thinking, communicating and utilizing information in the future. As first published in The Innovation Enterprise.

Road to Success for P&C Insurers

To get on a path toward digital prominence, insurers need a strategy that ties legacy systems into future-proof distribution.

||
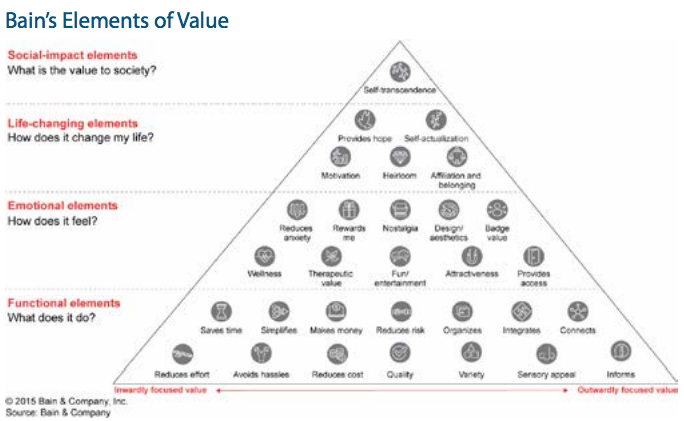
Digital transformation initiatives have become an imperative for businesses in the modern age, but many organizations struggle to reach their objectives. Based on a survey of 200 respondents (the majority in the financial services field) conducted by IDG Research Services, more than half of organizations have been forced to pause or completely abandon digital transformation projects. Where the insurance industry is concerned, the struggle is real. Friss, a risk assessment and detection services provider, discovered that only 69% of insurers offer some form of online distribution. On the surface, it appears that the industry is moving in the right direction, with more than half of insurers on the digital track. However, this number has risen only 4% since 2016, even though as many as 80% of consumers use digital channels during the purchasing process, according to some research. Survey findings indicate a strong disconnect between insurer expectations and objectives. In 2016, 25% of insurers that had not introduced online distribution expected to do so within a year. Had they been successful, the current number of online insurers would now be around 75%. Currently, only 69% of insurers report offering some form of digital distribution. Through its research, IDG discovered that organizations stall or fall short because they have failed to lay the groundwork for successful transitions. Sixty-two percent have not documented or communicated their plans across the organization, and 64% have no plan for dealing with outdated or legacy technology. To put the insurance industry on a contemporary path toward digital prominence, insurers need to plan for the obstacles they face and implement a strategy that ties legacy systems into future-proof distribution designed to reduce internal costs and meet the needs of consumers. Understanding Digital Transformation Opportunities and Challenges According to Forrester, implementing digital technology “dramatically alters the balance of power between customers and companies.” Customers gain the upper hand with better information and choice, but insurers succeed by lowering the cost of doing business. Digital leaders find it a factor of 10 cheaper and faster to engage customers and provide them with an experience that meets their rising expectations than those relying on traditional practices. Considering the benefits, digital transformation tops the agendas of many executives, but businesses across the board find it difficult and costly to modernize their operations. In IDG’s research, 64% of companies cited legacy technology as a top transformational impediment, followed closely by technology silos (59%) and cost (50%). At least half don’t know where to start. It’s interesting to note that businesses in general experience many of the same top challenges as insurers when it comes to digital transformations. Often, policy administration is handled in silos operating on outdated technology stacks. With so much data at stake, it’s difficult to create a plan of attack for uniting back-end systems. However, it’s a situation where the effort is worth the price. Bain prioritized 30 fundamental values that, when in place, can elevate the customer experience and push insurance products above the commodity status. Values were divided into four categories: social impact, life-changing, emotional and functional. Each category is defined by consumer needs, such as “saves time,” “reduces anxiety” and “avoids hassles.” Insurers that rank high in more elements of value achieve higher Net Promoter scores and realize above-average growth, according to Bain. To excel in these categories, however, insurers need to establish relationships with customers. According to Bain, staying in frequent contact, digitizing purchasing and servicing and offering ancillary services are the primary components of an insurer’s relationship-building strategy. However, legacy technology and product silos impede insurers’ ability to swiftly react to customer inquiries and issues. Accessing the necessary information is often limited or time-consuming, and, when it comes to offering additional products or services, insurers are unable to extract the necessary insights quickly enough to make real-time product recommendations a reality. Beyond technology considerations, 62% of organizations have failed to lay a solid foundation for transformation by establishing a plan and effectively communicating it to relevant stakeholders. Planning and communication become necessary in light of the impact digitization has on the organization, particularly where resource management is concerned. As insurers engage in digital transformations, processes within the organization change, affecting job functions and the people who perform them. McKinsey says that up to 25% of current business processes could be automated, resulting in the consolidation or elimination of up to 25% of full-time positions. See also: Culture Side of Digital Transformation   Technology and automation also open doors to new roles and occupations. McKinsey points out that 25 years ago jobs in areas such as IT development, hardware manufacturing and app creation did not exist. Just as new employment opportunities arose out of the technology revolution, automation will generate demands for new skills, creating job roles in insurance that we can’t imagine today. Part of a successful transition is understanding what processes will change and how those changes will affect existing roles across the organization. Envisioning new roles at the beginning allows insurers to identify existing talent that can be upskilled or reskilled to fill new vacancies. Making for Successful Digital Transformations At the heart of successful digital transformations is a focus on the customer. Digital leaders understand this, with 92% reporting that customer experience is central to their strategy. Digital leaders, such as Amazon, become industry giants because they can tie revenue outcomes to specific measures of customer satisfaction and tweak or completely revolutionize their business approach accordingly. According to Forrester, digital leaders succeed by adhering to four basic principles: A customer focus during digital transformations ensures that outcomes meet the intended objectives. Insurers can plan from the outset to build the necessary speed and efficiency into digital channels while ensuring cross-functional capabilities. A recent consumer study conducted by Facebook and comScore revealed that the typical insurance-buying journey is short. Thirty percent of consumers made a decision within a day, while the same number took less than a week to select their insurer. That gives insurers a short window of opportunity to engage with consumers and secure their business. According to J.D. Power, a preference for digital interactions is on the rise. In their surveys, over 60% of consumers use online channels when researching insurers, but only 42% use these channels to purchase. Pitted against consumer expectations shaped by the Amazon experience, too many insurers fail in speed, efficiency and convenience, J.D. Power says, forcing consumers to seek out more digitally proficient insurers or to switch to other channels when purchasing coverage. Filling the Gap with Digital Transformations When it comes to improving the customer experience, insurers are filling the gap between expectations and reality by ramping up their digital capabilities. In a recent survey of industry executives conducted by SAP, 85% were prioritizing the development of digital and mobile channels. Findings like these indicate that insurers understand the need for digital engagement. However, there is no indication that insurers have conquered the impediments to creating an efficient omni-channel environment. To do so, they need to unite back-end systems to obtain a complete view of the customer, including every policy on record, as well as consumer data and related insights. With legacy technology and siloed systems at the top of executive concerns, it’s no wonder that business leaders are partnering when it comes to gaining digital capabilities. Respondents to the IDG study expect more than 1/3 of their transformation initiatives to be handled by a third party. This approach is particularly applicable to the insurance industry where overhauling systems is risky and problematic. “In a time of disruption, the smartest insurers recognize they can’t do everything on their own. They’re teaming up with insurtechs and other companies to modernize their operations, from distribution to claims processing,” said Dr. Henrik Naujoks, head of Bain & Co.’s financial services practice in Europe, the Middle East and Africa. Integrating third-party solutions with existing technology puts insurers on the digital fast track without the worry of disrupting data held in traditional systems. According to Rick Huckstep, chairman, Digital Insurer, the insurer’s existing system becomes the system of record, while digital distribution platforms supply the digital front end. In the process, back-end systems are connected through a single point of access, providing clear visibility across policies to all channels. This capability is necessary to ensure an efficient omni-channel experience for the customer. By connecting all policy silos, agents and customers are able to quote, issue and bind multiple policies from a single application. Through automation, the process is completed in minutes, ensuring that insurers capture customer purchasing intentions at the moment they are ready to buy. See also: Future of Digital Transformation   Digital distribution platforms also simplify the approach to ecosystem environments, providing insurers with a ready platform for connecting with ancillary service providers or other insurers. Bain’s in-depth consumer research reveals that digital leaders are excelling with three main capabilities. These core components of a leading digital strategy are all easily addressed with the application of a digital distribution platform: Core Business High-quality products are delivered at competitive prices. Customer experiences are simple and digital. How a Digital Distribution Platform Helps: Automating much of the quote-to-issue lifecycle reduces insurer costs and provides an ecosystem environment where insurers can connect with other insurance companies. By using products from other insurers to meet price points or when there is no appetite for the risk, insurers can always fulfill the needs of their customers. Going Beyond Insurance Insurers foster engagement and a sense of affiliation by offering ecosystem services from third-party providers. How a Digital Distribution Platform Helps: Outside vendors can be connected to digital distribution platforms, allowing customers to move freely from the insurer’s website to third-party applications. Customers can simply and easily take advantage of ancillary services right from the insurer’s website. Prioritize Innovation Insurers understand the urgency behind digital initiatives and push for speedy digital transformations. How a Digital Distribution Platform Helps: Digital distribution platforms provide insurers with a complete digital environment, from online storefront through back-end integration, in a matter of weeks. Connecting with digital distribution platforms drastically improves the odds of transformation success. Aside from implementation simplicity, insurers gain the benefit of expertise. Platform providers are well-versed in the impacts that transforming to digital distribution have across the organization and are equipped to lead insurers through the process. They advise on staff changes and have resources on hand to fill talent gaps, thereby increasing the odds of success.

Tom Hammond

Profile picture for user TomHammond

Tom Hammond

Tom Hammond is the chief strategy officer at Confie. He was previously the president of U.S. operations at Bolt Solutions. 

Musings on the Future of Driverless Vehicles

What might a future world look like where all transportation is via autonomous vehicles? Here are 10 possibilities.

What might a future world look like where all transportation is via autonomous vehicles? Although we might be decades away from this vision, there are useful insights to be gained for today’s strategies in thinking through the possibilities. While I don’t personally own a crystal ball, this blog floats some ideas regarding what the future may hold. In the meantime, SMA’s recent research report, Connected Vehicles and Insurance: Ten Strategic Considerations, provides some practical advice for insurance strategists today by identifying the potential value levers in the evolving connected vehicle area and exploring 10 strategic questions. See also: Rapid Evolution of Autonomous Vehicles   With that as background, here are 10 predictions for the future of transportation:
  1. Vehicle ownership by individuals will be so rare that people will need to visit theme parks for the “experience” of driving a car.
  2. People will be able to summon autonomous vehicles on demand for travel anywhere on the planet.
  3. Autonomous vehicles will be everywhere on land, on sea, in the air and underground – none will require drivers or operators. (For example, drone taxis will fill the skies.)
  4. Travel times will be significantly reduced as speed limits increase and high-speed transportation dominates. Very high-speed travel will be common via Hyperloop, supersonic aircraft or high-speed rail.
  5. The physical infrastructure for travel will be substantially different: no signs, no traffic controls and no fuel stations. The whole system of roadways will be transformed, with no need for median strips, lane markers, etc.
  6. All land-based vehicles will be powered by electricity and recharged directly from the road surface.
  7. The urban/suburban balance will change once again, with a concentration of individuals in mega-smart cities combined with new forms of living spaces and communities in rural/satellite areas. (Think about what could be done with all the garage space in residences when individuals do not own cars.)
  8. Vehicles of all types will be real-time, information-rich machines with augmented reality, virtual reality and instant access to information/entertainment content.
  9. Vehicular accidents will be virtually eliminated, but, when accidents do occur, they will be mega-accidents. (Imagine a software glitch or a freeway hack that causes pileups of hundreds of vehicles.)
  10. The variety of vehicles for transporting both people and goods will be astonishing, ranging from individual travel pods to gigantic vehicles transporting thousands of people at a time.
See also: Driverless Vehicles: Brace for Impact   Also not to be forgotten is the complete reshaping of the industries that build vehicles, sell and service them and, of course, insure them. The journey to this future (or something like it) is highly uncertain in terms of timing and eventual outcomes; however, there is little debate that we are in the beginning of monumental transformation.

Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.

Clarity of History Can Reduce Cyber Risk

Cyber liability and technology E&O insurers are not only giving hackers the upper hand but are endangering their own existence.

Indemnity, through the use of insurance, has a long pedigree. However, insurance as we know it today did not really start until the end of the 17th century. It was at that point that insurance companies started to be formed to combat one of the oldest enemies of civilization: untamed fire. Moreover, fire insurance companies understood their enemy well and worked swiftly to combat it; those efforts ultimately gave rise to our present day in which millions of people around the world live largely free from the threat of a fire destroying a neighborhood or city. That pedigree sired all the forms of insurance that we know today, whether it be general liability or cyber liability. However, the landscape, as it relates to cyber liability and technology E&O, does not show the responsible insurance traits that such thorough breeding would be expected to produce, and we need to review three prominent examples of where cyber liability and technology E&O insurers are not only giving their enemy, hackers, the upper hand but are also endangering their own existence. Perhaps one of the most recent blatant examples of how insurers are failing their lineal forebearers occurred toward the end of 2018 when an insurer created a partnership with one of the world’s largest e-commerce merchants to provide physical cyber tools to policyholders to help “protect” homes. All the available evidence suggests that the cyber tools were championed by the insurer without the organization having done considerable research on, and testing, the physical devices to ensure that they were highly resistant to being hacked. None of the products the insurer recommended were rated as “secure” by any respected independent testing lab. In fact, none of the products were rated “secure” on the manufacturer’s website. For a cyber liability insurer that also offers homeowners and renters insurance, the championing of such products directly undermined the insurer’s cybersecurity credibility and sullied its pedigree, all for marginally increasing its bottom line. See also: Breaking Down Silos on Cyber Risk   Another timely and alarming example of an unfortunate mistake of cyber liability insurers is the recent creation of the Global Cyber Alliance and the Cybersecurity Tech Accord. The effort of both is to create a cooperative atmosphere in the private sector to combat cybersecurity threats while also working to provide responsible cyber products. There are many respectable companies that belong to each organization, but not one cyber liability or technology E&O insurer can be found among the members of either organization. When we read in the news that company ABC suffered a $40 million data breach, that means, assuming the organization had a cyber liability policy, that millions of dollars are being lost by the cyber liability insurer. Due to the current and highly competitive cyber market, the premiums of cyber liability policies are not typically commensurate with the amount of risk and financial loss to appropriately offset the millions of dollars the insurers pay out in such a breach. Thus, insurers mistakenly are not advocating or supporting the very organizations, like the Cyber Tech Accord, that are indirectly trying to help them reduce their losses and those of their clients. Illustrative of a mistake by cyber liability insurers in this matter is something that insurers say. It is not uncommon to read in a cyber liability brochure that the insurer is not going to restore a client to a better state than the one the policyholder had prior to a cyber breach. On its face, the logic is reasonable and even is in the pedigree of fire insurance companies. After all, fire insurance companies would not build a person a five-bedroom, four-bath home with a four-car garage when a person’s two-bedroom, one-bath home with no garage burned down. However, fire insurance also followed the principle of indemnity, and that principle clearly states that an insured is to be restored to her original condition after a fire. Cyber liability insurance policies DO NOT FOLLOW the principle of indemnity, and that distinction matters considerably. There is no reasonable way to calculate how much a cyber liability breach will cost an insured or her cyber liability insurer. After all, laws across the U.S., let alone the world, vary in their intent and letter as to what needs to be done after a cyber breach. Not only that, but the size of a company, how a company was breached, when it was breached, what was stolen, if anything, what was done with what was stolen and a number of other important factors inextricably but subjectively determine the impact a breach will have on a client. That those factors are subjective in their cost means that all insurers have no accurate way of determining the cost of a breach. When a $500,000 home burned down, an insurer could reasonably expect the cost of replacing that home to be within a certain percentage of $500,000. When a major retailer suffered a cyber breach in 2013, the annual report the following year specifically stated that it did not know what the true cost of the breach would be, but it was expecting the cost to increase beyond the initial amount. If such a policyholder was unable to determine the true cost of the breach, then how could the insurers of its cyber liability policy know, either? One of the major tools that fire insurance companies used in the past to combat fires was to understand how susceptible a building material was to being damaged by fires. However, to this date cyber liability insurers have not founded an institute funded by themselves and created for the express purpose of determining the quality of products that have a direct impact on policyholders' ability to resist attack. This in turn creates an inextricable link to a policyholder’s sense of cyber security safety. Cyber liability organizations sometimes use the services of a cybersecurity firm to determine, prior to underwriting a policy, if an applicant’s network exhibits any signs of unusual network activity that could be suggestive of a cyber breach. However, that is an inadequate way of providing a policyholder with any meaningful comfort, let alone allowing an insurer to have a solid basis to believe a risk is worth underwriting. In fact, the closest organizations that exist for the express purpose of determining a product’s cybersecurity strength is Cyber ITL (Independent Testing Lab) and the NIST (National Institute of Standards and Technology). However, neither of those firms was created by insurance companies, and neither has the vested interest that insurers have in protecting their policyholders and guaranteeing cyber liability remains profitable to underwrite. Therefore, it is time for all cyber liability insurers to either join with an organization like Cyber ITL or to create their own like-kind organization. The browser application, the version number of a browser application, what operating system is used, what kind of router a computer is connected to, what kind of firewall is in place and numerous other factors all play a part in increasing or decreasing the strength of users’ cybersecurity. However, until cyber liability insurers measure and rate everything that pertains to cybersecurity, they and a vast majority of their clients will be allowing hackers to gain an undeserved advantage. Beyond the need for an independent testing lab there are other measures that insurers need to take, and these measures have been previously proposed. However, it is extremely unfortunate that insurers have yet to rally to the cause of their clientele by implementing the following strategies. In the April 2016 edition of the PLUS Journal, it was argued that insurers need to work with other companies involved in technology, marketing, lending and other parts of the private sector to create an international competition. This competition would give students a creative outlet to display their skills, whether they be in coding, design or writing. By establishing such a competition and working with educators, worldwide insurers and other companies can give pre-college students the ability to demonstrate, on a world stage, the ingenuity and adaptive reasoning that bright young people often possess. However, the benefit of the competition is not only for the students; it absolutely benefits the corporate sponsors of the international competition. For insurers, it allows them to persuade students that the insurance realm is a viable and worthwhile place in which to work. It also allows insurers to gain the opportunity to create a list of candidates from which to recruit when the winners of the international competition graduate from university. The same list of students that insurers create can also be used for their clients when they need to hire a software engineer or a laureate. If insurers have some of the brightest and most talented young people working for them, they can create more efficient internal systems and more advanced lines of insurance coverage, and they can also provide better methods for ensuring that their policyholders have the right tools with which to mitigate cybersecurity risk. Additionally, it is not profitable or reasonable to believe that cyber liability follows the principle of indemnity, because believing that hurts the insurer and, to a greater extent, the insured. If an insured uses the same computer, router, browser and other items after a breach has been fixed that were used prior to the breach, then there is nothing to stop another breach from occurring. In the near term, to reduce the number of clients suffering recurring breaches, an insurer should pay for one year of monitoring by a respectable cybersecurity firm. It would also be useful to conduct an on-site visit by an auditor three to six months after the original breach has been fixed to see what steps the insured has taken to prevent future ones. In time, if an independent testing lab is established, an insurer could even offer a policyholder an improved router and firewall to further protect the client. The less susceptible any client is to an attack, the less likely a claim will arise, and fewer claims means more underwriting profit. See also: How Insurtech Boosts Cyber Risk   However, technology E&O insurers also bear a responsibility for helping to prevent cyber breaches. After all, how well a software engineer or an electrical engineer professional writes software code or builds physical products is the basic element that will later determine, to a high degree, whether a breach occurs or not. Technology E&O insurers need to work with universities to establish teaching standards that are uniform across the globe and engineering standards in the work place that establish the highest minimum standard possible. In the January 2016 edition of the PLUS Journal, it was also demonstrated that technology E&O policies can be written to encourage more responsible software engineering practices to further minimize claims. If the above practices are put into place, then perhaps lives lost to faulty software, like those in the recent two plane crashes of a U.S.-based commercial jet manufacturer, need not happen in the future. The closest fire insurance companies had to a dynamic enemy were arsonists who were few and far between. Despite the general absence of an active enemy, those organizations spent about 200 years directly influencing the development of urban landscapes whether through building codes or the layout of a city. Today, their efforts have largely paid off because they acknowledged the challenges they faced and met them with courage and creativity. They did not accept that they could do nothing to make their clients safe or secure their profitability. However, today beyond a few web portals that insurers or third parties have created that can provide minor tools to a policyholder, and beyond creating semi-close relationships with some members of the cybersecurity community, cyber liability and technology E&O insurers have spent a significant part of the 21st century accepting losses, writing checks and never acknowledging that hackers and poorly crafted technology products are their mortal enemies. Hackers are costing the global economy tens of billions of dollars, if not more, every year, and businesses are closing or suffering severe financial loss because of cyber breaches. How many more people must die and how much insecurity must exist in this world before insurers acknowledge that the war is here, and the enemy is at the doors of organized civilized societies? When will insurers take the prudent course and glean from history and their forebearers all the lessons they offer, and in so doing prove that they are worthy of their trust?

Jesse Lyon

Profile picture for user JesseLyon

Jesse Lyon

Jesse Lyon works in financial fields that involve retail banking, residential property valuation and professional insurance. He is deeply interested in the fields of cyber liability and technology E&O, and his research has led to four published papers on those topics in the U.S. and the U.K.

Future of Claims: Automation, Empathy

Recent research shows that auto insurance carriers are succeeding in striking a balance between empathy and automation in claims.

The advance of automation in the auto insurance industry could have come at the expense of the personal touch that consumers expect. But recent research shows that auto insurance carriers are succeeding in striking a balance. A 2018 survey of 24 of the top senior-level auto insurance executives combined with 1,755 auto insurance customers by LexisNexis Risk Solutions found that carriers are increasingly using automation to be more efficient, reduce costs and improve their competitive edge through better customer service. Consumers are enjoying the gains of automation, as well. They now expect the carriers they do business with to offer easy digital access to products and services, but while also providing a personal touch, including being empathetic. Much innovation is taking place across the claims automation continuum – from traditional to touchless handling. For example, the research found that carriers are:
  • Continuing to embrace virtual claims options with 95% of respondents using or considering virtual claims processes.
  • Touchless claims is growing in popularity as well, with 79% of carriers surveyed saying they are considering or are open to the idea.
  • And carriers already using claims automation are reporting a reduction in touches, faster cycle times, increased employee productivity, lower loss adjustment expense (LAE) and higher customer satisfaction.
On the consumer side:
  • 57% of consumers indicate they are fairly or very comfortable with automated processes.
  • Customers with prior claim experience quickly become dissatisfied when they have to talk with more than one person.
  • One in five consumers prefers claim self-service options, mostly driven by the younger generations, but complain that the self-service first notice of loss (FNOL) process asks too many questions.
  • Customers prefer fewer touches and expect fast cycle times, as they have become accustomed to the speed of digital service in other industries.
  • Even the consumers who are the most supportive of automated processes still want a personal touch when they need it (for example, first-time claimants).
See also: 21st Century Claims: Boosting Efficiency   These findings suggest that carriers need to carefully align their automation strategies with customers’ needs. Automation adoption can be accelerated by matching data and technology solutions to consumer needs and sharing information with consumers. Done correctly, carriers can extend automation for greater mutual benefit ― as long as they maintain an empathic, personal touch with their customers through the communication method of their customers’ choosing. Yet, while many carriers said their automated processes have increased significantly over the past three to five years, that doesn’t mean they’re using a broader array of automation. Rather, it’s most common to see automation in the form of rules-based logic and software-driven photo estimation for non-complex claims at specific parts of the claims process. For example, some carriers are employing automation to simplify and accelerate documentation gathering, enabling customers to upload digital documents and photos via an app, text or website and using automated tools to pull other relevant external documents like police reports. Similarly, automation is being used by some carriers to improve the customer experience to quickly automate claims payments based on a rules-based system (such as those with low dollar value or who use a direct repair program shop). The Need to Simplify Self-Service The study also found that as carriers make small advances toward virtual claims handling, they are also becoming more receptive to touchless claims handling in the quest to fully automate claims. This includes deploying automation solutions such as data prefill to make self-service options easier for customers. However, they need to keep in mind that full automation doesn’t suit everyone. The demand from consumers for self-service options is growing but overall still low and tied mostly to millennials and the younger generations. Until these generations compose a larger portion of the customer base, cost reduction and improving the customer experience will likely remain the key drivers behind further automation. The findings also suggest that low customer demand for self-service is related to customer dissatisfaction with the vast number of questions asked at FNOL and carriers’ failure to fully integrate data upfront in the claims process to simplify self-service for customers. Carriers need to rectify these issues before investing too deeply in touchless claims handling. Though consumers are receptive about increased automation, they still want support in the form of a real person ― particularly if they’ve never filed a claim before and are uncertain about the process. Even millennials don’t want self-service for every situation; they also want human interaction easily available when they need it. It’s critical that customers still get the human touch they want at the relevant parts of the claims process. Remaining Challenges As carriers adopt greater automation capabilities, they’re finding that integrating more data earlier in the claims process leads to more efficient handling. Carriers need to integrate more data prefill solutions that leverage external data sources into the claims process so that self-service options are as easy and painless as possible for customers. The study found that carriers that use a data prefill solution at FNOL experienced a 14% improvement in days-to-pay for bodily injury claims, a 10% reduction in severity as compared with the industry and a 15% improvement in their shopping-rate ratio as compared with the industry. Additionally, while automation progresses in the industry, the research uncovered reluctance to automate. This reluctance is driven by the concern that it will introduce more error and a higher risk of fraud into the non-complex claims process. Carriers are not fully confident that systems are mature enough to counterbalance these types of situations. It is a concern shared by consumers, as well. Consumers’ reluctance ranges from the fear of making a mistake to potential glitches or technology issues that could hurt their claim. These concerns are significantly higher among those who have not had a claim than respondents who have recently filed a claim. Perhaps there is an opportunity for carriers to share more testimonials of customers who have had a positive experience with automated claims processing. See also: Claims Technology: One Size Won’t Fit All   Final Thoughts: Balancing Automation With Empathy The research shows carriers and consumers are largely in sync when it comes to automated claims processing. Even though improving the customer experience may not have been the first or top motivation for embracing automation, the good news is that they’ve achieved it anyway. To retain those customers, they will need to employ a soft variable ― empathy. While consumers, especially younger consumers, increasingly demand self-service and digital access, there are times their biggest desire is a human touch. In summary, automation can help carriers deliver this human touch by freeing representatives to be available when a customer needs personal attention. Carriers must also find ways to customize how they integrate the human touch into the claims experience. Tailoring the claims approach with a blend of automation and human touch to meet the customers’ preference will help carriers do a better job of personalizing the claims process. While the human element of treating others with empathy may be more difficult to improve upon than adding more automation, data and analytics can be deeply incorporated into the claims process to improve accuracy and efficiency. Those factors affect how customers feel about their claims experience.

21st Century Claims: Boosting Efficiency

Customers now demand choice in how and when they engage. That means insurers must provide a digital, yet humanized, claims experience.

The voice of the customer has never been so important to business; a growing number of customers now rely on the reviews and experiences of others to help guide their purchasing decisions, and this trend will only increase as millennials make up a greater portion of insurance carriers’ customer bases. This should be viewed as a positive development. Customers, after all, vote with their wallets, and a scenario where carriers provide what customers want (rather than what is best for the carriers) can only drive standards higher. The claims process is where the customer experience can be best affected, so it is no surprise that it is currently in sharp focus. Customers want choice in how and when they engage, as well as the information they receive, but, during a claim, when a distressing loss may have occurred, the importance of human empathy cannot be understated. To deliver these aspects requires a digital, yet humanized, claims experience. In an intensely competitive environment, how can carriers identify quick wins to maximize the impact on customer experience and efficiency for minimum output and disruption? See also: Key Technology Trends for Insurers in 2019   Insurance Nexus held a webinar with claims experts from five companies focusing on improving the claims process with digital technologies: Bea Rolbiecki (AVP senior experience, USAA), Patrick Klas (associate, American Family Ventures), Daniel Regan (vice president, financial services, SAP Ariba), Allan Robinson (EVP field operations and sales and chief claims officer, Horace Mann Insurance) and John Langowski (EVP, chief claims officer, Swyfft). Listen to the webinar recordings today Throughout the webinar, the most striking consistency was the importance all panelists place on the customer. “Put customers first when building your digital experience” Bea Rolbiecki says. This means understanding the customer journey, what they need to do and how they feel at each stage of the journey. By identifying where bottlenecks and pain points are, investment can then be prioritized to deliver the maximum impact on the customer experience. This is a significant departure from past practice, when investments, technological or otherwise, were usually made with profits and board member dividends in mind. Instead, the inverse is now advised. Swyfft’s John Langowski asks of any proposed change, “What would a panel of policy-holders think of this?” It can be easy to be attracted to the new and unknown, but “don’t just grab the next best thing out there,” he warns; investment must be targeted to specific customer needs. Our discussion also highlighted the importance of the relationships between carriers and claims service providers; there is a “definitely a fear of start-ups,” American Family Ventures’ Patrick Klas says. Understandably, carriers might be hesitant to devolve responsibility of their claims processing to a third party who does not have the experience or reputation of a legacy insurer. Rather than see newcomers as “attackers,” however, Klas opines that companies such as Lemonade and Hippo have succeeded in raising industry standards. Customers prefer, and now expect, digital, personalized and seamless experiences, and it is up to carriers to ensure they meet these standards. A final point may reassure those who fear job losses due to the "rise of the machines"; according to Rolbiecki, the whole aim of digitizing the claims process is to deliver a “sympathetic and connected claims experience.” While AI can do much that humans cannot, providing a sympathetic ear after a distressing loss is not one of them. Horace Mann’s Allan Robinson goes further, claiming that “from a claims adjusters’ perspective, the idea we won’t need adjusters is wrong.” Incorporating aspects of AI, intelligent automation and robotics will allow for straight-through processing of less complex claims, meaning adjusters and investigators can focus on more complicated and, ultimately, more interesting claims. This will actually make insurance, particularly claims, a “more interesting…and more fulfilling role.” See also: Using Technology to Enhance Your Agency   This webinar was run in conjunction with Insurance Nexus’ coming Third Annual Connected Claims USA Summit 2019, taking place June 5-6, at the Marriott Marquis Chicago Hotel. Welcoming over 750 senior attendees, Connected Claims USA is the world’s largest gathering for claims executives striving for efficient, customer-centric claims processing. 

Mariana Dumont

Profile picture for user MarianaDumont

Mariana Dumont

Mariana Dumont is the head of U.S. operations at Insurance Nexus and is currently focused on helping carriers to transform claims processes to deliver a seamless claims experience.