Download

How to 'Detangle' Your IT Issues

Trying to detangle the spider-web information systems that exist in organizations today is a lot like bargaining with a four-year-old.

If you have ever experienced detangling a four-year-old’s hair, you know it is a mess! The amount of fighting and screaming along with negotiations (I will give you ice cream), sometimes threats (no iPad for you) that go into that process can be unbelievable. The situation is not so different a scenario when we try to detangle the spider-web systems that exist in organizations today. Business folks fight with IT, have back-door negotiations with leadership about priorities and engage in countless back-and-forth exchanges of business requirements. Sound familiar? How can organizations cope in a “detangle” situation? Here are three recommendations: 

1. Comb through your systems one small section at a time. If you have tried to comb through a large section of tangled hair, what happens? You get stuck, or your comb breaks. If you comb a small section at a time, you could effectively detangle. Take one part of your process, application, module, etc. and determine ways to streamline the operation. “Eat the elephant one bite at a time” to ensure you won’t get stuck in your innovation and transformation efforts or end up in a mental asylum. 

See also: Creating Win-Win-Win Scenarios   

2. Use a detangle spray. I love detangle spray! Taking a small section of the hair and applying the detangle spray makes the combing faster. Here is where I would recommend organizations look at outside help. Is there a service like virtual transformation office that can expedite your transformation or innovation efforts? Transformational consultants are of a different breed. They cut through the BS; if they don’t, you don’t have the right one working for your organization. These folks bring outside technology, industry-level perspectives and agile processes to act as a “detangler” in your initiatives. For most organizations, operational needs tend to outweigh innovation efforts. An external perspective can ensure organizations are looking beyond the operations and focusing on innovation. 

3. Chop it off. Chopping off the hair was my final resort with my toddler’s hair. I went to the barber and had her hair cut. Why? It was just too painful to continue to maintain. With your spider-web systems, you will come at a point where you have to say good-bye--good-bye to your green screen friends, VB screens from the early 2000s and old funky .asp apps. Are there startups that you can bring to your organization to provide new tech that can eliminate multiple legacy applications? At Benekiva, we pride ourselves on eliminating four to nine systems leveraged by claims staff to process one claim. How many systems are your teams using to complete a task or work unit? You may not be ready to chop everything off, but you can do it gradually. Change takes time. 

See also: Culture Side of Digital Transformation   

Disrupting is the name of the game for all organizations. Even if you are a giant company, you have to keep up or you risk going bald, at which point no amount of combing, spraying or chopping will help.


Bobbie Shrivastav

Profile picture for user BobbieShrivastav

Bobbie Shrivastav

Bobbie Shrivastav is founder and managing principal of Solvrays.

Previously, she was co-founder and CEO of Docsmore, where she introduced an interactive, workflow-driven document management solution to optimize operations. She then co-founded Benekiva, where, as COO, she spearheaded initiatives to improve efficiency and customer engagement in life insurance.

She co-hosts the Insurance Sync podcast with Laurel Jordan, where they explore industry trends and innovations. She is co-author of the book series "Momentum: Makers and Builders" with Renu Ann Joseph.

Drugged Driving Kills; Why Can't We Stop?

While Americans know that driving after smoking or ingesting marijuana is dangerous, one-fourth of them admit to doing so.

|
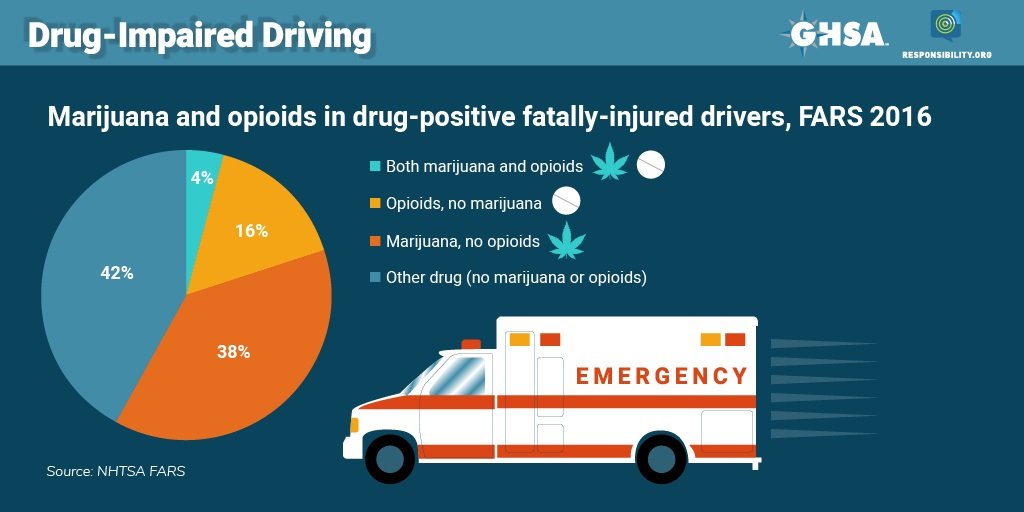
DriversEd.com has released a new study on the awareness and prevalence of marijuana-impaired driving, finding that while an overwhelming number of Americans have an understanding that driving after smoking or ingesting marijuana is dangerous, one-fourth of them have admitted to doing so themselves. According to DriversEd.com’s 2019 Cannabis and Cars Report, 58% of Americans believe that legalized recreational marijuana use leads to increased danger on roads, and 91% of Americans believe marijuana can impair a driver’s ability. Even so, 20% of drivers admit to driving after smoking marijuana, and 6% admit to driving after ingesting it. This may come as no surprise, as 34 states, District of Columbia, Guam, Puerto Rico and the U.S. Virgin Islands have approved a comprehensive, publicly available medical marijuana/cannabis program as of March 2019. Marijuana is more out in the open than it ever has been before, but its accessibility is preceding development of proper oversight. Without correct traffic safety measures in place, the prevalence of drugged driving is growing, as drivers likely believe they won’t get caught, aren’t noticeably driving dangerously or don’t consider marijuana’s side effects to be risky enough to stay out of the driver’s seat. See also: Pledge to Put Your #phonedown   According to the Brain Injury Society, significant cognitive impairment begins the moment marijuana is consumed. THC, or tetrahydrocannabinol, is the chemical responsible for most of marijuana's psychological effects. It interferes with the natural communication of cannabinoids between neurons in the brain, especially in the cerebral cortex—which plays a huge role in how memory, thinking and consciousness are affected. A 2018 Governors Highway Safety Association study, Drug-Impaired Driving: Marijuana and Opioids Raise Critical Issues for States, found that, in 2016, 44% of fatally injured drivers with known results tested positive for drugs, up from 28% just 10 years prior. More than half of these drivers had marijuana, opioids or a combination of the two in their system. The best way to reduce drugged driving, according to Mothers Against Drunk Driving (MADD), is the use of standardized field sobriety testing (SFST), the foundation of impaired driving detection and enforcement for 800,000 law enforcement officials across the country. Some states, however, do not require SFST training for officers assigned to patrol functions. As MADD says: Myths and misinformation are part of the problem. Get the facts—and share them with your loved ones, especially young adults. Why? More than one-third of teens mistakenly believe they drive better under the influence of marijuana. The 2019 Cars and Cannabis survey was conducted online using Survey Monkey. One thousand and sixty-three participants were polled, spanning the U.S., with the U.S. driving population represented by the 997 respondents who, before completing the survey, answered that they have a driver’s license. The demographics of those polled represented a broad range of household income, geographic location, age and gender. This article was originally published on DriversEd.com.

Andrea Leptinsky

Profile picture for user AndreaLeptinsky

Andrea Leptinsky

Andrea Leptinsky is a 15-year news veteran with experience in community journalism, automotive reporting and traffic safety marketing. She started as managing editor at DriversEd.com in 2017.

Some Hope in the Face of the Wildfire Threat

There are lots of reasons why fires get out of control, and it turns out the biggest issue is a lack of real-time information. 

sixthings

In 2018, there were over 6,000 wildfires in California alone, destroying well over 10,000 structures, producing over $9 billion in property damage and claiming the lives of at least 88 people. Horrific. But there’s hope. More than 95% of the wildfires in California are controlled within the first 24 hours and are contained to 10 acres or less. In other words, fewer than 5% of wildfires grow out of control and move into day 2, producing most of the devastation. And improvements in technology can help us tackle that 5%. 

I say that after having had the privilege of being invited to a workshop hosted by the Gordon and Betty Moore Foundation, in collaboration with the University of Maryland, last week. (Yes, that Gordon Moore, co-founder of Intel and author of what has come to be known as Moore’s law.) The workshop pulled together 28 of the smartest people I have ever met, all committed to curbing the impact of wildfire, not only in California, but also across the globe. 

There are lots of reasons why fires get out of control, and it turns out the biggest issue is a lack of real-time information. The best technology available to the commanders making strategic decisions and firefighters in the field gives them information that is usually six to 12 hours old. Fire can do a lot in six to 12 hours.

The workshop identified a number of technologies that could greatly improve the information flow, three of which stood out to me: offerings from Planet Labs, Jupiter Intelligence and Descartes Labs.

Planet Labs has deployed a pearl-like string of shoe-box-sized satellites that provide an image of the entire globe every 24 hours. The image is accurate to about three meters—you won’t be able to pick out a person, but if you’re looking for anything as big as a pick-up truck or bigger, you’re good—and will let firefighters watch for danger.

Jupiter Intelligence provides a supercomputer platform that models potential dangers from one hour to 50 years out and could be used to monitor fires in near-real-time.

Descartes Labs combines data from lots of different sources, including sensors and imagery, and refines that data so it can be used for modeling that can spot and monitor potential problems as well as actual fires.

The folks at the workshop are committed to pulling together these and other technologies to better understand the traits (weather, terrain, vegetation, humidity, wind, etc.) that might signal the right conditions for an uncontrollable wildfire. The group will also integrate technologies and other capabilities to provide firefighters with real-time data about a fire and its movement. 

We have written many times in this commentary about how technology is moving insurance and risk management into a predictive and (we hope) preventive role, rather than simply helping us get better at responding after losses occur, and that change will need to extend beyond technological improvements. I learned last week, for instance, that we are probably a decade behind in controlled burns. We should be control-burning about 2 million acres per year to limit wildfires, but we have been control-burning only approximately 100,000 acres a year for a long while. No wonder there is so much fuel to feed those wildfires. (Some environmentalists may push back on the need for controlled burning, but the wildfires seem to have created a new level of realism all around. Unless we’re going to unleash tens of thousands of goats on our forests, controlled burns are the only alternative.)

As always, we in the insurance industry can help. While the data we use for making decisions about risk and pricing may not be the same as what authorities need to prevent or fight fires, there is significant overlap, and we must all work together in this time of acute need.

I’d love to hear any thoughts about what the Moore/Maryland group or we as an industry should be doing in the face of the wildfire threat.

Wayne Allen
CEO


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Who Is Your Customer; How Is the Experience?

The amount of low-hanging fruit with few costs and high impact for both the customer experience and optimized operations is incredible.

In today’s digital world, companies have to focus on customers and their experience. No longer is it just about optimizing the business and processing the transaction; the overall experience matters for retention and renewal. It is essential to create a seamless digital experience that is tailored and personalized, based on understanding customers and their needs. The first thing an insurer must do is define who the customer is. Depending on a company’s channel – direct, captive or independent agents – the definition becomes not only complex but political and even cultural and structural. Historically, for many insurers whose channels have been independent agencies, the agent or broker has always been the customer. But more insurers have embraced the reality that the policyholder is also the customer. There is often a debate as to where the CX focus should be: on the policyholder or the agent? I believe insurers need to consider both as customers – different customers, but both customers. In most cases, agents own and manage the relationship with the policyholder, and the insurer provides services to the policyholder. Insurers need to embrace both agent and policyholder and the connectivity of the triad relationship, and how these relationships and connections fuel one another. See also: Bold Prediction on Customer Experience   Ease of doing business is the requirement for any insurance customer in today’s digital, connected world. Agents choose where to place the business based on ease of doing business (along with the relationship, product coverages and pricing). There are a few key areas to focus on to improve the agent experience, like providing agents with the right technology solutions and tools to quickly and painlessly quote, bind, issue, endorse and renew. Agents expect it to be fast and easy to understand each insurer’s product and risk appetite and to have clear visibility into the status of all interactions between the agency and insurer – as well as the policyholder and insurer. While the agent may have a personal relationship with the insured, insurers do interact with policyholders: making payments, changing pay plans, asking questions around a final audit invoice, having loss control visits and, of course, experience the whole claims process. The key to providing a really great customer experience for the policyholder includes providing a personalized touchpoint in any channel – whether it is paper, digital or face-to-face – and ensuring communications are easy, accurate, consistent and straightforward. Last, but not least, minimizing or even eliminating the need to call, maximizing the experience when customers do need to call to a one-call-resolution and providing the option to go to the self-service portal are all goals of the transformed customer experience. As we look at the customer experience today, there is tremendous opportunity to transform not only the customer experience but your company, as well. As we work with insurers on their CX transformation journeys, the amount of low-hanging fruit with minimal costs and high impact for improvement to both the customer experience and the optimization of operations is incredible. But first, you must be clear as to who your customer is. Then, declare that your company is on a CX transformation journey. Now, you are ready to move forward.

Deb Smallwood

Profile picture for user DebSmallwood

Deb Smallwood

Deb Smallwood is the founder and CEO of SelfPowerment.

She spent four decades in corporate leadership across the insurance industry, operating at the intersection of business, technology, and organizational transformation. Her leadership inflection point led her to research the experiences of more than 50 high-achieving women and 10 men leaders. This formed the foundation of her book, SelfPowerment: The Inner Shift for High-Achieving Women Who Want More Than Just Success. The work introduces a research-informed framework that redefines success from within and invites women to shift the question from, “Will they choose me?” to “Do I choose them?”

Curve Ahead: Managing Autos

As a safety manager, what’s the best practice for managing the ever-decreasing road capacity along with the host of new exposures?

My first job out of college was very hands-on. I worked in a laboratory testing the bituminous materials used in road construction. Every month or so, I’d move to a different, temporary laboratory/trailer in a strange city near another highway being resurfaced, and I’d get to work ensuring the road materials were in compliance with the requisite specifications. I quit that job when I noticed that the chemical solution used to separate bitumen from rocks was dissolving my fingerprints. Hands on. Fingerprints off. Unless I wanted to be a burglar full-time, I needed to find a different occupation. I got a job designing traffic signals and road junctions. While there is a lot of math involved, there is also a lot of studying human behavior. The role was more of a black art than a science. Quite often, people – both pedestrians and drivers – do something other than what you expect them to do. Someone goes straight in a right-turn-only lane. It happens. Run a red light because the two cars in front of you did? That, too. My specialty was designing traffic light junctions. Humans are hugely inefficient at negotiating junctions, even those that have colored lights telling you what to do. Sit third or fourth in a line of cars at a set of traffic lights and see for yourself. It was a problem I worked on for years as a traffic engineer. It is worse now, of course, with many more distractions available via smartphone. Next time you’re in traffic, look at how many other people on your gridlocked commute are messing with something they shouldn’t be rather than paying attention. A conservative estimate would suggest that a third of drivers are distracted by their smartphone when they should be driving. That has to have an effect. To this day, I cannot help but critique road junctions and their layouts. I will be sitting in unnecessary traffic studying the layout of a junction, then perhaps remarking to my wife – or, worse, my kids – about some deficiency, then, of course, hate myself for doing so. I save the majority of my angst for new installations. I can’t criticize a traffic engineer from the 1960s who never envisioned a four-fold increase in vehicles passing through his carefully designed intersection. I am sure you have been driving somewhere on the highway when, for no apparent reason, you suddenly find yourself braking and eventually grind to a complete halt. You sit there for a while, pondering what choices led you to this point in your life (whipping out your smartphone to check the length of backed-up traffic), then, just like that, you and everyone else around you start to move and, within a relatively short time, you are back to your regular speed. The thing is, the wreck you assumed was holding you up is not there. It is gone by the time you get to it, or, more likely, it never existed. Instead, you got caught up on a section of highway that was over capacity. Oh, and congratulations, you just survived a shock wave. As a nascent traffic engineer back in the 1990s, I learned about road capacity. That is the measure of how many vehicles a certain stretch or road can handle before things become inefficient and congestion occurs. Say it is Friday circa 4 p.m. Cars in all lanes, in front and behind you. When someone enters from the on ramp, those in the far right lane have to start braking because there is too much traffic around them to allow them to change lanes. That braking makes its way down the line of traffic, growing as it moves backward. If the first guy has to tap his brakes to allow a car in his lane, the car 50 cars behind him is coming to a complete stop. Now imagine that at every on ramp or every time someone rashly changes lane without signaling. The more traffic you direct onto a road, the higher the frequency of traffic jams. Absent a few years directly after the 2008 financial crisis, the number of miles driven in the U.S. has increased year over year, with lower gas prices aiding this. In short: Our roads are filling up with cars faster than we can build new roads. At some point, things stop working. Gridlock ensues. So what, right? Nothing new here. There have always been traffic jams, and autonomous vehicles will solve all of our woes, after all. Move along, nothing to see here. Maybe AVs will make all the problems go away, but that claim has yet to be tested. It is a hypothesis, and we do not yet know whether cars that drive themselves will do anything to solve traffic issues. They will certainly help with traffic flows, particularly in congested cities, but, even then, the benefits will likely be temporary and finite. More vehicles should get through busy road junctions, but maybe we're just pushing the issue down the same road a little. If you free up space on the roads, what will happen? Absent another fuel crisis, the empty spaces on roads will be filled by more vehicles wishing to drive on them. Automated vehicles or not, once you reach capacity, passengers and drivers will suffer. Road capacity is finite. There are only so many vehicles and people you can get on them at any one time. Since the turn of the century, we have seen a huge reduction in accident frequency, but a lot of that is down to significant technological increases in vehicles braking, improved tire design and a plethora of safety features that no one had thought about in the 1990s. The increase in lift from each technological advance will tend to be smaller. You now have to share the road with many other commuters, big-box delivery trucks, last-mile Amazon deliveries, ridesharing independent contractors, utility service workers and the sidewalks with 20 mph scooters, pedestrians preoccupied with cell phones and, soon, robotic pizza delivery drones. Despite the technological advances in safety, it is becoming increasingly hard to prevent auto losses from occurring. How do you combat this? As a safety manager, what’s the best practice for managing the ever-decreasing road capacity along with these new exposures? I recommend the following:
  • Keep your vehicle use guidelines updated and communicate to your drivers as often as possible, at least every time there’s a modification to them.
  • Read. Every day a new challenge arrives and there is a new safety feature to deal with it. Perhaps in-cab cameras would benefit your fleet? Perhaps it is additional training for your drivers on the risks that scooters pose.
  • Understand the inherent exposures that your fleet possesses. Is there a vehicle in your fleet that can drive autonomously already? Do your large truck drivers have difficulty viewing vehicles approaching from adjacent lanes?
  • Minimize distractions in the vehicle. Address the use of cellphones when driving and limit consumption of food in the vehicle to when it is parked.
  • Factor in a likely increase in journey times for your drivers. There should be nothing gained by speeding.
  • Talk. Provide training to your drivers, particularly on the new hazards. Discuss techniques for handling these hazards as a group.

Tony Hughes

Profile picture for user TonyHughes

Tony Hughes

Tony Hughes is a commercial auto product manager at Safety National, with more than 15 years of experience in operations, claims, product management and underwriting. His comprehensive knowledge about the auto insurance industry results from having worked in related fields in the 1990s.

How Insurers Are Innovating Right Now

Connected insurance is the biggest potential for transformation that insurance has witnessed since the invention of the computer.

From day-to-day operations, to the very relationship between insurers and policy-holders, it is no exaggeration to say that connected insurance represents the biggest potential for transformation that insurance has witnessed since the invention of the computer. See, for example, the ability of an insurance carrier to react to live data, in real time, and prevent a loss from occurring. From simply mitigating the effects of a loss, they become partners in risk-prevention. In an increasingly competitive, technology-driven market, insurance carriers must continually innovate to deliver connected products and services that resonate with customers and provide what they need, rather than what the insurer can offer. Likewise, as technology develops and the digital distribution of insurance products increases, product development itself must become similarly agile and responsive. Squeezed between decreasing profit margins, increasing customer expectations and greater competition, however, all insurance companies find themselves in a potentially make-or-break position; innovate or die. See also: Understanding New Generations of Data   Yet while technology represents insurers’ best chance at outstripping competitors in terms of product development, efficiency and customer experience, with so many new technical possibilities available (many of which are relatively unexplored), there is also ample opportunity for them to overspend and underdeliver. To provide some clarity, Insurance Nexus recently interviewed over 300 executives to understand where insurance companies are concentrating their efforts to improve connected product and service innovation, who is responsible for these projects and how things are expected to progress in the future. In the course of our research, it was striking to note the degree of importance with which executives are now viewing connected insurance innovation. 50% of respondents believe that CEOs and heads of strategy must take the lead in connected product development--a clear indication that innovation is rightly regarded as an enterprise-wide undertaking. Our results also suggest that insurers recognize the scale of these projects and that, in many cases, they do not have the required competencies in house; 54% said that leveraging the expertise of external technology partners and insurtechs has been of greater value than relying solely on in-house talent. On the subject of departmental collaboration, the results show that data and analytics departments feature heavily in connected product innovation. This is significant principally because the success of the AI and machine learning systems that underpin so much of connected products is predicated first and foremost on data, both volume and quality. If insurers can maximize the potential of the data they already possess and then intelligently insert aspects of AI (as opposed to hastily implementing an AI system and feeding it on poor-quality, invalid or disparate data), they will see the greatest results. One particularly eye-catching statistic was that over half of respondents claim that their most successful channel for communicating product development and new services is by word of mouth. Although initially surprising to us in the digital age, this will be of great comfort to marketing teams everywhere because it tends to support the idea that product development should begin with the customer and their needs. If those needs are met, customers are showing themselves willing to become brand ambassadors themselves, a particular boon to insurers in such a saturated marketplace. Download the infographic for detailed statistics on:
  • Which technologies are insurers embracing and actually integrating into their everyday procedures and products, including AI, ML, data analytics, automation and IoT?
  • Where are insurers prioritizing investment: operational efficiencies and internal procedures or customer-facing UX technologies?
  • What are the proven internal blends of skill sets that drive transformation forward, including leadership buy-in and recruitment initiatives in IT and data analytics?
  • How to incorporate external technology experts and insurtech that supercharge what you can offer your customer.
This infographic was created in association with Insurance Nexus’ coming Connected Insurance Europe Summit, taking place May 15-16 at the Novotel Hotel in Amsterdam. Welcoming more than 350 senior executives from across departments, the event will provide organizations with the necessary strategies and insights to transform each core pillar of product development, strategy and innovation and communication of value to the customer. For more information about Connected Insurance Europe, please visit the website.

Graham Proud

Profile picture for user GrahamProud

Graham Proud

Graham Proud works closely with insurer senior-management teams to identify the challenges and solutions in bringing about transformation. Proud produces a number of white papers, webinars and major industry events to reflect the industry's latest trends.

Google and Applied Systems: 6 Months In

The big Google investment suggests it sees a great future for independent agents. So, what's the verdict after six months?

The insurance world was caught by surprise last October when Google’s Capital G investment arm announced a substantial investment in Applied Systems (north of $100 million). It was seen by many as an endorsement of the independent agent (IA) channel. If Google believes it will make a nice return on investment in a company serving the IA channel, then it must believe the channel will survive and grow. From the Applied Systems viewpoint, in addition to the extra capital to invest in the platform, it was anticipating access to world-class technology and expertise from Google. So now that the investment/partnership is six months in, what can we say about the progress? Recently, I was fortunate to witness some of the activity first-hand, as Applied invited me to join them at the Google Cloud Next event in San Francisco. For me, it was a chance to “experience” Google and meet some of the players in the Applied/Google partnership. I’ve come away with several observations about Google and Applied Systems.
  1. Deep partnership: As originally promised, the Google investment was more than money looking for a return. Applied and Google are collaborating at the development level, with dozens of Applied developers being trained and exposed to Google tech.
  2. Future promise: It is still early in terms of how Google tech and expertise will influence Applied/IVANS systems, but there are indications that the first fruits will be visible this summer, and more enhancements and capabilities will be built into the product road map over the next several years.
  3. New era of computing: The shift to a new era of computing is well underway. The event was focused on developers, and the entire event was filled with sessions and discussions about containers, connectors, Kubernetes, APIs, big data, cloud, edge computing security, AI/machine learning and other technologies and approaches that are transforming how computing systems are designed, built and managed.
See also: Whole New World for Customer Contact   My one disappointment at the event was that insurance was not very visible. There were hundreds of speakers and dozens of use cases, but nothing for insurance. Banking, retail and healthcare use cases and solutions were prominent (as were those from many other industries), but insurance only received a passing mention. Let's hope the Applied/Google relationship will change that, and that more technology harnessed to address specific insurance use cases will be in evidence by next year’s event.

Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.

Myth Busting on GDPR Insurance Policies

If companies with as many resources as Google are facing fines related to GDPR, how can far smaller businesses address this risk?

As we approach the one year anniversary of GDPR implementation, we have seen that many companies still don’t understand how the privacy regulation works or how to properly mitigate the risk. Earlier this year, Google, one of the largest technology companies in the world, was fined $57 million for a GDPR breach in France. If companies with as many resources as Google are facing fines, how can far smaller businesses address this risk? One effective solution is to mitigate the risk through cyber insurance policies. Insurance helps businesses self-regulate their actions and acts as the last line of defense in the event of a major fine. But, not all policies are created equal, and it can be difficult to navigate the oftentimes confusing language in various insurance policies. I've spent time evaluating numerous policies and examining GDPR-specific risks—even more so since my company, Coalition, developed a policy tailored to address GDPR. From this review, some myths and truths from GDPR became clear. Here are a few: Myth: Only big companies and big fines matter It is important to recognize that big businesses are not the only target of GDPR. While it is true that any business can be penalized, it’s safe to say that the largest fines are for the largest companies and the most egregious violations. However, this doesn’t mean that smaller fines and smaller offences aren’t being monitored. In fact, smaller fines are levied on a regular basis. For example, one GDPR fine of $5,400 was issued for a retail establishment’s CCTV camera system that partially surveyed a public sidewalk. Even though it didn’t involve an egregious failure, nor an enormous company, action was taken and a fine levied. This points out two elements of GDPR that are myths: that only large companies and large fines matter. To a smaller company, any fine and attorney’s fees is enough to be deadly, and countries are monitoring activity for all companies. See also: What GDPR Means for Insurtech   Myth: Only European businesses need to comply with GPDR Last year, the number of companies offering cyber insurance in the Lloyd’s of London commercial insurance market jumped more than 20%. According to Lloyd’s chief executive, gross written premiums for European cyber insurance could reach more than $2 billion annually by 2020, partly as a result of GDPR. While this growth supports the fact that E.U. businesses need to mitigate the risk of compliance with GDPR, it fails to acknowledge that U.S. companies are also subject to GDPR. This is because GDPR has a much wider scope than just European companies. It protects personal data even across the Atlantic. Accordingly, a U.S. company can just as easily violate GDPR when collecting, using or maintaining data regarding E.U. citizens. Come time for fines, if a business only collects a third of its revenue from European customers, it will still be fined on its revenue from all markets. Therefore, businesses outside of Europe need to evaluate GDPR compliance and insurance, as well. Myth: A vendor’s breach does not affect my company Your business is liable if your trusted vendor lost your data. Therefore, you may consider requiring that your vendors procure GDPR insurance policies, naming your company as an additional insured. If your company was entrusted with data, you are liable even if one of your vendors loses the information. Truth: Risk mitigation can help A 2018 study of privacy professionals found that 56% of respondents were at companies that were not yet compliant with GDPR, and 19% said that their companies would never be fully compliant. This is clearly an unsustainable approach to GDPR. Mitigation techniques are a crucial aspect of a good policy. Leading insurance companies help businesses comply with regulations by educating them and evaluating their privacy practices. The use of these techniques, in turn, help protect businesses against allegations. Truth: The right cyber insurance policy could save your business. From the day GDPR went into effect, May 25 of last year, to the end of this past January, there have been 91 GDPR fines issued. That is more than two fines per week. To purchase an insurance policy that will allow your business to survive a fine, it is paramount to review what specifically is covered. It is important to protect your company with a policy that covers you not only in the event of security failures and data breaches but also when often-forgotten repercussions arise regardless of whether data was compromised. GDPR is unique in that it codifies privacy regulations. Not only are companies fined if they expose customer data as a result of a cyber breach, but companies are also receiving penalties for failure to follow their own privacy policies. See also: Europe’s New Data Breach Requirements Not following your own privacy policies is called “failure to comply” and can result in fines from GDPR. For example, if your company says in its privacy policy that it will delete certain information, which is also known as “the right to be forgotten,” it must hold up its promise. Failure to comply with that very privacy policy could result in fines and penalties. To mitigate this risk, companies should review their privacy policies regularly and also ensure that failure to comply is included in their chosen GDPR insurance policy. Truth: Take action now GDPR has been in effect for almost a year, so, if you haven’t yet taken measures to prepare your company for the event of a fine, do so now. Whether your company is big or small, it’s important you consider a GDPR insurance policy, and when you look be sure to find a policy that both covers fines resulting from a cyber breach and from failure to comply. Additionally, look to see if the insurance provider offers risk mitigation techniques and evaluate the provider's payout limit. It can also be important to review the vendors critical to your business and encourage them to procure coverage as well to avoid a business disruption or third-party liability. With these considerations in mind, your business will be ready to purchase a policy that will prevent you from going under in the event of a fine.


Shawn Ram

Profile picture for user ShawnRam

Shawn Ram

Shawn Ram is head of insurance at Coalition, a company founded at the intersection of the insurance and cybersecurity industries by a team of insurance, technology and intelligence community veterans.

In a Crisis, Will You Be Ready?

You won’t have all the answers--you don’t yet know all the questions--but begin a crisis management process with your families and firms.

S___ happens! Fifty years ago, Rock, David and I were at Pelican Aviation’s hangar listening to several seasoned pilots talk about their most terrifying experiences in the air. One said, “The engine made a loud noise, the plane shook violently and suddenly I couldn’t see a thing.” One of us innocently asked, “What happened – did the windshield shatter?” His answer was simple, “No, tears.” Having spent much of my adult life in insurance, I’ve seen many disasters. The question is: Are we ready? Hurricane Katrina was a terrible event for Mississippi. In New Orleans, there was minimal wind damage, but there were levee failures and accompanying social/civil chaos. There was also a little-noticed success story: LSU’s medical school relocated from New Orleans (blocks from the chaos) to Baton Rouge in about a week. This required some luck, community (BR and NO) support and, I believe, some divine intervention, but it was an example of leadership at its best. What if you had to relocate your office, all your team and everyone’s families following a catastrophe? Have you even considered the possibility? See also: 4 Lessons From Harvey and Irma   Here’s reality – many if not most of us will face great challenges. Some may parallel experiences we’ve seen before, just with greater or lesser intensity. There will be more fires, hurricanes and floods. Terrorists will attack us again. Planes will crash. We can’t stop all the bad in the future – the best we can do is try to avoid or at least mitigate the damage. Most of us watched the successful rescue of 12 young soccer players and their coach from a flooded cave in Thailand. Relative to 9/11 or Hurricane Katrina, it is a minor event, but I believe it will prove to be one of the best case studies anywhere of what to do when the stakes are high, time is limited and you don’t know what to do. Remember, these folks were lost for about 10 days before anyone even knew where they were. The last few days of their stay were examples of calm, leadership, courage, planning, possibilities and then very deliberate action. Every Seal, volunteer, civilian, etc. should be celebrated for their effort, courage and patience – living and learning as they progressed. They didn’t rush in, reacting to a terrible situation. They walked, crawled, and swam in, well-prepared and observing appropriate caution. In construction, we’d say: Measure twice, cut once. Never forget that one of the rescue team died early in the process. Was this loss the impetus to do things differently? I don’t know. I do believe our greatest learning occurs in adversity – it is the wisdom of scar tissue! The death was tragic but may have slowed the process and improved results. I encourage each of us to consider the disasters that could be on our horizon. Begin a crisis management process with your families and your organizations. You won’t have all the answers, and you don’t yet know all the questions – nonetheless, be as prepared as you can and program for the unexpected. Plan your actions and act your plan. See also: Innovation — or Just Innovative Thinking?   A speaker once said at an agents meeting, “the merchant of misery is either at your door, just left or will soon arrive.” The best thing you can to is to be as prepared as possible and hope and pray you are blessed with the courage, skills, patience, process and RESULTS that these Thai crisis managers enjoyed. Be prepared. Practice your preparations. Preparedness is a process not a one-time event. If in the end all of your preparation is not needed, BE THANKFUL. If it is needed, you may thank me for the suggestion. Good luck and Godspeed.

Mike Manes

Profile picture for user mikemanes

Mike Manes

Mike Manes was branded by Jack Burke as a “Cajun Philosopher.” He self-defines as a storyteller – “a guy with some brain tissue and much more scar tissue.” His organizational and life mantra is Carpe Mañana.

Choosing a Policy Handling Application

Choosing the right policy handling application may unlock significant value; the wrong one may impose a strategic constraint for years.

Choosing the right insurance policy handling application may unlock significant value, but choosing the wrong one may impose a strategic constraint lasting years. As such, it is good practice to take the decision on what application to progress in a structured manner. This article proposes a series of elements to consider. Policy Only vs. Integrated: Choosing between a solution for policy handling only and a solution that offers policy handling capabilities together with other modules such as billing, claims and rating is a question of analyzing the existing capabilities of the insurer to determine what needs, or may in the future need, updating and what does not.
  • If the insurer wants to improve its capabilities in areas other than policy handling, then an integrated solution could be considered. The options in this case are to either implement the policy solution and the relevant module/s at the same time, or first implement the policy solution as a minimum viable product (MVP) and then implement relevant modules later. The thinking is that implementing multiple components from the same suite may be simpler than implementing components from different solutions.
  • If the insurer is confident that it has strong capabilities in all areas other than policy handling, and that in coming years it will not need to upgrade these capabilities, then there may be a case to pick an insurance solution that only has the policy handling module.
Public Cloud vs. Private Cloud vs. Hybrid Cloud vs. On Premise: Focusing on hosting for the policy handling application, the key options are:
  • Public cloud, where the application is hosted on a cloud owned and managed by a third party. Advantages of this approach are lower maintenance, high scalability and high reliability.
  • Private/enterprise cloud, where the application is hosted on a cloud owned and managed by the insurer in question. Advantages are high flexibility with regard to configuration and security.
  • Hybrid cloud, which combines elements of private and public clouds. The key advantage is that the host insurer can choose to maintain highly sensitive assets on private cloud and the rest on public cloud.
  • On premise, where the application is hosted on infrastructure owned by the insurer. The main advantage is that, because data is not being processed on a cloud, a number of regulatory restrictions do not apply.
See also: Awareness: The Best Insurance Policy   The decision on what hosting approach is best for the insurer can then inform the choice of policy handling solution in two ways. First, validate for each application being considered whether it was natively developed for the preferred hosting approach or whether it was adapted to that hosting approach. For example, an application that was originally developed as on-premise only may have been “ported” to be deployable on cloud. Second, analyze what success other insurers had in implementing each insurance application with the preferred deployment approach. Customer-Facing vs. Non-Customer-Facing: A front-to-back insurance policy handling solution has both a customer-facing front end, such as a web front end, and a non-customer-facing engine for the processing of policies; a back-end-only solution lacks the former.
  • If the insurer does not wish to transact through new customer-facing channels, then a back-end-only insurance solution may be desirable. Validate that the existing channels can be effectively integrated with the prospective back-end-only application.
  • If the insurer wishes to implement new web quote and purchasing capability, then it may be beneficial to select a solution that already encompasses the relevant functionality. Examples are applications that have a pre-built web front end that is already integrated with the back-end policy handling engine.
High vs. Low Automation: High-automation policy handling solutions have labor-intensive tasks, such as issuing renewals and rating quotes, handled automatically; low-automation solutions, the opposite. Although it could be thought that greater automation is always advantageous, that is not always so. The appropriate level of automation depends on the type of business being transacted.
  • High-volume, low-value business, such as travel, is well-suited to automation. Because transactions are highly standardized, it is more efficient to have the application run them automatically than it is to have handlers do the work.
  • Low-volume, high-value business, such as directors and officers, on the other hand requires, significant personal interaction with brokers and clients, meaning that a low-automation solution is appropriate.
  • For anything in between, case-by-case analysis should be done. Following that, candidate insurance applications should be analyzed to determine whether they natively include the relevant automated transactions.
Data Migration vs. No Data Migration: The migration of one or more mature books of business from a legacy application to a new insurance application is in many cases the underlying business case for the implementation of the new insurance application, but that is not always the case. Where one or more books of business are to be migrated onto a new insurance application, analysis should be performed on what capabilities the application has with regard to policy data migration. Specifically:
  • Does the out-of-the-box application allow for the creation of migration records?
  • Have other insurers performed policy migrations into the application, and did they succeed?
  • Does the solution have an integration layer that can be used as part of the extract/transform/load (ETL) process?
  • What level of customization would be needed to enable manual data migration?
See also: Understanding New Generations of Data   Key Takeaways:
  • An integrated solution encompassing modules such as billing, rating and claims may be adequate where the insurer wants to improve those capabilities.
  • The choice of hosting approach, focusing on either cloud or on-premise, may influence the choice of policy handling solution.
  • Where the insurer wishes to introduce new customer-facing channels, selecting a solution featuring out of the box a front-end, customer-facing solution may be advantageous.
  • More automation is not always best; low-volume, high-value books of business may require lower levels of automation of core transactions.
  • If there are books of business that are to be migrated into the prospective application, analyze what capabilities the application has with regard to data migration.