Download

ITL FOCUS: Parametric Insurance

"By having a simple yes/no metric, such as a temperature that rises above a certain level or drops below a specified level for an agreed-upon amount of time, parametric insurance removes the need to have an adjuster go into the field..."

sixthings

JANUARY 2022 FOCUS OF THE MONTH

PARAMETRIC INSURANCE
FROM THE EDITOR

When you strip insurance down to its essence, there are just three components related to indemnification. There is a client/contract. There is a yes/no mechanism for determining whether a payment is triggered to that client under that contract, as well as the amount. And there is capital, whether from an insurer, a reinsurer or the capital markets. That's it: a client, a judgment mechanism and money.

And when industries go digital, as insurance is, they get stripped down to their essentials, which can be recombined in new, even surprising, ways. Look at photography. For more than a century, since George Eastman patented the first roll of film and founded Eastman Kodak in the 1880s, photography was associated with its physical manifestations--the cameras, the film, the chemicals and the prints. In the digital age, photography is stripped down to its essence: an image. Cameras now are built into almost every conceivable type of device, especially smartphones, and images are shared without ever getting near a chemical or piece of paper. As a result, profits and market value have moved away from the physical manifestations, including Kodak, and to Facebook/Instagram, TikTok, etc.

This is where parametric insurance comes in. By having a simple yes/no metric, such as a temperature that rises above a certain level or drops below a specified level for an agreed-upon amount of time, parametric insurance removes the need to have an adjuster go into the field to inspect, say, crop damage and offers a path to accelerated digitization for insurance. The approach both cuts costs and greatly speeds payment--offering benefits both to insurers and customers.

As always, there's complexity to parametric insurance. Almost nothing about digitization is as simple as the theory suggests. Remember when ATMs replaced bank branches? When travel websites eliminated travel agents? Yeah, neither do I. But parametric insurance has great potential, which I hope you'll explore by reading this month's interview and by exploring the the links we've provided, including to the six articles below.

Cheers,

Paul Carroll, ITL’s Editor-in-Chief


INTERVIEW WITH HENRY GALE

As part of this month’s ITL Focus on parametric insurance, we spoke with Henry Gale, parametric insurance research lead at Instech London, on the prospects for this increasingly popular approach to insurance.

“We've just seen more and more products being announced, more and more startups emerging and getting investment, more partnerships and more adoption as bigger insurance companies get involved, as well. If you like, 2021 was a big year of announcements, and we’re looking to 2022 as maybe a year in which some of these products scale and we see success in parametric insurance”

Henry Gale 

WHAT TO READ
Growing Case for Parametric Coverage

There have been four notable launches or expansions just in the past month for parametric insurance--innovation is speeding up.
Read More

Parametric Insurance: Is It the Future?

It’s worth looking beyond COVID-19 to consider a funding mechanism that can radically change the most basic nature of insurance.
Read More

Parametric Insurance: 12 Firms to Know

These companies are worth considering as examples of how parametric insurance works, and what the future might look like.
Read More

Parametric Solution for Wildfire Risk

Parametric insurance products could provide immediate relief through automatic payouts to vulnerable people in affected areas.
Read More

Insurtech Trends for 2022

We’re well past simplistic disruptive thinking, where startups would present themselves as the Uber of X.
Read More

How We Can Overcome Uninsurability With Data

The pandemic has accentuated the global insurance protection gap. Digitalization can be a great lever for re/insurance to reduce it.

Read More


WHO TO KNOW


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

An Interview with Henry Gale

As part of this month’s ITL Focus on parametric insurance, we spoke with Henry Gale, parametric insurance research lead at Instech London, on the prospects for this increasingly popular approach to insurance.

sixthings

As part of this month’s ITL Focus on parametric insurance, we spoke with Henry Gale, parametric insurance research lead at InsTech London, on the prospects for this increasingly popular approach to insurance. In addition to the interview, you can check out these recent posts from InsTech London:

How we spot parametric insurance trends
and
Best of both: bundling parametric with indemnity insurance

ITL:

At InsTech London, you put a clear stake in the ground a year and a half or so ago and declared that parametric insurance was a real breakthrough. Do you still feel that way?

Gale:

We do. We've just seen more products being announced, more startups emerging and getting investment, more partnerships and adoption as insurance companies get involved, as well. If you like, 2021 was a big year of announcements, and we’re looking to 2022 as maybe a year in which some of these products scale and we see greater success in parametric insurance.

For specific examples, I'd steer you to a report we released last year that profiled over 50 companies in parametric insurance; we'll update that later this year.

ITL:

Is there a particular area, such as agriculture, where you expect to see the breakthroughs?

Gale:

Catastrophes have always been the biggest area of parametric insurance. There's still potential for growth in that area. So that will stay the dominant trend, both for agriculture and for other areas.

It's been interesting to see new distribution methods to get farmers in different parts of the world better-insured. In addition, there’s lots of potential in things like travel insurance, event insurance, or cyber business interruption.

ITL: 

What are some of the new forms of distribution?

Gale:

When it started, parametric insurance was very much concerned with big corporate risks and reinsurance. The innovations in the last few years have been expanding that to smaller and medium businesses or even to individuals. And all of those need quite different approaches to distribution.

With corporates, they are becoming more and more aware of parametric insurance, especially for traditional catastrophes like hurricanes and earthquakes. The challenge will be maybe making them aware of the potential with other natural perils, and getting brokers more involved in selling parametric insurance. For smaller and medium businesses, there are less established distribution routes to parametric insurance. So people are looking at whether you can do embedded insurance or go through brokers.

In almost all cases, parametric insurance is still best combined with indemnity insurance. For instance, you could take a deductible buy-down approach. If you’re a big corporate, you might have a high deductible on your earthquake risk but achieve that deductible by taking out a parametric insurance policy against earthquakes. You get an instant payout and then the rest of your damage gets covered by the other policy.

One trend that I was looking at recently is combining parametric triggers into an indemnity-based insurance policy; products that are partly parametric based on some events but also indemnity in other realms.

ITL:

Do you have a favorite example?

Gale:

One recent example that we found very interesting is that Vave, an MGA that Canopius set up, is going to be including extreme-temperature insurance in its policies. Whether it's because of a cold snap or extreme heat, anyone who's insured on those commercial property policies will get an automatic payout, as well as being covered for everything else that they have in their commercial property insurance.

ITL:

Parametric has always been intriguing to me, partly because the payout can be so quick and partly because you just take the expense of the claims adjustment process out of it. Do you have a way of quantifying those gains?

Gale:

In terms of the speed of payout, it depends on the sort of product and the amount of money, but we’re seeing companies make payments in hours. And, if you’re insuring large corporate risks, it's a big improvement to be paying the claim in days or weeks rather than in months or longer.

Parsyl, which has collaborated with Lloyds, insures vaccines and seafood and other perishable goods. When the shipment reaches its destination, if the sensor in the cargo shows that the temperature has gone above a certain level, spoiling the batch, the person receiving the shipment scans the QR code. In July, Parsyl paid a claim in eight hours.

ITL:

Is there a particular part of the world where parametric insurance seems to be happening faster?

Gale:

There are regional patterns. In Africa, there's potential for ensuring smallholder farmers, and we’re seeing several parametric programs in action. There's also agricultural parametric insurance happening elsewhere in the world, like India. In terms of catastrophes, the U.S. is always going to be a big focus, as well as Latin America. There's quite a lot of initiatives to insure vulnerable people in the Caribbean or South America against the risks associated with earthquakes and hurricanes. Some of the other applications, for non-damage business interruption or flood risk, apply quite universally.

ITL:

You’ve mentioned a couple of companies. Are there others to watch?

Gale:

Descartes Underwriting has managed to scale up its underwriting for parametric insurance against climate and catastrophe risk for large corporates. Generali is the insurer behind them. Global Parametrics has been structuring a lot of solutions to help vulnerable communities across the world. New Paradigm Underwriters handle large risks against hurricanes and earthquakes in the U.S.

ITL:

What haven't I asked you about that you think is important for people to understand about parametric insurance?

Gale:

Insurers are looking at opportunities for parametric insurance in areas other than climate and catastrophe, such as business interruption and cyber. Finding a scalable product for small and medium businesses is a big opportunity for insurers to write new business.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

How Important Is the Human Touch Really?

There's a division of opinion. Is the human touch overrated: Do customers want to serve themselves online? Or are they demanding human attention when they buy policies and file claims?

sixthings

While ITL serves as a platform for the varied insights and opinions of others, they tend to coalesce around certain themes: on the need to innovate, on the importance of moving faster than the industry historically has, etc. It's not often that I see articles with almost opposite points of view, let alone have them arrive on top of each other, but that's what occurred with two of the six articles I highlight below.

One argues that the human touch is overrated these days, that what clients really want is much more ability to self-service. The other says, among many other things, that "two in three consumers are resistant to the idea of purchasing insurance or filing claims on a website or app without speaking to a human being."

Who's right, and who's wrong? Well, I have my own opinion on that.

Basically, I think that both articles make important points but that the right answer--as you've seen me say many times now about almost all things digital--needs to be a hybrid based on constant, small tests. Those tests will let you gradually find your way to the right approach, for now, and to let you keep adapting as your customers and competitive environment change.

Personally, I'm big on self-service. I have zero interest in talking to an agent of any company about anything if I don't have to. So, I resonate with the statistics in "Human Touch: How Crucial Is It Really?": that "90% of consumers expect a brand or an organization to offer a self-service consumer support portal"; that "today's customers manage 85% of the relationship with an enterprise without interacting with a human"; and that "73% of all consumers say that valuing their time is the most important thing companies can do to provide them with good customer service."

I have no reason to doubt any of those stats, and I suspect that many insurers, while moving in the self-service direction, still lag well behind their customers' desires.

At the same time, as "Customers Wary of AI-Driven Insurance" argues, based on an extensive survey by Policygenius, "despite faster claims turnaround times, the potential for lower rates and other AI-enabled transformations, customers still value a human touch." The survey found that "83% of consumers wouldn’t feel comfortable if their home, auto, or renters insurance claim was reviewed exclusively by artificial intelligence" and that, after a loss, only "around 43% of homeowners would agree to let a drone evaluate their property rather than a human." Policygenius also reports that "72% of consumers wouldn’t be comfortable purchasing insurance online without ever speaking to a real person, and 64% wouldn’t feel comfortable filing a claim on a website or app without human interaction."

If you pay attention to all the stats, you can find your way to a middle ground. You let customers handle as many of the routine matters on their own as possible--updating policies, determining when a payment is due, etc. But you make sure a human is always on call, at least during business hours, and you introduce a human into every process that might require advice or any sort of emotional support, whether that's as fraught as filing a claim might be or as straightforward as assuring someone they've made the right choices as they've done research and chosen insurance coverages online.

But that's just the broad outlines of a hybrid. There's a lot of play in the details. Preferences will vary based on the age of the client, the income, the education level, the location, the... who knows what else?

The best way to see what customers want is to offer them options and then watch and listen to how they react. Do agents need to be monitoring all changes that clients make to their policies online, including to coverages, or just some? Is there some way to give clients freedom online but then ping agents about where they might way to follow up? What is the best way to help people do their own research online while introducing agents at just the right time and in just the right way to turn a search into a sale?

I encourage you to click on and read the first two articles below so you can make up your own mind. But my mantra on innovation for 25 years has been, Think Big, Start Small, Learn Fast. So, while I think the statistics in the articles are very helpful--I wouldn't have published them otherwise--they're just the starting point. The only way to learn what the right answer is for you is to test and learn, then test and learn some more and some more and some more.

Cheers,

Paul


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Consumers Wary of AI-Driven Insurance

83% of consumers wouldn’t feel comfortable if their home, auto, or renters insurance claim was reviewed exclusively by artificial intelligence.

The property and casualty insurance industry is turning to artificial intelligence (AI) to solve its most pressing issues. Record catastrophe losses created a demand for AI-driven climate models to better predict and manage risk. The pandemic accelerated investment in touchless consumer-facing technology like AI claims processing and remote inspections.

This past August, our team at Policygenius ran a survey to gauge consumer comfort around new tech being deployed by some insurance companies. The survey found that, despite faster claims turnaround times, the potential for lower rates and other AI-enabled transformations, customers still value a human touch.

A few other key findings from the survey include:

  • 83% of consumers wouldn’t feel comfortable if their home, auto, or renters insurance claim was reviewed exclusively by artificial intelligence.
  • Around two in three consumers are resistant to the idea of purchasing insurance or filing claims on a website or app without speaking to a human being.
  • 58% of drivers said they wouldn’t use an app that collects data about their driving behavior and location, even if this resulted in significant savings.
  • 55% of homeowners said they wouldn’t install smart home devices that collect personal data, even if doing so earned them lower home insurance rates.
  • After a loss, around 43% of homeowners would agree to let a drone evaluate their property rather than a human.

See also: Survey Data Is Your Secret Weapon

Consumers still appreciate a human touch

Despite the increasing shift toward digitized insurance, customers in all age ranges still prefer the human element when it comes to purchasing coverage and filing claims. 

The survey found that 72% of consumers wouldn’t be comfortable purchasing insurance online without ever speaking to a real person, and 64% wouldn’t feel comfortable filing a claim on a website or app without human interaction. 

Claims reviews by artificial intelligence have skyrocketed in recent years as a means of cutting down on fraud and expediting the process. But just 17% of consumers said they’d feel comfortable if AI reviewed their claim from start to finish. Almost 60% said they were so uncomfortable with this scenario that they’d take the additional step of switching insurance companies to avoid start-to-finish AI claims.

Privacy concerns outweigh financial savings

Telematics and smart home tech can lead to lower premiums and risk reduction. But our survey found consumers haven’t fully embraced these products. 

Around 43% of drivers said they’d use an app that tracks their driving behavior and location if they were offered a discount. But 74% of those drivers said they’d only use such an app if it lowered their rates by more than half.  

These privacy concerns extend to homeowners and renters. Just 32% said they'd install a smart home device that collects personal data, even if doing so reduced their home or renters insurance rates by more than half. And 67% said that no home or renters insurance discount would be worth installing a smart doorbell camera that shares facial recognition data with third parties.

Consumers not ready for big tech to insure their home or car 

Consumers are also wary of the possibility of a major tech company expanding into P&C insurance. Two in three consumers said they wouldn’t be comfortable with a company like Amazon insuring their home or car, with 40% saying it would make them very uncomfortable.


Pat Howard

Profile picture for user PatHoward

Pat Howard

Pat Howard is a managing editor and licensed home insurance agent at Policygenius, where he specializes in homeowners insurance. His work and expertise has been featured in MarketWatch, Real Simple, Fox Business, VentureBeat, This Old House, Investopedia, Fatherly, Lifehacker, Better Homes & Garden, Property Casualty 360, and elsewhere.

Human Touch: How Crucial Is It Really?

According to Gartner Predicts, today’s customers manage 85% of the relationship with an enterprise without interacting with a human.

featured
|||

Building a strong client base is the goal of every business, and providing good customer service is key to accomplishing it. The insurance industry has traditionally believed that good service means providing the human touch, with agents and office staff readily available to answer questions, make policy changes and process payments. But is this what your clients want and need?

As stated in Parature’s 2015 Global State of Multichannel Customer Service Report, 90% of consumers expect a brand or an organization to offer a self-service consumer support portal. In fact, according to Gartner Predicts, today’s customers manage 85% of the relationship with an enterprise without interacting with a human. How does this compare with your organization? If you aren’t providing your clients top-quality digital service, here’s why you need to do it now. 

Saving Customers Time

Nearly three-quarters (73%) of all consumers say that valuing their time is the most important thing companies can do to provide them with good customer service, as reported by Forrester. Why? Because people are busy, and small business owners are no exception. That’s why they look for and expect the ability to manage their policy when it’s convenient for them. This means they always want easy access to their policy and billing documents and from any place. Business owners’ needs don’t stop at 5 p.m. when your office closes. Customers expect and want to be able to manage their policy, obtain proof of insurance, make payments and more, 24/7. With digital service, they can.

Promoting Customer Satisfaction

Clients who feel in control of their policies tend to be more satisfied with their purchases, which can improve retention.

When you save your clients time and effort and give them the information and easy access to their accounts when they want and need it, you reinforce your value to them, as well as differentiate yourself from the competition. That’s good customer service!

But we all know that not all digital experiences are the same. At Insureon, for instance, we aim to partner with carriers with digital service centers to reinforce value and increase ROI.

See also: Building a Digital Field of Dreams

Increasing Your ROI

When your clients use a digital app to manage their policies and make payments, you have more time to spend on activities that can help you build your business or work on more complex service needs. So, digital services are a win for you, too. 

Changes in technology affect the way we live, and the buyers of insurance are no different than anyone else. As business owners, we need to meet our customers where they are and give them what they want.

Tech Is Changing in Personal Lines

Insurers currently favor digital capabilities that replace face-to-face interactions – continuing a trend that emerged early in the pandemic.

Policyholders faced innumerable challenges within the past two years, resulting in unprecedented changes to their consumer behavior. Personal lines insurers responded swiftly to meet insureds’ new and evolving needs. They went all-in on digital self-servicing capabilities for customers, agents and employees, but recent market activity suggests that insurers’ top technology priorities of the past year may be different in 2022.

New research from SMA shows that the plans and progress of some transformational technologies are accelerating as others have hit the brakes. The “Transformational Technologies in P&C Personal Lines: Insurer Progress, Plans and Predictions for 2022 and Beyond” report offers a glimpse into which technologies have the most activity in the industry, where insurers are investing and what insurance executives think about the potential of the technology to transform their businesses.

Of the 13 technologies deemed transformational in the report, including AI-related innovations and others that fall outside of the AI family, six are seen as having a short-term impact on personal lines, yielding significant changes to business operations and the customer experience. The report also examines technologies in the mid-term horizon that are expected to become more mainstream in the industry in the next two to three years and long-term horizon technologies.

Personal lines insurers are currently reprioritizing their plans with a blend of investment activity and maturity levels. Research shows insurers currently favor digital capabilities that replace face-to-face interactions – continuing a trend that emerged early in the pandemic. One example of a technology under rapid development is virtual payments. Nearly seven in 10 personal lines insurers report investing in digital payment technologies during the pandemic, including mainstream services like Venmo and Zelle and insurance-specific vendors. While the initial focus has been on inbound payment solutions, SMA observes that piloting and implementation of outbound claims payment solutions are already beginning to expand.

See also: 2022 Resolutions to Foster Innovation

When looking at long-term transformational technologies, 5G/edge computing shows increased promise in personal lines, with more insurers reporting interest in the technology now than in previous studies. Many of the possibilities related to the Internet of Things, autonomous vehicles and new user interaction technologies, and others will depend highly on the widespread availability and adoption of 5G. As the technology becomes more widely adopted, it is likely to move to the mid-term horizon before becoming a short-term technology.

As the pandemic continues to play out and a post-COVID era emerges, personal lines insurers will continually need to review and revise their technology strategies and plans. The move toward broad-based digital capabilities will require insurers to understand how specific technologies contribute to digital transformation and how priorities and road maps are changing in the current environment.

For more information on how personal lines insurers plan to make use of these technologies, see SMA’s recently published research report: “Transformational Technologies in P&C Personal Lines: Insurer Progress, Plans and Predictions for 2022 and Beyond.”


Heather Turner

Profile picture for user HeatherTurner

Heather Turner

Heather Turner is the lead research analyst at Strategy Meets Action.

Turner supports SMA's advisory and consulting engagements through rich written content, quantitative and qualitative primary research, market and technology trend analysis and the management of SMA IP materials.

Prior to SMA, Turner was managing editor of the NU Property & Casualty Group at ALM, which includes the insurance industry publications PropertyCasualty360.com and NU P&C and claims magazines. She started her career as a journalist reporting on the property and casualty insurance industry at Insurance Business America and its sister publications in Canada and the U.K. 

Hospitality Industry Faces New Risks

Keeping hotel guests and restaurant and bar patrons safe is just one part of how the hospitality industry can move toward full recovery.

featured

In response to COVID-19, the hospitality industry has stepped up its tech investment to facilitate safer guest interactions and cut costs. For example, some hotels have swapped out front desks for check-in kiosks as smart phones increasingly drive contactless guest interactions.

But keeping hotel guests and restaurant and bar patrons safe is just one part of how the hospitality industry can move toward full recovery. There remains a huge shortage of workers, and employers must keep their existing employees safe from the remaining threat of COVID-19.

And perhaps the most troubling risks have been linked to technology — cybercrime in particular.

Cyber risk skyrockets

Two of the worst data breaches of 2020 were at hotel chains: Marriott (the personal information of 5.2 million guests) and MGM Resorts (compromising the records of 10.6 million guests). 

Cyber insurance premiums are rising as much as 30%, so hotels having strong cyber security can benefit with reduced premiums.

To start, hotels need basic protections like firewalls, antivirus software and regular system backups, with dual authentication and virtual private networks providing additional layers of protection. For these measures to be effective, employers must train staff on cyber security.

Regular outside system audits will spot holes in a security plan. And because vendor lapses may cause breaches, checking and auditing vendors’ cyber security practices should be part of a cybersecurity plan.

See also: The Bigger Picture of COVID-19 Data

Step up training

Cybercrime is not the only risk hospitality operations must confront, and training and educating staff on how to recognize reemerging risks is critical to keep any hospitality operation functioning.

Keeping workers and patrons safe from COVID-19 remains paramount. Vaccinations cannot fully protect individuals, as evidenced by breakthrough cases of the virus infecting those who are vaccinated. One well-documented outbreak occurred in a vacation spot with high vaccination rates. Keeping workers masked is important to protect employees and patrons.

There are other risks, as well. For instance, any establishment serving alcohol must remember that, in many states, they are held responsible for the actions of those who become intoxicated at their establishment. In some states, general liability policies do not cover this liability, but it is covered under separate liquor liability insurance.

As patrons may overindulge at times — especially as many haven’t been to bars and restaurants or taken vacations for more than a year — it’s important to update policies about serving alcohol and help servers learn how to minimize the risks. Part of this includes coaching staff on common signs of inebriation and on their right to refuse service.

Another risk in hospitality: the labor shortage. However, offering benefits, especially health insurance, can be an enormous advantage to attract and retain employees in hospitality.

As the hospitality industry continues to come back from a long, hard pandemic year, it’s important to keep in mind that the work is far from done. "Prevention" and "training" are the operative words to offset risks.

Ready...Set...Grow!

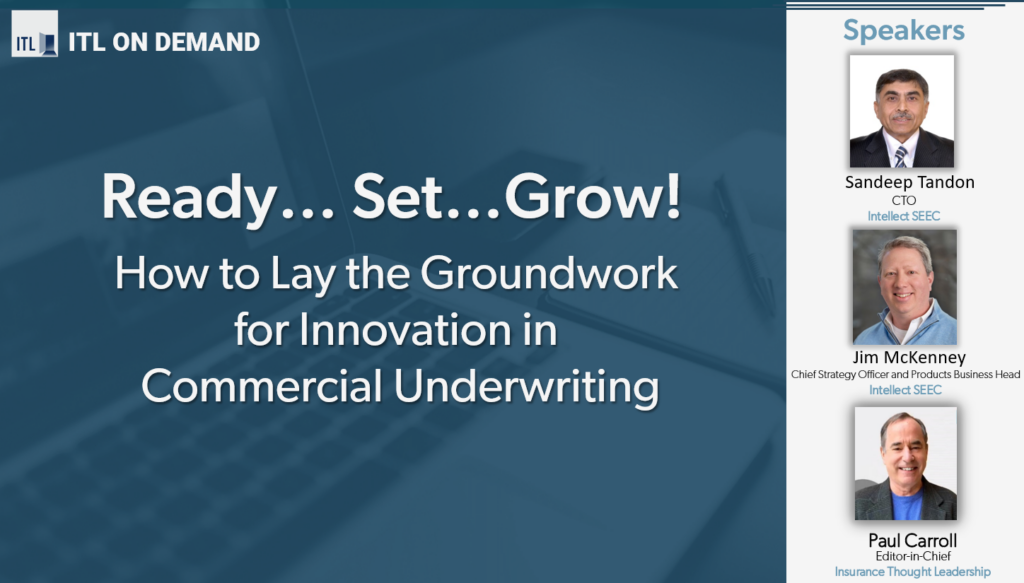
In this webinar, ITL Editor-in-Chief Paul Carroll sits down with Jim McKenney, chief strategy officer and products business head at Intellect SEEC, and Sandeep Tandon, CTO of Intellect SEEC.

sixthings

In this webinar, ITL Editor-in-Chief Paul Carroll sits down with Jim McKenney, chief strategy officer and products business head at Intellect SEEC, and Sandeep Tandon, CTO of Intellect SEEC. They discuss how companies can lay the groundwork for modernization and innovation by reconfiguring their approach to core systems.

You will learn:

--Why changes in the business environment require a modernized approach to underwriting

--How you can vastly increase the speed at which you deliver capabilities and new systems - cutting deployment times to hours or days, from weeks or months, while delivering a clear ROI

--Why you should think in terms of microservices and application programming interfaces (APIs), decoupling capabilities from core systems so they can be deployed flexibly across the whole enterprise

--How to make better buy-vs-build decisions


Sandeep Tandon

Intellect SEEC, CTO, Americas

Sandeep is passionate about technology with strong capabilities in architecting solutions for banking and insurance. He has been recognized for delivering top-level technology experiences across business segments and consistently delivering customer focused solutions. He is experienced in visualizing and capturing the transformational potential of emerging technologies.
In his 30+ years of experience working with global banks and insurance companies, Sandeep has demonstrated success in delivery of large-scale projects through the initial specification, design, development and implementation phases. His understanding and knowledge of the industry and technology has allowed him to successfully provide thought leadership to customers through innovative solutioning/consulting. Sandeep brings an extensive ability to connect business and technology to create solutions that result in value creation.

Jim McKenney


Intellect SEEC, Chief Strategy Officer and Products Business Head


Jim McKenney is Chief Strategy Officer and Products Business Head at Intellect SEEC. Jim is an experienced insurance executive, spending 18 plus years in various roles for Liberty Mutual Insurance. Most recently, Jim led Liberty's Product and Underwriting organization for the mid and large commercial segment. Prior roles include experience in small commercial underwriting segments and in various finance roles. Jim is a certified public accountant and graduated from the University of MA Amherst.

Paul Carroll


Editor-in-Chief, Insurance Thought Leadership


Paul is the co-author of “The New Killer Apps: How Large Companies Can Out-Innovate Start-Ups” and “Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years” and the author of “Big Blues: The Unmaking of IBM”, a major best-seller published in 1993. Paul spent 17 years at the Wall Street Journal as an editor and reporter. The paper nominated him twice for Pulitzer Prizes. In 1996, he founded Context, a thought-leadership magazine on the strategic importance of information technology that was a finalist for the National Magazine Award for General Excellence. He is a co-founder of the Devil’s Advocate Group consulting firm.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

What Is 988? Future of Crisis Services

There will soon be a three-digit hotline for mental health emergencies -- 988 -- that will greatly simplify and improve assistance.

Coming soon... A three-digit hotline for mental health emergencies

Crisis services use has increased year after year as accessibility improves and people are more aware of their benefits. Established in 2005, the National Suicide Prevention Lifeline has answered over 12 million calls. The Crisis Text Line, founded in 2013, has responded to over 5 million conversations. Given the ever-emerging technology and science surrounding crisis intervention, these services are continually evolving. Training and accreditation processes improve standards, professionalism and quality assurance.

What is the New Movement to 988 Crisis Hotline?

In many ways, I am encouraged by moving our mental health crisis support to the 988 call system. First, 988 is much easier to remember than 800-273-8255, so access to qualified mental health crisis supports should increase significantly. Second, with the appropriate infrastructure and funding support required to make this successful, the shift to 988 symbolizes the importance of mental health crisis support. 911 responses to community safety will be on equal footing in importance to the 988 mental health crisis responses. Third, I hope that this shift to 988 also means a shift in the way crisis services are delivered:

  • Less reliance on a law enforcement response and increased engagement with peer support
  • Less fear and more compassion

Finally, the development of 988 will bring a much-needed coordination of services similar to air traffic control. So, people will have a better chance of getting matched to the right level of service.

For a full explanation see: https://crisisnow.com/

There are also excellent talking points in this video: https://youtu.be/M6BPxH09tqU

In late 2019, a law to create a three-digit number for mental health emergencies came into effect. It will pave the way for more support, implementation and adoption of the 988 number many call centers already use, and make it easier for people in distress to get the support they need.

More Accessible

A simple three-digit number is easier to remember and dial during mental health emergencies. In addition, the branding of the new crisis response will go beyond just support for people experiencing suicidal despair and will include all psychological emergencies and even emerging mental health hardships. The design of the new system is intended to help facilitate a warm-handoff connection to qualified supports and to follow up to make sure those referrals are a good fit.

See also: New Guidelines for Preventing Suicides

Stable Funding

To work, funding and infrastructure support need to be commensurate with the scope of the shift to 988. This will resolve the funding issues that make it hard for local crisis centers to respond to callers through the current line.

Taking the National Suicide Prevention Lifeline as an example, there is a general misperception in the community about how the Lifeline works. While the leaders of the Lifeline call center system are under one umbrella, each call center is responsible for its own funding and operation. As the calls to the Lifeline have swelled each year, the call centers have been left to manage the load with minimal margins. The increased support required by the shift to 988 will give the call centers a fighting chance to be sustainable. 

Less Fear, More Care

The 988 line will significantly reduce the numerous problems arising from calling 911 during mental health crises and help people get the assistance they need.

911 usually activates a law enforcement response. Law enforcement is best-suited to take control of chaotic and life-threatening situations. The skills and mental abilities of law enforcement under these circumstances are NOT best when responding to someone having a mental health crisis. Many police officers can feel out of their element when responding to people who are despondent, grieving, traumatized or highly anxious.

Additionally, for communities of color or for transgender people, a 911 call can often escalate to violence, regardless of the nature of the call. People of color living with mental health conditions are much more likely to be detained than white people. Thus, they are highly reluctant to call 911.

988 will link people to crisis responders trained to help them cope with and feel supported and understood during suicidal intensity and other mental health challenges. They’ll get the assistance and care they need instead of becoming embroiled in aggressive altercations with the law or ending up in institutions ill-equipped to help them recover. So, calling for help will connect them to people trained to listen empathically and provide accurate information and referrals instead of worsening their situations.

Help During the Transition

The line won't be available for another year. Given the mental health crisis caused by the pandemic, that's disheartening and distressing. Policy and funding changes that could help significantly during this transition include:

  1. Establishing mobile crisis response teams in every community
  2. Establishing LOSS teams in every community for suicide “post-vention” support
  3. Establishing peer respite centers in more regions for people experiencing mental health challenges who do not need urgent care
  4. Encourage the continued development and evaluation of technology (e.g., virtual peer support, apps for peer support)

Looking Forward: Additional Advancements

988 call centers need to not only be prepared to support people experiencing suicidal intensity but also people affected by suicide death. Many crisis call centers would benefit from specialized services addressing the complicated trauma and grief suicide brings. 

See also: The Long Haul for Mental Health at Work

Integrating more people with lived experience with suicide and mental health crises will be essential in 988's effectiveness. The voices of people who have been there give us tremendous insight into what works and what doesn’t – when the focus is on helping people. What the wisdom of people with “lived expertise” tell us is that we will all be better off moving away from a fear-based approach and toward one built on upholding dignity, collaboration and compassion.

The new law is a significant and positive development. It promises an opportunity to reduce the bias of mental health issues and people fighting through them. Three simple numbers—988—send an unspoken message that these emergencies are legitimate and require a different kind of care and vigilance.

You can read about the new law here.


Sally Spencer-Thomas

Profile picture for user SallySpencerThomas

Sally Spencer-Thomas

Sally Spencer-Thomas is a clinical psychologist, inspirational international speaker and impact entrepreneur. Dr. Spencer-Thomas was moved to work in suicide prevention after her younger brother, a Denver entrepreneur, died of suicide after a battle with bipolar condition.

Commercial Insurers Shift Tech Priorities

13 “transformational” technologies, working with foundational technologies, are moving the industry into the new digital-connected era.

It is difficult to imagine where digital business operations would be today if it wasn’t for the catalyst that is the pandemic. For nearly two years, businesses across industries, and especially within insurance, accelerated digital transformation plans to adapt to remote access for customers and employees. Insurers prioritized many self-service capabilities, such as virtual inspections, digital payments and automated workflows, while also focusing on investing in artificial intelligence (AI), the Internet of Things (IoT), new user interaction tech and other advanced technologies. However, as the effects of the pandemic continue to play out, market activity indicates commercial lines insurers are reprioritizing their tech-oriented projects, with some plans continuing to move forward while others have slowed down.

Today, there are 13 “transformational” technologies working with foundational technologies, such as core systems, portals and CRM systems, to move the insurance industry into the new digital-connected era. A new SMA research report, “Transformational Technologies in P&C Commercial Lines: Insurer Progress, Plans and Predictions,” examines these technologies and how they will affect commercial lines insurers now and in the future.

Commercial lines insurers are approaching both AI-related and non-AI-related transformational technologies at varying levels of investment and rates of adoption. Over the years, SMA has monitored these technologies, organizing them into three strategic planning horizons: short-term, mid-term and long-term.

In 2022, computer vision, IoT, machine learning (ML), natural language processing, robotic process automation, user interaction tech and virtual payments will continue to garner significant activity and yield a high impact on commercial lines. However, some insurers indicate they are decelerating their plans for certain short-term technologies. Last year, 51% of commercial insurers said they were in the midst of new implementations of ML solutions, but the plans through 2022 show only 45% implementing, primarily among Tier 3 and 4 companies. This pullback in building ML capabilities for smaller insurers is mainly due to the events surrounding the COVID health crisis. 

See also: Insurtech Trends for 2022

When looking further into the future, 5G/edge computing, blockchain, AR/VR and autonomous vehicles are expected to have a transformational impact on the industry. Compared with a year ago, more commercial lines executives recognize their potential in certain business segments. For example, the potential for 5G/edge computing increases as the major wireless networks expand coverage and more devices accommodate the technologies. In a 2021 SMA survey, 24% of commercial lines insurers reported that they are monitoring and developing initial strategies around 5G/edge computing, up from just 18% in 2020. A range of areas within commercial insurance can be transformed by 5G, including IoT, autonomous vehicles and new UI technologies. So as the technology becomes more widely adopted, it will likely become a short-term technology for insurers’ planning purposes.

The transformational technologies underway in the industry today will only become more critical as virtual and digital interactions become the norm. Regardless of where commercial insurers are on their digital transformation journey, their strategies must be continually reviewed and revised in today’s ever-evolving technology landscape.

For more information on how commercial lines insurers plan to make use of these technologies, see SMA’s recently published research report: “Transformational Technologies in P&C Commercial Lines: Insurer Progress, Plans and Predictions.”


Heather Turner

Profile picture for user HeatherTurner

Heather Turner

Heather Turner is the lead research analyst at Strategy Meets Action.

Turner supports SMA's advisory and consulting engagements through rich written content, quantitative and qualitative primary research, market and technology trend analysis and the management of SMA IP materials.

Prior to SMA, Turner was managing editor of the NU Property & Casualty Group at ALM, which includes the insurance industry publications PropertyCasualty360.com and NU P&C and claims magazines. She started her career as a journalist reporting on the property and casualty insurance industry at Insurance Business America and its sister publications in Canada and the U.K.