Download

Car Prices Causing Turmoil for Insurers

Used cars are suddenly worth more instead of less. So, for claims in progress, there's a significantly higher payout for fixing and replacing cars.

auto

Great opportunities often arise in times of great change, and that is certainly the case for the auto insurance market.

Used cars are suddenly worth more instead of less - an inversion of the normal depreciation curve is imploding claim reserves at both primary carriers and reinsurers. The price index for used cars has climbed recently at about 70% above the run rate for the last 10 years. The result is that, for claims in progress, there's a significantly higher payout for fixing and replacing cars.

In just the last six quarters, the normal and expected phenomenon of a car getting cheaper as it gets older has been flipped on its head. Data from J. D. Power tracks used car prices in a value index for the fleet on the street under eight years old. Consumers typically secure full insurance coverage for such cars, which are also the kind still under a loan or just recently paid off. We have not seen this extreme price inversion in this century, so actuarial and predictive analytics models have not been trained for this event. Even a portfolio stress test for auto property damage would not expect a 50% to 70% increase in severity.

Many companies are rapidly filing rate increases; more will likely join them. At the same time, many advertising channels are "going dark" so they don't drive sales of a product with high loss likelihood. It may take several underwriting cycles for rate and risk to again reach equilibrium.

The only silver lining is that newer and better VIN data sources have come to market recently at scale. These detailed configuration and specification data permit VIN-personalization where the actual price new and the current street price can reflect the individual build data per VIN. The only way to accurately set total insured value now is to re-value your portfolio/fleet by VIN to see the magnitude of where you already know the direction of the possible loss ratio.

See also: The End of Auto Insurance

For a fleet of 1 million vehicles, append 1 million current prices. Check your TIV. Check your total loss calculator. Check your open reserves. Check your intrinsic diminished value subrogation if that is on your radar. At least when things age for a while, you will have actual data to show your board of directors, the audit committee and the solvency inspector from the DOI. If you are signing your own name to the reserve opinion this year and next, you may feel smart with a frequent append of VIN-to-price for your fleet in each of the next months and quarters. An opinion of magnitude is better with street pricing of actual cash value -- at least until simpler times of downward-trending depreciation returns.

One of the many takeaways from J.D. Power's quarterly auto insurance shopping report is that consumers are seeking value when buying insurance and are open to methods that allow for personalization of policies. Now, it's up to insurers themselves to take advantage of this dynamic and better align their practices to meet the needs and preferences of these consumers while also making sure their own foundation is strong.

NFTs Are Hot; Where Is the Insurance?

While there aren’t yet a slew of policies stepping into the breach to cover NFTs, a new class of policies will manage risk for this emerging market. 

money

NFTs are creating a buzz in the art world. Touted as an innovative way for digital artists to get paid for their work, non-fungible tokens, or NFTs, offer a proof of ownership for things that by definition are intangible. NFTs also represent a whole new world of risk, and with risk comes insurance. 

In some ways, the risks introduced by NFTs are novel, but in other ways they are as old as the insurance industry. And, while there aren’t yet a slew of policies stepping into the breach to cover NFTs, a new class of policies is emerging to manage risk for this developing market. 

Basics of NFTs

An NFT is a nonfungible token. Something that is fungible can be traded for something exactly comparable. A $20 bill is fungible. A Picasso isn’t. 

NFTs are pieces of computer code. They are made up of URLs that point to something in the world – typically a piece of digital art hosted on a server somewhere, along with a metadata description of the thing the NFT represents. 

If someone draws a character on an iPad and then hosts that character on a server, that artist can create an NFT linked to that digital art and then sell it, transferring ownership in a verifiable way. NFTs are tracked through a blockchain ledger, creating a publicly validated chain of ownership. 

The owner of the NFT can store it in their digital crypto wallet and has the right to sell it to anyone else down the line. 

A common confusion is that many people see NFTs as the art itself, but it is better thought of as a “digital deed of ownership.” Just like a deed represents ownership of your home, an NFT represents ownership of something else. While NFTs are often used for digital art, they can be associated with just about anything, even real-world art, baseball cards or real estate. 

See also: The Opportunities in Blockchain

NFT Insurance

Insuring an NFT depends on what in particular you are looking to protect. 

NFT policies can protect the digital asset itself, just like a homeowner’s insurance policy can protect an oil painting. If the art is destroyed, the policy could pay out. 

But that is not the only place where NFT insurance comes into play. The digital NFT – the computer code – could also be insured in case the URL or the metadata is somehow corrupted. 

When an NFT is minted, it comes with both a public key and a private key. The public key is what moves through the blockchain ledger. The private key is your proof of ownership, just like the private key to cryptocurrency, and is necessary to validate ownership or sell it to someone else. 

If that private key is lost, ownership is essentially lost, so an insurance policy can cover this. 

If a hacker gets that private key, they can transfer ownership, essentially stealing ownership of the art, and that possibility, too, can be insured. 

Finally, the ability to transfer the NFT to an heir after death could be insured. 

Most insurers aren’t offering NFT policies at this point. There is a policy offered by Coincover. Some auction houses may also be able to connect high-end buyers with other specialty lines, such as Lloyds.  

NFT best practices

Because of its novelty, there are some unique challenges inherent to NFTs. 

First, setting valuation is difficult. Because the art or property an NFT represents isn’t fungible, there is no market price to establish valuation the way a cryptocurrency can be valued. 

There is also a challenge when it comes to copyright around NFTs. Because NFTs aren’t the art, but rather a proof of ownership of that art, if someone mints a fraudulent NFT it isn’t completely clear who is the crime victim. The artist wouldn’t necessarily have a copyright claim because the art itself wasn’t reproduced. 

The person who bought the bogus NFT could have a fraud claim. It is akin to someone making a fraudulent deed to their neighbor’s house. They can sell that fraudulent deed, but that doesn’t transfer ownership, so the homeowner isn’t necessarily the victim — the person who bought the bad deed is the victim. Now, if someone with a bad deed tries to move in, then the homeowner has a claim, but it isn’t necessarily against the person who sold the deed, but instead against the person trying to move in and take ownership. Needless to say, things can get complicated fast.  

Fraudulent NFTs have been a high-profile problem on some of the public art markets, with fraudsters and even bots minting bogus NFTs and then selling them on the exchanges, as recently reported in insuranceQuotes.com’s 2022 guide to protecting non-fungible tokens. 

So, beyond the question of insurance, there is a large element of buyer beware where prospective buyers need to validate that they are buying something the other person has a right to sell in the first place.

NFT owners also must practice good crypto habits – protect their wallets, protect their private keys and use a custodian to ensure that, if the owner loses the private key, it can still be recovered. 

It is also essential to back up the digital asset in as many ways as possible – on-site, on the cloud, or even through more complex solutions, such as a distributed file system, in case the original is damaged. 

See also: The Defining Issue for Financial Markets

Conclusion

NFTs seem exotic, but protecting art and assets falls squarely within the constraints of typical insurance policies. Even protecting a deed could fall into the realm of title insurance. So, while NFTs themselves are new, the issues are all solvable. 

As the NFT market matures, billions of dollars are expected to flow into this market, so more insurance policies will inevitably emerge. 

But, while those factors fall into place, NFTs will remain an area of huge potential, and potential risk, that will inevitably shake out.

Interview with Sanjeev Chaudhry

As part of this month's ITL Focus on blockchain, we spoke with Sanjeev Chaudhry, founder and CEO of Gigaforce, about how far blockchain has already progressed as a force in the insurance industry and about where it can go from here. 

a blue graphic reading "ITL Focus: An interview with Sanjeev Chaudhry"

ITL:

Blockchain has been a hot topic of conversation for a few years now. How far has the technology progressed?

Sanjeev Chaudhry:

Blockchain is not a new technology, per se. It has been around for a while and has definitely proved its mettle. I'm very confident about the stability of the platform, the stability of the technology and the impact it can have. What we’re trying to do is to bring it to the enterprise world, and we do see some success. We are hearing more buzz in the market than we ever heard before. People want to hear about it and want to talk about it. They’re ready.

ITL:

Can you give us a couple of examples of where blockchain applications are currently in production?

Chaudhry:

Gigaforce is currently focusing on mainly three areas. One is subrogation, another is salvage, and the third is reinsurance. Other companies are specializing in areas like title. Outside of insurance, the financial area is very strong for blockchain, including some of the stock exchanges implementing it for the settlement process.

I think the biggest thing that blockchain is able to do is bring trust, because there's always a history there and always the possibility of audit. You can go back and see all previous transactions.

The blockchain is built on two parts, cryptocurrency and a distributed ledger. Let's say there are three companies involved in a process, and they're part of one transaction. Any update that takes place automatically can get reflected in every ledger that’s part of the blockchain transaction. Let's say there's an uninsured motorist, and money gets collected from that person by a collection agency. The moment that money gets collected, the carrier can know about it. So can in-between parties, like law firms and recovery agencies. There is a misconception in the insurance industry that all the parties have to sign up before being part of the transaction, but a private blockchain operates no differently than Docusign. All you need to be part of a transaction is an enabler like Gigaforce and a browser.

Now let's extend this and look at it from the reinsurance perspective. Once a transaction from a carrier hits the threshold, the reinsurer would like to know each and every update happening on that transaction. Money is just one piece of the information here. Everything, even all the documents exchanged between law firms, is part of a new phase of visibility at the reinsurance level. Now, nobody has to transfer the information manually, on a document-by-document basis. This represents the biggest gain in efficiency.

ITL:

We've come quite a ways in the years I've been following blockchain. Are there other applications that you see becoming possible in insurance sometime over the next year or two?

Chaudhry:

For two years, when I talked with people in the industry about blockchain, they’d say, “We have a hammer; we’re just looking for a nail.”

There’s a whole range of opportunities across the whole spectrum of activities in the industry – distribution management, underwriting, payments, claims, policy administration and reinsurance – although some of the opportunities have trouble gaining traction with management even though they promise efficiencies and better engagement with customers.

I think subrogation should be the first use case because there are multiple partners updating and sharing data, and a sequential process has to be followed in a timely way.

ITL:

What should the industry be doing today to get ready?

Chaudhry:

We suggest companies ask themselves six questions about each of their processes:

  1. Are multiple parties sharing data?
  2. Will multiple parties be updating data?
  3. Is there a requirement for verification?
  4. Is verification adding cost and complexity?
  5. Are interactions time sensitive?
  6. Will transactions by different users depend on each other?

If a company answers yes to four or more of those questions, then the company should consider using blockchain.

When people talk about security, they say you’re only as secure as the weakest link in your chain. The same is true when companies talk about how far along they are with digitalization. If a company only talks about digitalization at the company level, they are not digitized. You’re only truly digitalized if you’re digital all the way down to the level of your processes and subprocesses. You need to go across corporate boundaries, too, so you’re collaborating with all the digital sources out there.

The pandemic has been an eye opener. There were a lot of manual activities that could be done only in the office. That’s where the check would come in, so you’d have to be there to make a copy of the check, turn it into a PDF and send it to the next party involved. Now, because everything is digitized, the moment that a check is collected by the first company, everybody in the chain can automatically know. Nobody has to make a copy, scan, email, mail, etc.

There's also a huge labor shortage in the industry, which puts pressure on companies to automate. And blockchain is a technology that gives you automation right out of the box.

It also cuts costs – we can reduce the cost of claims processing 10% to 15%.

So, I think it’s just a matter of matter of time before blockchain is widely adopted. I don't think there is any choice.

ITL:

That’s great. Thanks, Sanjeev.


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

InsurTech Ohio Spotlight with Ron Rock

Ron Rock discusses how the insurance industry is rapidly evolving, and the importance of recruiting and retaining top software and programming talent. 

a photo of Ron Rock and a blue graident reading "insurtech ohio spotlight with ron rock"

Ron Rock is a Senior Director at JobsOhio, a private nonprofit corporation designed to drive job creation and new capital investment in Ohio through business attraction, retention and expansion efforts.Ron was interviewed by Michael Fiedel, a Managing Director at InsurTech Ohio and Co-Founder at PolicyFly, Inc.

Read the Full Interview


ITL Partner: JobOhio

Profile picture for user JobsOhio

ITL Partner: JobOhio

JobsOhio is a private nonprofit economic development corporation designed to drive job creation and new capital investment in Ohio through business attraction, retention, and expansion. JobsOhio works collaboratively with a wide range of organizations and cities, each bringing something powerful and unique to the table to put Ohio’s best opportunities forward. Since its creation in 2011, JobsOhio and a network of six regional partners have collaborated with academia, public and private organizations, elected officials, and international entities to ensure that company needs are met at every level. As a privately-run company, JobsOhio can respond more quickly to trends in business and industry, implementing broad programs and services that meet specific needs, including but not limited to: Talent Services: Assists companies with finding a skilled, trained workforce through talent attraction, sourcing, and pre-screening, as well as through customized training programs. SiteOhio: A site authentication program that goes beyond the usual site-certification process, putting properties through a comprehensive review and analysis, ensuring they’re ready for immediate development. JobsOhio Research and Development Center Grant: Facilitates the creation of corporate R&D centers in Ohio to support the development and commercialization of emerging technologies and products. JobsOhio Workforce Grant: Promotes economic development, business expansion and job creation by providing funding to companies for employee development and training programs. A team of industry experts with decades of real-world industry experience lead JobsOhio and support businesses by providing guidance, contacts, and resources necessary for success in Ohio.

Use Halo & AI For Claims Processing to Proactively Identify and Mitigate Emerging Fraud

Daisy AI solutions recommend step-by-step implementation of Halo Effects into your fraud detection, claims management and underwriting processes, including useful examples that can be put into practice

a graphic that reads "proactively identify and mitigate emerging fraud"

This whitepaper explores practical steps to incorporate the Halo Effect within your organization - which will proactively identify and mitigate emerging fraud and elevate insurers to focus on their continued success in this pivotal year of business.

Download Whitepaper


Sponsored by Daisy Intelligence 


Daisy Intelligence

Profile picture for user DaisyIntelligence

Daisy Intelligence

Daisy Intelligence is an AI software company that delivers Explainable Decisions-as-a-Service for insurance risk management. Daisy’s unique autonomous (no code, no infrastructure, no data scientists, no bias) AI system elevates your employees, enabling them to focus on delivering your mission, servicing your customers, and creating shareholder value. The Daisy system detects and avoids fraudulent claims while enabling claims automation, minimizing human intervention in claims processing. Daisy’s solutions deliver verifiable financial results with a minimum net income return on investment of 10X.


What Happened to the Insurtech Revolution?

Don't look now, but some of the big insurtech names -- Lemonade, Hippo, Oscar, Root and Metromile -- are having a rough go of it. 

Image
a computer showing a stock's value over a period of time it starts off strong but then decreases as time progresses

We were promised an insurtech revolution, right? Well, don't look now, but some of the biggest names are having a rough go of it. 

Lemonade's stock price is down 81% since its peak in the middle of February, even as the S&P 500 average has climbed 15%. Hippo is down 85% over the same stretch. Root is off 91%. Metromile has plunged 92%. Oscar has tumbled 81% since mid-March.

What happened?

The short answer is: nothing. Lemonade still has a $1.97 billion market capitalization, the sort that most entrepreneurs would kill for. Hippo carries a $1.18 billion valuation; Root, a valuation north of $500 million; and Oscar, a market cap of $1.4 billion. Even Metromile, which is being acquired by Lemonade, carries a price tag of roughly $250 million (half the stated value when the purchase was announced in November because the transaction is all stock and Lemonade's share price has fallen 50%).

Not too shabby.

Yes, some investors have lost money, but as the Cockney saying has it, "You pays yer money, and you takes yer chances." Most of the investors have surely done plenty well elsewhere in a robust investing climate. From a business standpoint, while all certainly face challenges, the insurtech superstars are maturing into sustainable businesses, even if they may not turn out to be the rocket ships to the stars that many assumed a year ago.   

The longer answer is that there has been a resetting of expectations about the role of insurtechs, and this sharp lowering of valuations seems to just be part of that.

At ITL, we've published any number of articles over the years that aimed to temper enthusiasm about some of these "full-stack" startups, which were designed to become full-fledged carriers that competed head-on with incumbents. Like just about everyone else, we were captivated by the charismatic founders, the novel ideas, the crisp use of technology and the friendly user interfaces, but we stayed pretty firmly within the grasp of reality, largely thanks to Matteo Carbone and some colleagues. They wrote occasional articles that cut through the hype and looked at the numbers to see how Lemonade, Root and Metromile were doing as they tried to move up the learning curve on understanding and pricing risks and attempted to keep their early, exponential growth going. Here, for instance, is the latest article on the three companies, from 2020, raising some issues about, in particular, Lemonade and Metromile. 

I, for one, was more surprised at the valuation north of $10 billion for Lemonade and at the peak valuations of the others than I am about today's market caps, which still seem quite healthy to me. The decline makes even more sense when you think about how quick these companies were to enter the public market -- many insiders surely took the opportunity to lock up some serious wealth by cashing out part of their holdings, even if they still believe fervently in the long-term prospects. 

The tumbling back toward Earth of these big-name companies doesn't, for me, indicate anything about the continued opportunities for breakthrough innovations. 

There will always be opportunities for what were known as "arms suppliers" during the internet boom. The term, despite being military, actually originates from the Gold Rush days. While few miners built huge fortunes -- and while I couldn't name you a single famous mining family despite having lived in Northern California for 25 years -- loads of people made bank by "arming" the miners. A guy who sold jeans to the miners is the namesake for the San Francisco 49ers' Levi Stadium. A guy who built railroads that connected the Gold Rush to the rest of the country, and not a miner, has his name on Stanford University up the road. And so on. During the internet boom of the mid- to late 1990s, lots of attention went to the companies that swung for the fences, like Exodus Communications, which became the biggest web hosting company and hit a market value of $32 billion in 2000. But some of the smart folks I knew said at the time that the far safer bet was to be an "arms supplier" like Sun Microsystems, which sold the servers that powered Exodus and so many other companies. Sure enough, Exodus filed for bankruptcy in 2001 and was sold for parts, while Sun sold itself to Oracle for $7.4 billion in 2009.

In insurance, there have been lots of "arms supplier" stories -- RiskGenius folding its AI into Bold Penguin, which was then bought by American Family Insurance mostly for its brokerage platform -- and there will be many, many more.

As you've seen if you've been following this newsletter for any length of time, I also think there is huge opportunity in platforms like Bold Penguin's -- or those of Bolt, Matic, Branch and more -- and in ecosystems of partners that share data and coordinate activities via application programming interfaces (APIs). So, I believe that innovation is just starting to gather steam in the insurance industry, no matter what the hit to some high-profile stocks might suggest.

Cheers,

Paul      

The Need to Offer Better Perinatal Plans

Comprehensive perinatal education helps employers address at least five related opportunities.

The Need to Offer Better Perinatal Plans

For many families, pregnancy and parenthood stir up uncertainty and self-doubt. When a complicated pregnancy and delivery is added to an already overwhelming life transition, it can be incredibly challenging for a new family to adjust to parenthood. A holistic and comprehensive wellness program can help expectant families thrive by developing skills to reinforce a healthy lifestyle. Perinatal wellness education contributes to a healthy pregnancy, a positive birth experience and increased confidence to help them take care of their newborn. Effective perinatal education protocols and resources are evidence-based, clinically vetted and endorsed by a credible organization.

Maternal health continues to be a priority for the U.S. government and healthcare system. It is estimated that 80% of women in the U.S. have healthy pregnancies and deliveries. However, the U.S. is experiencing a rising number of pregnancy and childbirth complications despite a decreasing number of births. 

The U.S. Department of Health and Human Services (HHS) released a plan to improve maternal health in December 2020. Sadly, the study cites 2018 data showing the U.S. maternal mortality rate was 17.4 deaths per 100,000 live births. The study reports this is higher than most other developed and high-income countries. 

The Rising Risks of Pregnancy and Childbirth Complications

According to the National Center for Health Statistics, the number of births for the U.S. decreased for the sixth consecutive year, dropping 4% in 2020 from 2019. This is the lowest rate since 1979. However, a BlueCross BlueShield (BCBS) study released in July 2020 highlights growing concerns with pregnancy and childbirth complications. The rising complications are associated with gestational diabetes, preeclampsia, preterm labor, cesarean deliveries and postpartum mood disorders. 

Impact of Pregnancy and Childbirth on Short- and Long-Term Disability Claims

In September 2020, the International Benefits Institute (IBI) reported pregnancy and childbirth as the leading cause of short-term disability (STD) at 23% of all new claims in 2019. IBI further reported pregnancy and childbirth as the sixth-leading cause of long-term disability (LTD), with 6.8% of new claims in 2019. 

In 2017, UNUM reported positive news from their data that “long-term disability claims for complicated pregnancies have decreased nearly 50% over the last decade.” Major reasons UNUM cited include early interventions to specialty care for high-risk mothers, improved prenatal education and reduced deliveries by caesarean section resulting in fewer surgical and post-operative complications. 

Pregnancy Risk Growing Due to Increasing Chronic Health Conditions

BCBS conducted a major study of 1.8 million pregnancies between 2015 and 2018 among their insured population. A significant finding of this research showed an increasing number of women are experiencing pregnancy complications and childbirth complications. During the study period, there was a 32% increase in the number of women experiencing complications relating to both the pregnancy and also during childbirth. 

See also: Surest Path to Healthy Prospect Pipeline

The major finding of this study determined a growing prevalence of chronic physical and behavioral health conditions before becoming pregnant. Pre-existing conditions increase the risk of pregnancy complications and childbirth complications. BCBS data revealed the largest increases were attributable to diagnosed obesity and major depression. The data table below captures the percentage increases of the major existing chronic physical and behavioral health conditions: 

Exhibit 1: Prevalence of Pre-Existing Conditions Prior to Pregnancy  (Rate per 100 Pregnancies) 

This image has an empty alt attribute; its file name is image-2-1024x328.png

Source: BlueCross BlueShield. Trends in Pregnancy and Childbirth Complications in the U.S. https://www.bcbs.com/the-health-of-america/reports/trends-in-pregnancy-and-childbirth-complications-in-the-us 

The BCBS study further revealed the number of women diagnosed with postpartum depression (PPD) is rising. In fact, nearly one in 10 women who delivered a baby in 2018 was diagnosed with PPD. That number increased 29% from 2014. The study highlighted a relationship between PPD and pre-existing behavioral health conditions. These findings reinforce the need for perinatal education before, during and after delivery, especially with the growing reports of stress, anxiety, depression and substance misuse during the pandemic. 

Although the study period predated the onset of the COVID-19 pandemic, the report included several important effects the pandemic has had in disrupting expected delivery of prenatal care. These disruptions included patients missing vital prenatal care during the first trimester, a high percentages of prenatal care sessions being skipped or shifted from in-person to virtual sessions, as well as patients completing fewer than the recommended 10 prenatal visits. 

Examples of Disparities in Maternal and Infant Outcomes by Race and Ethnicity

In 2020, the CDC reported that one in 10 infants were born pre-term, meaning they were delivered before 37 weeks of pregnancy was completed. (A full-term delivery is 40 weeks gestation). However, there are racial and ethnic disparities in pre-term labor rates, especially among Black women, with 14%, compared with 9.8% for Hispanic women and 9.1% for white women. 

According to HHS, pregnancy-related mortality for Black Americans and American Indian and Alaska Native women are about three and two times higher, respectively, compared with white, Asian/Pacific Islander and Hispanic women. According to the National Vital Statistics Report, infant mortality has declined 17% since 1995 in the U.S., and 2018 marked the lowest mark of infant mortality ever at 5.67 per 100,000 live births. 

However, higher infant mortality rates are another area of racial and ethnicity disparity relating to pregnancy as reported by the CDC for 2018:  

This image has an empty alt attribute; its file name is image-3-1024x411.png

The Importance of Perinatal Education to Reduce Pregnancy and Childbirth Complications

More expectant mothers are using the internet, social media and smart phone apps to seek information about pregnancy and infant care. There is concern that mothers are missing a full spectrum of information when they are only looking at parts and not the whole. For example, they may only focus on the development stages of the fetus but miss exercise and nutrition recommendations. Likewise, they could be concerned about gestational diabetes and overlook hypertension or cardiovascular risk factors. 

And with all the incomplete or misguided information available today, expectant parents are not sure what to expect, what advice to follow or what information to believe. It is natural for them to feel anxious. With an online comprehensive perinatal wellness program, expectant families get everything they need, not just pieces of a puzzle. They get an entire roadmap for maternal, infant and family health. Ideally, a perinatal program should have an online community (unconnected to social media) that is moderated by a team of clinicians to prevent misguided information and to keep things focused and private within the group. The platform should be HIPPA-compliant, secure, and encrypted.

5 Ways Perinatal Education Is a Strategic Workplace Employee Benefit 

Comprehensive perinatal education helps employers address at least five related opportunities:  

1. Human Resources Talent Recruitment and Retention

During the war on talent due to the shrinking workforce, employers are increasingly focused on ensuring benefit offerings are viewed favorably as competitive and best in class. Employees are seeking innovative health and wellness benefits focused on improving their personal lifestyle. Such programs help shape the perception of the company as an employer of choice.  

2. Organizational Culture Focused on Diversity, Equity, Inclusion and Belonging (D/E/I/B)

Perinatal education can be an effective tool for employers to address D/E/I/B among their employees. An effective perinatal education platform levels the playing field among sub-populations of employees by addressing existing inequities in health outcomes among high-risk populations. As companies increase the use of employee resource groups, greater emphasis is being given to starting new mothers groups and expanding parent mentoring programs. 

3. Removing Barriers and Improving Access to Care 

An effective strategy being used by employers is requesting employee assistance programs (EAPs) to embed perinatal wellness education for expectant mothers and parents as an employee benefit. This is an excellent way for employers to increase use of their existing EAP by improving access to care and moving behavioral health upstream toward earlier interventions. 

4. Risk-Reduction Strategy 

Perinatal education programs serve as a risk-reduction method by improving preventive screening. Early interventions for smoking cessation, high blood pressure, obesity and weight management, gestational diabetes, depression and substance use disorders improve maternal health and reduce risks of pregnancy complications. Risk reduction is especially important in populations experiencing health disparities.  

5. Healthcare Cost Containment

Perinatal education programs are effective at achieving healthcare cost containment by promoting both stay at work and return to work by teaching healthy prevention techniques. The reduction of complications in pregnancy and childbirth result in significantly reduced healthcare expenditures. For example, the BCBS data revealed “pregnancy complications increase the average cost of a vaginal delivery by 16% and a C-section delivery by 18%, while childbirth complications increase the average cost of these deliveries by 63% and 52% respectively.” 

See also: 2022 Will Challenge Health Insurers

Conclusion

Offering comprehensive perinatal wellness education is an important employee benefit strategy. Perinatal wellness can address a broad range of organizational and cultural objectives. At the same time, such programs offer a low cost and potentially high return on investment by targeting risk reduction and cost containment. 

Data shows the human capital and financial stakes of complications in pregnancy and childbirth have risen. Thinking about the multiplier impact of the pandemic on these data trends is concerning. Now is the time to consider investing in a comprehensive perinatal educational program to coach expectant mothers to adopt lifestyle choices to reduce chronic health conditions contributing to pregnancy and childbirth complications.


Calvin Beyer

Profile picture for user CalBeyer

Calvin Beyer

Cal Beyer is the vice president of Workforce Risk and Worker Wellbeing. He has over 30 years of safety, insurance and risk management experience, including 24 of those years serving the construction industry in various capacities.

Ready for New Accounting Standard?

IFRS 17 might be a major factor in insurers’ decisions on buying reinsurance, so it's important to understand key issues and start preparing. 

reinsurance

Insurers buy reinsurance for a variety of reasons, but an insurer’s accounting rules and solvency regulations are inevitably at the heart of the decision. Whether they are primary drivers or simply help insurers judge acceptable pricing for a risk- or service-motivated transaction, these rules and regulations are a key part of the equation.

IFRS 17 is the imminent new global accounting standard for insurance (outside the U.S.), and a few countries also link solvency regulations directly to IFRS. It is therefore natural to think IFRS 17 might be a major factor in insurers’ reinsurance buying decisions. To prepare for this, RGA has met with life and health insurers around the globe over the past several years to better understand and predict how those decisions might eventually change.

The transition from IFRS 4 to IFRS 17 could be different in every country and for every insurer, but there are clear, recurring themes. This article will explore those themes and share some of the related insights RGA has gained in the process leading up to IFRS 17, as well as the challenges insurers are experiencing as they adjust to the new standard.

Recurring Insurer Themes

IFRS 17 requires the adoption of a prospective economic valuation method for insurance liabilities with an updating of the assumptions in the valuation at each future reporting date.

The feedback gained from clients globally when discussing IFRS 17 revealed three major areas of concern about the new standard:

  1. Cost and complexity of implementation, including data collection, IT systems development and management processes
  2. Volatility in earnings over time due to use of current assumptions
  3. Slow pattern of expected earnings emergence

IFRS 17’s prospective economic valuation has entailed costly and challenging implementation efforts for insurers, especially life insurers. Paradoxically, IFRS 17 first required insurers to focus on the past to collect large amounts of data and to recreate history to project the future based on IASB beliefs. Needing to then perform individual policy level projections repeatedly is the next-level challenge. IFRS 17 also requires companies to track, recalculate and amortize assorted values (e.g., “loss component” and “contract service margin”), which have complex links to other values at different times. The final challenges will be understanding, explaining and ultimately using these outputs. These combined challenges have proven formidable and caused the cost of implementation projects to grow beyond original budgets. Bemoaning this ever-expanding cost and complexity has become a constant refrain from insurers in the global IFRS 17 environment.

See also: Health Issues: a Rising Economic Threat

Only after companies make significant progress in implementing IFRS 17 systems are they typically ready to start meaningful discussions on the IFRS 17 accounting values. At this stage, volatility in earnings is a consistent complaint. This volatility boils down to two items:

  1. The period-to-period fluctuations in the total income statement (consolidated statement of comprehensive income) as assumptions are updated and experience emerges
  2. Division of the total income statement into the consolidated statement of profit or loss (P&L) and other comprehensive income (OCI), thus separating financial data that belong together and causing P&L volatility

Once companies understand the sources of this volatility and try to minimize it, they typically express dissatisfaction with the inherent pattern of IFRS 17 earnings emergence. Though this overlaps somewhat with the problem of volatility, there is indeed a distinct issue and underlying cause here. The core issue is that IFRS 17’s foundational beliefs and chosen methods lead to slow earnings emergence.

IFRS 17 Fundamental Observations

After receiving feedback from many clients over the years about their challenges and frustrations with IFRS 17, RGA has explored a range of potential solutions. In the process, we have deepened our own understanding of IFRS 17, investigating the foundations of the standard to consider its implications. Based on that journey, we believe the recurring insurer themes derive from an incompatibility between IFRS 17 design elements and the insurance environment. 

A broader, clearer understanding of these underlying issues will allow companies to determine which problems to tackle and how to solve them. While reinsurance solutions will help address new IFRS 17 issues, much of the transition will require familiarizing internal and external stakeholders with earnings patterns that simply look different but are fundamentally neither better nor worse than those seen before IFRS 17.

1. Beliefs of IFRS 17 authors

Volumes have been written on IFRS 17’s creation, but the following paraphrased subset of International Accounting Standards Board (IASB) beliefs underlying IFRS and IFRS 17 is most relevant to this article:

  • Insurance profit should be recognized gradually over time, as insurance services are delivered. Conversely, no profit should be recognized at inception (because no insurance services have been provided).
  • The income statement can be split into two parts (i.e., P&L and OCI), one of which (P&L) is more relevant to evaluating management’s performance and the other of which (OCI) is much less so.
  • Some investment results should be separated from overall insurance product results and shown in the “less accountable” (OCI) section of the income statement.

 2. Wishes of IFRS 17 users

Investors naturally wish to own businesses that generate profits in ever-increasing amounts with no surprises. IFRS P&L is one of their tools to evaluate performance of managers in this area. Company managers naturally wish to demonstrate they are delivering on expectations and running their businesses in a way that produces healthy accounting profits every period and leads to predictable increases in subsequent years.

3. Reality to which IFRS 17 applies

Two elements are notable. First, life insurance products globally are predominantly savings vehicles versus simply serving as a means of risk protection. Owners of life insurers offering savings vehicles expect a material portion of total profits to come from investment performance, and that their managers will operate the overall business to optimize this performance. 

Second, applying a prospective economic valuation framework to insurance liabilities reveals that these values are very sensitive and that capturing the corresponding change in assets supporting those liabilities is necessary to achieve stability.

Considering these three elements in relation to the client themes discussed earlier, one can construct the following arguments:

  • “Value” and “performance” are two distinct measures, and having both clearly and correctly captured by one insurance measurement system may be too much to ask for.
  • Volatility is inherent on both sides of an insurance balance sheet under prospective economic valuation, and even well-managed portfolios may show material net volatility that will be difficult to keep out of the P&L statement.
  • IFRS 17 effectively contains two compounding levers to defer investment profits on typical life insurance savings business, so this business will naturally have a very long profit signature.

Value Versus Performance

The clear focus of IFRS reporters and their investors is P&L, which is used to measure performance. Much less attention is paid to the IFRS balance sheet, and those who do start with the balance sheet to assess company value inevitably make fundamental adjustments. (A topic for another day is the degree to which IFRS 17’s contract service margin (CSM) and risk adjustment (RA) might reduce the need for analysts to make these adjustments.) Most of the newest life insurance solvency regimes – which are essentially measuring the value of the business in different scenarios – created their own prospective economic balance sheets instead of using that of IFRS. 

The most prominent of these regimes is Solvency II, which does not include an income statement. This makes us wonder whether an economic balance sheet is simply incompatible with traditional performance measurement. Our conclusion is that some of the persistent dissatisfaction with IFRS 17 comes from the new standard introducing value measures to the balance sheet that can be difficult to reconcile with income statement expectations.

Two examples of this are deferred acquisition cost (DAC) and loss component (LC). Neither appears on the IFRS 17 balance sheet because the prospective economic liability valuation naturally captures the DAC effect and produces the relevant LC effect and passes them via the P&L statement into balance sheet equity. 

The theoretical IFRS 17 income statement, therefore, does not need to include future explicit amortizations of either of these values (they happen naturally via the liability revaluation). However, presumably to satisfy pre-IFRS 17 practices regarding performance measures that need reporting, the income statement post-IFRS 17 will include amortizations of DAC and LC. Each of those amortization values will actually show up twice in each income statement – once as a minus and once as a plus – to reflect their net-zero impact on the balance sheet.

Financial statements generally provide supplementary disclosures that are valuable to investors, but to take this information and insert it into the mathematically derivable income statement is a new step and contributes significantly to the implementation challenges of IFRS 17.

Unavoidable Volatility?

Consider an income statement to be the difference of differences among four large numbers:For IFRS, the P&L is seen as the “more accountable” subset of that total result, and parties involved generally prefer that it not be volatile. There are at least two layers of challenge in getting P&L stability from this liability volatility:
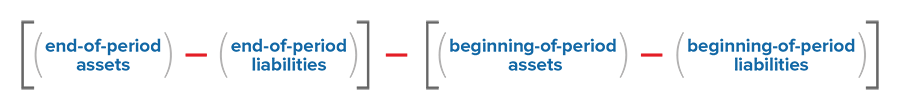
  1. If the liabilities were perfectly matched by the assets (which is rarely the case) and if the accounting for both the assets and the liabilities were perfectly synchronized (which does not appear to be the case), then a non-volatile total income statement might be possible. 
  2. If accountants then try to split out a P&L for management performance measurement and leave OCI for items outside their control, they will need to find, and then meticulously codify, the dividing line between P&L and OCI.

As IFRS 17 has evolved, numerous amendments to address both issues have emerged. Synchronizing the asset and liability accounting, for example, is aided by discretionary policy elections and classifications in IFRS 9 and IFRS 17. The split between P&L and OCI, meanwhile, was refined late in the process with the introduction of the variable fee approach (VFA) and the extension of the risk mitigation option to also apply to reinsurance.

It is our impression that the IFRS 17 P&L remains more volatile than many stakeholders would like. We believe, however, that there are meaningful limits to the effectiveness of further attempts to reach greater P&L stability without changing underlying beliefs.

See also: Reinsurance: Dying... or in a Golden Age?

Double Deferral of Spreads

Many commentators have written about the late emergence of profits under IFRS 17, especially for business that falls under the VFA. This phenomenon is a direct result of IFRS 17’s decisions to (1) initially not account for some of the significant investment profits that companies do, in fact, expect; (2) defer all initially expected profits; and (3) further defer unexpected investment profits when they do arise. 

The first element in that chain refers to the setting of liability discount rates that include only partial credit spreads. The two subsequent elements are simply the intended effects of the contract service margin (CSM). The CSM mechanics on their own would likely have produced late-emerging profits, but the extra effect of the VFA and credit spreads has produced a situation clearly at odds with the wishes of management and investors.

Closing Thoughts

We have shared these ideas in discussions with life insurers, who have found them helpful in selecting more effective commercial paths.

To respond to insurers’ challenges with IT systems, we have found some small ways to make their lives easier. We can’t reduce the number of times they need to fully project individual policies (twice as often if policies are reinsured), but we can modify reinsurance conditions or underlying policy conditions to make some of those projections simpler and better aligned.

As far as reducing income volatility, a significant portion of the “solution” has been companies gradually starting to accept the inevitability of this effect and the need to address it in their explanations when rolling out each period’s results. In addition, the usual full range of reinsurance solutions can play a role.

Finally, accelerating the pattern of income emergence is the most active area of our current IFRS 17 client engagement. The basic story is very similar to that of volatility, both in acceptance and reinsurance relevance.

The generalized lesson from these last two paths is that reinsurance can indeed help with volatility or the natural shape of earnings, but that reinsurance is generally most helpful to insurers that have a range of financial priorities and constraints (not just IFRS) and that have a clear strategy for how to prioritize and optimize those challenges.


Paul Sauve

Profile picture for user PaulSauve

Paul Sauve

Paul Sauve is the global head of RGA global financial solutions' capital solutions product line, where RGA designs reinsurance solutions optimized with respect to solvency regulations and accounting standards. He is a Canadian actuary who has been working overseas for most of his 30-year career in life insurance and reinsurance. 

Adding ESG to Investment Practices

Nearly 80% of survey respondents indicated that their firms began addressing ESG concerns within the last two years, apparently heeding the global clarion call.

ESG

U.S. insurance companies appear to be rapidly incorporating ESG (environmental, social and governance) factors into their investment strategies, according to a recent survey of U.S. insurance decision-makers commissioned by Conning.

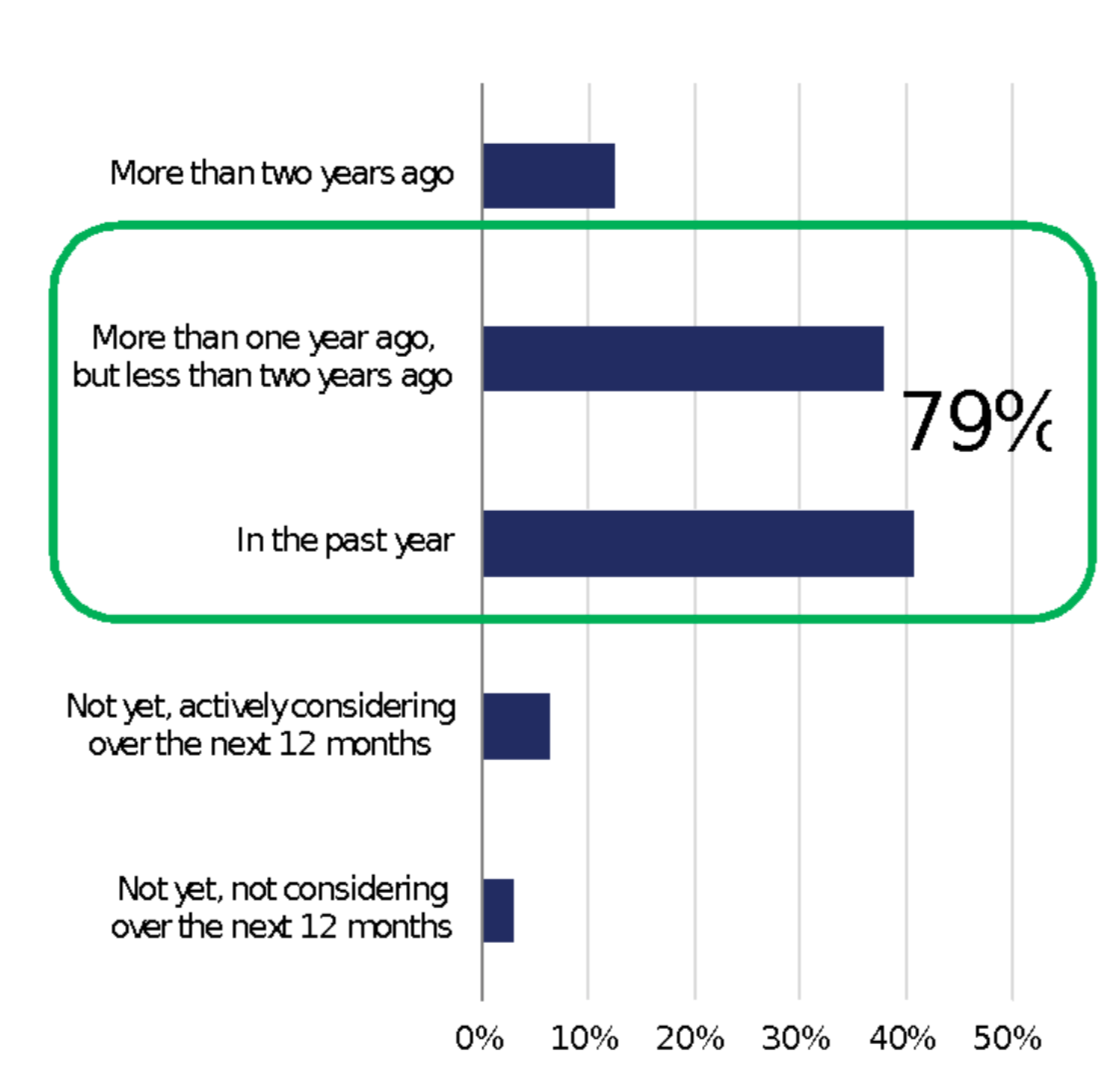
Nearly 80% of survey respondents indicated that their firms began addressing ESG concerns within the last two years (see Figure 1), apparently heeding the global clarion call regarding ESG investment practices. While U.S. insurers have long considered ESG and climate-related risks in underwriting, previous global surveys have indicated that U.S. insurers, in general, have trailed counterparts in Europe and Asia in incorporating ESG factors into their investment practices. However, U.S. insurers may be closing the gap.

With ESG interest rising among industry regulators, it is no surprise that respondents point to regulators as a key influencer in their greater attention to ESG. But according to survey respondents the greatest influencer–slightly ahead of regulators–is the insurers’ corporate reputation.

Figure 1: When did ESG become a part of your investment considerations?

chart
©2022 Conning, Inc. Prepared by Conning, Inc. The Conning ESG Survey of U.S. Insurers utilized survey technology provided by Qualtrics, LLC in 2021. Surveys were sent to more than 7,000 U.S. insurance company decision-makers with 280 qualified responses. Results may not be representative of any one respondent’s experience as they reflect an average of all, or a sample of all, of the experiences of surveyed U.S. insurance company decision-makers. Qualtrics, LLC was paid a fee for services rendered.

A large majority of survey respondents also said that they agree with the importance of including ESG criteria in their firms’ investment processes, regardless of whether the investments are handled internally or externally. While admitting that adding ESG considerations may require additional resources, respondents said they believe the reward is worth the cost. However, they also noted concerns over the lack of standardization with respect to ESG metrics and, less significantly, potential ESG constraints on portfolios. Although ESG considerations have increased in performance, they do not dominate investment concerns, as respondents remain more concerned about more traditional issues, including inflation, market volatility and monetary and fiscal policy.

The following is a look at some highlights of the survey, including some variances by life/annuity versus P&C insurer respondents and by company size.

Broad-Based Interest in ESG

Interest in ESG seems broad-based, according to the survey respondents. Only 9% had not yet made ESG a part of their investment considerations, and two-thirds of them said they plan to consider it during the next 12 months. Life/annuity companies had a slight edge as early movers: 16% of life/annuity company respondents said they had adopted ESG two or more years ago, compared with 11% of P&C respondents.

Larger companies, in general, have been leading the way, having adopted the inclusion of ESG in their investment considerations sooner than smaller companies. Companies with less than $500 million in assets were more likely to have adopted the principles in the past year, although there are quite a few “earlier adopters” among companies in the $500 million to $1 billion asset size.

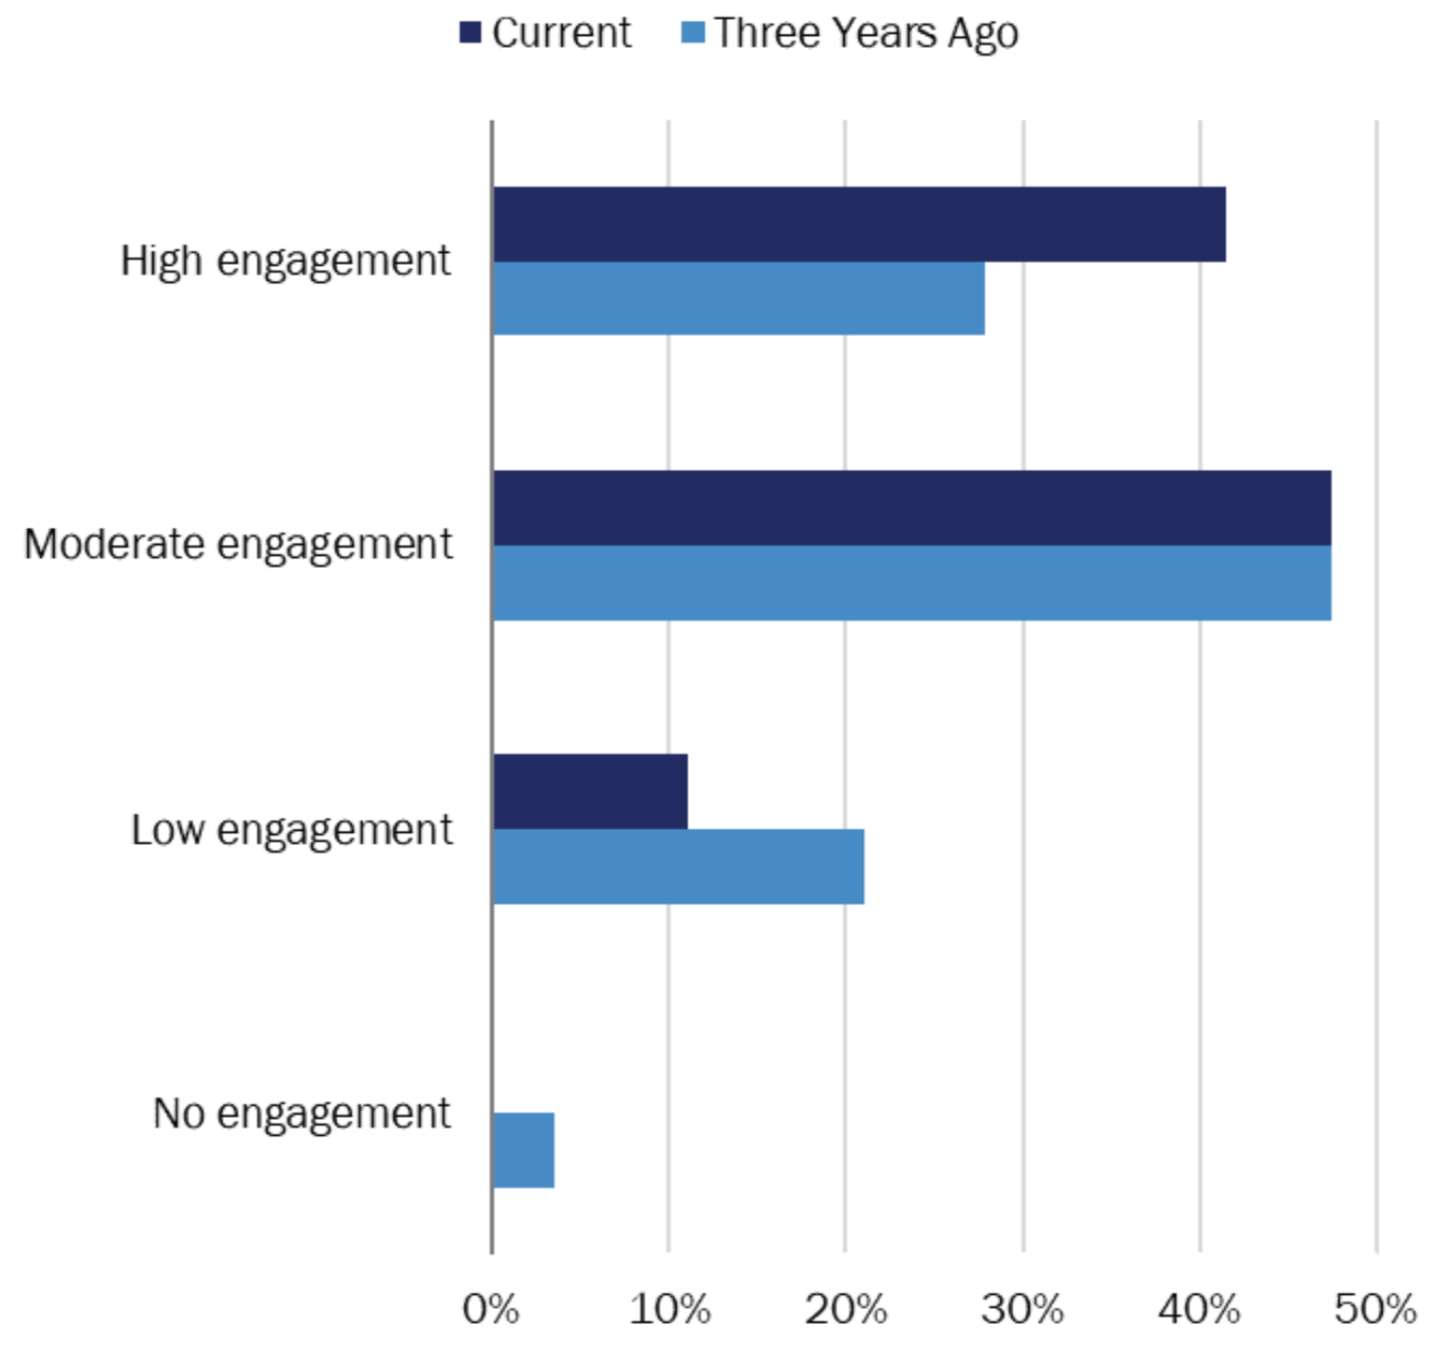
The level of engagement among respondents’ firms is also growing: 35% of respondents said their firms have “high engagement” with ESG versus 21% three years ago. Much of that gain is reported by respondents who identified as having roles with their firms in investments rather than operations, which includes underwriting, risk management, claims and corporate development.

See also: Is Your Approach to ESG Creating Risk?

Reputation and Regulation

When asked what was influencing their firms’ ESG engagement, the highest-rated response referenced the potential impact on corporate reputation. Regulatory requirements, which could be considered a purely defensive reason to address ESG concerns, had the second-highest proportion: 53% said it was “very important,” and it was the third-most-common response when we combined those who answered either “very important” or “important” (88%).

Customers’ and clients’ concerns were less commonly considered “very important” but rose to second-highest in influence when combined with the “important” response. Despite a common opinion that ESG can create a competitive advantage, the importance of that concept did not stand out from others, as it was ranked a middling fifth in importance out of 10 responses.

Concern Over Metrics, Definitions

While survey respondents agreed with the statement, “ESG is an important aspect of assessing investments,” measurement standards and definitions are lacking, and this concerns insurers.

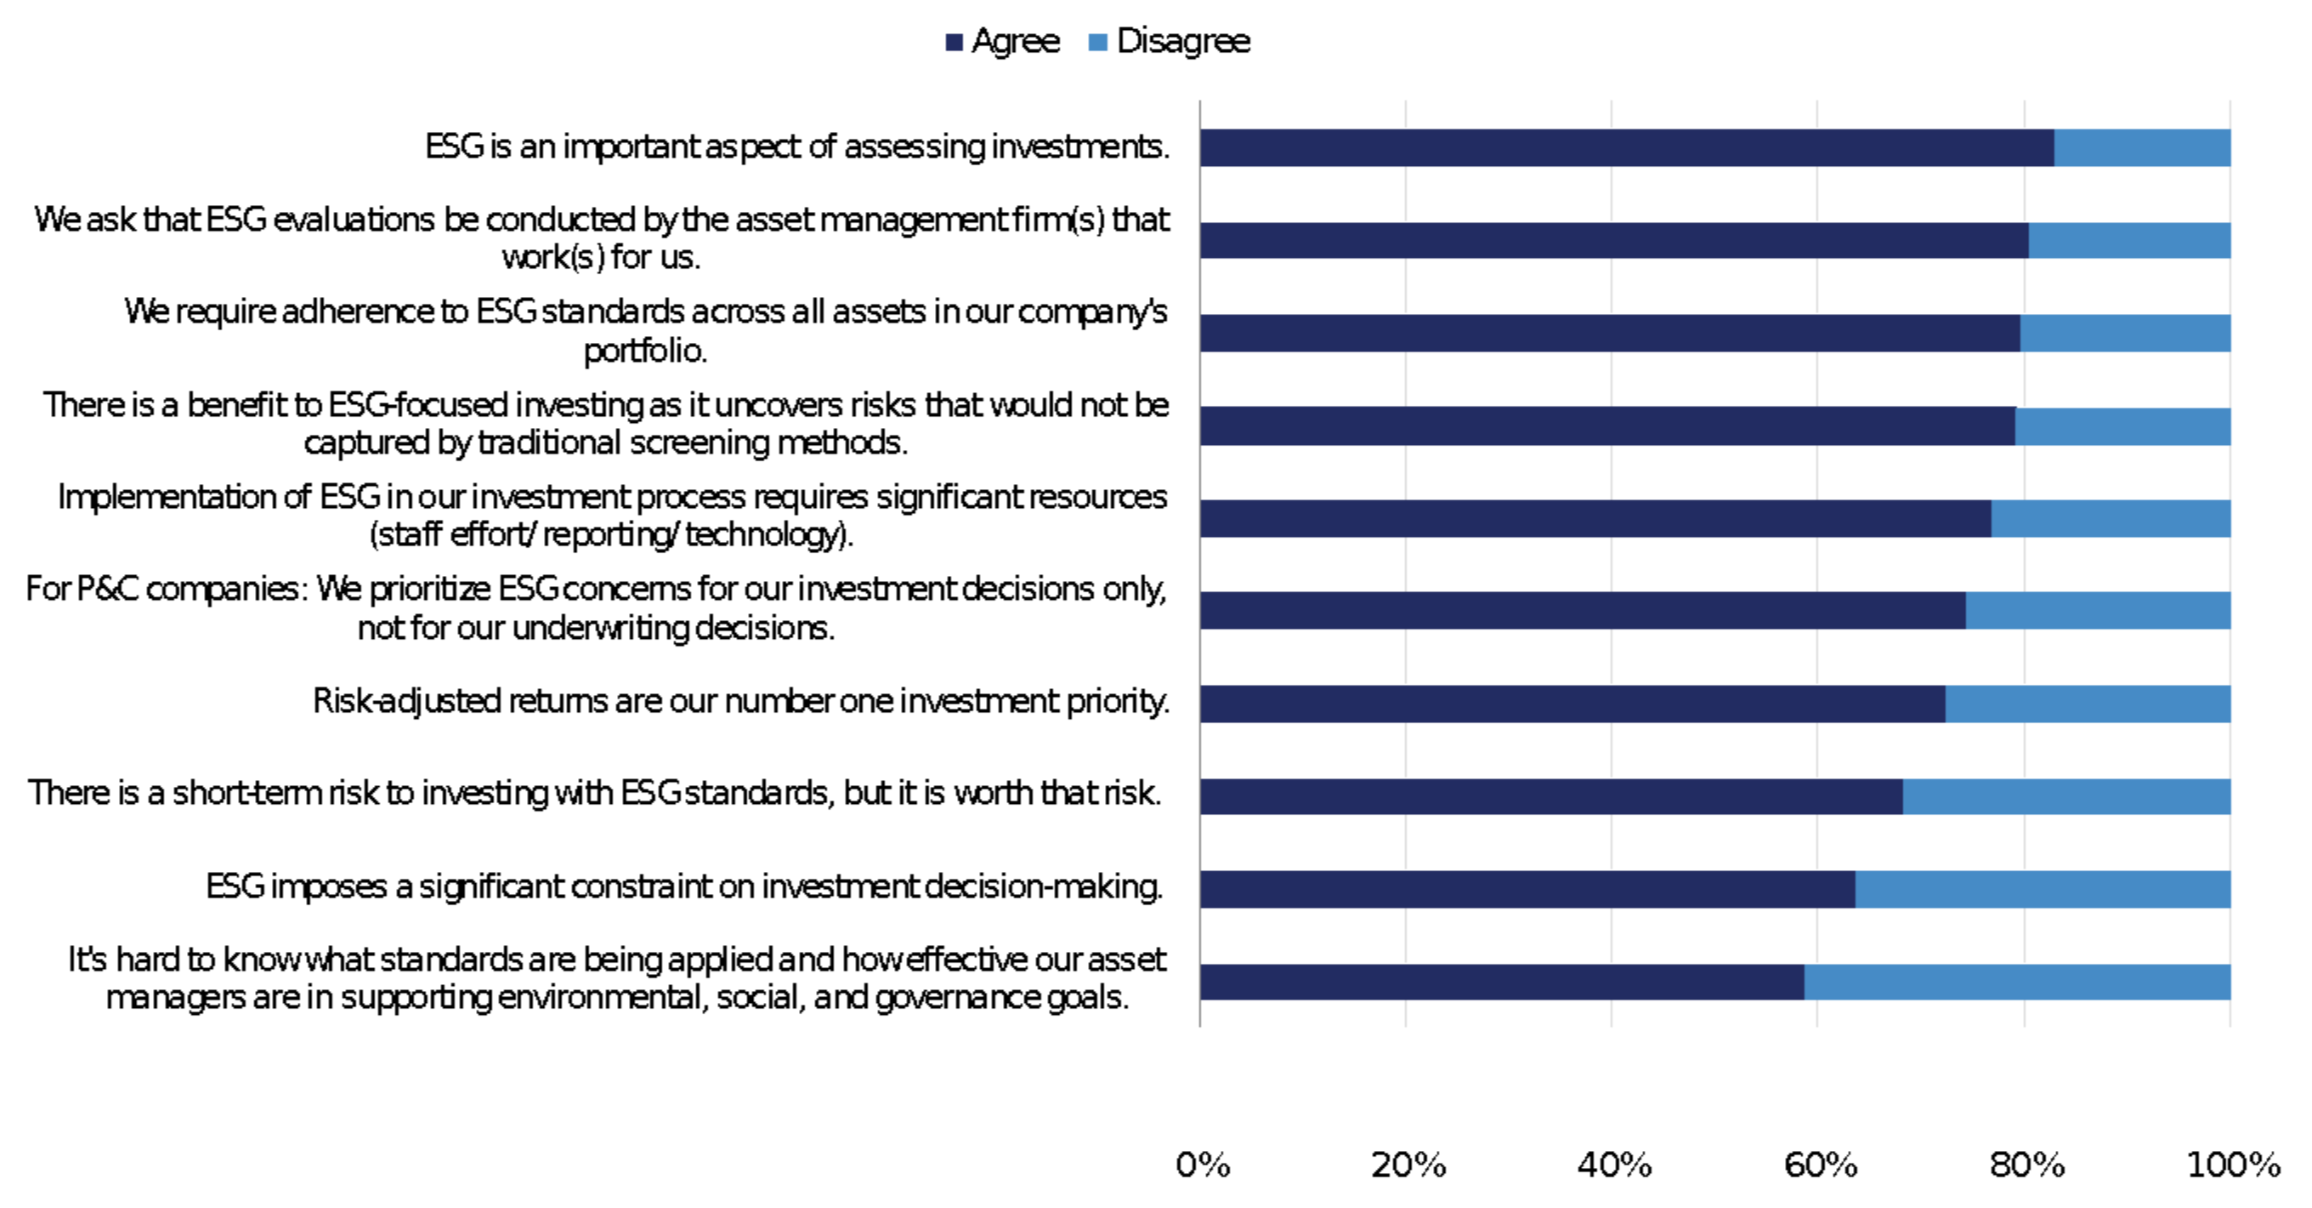
As illustrated in Figure 2, 59% agreed with the statement, “It’s hard to know what standards are being applied and how effective our asset managers are in supporting ESG goals.” (Larger companies were much less concerned with clarity regarding “standards” than smaller companies.)

Figure 2: Regarding ESG as it relates to your investments, indicate if you agree or disagree with the following statements

chart
©2022 Conning, Inc. Prepared by Conning, Inc. The Conning ESG Survey of U.S. Insurers utilized survey technology provided by Qualtrics, LLC in 2021. Surveys were sent to more than 7,000 U.S. insurance company decision-makers with 280 qualified responses. Results may not be representative of any one respondent’s experience as they reflect an average of all, or a sample of all, of the experiences of surveyed U.S. insurance company decision-makers. Qualtrics, LLC was paid a fee for services rendered.

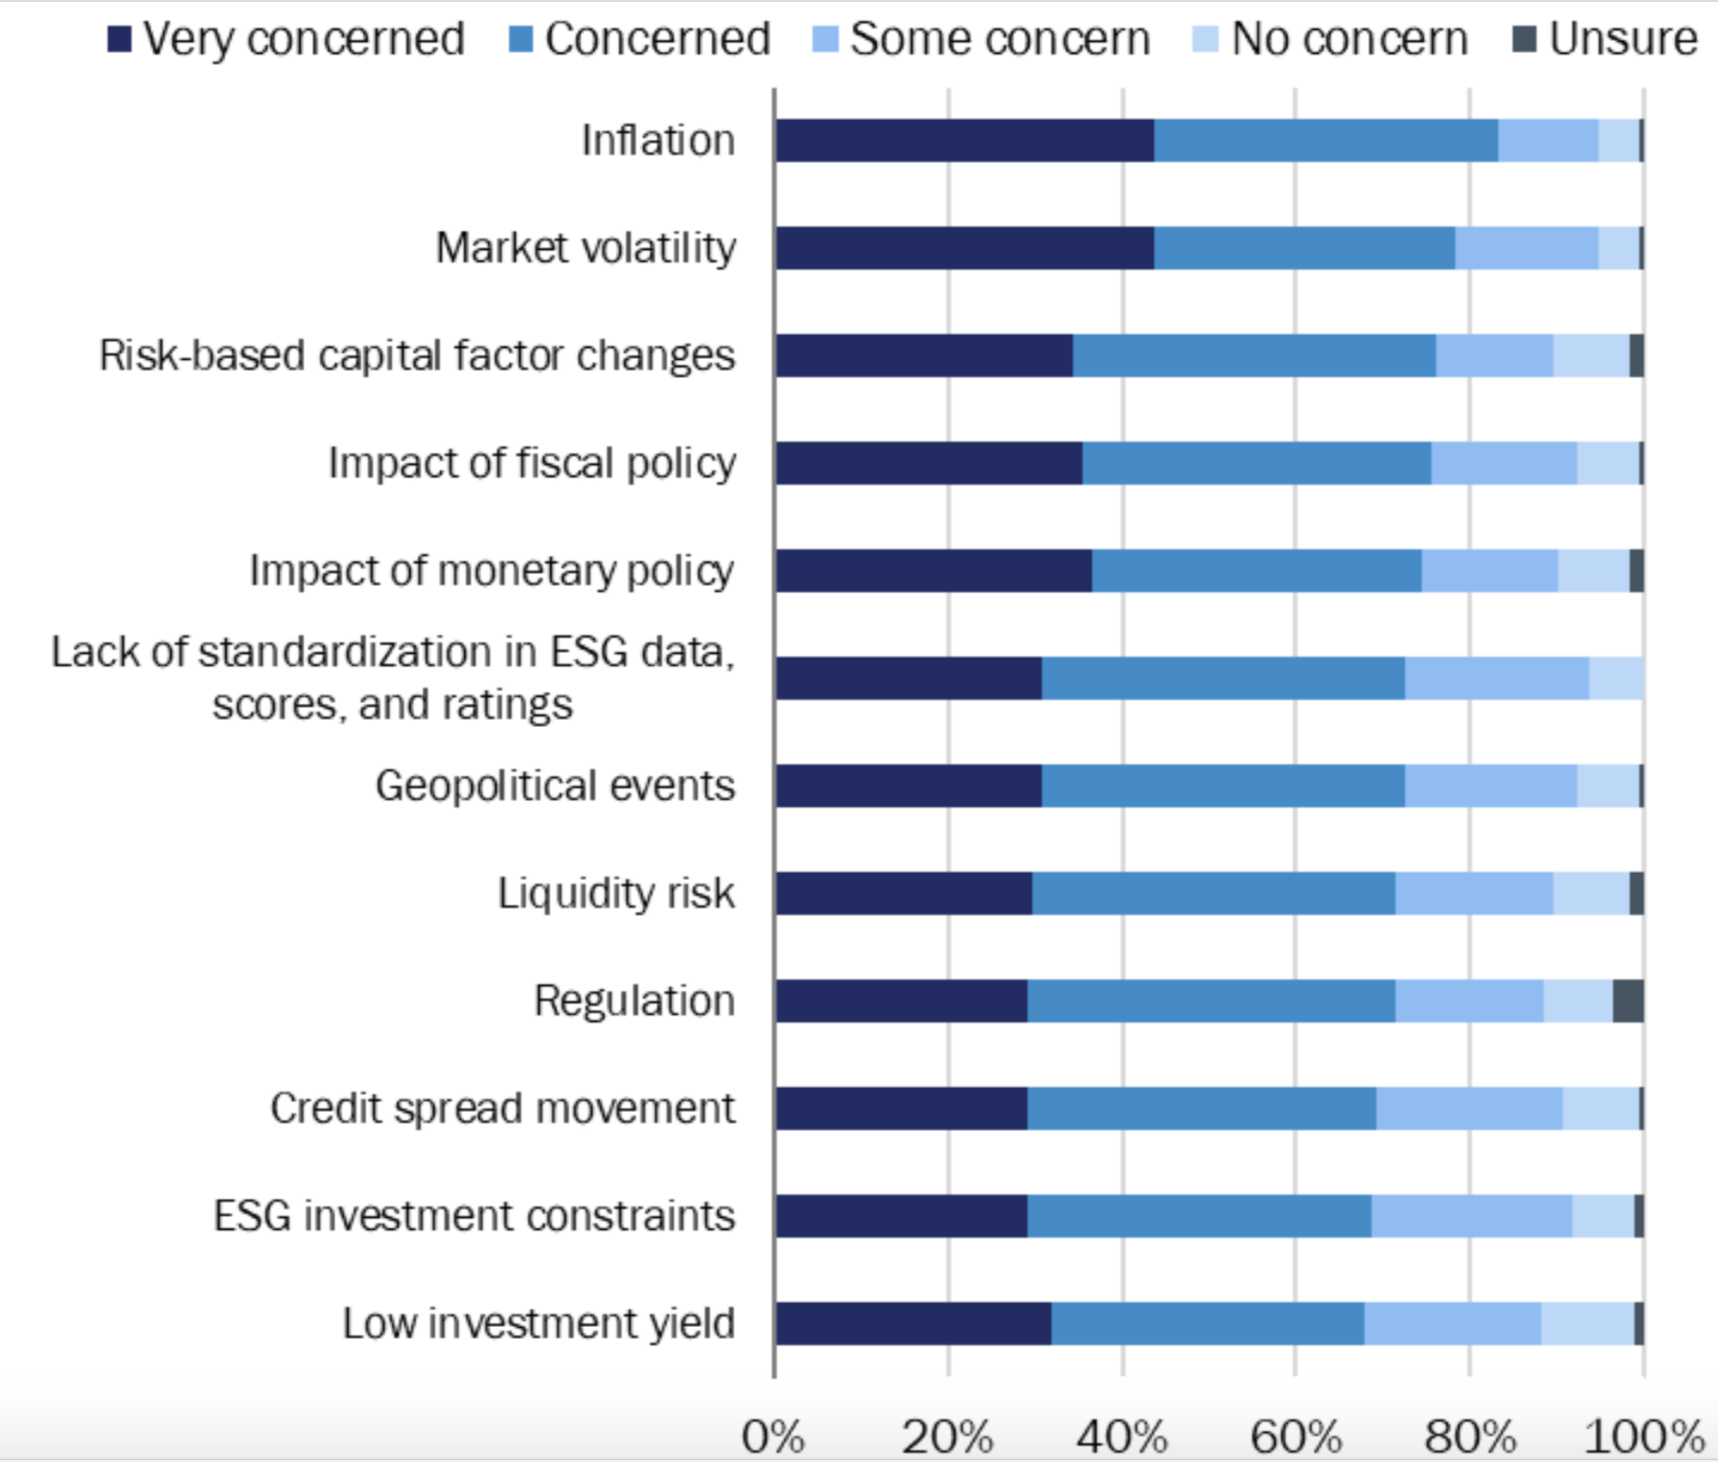
According to survey respondents, ESG issues do not rise to the top of the list of investment portfolio concerns during the next two to three years (see Figure 3). With inflation emerging as more than a transitory problem in early 2022, more respondents noted that they were either “very concerned” or “concerned” about the effects of inflation on investment portfolios than any other risk category. There was a distinctive split related to the low-yield investment environment: Life/annuity insurer respondents ranked it as their third most important concern, while it was ranked last of the 12 by P&C insurer respondents.

Concerns about ESG investment constraints on portfolio performance were second to last among the 12 areas considered among all respondents—although fully 69% of respondents did indicate that they were either “very concerned” or “concerned” about ESG investment constraints. While screening out a security for ESG reasons could constrain portfolios, incorporating ESG principles into the investment process provides a more holistic assessment of a security. It’s important to note that the survey results suggest that the “lack of standardization with respect to ESG metrics” carried greater weight than concern regarding investment constraints.

Figure 3: Rank your concern about the impact of the following on your firm’s investment portfolio in the next 2-3 years.

data
©2022 Conning, Inc. Prepared by Conning, Inc. The Conning ESG Survey of U.S. Insurers utilized survey technology provided by Qualtrics, LLC in 2021. Surveys were sent to more than 7,000 U.S. insurance company decision-makers with 280 qualified responses. Results may not be representative of any one respondent’s experience as they reflect an average of all, or a sample of all, of the experiences of surveyed U.S. insurance company decision-makers. Qualtrics, LLC was paid a fee for services rendered.

Four statements were aimed at capturing perceptions of the costs and benefits of including ESG in the investment process, and 79% of respondents agreed with the statement that there is a benefit to ESG-focused investing. Almost as many, 77%, agreed the implementation of ESG requires “significant resources,” 68% agreed there were “short-term risks but it was worth that risk” and 64% agreed that ESG imposes “a significant constraint on investment decision-making.” While the differences in the percentages are not particularly large, it is noteworthy that the statement about the benefits of ESG had greater agreement among respondents than the three statements about ESG costs, constraints and risks.

See also: ESG Means 'Extremely Strong Gains'

The Road to Implementation

According to the survey respondents, incorporating ESG factors in their firms' investment processes has clearly grown in importance to insurers. They see that adopting it in their investment practices will be important to their firms’ reputation and necessary to meet regulatory demands, and they generally believe that the challenges to implementation will be worth the cost and effort. However, what that implementation will be remains to be seen.

ESG, while an important issue to most respondents, does not rise to the top of the list as a critical concern, but rather is a new concern among more familiar issues such as inflation, regulation, RBC changes and fiscal and monetary policy. ESG is also an aspect that for many neither is clearly defined nor has clear measurement criteria to assess progress.

Figure 4: How would you assess your company’s engagement with ESG currently, and three years

data
©2022 Conning, Inc. Prepared by Conning, Inc. The Conning ESG Survey of U.S. Insurers utilized survey technology provided by Qualtrics, LLC in 2021. Surveys were sent to more than 7,000 U.S. insurance company decision-makers with 280 qualified responses. Results may not be representative of any one respondent’s experience as they reflect an average of all, or a sample of all, of the experiences of surveyed U.S. insurance company decision-makers. Qualtrics, LLC was paid a fee for services rendered.

Incorporating ESG factors into investment practices, in whatever form it takes, will likely add to the complexity of insurance portfolio management. Many insurance firms may find value in working with external asset managers that have deep experience in insurance portfolio management along with a broad understanding of ESG and can help insurers develop a customized strategy that incorporates ESG factors as part of their unique business needs.

About the Survey

The Conning ESG Survey of U.S. Insurers was conducted by Qualtrics, LLC in November 2021. The survey was sent to more than 7,000 insurance industry representatives, resulting in 280 qualified responses from U.S. insurance decision-makers in the life/annuity and P&C sectors. Results may not be representative of any one respondent’s experience as they reflect an average of all, or a sample of all, of the experiences of surveyed U.S. insurance company decision-makers. Conning paid Qualtrics, LLC a fee for services rendered. Analysis of results was done by Conning’s Insurance Research team with additional analysis by the firm’s investment team.


Terence Martin

Profile picture for user TerenceMartin

Terence Martin

Terence Martin, FSA, MAAA, is a director and leads the research team responsible for the life and health insurance industry.

Prior to joining Conning in 2004, he was director of actuarial reserving for Oxford Health Plans and previously was at Arthur Andersen, providing actuarial consulting regarding life insurance, health insurance and managed care, continuing care retirement communities, GAAP and statutory financial reporting, demutualization and expert witness testimony.

Martin earned BS and MS degrees in actuarial science from the University of Michigan.


Matthew Daly

Profile picture for user MatthewDaly

Matthew Daly

Matthew Daly, CFA, is a managing director and head of corporate and municipal teams and a member of Conning’s investment policy committee.

Prior to joining Conning in 2003, he held credit analyst roles with Webster Bank, Brown Brothers Harriman & Co. and FleetBoston.

Daly earned a degree in economics and business administration from Gordon College.

Improving Customer Experience In 2022

Far too little time and resources are spent understanding a customer’s buying journey or their communications preferences. This represents a massive opportunity.

Customer experience

According to Swiss Re Institute, demand for risk protection will continue growing steadily in the years ahead, and the insurance industry is poised to keep growing accordingly. The global insurance market is set to exceed $7 trillion in premiums for the first time in mid-2022 and grow 3.3% in inflation-adjusted terms in 2022 and 3.1% in 2023. 

With demand already high, and increasing, the insurance industry must be ready to serve the market. To do that, it’s essential to understand what customers want – and how to deliver that experience most efficiently. 

Rethinking the Customer Experience  

Insurance agents and insurers spend lots of time and resources every year trying to understand the market. Most of this energy is spent on demographic information – age, marital status, driving history, employment, family, hobbies, owning or renting, etc. Of course, the better that agents and insurers understand their current and prospective client base, the better they can build and tailor products – even ones for niche segments – to serve everyone’s needs and capitalize on business opportunities that may come along.

By contrast, very little time and resources are spent understanding a customer’s insurance buying journey, or their communications preferences. This represents a massive opportunity for the industry – one that’s mostly untapped, yet keeps growing in parallel with demand for insurance products. 

Several key questions are important to understanding a buying journey, such as:

  • At what specific point(s) does a customer become likely to buy a product? 
  • How does that customer prefer to be communicated with, in terms of time of day, channel, medium, etc.? 
  • What words and phrases are most likely to resonate and influence them to take the next step in their buying path? 
  • How and when does the customer want to engage, test and experience the product?
  • How often does the customer want to be engaged throughout the life of the policy?
  • How can communications facilitate a two-way conversation and feedback loop, instead of just a one-way information push?
  • How can insurance professionals ensure that each current and prospective customer receives timely, tailored communications throughout their buying journey so that they have the information they need to make a good decision and a positive brand/product experience to base their decision on?

The more that insurance agents and insurers can find answers to these questions, and implement processes and tools to help them engage with the customer, the better their chance of optimizing customer retention, service and top-line revenue.

Yet, until recently, insurers have been hamstrung on the customer engagement front by their technology infrastructures. In many cases, those systems are 20 to 30 years old, featuring applications that don’t interoperate particularly well on top of storage and bandwidth systems that haven’t enabled their business to scale well. As time has gone on, insurers have added layers of high-code applications, and these have complicated the overarching stability of the legacy core systems that support their services and products. They also have come with other side effects, including rigid and template-like communications, slower policy management and claim response times, compromised data security and more staff time spent managing it all instead of pursuing higher-value business activities. 

See also: 8 Key Changes for Customer Experience

New Technology Enables Tailored Real-Time Customer Experience  

Gartner, in its August 2021 report “Composable Commerce Must Be Adopted for the Future of Applications,” says that applications have evolved to better serve their owners. The report states, “to achieve flexibility in delivering experiences, modular packaged business capabilities (PBCs) are brought together to form composable digital commerce platforms that align to the future of applications.” 

Today’s technology has led to the advent of composable applications: platforms and software with functional blocks that can be separated from the whole and then integrated with other applications or their parts to create new applications with the exact functionality and purpose their owners need. 

In other words, these new applications have the flexibility and scalability to tie together the various aspects of an organization’s technology suite to accomplish specific objectives. They also can layer other important capabilities and features on top to make everything faster, more secure and more productive. 

The way to improve the insurance customer experience, then, is to find or build the right composable application that fits with your unique technology infrastructure and enables each specific aspect of the experience you want to deliver automatically.

Take website forms. When a customer fills out a company form, it initiates a workflow that can make or break the entire customer experience. On the back end, if the process is a clunky, manual workflow that requires several action steps from one or several employees, such as reviewing the data, storing the information and scraping the customer information in the company’s system, there’s a good chance something will get missed. In the year of the “Great Resignation,” relying on one specific person to manage this workflow puts your organization at risk of losing track of several customers should that employee leave the business.  

You can see how inefficient this type of workflow is and how the customer experience suffers, and it all began with one single form that was disconnected from other applications. 

Understanding context for your customer and their journey is paramount. There are several keys to keep in mind:

  • Procure and deploy an application that synthesizes data from across the entire business – a complete end-to-end solution. 
  • Include building blocks relating to sales, communications, operations or any business function that’s directly involved with your customers’ typical buying journey. Then use them to execute the programs you desire. 
  • Integrate artificial intelligence and analytics to help you predict when your customers and prospects are most likely to take certain actions or want specific products. Then set up and activate the systems needed to deliver through the right channels at the right times.
  • The best applications will automate as much of the work involved with delivering a customer’s experience as possible. This will free you and your team up to work on other value-added initiatives for your business.
  • Also, be sure to host your application in the cloud. This has emerged as the best practice for the back end of these applications, because it ensures continuous uptime, infinitely scalable bandwidth and storage capacity, the tightest security compliance and optimal overall efficiency.

There’s no doubt this is a highly complex process, but that doesn’t mean it has to be difficult. An entire industry category has materialized to help organizations map their customers’ buying journeys and find and build the right composable applications for their business. For instance, Agencymate has developed applications suited for the insurance space – and we’re always experimenting with new features and technology to add more value to our platform-as-a-service and software-as-a-service offerings. 

See also: ITL FOCUS: Customer Experience

The adoption of artificial intelligence (AI), for example, has given insurance agencies a competitive advantage by making sense of the data-heavy world customers live in. AI has simplified the process of data analytics by providing context around the data – a critical part of mapping out the customer journey. So, when organizations ask the questions: “How and when does the customer want to engage, test and experience the product?” and “how often do they want to be engaged with,” AI and data analytics decipher that information within the context of that individual, giving insurance agents the necessary background to create a better experience.

We’re living and working in a time of great change in business and society. The insurance industry is no different, yet there are tremendous opportunities for insurance agencies and insurers to lead the way forward. In 2022 and beyond, they need to take advantage of new technologies to build more tailored products and customer journey experiences that individuals and businesses can use to protect themselves and their assets. If they can do so, they will position themselves well for success.


David Buckley

Profile picture for user DavidBuckley

David Buckley

David Buckley is general manager, operations, at CoTé Software & Solutions. He has over 25 years of experience in business systems management, project management and business assurance, predominantly in the insurance sector for IAG, CGU. He has in-depth understanding of back-office and front-office applications and process as well as risk and governance around insurance products and services. Buckley brings to CoTé a solid foundation transferrable to many industry verticals that struggle with how to adopt digital transformation across all lines of business while using technology to also increase customer engagement in a highly regulated environment.