Download

Setting Record Straight on Auto Claims Severity

While the assumption has been that higher repair costs for advanced driver assistance systems features offset ADAS loss-cost benefits, a new study finds significant benefits.

auto

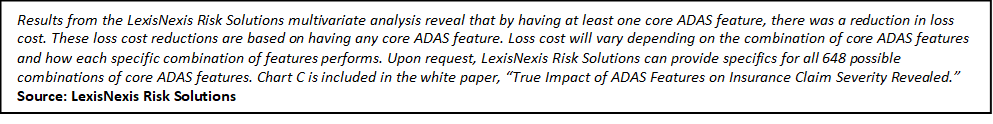
While insurance industry sentiment is that higher repair costs for advanced driver assistance systems (ADAS) features offset ADAS loss-cost benefits, a new study from LexisNexis Risk Solutions finds that’s not entirely true. 

The report, “True Impact of ADAS Features on Insurance Claim Severity Revealed,” provides a look at a sampling of 11 million vehicles from model years 2014-2019 to examine the multivariate effect of ADAS features on claim severity. While changes in claim severity in vehicles equipped with ADAS features were minimal, the decrease in claim frequency was significant. 

U.S. insurers have been trying to get ADAS feature information at a VIN level for years. Still, many believe technology has advanced too quickly, and the expense of repairing these features neutralizes the loss-cost impact of ADAS. However, as can been seen in the chart below, having at least one core ADAS feature provides a reduction in loss cost, which will vary depending on the combination of core ADAS features and how each specific combination of features performs. According to the report, having ADAS feature information can result in the following:

  • 23% reduction in bodily injury loss cost;
  • 14% reduction in property damage loss cost; and
  • 8% reduction in collision claim loss cost in ADAS-equipped vehicles compared with similar non-ADAS vehicles.
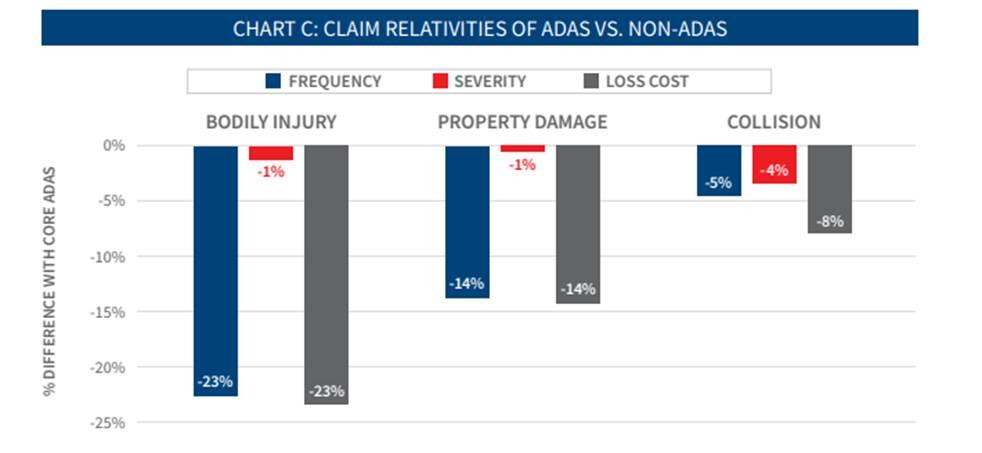
An educated guess for why all coverages resulted in a decrease in severity in ADAS-equipped vehicles is that the decrease in severity for liability coverages can be justified by the idea that vehicles with ADAS may collide with less force, resulting in less damage to another vehicle (property damage claim) or injury to a third party (bodily injury claim). 

A decrease in collision severity, however, deserved a deeper look. By controlling for common rating variables, the report isolates the impact of ADAS. With collision, there tends to be proportionally lower percentages of high severity claims with ADAS within a given cluster of values of control factors, resulting in an overall lower severity.

See also: Key to Transformation for Auto Claims

Depending on which ADAS features are present, the level of warranted discount will vary. This brings us to the challenge insurers face when trying to get normalized ADAS feature information across automakers, which often have their own naming conventions for features of the same technology (e.g., collision avoidance vs. automatic braking). Thus, solving for the multiple naming conventions found among ADAS features, vehicle build data provides greater transparency for specific features often equipped above standard base trim lines. Insurers focused on total risk analysis can begin to understand the safety features on the vehicle in combination with the risk factors associated with the driver. This new data can be used as a part of insurance companies’ rating segmentations to better meet the expectations of their customers, who often purchase vehicles with advanced safety features with the expectation that the features will help lower their insurance rates.

Understanding which vehicles have which ADAS features, combined with loss-cost performance, equips insurance carriers to apply appropriate discounts to the individual and the vehicle, delivering on consumer expectations along the way.

LexisNexis Risk Solutions has good news for insurers – this ADAS data helps show there is a distinct loss cost-benefit, and normalized VIN-level feature information is now available.
John Kanet

Profile picture for user JohnKanet

John Kanet

John Kanet has been with LexisNexis Risk Solutions since 2014. Kanet is responsible for strategy and innovation around data products for auto insurers, as well as ensuring organizational alignment around new initiatives.

Previously, Kanet spent six years in sales and product roles at Trimble Navigation working with heavy machine automation, telematics and data management solutions.

Kanet earned a bachelor's degree in civil engineering and a master's in business administration from Clemson University. He also holds a professional engineer certification from the Texas Board of Professional Engineers.

6 Keys to Successful CRM Implementation

CRM software does not solely benefit relationships with customers. It also helps in communication and collaboration among various departments.

software

Implementing customer relationship management (CRM) software offers an array of benefits. It enables agencies to improve customer relationships, optimize daily operations, close more deals and make better decisions. However, before implementing an insurance CRM system, it is crucial to understand that the software does not solely benefit the business’ relationships with prospective and existing customers. CRM also aids in communication and collaboration among various departments.

To seamlessly deploy a new CRM system, businesses must ensure proper implementation.

Step-by-Step Guide for Implementing Insurance CRM Software

Implementing insurance CRM software requires a lot of planning, budgeting and effort. Without due preparation, it can end in failure. Here are the six steps insurance agencies must follow when implementing a new insurance CRM system: 

1. Identifying the Needs and Requirements

Before embarking on the journey for software selection and implementation, businesses must first identify their goals and needs. Hence, the first step involves identifying the reason behind implementing a CRM. Businesses must monitor their existing processes and systems and find areas that can be improved and challenges that can be resolved with a CRM system. 

Ascertaining the scope of the project is crucial to ensuring its success. Businesses that do not remain focused on specific workflows and requirements have a hard time choosing the right CRM software. Once the business has identified the challenges and built a convincing case for change, it can kickstart the process of CRM implementation. 

2. Creating the Implementation Team

Insurance CRM implementation requires skill, time and resources. Hence, it is crucial to have key players in the implementation process. The arrangement of the CRM implementation team depends on an array of factors such as the size of the business, expectations and customizations. 

See also: How to Choose the Right CRM Package

The implementation team must consist of representatives from different departments, such as sales, marketing and customer support. The different perspectives help the team members better understand and adapt to the processes. When building a team, make sure to define proper roles and responsibilities for the team members. Ideally, the insurance CRM implementation team must consist of: 

  • Project owner
  • Project manager
  • Subject matter experts
  • Department heads
  • Cross-departmental users
  • Technology resource

3. Finding the Right Insurance CRM Vendor

Nowadays, there is no dearth of vendors dealing in CRM software for insurance companies. However, finding the right vendor is key to ensuring a successful insurance CRM implementation. Here are some questions that businesses can ask: 

  • How long have they been in business?
  • How often do they release software upgrades and updates? 
  • Do they keep pace with the rapidly changing needs and requirements of the industry? 
  • What kind of after-sales support and training do they offer? 
  • What is their standard implementation roadmap? 
  • Can the insurance CRM software be customized to meet the business' unique needs? 
  • Do they offer a free trial or demo of the software? 

4. Setting a Realistic Budget

Irrespective of the scale of the implementation or the level of research, unforeseen costs are unavoidable. For instance, the insurance CRM implementation cost may increase according to the level of customization required by the business. When setting aside a budget for the software implementation, a number of businesses often overlook onboarding and training costs. The total cost of ownership for CRM typically includes: 

  • Monthly or annual subscription fees
  • One-time implementation costs
  • Data handling and migration costs
  • Software licensing costs
  • Testing and retesting expenses
  • Customization and process re-engineering
  • Software support and maintenance expenses

Apart from setting a budget, businesses must also set a realizable timeline for the implementation. They must bear in mind that not all CRM systems work identically. While small agencies can easily implement a CRM within one to two months, larger corporations can take four to six months. 

5. Developing an Implementation Strategy

After setting the budget and selecting the vendor, businesses must formulate an insurance CRM implementation road map. The business must gain an understanding of how the different team members will participate in the software implementation process. After that, the business can equip them with the right training. 

Businesses that are overhauling legacy systems can also improve and integrate their existing CRM workflows. The CRM implementation strategy depends on the type of deployment, be it cloud-based or on-premise. 

Once the insurance CRM implementation strategy is set, businesses can start the deployment. They can also plan a phased rollout and change to the new software in increments over an extended period. This helps in ensuring that any problems or challenges remain isolated from business processes. 

6. Post-Deployment Support and Upgrades

The insurance CRM implementation process does not end with deployment. To get the most out of the investment and achieve long-term benefits, businesses must nurture their CRM implementation. The CRM implementation team must now shift its focus to gathering feedback from the end-users and tweaking the software. 

Modifications or customizations may be required as more features are rolled out. Businesses will also have to make provisions for onboarding and training new employees. On-premise insurance CRM software users will have to install updates and even upgrade the hardware when needed. 

Finally, the business can evaluate the success of its implementation and assess if the insurance CRM system meets its expectations. 

See also: Sorry, but There Is No Magic Bullet

Final Words

When implementing CRM software, insurance companies must also pay attention to the software selection process. Small and medium-sized insurance agencies can opt for cloud-hosted CRM systems, as they are quicker to implement and easy on the pockets. On the other hand, businesses with a significant budget and infrastructure capabilities can go for on-premise insurance CRM systems. Irrespective of the deployment, businesses must apply the above-mentioned best practices to ensure a successful software implementation.

How to Achieve Cyber Resilience

If an organization does not have a well-thought-out incident response plan with trusted and tested backups in place, a cyber attack can be devastating.

cyber

Our economy is increasingly global, digitized and connected by supply chains involving transactions among large companies and small and medium-sized enterprises (SMEs). However, the roles SMEs play in the supply chain create some concerns.

According to the World Economic Forum’s Global Cybersecurity Outlook 2022, “88% of respondents indicate that they are concerned about cyber resilience of SMEs in their ecosystem.” Typically, SMEs do not have the same resources as their larger counterparts to spend on cybersecurity and are often exploited as a means to ultimately victimize another company in the supply chain. In fact, the WEF also reports, “Nearly half (44%) of the surveyed CEOs indicated that software supply chain attacks will have the greatest influence on their organization’s approach to cybersecurity in the future.”

What can be done? 

To secure supply chains overall, each link along the chain must be secured. This starts with creating, at all levels, a culture of cybersecurity -- technical measures to safeguard against cyberattacks such as phishing, ransomware and social engineering. Cyber resilience incorporates these technical measures and supplements them with a prevention-oriented and preparedness mindset embodied by each employee and each company along the supply chain. It also enables the business to recover quickly when an incident occurs.

For the past few years now, organizations operated under the assumption they will fall victim to a cyber attack at some point. As a consequence, detection and prevention, the primary domains of cybersecurity, are no longer sufficient. Preparedness and the ability to recover effectively and maintain operations in the event of a cyber incident is cyber resiliency. 

We must recognize that cybersecurity best practices are everyone’s responsibility and that it is a journey, not a destination. Bad actors and their tactics are constantly evolving; so, too, should an organization’s cyber resilience. Furthermore, cyber resilience encompasses the aftermath of an attack and acknowledges that cyberattacks do not end when the ransom is paid, for example. Rather, the affected organization should have an incident response plan in place to facilitate business continuity in the event of a cyberattack, as well as share lessons learned from the incident with others so similar incidents can be prevented. 

See also: Quest for Reliable Cyber Security

Another part of cyber resilience is acquiring cyber insurance. While simply buying a cyber insurance policy may not make an organization fully immune to a cyberattack, it will reduce the financial uncertainty involved in how the organization responds. Most policies encourage the adoption of cybersecurity best practices, such as multi-factor authentication and cybersecurity awareness training across the whole organization.

A good policy provides businesses with peace of mind, knowing that they are doing everything in their power to defend themselves against a cyberattack and that, if one still manages to penetrate their walls, the effects will not wreak total havoc on the business. Having a cyber insurance policy alone is not enough, but it is certainly a step in the right direction to achieve cyber resilience. 

The aftermath of a cyberattack is often wrought with reactive measures and questions like, “How can we afford this ransom payment?” and “How will we recover our lost data?” If an organization does not have a well-thought-out incident response plan with trusted and tested backups in place, a cyber attack can be devastating. Practicing cyber resilience, however, will help tremendously.

Insurtech's Lasting Role in Insurance

Thousands of lines of insurance haven't been innovated in 30 years. With so much opportunity, it's time to think about insurtech as a permanent fixture in the larger ecosystem

ocean wave

Growing up in Australia, where surfing is part of the culture, I have a healthy respect for waves. They're a part of something powerful, cohesive and much larger than the individual.

As an insurtech CEO since mid-2020, I've been getting asked about waves a lot--specifically, the first, second and third waves of insurtech. On the heels of our recent Series B raise, fintech reporters want to know: Is insurtech still perceived as a bubble or a blip?

Depending on your definition of the advent of insurtech, we're about a decade in. Yet there are still tens of thousands of lines of insurance, some of which haven't been innovated in 30 or more years.

With so much opportunity to offer better delivery, service and risk innovation, it's time to think about insurtech as a permanent fixture in the larger insurance ecosystem--and about how we evolve together, for the sake of our customers, our industry and the economy.

Investor Interest is Increasing

Market speculators and media headlines always make a great deal of noise around any adverse activity in our industry, but insurtech itself has been a steam engine since its inception. In Q3 of 2021, insurtech funding reached $5.3 billion (compared with $1.87 billion in Q3 of 2020), and topped $15 billion for the first nine months.

2021 was a landmark year for VCs as a whole, most of whom need to deploy their capital within the next five years. Any hesitancy in early 2022 is largely a byproduct of general economic uncertainty as global markets adjust to a third Q1 of pandemic conditions. The most forward-thinking venture capitalists are allocating specific funding toward insurtech to expand and add sustainable growth to their fintech portfolios.

Mutual Respect Between Incumbents and Insurtechs is Growing

Initially, incumbents were hesitant to acknowledge insurtechs as competitors, and vice versa. Many "1.0" insurtechs sought to disintermediate or automate fundamental insurance functions such as underwriting, broking and relationship management. Many incumbents believed they could beat insurtechs by rushing tech upgrades to antiquated quote-rate-issue platforms, only to be met with myriad challenges in adoption, training and cost.

Today, most of the longest-tenured global carriers have incubators and accelerators within their headquarters dedicated to insurtech. While true insurtechs have a bit of a leg up when it comes to agility and deployment because we are able to build from scratch rather than convert or upgrade legacy systems, it's a net positive for customers and the industry that incumbents are now constantly challenging and innovating. And early insurtechs learned a lesson in that you can't build an insurance company without serious insurance talent. Which brings me to my next point.

See also: 2022 Resolutions to Foster Innovation

Diversification of Opportunity Enriches Industry Talent

Not every insurance professional is a fit for the pace at an insurtech, and not everyone who thrives at an insurtech would succeed at a legacy company. Many will succeed in both arenas. But what the "great resignation," pandemic and "aging out" of talent in our industry have laid bare is that nurturing a talent pipeline for insurance is a responsibility we all must take seriously. There is a substantial benefit to having a breadth of career options industry-wide that draw from the traditional insurance paths--underwriting, claims, actuarial, risk management, safety--as well as innovators of technology, engineering, marketing and product development.

Younger generations in the workforce prefer to view careers as a jungle gym over a ladder, and the ability to move among legacy, insurtech or hybrid workplaces can offer the kind of development and enrichment critical talent thrives on. A stronger talent pool and happier, healthier workforce makes our industry better--and makes us better at serving our customers.

We Serve a Common Purpose

In the business of insurance, at the end of the day, someone is looking to us when things have gone wrong. They don't care whether we call ourselves an insurtech, a mutual or state fund or a global carrier.

You can call what's happening with insurtech a bubble, or 2.0 or third wave. But if we're each solving for one of those 10,000 lines of business that haven't been innovated in the last 30 years, I call that a win.


David Fontain

Profile picture for user DavidFontain

David Fontain

David Fontain is founder and CEO of Foresight Commercial Insurance, the fastest-growing workers compensation insurtech for the middle market.

Auto Insurance in 2022: What to Expect

2022 will look a lot like the second half of 2021, but opportunities are emerging for auto insurers to differentiate themselves, especially through telematics. 

cars

It’s been a wild year for insurance, and for auto insurance, in particular. As the pandemic and local governments’ responses to it have evolved, motorists have significantly changed their driving frequency, driving behaviors and ownership patterns. And, unfortunately, there’s no reason to think that 2022 will be any more settled than 2021. 

For starters, driving patterns have been fluctuating dramatically. In January 2021, travel on U.S. roads and streets totaled 223.3 billion vehicle miles, down 11% compared with the same month in 2020, according to the U.S. Federal Highway Commission. By November 2021 (the most recent month for which data is available), there were 278.4 billion vehicle miles, a 12% increase over November 2020. In fact, though traffic was down significantly in the early part of 2021 over 2020, by November, total vehicle miles for the year was up 11%!

In addition, it’s  common to hear people complain that motorists seem to be driving worse than before the pandemic. Statistics show that it’s not our imagination: The Zebra’s annual survey on distracted driving found that 40% of respondents said they interact with their Apple devices while driving, a 14% increase over 2020, and 55% of Android users said they did so while behind the wheel, a 2.7% increase over 2020. 

People are also holding onto their cars longer than ever before, with the average age of vehicles on American roads climbing to 12.1 years in June 2021. Supply chain disruption caused a shortage of new cars on the market just as demand for vehicles soared. As a result, the price of a used car rose by anywhere from 32% to 36% in 2021, depending on whom you ask.

Finally, new cars have significantly more technology than older cars. And while these technologies do increase driver safety and prevent accidents, when there is a wreck, damage will be more costly to repair.

See also: 5 Trends Changing Auto Insurance

Impacts on Auto Insurance in 2022

Lasting impact of new vehicle technologies: Damage severity is increasing. That’s not surprising, with so many sensors embedded in the bumper and other exterior areas of a car. A simple fender bender can damage these sensors to the point of making a car undriveable. As a result, the average claim will grow, and roadside assistance will be required for accidents that previously left vehicles perfectly safe to drive.

Insurers’ roadside assistance programs will also be affected in another way, because, as vehicles become more complex, it’s more difficult for a single towing and roadside assistance service provider to become specialized on all vehicles. For example, at least half a dozen car models have no exterior door handles, or they have handles that only pop out when a fob is present. This makes lockouts much more difficult to perform. It’s not out of the question that five to 10 years from now, tow providers will need to work through secured software or remote relationships to get these vehicles open, jumped or even towed. 

Another factor will also increase the severity of damage. People are holding onto cars far longer than they used to, and, the older a car is, the more likely it is break down at some point and initiate a claim. 

Roadside assistance programs: Roadside assistance is by far the most common claim for auto insurers, and the whipsaw trends in traffic volume have caused significant disruption. When traffic volume cratered in early 2020, tow providers had to lay off employees and even sell trucks and equipment to survive. Now, with traffic volume surging, they’re scrambling to keep up. In fact, a recent HONK survey of more than 580 tow providers found that more than one in five are having to turn down work. Tow business owners are working to hire employees and buy trucks so they can meet demand, but, in the meantime, the survey shows tow providers are prioritizing jobs that are closest to an available truck. Dispatching systems that take location into account can help reduce wait times for customers, but until the supply-and-demand imbalance is righted, insurers’ customers will likely see longer than usual wait times for help across the board.

Opportunities ahead: Despite the difficulties, there are big opportunities ahead for auto insurers. One of the largest involves telematics that can help with risk assessments and claims management. As a result, insurers can get a much more accurate, up-to-date picture of an individual’s risk, managing it in real time on a trip-by-trip basis. Instead of basing risk on predictors like financial history, where a motorist attended college and where the car is typically parked, insurers can look at individual behaviors in real time. 

See also: Nonstandard Auto Insurance's Key Role

There will be a lot of regulatory hurdles to overcome, but the momentum is clearly behind applying more sophisticated telematics to risk assessment. Insurers that have thoroughly digitized their operations will be well-positioned to capitalize on this massive amount of data once it becomes possible for insurers to access and use it.

In sum, 2022 will look a lot like the second half of 2021 for auto insurers. But it’s also clear that there’s much opportunity for insurers to lay the groundwork to differentiate themselves and position themselves for growth once the disruptions caused by the pandemic settle out.


Rochelle Thielen

Profile picture for user RochelleThiele

Rochelle Thielen

Rochelle Thielen is chief revenue officer at HONK, which provides a next-generation roadside assistance platform for motorists, insurers and fleets.

She previously served as CEO of Estify and in senior positions at Mitchell.

Smart Homes Are Finally Getting Smarter

Apple, Google and Amazon just announced a new standard for communication for devices that could finally unleash the smart home's potential. 

Image
a picture of a phone connecting to smart home features

Despite all the hype for smart homes, I've remained a skeptic for the 30 years or so since I first heard about the concept, partly because there wasn't a standard way for all the disparate devices to talk to each other. There wasn't a sort of operating system for the house, and a bunch of one-off devices weren't going to provide enough benefit. 

Well, three of the biggest guns in the tech world -- Apple, Google and Amazon -- just announced a new standard for communication that will be available later this year. The standard, called Matter, will let just about all new smart home devices, and even many old ones, talk to each other. 

Progress will still take time, and I remain to be convinced that many of the long-touted "benefits" of the smart home -- an internet-connected toaster or the ability to turn lights on and off remotely, for instance -- actually offer anything of value, but at least there will finally be a communication platform that will let companies, including insurers, tie all the benefits together and look for synergies.

To see how a platform like Matter can unleash a market, you can look to any number of examples from the history of technology. For instance, personal computers were available in the second half of the 1970s, but they all operated using different software. When IBM debuted its PC in 1981 and used a Microsoft operating system that any company could license, the standardization of the computing platform let the PC market take off. The search engine became far more powerful when Google became a standard. The market for music transformed when Spotify became the standard for streaming. In the physical world, Amazon's Prime has set a standard for shipping that has taken e-commerce to new heights.

Yes, all those standards have given rise to monopoly complaints. Google faces privacy concerns, too, and Spotify's attempts to build on its success and move beyond streaming have given it a great, big Joe Rogan problem. The monopoly and privacy concerns, if not problems with overreach, could well surface with smart homes at some point, but those are mostly to be dealt with down the road, after the market expands considerably. For now, standardization will almost entirely provide benefits.

For insurers, having an operating system for homes would help them work with technology suppliers and other partners to tie together sensors for water leaks, fire, radon and carbon monoxide, etc. and offer discounts on policies while better protecting clients. Building on Matter, insurers and partners could also better integrate those sensors and cameras with security systems that protect homes and offices. Insurers could also tap into devices such as the Amazon Echo and Google Home to provide voice alerts that a big storm is heading for your neighborhood, so you should remove anything from the patio that could get damaged or turn into a projectile, or that the possibility of a hail storm means you might want to keep your car in the garage all day. 

Or whatever. The point is that, once you have a platform, innovations can build on each other, often in unexpected ways. And I think Matter could finally provide that platform for the smart home. 

If you're interested in reading more, here is a Wall Street Journal article that explores Matter in some detail. Here is me complaining in 2016 about how the lack of a standard means of communicating limited the utility of smart home devices; the commentary includes links to a piece by an old colleague that goes into even more detail. Here is me in 2020 explaining that insurers will eventually have to make a business case for smart home technology and show that widely deploying, say, sensors for water leaks has to cost less than the price tag for the damage they would prevent -- concluding that we weren't there yet. And, lest you get the sense that I'm always pessimistic, here is a link to the ITL Focus from December, on smart homes, which includes some commentary from me, an interview with Mr. Telematics himself, Matteo Carbone, and six articles on what insurers are doing with smart homes.

Finally, my daughters suggest I steer you to a Disney movie called "Smart House" from 1999, which they recall watching as little kids. The movie is about a home that gets too smart for its own good, presaging at least some of the problems we might eventually encounter, but, remember, it's a Disney movie, so it has a happy ending. 

Cheers,

Paul


The Power of Low-Code Platforms

Customers now expect exceptional service from all businesses, and low-code platforms hold great promise for businesses’ internal and external users alike.

digital

Customers now expect exceptional service from all businesses, and low-code platforms hold great promise for businesses’ internal and external users alike. They’re capable of aggregating data from multiple administrative legacy systems and quickly bringing value to customer service functions. 

Many of these platforms are rich in user interface functionality. They allow for drag-and-drop efficiency instead of burdening users with extensive lines of code. Circumstances may not be as flexible as with other technology, but the speed and integrity of low code make it a viable choice.

Additionally, integrating low code to existing IT operations provides modern tech experience to in-house system managers who, in turn, grow their expertise. For example, domain experts can immerse themselves in articulating need requirements and even build out the solution. Those who already have systems development expertise can be assets in the transformation.

See also: Thinking Big for True Transformation

Low-code platforms are rich in functionality and capable of rapidly creating enterprise-level applications, and vendors offer different solutions with varying levels of functionality. Some are robust with powerful capabilities, providing user interfaces, automated workflows, automated case-management processes, integration with many different systems and more. 

These solutions often come through built-in connectors to automate processes. 

IT pros in the insurance industry both influence and benefit from digital transformation. IT has significant experience with methodology and process. Pros understand and can describe business requirements in a product backlog and are familiar with testing and deployment processes. Such IT experience can be advantageous if complex integration needs arise. In turn, the platform offers significant leverage to the product team seeking an automated solution to a business problem.

Some businesses find themselves frustrated by the functionality of commercial off-the-shelf packaged software. Those products result from requirements dictated by the larger market needs and generalized feature set, though this is now changing. These features may not apply to all and may need heavy customizations to adapt within an existing ecosystem. Such frustration is a low-code opportunity that's tailorable to a client, suits its needs, is cost-effective and is simply a better fit.

There are four ways for insurance organizations to leverage low-code:

  • Build out enterprise-class applications. 

A full-stack platform brings everything necessary to create a customer-facing user application. That includes a user interface, business process management, business rules, case-centric capabilities, content and document management power and third-party connectors that allow connectivity that provides for and extends legacy systems. 

  • Complement an existing system. 

Underwriting often involves manual processes where paper notes present valuable information. However, it is hard for software systems to digest and make sense of this material. Low-code solutions with character recognition and language processing capabilities can integrate and automate gathering this vital information. 

  • Integrate relying upon multiple existing systems. 

Low code can orchestrate leveraging these systems into modern service, whether administrative, claims, internally developed or inherited systems or multiple other varieties.

  • Reduce technical debt

Low code is easy to maintain and increases user productivity by speeding the development process. It reduces several tasks to a single workflow, enabling more automation and integration of apps, ultimately reducing overhead costs.

Many legacy systems are expensive and complicated to migrate. Retaining these systems but capturing information held within them through low-code platforms makes all that intelligence available to the user. Low code simplifies. It brings efficiency and value to the business while managing costs and risks.

See also: 3 Ways to an Easier Digital Transformation

Moving to this level takes significant commitment. Insurance IT infrastructure can be well out of date. If merging old technology with new was a simple one-to-one proposition, every company would’ve done it long ago. Additionally, mergers and acquisitions among organizations that keep creating short-term demands to absorb various legacy systems steal from long-term transformation plans.  

There are no indications that this fluctuation will slow any time soon. While making sense in a chaotic environment,  insurers must also choose and commit to agile, modern digital solutions that address this legacy influence. 

No plug-and-play solution resolves all these complicated obstacles. Demonstrated expertise in navigating technical roadblocks should be sought. Doing this will position the business to incorporate the latest technology to design a system that functions with power and features that meet the business needs and customer demands.


Vinayak Joglekar

Profile picture for user VinayakJoglekar

Vinayak Joglekar

Vinayak Joglekar is head of India operations and chief technology officer at Excellarate, with more than three decades of professional software development and delivery experience.

Joglekar is a certified J2EE programmer and an architect interested in social, mobile, cloud and big data technologies.

Joglekar earned his mechanical engineering degree from the Indian Institute of Technology and a master’s degree from the Indian Institute of Management and mentors bright minds in software development and product delivery.

In2Risk Call for Proposals

What does the future of insurance look like? We want to hear from thought leaders like you. Submit a proposal today and explore all the ways insurance is Shaping the Future. The possibilities are endless. 

"ready...set...submit"


Elevate yourself as a thought leader in the risk management and insurance industry by submitting a proposal to speak at In2Risk 2022, one of the risk management and insurance industry’s best annual events hosted by the CPCU Society. Each year, thousands of insurance professionals with a diverse range gather to network and explore emerging issues and educational topics. to be considered for In2Risk, taking place this Nov. 10–12, in San Francisco.

Shaping the Future

What does the future of insurance look like? We want to hear from thought leaders like you. Submit a proposal today and explore all the ways insurance is Shaping the Future. The possibilities are endless; consider the future of:

  • Exposures
  • Coverages
  • Underwriting
  • Insurtech
  • Technology risk
  • Microinsurance
  • Parametric Insurance
  • Artificial intelligence in insurance
  • The insurance workforce
  • Diversity, equity, inclusion
  • Risk management
  • Risk mitigation
  • Loss control
  • Career development
  • Leadership
  • Customer success and sales
 

How to Submit a Successful Proposal

on submitting a successful proposal for In2Risk 2022 and increase your chances of being heard.

Don’t delay, share your ideas and let your creative, relevant, and inspiring presentation shape the future. We look forward to hearing from you. Not ready for a full-hour presentation? Submit a proposal for a 10-minute, Ted-style flash talk.


If you have questions about this process, we’re here to help! Please reach out anytime to our Member Resources team by email at or by phone at (800) 932-2728.


Secure your In2Risk 2022 Sponsorship Today

Click here to learn about sponsorship packages and custom options.

For more information, contact Adam Lachowicz

at Lachowicz@TheInstitutes.org or (610) 251-2738


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Data Modernization Isn't One-Size-Fits-All

Large and small carriers, in most cases, have inherently different business processes, capabilities and priorities due to their variance in size.

data

The insurance industry’s historic legacy is a double-edged sword. As an industry with roots that span as far back as the days of Hammurabi’s Code, the insurance world’s stability has both provided security and, at times, resisted necessary change. One of these necessary changes is the adoption of new technologies to structure the processing of the massive increase in data that the modern world brings. As the global insurance ecosystem dives further into digitization, the problem of big data will only persist should carriers choose not to adapt to this new status quo. 

However, not all challenges may affect all insurance industry players equally. Large and small carriers, in most cases, have inherently different business processes, capabilities and priorities due to their variance in size. How might these key differences affect their abilities to address the needs of the 21st century with new data-structuring technologies?

Larger carriers’ challenges lie in their scope and age. These organizations have typically existed for longer than their smaller counterparts, meaning they usually rely on relatively older legacy systems and processes. This long-standing dependency on legacy systems creates a greater technical debt, meaning that larger carriers will usually have to play digital “catch up” on a deeper structural level in their business processes. 

Additionally, larger carriers typically use multiple platforms for the same business operations (e.g., multiple policy admin systems across different lines of business), as opposed to smaller carriers, which typically use one. Larger carriers face a lack of uniformity in data collection, adding operational efforts (such as extract, transform and load, or ETL) to sync up data formats from different sources. 

The challenges smaller carriers face differ, but they are equally pressing. These smaller organizations often have a lower budget allocation for IT modernization. This may result in compromising on the benefits of data structuring in favor of short-term growth. Smaller carriers typically also face more competition in their segment of the economy, so any data restructuring may not establish them as leaders in their field right away. Additionally, once their initial investment is made, smaller carriers must keep up the momentum by staying in the loop of even newer technologies. This fast-paced modernization may cause some strain on their budgets and could be unsustainable. 

See also: Technology Addiction: A Fatal Distraction

Larger carriers’ advantages come from their size and resources. They typically have larger IT budgets, so investments in new technology will not put as much of a financial burden on them. Because of these larger budgets, they also can sustain these investments for the long term. Larger carriers often inherently have more data than smaller carriers due to their many platforms and lines of business, and leveraging such data enables them to reap the benefits of modernization more immediately than their smaller counterparts. 

Smaller carriers, on the other hand, have advantages in that they are typically dealing with less data relative to that of larger carriers. The platforms they use for business operations (such as billing and claims), are typically common across lines of business, as opposed to larger carriers that usually have multiple platforms. Due to these reasons, smaller carriers can adopt new technologies to facilitate data structuring with greater ease and flexibility. 

Regardless of the unique considerations for differently sized carriers, it is clear that adopting technologies to drive better business function is an overriding business need. The benefits of embracing data structuring are far and wide; it can not only enhance the efficiency of insurance functions but can improve their accuracy. From risk underwriting to pricing algorithms, and target-driven product development to claims fraud detection, all aspects of the insurance value chain can greatly benefit from the enhancement of data organization.

How, then, can carriers of different sizes tackle the challenges of adopting new data structuring technologies? For smaller carriers, a key strategy is tighter planning and allocation of resources. Stakeholder expectations must be set realistically, as data restructuring may not yield immediate results. A well-tested method of alleviating financial strain is taking advantage of open-source or relatively inexpensive technologies to provide a basic framework for adoption. This helps alleviate the risks involved in investing with a limited budget.

For larger carriers, establishing long-term goals for adoption can help provide a solid foundation for implementing new technologies. The level of restructuring required at carriers of such a size is innately more complex and time-consuming than that required of their smaller counterparts. Therefore, aligning objectives and intent across the organization is an essential step in preventing delays and inaccuracies as new technologies are applied.

See also: Insurance Technology Trends for 2022

Carriers of all sizes would benefit deeply from an investment budget that is flexible and makes room for contingencies. Persistence is the key when it comes to implementing modern technology. Defining clear goals and setting achievable expectations based on available resources will both allow technological investments to be sustainable and build a better foundation for future adoptions. 

As the insurance industry becomes more global and digitized each year, the fact still stands. All organizations, large or small, must acquaint themselves with these new methods of enabling standardized data structuring, collection and sharing – or risk getting left behind in the modern digital age.


Vaibhav Uttekar

Profile picture for user VaibhavUttekar

Vaibhav Uttekar

Vaibhav Uttekar is vice president, products and development, at ACORD Solutions Group.

He has responsibility for overseeing resource-intensive, insurance-centric software products that operationalize the industry-wide ACORD standards to drive efficient data exchange and digitization.
 

A Better Approach to Extended Warranties

Field service management software can digitize steps of the warranty workflow to improve customer satisfaction and provide quality and convenience.

digital

Home and extended warranty providers cover appliances and products that break down – a useful service if you are a customer facing hefty and unexpected repair bills. However, customers are often frustrated when engaging their warranty plans because of confusing terms and coverage plans, long wait times and an unclear process. Field service management software can digitize steps of the warranty workflow to improve customer satisfaction and provide quality and convenience.

1. Put the customer first

The warranty market is a client-first industry that is focused on insuring items that mean a lot to customers. Therefore, it’s critical that the customer journey provided by warrantors is seamless from end-to-end. By implementing connected digital platforms into the service experience, providers increase transparency and communication with their clients, giving them step-by-step updates on their requests, timelines and invoices. Customized, self-service online portals enable customers to schedule maintenance or repair, check service technicians’ whereabouts and status and communicate directly within a mobile application or browser. In fact, 90% of customers expect a business to offer an Uber-like experience with a self-service portal. A centralized location for all service information allows customers to access details of their policy and work history at a moment’s notice and provides simple touchpoints for interaction with the servicer. Consumer-related metrics like customer happiness and response times account for 55% of Forbes Home’s rankings of warranty companies, reinforcing that, when customer is king, the entire business prospers.  

2. Improve the on-site experience

The structure of the warranty system means companies rely on field service technicians to represent their organizations when interacting with the customer. It is therefore crucial that technicians are properly prepared to deliver high-quality service during their visit, to build customer loyalty through an enjoyable experience that resolves the customer problem. Providers that leverage artificial intelligence (AI) through field service management systems can intelligently dispatch the best technician for the job, equipped with the tools and parts needed to get the job done. Leveraging AI-based schedule optimization software can increase productivity by 68%, and AI capabilities not only delight the customer during the service interaction but can also help clients manage their possessions within their policy. Integrated AI can send out alerts to connected devices warning against imminent product recalls and predict potential repairs. Implementing technology that puts the customer first and focuses on service experience will differentiate warranty businesses from their competitors. In fact, consumers that purchase extended warranties and service contracts are twice as likely to recommend the retailer where they made purchases, making their experience all the more important.

See also: How Technology Is Changing Warranty

3. Simplify the process

Once the service work is completed, the servicer must be paid for work performed, and the repair must be logged against the warrantee’s policy. The best full-service digital platforms offer management solutions that enable automated warranty claims processing and intelligent audits based on business logic. Automated claim adjudication with built-in validation improves efficiency and protects warranty reserves. This automated technology also prevents fraud and reduces costs by only validating claims that are eligible for payment and reducing turnaround time on claim status and payment processing. Internet of Things (IoT)-enabled claims management and real-time business intelligence allows providers to cull through information faster to make data-driven decisions. With an organized system of information easily accessible, business leaders can automate standard processes and quickly review key performance indicators (KPIs) in real time to understand and improve service operations. 

4. Expand support systems

Warranty providers often cover products for third-party organizations, meaning they usually serve a wide range of clientele. Warrantors, in turn, must often depend on a blended workforce of full-time, part-time and contracted technicians and employees to meet demand. However, properly managing a large remote workforce that is constantly on the move is challenging and time-consuming. Field service management software is a comprehensive tool that offers providers the ability to engage a broad network of qualified technicians, integrate contractor onboarding and intelligently dispatch workers for the best results. Blended workforces can help eliminate skill gaps, expand geographic reach and support changing demand with a supplementary service provider network. By using software that ensures dispatched service techs have the required background screenings, insurance coverage and certifications and that dynamically chooses contractors based on rankings and credentials, warrantors can increase appointment bookings and reduce rework. In fact, 73% of companies with a blended workforce outperform competitors with employed-only staff, and leveraging workforce managing technology can help businesses scale without dampening service quality. 

Warranties are an important part of home and property management. As more individuals choose to work remotely and increase the time spent using their appliances, devices and vehicles, the coverage for these items will be more important than ever. Implementing comprehensive service management software into warranty business operations can help improve customer service, expand service offerings and automate existing processes to free time and reduce costs, all while improving the quality of service for steady customer retention and brand reputation.


Brad Hawkins

Profile picture for user BradHawkins

Brad Hawkins

Brad Hawkins is senior vice president of products and solutions at ServicePower and oversees product management and pre-sales engineering across North America and Europe. A long-time veteran in the world of field service technology, Hawkins brings more than 20 years of experience in workforce management software.