Carrier’s Perspective on Large WC Claims
Large workers' compensation claims are infrequent but are increasing rapidly and can now reach $20 million.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Mark Walls is the vice president, client engagement, at Safety National.
He is also the founder of the Work Comp Analysis Group on LinkedIn, which is the largest discussion community dedicated to workers' compensation issues.
The answer is now clear: It's important to be insurtech. Many startups are generating real value.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Karen Pauli is a former principal at SMA. She has comprehensive knowledge about how technology can drive improved results, innovation and transformation. She has worked with insurers and technology providers to reimagine processes and procedures to change business outcomes and support evolving business models.
The latest hype from Lemonade is about a revolutionary “open source” homeowners/renters policy. Let's look at what's in there.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
William C. Wilson, Jr., CPCU, ARM, AIM, AAM is the founder of Insurance Commentary.com. He retired in December 2016 from the Independent Insurance Agents & Brokers of America, where he served as associate vice president of education and research.
How do you ensure that you are doing the right things at the right times and in the right sequence?
Becoming a digital insurer is an essential requirement for being competitive in insurance today – but even more so for the future. Your digital strategy becomes the framework from which to leverage all other transformational initiatives, not only for the customer experience but for the employee and operational experiences, as well. This process requires clarity on priorities, focus and mindset to determine the path, the sequence and the right investments to reach the ultimate goal – going beyond a digital experience to transformation.
See also: Seeing Through Digital GlassesOur research shows us that while no single insurer is doing everything, every insurer is doing something, and some are doing more than others. So, how do you ensure you are doing the right things at the right times and in the right sequence? The following is a list the 10 essential actions required for success as you develop and execute your digital strategy:
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Deb Smallwood is the founder and CEO of SelfPowerment.
She spent four decades in corporate leadership across the insurance industry, operating at the intersection of business, technology, and organizational transformation. Her leadership inflection point led her to research the experiences of more than 50 high-achieving women and 10 men leaders. This formed the foundation of her book, SelfPowerment: The Inner Shift for High-Achieving Women Who Want More Than Just Success. The work introduces a research-informed framework that redefines success from within and invites women to shift the question from, “Will they choose me?” to “Do I choose them?”
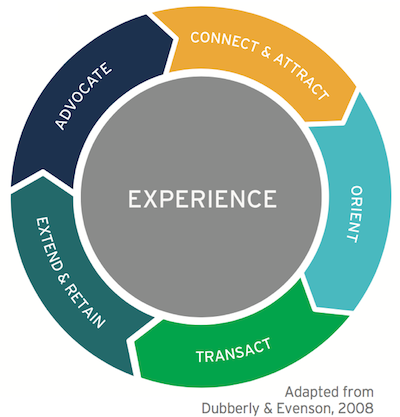
You must understand the phases of the customer experience cycle and align all channels around the experience you want to create.
1) Connect and Attract: We must find the people who are best suited for what we offer and engage them in a way that’s meaningful to them, leading to openness to learning about what we can deliver.
Best suited means many things. With life insurance, in particular, it can mean health classification, financial status, need or even geography, as residents of certain states can’t get access to all products available. To figure out how to sort people, we need the most sophisticated tools at our disposal.
In addition, we must communicate in an authentic way, especially in scenarios where there is no human being talking with customers. If they are engaging in an online environment, the communication needs to “feel” human and real.
2) Orient: Here is where we help people understand what they should expect in the process, how long it takes and why we do things the way we do (e.g., asking personal questions). This helps set the expectation for what comes next so that they feel empowered and not “in the dark.”
3) Transact: Here is where we actually exchange a person’s time, data and money for a product. In life insurance, this is where the application lives and the way in which we take payment. There has been a great deal of industry focus and technology development around this phase to help life carriers improve the customer experience, work smarter (not harder) and attract new business by leveraging data and advanced analytics to use a more streamlined approach to assessing risk.
4) Extend and Retain: This is fancy talk for how we make sure we are delighting our new customers in unexpected ways and keeping them. For the life insurance industry, this phase will be particularly challenging, as it has been focused mostly on the process of how bills are received, preventing lapses and, ultimately, how claims are handled. These, however, are table stakes. Raving fans don’t come from meeting expectations; they come from exceeding them.
5) Advocate: Here is where a raving fan gets to tell others about his/her experience and presumably get others involved. While life insurance is generally a low-involvement product category, and one that is challenged by negativity associated with death, there are indirect ways to find positives within the experience.
We have an opportunity to create positive experiences through services, information exchange and learning and creating awareness of others’ experiences. The Ice Bucket Challenge for ALS is an example of where negative feelings of fear and helplessness were turned into people feeling empowered to help. The challenge went viral, creating much greater awareness and research funding for a disease that many knew little about. In what ways might the life insurance industry take a lesson from that?
The key to all of this is a deep understanding of your customers and potential customers coming from unrelenting curiosity, leading to compassion and empathy. Learning and embodying the tenets of the customer experience cycle is a good first step to understanding.
See also: Making Life Insurance Personal
If you’d like to learn more, click here to register to join us for a complimentary 45-minute webinar with 15-minute Q&A on Thursday, May 24, 2018, at 2:00 p.m. ET in partnership with LexisNexis Risk Solutions. During this first webinar, our speakers will explore the first phase of the customer experience cycle — Connect and Attract — and share key insights and findings that life carriers can use to transform the customer experience in life insurance, starting at the point of marketing.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Maria Ferrante-Schepis is the managing principal of insurance and financial services innovation at Maddock Douglas.
Eventually, organizations evolve into totally dysfunctional bureaucracies that must be ripped apart to allow for something new.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Mike Manes was branded by Jack Burke as a “Cajun Philosopher.” He self-defines as a storyteller – “a guy with some brain tissue and much more scar tissue.” His organizational and life mantra is Carpe Mañana.
The mobility-insurance market can become one connected ecosystem to the benefit of all participants.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.
Bill Brower is senior vice president, industry relations and North America claims sales, at Solera.
Technology is opening the door to realignment of the insurance value chain, the product itself, technology stacks and IT management.
Realignment of the Technology Organization. All business units are more dependent on technology than ever before, and the widespread adoption of agile is helping to improve communications, relationships and collaboration between IT and other business units in many ways. But there’s still a fundamental disconnect in many companies between the way that IT evaluates its own performance and the way that other business units evaluate IT’s contribution to achieving the company’s goals. We published research this year on the benefits of using business KPIs and IT value metrics, to ensure shared understanding and the feeling of shared values between IT and other business units.
I closed with our nine questions for insurer IT leaders, all of which encourage re-evaluation of current practices and attitudes from an outside perspective. For example, instead of asking how to manage the threat of insurtech, ask what can be learned from these new entrants that are approaching the industry with a fresh point of view. Instead of asking how to win the war for talent, ask what is the value of working at your company? And instead of asking how to justify an IT investment, ask, how does the IT capability drive business results?
Guest Keynote: Scaling and Growing High-Performance Organizations
Chris Yeh has founded, invested in or advised more than 50 high-tech startups. He is the co-author, with LinkedIn founder Reid Hoffman, of The Alliance: Managing Talent in the Networked Age and the forthcoming Blitzscaling, based on a class he team-taught with Hoffman and others at Stanford. His presentation covered material from both works. If I had to pick out a single theme from his keynote, it would be clarity.
Blitzscaling, the ability to grow an enterprise quickly, requires a clear understanding of the goals and risks. It’s defined as: “The pursuit of rapid growth by prioritizing speed over efficiency in the face of uncertainty.” This is a conscious choice to do things in a particular way that might be viewed as “wrong” by other frameworks but makes perfect sense when viewed against the Blitzscaling opportunity.
The clarity of the strategic decision cuts through the noise of demands for efficiency. While insurers may not have many opportunities to Blitzscale, having this same level of clarity around goals to insulate them from traditional operational demands is critical to the ability to drive innovation.
See also: How Technology Drives a ‘New Normal’
The Alliance framework for talent acquisition and management has a similar level of clarity to it. Companies and the people they need each have diverse objectives, some of which align and some of which do not. However, most talent strategies don’t acknowledge this, and are built on a level of disingenuity on both sides. By starting from a clear-eyed assumption that the employee is building a career that may involve leaving the company at some point, both parties can focus on creating mutual value and growth during the period of their alliance.
As one CIO commented to me later, “Chris talking about looking at your employees as having ‘tours of duty’ and how we as leaders need to look at how we help them ‘level up’ was very relevant to some actual personnel situations I’m dealing with.”
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Matthew Josefowicz is the president and CEO of Novarica. He is a widely published and often-cited expert on insurance and financial services technology, operations and e-business issues who has presented his research and thought leadership at numerous industry conferences.
How do we effectively integrate “technology of tomorrow” with “business models of today” and interpret the “culture of yesterday”?
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Steven Schwartz is the founder of Global Cyber Consultants and has built the U.S. business of the international insurtech/regtech firm Cyberfense.
If the complex renovation of systems at many insurers casts a cloud, then the silver lining is the greater scale that it will enable.
"Advanced analytics, combined with digital and social tools, can provide a much more cost-effective way of reaching clients, and educating them about risk and prevention. We know that clients understand the concept of life insurance but still aren’t familiar with the products themselves. Through analytics tools and possibly AI we can deliver more information to the market, customised to clients, in a proactive way." — Catherine Bishop, Head of Insurance Strategy and Data at RBC InsuranceObviously, some products and segments are riper for growth than others, and it is by identifying these early on – as well as the particular customer pain points to be overcome – that insurers can bring much-needed focus to their transformation efforts, which otherwise threaten to become too thinly spread and to do no more than reduplicate the flaws of the legacy business, just in a shinier form. ‘Insurers need to shift their orientation and look at the needs of individual market segments. Instead of starting with the risk, they need to start with the market,’explains Novarica's Matthew Josefowicz. ‘They need to be asking: what kind of coverage does the market need, how much detail do they want in it and how comprehensive does it need to be in terms of what they need to buy?’ Josefowicz points to several innovative new entrants who are successfully taking this bottom-up approach to insurance. ‘There are innovative companies like Slice that are doing insurance for the gig economy, and there are folks like Trōv who are doing single-item insurance in a scalable way – so there are many ways to approach the different kinds of risk that buyers need insuring,’ he expands. In many cases – particularly in mature markets like North America – the factor inhibiting growth is not the price or extent of coverage per se but rather insurers’ failure to distribute the product in an appropriate way. ‘I think that for some insurance lines, for example in life insurance, the reliance on traditional distribution and traditional sales processes is actually boxing the industry out of some market segments, who just won’t tolerate that buying process,’comments Josefowicz. ‘Life insurance is very under-penetrated in North America, and I think the opportunity is to use technology to make the buying exercise easier for those under-served segments that have been put off by inefficient and unpleasant buying processes.’ The injunction to double down on the customer – rather than simply redoubling sales efforts on fundamentally outdated products – applies not just to personal lines but also to commercial ones. The reality of doing business, whatever industry you are in, is changing rapidly, and the palette of risks businesses need protection against would be unrecognisable to the insurers of yesteryear, one conspicuous addition being cyber risk. Josefowicz believes that it’s still early days but that insurers are now moving towards effective product offerings in this challenging area.
"The most progress will likely be made by partnerships between innovative nimble start-ups and incumbents who are skilled at navigating a highly regulated and complicated ecosystem. Insurtech is not a zero-sum game." — Nick Martin, Fund Manager at Polar Capital Global Insurance FundWe have touched on the endeavours of Insurtechs Trōv and Slice in creating more fit-for-purpose insurance products, but it is important to bear in mind that the confrontation between insurers and Insurtechs is not a zero-sum game, given that it is happening in the context of an expanding addressable market. We asked our local commentators to go into a bit more detail on how they see this ‘confrontation’ playing out. As we see in our other regions, there is a trend towards collaboration between incumbent insurers and Insurtechs. While the disruptive intent of some players is clear, many of them, strongly backed by none other than insurers themselves, will end up as components of the overall technology stack. In some cases, the Insurtech start-up is in fact just an incumbent appearing in a nimbler guise. Insurance Solutions Group's Stephen Applebaum gives the example of Canadian insurer Economical, which last year created brand-new start-up Sonnet as a way of innovating more quickly than they would be able to in-house. ‘Economical traditionally was an agency distribution model, so all of their insurance was sold through agents,’ clarifies Applebaum. ‘Sonnet is a direct-to-consumer business, so that’s the way Economical is going to walk both sides of the street.’
"There will be an evolution of customer experience. Economical is the first to launch as a coast-to-coast, fully digital service and there is education required in the marketplace, but my expectation is that others may well follow our path and this will be the customer’s expectation." — Michael Shostak, SVP and Chief Marketing Officer at Economical InsuranceJosefowicz stresses the role of Insurtechs as trailblazers over and above their much-hyped role as predators. ‘A lot of the new entrants are pointing the way. I don’t know how many of them will become significant competitors in and of themselves, but they are clearly demonstrating to insurers that there is an opportunity to engage differently with customers and that customers are hungry for a different type of engagement,’Josefowicz explains. ‘To put it in a capsule, I don’t think Lemonade is going to become the biggest personal insurer in the world, but I do think a lot of personal insurance is going to look like Lemonade in the near future.’ See also: Global Trend Map No. 7: Internet of Things Following Insurtechs down this route, be it through imitation, partnership or outright buying, will allow insurers to open up and serve those market segments that have hitherto been cut out of traditional forms of distribution and service – much like prospectors returning to bypassed reserves in mature oilfields – and this is where they should set their sights. ‘I think the most successful Insurtechs will be purchased by insurers, similar to the Allstate purchase of Esurance from the previous generation of e-insurance start-ups,’Josefowicz concludes. That concludes our Regional Profile on North America. Next week we move on to our Regional Profile on Asia-Pacific, with insights from Steve Tunstall, CEO at Singapore-based Insurtech start-up Inzsure, João Neiva, Head of Innovation, IT and Business Change at Zurich Topas Life in Indonesia, and HK-based David Piesse, Chairman of IIS Ambassadors and Ambassador Asia Pacific at the International Insurance Society (IIS). Key discussion points include:
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Alexander Cherry leads the research behind Insurance Nexus’ new business ventures, encompassing summits, surveys and industry reports. He is particularly focused on new markets and topics and strives to render market information into a digestible format that bridges the gap between quantitative and qualitative.Alexander Cherry is Head of Content at Buzzmove, a UK-based Insurtech on a mission to take the hassle and inconvenience out of moving home and contents insurance. Before entering the Insurtech sector, Cherry was head of research at Insurance Nexus, supporting a portfolio of insurance events in Europe, North America and East Asia through in-depth industry analysis, trend reports and podcasts.