Download

Visions of Safety and Pictures of Success

The construction industry needs more video cameras to prevent accidents -- and shows the insurance industry a path to progress.

Sight is the savior of the insurance industry. Where insurers were once lost, where they were once blind, they can now find their way because they can see the way to safety and success. That technology allows policyholders to see everything is the best insurance policy of all. That video cameras reveal what we cannot otherwise see, that we have the power to prevent accidents by avoiding the most egregious ones altogether, that I continue to say what I see—that I have written about this issue twice before—should inspire insurers, I hope, to acknowledge that what is essential to one industry, the construction industry, is also essential to the insurance industry. Specifically, video cameras are a necessity for crane operators and their fellow construction workers. Video cameras are a necessity for all people at or near a construction site, because were a piece of equipment to fall and kill a worker, as it did in Bradenton, Fla.; because were a similar accident to happen again—that it will happen again is almost inevitable—insurers will have to pay tens of millions of dollars in damages, unless they accept the truth by seeing it for themselves: that construction is perilous; visibility (without video cameras) problematic; safety precarious. See also: Construction Safety: Listen, Learn and Lead   Sight is not the problem. The inability to see without the help of video cameras is—and will remain—a problem, not because crane operators do not have perfect eyesight, but because no person can see what is not in his line of sight. The refusal to subsidize the purchase of video cameras, or to give policyholders incentives to buy and install these cameras, is the biggest problem facing insurers on behalf of the construction industry. According to Chris Machut of HoistCam, lack of sight is no oversight. Which is to say crane operators cannot see what they need to see—what they have a right to see—if they do not have video cameras to assist them. “Far from increasing liability, video cameras lower the risk of accidents or injuries. In so doing, insurers can save more money than they spend regarding payouts to construction companies,” Machut says. If insurers are reluctant to change, and they are, it is more a matter of operations than opposition. They run their companies like they underwrite their policies, with caution, which can cripple their ability to change, which can—and has—cost them the chance to stay ahead, which may cost them clients in many industries. See also: Let’s Open Our Eyes to Work Safety Issues   If insurers listen to construction workers, if they do more than listen, they will know where to look and what to see. They will see the images that crane operators see, courtesy of the video cameras on construction cranes, that make it less expensive and more efficient for these workers to do their jobs. If insurers embrace today’s technology—if they have even modest expectations about the present—they will nonetheless make tomorrow a vision to behold. That vision is worth the investment. That investment starts with video cameras. That vision is too great to ignore.

Start-up Financials Show Progress in 2018

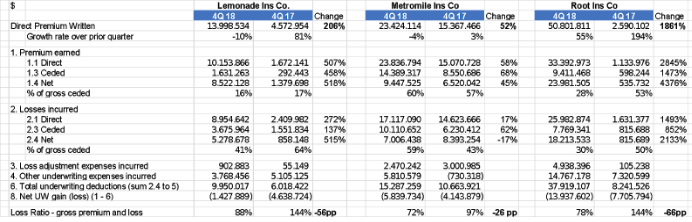
Quarterly growth for Lemonade, Metromile and Root was the slowest ever, but all three paid out in claims less than they collected in premium.

|||||
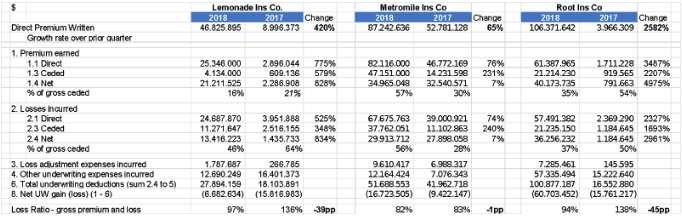
The three P&C venture-backed U.S. insurtech start-ups -- Lemonade, Metromile and Root -- finished 2018 with pretty good results. Quarterly growth was the slowest ever, but all three paid out in claims less than they collected in premium. All three start-up carriers have more work to do to achieve sustainable financials. A year ago, when I started with my friend Adrian a public conversation about insurtech statutory results, the picture was ugly -- loss ratios well over 100%, an aggressive focus on price and promotional messages on company blogs that dismissed traditional measures of success in insurance. Since the first post titled "5 Dispatches From Insurtech Island,” the conversation has shifted dramatically. Fast forward a year, and one founder said he “messed up an entire quarter” because premium growth turned negative, when in fact the company generated its best quarterly loss ratio ever. In the months since, several start-ups have hired top underwriting talent from their traditional competitors, showing that they increasingly recognize the value of traditional insurance skills. Skeptics point out that a quarter doesn’t mean much, that there’s a long way to go before reaching sustainability and that each additional point of loss gets harder to take out. True, but the increased focus this year on reducing losses and increasing prices is making a difference. Here are the quarterly results: I think – as already mentioned in the previous articles - these companies have strong management teams who could ultimately create valuable businesses. This will take several years, but all three companies are well-funded, even if the combination of statutory capital injections and operating losses consumes tens of millions in capital each year. (The Uber/Lyft model of growing rapidly while also incurring large losses is doubly penalized in insurance because carriers have to maintain statutory capital that increases with premium.) Here is a year-over-year comparison. The three companies have sold in the last 12 months between $40 million and $110 million, less than some of the early 2017 enthusiastic forecasts that Lemonade (for example) would hit $90 million of premiums by the end of 2017. In auto, I pointed out at my IoT Insurance Observatory plenary sessions that the pay-as-you-drive telematics approach seems to attract only the niche of customers that rarely use cars – maybe a growing niche, but not a billion-dollar business (in premium at least). See also: 9 Pitfalls to Avoid in Setting 2019 KPIs   Loss Ratios Loss ratios have all been below 100%, which is a great improvement from the 2017 performances. The quarterly dynamics show a positive trend, but these loss ratio levels are far from the U.S. market average for home insurance (Lemonade) and auto insurance (Root and Metromile). While loss ratio is a fundamental insurance number – claims divided by premiums -- I've been asked how to normalize/adjust the loss ratio of a fast-growing insurtech company. Imagine a fast-growing insurer with the following annual figures:
  • Premiums written: $10 million
  • Premiums earned: $6 million
  • Claims paid: $2 million
  • Losses incurred but unpaid: $5 million
Any of the following numbers might be called a “loss ratio”:
  • Claims paid divided by premiums written: 20%
  • Claims paid divided by premiums earned: 33%
  • Claims paid and losses incurred divided by premiums written: 70%
  • Claims paid and losses incurred divided by premiums earned: 117%
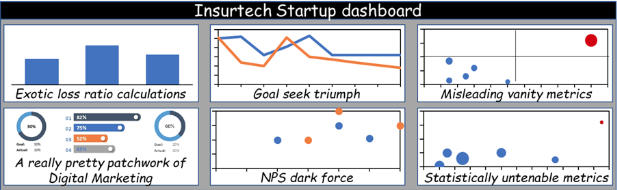
The least attractive is the right one. Claims paid and losses incurred divided by premiums earned is the loss ratio, for a fast-growing start-up as for a large incumbent. The others are only “exotic loss ratios.” I’ve heard people say that accounting rules cause the loss ratio to be overstated based on the following unlucky scenario: There is a book of business done by a one-year homeowner’s policy sold for $730. This policy will earn $2 of premium each day. If a $100 claim (net of the deductible) is received on that first day, the loss ratio is 5,000%. That’s how it works, but is it overstated? Well, as long as premium is being earned, more claims could arrive and the loss ratio could go even higher still. Obviously, you expect the following 364 days to be less unlucky for this portfolio. But I don’t think there is any need to adjust that loss ratio…only to know that is not (statistically) relevant. The analyzed start-ups have portfolios of more than 100,000 policies, so the bad luck can’t be accountable for eventual unfavorable loss ratios. It could be that some approaches are specially targeted for fraud, and it only takes a few fraudsters to cause big problems in the loss ratio on a small book, as the above illustration shows. Some start-ups have advertised how quickly they pay claims, sometimes not even having a human review them, which invites unsavory people to pay a small amount to start a policy then “lose” a valuable item. Early on, when less premium has been earned, this fraud has a particularly great impact on the loss ratio. Over time, in a bigger and more balanced book, fraud gets tempered by the law of large numbers. Additionally, some start-ups have offered large new-business discounts. If they can retain customers, reducing the premium leakage, their second-year loss ratios should be more reasonable, but the overall loss ratio will be elevated for however long they are acquiring customers with aggressive discounts. Expense Ratios I would love to discuss also the other lines of the income statements, but unfortunately they are not meaningful or comparable any more, because companies now move expenses among their entities not represented in the yellow books. The cost amounts represented in the yellow books are only a part of the real costs necessary to run the insurance business. The statutory information I’m commenting on is reported only for insurance companies, not agencies, brokers or service companies. The term “insurance company” or “insurer” has a very specific meaning: “the person who undertakes to indemnify another by insurance.” Within an insurance holding company, it is typical to have an insurer and an affiliated agency, and sometimes other affiliates such as claims administrator. The insurer pays the agency to produce policies. This may feel like moving money from one pocket to another, but there would be reasons for it -- which I won’t get into now. The point for commentators and investors is to beware of this: If an insurer (for whom the public receives financial data) pays an affiliate 25% of its premiums to provide certain services, then the insurer’s expenses (which are reported in the yellow book) are set at (or close to) 25% of their premiums, regardless of what they actually are. Major investors are typically privy to large amounts of information and can disentangle the back-and-forth between the insurer, agency and holding company. For smaller investors, or those who simply pick up a statutory filing, it is easy to be misled. At the beginning of 2018, Lemonade was no longer consolidating its parent and affiliate expenses into Lemonade Insurance Co., its statutory entity. Lemonade’s CEO commented that this change was at the request of its home state regulator. Root followed suit in October 2018, so the 4Q18 expense ratio is moved to 28% from the 70% in the 3Q18. So the “new” expense ratios (and therefore combined ratios) are artificial and not comparable with the previous ones or with competitors'. While regulators may have reasons for their actions, it is better for students of insurance innovation to know the full, real financials, so as to determine if the start-ups are ever able to “walk the talk” of better expense efficiency from “being built on a digital substrate.” Unfortunately, bloggers are not the main audience of statutory filings. Nonetheless, innovation cheerleaders, investors and journalists …please pay attention to these accounting differences before commenting the performances. Since the beginning of the quarterly discussion of U.S.-based insurtech carriers’ financials based on their public filings, many have responded that these players needed to be evaluated on other metrics, too. I agree, so let’s look at one of those measures and talk about some questions to determine whether the measure really stacks up. Misleading vanity metrics The insurance value chain is complex and difficult to compare across models. This can lead to comparisons between very different companies. Take these two hypothetical companies:
  • Company A — flashy Start-up Insurance Co. uses outsourced call centers, bots, incessant Instagram ads, comparison rater websites, third-party claims administrators and a slick app. It sells one line of insurance, only personal, with low limits, and has no complicated old claims (yet). If your house burns down, you open an app and wait. The company has a low expense ratio, high acquisition costs and a high loss ratio.
  • Company B — old Traditional Insurance Co. uses a mix of direct sales, captive agents and independent agents. Claims are handled mostly by agents and in-house staff. If your house burns down, your agent turns up with a reservation for a nearby hotel, billed directly to the insurer. The company sells 12 lines of insurance, including small commercial, and a wide range of products within each line, with bundling encouraged. The company has a high expense ratio, high acquisition costs, strong customer loyalty and losses less than the industry average.
A “vanity measure” could easily make one of these companies look better than the other. The start-up, for example, may claim performance several times better than the incumbent on a “policy per human” KPI, considering in the count of “humans” agents and brokers. Why does a policy-per-human number matter at all? And why is more policies per human better than fewer? See also: Insurtech: Mo’ Premiums, Mo’ Losses   Company A and Company B are two different business models, with two opposite approaches about humans -- neither of which is necessarily better. Steve Anderson and I wrote a heartfelt defense of the model based on agents, brokers and other distribution partners a few months ago. To measure efficiency, I prefer to use the two traditional components of the expense ratio:
  • General operating expense ratio = general operating expenses ÷ earned premiums
  • Acquisition ratio = total acquisition expenses divided by the earned premiums (for high growth companies, it’s acceptable to do the division by written premium). This metric includes advertising, other marketing expenses, commissions and other distribution expenses. However, this number (like CAC) can be difficult to compare - for example, are fixed marketing expenses included or excluded? And the economics of customer loyalty are different between direct (where initial CAC is high but renewal is low) and agent sales (where initial CAC is lower and variable but renewal commissions are significant).
***** I love numbers and – as shared in an interview with Carrier Management - the absence of quantitative elements in self-promoting website articles, conference keynotes, whitepapers and social media exchanges have been one of the reasons for starting the publication of articles about the full stack U.S. insurtech start-ups. Although I’m sometimes described as “critic” or “cynic” about insurtech companies, I’m only critical of the misuse of numbers and am a big fan of those who get the old school insurance KPI right. I’d love to see innovation succeed in the insurance sector, and I wish all the best to these three players and their investors.

3 Keys to Controlling Litigation Spending

Legal departments can take advantage of advanced analytics, cloud technology and other strategies to manage costs.

While the commercial and consumer insurance industry has helped drive economic growth, significant changes similarly are driving increased pressures across multiple lines of business, including legal. Price increases due to record catastrophic losses from natural disasters throughout 2017, economic fluctuations, market volatility, regulatory changes, personal insurance startups and substantial merger and acquisition activity are just a few of the reasons the insurance industry is embracing innovations in analytics and technology. Legal is no exception. Over the last few years, insurance companies have had to deal with a rise in case filings for all types of insurance, including automobile, homeowner, business liability and life insurance claims, with litigation one of the biggest contributors to rising general liability costs. To address these costs, forward-thinking legal departments are taking advantage of advanced analytics, cloud technology and other strategies to not only manage costs, but also realize operational efficiencies and make repetitive insurance litigation a more predictable and repeatable process. Understanding the opportunity Many insurance companies still manage their casework in silos, sending documents and data to multiple law firms and outside vendors, perhaps by area of expertise—when, in fact, a lot of litigation or regulatory inquiries may involve the same insured or type of claim, and thus many of the same documents. Under the current model, the same documents are collected, processed, reviewed and produced for each new matter. When that case is complete, the data and work product is dispositioned. This approach creates massive inefficiencies and unnecessary costs, at a time when legal departments are increasingly being called on to rein in costs and operationalize discovery processes. However, the documents and data that companies produce related to the insured and the types of claims can be a powerful resource for reining in costs early on. With evolving technology--using the economics and access enabled by the cloud--and a centralized approach, legal departments can more effectively manage day-to-day discovery, gain greater oversight and control of litigation and their outside counsel spending—while moving to a knowledge-driven strategic business. See also: Claims Litigation: a Better Outcome?   Centralizing legal data Centralizing legal documents is the key to a more efficient process. In a siloed approach, coding decisions on documents from prior matters cannot be applied to future matters involving many of the same custodians and documents. Coding decisions and even attorney-client privilege documents may differ from one matter to the next, depending on the individual reviewer’s judgments. This increases the company’s risk of inadvertent exposure of sensitive information. When working in silos, you miss the opportunity to “review once and produce many times.” Accordingly, multiple claims by an insured would not need to be recollected and reprocessed, re-reviewed and reproduced each time—again, generating inefficiencies, unneeded cost and risk. Storing your company’s legal documents in a single repository enables your team to leverage prior decisions and documents and aggregate key metrics across cases to support informed business decisions. Centralization also helps keep your data secure by allowing in-house teams to more effectively manage documents throughout the data lifecycle, controlling access and limiting the flow of sensitive information. When using a multi-matter management system with a core repository, each new matter creates greater efficiency because data is collected and processed just once. When new matters arise, documents can be assigned from the core repository to a new matter without needing to collect or process the same data (additional costs), and prior coding can be pre-populated (greater efficiencies)—that is, coding decisions or “tags” such as privilege, confidentiality and other designations are retained for use across multiple cases. Documents can then be efficiently reproduced across matters, allowing for a “review once, produce many times” workflow for commonly produced records. Using technology-assisted review Advanced technology-assisted review (TAR), a form of machine learning, can further reduce costs by decreasing the volume of documents needing human review. The use of TAR 2.0, predictive analytics based on the continuous active learning (CAL) protocol, allows an insurance company's legal teams to review far fewer documents than linear review (reducing document volumes subject to review by 80% or more) or earlier TAR systems, surfacing most relevant ones first. When your team begins coding the documents, the TAR engine continuously surfaces the most likely relevant ones first based on the previous coding decisions. In other words, it is always continuously and actively learning. When the system mixes in contextually diverse documents, a process by which the algorithm is actively finding documents that may be related but are unlike other documents that have been reviewed, the review team will find documents they might not otherwise see. With recent advancements in TAR, it is now effective for more than large outbound productions—it equally is effective for nearly any review task of any size—for investigations, opposing party reviews, deposition preparation and issue analysis and privilege and privilege quality control. The result is that you can continue to increase savings on review and outside counsel fees for nearly every case. See also: Understanding New Generations of Data   Adopting business intelligence By aggregating legal and discovery data, a core repository enables meaningful reporting and business intelligence (BI) for data-driven decisions—outside counsel and vendor spending, effective resource allocation across matters, budgetary impacts of custodian collections, case progress and other key performance indicators. Cross-matter reporting can be used to track across enterprise custodians, collections, deadlines, review metrics and related legal spending, for each and every matter. More advanced technology will have capabilities for providing custodian profiles that track legal hold status, prior collection interviews, historical review metrics and more. Moving legal to a knowledge-driven business unit Legal executives at insurance companies, in particular, due to the nature of repetitive claims and litigation, increasingly appreciate the opportunities afforded by capturing and re-using historical work product and documents where possible, and applying meaningful metrics to manage day-to-day discovery. The traditional silo approach makes that approach virtually impossible. By centralizing your data in a core repository, using advanced analytics to cut review volumes, time and cost and adopting a comprehensive business intelligence strategy, discovery efforts will result in substantial cost savings and move your department to a knowledge-driven strategic business.

Daniel Gold

Profile picture for user DanielGold

Daniel Gold

Daniel Gold is a senior enterprise director for Catalyst (an OpenText company), where he advises corporations on technology-driven strategies.

Why to Rethink Dental Checkups

Four out of five dentists recommend twice-a-year teeth cleaning. Here’s why the fifth dentist is right.

Four out of five dentists recommend twice-a-year teeth cleaning. Here’s why the fifth dentist is right. Ask yourself these questions:
  • Are you healthy?
  • Do you brush your teeth every day?
  • Is your mouth free of problems such as bleeding gums or sensitivity to cold or hot foods and drinks?
  • Do you dislike wasting your money and your time?
If you answered "yes" to all four questions, your answer to "do I need a dental hygiene visit twice a year?" should be a firm NO. Let's face it, we all want to do what we can to have good oral health and a great smile, but it's possible we are overdoing it. Getting your teeth cleaned by an oral hygienist twice a year is not a substitute for the important daily flossing and brushing that you should be doing anyway to maintain healthy teeth and gums. According to research, there are no strong reasons for visiting your dentist twice a year if you are healthy and have no oral symptoms. You might say: "But my dentist insists on twice yearly visits, and he/she is paid by my dental plan!" To which we would say, the reason you might think you have to visit a dentist twice a year is based on marketing, not science. We can go back as far as a successful pre-World War II marketing campaign for Pepsodent toothpaste that encouraged people to brush twice daily and to see their dentists twice yearly. This "twice-a-year" standard obviously benefited both the toothpaste manufacturer and the dental professions. As dental insurance emerged in the marketplace, these plans made coverage of the twice-yearly visit a standard covered service, often at no charge to the policyholder. Voila, a standard of care—one based on no supporting data at all—was born. So you might ask, how often should I see the dentist? It is true that, on average, Americans should be visiting the dentist about twice a year—some more, some less. Here are reasons why you might get dental checkups more than twice a year. For instance, maybe you have risk factors for gum disease or already have gum disease. We also know, for example, that mouth-breathers, smokers, tobacco-chewers and people on medications that cause dry mouth (such as opioids or even diphenhydramine, the main ingredient in Benadryl), have a higher chance of developing cavities. If you have excessive tartar on your teeth, or have had extensive dental work or braces, more frequent dental visits might be wise. See also: Insurtech: Mo’ Premiums, Mo’ Losses If you otherwise have a healthy mouth, a once-a-year visit should suffice. Between visits, the main person responsible for your oral health is you. Poor oral health may be linked to other health problems such as heart disease and pancreatic cancer, and, while those links aren’t fully established, attending more closely to your oral health may prove helpful. Bottom line: Pay attention to the daily tasks of brushing and flossing. If you are healthy and practice good dental hygiene, more than once-yearly dental visits could lead to additional unnecessary costs to you. Four out of five dentists recommend you visit them exactly twice a year. Maybe the fifth dentist knows what he’s talking about. Note: This blog post could inform your dental benefit design. Instead of covering two dental checkups for everyone, for about the same cost, you could match the coverage to the need. Pay the first checkup at 100%, the second at 80% and the third (and possibly fourth) at 60%. It’s the employees who need three or four who are going to have the most dental (and possibly medical) issues down the road.

AI and Results-Driven Innovation

Insurance companies that commit to AI to the same extent as top-performing businesses could boost their revenue by an average 17%.

Data is more abundant than ever, yet in many cases is unstructured, disparate and, well, just very big. Customers now demand seamless, omnichannel and personalized service, and, with a shortage of technical expertise hitting every industry, leveraging the availability of data and the potential of technology is difficult. Moreover, as first movers begin to reap the rewards of integrating advanced technologies, time is running short. As Accenture’s Future Workforce Survey recently found, insurance companies that commit to AI to the same extent as “top-performing businesses could boost their revenue by an average 17%” by 2022. It is therefore incumbent on those that have not acted to do so now, or face irrelevancy. See also: Insurance: On the Cusp of Disruption   Despite the upheaval, opportunities are arising as carriers learn how to leverage changes in their environment. Insurance Nexus spoke to insurance data experts Paul Travers (SVP of finance technology, data and process, MetLife) and Amish Amin (director, claims data analytics, Nationwide) for their perspectives on how carriers can leverage AI, machine learning and chatbots to improve profitability, turbocharge customer experience and make the most of the explosion in data and computing power. Access the full whitepaper here to find out more Our discussions first centered on defining and describing the types of disruption in evidence across the insurance spectrum, with three phenomena in particular having profound impacts: the proliferation of data, rising customer expectations and a lack of suitable talent among the workforce. Addressing these drivers will necessitate changes from top to bottom, from insurance companies’ use of technology to organizational structures and the very nature of job functions that have remained constant for decades. Suffice to say that understanding the causes of disruption is key in such a rapidly shifting environment. The theme of data is very much at the forefront of carriers’ minds. As Travers says, “Insurance is just ripe for disruption…[because] the availability of both structured and unstructured data is unprecedented.” More data may sound promising, but coming from many different internal and external sources and types of technology, the result is “disparate, unstructured data” that makes “traditionally used methods of analysis much harder.” Yet, with the right data governance structures and technology in play, the potential is enormous: MetLife enabled prescriptive analytics of business drivers to unlock real-time decision making. Among all the talk of technology and processes, customers themselves were never far behind the scenes and possibly represent the greatest impetus for insurance carriers to act now. More and more B2C brands (not just insurance) are taking the customer experience as their starting point for innovation due to the influence of new players: agile and digitally native start-ups. These organizations, which have typically arrived on the scene in the past decade, have a massive advantage in that they do not have multiple legacy systems to contend with, so creating a cohesive, personalized and digital experience is easier (relatively speaking, of course). Ultimately, customers vote with their wallets and have demonstrated the appeal of these types of on-demand, personalized and omnichannel service (see the successes of Lemonade, Hippo and Metromile). Legacy carriers need to match these standards and in the process will find manifold benefits other than just to the customer experience. Amin detailed unexpected benefits that Nationwide encountered after revising aspects of the customer interface, which included massive time savings for call-handling agents, as well as the improvement to the customer journey and more efficient processes. See also: New Phase for Innovation in Insurance   Advanced technology and all the data in the world mean very little, however, without the technical expertise and business knowledge needed to analyze data, draw insights and apply them in the real world; “You can’t just get a data scientist to come and solve your insurance problems,” one executive says. Although some organizations have set up partnerships and skills pipelines with local schools, colleges and universities to tap into the next generation of data scientists, few carriers have the resources to hire and train a new team with the required technological expertise and insurance business acumen. There will have to be more creative hiring and training practices than have traditionally been employed in insurance, and our experts shared several strategies to finding and creating the workforce with the right requisite blend of talents, skills and experience. The whitepaper, Results-Driven Innovation: Turbocharging Insurance Profitability and CX with AI, Machine Learning and Chatbots, was created in association with Insurance Nexus’ sixth annual Insurance AI and Analytics USA Summit, taking place May 2-3, 2019, at the Renaissance Downtown Hotel in Chicago. Expecting over 450 senior attendees from across analytics and business leadership teams, the event will explore how insurance carriers can harness AI and advanced analytics to meet increasing customer demands, optimize operations and improve profitability. For more information, please visit the website here.

Ira Sopic

Profile picture for user IraSopic

Ira Sopic

Ira Sopic is currently focused on how insurance carriers are integrating AI and advanced analytics into their existing processes to increase efficiency and revolutionize the way they work. This includes the key partnerships that the industry is creating and a clear picture of how the future will be shaped.

What Ethiopia Crash Says About Safety

The frequency of air disasters has been publicly acceptable for a long time, but the safety margin of “smart” jet transports needs attention.

When news broke about the crash of an Ethiopian Airlines Boeing 737, the first question that popped into my head was whether an older 737 model, still using the flawed rudder actuator, might have been involved. Of course, it was actually the newest iteration of the 737, the Max 8. I’m no longer covering aviation. But having chronicled the saga of the 737 flawed rudder design, which Boeing ultimately replaced, here is what I’m wondering:
  • I wonder if this will turn out to be yet another in a long line of the manufacturer or the airline pushing the edge of the safety envelope, for commercial reasons, with a catastrophic result that should have been anticipated and accounted for.
  • I wonder if there is a trail of maintenance records of related, precursor glitches occurring in the Max 8 fleet.
  • I wonder how rigorous the FAA was in vetting and approving the safety margins for the advanced functions in the Max 8’s complex, automated controls intended to extend the range and capacity of not just the Max 8 but also other 737 models now routinely being used on long-range flights, including from the U.S. mainland to my home state of Hawaii.
If there is any evidence of the steady thinning of the 737’s safety margin translating into operational hiccups that point to the Ethiopian Airlines catastrophe, it should exist in the FAA Service Difficulty Reports airlines are required to file. This is likely where plaintiff attorneys representing victims will hunt — for leverage to win claims for their clients.  However, with so much at stake, it wouldn’t surprise me if there’s a big push by the defendant attorneys representing Boeing and the airline to settle all victims claims quickly for higher-than-normal amounts, thus shutting down the plaintiff attorneys.  This is what happened in the Lauda Air 767 crash in Thailand, caused by a malfunctioning thrust reverser. See also: New Risks Coming From Innovation   Boeing launched the 737 in the 1960s as a small, short-haul transport under intense competitive pressure from McDonnell Douglas’ hot selling DC-8. Competitive pressure drove Boeing to persuade the FAA to relax rules limiting the use of twin jets for very long overseas flights, first to enable trans-oceanic 777 and 787 flights, and then trans-oceanic 737 flights. The frequency of major air disasters has been at a publicly acceptable level for a long time. But this disaster shows the safety margin of “smart” jet transports needs more attention. The grounding of Max 8s reinforces that notion. I hope regulators and the industry honor the 157 lives lost on the Ethiopia Air flight and address the systemic factors, and well as the specific cause, that precipitated this tragedy. This article first appeared here.

Byron Acohido

Profile picture for user byronacohido

Byron Acohido

Byron Acohido is a business journalist who has been writing about cybersecurity and privacy since 2004, and currently blogs at LastWatchdog.com.

What to Look for in an AI Partner

Without a clear vision of the problem to be solved, AI can take an organization down a long and unnecessarily winding road.

As the uses for and ultimate value of artificial intelligence (AI) become more widely understood, organizations across numerous verticals, be they insurtech, fintech or healthcare, are seeking ways to implement AI to their advantage — and vendors are lining up to tell them exactly how to do it. But without a clear vision of the problem to be solved, compounded with a lack of experience in that specific function, AI can take your organization down a long and unnecessarily winding road. It may seem pretty; it may be exciting; but it probably won’t take you where you want to go.

To help your organization find the right match for its needs, here are my top tips to consider when choosing an AI partner: Gain Alignment on the Objective You know you want to use AI and data science within your organization — whether to improve outcomes, achieve greater efficiency, drop operational costs or for another reason altogether. This is a great start, forward progress, but it is sort of like the act of bringing the ball onto the field or the court before the start of a game. AI has permeated marketing speak over the past few years. As a result, many solutions come across as generic or just scratch the surface of what is possible. For this reason, it is imperative that you know what your organization needs and why. Where exactly are the problems? What is the source of leakage? Which bottlenecks do you want to address? What are customers not currently delighted with? Furthermore, think about what metrics you are going to use to measure success and how you are planning to track them. Make a game plan for your team — and remember that you are actually a team with strengths and weaknesses. Understand where they exist and how an AI solution can mitigate those weaknesses. Everyone must be aligned on objectives and strategy for the team to function optimally. Address THE Problem Now that your organization is aligned on objectives internally, it’s time to seek out the vendors that demonstrate a high level of focus on a particular problem and a clear view of how solving that problem creates value. If a company spends its time and resources explaining all about how blockchain, AI and IoT work with its products — and it is being presented broadly as a technology player — this vendor is probably not ready to address your particular organization’s needs. Good AI providers shouldn’t offer an all-you-can-eat buffet. Instead, they should deliver a very precise statement of capabilities. See also: 3 Steps to Demystify Artificial Intelligence   If they can’t dive deep into their problem statement, it doesn’t necessarily mean it is a bad company, but it is a sign of the company’s immaturity. The more the company professes about what its technology can do and the more issues it can address, the more you need to think the company is perhaps a little early in product evolution. Expertise Is a Must Focus is not always enough. Does your potential partner have the expertise to actually solve your particular problem? Expertise is a complicated issue. Partners need a certain level of domain knowledge. The team assigned to your organization must possess an understanding of your unique pain points and overall business. The understanding doesn’t have to be exhaustive, but every industry is unique in some way, whether it’s in terms of regulations or customer profiles or something else, and, if your team is not familiar, it can lead to big problems later. At the same time, deep data science experience is also essential. The models are the foundation of every AI solution. They must be carefully constructed, and now for the super challenging part: They need to be packaged in consumer-grade software and delivered through services that can drive operational impact in a manner applicable to your domain. And expertise does not stop there. Your chosen partner needs to be able to map out a clear path to implementation. Does the partner have a plan for how its solution will be rolled out and who should be involved? Your prospective partner should be able to detail exactly how it will put its solution to work. Ask the partner to walk through how it operationalized its solution within similar environments. Look for a Proven Track Record of Delivering Value When you consider the ultimate value you hope to derive from a new AI solution, you and your AI partner should be aligned — and the partner should be able to show how it will gauge that value. For example, the partner needs to define the specific metrics it is targeting. It’s not enough to say the partner is going to show cost savings and identify lost revenue. How is the company going to do that? What are the methodologies and indicators it will use to quantify, track and analyze? Specifics matter. In this regard, case studies can be particularly helpful because you learn what was done in the real world, why and the specific outcomes of those decisions. The partners that can show discernable evidence of value have a leg up. Interestingly, I have found that one of the things no one tells you is that only part of the value is derived from technology itself. Critical contributions come from those who can identify a very specific problem, see how technology can be applied to solve it and then get the right technology into the hands of people who will put it to work effectively — before they track and calculate its value. There is so much that goes into the entire process, and it’s hard work. So, the challenge is not in finding great technology, the real challenge is in packaging that technology within the context of a business problem and getting a concrete view of how well it’s attacking that problem. An Aside: Set Your Expectations Accordingly If you believe implementing a compelling AI solution will be a quick add-on, you will likely find yourself disappointed. To get it right, to yield the outcomes that matter to your organization, requires an iterative process, just like AI itself. AI partners should be honest about this. While some offer clear advantages and make things as easy as possible based on their expertise and maturity, expect a journey. See also: Chatbots and the Future of Insurance   Also, to ensure expectations are met over the long term, take a long view. Develop a road map for what you want to accomplish in the future, and don’t just solve for where you are today. Because you are looking long-term, let the thought settle in that you are probably going to work with the same AI partner for a considerable period (years, in fact). Transparency becomes very important. The partner's road map matters, as well, in terms of how it will be able to support your continuing objectives. The more of a black box the partner creates around its future plans, the more concerns about maturity this should raise. Although there is a lot to consider when selecting an AI partner, know that selecting the right partner will be worth it. AI’s capabilities and benefits are truly transformative when applied in a thoughtful way. Best of luck to you as you embark on your AI journey. As first published in InsideBigData.

Machine Vision Usage in Insurance

Insurers now have access to an unprecedented quantity of image and video data and are beginning to invest in machine vision to process it.

Insurers now have access to an unprecedented quantity of image and video data. Many still manually review these data sources, but this provides limited insight. Carriers are beginning to invest in machine vision technology to process this data, programmatically analyzing risk factors and making sense of these vast image stores. Machine Vision: What Is It? Machine vision is the AI-based analysis of images from sources like smartphone photos, drones, low-lying aircraft, satellites and dashcams. Machine vision platforms offer analysis—i.e., the ability to upload images from a proprietary source into a platform—or they can be trained from scratch to work with an insurer’s business. Dedicated platforms can provide a relatively lightweight way to help insurers automate, scale and enhance risk evaluation while seeing gains in operational efficiency and cost reduction. The Move to Purpose-Built Platforms General machine learning platforms may be capable of image- and video-based analysis of risk factors in the not-too-distant future. Yet, for the time being, insurers are likely to see more tangible results by implementing a machine vision platform built specifically for insurance needs in claims and underwriting. These solutions are likely to provide more value with fewer resources and less investment. Some purpose-built machine vision solutions for the insurance industry may use general-purpose platforms from other providers behind the scenes. But the insurance-focused vendors have done the work of training solutions for specific insurance use cases so that insurers don’t have to. See also: Rise of the Machines in Insurance   Machine Vision Use Cases Most current machine vision use cases focus on commercial and personal property underwriting and claims due to the proliferation of property imagery, especially for roof analysis. Usage is emerging for auto claims, where the predominant application is claims damage and estimation. Machine vision is mostly exploratory in other lines of business; one emerging example is life insurance, in which machine vision can perform image analysis to aid in underwriting. Use of images to determine claims and underwriting risk factors isn’t necessarily a new concept for insurers; underwriters have been using sources like Google satellite images for years for this precise purpose. Yet unstructured sources of photo and video data continue to proliferate, and machine vision can help insurers evaluate a broader range of risk and automate decision-making. More information on the space is available in Novarica’s latest report, Machine Vision in Insurance: Use Cases and Emerging Providers, which provides an overview of machine vision technology as well as prominent vendors.

Jeff Goldberg

Profile picture for user JeffGoldberg

Jeff Goldberg

Jeff Goldberg is head of insurance insights and advisory at Aite-Novarica Group.

His expertise includes data analytics and big data, digital strategy, policy administration, reinsurance management, insurtech and innovation, SaaS and cloud computing, data governance and software engineering best practices such as agile and continuous delivery.

Prior to Aite-Novarica, Goldberg served as a senior analyst within Celent’s insurance practice, was the vice president of internet technology for Marsh Inc., was director of beb technology for Harleysville Insurance, worked for many years as a software consultant with many leading property and casualty, life and health insurers in a variety of technology areas and worked at Microsoft, contributing to research on XML standards and defining the .Net framework. Most recently, Goldberg founded and sold a SaaS data analysis company in the health and wellness space.

Goldberg has a BSE in computer science from Princeton University and an MFA from the New School in New York.

It's Groundhog Day for WC Claims Handling

Why have attempted fixes via legislation and technology failed to fulfill promises for decades, for almost a generation of workers?

The popularity of the 1993 Bill Murray movie rendered the phrase “Groundhog Day” with a common reference to a continually occurring unpleasant situation, according to Wikipedia. Workers’ compensation claims handling seems to be stuck in a time warp with the same unpleasantries year after year no matter how many attempts have been made to address these issues through various avenues, including legislation and technology. 2019 began with the same challenges reverberating: provider fraud; medical disputes arising from applying evidence-based medicine together with a pharmacy formulary; inefficient and ineffective reactive claims management practices; through to the methods used for outgoing payments. In California, the opportunity for providing high-quality, coordinated care as well as controlling medical costs and fraud has existed since the passing of SB1005 some 26 years ago, yet there are still complaints from dragged out-medical care and poor recovery through to unacceptably high medical costs and fraud levels never witnessed before in the history of workers’ compensation. See also: The State of Workers’ Compensation   Technology has always been touted as a means to improve claims handling. Programming languages available 50 years ago, like COBOL and PL/1, enabled computer programmers to code logic to address all the needs of claims handling processes, including disbursements over any number of payment methods. Coding languages allowing predictive analytics, such as SAS, also known as Statistical Analysis System, have been available for over 40 years, and data management through a relational database using the Structured Query Language is also almost 40 years old. At the same time as these technologies became available, technology entrepreneurs planted seeds to raise awareness for the next evolution of analytics: artificial intelligence. Little (if any) of this technology, however, has been harvested in claims handling over the past four decades. Why then have the legislation and technology paths been littered with failed promises for over the past three decades or so, or indeed almost a generation of workers? The answers are simple: mindset and execution. In any business enterprise, including P&C insurance, money is the bottom line in every decision made. The objective of the P&C claims administrator is to close claims quickly with minimum payouts, which can incite adversarial claims handling. Workers’ compensation, which in 2017 accounted for 16% of P&C's written premiums in California, is governed by statute requiring employees injured at work to receive all the necessary care, including medical treatment, to enable their prompt return to safe, sustainable and gainful employment. However, to fully undertake the management of an injured worker’s recovery process as well as develop a successful reintegration strategy is not in the P&C DNA. Hence, the insurers are required to operate through profit-making middlemen, enterprises that prosper by manufacturing crisis and creating chaos. Their excessive costs for services have resulted in the rationing of medical care by restricting access to both resources and therapies. For instance, California allows P&C companies to establish their own treater networks, combined with their utilization review program, with oversight through an independent medical review process. Unfortunately, this approach has fallen into disrepute because of countless allegations of delays and restricted access to treatments, as illustrated in IMR Case# CM18-0238095. In this case, an off-work, 54-year-old woman with a shoulder pain rating of nine out of 10 waited for 69 days just to be informed her medication costing 92 cents was medically unnecessary and inappropriate as per the California Medical Treatment Utilization Schedule (MTUS). In 2017, 2.8 million employees in private industries experienced a nonfatal injury or illness, according to the U.S. Bureau of Labor Statistics, of which 882,000 (or 31%) required time off work. Over three decades, this equates to 26,5 million families (assuming the same annual figure) whose lives most likely experienced upheaval and disruption caused by the failed promises. See also: 25 Axioms Of Medical Care In The Workers Compensation System   Workers’ compensation claims handling for injured employees has been a major and inexcusable fiasco and in urgent need of a new breed of claims administrator, one who is forward-thinking, using outside-the-box approaches to effect change and break through the Groundhog Day time warp. A longer version of this article is available here.

John Bobik

Profile picture for user johnbobik

John Bobik

John Bobik has actively participated in establishing disability insurance operations during an insurance career spanning 35 years, with emphasis on workers' compensation in the U.S., Argentina, Hong Kong, Australia and New Zealand.

15 Keys to Mental Health Safety Net

Here are the questions to ask to ensure that your employee assistance program provides robust help for employees' mental health.

sixthings
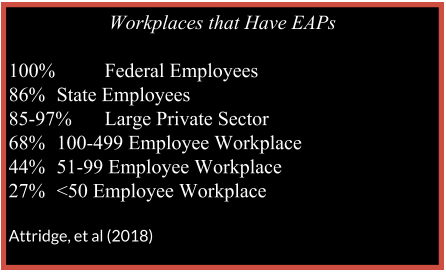
Acknowledgment: Thank you, Dr. Jodi Frey and Jon Kinning, for assisting in the preparation of this article. The employee assistance program (EAP) might be one of the best-kept secrets for many employers. Instead, EAPs should be resources widely publicized to help encourage managers, employees and often their family members so that support services for personal and workplace problems can mitigate risk and promote vibrant workers. Many employers simply “check the box” when signing up for the EAP benefit, figuring health insurance will cover the mental health needs of their employees; however, most employers really don’t know what the EAP services entail or the value the services can bring to a workplace. With that said, not all EAPs are created equal. EAP services vary greatly, including some or all of the following::
  • biospsychosocial assessments, including substance use assessments
  • individual and family counseling
  • financial and legal coaching and referrals for counseling
  • referrals for additional services, with follow-up
  • psychoeducation through workshops, newsletters and other communication for personal and workplace concerns, including stress management, parenting, mental health literacy, relationships and organizational change and individual crisis prevention, crisis response and support
  • mediation and team development
  • leadership consultation, coaching and development
  • fitness for duty evaluations
  • suicide risk assessment, treatment and “postvention” (i.e. what to do after a suicide)
  • staff training on best practices on how to support someone in distress
  • and more
Sometimes, the services are cursory, such as a brief telephone assessment and referral by a contracted outside provider. Other EAPs provide robust and high-touch services like 24-hour support; on-line assessment and information; telephone and in-person assessment and counseling; on-demand crisis consultation; on-site workshops; mental wellness promotion; and much more. As with many things, you get what you pay for, so employers need to decide how much they are willing to invest in the mental wellbeing of their workers and conduct a cost-benefit analysis. However, EAPs, even more customized programs with onsite services, have been shown to be cost-effective to employers through the years. Are EAPs Effective? While the research on the effectiveness of EAPs is limited, studies have found that employees' use of EAPs enhanced outcomes, especially in "presenteeism" (how healthy and productive employees are), life satisfaction, functioning and often absenteeism (Joseph, et al., 2017; Frey, Pompe, Sharar, Imboden, & Bloom 2018; Attridge et al., 2018; Richmond, et al., 2017). In one longitudinal, controlled study, EAP participants were more likely than non-EAP participants to see a reduction in anxiety and depression (Richmond, et al, 2016). Another matched control study found that users of EAP services often reduced their absenteeism more quickly than non-EAP users experiencing similar challenges (Nunes, 2018). In another longitudinal study (Nakao, et al, 2007), 86% of people who were suicidal when they engaged with their EAP were no longer suicidal at two years follow-up. Researchers have concluded that, while not all EAPs are created equal, they often provide accessible services that are effective at improving employee mental health and well-being. See also: Impact on Mental Health in Work Comp   Are EAPs Prepared to Support an Employer Facing an Employee Crisis With Suicide? When it comes to the life-and-death issue of suicide, EAPs have the potential to provide evidence-based suicide prevention, intervention and postvention services to employers. The EAPs’ contribution to the comprehensive workplace suicide prevention strategy is essential, and many would benefit from annual state-of-the-art training in evidence-based methods of suicide risk formulation and treatment to help distressed employees get back on their feet. Social workers, who provide the majority of EAP clinical services in the U.S., often report having no formal training in suicide formulation, response and recovery (Feldman & Freedenthal, 2006; Jacobson et al., 2004), so annual continuing education on suicide intervention and suicide grief support is often helpful to providers. Once trustworthy and credentialed providers have been identified, they should be highlighted in the “suicide crisis” protocol, so that companies are not trying to do this leg work in the midst of a crisis. If one of the main messages in suicide prevention is “seek help,” we need to make sure the providers are confident and competent with best practices approaches to alleviating suicidal despair and getting people back on track to a life worth living. Thus, dedicated employers will evaluate and even challenge their EAP providers to demonstrate continuing education in the areas of suicide prevention, intervention and postvention skills. In fact, some states are mandating that all mental health professionals, including licensed providers of EAP services, have some sort of continuing training in suicide risk formulation and recovery. Do Employees Know About the Benefit of Their EAP? In addition to making sure the providers have the needed skills, companies need to make sure that their employees know when and how to access the care. Recently, the American Heart Association and CEO Roundtable worked with experts in the behavioral health field to develop a white paper for employers, which includes seven specific actions employers can take to improve the mental health of their employees (Center for Workplace Health, American Heart Association, 2019). The report can be viewed online here. Dr. Jodi Frey, expert panelist for the report and internationally recognized expert in the EAP and broader behavioral health field recommends that “employers need carefully consider their workplace’s needs when selecting an EAP, and then should work with their EAP as a strategic partner to develop programs and communications that encourage utilization of the program and continued evaluation to improve services over time.” (Dr. Jodi Frey, personal communication, March 18, 2019). Employers that are mindful of their workers’ well-being will continually promote well-vetted and employee-backed resources throughout the career of the workers. Leadership testimonials of the efficacy of the resources after the leaders have used them for their own mental health would bring credibility to the resources and model appropriate self-care to the employees. Bringing the resources on-site to the workers (and not waiting until the workers stumble upon the resources) is another way to break through the barriers to care. The Employee Assistance Society for North American (EASNA) developed a guide to help employers evaluate EAPs and determine appropriate vendors. The guide also can be used to help employers evaluate their current EAP and decide if needs are being met or if more attention to what services should be offered needs to be addressed. The guide can be downloaded free. Are There Different Types of EAPs? Much diversity exists in EAP structure and quality (Frey, et al, 2018). Some companies use internal EAPs, where providers are also employees of the company. This arrangement often provides the benefit of having an immediate resource that has clear knowledge of the company and industry culture. Evaluation of internal EAPs has found increased utilization, customization and supervisor referrals (Frey, et al, 2018); however, there are some drawbacks. Internal EAPs, because they are so closely connected to the company, run the risk of being perceived as having blurred lines of confidentiality and objectivity. By contrast, external EAPs are often more diverse and can respond 24/7 across a vast geography. Because of these benefits and consequences, many companies have moved to a hybrid model to get the best of both models. Hybrid EAPs often have an internal employee to manage the EAP and to work with managers and employees on critical incident response, strategic planning and organizational change, and to provide onsite assessment and problem resolution. They can be an important ally for the employer to understand the potential for an EAP and to help evaluate whether EAP providers are effective in their response and offering high-quality services (Frey, 2017). See also: What if They Say ‘Yes’ to Suicide Question?   EAPs are most effective when they understand the industry and organizational culture, have business acumen and can adapt to changes in organizational structure (Frey, et al., 2017; Frey, et al., 2018). Thus, employers seeking to find a best fit for their employees will interview mental health providers about their knowledge of the unique stressors and strengths in the industry. Some industries (e.g., emergency responders and aviation) have gone so far as to credential mental health providers as being specialists in their industry to avoid a mismatch. Case Study From the COO of a Construction Contractor "We had an issue where our EAP was referring counselors outside of our healthcare providers, so, after the three free sessions, the participant learned they could only continue with the suggested provider at $150 a session; so the employees would drop out. My understanding is that counseling often takes around seven sessions to have a sustained impact, so, I put in a mandate with our HR team to renegotiate our EAP to ONLY refer in-network counselors, or they would pay for the continued care. "We then incorporated our EAP into our safety program. When there is a serious accident, we deploy counselors and have our EAP involved for post-accident assistance to our employees. Accidents can bring up traumatic responses from our employees, and these experiences bring up memories from other accidents they may have been involved in or around. This cumulation of trauma can be highly distressing for them. "In the early years, we had to work through the skepticism that the EAP would notify management of anyone that used the service. Since HIPAA came into play, we have less of this skepticism. The employees thought they would get fired or laid off first if they had issues. "I’ve worked with our safety and wellness groups to actually pick up and call the EAP for someone in distress and get them on the phone. Once they lay the groundwork with the counselor, they hand the phone over and leave and let the employee get the help they need. This helps break down the stigma, and some people just don’t have the courage or have a mental block about picking up the phone for help. This has been VERY effective to get those in need the help they need. "We promote our EAP in our weekly newsletter, and we also have business cards with the information, and we utilize hard-hat stickers that have all the information. This helps it be available when they need it. "I’ve also encouraged our managers to use the system so they can promote it from their point of view. This also has helped remove the stigma around using the EAP. I also talk when in front of our employees about the program and educate them so they will use it. Our utilization rate is the highest in our EAP network, and I think this is the reason why." 15 Questions Workplaces Should Ask to Strengthen the Mental Health Safety Net Employers should remember they are the customers of their EAP, and they should do the due diligence to make sure they are getting the best benefit possible. Here are 15 questions employers should ask their EAP to get the best services possible:
  1. What services does your EAP cover? Are these services available 24/7?
  2. Who answers the calls of the EAP, and how are they trained and supervised? What professional and educational preparation and certifications do they have? Are they licensed?
  3. How are counselors selected and trained? Are certain licenses and other credentials required to be a part of the EAP provider network?
  4. What types of training have EAP providers received? Specifically, when was the last time they received training in suicide risk formulation and treatment?
  5. How is your EAP reporting utilization? How does your workplace’s utilization rate compare with others in your industry and what can be done by the EAP and by you as the employer to encourage more utilization?
  6. Do your employees know about your EAP services and how to access them?
  7. For those who have used the EAP, how satisfied were they with the services? Did the services help with the problem for which they were seeking support?
  8. When employees completed EAP services, did the EAP follow up (or attempt to follow up) with the employee to make sure all needs were met?
  9. How does your EAP interact with health plans? Are EAP providers also providers of outpatient mental health, and, if not, are they well-versed in the benefits of employees to make effective and seamless referrals?
  10. How is your EAP measuring outcomes? Can they also provide you with a return-on-investment (ROI) or other cost-benefit analysis?
  11. How is the EAP promoting upstream mental health efforts like prevention, resilience, positive psychology and work-life integration?
  12. Are there general mental health screening or other wellness tools the EAP can offer the workers to help them understand and monitor their mental wellness? Does the organization also assess its own culture of system-level mental wellness?
  13. Does the EAP have experience serving clients in our industry? If yes, what are some recommendations to improve how EAP services are promoted and offered at our workplace?
  14. Is the employer receiving regular reports (i.e., bi-annual, annual) from the EAP on utilization, presenting problems, satisfaction and other workplace outcomes?
  15. Does the EAP provide manager or HR training on how best to support an employee experiencing a mental health or suicide crisis? Are there additional staff training on skills needed to identify and assist employees in distress?


Sally Spencer-Thomas

Profile picture for user SallySpencerThomas

Sally Spencer-Thomas

Sally Spencer-Thomas is a clinical psychologist, inspirational international speaker and impact entrepreneur. Dr. Spencer-Thomas was moved to work in suicide prevention after her younger brother, a Denver entrepreneur, died of suicide after a battle with bipolar condition.