Download

What's Next for Social Inflation? (Part 5)

At what point does social inflation severely constrict the availability of certain lines of coverage and thereby give rise to legal remedies, such as tort reform?

Sky visible through a circular hole

As society continues its halting emergence from the COVID‑19 pandemic, court activity has resumed. With that activity has come a return to the eyebrow-raising verdicts seen pre‑pandemic:
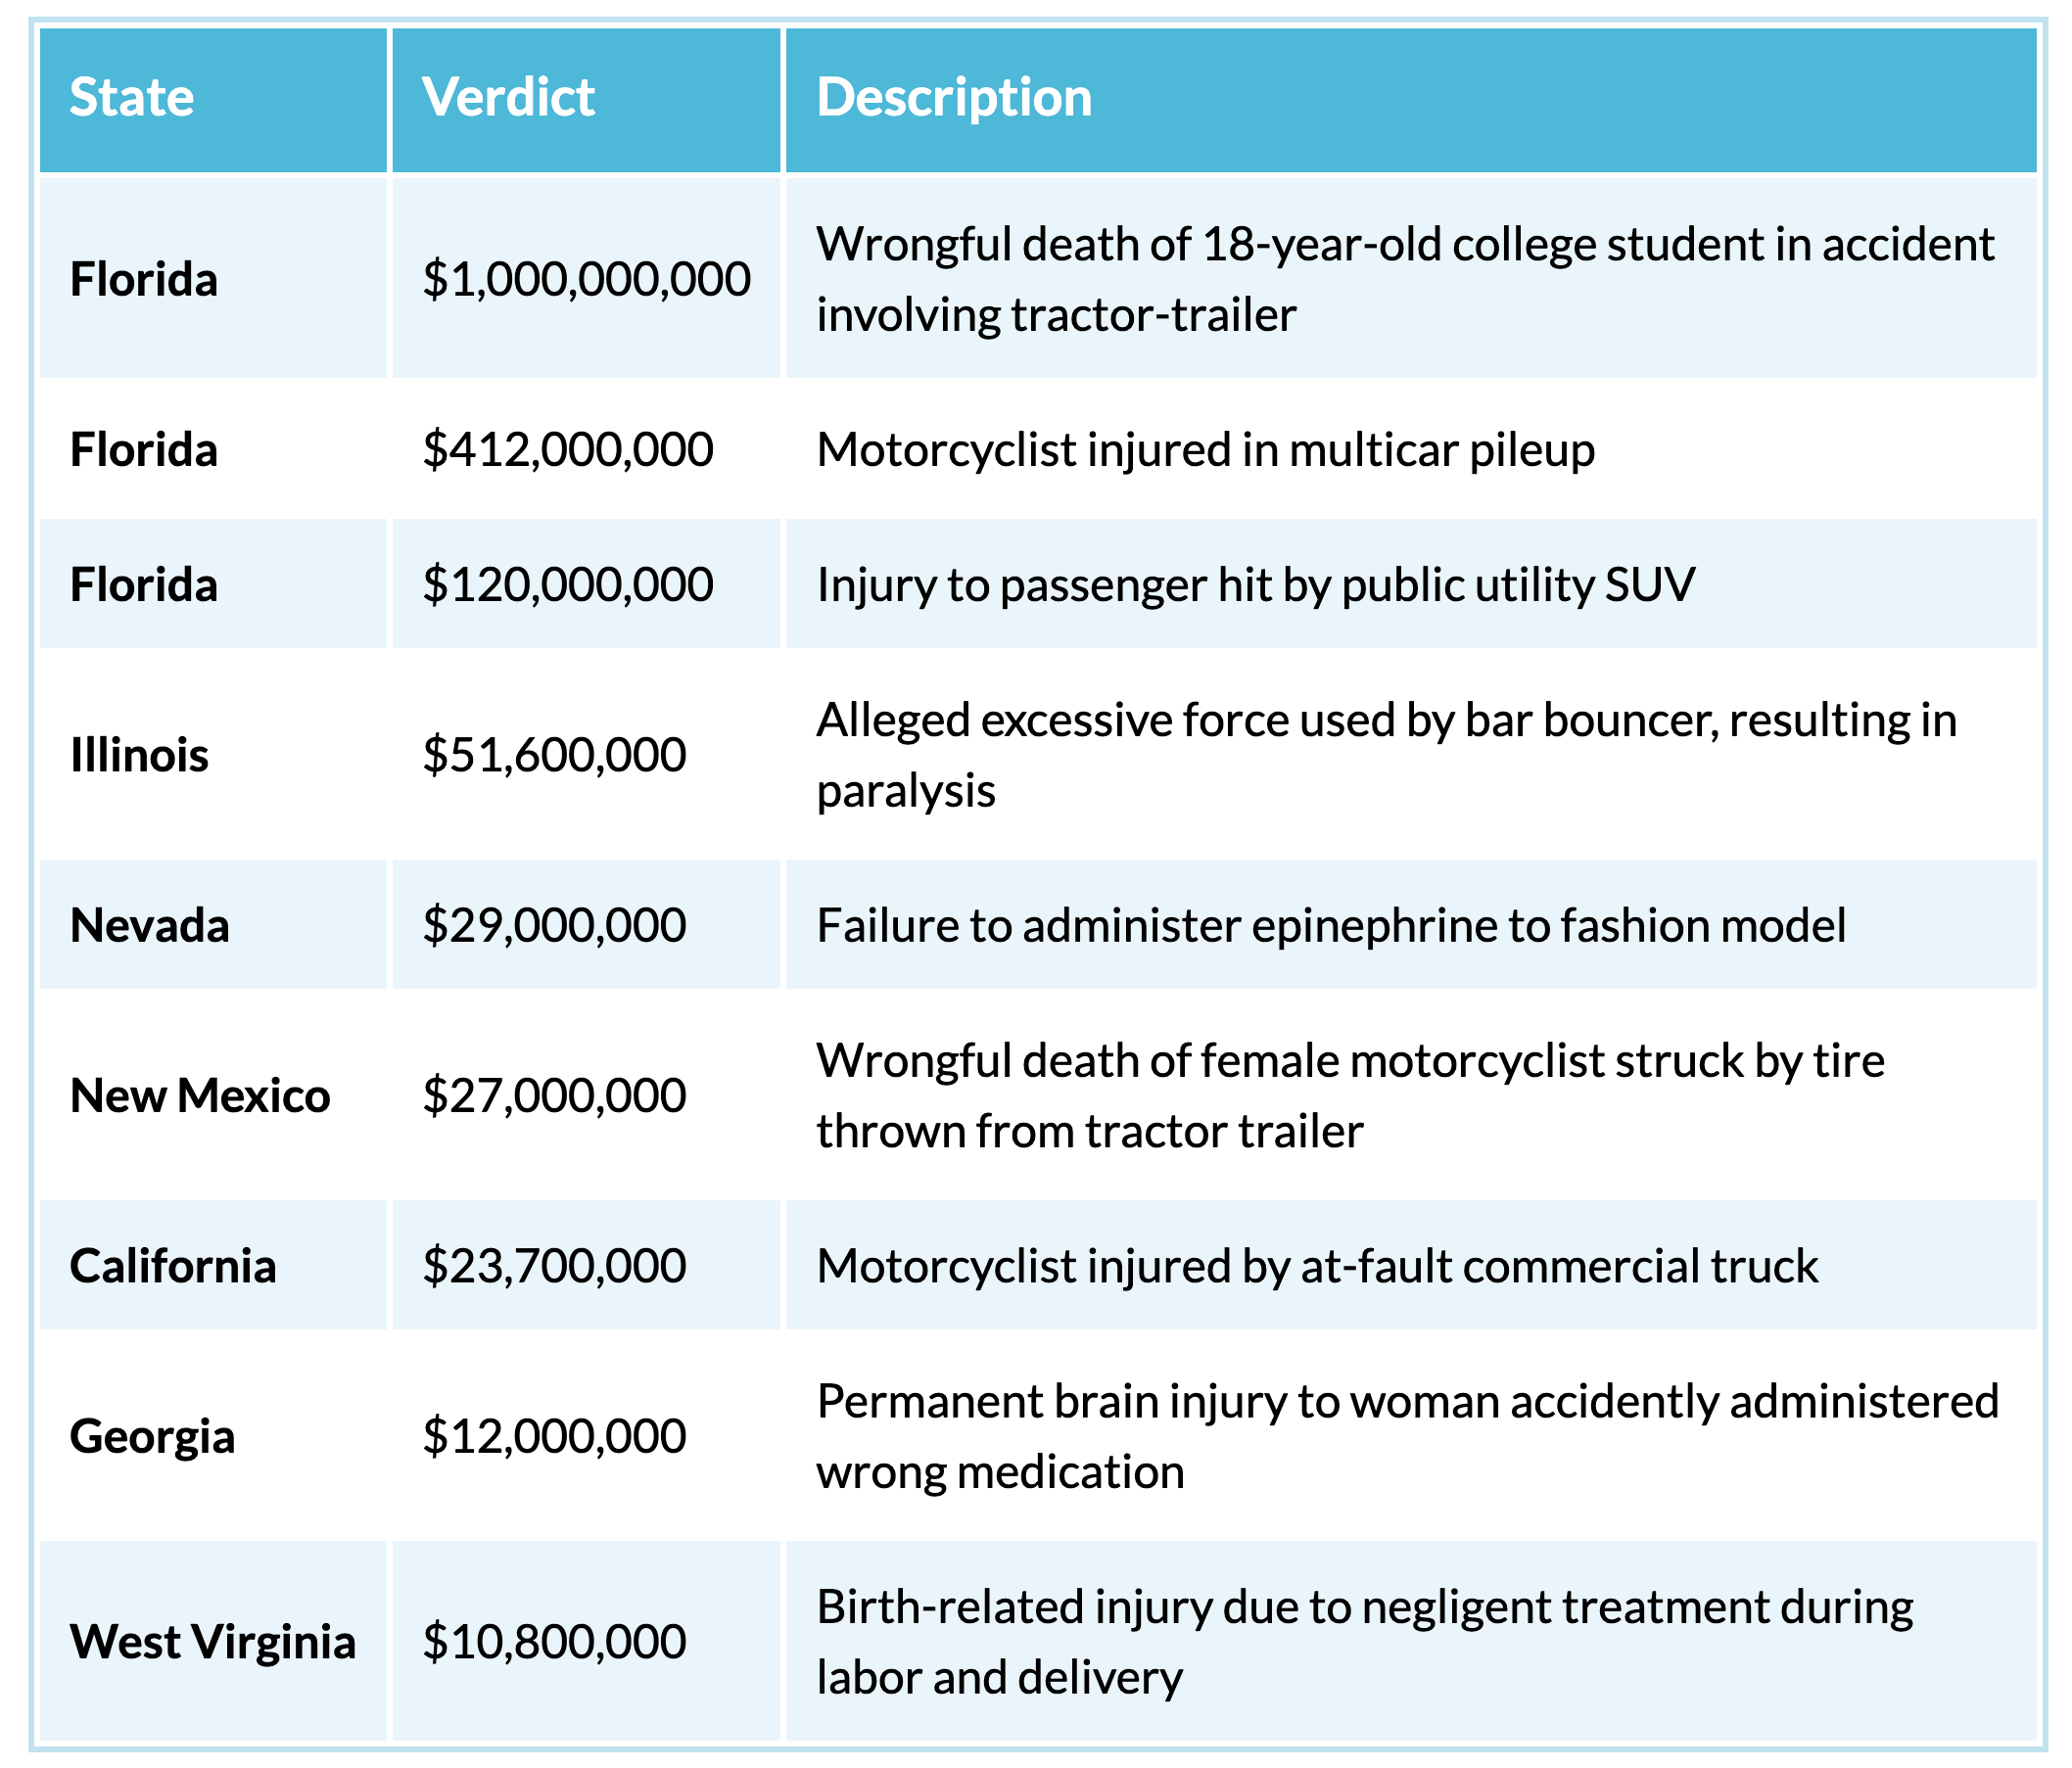
Table showing recent verdicts

Source: Law 360

Fueling those verdicts are the trends discussed previously in this blog series – changing juror demographics and attitudes, a plaintiffs bar eager to feed juror concerns over personal safety and perceived disenfranchisement, as well as litigation funders seeking to maximize returns in the current low-interest environment.

With preliminary signs indicating that social inflation will continue its seemingly inexorable rise, an obvious question comes to mind: At what point does social inflation severely constrict the availability of certain lines of coverage and thereby give rise to legal remedies, such as tort reform? Are we approaching a precipice?

Past as Prologue

A look backward reveals a time when social inflation ran rampant and caused much consternation among policyholders and carriers alike:
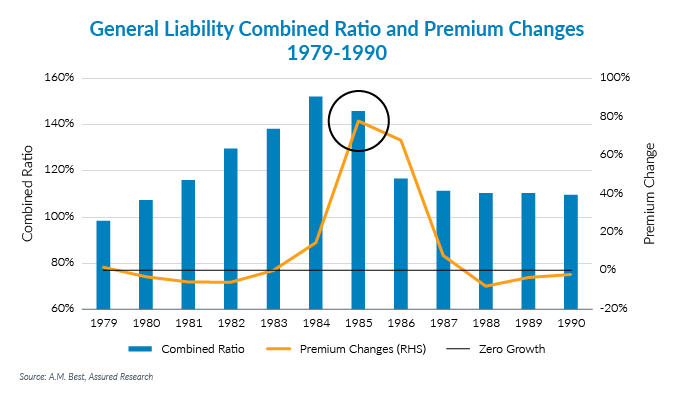
Graph showing general liability combined ratio and Premium Charges

During this period, the liability combined ratio peaked at 151% in 1984. Liability premiums skyrocketed as well, increasing 78% in 1985 and 68% in 1986. Not surprisingly, coverage for certain lines vanished, with specialty lines – such as Medical Malpractice – being particularly hard-hit. Seeking to quell this maelstrom, state legislatures ushered in an unprecedented era of tort reform that resulted in 39 states passing 82 different tort reform measures between 1985 and 1990. The era also spawned creation of well-known advocacy groups, such as the American Tort Reform Association.

By placing caps on noneconomic damages, reducing statutes of limitation and implementing other procedural changes, tort reform stabilized and ultimately reduced liability premiums. However, its full effect proved to be only temporary, as evidenced by a number of successful legal challenges on equal protection and other grounds. Many of the late-20th century tort reform measures remain intact but continue to be under attack.

See also: The Future Isn’t What It Used to Be

Back to the Future?

While social inflation shows signs of someday igniting into a full-blown conflagration, the indications are mixed as to whether that will occur sooner or later. While there are many metrics to consider, industry combined ratios for 2020 remain below 100; moreover, the top eight writers of Personal Auto saw their combined ratio drop to 88 in 2020 from 93 in 2019.

While pandemic-driven lockdowns and working from home likely caused the decline in 2020, the fact remains that combined ratios will need to climb stratospherically before a reprise of the crisis last seen in the 1980s occurs, although even incremental growth has ramifications.

Nevertheless, the social inflation fires could be either fanned or extinguished, at least partially, by a number of cultural factors:

  • Individual Perceptions of Risk Tolerance – During this COVID‑19 pandemic, each of us is making personal decisions as to how much – or how little – risk we are willing to tolerate. Do we return to the office? How comfortable are we eating in restaurants? To what degree is out-of-state travel – and by what means – acceptable?

    How an individual answers these questions will provide insight as to attitudes toward personal responsibility, risk tolerance and expectations of a corporation or business defending itself in a tort liability lawsuit.

  • Intergenerational Wealth Disparity/Economic Inequality – Much has been written about increased wealth concentration, the decline of the traditional middle class and the growing number of dislocated workers subsisting on gig or part-time jobs. Similarly, multiple data points suggest that Baby Boomers hold a disproportionately large percentage of the country’s wealth.

    Will these economic trends continue to fuel the distrust and resentment that is thought to partially explain the spate of “nuclear” verdicts and out-sized settlements? Or will the promise of an estimated $3 trillion wealth transfer from the Baby Boom generation and hoped-for economic improvement post-COVID bear out and level the economic disparity, and could it restore the societal faith in institutions that once existed?

  • Impact of Social Media – Twitter, Facebook and LinkedIn are only a few of the tech companies that have enabled people to connect in ways unimaginable a generation ago. However, to varying degrees these platforms have also become fruitful ground for the spread of misinformation – and in some instances outright disinformation campaigns. One commentator suggests conditions are ripe for groups to display what social scientists refer to as “in‑grouping;” that is, a belief that social identity is a source of strength and superiority and that other groups are to be blamed for their problems.

    Could this spread of misinformation be influencing juror attitudes and perceptions of certain groups? Do we now have a growing number of Americans living in an alternate reality that does not comport with credible and factual information? Or is the effect too slight to be much of a factor at all?

  • Insurance Industry Response – As with other industries, insurance will continue to experience significant transition. Over time, the industry’s 2.8 million employees have moved from being managed by Baby Boomers and Gen Xers to Millennials. Filling entry-level underwriting positions are recent Generation Z graduates, with many coming from the growing number of strong risk management and insurance programs that have arisen in the last two decades.

    At one level, this transition will entail loss of decades of practical experience. At another, it will represent the career dawn of a workforce more educated and more culturally diverse than its predecessors. Presumably, with their greater educational and cultural diversity will come creative and “out of the box” solutions to vexing industry problems, such as social inflation. As mentioned elsewhere in this series, “big data,” artificial intelligence and predictive modeling hold the key.

Conclusion

Over the past several years social inflation has caused much discussion – and the initiation of exhaustive searches for its causes and potential solutions. This 5‑part blog series has endeavored to contribute to that effort, with perspectives offered from a variety of disciplines. While the journey will continue for many more months and possibly years, with the ultimate solution far from known, the insurance industry has shown itself capable of meeting great challenges, such as the one social inflation represents.

How quickly and effectively the industry meets that challenge rests on the shoulders of the dedicated professionals who have made insurance their chosen career.

Tim Fletcher

Profile picture for user TimFletcher

Tim Fletcher

Tim Fletcher, J.D., CPCU, is Gen Re’s senior emerging issues specialist and a vice president.

He heads the company’s Emerging Issues unit, drawing from years of experience and a wide range of responsibilities to identify emerging risks and exposures to Gen Re clients and internal colleagues.

Fletcher is a past president of the Atlanta CPCU chapter and currently serves on CPCU’s RE&S (Reinsurance, Excess & Surplus) interest group. He is also a guest lecturer on risk management and insurance at Georgia State University.


Andrew Pauley

Profile picture for user AndrewPauley

Andrew Pauley

Andrew Pauley, JD, CPCU is government affairs counsel for NAMIC and serves in a cross-functional role supporting state, federal and international issues.

Pauley further acts in a lead role with NAMIC public policy development groups including the Workers’ Compensation Council, the Amicus Advisory Group and the International and Market Regulation working groups.

Social Inflation: A Claims Perspective (Part 4)

How do businesses/defendants and carriers combat the effects of social inflation? It is definitely not a simple challenge, but here are three key considerations.

Woman in suit shaking hands with a client

Social inflation is seemingly being discussed everywhere, from news articles to conferences to quarterly earnings calls. And those working in claims are likely dealing with it in some capacity on a daily basis. But what can be done to combat it?

In simple terms, social inflation is the increase in defendants’/insurers’ claim costs over and above general economic inflation. It is not a new phenomenon. Social inflation occurred in the 1980s, manifesting in the swarm of asbestos and environmental claims/liabilities, and again in the late 1990s/early 2000s in connection with medical malpractice developments. Moreover, social inflation is not unique to the U.S.; it affects economies across the globe.

Causes

Class action filings have increased, nuclear verdicts are on the rise and large settlements are becoming more commonplace. Numerous factors are driving these trends:

  • Plaintiffs’ Attorneys – To give credit where credit is due, plaintiffs’ counsel has become increasingly aggressive, coordinated and savvy. Their advertising investment is up considerably, they have embraced technology and social media and they are using the reptile theory quite effectively.
  • Legislative Reform – Numerous states have recently enacted laws to not only extend statutes of limitations but actually “revive” previously time-barred claims, such as sexual molestation claims.
  • Third-Party Litigation Financing – Increased third-party litigation funding has provided significant capital to plaintiffs’ firms. For more detail, please refer to the previously published Part Two in this series: Social Inflation Is Complicated and Costly – Legal and Regulatory Changes.
  • Jury Makeup – Mistrust in large corporations remains, and jurors – particularly millennials – are more than ever aware of social injustices and income inequalities.

Combatting Social Inflation

How do businesses/defendants and carriers combat the effects of social inflation? It is definitely not a simple challenge, but some considerations include:

  • Case Evaluation/Communication – Early, candid analysis is critical. Generally speaking, claims/cases do not improve over time. Attorneys get involved, demands escalate, bad faith and time limit demand strategies are employed, etc. Internally, it is important to cultivate a “no surprises” culture. Claims professionals are the constant bearers of bad news and must be comfortable both receiving and delivering it, the earlier the better. Identify the challenging cases early and develop a strategy to attack.
  • “Embrace the Suck” – This is an old military expression that counsels one to lean into the suffering and get comfortable being uncomfortable. The claims world is a challenging one. Days are filled with layers of gray, difficult choices, challenging outcomes and associated risk. Outcomes won’t be perfect. Juries are unpredictable, and some losses will be suffered along the way. But it’s important to embrace the process, ensure certain cases are resolved early and identify the right ones in which to invest and bring to trial.
  • Talent – The insurance industry as a whole is faced with talent challenges. Unfortunately, insurance does not top the list of most desirable industries for college graduates – they just don’t know what they are missing! Recruiting, training, developing, and retaining top, diverse talent must remain a priority for our industry. Outside counsel is another critical component. It is not only imperative that potentially challenging cases are identified early, but appropriate counsel must be retained; we have to get the right cases to the right attorneys.

See Also: How Social Inflation Affects Liability Costs

Technology to the Rescue?

While still fairly limited in number countrywide, many “nuclear verdicts” – generally defined as those of $10 million and above – share a theme: They too often come as a complete surprise to the policyholder, defense attorney and the insurance carrier. Furthermore, any unexpected trial result carries the potential for a claim department to harvest learnings, find commonalities that may appear again and then apply those learnings to future cases that may contain similar attributes. In the past, an astute claims department may have held a “post- mortem” on such a case, possibly captured a key point or two and then passed that information on to the larger organization. However, such practices have historically brought mixed and inconsistent results.

It has been noted that no industry takes in more data than does insurance, but then does so little with it. Contained within each claim file is a trove of structured and unstructured data. Could analytics and predictive modeling take those data elements and then forecast a range of outcomes that could enable claim professionals to better quantify the “downside” of a catastrophic injury case, or – perhaps even more beguilingly – identify the “outlier” case with unforeseen potential to generate a nuclear award? Developers are working on such data-driven approaches, with great strides expected to be made in the coming years.

Other tools are on the horizon that may further stem the rising tide of social inflation. One such area involves employing analytics to better manage legal expense that, according to one author, consumes between three and eight percent of direct written premium. The ability to better quantify law firm expertise and efficiency would bring a litany of benefits, ranging from being better able to “match” the defense attorney expertise to that of an adversary, to assessing which firms complete discovery most efficiently. Related is the possibility to better tie firm compensation to claim outcomes in a way that would move away from the traditional hourly billing model. Development in this area continues as well, with a handful of products coming to market in recent years and greater refinement expected over time.

The Future

Social Inflation has hit the defense/insurance industry like a large wave in recent years. By refining claim handling practices, recruiting top-flight talent and jumping onto the potential benefits that artificial intelligence and predictive modeling potentially represent, claim departments can address the social inflation tide.


Glenn Frankel

Profile picture for user GlennFrankel

Glenn Frankel

Glenn Frankel is senior VP, head of North America Property/Casualty Claims at Gen Re.

He joined in May 2020. He was last at CNA, where he led Complex Commercial Claims, including Environmental & Mass Tort, Construction Defect, Life Sciences and Opioid exposures. Prior to that, he was in leadership roles at The Hartford’s insurance and reinsurance units. Frankel started his career with the law firm of Day Pitney and as Managing Counsel at Travelers.


Tim Fletcher

Profile picture for user TimFletcher

Tim Fletcher

Tim Fletcher, J.D., CPCU, is Gen Re’s senior emerging issues specialist and a vice president.

He heads the company’s Emerging Issues unit, drawing from years of experience and a wide range of responsibilities to identify emerging risks and exposures to Gen Re clients and internal colleagues.

Fletcher is a past president of the Atlanta CPCU chapter and currently serves on CPCU’s RE&S (Reinsurance, Excess & Surplus) interest group. He is also a guest lecturer on risk management and insurance at Georgia State University.


Andrew Pauley

Profile picture for user AndrewPauley

Andrew Pauley

Andrew Pauley, JD, CPCU is government affairs counsel for NAMIC and serves in a cross-functional role supporting state, federal and international issues.

Pauley further acts in a lead role with NAMIC public policy development groups including the Workers’ Compensation Council, the Amicus Advisory Group and the International and Market Regulation working groups.

Social Inflation: Complicated and Costly (Part 3]

While many factors contribute to social inflation, analysis suggests that an increase in non-fatal auto accidents may be one of the most influential.

Person signing name at the bottom of a contract

As social inflation has been more widely examined in recent years, it has grown to encompass almost any unfavorable aspect of modern Casualty insurance. However, while many Casualty lines are under strain, some are performing well despite purportedly being susceptible to many of the same forces. Segmenting Casualty lines into those performing well and those under strain, and considering what the well-performing lines have in common that is not shared by the lines under strain, can help define which aspects of social inflation are most important. This information is crucial to formulating an effective response against these damaging influences.

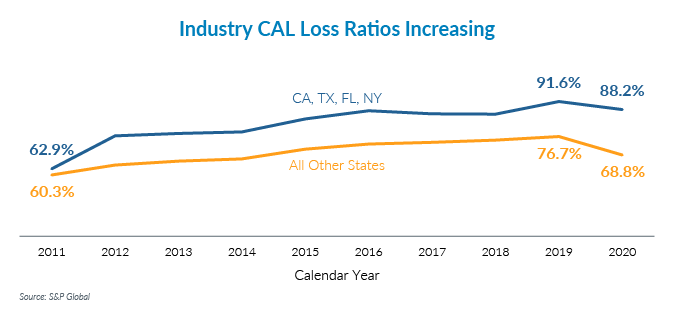
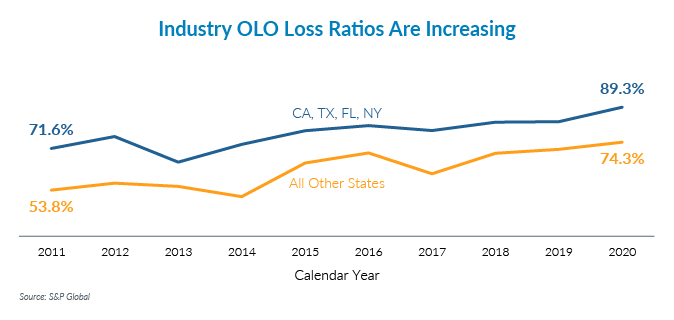
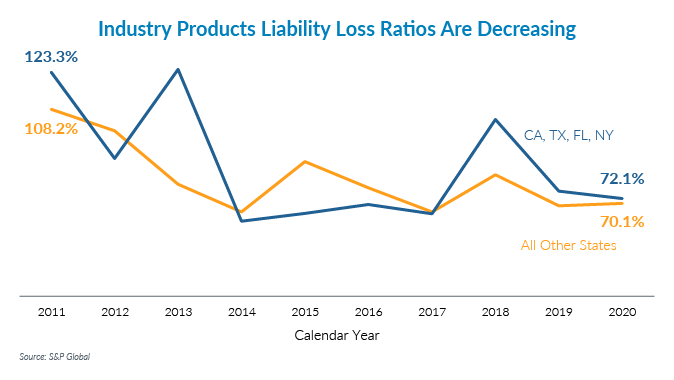
Consider that industry-wide loss ratios have grown steadily over the past 10 years in Commercial Auto Liability (CAL) and Other Liability Occurrence (OLO, which includes Umbrella), but have shrunk in Products Liability (PL). The change in calendar year loss ratios reflects the late development from prior accident years, which highlights unexpected changes in market conditions – such as social inflation. Even though some PL business is written on a claims-made basis, the downward trajectory of calendar year loss ratios is still indicative of improving market conditions for the line. The four largest states – California, Florida, New York and Texas – represent roughly 40% market share in each of these lines and have loss ratios higher than the rest of the states, but loss ratios are moving in the same direction for all states. What is happening in CAL and OLO that is not happening in PL?

Graph showing CAL loss

Graph showing OLO loss

Graph showing products liability loss

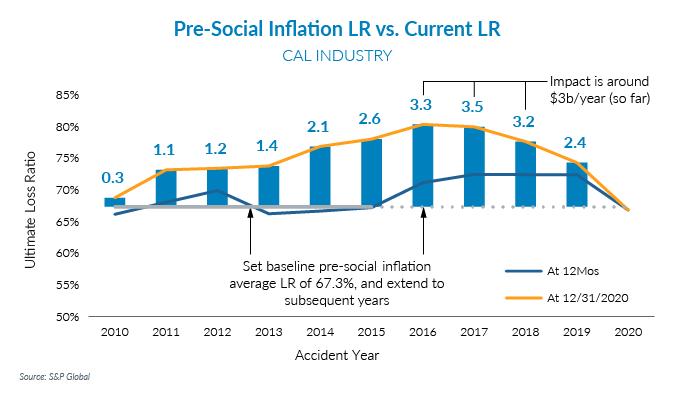
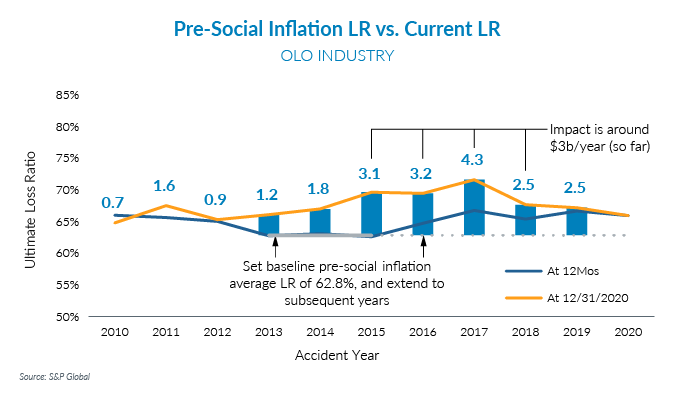
To answer that question, it is helpful to put some context around these increasing loss ratios by estimating the dollar impact. If what the loss ratio would have been in recent years without social inflation was known, it could be compared against the actual loss ratio and that difference multiplied by the premium to measure the magnitude. This is impossible, of course, but an approximation based on historical data can be made. One rough estimate of this “pre-social-inflation” loss ratio is the average ultimate loss ratio at 12‑months maturity for the years leading up to the onset of social inflation – widely accepted as around 2016. For CAL, this baseline is 67%, and for OLO this is 63%.

If these loss ratios had continued, instead of the actual loss ratios at the latest valuation, then industry-wide losses would have been more than $3 billion per year lower for CAL and roughly the same amount lower for OLO, or more than $6 billion per year total. It’s impossible to know for certain how these years would have played out under different circumstances, but this gives a rough estimate of the magnitude.

Graph comparing LR

Graph comparing LR

Graph comparing LR

See also: Insurers' Social Inflation Problem

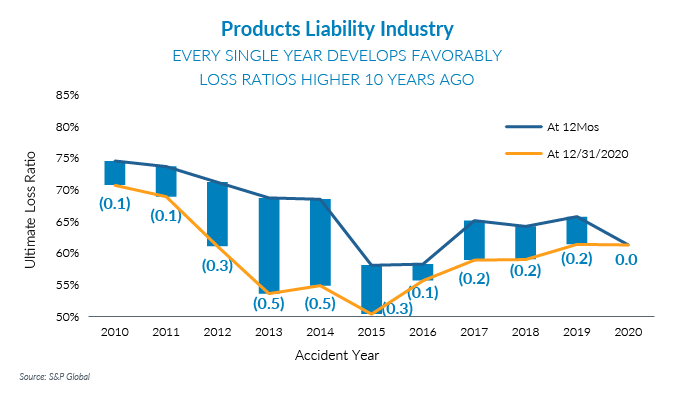
Meanwhile, for PL, every single recent accident year has developed favorably by around $200 million per year, and loss ratios were higher 10 years ago than they are today. Note that the upward trajectory of recent loss ratios is somewhat illusory because it can safely be assumed that recent years will also experience future favorable development similar to prior years. Granted, the fact that some PL business is written on a claims-made basis helps shorten the reporting pattern, but this favorable development is in stark contrast to the deterioration seen in CAL and OLO. This is counterintuitive, as PL would seem to be susceptible to many of the same causes of social inflation that are driving up the CAL and OLO loss ratios, including:

  • Nuclear verdicts, because many of the largest verdicts in recent years come from products cases such as weed killer, talc powder, tobacco, car manufacturers and pharmaceuticals.
  • Reptile Theory tactics, where a plaintiff’s lawyer appeals to jurors’ emotions by portraying the defendant as a threat to society that demands harsh punishment
  • Increased anti-corporate sentiment among jurors

Furthermore, because PL is a much smaller line than the other two, it would not take as much claim activity to have a noticeable impact on results. Various measures of industry-wide rate change suggest that PL rates have not increased as much as other Casualty lines, implying that loss activity, rather than premium adequacy, is to blame. There are many other differences among these three Casualty lines, but one would still expect that they all would suffer if the above judicial phenomena were the leading drivers of social inflation. While the importance of the issues listed above cannot be discounted, other factors appear to be having an even greater impact.

One notable distinction among these lines is the types of injuries sustained. The claims for CAL and OLO – of which Umbrella is a major component – contain a high concentration of auto accidents, where high-speed blunt force trauma injuries result from vehicle operation. PL claims contain a much broader range of injury types, from a wider array of potential hazards, and the PL line is more diversified. For example, if exercise equipment gets 5% more dangerous next year, that only affects a small subset of PL risks, whereas if vehicles get 5% more dangerous next year, that affects all of CAL and much of OLO.

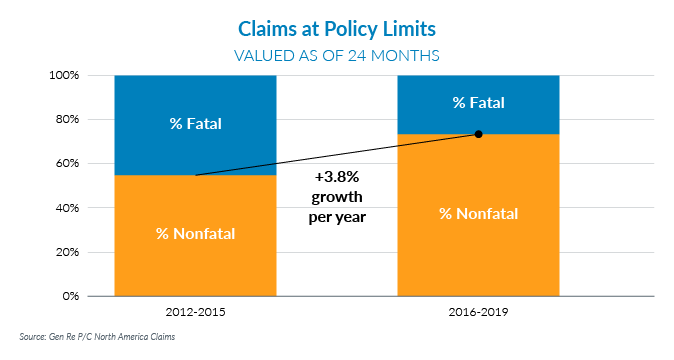
Looking at Gen Re’s Personal Umbrella claim experience provides further insight. Personal Umbrella was selected because it contains fairly homogenous exposures and claim types, is a Casualty line that appears to be affected by social inflation and is an excess cover that captures changes in large claim severity. A key finding was that among claims that hit the Personal Umbrella policy limit, a growing proportion of those claims are coming from non-fatal injuries. This would be expected if improved vehicle safety was preventing fatalities and instead an otherwise-fatal crash resulted only in injury, but National Highway Traffic Safety Administration data suggests this accounts for only a small part of the growth. Instead, a dramatic shift in the make‑up of large claims is occurring. Insurance claims executives have observed a marked increase in non-fatal traumatic brain injuries, and more work is being done to quantify this. It appears that this increase, which would have a substantial impact on CAL and OLO but a relatively minor impact on PL, may be driving much of the social inflation seen across Casualty lines.

Claims at policy limits

Social inflation has had a profound impact on Casualty insurers in recent years and is expected to increase for the foreseeable future. There is still much to learn about social inflation, its causes, and its impacts. Understanding what is driving social inflation is crucial to developing an effective response; for example, is it more important to focus on improved safety to reduce injuries, or on tort reform to reduce bias in the judicial system?

While many connected factors contribute to social inflation, this analysis suggests that an increase in non-fatal auto accidents may be one of the most influential. Unless specific appropriate actions are taken to address the recognized causes of social inflation, Casualty insurance results will continue to suffer.


Tom Karol

Profile picture for user TomKarol

Tom Karol

Tom Karol serves as general counsel - federal in NAMIC’s Washington office.

Karol represents NAMIC in Washington on issues affecting property/casualty insurance companies and has primary management of NAMIC’s response to Dodd-Frank legislation and regulation. He is also the leader of NAMIC’s investment services practice. Karol has extensive legal, regulatory and operations experience with major financial services companies, law firms, regulatory agencies and Congress. He was a leader in Deloitte’s global financial services practice, a supervisory principal for a broker dealer, with the S.E.C. Division of Enforcement and with the U.S. Senate Committee on Governmental Affairs.

Karol graduated from the University of Notre Dame Law School and has a political science degree from St. John Fisher College.

Social Inflation: Complicated and Costly (Part 2)

There is no simple cure to the ills of social inflation, but a sustained and consistent effort by insurers can start to address some of the symptoms.

Two people in suits shaking hands

In the U.S., the property and casualty insurance marketplace, along with the rest of the insurance industry, faces a wide range of issues arising out of the COVID‑19 global pandemic. Meanwhile, social inflation continues to present significant long-term challenges to those insurers.

The causes of social inflation are numerous and the source of much debate among insurance professionals, industry advocates, consumer advocacy groups and legal professionals. From a legal and regulatory perspective, the simplest description of social inflation is legislative and litigation changes that shape and ultimately affect insurers’ legal liabilities and claims costs. These transformations have accelerated over the past five years and appear poised to continue for the foreseeable future. There is no greater contributor to social inflation than legal and regulatory changes. This installment of the Gen Re/NAMIC social inflation series focuses on those changes and offers potential responses for insurers and their reinsurers to consider.

Third-Party Litigation Funding

A rise in third-party litigation funding is often identified as a leading cause of social inflation. There are various litigation funding business models, but in all of them a funding firm provides working capital to contingency-fee plaintiff firms.

Three factors have fueled an increase in such litigation:

  • The proliferation of funding firms combined with the appetite of the plaintiffs’ bar for capital to support case filings
  • The hiring of testifying experts
  • The use of sophisticated technology to aid trial presentations

In addition, these three factors have given plaintiffs and their lawyers the capacity to hold out for larger recoveries while increasing case investment returns.

To date, there has been no meaningful legal or regulatory check on the growth of litigation funding or its use in litigation. While a number of state legislative measures – which could have meaningfully addressed this concern – emerged in 2020, attempts to require disclosures of litigation funding arrangements have had difficulty gaining traction. Even more concerning is the recent development in Arizona and Utah allowing non‑lawyer investment in law firms. If these trends continue unchecked, the plaintiffs’ bar will continue to have ever-increasing access to capital to pursue litigation against corporate targets, including the insurance industry.

Statutes of Limitation

Another disturbing trend concerns legal and legislative attempts to circumvent statutes of limitation, which have long been an accepted and critical feature of the U.S. legal system. Legally established limitation periods to pursue a claim provide certainty with regard to the time period in which claims can be brought. The reasons for statutes of limitations are familiar: Not only do they provide certainty, but they avoid serious questions about the reliability of claims asserted or evidence offered many years after an event allegedly occurred. Nevertheless, a broad assault on limitation periods has occurred in recent years as many states have taken action to “revive” the period in which claims can be brought, by either extending statutes of limitation or passing legislation allowing claimants to “revive” claims that were previously time‑barred.

While indisputably well-intentioned, attempts to address the personal tragedy experienced by some individuals may prove, from a purely economic standpoint, to be a short-sighted reaction to arguably isolated incidents. Not only do such measures present constitutional questions and lead to many claims of dubious merit, but they also undermine a core principle of the American legal system and raise broader concerns that American businesses – including by extension insurers and reinsurers – will be faced with concerns of perpetual liability exposure.

Public Nuisance Theory of Liability

In addition to the many challenges already facing the property and casualty insurance industry in the U.S., it faces the growing acceptance of a public nuisance theory of liability in litigation relating to opioids, talc, climate change and, more recently, claims of alleged COVID‑19 infection in the workplace. The essence of these claims is that a product manufacturer, distributor or employer has engaged in legally permissible activity but has ultimately created or contributed to a public health crisis by engaging in that activity, and therefore needs to be found liable to “fund” the alleged societal cost. Plaintiffs argue that traditional requirements of causation should be disregarded because of the grave social issues involved.

Not only does this approach eviscerate longstanding legal principles, and, in many instances, bargained‑for contract provisions, but it effectively asks courts and juries to supplant legislators and regulators. Long-established causes of action already exist and allow plaintiffs to seek redress for alleged injuries or for a party’s violation of a duty or failure to adhere to a law or regulation. However, bypassing these established legal standards to create an avenue for recovery where none previously existed will harm not only businesses but the insurers and their reinsurers who provide needed support.

See Also: Keys to Limiting Litigation Liability

Liability Presumptions

In a related development, there is a growing trend of states enacting liability presumptions, particularly – though by no means exclusively – with respect to liability for alleged COVID‑19-related losses or illnesses. Pressure is growing in a number of states to enact more of these presumptions or to extend those already in place. Some of these measures have been effectively challenged in the courts, while others have been headed off by effective advocacy concerning the long-term ills of such presumptions, particularly where they look to rewrite bargained‑for written contracts. The insurance industry needs to continue to provide awareness regarding the risks of these measures and support advocacy efforts to prevent additional legislation that features presumption of liability.

Liability Waivers

Equally concerning is the declining enforcement of liability waivers. Where no reckless or intentional conduct has taken place, liability waivers – clearly written, identifying known risks and agreed upon by knowledgeable parties – should be enforced.

Consensus is lacking among insurance industry commentators as to whether the roll-back of tort reform measures in certain states, such as Missouri, have contributed to the rise in social inflation in recent years. Regardless of the degree of the impact, tort reform in the 1980s and 1990s – such as the establishment of caps on non‑economic damages – helped to curb the last major bout of social inflation in the U.S. Limits on non‑economic damages have proven to be the key to stemming “nuclear” verdicts that drive social inflation.

In the U.S., the property and casualty insurance industry can make significant strides toward reversing the serious threat of ballooning social inflation by instituting four strategies:

  • Advocating for legislation aimed at the regulation of third-party funders that fuel growth in litigation
  • Adhering to accepted legal principles
  • Promoting awareness of the long-term harm of liability presumptions
  • Encouraging renewed focus on tort reform measures

There is no simple cure to the ills of social inflation, but a sustained and consistent effort by insurers, and the advocacy groups they support, can start to address some of the symptoms.


Andrew Gifford

Profile picture for user AndrewGifford

Andrew Gifford

Andrew Gifford is senior vice president, general counsel and secretary for General Re. 

Gifford oversees the global legal, compliance and regulatory functions for the Gen Re group's insurance, reinsurance and financial services businesses. Prior to joining Gen Re, he was a partner with a global law firm, where he represented clients in a variety of international businesses, including insurance and reinsurance, auditing and consulting services, banking, mortgage lending and real estate.

He is a graduate of the University of Michigan Law School.


Andrew Pauley

Profile picture for user AndrewPauley

Andrew Pauley

Andrew Pauley, JD, CPCU is government affairs counsel for NAMIC and serves in a cross-functional role supporting state, federal and international issues.

Pauley further acts in a lead role with NAMIC public policy development groups including the Workers’ Compensation Council, the Amicus Advisory Group and the International and Market Regulation working groups.

Role of NLP in Claims Management

Natural language processing can transform a burdensome process, freeing claims professionals to apply their expertise where it makes the biggest difference.

Code on a computer screen

Claims management has always been a combination of art and science. The science part tends to be fairly easy to understand, at least at a conceptual level. After all, insurers base a great many of their decisions on statistics and probability. They search for anomalies, applying filters to discern which conditions fall outside of acceptable boundaries. If something unexpected turns up, they flag it for follow-up.

The art of claims management is quite a different story, though. What makes a great claims professional is his or her ability to read through detailed accident reports, medical notes and legal documents to determine which elements are meaningful and which ones simply constitute background noise.

In many respects, the claims professional’s role is to take in very large amounts of analog information and distill it into a form that can be understood through a more analytical, scientific lens. This is difficult enough, just on the face of it. It calls for an understanding of medical terminology and practice and legalese and the ability to decipher accident and medical reports. And it requires a knack for retaining and synthesizing information from multiple sources.

That difficulty is compounded, though, by the fact that virtually every claim is really a moving target. New information flows in constantly. Every fresh data point must be ingested, evaluated and understood in the context of the claim as a whole. Given the complexity and duration of many claims, making sense of all that detail is no small feat.

Technology can improve this process dramatically, easing the burden on claims professionals by ingesting new information the moment it arrives, discerning its meaning and placing it in context alongside all the other information in the case. Technology can detect which conditions may indicate a high risk of litigation and which ones might raise concerns about poor medical outcomes. Artificial intelligence (AI) functions as a kind of intelligent assistant to the claims professional, pre-processing information and calling attention to the details that matter most.

The key that unlocks that door is called natural language processing, or NLP.

Predicting Litigation Risk in Commercial Auto Claims

Let’s consider what this might look like from the perspective of litigation risk in commercial auto claims. After years of record losses, insurance carriers got a short reprieve during the COVID-19 shutdowns of 2020. Claims shot back up in 2021, though, raising the alarm on loss ratios and the factors that affect them.

Litigation prevention is a key factor in that equation. Experienced adjusters typically understand which kinds of claim details indicate likely attorney involvement; but seasoned professionals can be hard to hire and retain these days, and it takes considerable time for a new hire to come up to speed.

AI can improve the speed and accuracy with which claims data is assessed. That helps your most experienced people be far more effective, and it gives your newer staff a leg up. Perhaps most importantly, AI can flag at-risk claims early, enabling you to steer potentially problematic cases to the most experienced adjusters in your organization or push to settle those cases pre-litigation.

See Also: AI Investment in Commercial Lines

Finding Structure in Unstructured Data

In the commercial auto space, there are five types of structured data that adjusters look at to determine whether it’s likely that attorneys will get involved. These are the types and number of vehicles involved, the location of the accident, type of accident, injury details and the amount of vehicle damage. Unfortunately, important details are often buried in the claim file in the form of unstructured data.

A great deal of the information collected for commercial auto claims comes from phone conversations between the adjuster and the various parties involved in the case. Other information comes from medical notes, police reports and email communications. In a perfect world, all of this information would be entered into a claim system as structured, standardized data. In the real world, it’s often cryptic and somewhat difficult to decipher.

Consider a claim that includes the following note: “Insd emp/drvr contact became uncomfortable, attempted to reset/fix and rear-ended clmt … chain reaction.” To an experienced reader, that may indicate fault and liability. To a novice, it might pass under the radar. In either case, it’s invisible to a quantitative scoring system unless it can be scored and rendered as structured data.

NLP parses human language to discern its underlying meaning. It can detect context, decipher abbreviations and distinguish among seemingly nuanced variations of a phrase that might have very different implications. NLP can understand unstructured data such as notes, assigning a quantitative assessment indicating the likelihood that the insured driver was at fault. In this example, NLP might flag the claim as high-risk because it matches patterns that indicate an elevated risk of liability.

NLP can also fill in missing details that might be provided in an adjuster’s notes but were never included as structured data, per se. A claim might contain a note that says: “Was the driver an employee? Yes. Is there an alcohol consumption policy? No.” Clearly, the claims manager gathered this information but may have been too busy to enter it properly as structured information in the claims system.

Other examples include verification of accident details (e.g., “photos from insrd confirms hvy impct accdnt”), details that provide clues as to the severity of injuries (“passngr went to ER … admitted for 2 days … mltpl tests … no injuries.”) or details about claimants (“unsure if CV is insured”).

NLP parses that kind of unstructured information, rendering it as structured data and filling in the gaps that otherwise go unnoticed. AI-powered NLP is always on, ready to ingest information the moment it arrives. That empowers claims managers to act promptly when there’s a material change to one of their cases.

The role of claims professional will not go away any time soon, if ever. Nevertheless, today’s technology can assist tremendously with an otherwise very burdensome process, freeing up claims professionals to focus on applying their judgment and expertise where it can make the biggest difference.


Kieran Wilcox

Profile picture for user KieranWilcox

Kieran Wilcox

Kieran Wilcox is director of claims solutions at CLARA Analytics.

He has a broad range of claims management experience, including auto carriers, self-insured corporations and injury law firms. His experience and expertise in handling auto, injury, general liability and workers’ compensation claims as an adjuster and risk manager provide him with critical insight as the subject matter expert at CLARA for all things claims and insurance. 

Talent Gap: Getting Back to Basics

As the industry faces mass retirements and a challenging labor market, it’s time to get down to brass tacks. Maybe the solution is simpler than we think. 

Business people touching hands above a table

Across the country, the Great Resignation has seen professionals leaving their jobs and moving on for several reasons, including the COVID-19 pandemic, unsatisfactory or uninspiring working conditions, limited opportunities for growth and more. Just this March, a record 4.5 million people quit their jobs, leaving businesses with significant deficiencies in their workforces.

As we all know, concern as to how to attract the next crop of professionals is nothing new for the insurance industry. According to Insurance News Net, a quarter of the insurance industry is currently over the age of 55. We’ve faced a talent issue for several years and grappled with the best ways to tackle the challenge. Now, as the industry faces the looming threat of mass retirements from industry professionals and a challenging labor market to break into, it’s time to get down to brass tacks. Maybe the solution is simpler than we think. 

What the Industry is Doing Differently

Recently, the insurance industry has taken several different steps to address its talent deficit. For starters, we have seen growth in apprenticeship programs. These programs are designed to bring in nontraditional talent from a wide variety of backgrounds. Innovative programs like these aid in the recruitment of a variety of candidates, from parents returning to the workforce to high school students, to people from diverse geographic cultural and economic backgrounds, students with varying academic specializations and more. This hands-on experience gives them a taste of working in the industry and has proven valuable in showcasing the strength and variety of opportunities available within an insurance career.

At other businesses, we have seen the emergence of employee resource groups (ERGs). Serving as a tool for companies to show appreciation for their staff, ERGs create a safe environment for employees across backgrounds to share their experience working in the industry and learn from each other’s time at their companies. 

These measures and others have certainly moved our industry forward in terms of addressing the talent gap. At Pennsylvania Lumbermens Mutual Insurance Company (PLM), we are not afraid to think outside the box, but we also know that in addition to these new methods, more traditional methods of recruiting and retaining can continue to produce happy employees and good work product – provided companies invest the right resources into them. We have found great success in recent years providing prospective and current staff with the resources they need to develop careers in insurance that make them feel valued, appreciated, challenged and as if they are making a difference. 

A Focus on Education and Development

For longstanding industry professionals, education is key to keeping them engaged and inspired. Here, an emphasis on continuing education and developing varied skillsets can go a long way. 

At PLM, we require our employees to participate in continuing education. Career development is essential to building out our business and to the individual professional success of our team members. We encourage our employees to regularly participate in educational courses that further their talents and continue to grow their interest in the work. We also reward them financially for their efforts toward continuing education.

Additionally, we try to expose our staff members to several disciplines of the business so they can find what truly fits their skillsets and passion where possible. For example, we have people on our team who started in underwriting, switched to IT and then found their home working on our marketing team. We want our employees to feel they aren’t boxed into their current roles and have the chance to explore, try new experiences and expand their skills. 

Companies across the industry can improve their retention efforts with a renewed dedication to professional development. Staff members want to feel valued by their organization and want to believe they are making progress in their own careers. Working with them to develop their skillsets can be a valuable step forward.

See Also: Keys to Finding and Nurturing Talent

Work-Study Initiatives and College Internships

Insurance continues to have a reputation issue among younger audiences as an industry with limited intrigue, but by reaching them early, leaders can showcase not only the value of a career in the industry, but the value of insurance to society. They likely don’t realize that insurance is a key factor in keeping our global economy humming – providing opportunity for new retail, professional services, the creation of new life-saving medicines and more. Through education opportunities and practical experience, insurers can not only correct misconceptions about the industry, but paint the industry as the cog in our global economic engine that it is.

At PLM, we partner with the Cristo Rey Philadelphia High School, which has a work-study program that has allowed us to provide students with a clear, comprehensive introduction to both the insurance industry and the wood niche that we insure. Once a week, we work with their students to introduce them to the basics of an insurance career and show them how rewarding a career in insurance can be. Our partnership gives these students a glimpse at the inner workings of insurance, while also providing them with practical skills for their continued education. 

A more common tool used by the industry is of course college internships. College students looking to try new work and discover career paths can take advantage of internship programs to see if they fit in insurance. Often, we see college internships at companies in insurance or in other industries that only offer interns basic experience. Their work is often limited to administrative tasks, research projects and other hands-off responsibilities that don’t showcase the value of working in insurance. 

College internships should provide practical work experience and give interns a chance to really see what their day-to-day work would be like. They should also have the opportunity to try out different parts of the business and find what roles they truly enjoy. This can be helpful for the employer as well, as they could have a new hire in a few months who’s already been partially onboarded and exposed to the business, the team and company culture. At PLM, we’ve hired around five interns each year.

Show That You Care

Several recent studies have demonstrated that both new recruits and current industry professionals want to work in an environment where they feel they can make a difference. Part of the industry’s reputation problem has been a perception that a career in insurance is simply profit-oriented. What our industry has struggled to convey over the years is that insurance is an industry rooted in giving back.

In times of crisis, our industry provides critical protection and support to those in need. When a disaster occurs, insurance professionals are almost immediately on-site assessing damages and seeing what we can do to recoup what people have lost. 

The insurance industry actually has a big heart. A 2020 study from McKinsey found from 2015 to 2019, the industry donated around $560 million to $600 million to support those enduring hardships from food insecurity to homelessness and more. 

This dedication needs to be showcased to the next generation of talent. At PLM, we look to do this by folding volunteering and giving back into the fabric of our company culture. With our headquarters in Philadelphia, PLM leads several initiatives in the Philadelphia community throughout the year working with major nonprofits including the ASPCA, Ronald McDonald House, MANNA, Cradles to Crayons and more. We also match employee donations dollar-for-dollar to foster a culture of giving. Most notably, we annually host a month-long United Way campaign, which gathers our entire team for volunteering and giving initiatives. Last year, we had 100% participation and contributed a total of $205,411 for programs in the Philadelphia community. Through initiatives like these, we can highlight the industry’s dedication to giving and showcase our commitment to social good.

Moving Forward 

Like many industries today, insurance does have a talent problem. But our industry is working to combat this growing concern and has been for years. By continuing to innovate and come up with new programs to attract talent from a variety of backgrounds, as well as a renewed focus on tried-and-true measures with a new investment of resources, we’re up to the task. 

As an industry, we need to build on education and development programs, make a stronger commitment to recruitment initiatives and earlier outreach, and demonstrate our industry’s rich history of giving back and desire to engage our team members and our business efforts in initiatives for social good. This way, our industry can not only survive this talent crisis, but lead the way for others now seeing talent shortages of their own.


John Smith

Profile picture for user JohnSmith

John Smith

John Smith is president and chief executive officer at Pennsylvania Lumbermens Mutual Insurance (PLM).

With more than 40 years in the insurance industry, he has been a part of PLM since 1998.

Data Mesh: What It Is and Why It Matters

Demand for data in today’s insurance companies is outpacing supply, and, in most cases, the throttle is organizational rather than technical.

Green and red mesh

A seismic wave stirring for insurance data management may upend the decades-old data warehousing movement. Will the wave be colossal, like data warehousing, or will it peter out before hitting land, a la object-oriented programming?

I’m talking about data mesh. But what is data mesh exactly, and why is it gaining such momentum? I’ll get to that in a minute but, first, let’s look at why traditional data warehousing is coming up short.

Why Current Monolith Approaches Aren’t Working

Data is the lifeblood of insurance modernization, and stakeholders everywhere need current data now. Unfortunately, in many insurance companies, the data monolith just can’t keep up with demand. Data warehouses, data lakes, cloud warehouses and lake houses are all variations on a theme: a shared repository integrating operational data to meet cross-domain analytic needs – e.g., integrating claims with losses, campaigns with customers and revenue with producers. The paradigm is compelling in its simplicity and workability, but it has three inherent chokepoints:

  • One data producer can’t keep up with many data consumers
  • Data intelligence is at the source system, not in the backend data warehouse
  • The data warehouse is an extra hop

Fivetran recently found that 86% of analysts report having to use stale data and that 90% report unreliable data sources. Technology is not the issue because the bottleneck is structural – the monolith. Organizations need a paradigm that achieves data decentralization and enables self-service while ensuring governance and control. Enter data mesh: equal parts organization, process and technology. 

See Also: Turning Data Into Action

Data Mesh

The concept of data mesh, which is gaining ferocious momentum with early innovators, was first published by Zhamak Dehghani in 2018. She defines its four cornerstones as follows:

  • Domain Ownership: This principle says bye-bye to the onerous enterprise data model, ETL hub and centralized repository because these are chokepoints. Instead, data ownership is at the domain level (e.g., claims, losses) because these teams are closest to the data, and they can scale with the number of domains.
  • Data as a Product: There will be data producers and data consumers. Producers will create data products that are discoverable, addressable, understandable, trustworthy, accessible, interoperable and secure in a self-service environment. To counter the tendency toward silos, domains will be accountable for creating and sharing data products, and success will be measured on metrics such as data quality and usage and consumer satisfaction. 
  • Self-Service Infrastructure: Players in the data mesh will be enabled with an abstracted layer of data infrastructure (e.g., storage, CPU and SQL processing, workflow control) as a self-service platform that enables them to publish and manage data products using consistent, reusable patterns and models. 
  • Federated Governance: Data mesh governance balances the needs for the domains to operate autonomously with the needs of global optimization and control. All data will be protected and regulatory-compliant. Security controls will be embedded into the platform with observability and auditability.

The vision for data mesh vision is akin to an “API enterprise” wherein all digital events are callable from a restful state. For the analytic side of the house, the vision is radical, holistic and often so sensible you find yourself asking, “Why didn’t we see this sooner?” Data mesh addresses the built-in limitations of a data warehouse by achieving decentralization (aka organizational parallel processing), moving data production closer to source systems where the intelligence is and eliminating the extra hop.

In a post-data warehouse world, data mesh may become the norm. Just as MPP (massively parallel processing) was once for edge cases and is now universal, domain-level data provisioning – aka organizational MPP – may become the dominate choice in a post-centralization world. However, for insurance companies, the vision doesn’t answer some of the critical questions, such as :

  • Where do we get a single version of the truth?
  • What about duplication of data engineer headcount creating cross-domain integrations (e.g., aligning earned premium and incurred losses by year)?
  • How do we avoid run-away public cloud bills?
  • What about our data warehouse organizations?
  • Who owns reference data mappings across domains?
  • How does a mature insurance company move from this universe to that one?

Domain-supplied data products need to co-exist with data warehouses because the investment and reliance on the latter are so great. That said, IT patterns are emerging from early data mesh implementations that drive much-needed self-service and decentralization. For example, there can be product marketplaces where consumers search for data and insights, view context (e.g. rules, latency), provision assets and provide feedback; data producer portals that provide a unified experience for producers to onboard, govern and manage data products, including tags, quality, business rules, definitions, and policies; and data catalogs as the vehicle that makes data products discoverable, understandable, trustworthy and accessible.

Demand for data in today’s insurance companies is outpacing supply, and, in most cases, the throttle is organizational rather than technical. The data mesh approach of pushing data product ownership to the domains to achieve greater scale is promising. In terms of the technology adoption curve, data mesh is somewhere between the first stage, the Innovators, and the second, the Early Adopters. It seems that innovators are concentrated in banking, and we need to hear their lessons learned. 


Mike Lamble

Profile picture for user MikeLamble

Mike Lamble

Mike Lamble is managing partner of PremiumIQ, a specialist consultancy focused on data analytics needs of insurance companies.

He was formerly the CEO of Clarity Insights and managing director of Knightsbridge Solutions. 

Will Electric Vehicles Be Safer?

In theory, they'll be safer, if only because the massive battery power will allow for a profusion of sensors and related safety devices. But we all know how theories can play out in practice.

Image
Electric Vehicles

Now that we seem to have reached a tipping point and will see far faster adoption of electric vehicles, a key question arises for insurers: Will they be safer or riskier?

In theory, they'll be safer, if only because the massive battery power will allow for a profusion of sensors and related safety devices. But we all know how theories can play out in practice. So, Cambridge Mobile Telematics took a hard look at performance to date and found that the answer is... a definite maybe. 

The factors involved are complex, and the stakes are high, so it's worth taking a look at the countervailing forces they've identified and at their analysis.

On the one hand, the CMT report found that the greater acceleration possible with electric motors is leading to much higher risks from fast acceleration and from cornering for electric vehicles (EVs). Tesla drivers, for instance, were found to have acceleration risks that were 3 1/2 to four times higher than drivers of vehicles with internal combustion engines (ICE). Tesla drivers had 76% higher risks from cornering.

Tesla drivers also speed 7% more than ICE vehicle drivers -- though hybrids speed 18% less, and compact EVs speed 24% less.

Those high-risk behaviors don't, in fact, translate into higher accident rates for Tesla drivers -- but do for those seeking extreme performance. People who own both a Tesla and an ICE vehicle were actually almost 50% less likely to crash their Tesla, on a per-mile basis. Drivers of Porsche EVs, though....

The report says: "Porsche drivers are 129% more likely to accelerate, 40% more likely to hard brake and 15% more likely to speed in their Porsche. Porsche drivers are also 55% more likely to crash while driving their Porsche," than while driving their ICE vehicle.

The issues get more confusing when you start looking at variables that could change considerably over time, especially as the performance and range of batteries improve. At the moment, "the average trip for a compact EV is 10% shorter in time and 26% shorter in distance than ICE vehicles," the report says. The shortening of trips is even more pronounced in cold weather, when EVs lose 10% to 20% of their range. But battery technology is improving rapidly. 

Gasoline prices are another wild card. With the surge over the past two years, the percentage of trips taken in a Tesla by those with both a Tesla and an ICE vehicle has risen from 63% of the total in January 2021 to 70% now. But the surge in prices has been subsiding -- and nobody can know where they go from here, unless you somehow have figured out what happens with global supply chains and with the Russian invasion of Ukraine. 

As driver behavior, safety features, battery performance, gasoline prices and other factors sort themselves out, EVs may well turn out to be less likely to crash than ICE vehicles -- or not.

In other words, stay tuned.

Cheers,

Paul

P.S. If you want some detail on why I believe we're reaching a tipping point in terms of EV purchases, here is what I wrote on the topic in February. The clean air incentives in the Inflation Reduction Act that the Senate passed over the weekend should speed the move toward EVs. 


How to Cruise Through the New Florida Property Insurance Legislation

Coastal home and business owners need adequate protection now as much as ever, especially as climate change leads to more severe and frequent storms. 

a photo of a hurricane destroyed house on top of it in the center is a blue box that reads "How to Cruise Through the New Florida Property Insurance Legislation"

It is no small task to insure coastal properties. Coastal home and business owners need adequate protection now as much as ever, especially as climate change leads to more severe and frequent storms. Unfortunately, the nature of risk – especially catastrophic risk from hurricanes – has become harder to predict using traditional underwriting tools.

Florida's new $150 million “My Safe Florida Home” legislation and the "predict and prevent" philosophy it embodies, mandate that insurers provide policyholders a detailed explanation for denying coverage and offer free inspections and up to $10,000 in matching grants for home improvement and hurricane retrofitting projects. This new legislation aims to build a better future for Floridian homeowners, but insurance companies need the right tools and technologies, such as a property intelligence platform equipped with geospatial imagery, predictive analytics, and artificial intelligence (AI).

Betterview article quote


Dave Tobias

Profile picture for user DaveTobias

Dave Tobias

David Tobias serves as the general manager of insurance at Nearmap.

Previously, he co-founded Betterview, a property intelligence platform for P&C insurers that Nearmap acquired in 2023. Before founding Betterview, Tobias was instrumental in scaling Research Specialist, an insurance loss control company.

The Metaverse and Financial Services

While the metaverse is still largely theoretical, providers of group and voluntary benefits might be able to capitalize on this emerging technology. Let’s speculate!

A woman wearing a VR headset holding out her hand to a blue beacon

Banks, insurance companies and employee benefits providers have taken massive leaps throughout the pandemic to better personalize their offerings and deliver additional value to plan members. But the work is not over.

Now the metaverse, a network of 3-D virtual worlds focused on strengthening social connections, is touted as a solution to many of the workplace woes that have characterized the pandemic era. (Zoom fatigue, anyone?) Metaverse evangelists claim that deeper interactions with technology through virtual and augmented reality will have a transformational impact on distributed workforces.

Insurers and banks – already stretched thin by the demands of digital transformation – are wondering if investment in this new tech will pay off.

While the metaverse is still largely theoretical, there could be several ways group and voluntary benefits providers could further capitalize on existing trends using this emerging technology. Let’s speculate!

Is the metaverse mostly hype?

Metaverse hype exploded following Mark Zuckerberg’s highly publicized announcement in October 2021 that Facebook’s name would change to Meta and that the company’s strategic direction would shift to building out the metaverse. 

However, the concept of a virtual 3-D space where people meet, play games and conduct business using virtual and augmented reality devices goes much further back. The term “metaverse” actually emerged in the early ‘90s, and Meta is by no means the only major player in the space. Tech giants Google, Apple and Microsoft have all invested heavily in metaverse development, with foundational research going back several years. Virtual properties are being snatched up for tens of millions of dollars.

Certainly, the metaverse has no shortage of skeptics, and for good reason. The hype has often been over the top. But there is something there. Savvy financial services giants like JP Morgan and American Express have already claimed expensive digital real estate in the metaverse. 

There is serious movement in this space that should not be dismissed by insurers -- even if the VR headsets do look a little silly.

How Can Employee Benefits Insurers Profit in the Metaverse?

Extending virtual health offerings

Since the pandemic, health insurers have experienced increased demand for virtual health and wellness services, such as telemedicine. By delivering these services through the metaverse, insurers could capitalize on trends while offering a more immersive experience.

Several technology providers, such as XRHealth, already offer metaverse-based virtual telemedicine services that user avatars can access at any time of the day.

Remote workers could also participate in mixed-reality wellness programs and fitness classes alongside their colleagues. This can promote healthy living and build rapport among distributed workforces.

Life and health insurers could integrate metaverse services into their benefits. Insureds would then interact more closely with the carrier’s brand. 

Avatars and gamification offer richer experiences

Carriers are already deploying AI-based technologies like digital assistants to deliver timely and contextual customer service and coaching. The metaverse presents an opportunity to extend these capabilities by connecting with a user’s avatar. 

Avatars represent an individual’s entire digital identity in a far richer way than we’ve seen previously. As people conduct more “in-person” activities using avatars, insurers will have more data than ever to develop personalization strategies. 

Carriers can leverage metaverse gamification to deliver rich experiences. For example, Cigna partnered with Microsoft to create a mixed-reality digital health tool called the "BioBall." The ball is a handheld, electronic orb that works with a virtual reality headset to navigate users through an interactive game while collecting their health metrics and flagging potential risks.

That’s a little more exciting than an online form!

Voluntary benefits tailored to the metaverse

Depending on how ubiquitous metaverse technology becomes, underwriters may very soon have troves of new data at their fingertips to more accurately and quickly evaluate a plan member’s risk. 

Using digital enrollment platforms, sales teams can recommend additional voluntary coverage based on a plan member’s activity level and other data points tied to their user avatar. This data may not be available through more traditional methods.

Additionally, popular voluntary benefits like identity theft protection will have a more important role to play in the metaverse. When a plan member’s identity can be tied to his or her digital avatar, that may create a bigger risk of identity theft.

New voluntary products tailored to distributed workforces “residing” in the metaverse may be commonplace in the next five years.

See Also: Beware the Metaverse

Responding to real-world, metaverse-related health risks

As plan members increase their usage of metaverse technology, they may be increasing their exposure to additional real-world risks. Metaverse distraction could be dangerous.

Some insurers are already responding. Seguro GO is an insurance policy designed to protect Pokémon GO players from accidents, thefts and injuries that may occur while players interact with the popular, augmented-reality game. 

Lengthy interactions within the metaverse may expose insureds to chronic health conditions tied to a sedentary lifestyle. With tools like digital coaches, insurers can establish a positive foothold in the metaverse and improve plan members’ physical wellbeing.

Insurers should also consider the mental-health risks users are exposing themselves to by protracted stays in the virtual world. We saw firsthand the mental health crisis that unfolded during the pandemic as screen time went through the roof. Will the metaverse really be any better?

Life and health insurers should pay close attention to how users interact with the metaverse and design wellness products and programs that encourage healthy digital habits, perhaps by leaning into the metaverse itself.

Will the metaverse disrupt employee benefits?

Inevitably, new insurtechs will exploit the metaverse, posing potential risks (and partnership opportunities) to more established players. At present, there is no way of knowing whether they will be successful in disrupting the industry, or even if the metaverse itself will be a success in the long run. Today, we are just speculating. 

The metaverse could have significant implications for traditional benefits distribution models. As carriers deploy customer-engagement strategies across the metaverse, it is likely that direct-to-consumer sales will increase further than they already have in recent years due to the more immersive brand experience offered within metaverse applications.

The metaverse won’t disrupt the fundamentals of the insurance business, but it will almost certainly change the relationship between insurers and insureds. As the technology matures, benefits carriers can offer more robust digital coaching, personalized benefits selection, collaborative digital wellness programs and new products to meet the coverage demands of metaverse denizens.   

Artificial reality, AI, gamification and other elements of the metaverse aren’t new. Whether you call it the metaverse or not, technology is changing rapidly, and it’s hard to predict where it will take us. Leaders of benefits insurers must help their companies stay on top of trends and positioned to take advantage of the metaverse and evolving tech.