Download

Global Insurance Forum Experts Series 2022

Over this five-part series, hear from insurance industry leaders about the cascading challenges wrought by the pandemic and other social and environmental issues -- and enormous opportunities to rethink the old ways of doing business and plan a better path forward.

sixthings


Global Insurance Forum

The 2022 Global Insurance Forum brought together more than 40 insurance executives from around the world to address the industry's role in rethinking old ways of doing business and plan a better path forward.

Join Paul Carroll, editor-in-chief of Insurance Thought Leadership, as he sits down with speakers from the event to take a closer look at critical topics. Over this six-part series, hear from industry leaders about how the insurance industry can leverage technology, mitigate risks, safeguard resources, and help lead the Great Reset of the global agenda.

Webinar 1: A Conversation with Mick Moloney

In this interview with Paul Carroll, editor-in-chief at Insurance Thought Leadership, Mick Moloney of Oliver Wyman explores:

  • How, in these increasingly unpredictable times, insurers can focus on reducing risk while still managing for growth.
  • How the industry is restructuring -- in particular, as brokers and many private-equity firms thrive while life insurers struggle -- and why many are looking at "asset-light" models like those popular in Silicon Valley. 
  • How the nature of work is changing as employees return to offices -- sort of.

Register Now

Mick Moloney

Mick Moloney, 
Partner, Global Head of Insurance
& Asset Management
Oliver Wyman


Webinar 2: A Conversation with Olav Cuiper

In this interview with Paul Carroll, editor-in-chief at Insurance Thought Leadership, Olav Cuiper, Executive Vice President, Chief Client Officer at RGA, explains:

  • How to embark on a digital customer journey -- and why that has to happen now.
  • How the pandemic has opened the way to new forms of engagement with customers, based on advice and service that go well beyond traditional products. 
  • Why wholesale banking can be a good model for engagement in the insurance industry. 

Register Now

Olav Cuiper

Olav Cuiper
Executive Vice President, Chief Client Officer
RGA


Webinar 3: A Conversation with Ken Mungan

In this interview, Ken Mungan, chairman of Milliman, lays out an innovative idea for how insurance companies and pension funds can deploy their trillions of dollars of capital to finance initiatives to mitigate climate change and the risks it creates. He also:

  • explains the dimensions of the gap
  • explores the role of platforms in innovating ways to tackle the protection gap.
  • concludes with optimism about humanity's ability to innovate in the face of climate change
  • the insurance industry's capacity to protect people from many of the related risks.

Register Now

Olav Cuiper

Ken Mungan, FSA, MAAA
Chairman
Milliman


Webinar 4: A Conversation with Thierry Léger

In this interview Thierry Léger, group chief underwriting officers at Swiss Re, explains:

  • that effects from climate change now account for half of reinsurers' net cat losses
  • that the data for half the exposures just isn't good enough at the moment.
  • that demand is surging for cat coverage just as capacity is leaving the market, creating a "monumental" gap of perhaps $40 billion or $50 billion between the demand and the offer.

Register Now

Thierry Léger

Thierry Léger
Group Chief Underwriting Officer
Swiss Re


Webinar 5: A Conversation with Joshua Landau

In this interview, Josh Landau, president of the International Insurance Society, hits the high points from the recent Global Insurance Forum. He lays out:

  • how insurers are leaning in on climate change to increase coverage and mitigate its effects.
  • how companies are using embedded insurance to extend their reach and simplify the purchasing process for customer.
  • how insurers have a great story to tell about being there when they're needed -- as evidenced by the billions of dollars of claims they paid during the pandemic and following the spate of natural disasters. 

Register Now

Joshua Landau

Joshua Landau
President
International Insurance Society


ITL Partner: International Insurance Society

Profile picture for user IISpartnerpage

ITL Partner: International Insurance Society

IIS serves as the inclusive voice of the industry, providing a platform for both private and public stakeholders to promote resilience, drive innovation, and stimulate the development of markets. The IIS membership is diverse and inclusive, with members hailing from mature and emerging markets representing all sectors of the re/insurance industry, academics, regulators and policymakers. As a non-advocative organization, the IIS serves as a neutral platform for active collaboration and examination of issues that shape the future of the global insurance industry. Its signature annual event, the Global Insurance Forum, is considered the premier industry conference and is attended by 500+ insurance leaders from around the globe.

Additional Resources

Creating an Exceptional Employee Experience

by Corey Pinkham, Chief Executive Officer, The Jacobson Group

Creating an Exceptional Employee Experience

The insurance industry’s evolving workplace requires organizations to rethink employee experience to better support today’s workforce. Prioritizing employee experience can strengthen engagement, retention, productivity, and long-term business outcomes.

Read More


Building Sovereign Disaster Resilience

Building Sovereign Disaster Resilience

In Swiss Re's latest Risk REconsidered podcast, Public Sector Solutions’ Gerry Lemcke and Marina Oberholzer explore innovative risk-transfer solutions that can strengthen countries’ financial resilience to natural disasters

Read More


Early-Onset Cancer Is Reshaping Risk: A look into the research; What the progress, plateaus, and pressures mean for insurers

Early-Onset Cancer Is Reshaping Risk: A look into the research. What the progress, plateaus, and pressures mean for insurers?

Cancer trends are changing, creating new considerations for insurers. New research from RGA reveals that while overall U.S. cancer mortality has declined, progress is slowing among younger populations as early-onset cancers, including colorectal and breast cancers, continue to rise.

Learn More


RGA Leaders of Tomorrow: Strengthening Public-Private Partnerships to Enhance Resilience Against Rising Losses from NatCat Events

by Dr. Robin Huettemann, Junior Engagement Manager, McKinsey & Company

Strengthening public-private partnerships to enhance resilience against rising losses from NatCat events

NatCat losses are challenging insurance affordability and availability, making public-private partnerships (PPPs) essential to strengthen coverage, prevention, and risk mitigation. Clear governance, better risk data and planning, innovative risk transfer, and stronger claims management can help insurers and governments build long-term

Learn More


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

5 Key Trends at ITC

Even with the macro-economic headwinds and other market challenges, every aspect of insurance is being redefined in the context of the future.

Tall buildings shot from a low angle

ITC was an action-packed week with over 8,000 attendees and participants across all aspects of the industry! The energy was amazing and contagious! Majesco once again was active and hosted a panel discussion with executives from MMG, Foresight and Combined, with over 250 attendees (standing room only) and lots of questions after the session for all of us. Why such interest? 

Because the industry is rapidly moving forward. Even with challenging macro-economic conditions, there was excitement about the future. What also became clear is companies not actively engaged in optimizing their current business and innovating for the future are at risk. Future industry leaders are doing both aggressively.  

Our panel discussion provided a view into what is reshaping the insurance marketplace and a new generation of leaders. We talked about five key trends that are foundational for insurance leaders.

Customers

Welcome to the customer of the future. New expectations. Different lifestyles and behaviors. Robust digital proficiency. New risk needs. Demand for great experiences at the core. An expectation of value.

Today’s customers are increasingly disillusioned with the traditional insurance approach, creating a loyalty fault line between customers’ expectations and insurers’ ability to deliver what they want and need. While risk and trust tend to be constants, customers increasingly have no guaranteed loyalty to old models, even for trusted brands.

Customers are seeking simple, holistic experiences across their lifecycle and demonstrated empathy. Customers are no longer simply looking for a claim payout. They are seeking help with life and whole-life management. They are expanding their view of financial wellness. Rather than looking at life, health, retirement, auto or property risk separately, customers are increasingly seeking companies that help them manage insurance needs more holistically and broadly through the products, customer experiences and services they provide. 

Digital transformation is required to create a business for a very different future — the one customers expect..

See also: What Future Will We Choose?

Delivering Value

Insurance can be difficult, complex and time-consuming, with products and services that don’t appear to deliver value. Today’s customers expect more. They want a risk product, valuable services and an experience that provides them what they need to manage their lives. This means that insurance products and services are shifting to prevention and mitigation of risk. And in the process, they are humanizing the entire customer lifecycle.

Part of the humanizing aspect is offering niche, personalized products, services and experiences that align to their specific risk need and use their personal data. From an increased interest in life, critical illness and disability insurance to telematics and cyber insurance and more, customers want insurance products that assess their personal risk, lifestyle and behaviors.    

Traditional product-oriented strategies, however, handicap insurers. Instead, insurers must consider a product to be inclusive of the risk product, valuable services and the customer experience to meet customer expectations of delivering value. Part of that value is providing risk-prevention and mitigation capabilities and services that help customers avoid or mitigate losses, dramatically redefining the customer experience.

Our panelists talked about the innovative approaches they are taking to deliver value by offering more than just the risk product, such as a new critical illness product that provides DNA testing to support personalized cancer treatments, a new dental product that includes a smart toothbrush to monitor brushing for improved health and a workers' comp product that supports safety and risk monitoring. 

The bottom line… The potential is limitless to deliver greater value to customers' we just need to think outside the box and keep the customer lifecycle and needs in focus.

Market Reach and Channels

Complexity and out-of-date insurance processes affect almost every line of products. Many insurer innovations are refocusing to a “buying” over “selling” approach, through a multi-channel strategy that meets customers where and when they want to buy. If distribution channels are easy to use, with products that are easy to understand, then insurance has an opportunity to grow through friction-free, multi-channel distribution.

While agents and brokers remain a dominant channel, new channels, such as marketplaces and embedded insurance, are gaining a lot of attention and traction. In fact, embedded insurance was the hottest topic of discussion at ITC and one we have done a lot of research on.

Insurers looking to compete will find it challenging to do it alone. Creating an ecosystem of connected channels, using a range of digital capabilities and connecting with customers when and how they want to, requires collaboration.

In today’s connected world, insurance must play across a wide distribution spectrum of channel options, expanding channels and partners to reach customers when, where and with whom they want to buy insurance. These options form a distribution ecosystem that expands reach but requires a partnership approach, particularly for embedded channels. Embedded insurance completely changes this paradigm. With it, insurance is no longer sold, because it is bought as a part of something else.

The new and growing spectrum of channel options now available, especially the exciting opportunities for embedded insurance, will give innovative insurers and their partners tremendous opportunities for growth, with new markets, new offerings, satisfied and loyal customers…and growing books of business.

See also: Boldly Insure Where No One Has Gone

Technology

Technology provides a foundation to adapt, innovate and deliver at speed to execute on strategy and market shifts. The rising importance and adoption of platform technologies, APIs, microservices, digital capabilities, new/non-traditional data sources and advanced analytics capabilities are now crucial to industry leadership.

From the front office to the back office, SaaS platforms are reshaping the business focus from policy to customer, from process to experience, from static to dynamic pricing, from point-in-time underwriting to continuous underwriting, from historical view of data to predictive and prescriptive data, from traditional products to innovative products and so much more. Insurers’ ability to create and grow an ecosystem of partners to deliver increased value to the customer relationship will deepen and differentiate customer loyalty.

What distinguishes insurance leaders? In our discussion and in many of the sessions at ITC, it was evident that leaders see the market and technological trends as a many-fold opportunity for insurance. Leaders focus on initiatives instrumental to creating new business models, expanding distribution channels, entering new markets, adding services and developing new products by leveraging technology as a foundation and catalyst for innovation. Leaders establish a strong operational and technology foundation that brings together SaaS next-gen core insurance systems, digital experience platforms, partnerships, ecosystems and data and analytics. These are built on a modern architecture using integrated microservices or APIs running in the cloud with a focus on speed and scale.  

Leaders also use technology to fundamentally change the business operating model and to innovate – two key aspects tracked by AM Best in their innovation ratings, reflected in our Strategic Priorities research and AM Best assessments.

There is increasing evidence that those who focus on next-gen core, incorporate new sources of data and analytics, expand channels to reach new market segments and customers and offer innovative products and services are leaping forward from the competition in operational effectiveness and growth. Along the way, these insurers create a new, sustainable business model. They grow their expertise at providing compelling customer experiences to capture new business and foster a greater sense of partnership, trust and loyalty.  

It is clear, even with the macro-economic headwinds and other market challenges, every aspect of insurance is being redefined in the context of the future, and next-generation technology is foundational for that future.

Talent

Talent constraints are forcing companies to get creative. The Great Resignation, including increased early retirements is affecting the knowledge base. A move to virtual or hybrid work models is changing how companies transform themselves. The expanding gig economy and contract workers are giving us workplace in constant motion. Competition for talent and low unemployment rates have created their own source of inflation. These historic trends are fundamentally changing the essence of the workforce, affecting both the insurance culture and the balance sheet.

According to the U.S. Bureau of Labor Statistics, the insurance industry is about halfway through a massive 15-year shift, with 50% of the workforce retiring by 2028. For some insurers, it is even more dramatic, with some projecting 40% of their workforce will be eligible for retirement within the next three to five years. The loss of these employees will create a brain drain and loss of institutional and industry knowledge that insurers will be challenged to replace. Adding to this is the lack of interest in insurance … because it is not necessarily seen as cool or sexy when compared with other industries. 

To respond to the key trends shifting the insurance industry, retention and access to talent is crucial. The panel discussed a range of areas they are focused on, including: partnerships with local colleges to prepare and attract talent, retraining existing employees, embracing workforce flexibility with remote working, accelerating digital transformation operationally with next-gen core, data and analytics and digital. All of this will help insurers both capture the institutional and industry knowledge and decrease the dependence on those leaving, redefining jobs and roles that are more aligned to valued work and leveraging next-gen technology that will make roles broader and more effective. The result will be a reduction in siloed and transactional roles, and a greater degree of satisfaction and experience as employees engage with customers and channels. 

Leaders are finding ways to find and keep talent that is crucial and foundational to building and growing their new digital-first customer-focused businesses.

The Secret Sauce

What separates leaders from others?  What is the secret sauce that increases the chance for success? Fundamentally, what separates successful leaders from others is their focus on strategy – both operational and strategic. Leaders execute on their strategy. They embrace curiosity given the continued pace of change and the need to see the world from the customer’s viewpoint. Curiosity fosters innovation. It requires courage, because innovation is difficult and sometimes results in failure. Learning from failure, however, can create success.

Leaders keep the “pedal to the metal” by staying focused on priorities and initiatives that enable the strategy, including resources and funding. Even leaders might be tempted, in an uncertain economy, to overreact by cutting back budgets, reducing technology investments and pulling back on innovation. Recent history has proven that would be a big mistake. The dot-com crash in 200-2001 and the financial crisis of 2007-2008 proved this strategy to be short-sighted.

Those that continued forward and even increased investments in the face of those major market challenges leapfrogged the competition and were better prepared to respond to the emergence of insurtech competitors and the COVID pandemic that accelerated digital expectations! 

While we don’t know what major disruption is next, we do know that we must be prepared, and putting the pedal to the metal focused on operational and strategic transformation and innovation will make the difference!

Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Do You Really Need Blockchain?

Though blockchain has vast potential due to security and trust, some of its benefits, such as decentralization and distributed processing, can turn into limitations.

Hand underneath a ball of connected lights

Blockchain has been the hottest buzzword for the past few years. The hype is so intense that many private and institutional investors are pouring millions into this technology as the next big thing. But are blockchain virtues stronger than blockchain challenges?

It is an important question, especially for those considering investing in blockchain development. Believing that blockchain is the future, investors might place money into a blockchain product without a complete understanding of the potential benefits and limitations of this technology.

Likewise, a software company might push forward with a blockchain project even if the end product will add little value to an already competitive market. Becoming more knowledgeable about the technology, assessing the blockchain viability in advance and involving blockchain consultants is a sound way to avoid such failures.

In many cases, other technologies perform just as well or even better than blockchain. When developing a solution, it is important to ask whether blockchain offers a competitive advantage in the given situation.

Decentralization is not a must

Cryptocurrencies have their benefits. A cryptocurrency such as Bitcoin is inherently decentralized. When there is no central authority, such as a government, nobody can influence the network. Could Bitcoin be decentralized if it ran through central servers? There would be a risk that the parties controlling the servers would somehow manipulate the cryptocurrency and community.

Consider YouTube’s video streaming services. It might be possible to set up a blockchain to stream videos, but if we could turn to a central authority like Alphabet’s YouTube to administer the network, is a blockchain-driven solution needed?

See also: 4 Technology Trends for 2022-2023

Distributed processing may offer declining benefits

Is distributed processing important when computing power is cheap? In the past, setting up server farms and mainframes was cost-inhibitive, even for large organizations. Over time, however, the costs for high-end PCs, servers and mainframes have declined dramatically. These devices offer compelling and affordable blockchain alternatives.

One way to consider processing power expenses is to look at the cost to process gigaflops, or one billion floating-point operations per second. In other words, how much does it cost to process 1 billion operations? In 1984, it would have cost roughly $18.5 billion. As of 2022, it may cost a couple of cents. As processors become cheaper and more powerful, it is fair to wonder if distributed processing will add value to your particular project.

Companies that use massive amounts of computing power, like Amazon, set up large processing farms. Yet these organizations also have access to vast resources, and computing power is rarely a problem. Meanwhile, high-end PCs and more affordable server solutions are often enough to meet the needs of enterprises and those who would have needed to pay considerable amounts to access or set up powerful servers in the past.

Further, some companies design ways to store personal and corporate data on other parties’ hard drives.

Yet it is risky. What if the other party’s storage drives are damaged? What if the data-storing parties figure out a way to hack the encryption? Any party considering blockchain-based data storage will face a mistrust dilemma—can they fully trust the other party with their data?

Meanwhile, storage costs per gigabyte have plummeted. In 1990, a gigabyte of storage space cost $11,500. As of 2022, a gigabyte costs a mere 2 cents. Given the dramatic decline in storage costs, a blockchain-based cloud storage system may make little economic sense, even for parties who have to store massive amounts of data.

Blockchain is less useful when identities are known

One of the key advantages of blockchain is coordinating transactions between anonymous parties. For example, in a Bitcoin transaction, neither party knows the actual identity of the other party. If scammed, the wronged party would have little recourse because they would not know the scammer’s identity.

Blockchain reduces these risks by verifying the transaction on both ends. If someone wants to sell Bitcoin, the blockchain will first verify that the seller has the necessary funds and that they have not been traded. The seller will not confirm the transaction, by providing their 64-digit long private key, until they get the stipulated amount.

Thus, this system allows two mutually mistrusting parties to carry out a complex transaction without knowing their identities. 

In instances where both parties know each other’s identities, the benefits are less obvious. If a business sends payment to another business but does not get the products or services in return, the wronged party will have legal recourse.

Conclusion: blockchain does not fit every project

From nonprofits and governments to banking and healthcare organizations, blockchain technology expanded adoption to almost every industry sector. 

Though blockchain has vast technological potential due to security and trust, some of its benefits, such as decentralization or distributed processing, can turn into limitations.

Companies should ensure that blockchain’s specific applications align with its competitive advantages. Haphazardly applying blockchain to areas where it offers little-to-no benefit may result in wasted money, time and resources.

Embedded Insurance Is Everywhere

As InsureTech Connect showed, the embedded topic is cool among investors, and every funder is adding it to the pitch deck.

People swimming and wading in the ocean

Last month, we had the ITC event in Vegas, and I feel obliged to dedicate this edition of the newsletter to my takeaways from this conference. It took a while to digest the two days of discussions: the first day, nine straight hours of meetings with two dinners after, eight hours of meetings the second day and another two dinners.

My summary, with some anecdotal evidence:

  1. Some incumbents are getting more and more serious about innovation.
  2. Innovators understand that agents and brokers are here to stay.
  3. Shiny new things replaced the old ones.
  4. Everyone is trying embedding insurance somewhere.

1. Some incumbents are getting more and more serious about innovation

A few months ago, in one of the previous editions of this newsletter, I stressed my belief in the importance of innovation. Well, some incumbents came to ITC well-prepared to meet tech providers, discover new things and exchange thoughts with their peers. This kind of incumbent had a large delegation, a shared agenda among their executives and spaces to efficiently have the meetings.

Other incumbents did not show up, or dramatically reduced the number of their people at the event. Since insurtech stocks got hit and issues such as inflation hit P&Ls, insurance incumbents that were not serious about innovation have happily and quickly canceled insurtech from their agenda.

Since the hype has vanished, we have seen those who were committed to a multiyear innovation journey and those who were only pretending to innovate. To quote Warren Buffett -- he tends to be right -- "when the tide goes out, you discover who’s been swimming naked."


2. Innovators understand that agents and brokers are here to stay

Many (really a ton) of the tech players in the expo area were providing tools to support agents and brokers, and to help carriers to work with agents and brokers better. It looks like the people who work in innovation (finally) get that agents and brokers are here to stay.

The past ITC editions were all about digital sales, DTC (direct-to-consumer) and disintermediation. I have always struggled to make people digest that insurtech was more than D2C (and more than startups). We had tons of articles and interviews for all the pandemic period talking about the "digital shift" in the insurance sector. Even when facts and figures about the premium split were available, people still pretended that the reality was different.

Last year, we had the famous trio (Lemonade, Hippo and Root) doing a U-turn from dissing agents to using them for selling more policies (or selling them with a lower acquisition cost). I commented that "it seems agents and brokers are not useful when you have to raise money from VCs, but they are extremely useful when you want to build an insurance portfolio!" Well, looking at the ITC floor, you can raise money even acknowledging that agents and brokers are here to stay nowadays.

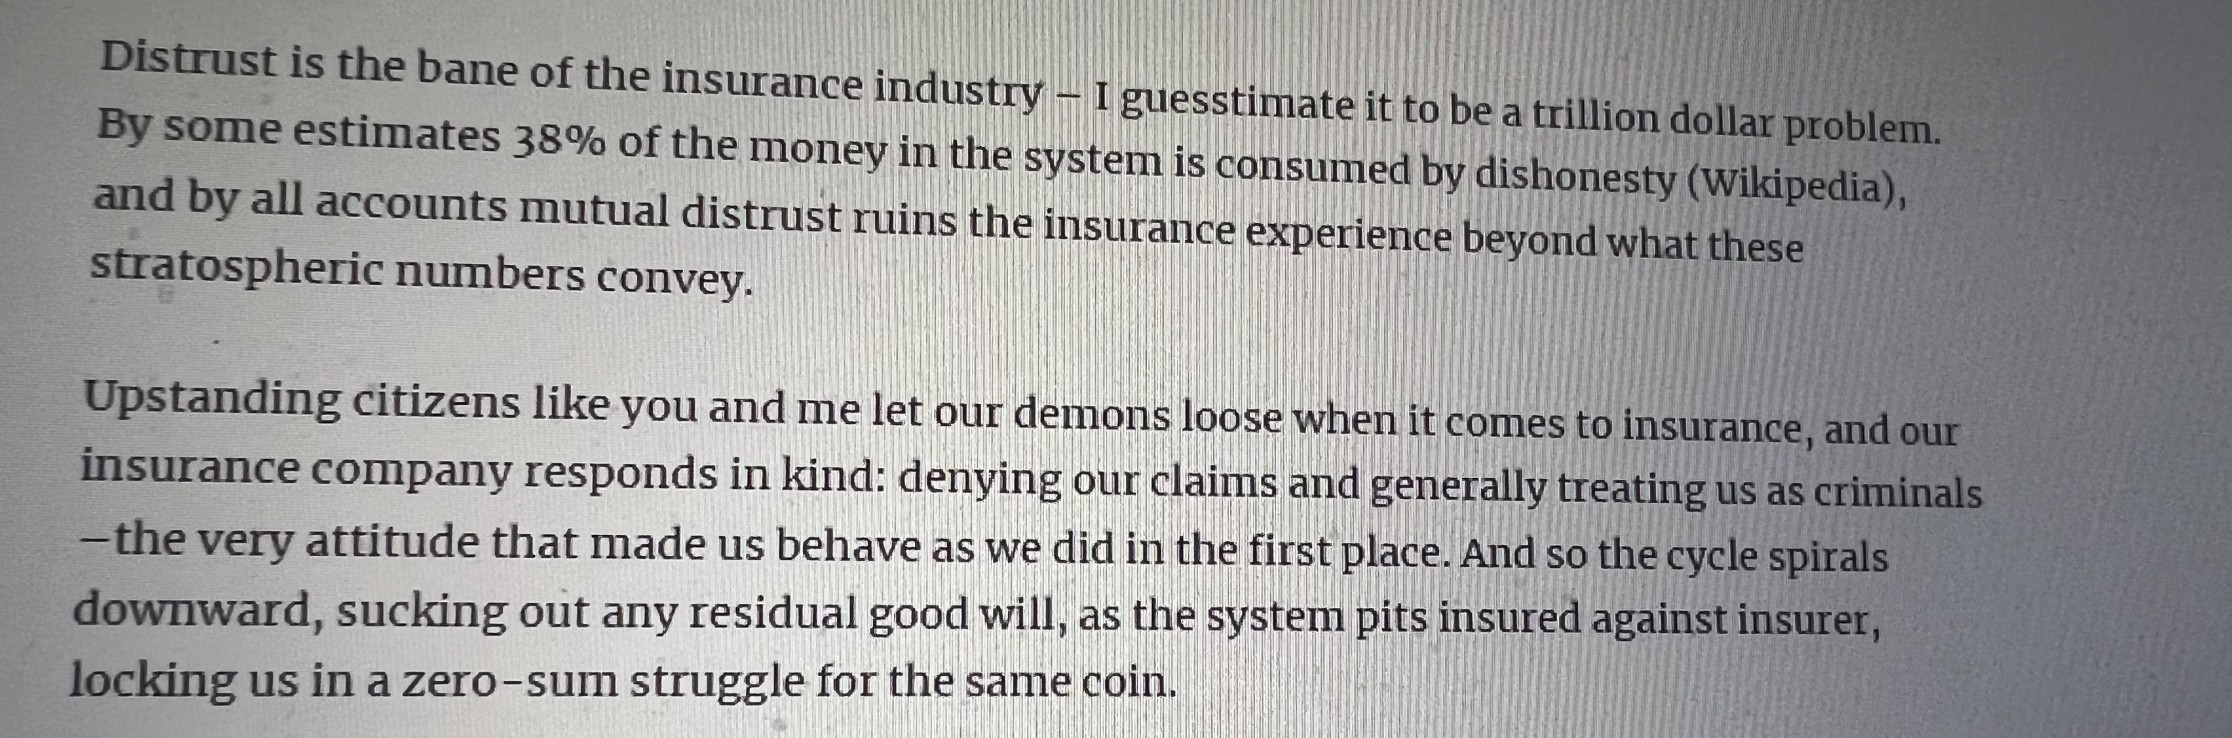
Lemonade has just done another big U-turn. Many of you probably remember when they were screaming daily about how insurance incumbents were bad. Here is a snapshot of Lemonade's CEO blog post from six or seven years ago:

Last week, Lemonade announced proudly that they enter the U.K. market with a partnership with Aviva. Here are the words of Lemonade's CEO now: “Pairing Lemonade’s strengths with Aviva’s promises to deliver insurance that is digitally native, yet rooted in the birth of modern statistics in the 1700s. It’s the best of both worlds, giving people a refreshing experience backed by a company they’ve known and trusted for years”.

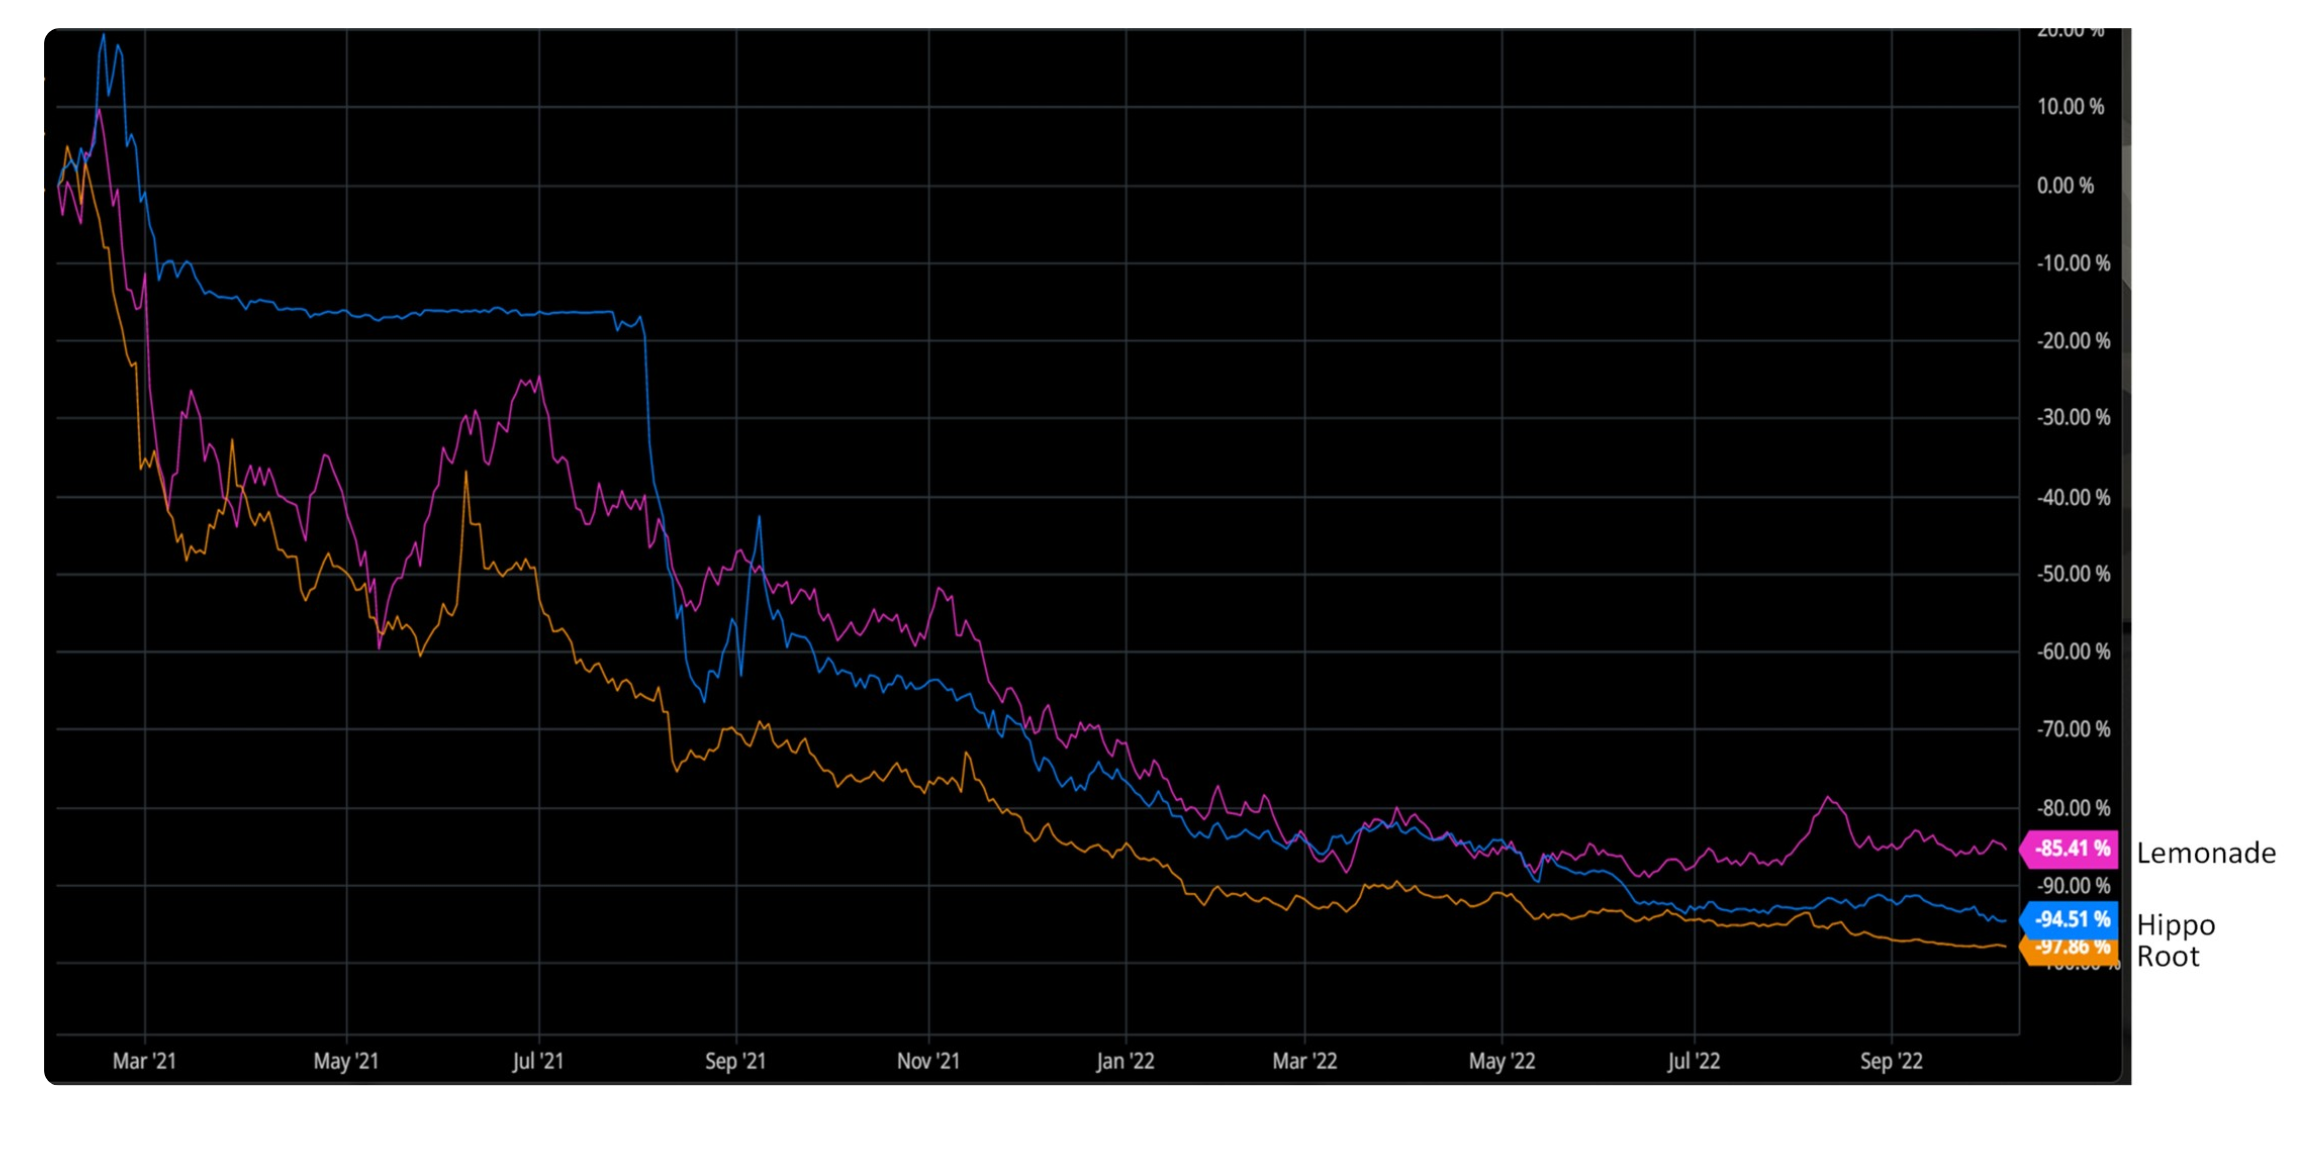
Yes, this is the same CEO (even if the stock lost about 86% of its value from the maximum in February 2021). A "disruptor" has moved:

  • from believing that insurers were chronically affected by "distrust"
  • to acknowledging the policyholders' trust in an incumbent insurance carrier.

3. Shiny new things replaced the old ones

Blockchain was missed at ITC 2022. Nobody mentioned it, even though in previous years just about any ew venture would claim to have some blockchain embedded in their approach.

One of the shiniest new toys seems to be the app marketplace. I heard about so many marketplaces in just two days in Vegas....

4. Everyone is trying to embed insurance somewhere

Everyone -- really, everyone! -- is trying to embed insurance somewhere. Most of the initiatives are still early enough to share only enthusiasm and big/vague expectations. Clearly, the embedded topic is cool among investors, and every funder is adding it to the pitch deck.

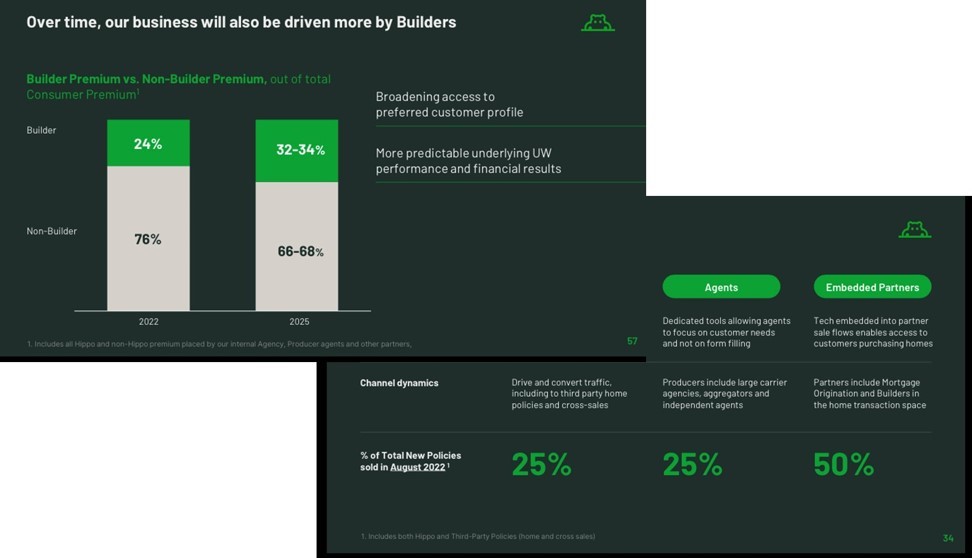
However -- to set expectations -- an embedded approach will not be enough to guarantee favorable evaluations. I described in detail Hippo's business model and results in a past edition of the Facts & Figures Newsletter, and even more about their success in distributing homeowner insurance through builders was shared on their investor day last September.

Two infographics overlapping

But, despite good performance on the currently hot topic, their stock doesn't show any sign of recovery. 

Graph of stocks

See also: Insurtech: Still No Sign of Disruption


How to Provide Better Coverage for Employees

As companies struggle to attract and retain people, there are ways to make life insurance more effective for—and attractive to—your employees. 

Two people having a discussion on a couch

HR managers haven’t had it easy since the onset of the Great Resignation. Employee turnover has become an increasingly dire problem for businesses. In the last year, more than half of all professionals have expressed a desire to change jobs, even to apply to completely new industries. So, HR managers have good reason to seek better ways to motivate employees to stay. Unfortunately, that’s easier said than done. 

One area of employee benefits that has been largely overlooked is life insurance, even though half of employees see life insurance benefits as more important now than before the pandemic. In fact, 80% of workers are highly interested in workplace life insurance benefits, which means companies that offer such benefits have a higher chance of retaining employees. 

That said, the current methods employers use to provide life insurance are less than ideal. The coverage amounts for group life insurance are usually inadequate to protect employees’ families in the event of a worker’s death. Group life insurance, as it’s currently designed, isn’t enough to allow companies to hang on to valuable employees.   

Fortunately, there are ways to make life insurance more effective for—and attractive to—your employees. 

Why Group Life Insurance Is Inadequate

As significant as life insurance is when a family really needs it, few employees give it much thought when they’re considering their benefits packages. They don’t realize the coverage is usually insufficient to provide financial stability for their families in the event of a tragedy. 

Some two-thirds of employees in the U.S. rely on life insurance in the form of employer-provided group policies. Although group insurance plans look good on paper, they tend to offer much less coverage than expected, sometimes as little as $25,000. Considering how many workers may have unpaid student debts, mortgages and dependents to care for, such low amounts are clearly not enough. Knowing this, many employers allow workers to purchase supplemental policies to increase coverage, but these aren’t guaranteed issue and may only reach up to $300,000 or less, which is still insufficient for many families. 

Additionally, group insurance plans through an employer generally aren’t portable, because the employer owns the policy, even though an employee may be paying a portion of the cost. Employees may not even realize that they’re paying into a policy that will essentially be null and void if they change jobs. 

Finally, because most companies rely on a single carrier to provide group life insurance to employees, workers may have limited options for coverage. Employees often find they have little to no control over life insurance benefits as offered through the workplace, even if such policies are easy to get and inexpensive. 

HR managers would do well to look closely at employee satisfaction regarding benefits packages. About 43% of people who resign from their positions claim that they did so at least in part because of inadequate workplace benefits. What most HR teams don’t realize is that they can easily offer employees much better options. 

See also: Adopting a New Mindset on Benefits

Ensuring Proper Coverage

HR managers can start to improve coverage by educating employees regarding life insurance benefits. For example, at least a third of employees don’t realize just how inadequate coverage offered through a group policy can be. A quarter of families will start to experience financial hardship just a month after the death of a primary wage earner, and nearly half will experience financial hardship within six months. And that’s primarily due to the low coverage amounts in group policies. 

Individual life insurance plans can be surprisingly inexpensive, contrary to popular belief. Around half of Americans overestimate the cost of an individual life insurance policy, often by at least three times. In fact, individual life insurance is typically available at almost the same cost as group plans and will likely provide much better coverage. For the same money, employees can receive coverage amounting to around $500,000. Knowing all this will encourage employees to seek supplementary life insurance or individual life insurance plans. 

Another area that many employees lack knowledge about is how easily and quickly they can obtain an individual life insurance policy. Many such policies in the past required medical exams, extensive paperwork and a long processing time, up to four weeks. But with accelerated underwriting and instant decision policies, workers can now get life insurance policies completely online within a matter of minutes, with no medical exam required. 

Besides educating employees, HR managers should work closely with company decision makers and insurers to create more life insurance options for employees. Ideally, companies should form relationships with multiple carriers, so employees can shop around for more personalized life insurance benefits. 

Final Thoughts

The way that you provide life insurance benefits matters. If nothing else, it’s a great way of showing employees that you genuinely care about them. Workers who feel like their employers care about them are nearly 70% less likely to pursue other employment opportunities. 

If you’re just checking a box by providing basic group coverage without helping your employees acquire adequate life insurance, your group plans can actually backfire and produce dissatisfaction. By contrast, if you can help employees find individual life insurance plans that offer adequate coverage, then employees will know you care about their well-being. You’ll likely experience less employee turnover and higher productivity as a result.


Bob Gaydos

Profile picture for user BobGaydos

Bob Gaydos

Bob Gaydos is the founder and CEO of Pendella, which automates underwriting through AI and big data.

Over the last 10 years, Gaydos has founded, invested in, advised and operated innovative companies in the benefit and insurance industry, such as: Maxwell Health, an online benefits administration platform acquired by Sun Life in 2018; Connected Benefits, an online insurance agency acquired by GoHealth in 2016; Limelight Health, a group underwriting platform acquired by Fineos in 2020; GoCo, an online platform for HR, benefits and payroll; and Ideon (formerly Vericred), an innovative data services platform powering digital quote-to-card experiences in health insurance and benefits.

How to Win in the Era of Wellness

Wellness-as-a-service models can produce great outcomes by closely integrating physical and financial wellness programs. 

Person balancing on her hands on a mountain peak

Even as the U.S. economy teeters on the brink of a recession, employers face a historically tight labor market and must compete for talent in new and creative ways. While competitive salaries are critical to attract and retain workers, company benefits often make the difference for companies trying to demonstrate that they value their employees and care about their physical, mental and financial health. 

For insurance companies, the increased focus on wellness represents a compelling growth opportunity. It’s also a win-win-win: Insurers that can help employers boost employee satisfaction and loyalty and promote healthier lifestyles for individuals will also benefit their own bottom lines. The substantial benefits to society should not be overlooked, either; the already massive and rapidly expanding retirement savings gap and the combination of longer lifespans and medical inflation place huge strains on government-sponsored programs. Stronger physical and financial wellness programs, when combined with traditional life and health policies, can certainly reduce that strain. 

Consumers are more interested in wellness than ever before. Capgemini research has found that large majorities of consumers want to improve their physical (69%) and financial (67%) wellness. And nearly as many are taking action to achieve that goal; 66% say they act on physical wellness (e.g., exercising, monitoring their diet, tracking health metrics), and 63% on financial wellness (e.g., budgeting, tracking expenses, saving for a long-term goal).

And the stakes around financial health will only increase during the coming economic stress. Employers certainly recognize the urgency, given the impact of financial stress on absenteeism and worker productivity. According to the Society for Human Resource Management, nearly 80% of companies believe financial stress hurts their employees’ productivity. Other studies have shown how financial stress increases absenteeism. Given the relatively low levels of financial literacy among U.S. workers, education is also key. 

Moving the needle on wellness

So how can insurers best respond to these powerful market forces? The key is to develop innovative solutions, such as wellness-as-a-service programs that address shifting consumer needs. Extensive education and useful tools are also critical to support and empower individuals to meet their unique goals. For insurers, wellness-as-a-service models provide deeper understanding of customer behaviors, the opportunity to engage more frequently and the ability to deliver personalized services. The long-term goals – higher levels of physical health and financial security – will pay off in the form of reduced claims volumes, more accurate assessment and more profitable pricing. It’s a powerful formula for near-term growth and long-term success. 

To be clear, many insurers have developed robust programs that promote healthier behaviors, with an emphasis on physical fitness, healthy eating and preventive care. These programs typically feature tailored prompts and reminders to exercise with motivational content and incentives for consumers that meet their goals. Relatively few insurers have applied these same behavioral techniques into their offerings for financial wellness. Consider how information and guidance for protection products, savings plans or investment options could be personalized based on key life events (e.g., getting married, having a child) or career stages (e.g., workers nearing retirement age). Wellness-as-a-service models are designed to produce great outcomes by closely integrating physical and financial wellness programs. 

See also: What Healthcare Insurers Need to Consider

Embracing an innovative and holistic approach

Wellness-as-a-service is a flexible model that focuses on three core priorities for physical and financial wellness:

  • Achieving physical wellness by helping consumers access emergency and regular medical care and establishing financial wellness by meeting current financial needs
  • Preventing future medical issues (e.g., by promoting adherence to prescriptions and fitness routines) and financial emergencies and preparing for unexpected expenses (e.g., through savings prompts and information on income protection)
  • Improving long-term physical and financial wellness through continuing advice about nutrition, exercise,\ and financial planning options, among other topics.

It’s a compelling opportunity for insurers that are looking for ways to increase their relevance to consumers’ lives and seeking to make inroads in the employee benefits market. But, according to the inaugural life and health insurance report from Capgemini, only 8% of insurers have established effective wellness-centric value propositions and built the necessary capabilities to execute on wellness-as-a-service strategies.

Realizing the benefits requires insurers to gain a deeper understanding of customer needs and expectations and to build the capabilities to act on such insights. Firms that get it right will be able to evolve from today’s focus on infrequent and standalone transactions toward engagement models based on stronger relationships and hyper-personalized experiences. 

Tailored communication and more frequent engagement will feed a virtuous circle of relationship-building, wherein insurers can enhance even basic transactions with personalized messaging and offers. Engagement will include specific touchpoints:

  • Relevant data monitoring and status updates, including health tracking and expense management
  • Delivery of personalized, goal-based nudges such as actionable health tips and recommendations, savings tips and retirement planning suggestions
  • Customized planning through regular touchpoints such as medical check-ups and portfolio rebalancing advice meetings
  • Hyper-personalized motivational tactics, with tangible and individualized incentives and rewards to customers following tips and advice and meeting goals

Insurers must also design and deploy the modular, data-driven and platform-focused technology architectures that enable sharper behavioral insights, stronger analytics capabilities and more pervasive use of artificial intelligence, machine learning and the cloud to deliver these customized experiences. Establishing sophisticated wellness-as-a-service models will not be easy, but we believe the potential upside more than justifies the necessary effort and investment. 

The global pandemic certainly heightened awareness of mortality and the need for greater financial security. It also clarified the intricate links between physical and financial health. Insurers are well-positioned to improve both dimensions of wellness because, as our research indicates, customers consider insurers as trusted advisers and providers for both physical and financial health. 


Samantha Chow

Profile picture for user SamanthaChow

Samantha Chow

Samantha Chow is the global market lead for life, annuity and health with Capgemini.

She has over 20 years of experience in the life insurance, annuity and benefits industry. She has deep expertise in product development, pricing strategies, competitive intelligence, operational process improvement, underwriting, claims, policy administration and change management. Chow is focused on growing enterprise-wide capabilities for facilitating transformational and cultural change, digital transformation, improving the customer experience, innovation and competitive advancement.

Life Insurers' Communication Problem

Insurers need to improve their communication by prioritizing customer experience as opposed to heavily relying on automation to do the job for them.

Person on the phone at a desk

There’s a record amount of interest in life insurance. Google Search traffic for “life insurance” increased by 50% between March and May 2020, likely brought on by the unprecedented COVID-19 pandemic. 43.1 million new life insurance policies were sold in 2020, and there has been a record amount of disbursement to beneficiaries.

Even with all this success, on average 4.2% of all life insurance policies lapse annually, while 6.4% of all term life policies lapse. Further, more than 40% of all life insurance policies have no active agent servicing the policyholder. 

Why is this happening? Well, the answer is it all comes down to communication. Life insurers are forgetting about the customers and coming up short delivering on customer experience. 

According to a recent study commissioned by Equisoft and conducted by Forrester, which compiled responses from over 200 North American life insurance executives, many of the barriers people face that prevent them from purchasing life insurance include not having someone to talk to when they have questions and not receiving follow-up information about the next steps. In essence, communication issues that can be resolved with improved customer experience. 

Life insurers recognize that the industry is plagued with communication issues. Our study found that 34% of respondents cited personalizing communication, experiences and interactions as a challenge for marketing execution. This statistic is especially troubling considering that customer expectations are rising due to the first-rate experiences people are accustomed to in every other industry.

So how can life insurers address their communication issues?

The good news is insurers have already tackled their first challenge: placing customer experience improvements at the top of the agenda. 66% of survey respondents said they want to improve their IT capabilities to enhance customer experience, and 72% of respondents also said improving the experience of customers is a top five priority in the next 12 months. 

The bad news is that insurers are placing too much emphasis on technology to improve customer experience and not enough on the human aspect of it. With all these new technologies that can streamline the needs for analysis, underwriting or claims processes, insurers are forgetting that adding the human touch to interactions can go a long way. 

Purchasing life insurance is an extremely intimate process‒asking consumers to confront anxiety-laden subjects like personal health, finances and their own mortality. It requires a personal touch that technology can’t always emulate. When a customer is looking for a life insurance policy, they’re looking for a company that can help them pick what’s best for them and their loved ones.

Insurers need to improve their communication by prioritizing customer experience as opposed to heavily relying on automation to do the job for them. This doesn’t mean getting rid of technology completely, but strategically incorporating it in areas where it can add value. 

See also: Digital Is the Assistant We Always Wanted

One example of how to do this is with data. New data analytics and collection technologies can be useful in streamlining the quoting process, as well as determining which prospective clients agents should reach out to first or what information to include in follow-up emails. The technologies can also be used to personalize communications and automate meeting scheduling, making it easier for agents who may be inundated with clients.

A part of improving communication is also making sure policyholders and prospective clients have someone to communicate with. Statistics show that 90% of new agents throw in the towel after a year. Over five years, resignation rates increase to 95%. Further, between 20% and 40% of agents will be aging out of the industry over the coming decade. That’s a lot of agents that policyholders rely on.

Many might think the solution here is to implement technology that can take on the job of the agent, but, in reality, it’s finding technology that can support agents and help them do their jobs more efficiently. It’s using technology to automate tedious and repetitive tasks, which then gives agents more time to meet and chat with policyholders. Adopting this path not only takes some of the weight off agents’ shoulders but also dissolves a key barrier that prevents people from purchasing life insurance. 

Life insurance is a people business. As insurers turn toward automation to solve their problems, it’s important to remember who they are truly helping and what their needs are. 


Brian Carey

Profile picture for user BrianCarey

Brian Carey

Brian Carey is senior director, insurance industry principal, Equisoft.

He holds a master's degree in information systems with honors from Drexel University and bachelor's degrees in computer science and mathematics from Widener University.

Unlocking Casualty Results With APD Science

Technology for assessing auto physical damage (APD) can enhance the casualty claims process and lead to better decisions, faster. 


Toy car on map of Europe

Claims has been an area of intense focus when it comes to digitization and new predictive tools. Nowhere has this been more pronounced than in auto physical damage (APD), and especially personal auto. 

Casualty claims, however, lack the finite universe of possible outcomes that APD enjoys, making it hard to deploy some of the advanced technology that’s benefitted the physical claim world. While the number and variety of cars and how they can be damaged is huge, it is still finite. With casualty, every human body is different, how injuries manifest and develop is different and so is the impact of those injuries on the people involved.

Casualty claim leaders have relied on expert judgment to wade through the large caseloads they face to focus on the matters with the highest risk of materially affecting the book to focus their expertise and skill effectively. 

Kevin Moynihan, VP of product management at CCC Intelligent Solutions (CCC), shared some of the historic and current best practices insurers have put in place to strive for accurate casualty outcomes. “Certainly, a focus on evaluation accuracy is a must, and a sophisticated medical bill review capability is a powerful ally for adjusters on most claims,” he said.

Bill review takes the previously manual and laborious process of combing through all medical bills on a claim to review accuracy and appropriateness of both charges and treatment and automates it to execute a carrier’s rules. The tool then flags inconsistencies and bubbles them to the surface for an adjuster’s review, for example, highlighting billing that the carrier deems unreasonable or unrelated.  

“These evaluation reviews are critical to achieving loss accuracy for any claims organization, but increasingly carriers need additional tools in their toolbox,” Moynihan said. “Evaluation occurs well into a claim’s life cycle, often many months after the date of loss. Rather than waiting, if carriers could tap into up front FNOL [first notice of loss] and APD data, they have a greater potential to set themselves up for claim handling success.”

Social inflation, which is driving settlement values up dramatically from their already high levels just a few short years ago, is another concern, and not the exclusive domain of severe claims and large losses. Several factors are driving this, including the increase in claims that have early attorney representation, up 26% over the five years ending in 2021, according to Sedgwick. And because the average cost of a claim with representation is 15.3 times higher than those without, according to Milliman, this shifting mix does not bode well for casualty loss ratios.

See also: How to Cut P&C Claims Leakage

Meg Sutton, SVP of casualty claims at Liberty Mutual, shares several factors fueling nuclear verdicts. “The business of litigation," she said, "has evolved to where there are nine-figure advertising budgets for some firms, increasing by almost two-thirds in a single year; the funding of litigation by third parties given the scale of potential settlements; and the increased use of high-tech presentation methods and highly specialized expert witnesses. Couple that with the change in perceptions of large corporations from trusted pillars of the community to organizations that are doing wrong and need to be punished, it’s not surprising that things have escalated to where they are now.”

Medical inflation is also extremely relevant here because most casualty claims have a bodily injury trigger at their heart. And the correlation between file age with indemnity and adjusting cost is well-established. Time delays also raise further opportunity for extra contractual risk.

The net impact is that casualty losses have been increasing dramatically, and we seem to be running out of tools to address this. In commercial auto liability, for example, all of these factors have led incurred losses to grow at an 11% compound annual growth rate throughout the 2010s, ending the period 2.5 times higher than at the beginning.

This issue is nothing new. What is different today is how we engage with it. While many APD tools aren’t directly relevant in the context of casualty claims, recent changes in those tools and the analytics tied to them are different now.

CCC has been using its Delta-V analysis, or the understanding of the change in velocity of the involved vehicles, and the resultant impact to both physical damage to the cars and bodily injury to passengers. For example, when a car decelerates from 20 miles per hour to zero in a fraction of a second, you will see great damage to the car and higher likelihood of severe injury to passengers than you would when the car decelerates from five miles per hour to zero over the course of a full second.

While that knowledge is helpful for predicting the likelihood of frame damage, for example, it can also be extremely valuable in assessing the validity of claimed bodily injury. This information can naturally signal potential fraud or a need for more involved adjusting, but it can also signal that a claim with little or no reported bodily injury may soon jump in severity as the injuries eventually get reported.

Sutton shares that Liberty Mutual is seeing tools like telematics and predictive modeling help in casualty matters already. Carriers can immediately recreate an accident and understand the forces at play to determine the best intervention and engagement with a claimant. Sutton says, “Because we have new tools and insights thanks to telematics, prediction, accident recreation, the physics with which an accident occurred, etc., – all things we never had before – it makes it easier to resolve matters faster. The more quickly you can reach out, price the claim and make a reasonable offer, the more likely the matter is to resolve before an attorney is involved, which would raise the risk of a nuclear verdict.”

CCC’s Moynihan provides additional context on Delta-V’s ability to affect casualty outcomes. “CCC has invested heavily to develop AI that can determine the change in velocity and principal director of force but will soon also do this from photos of the damaged vehicle. This new, meaningful capability will unlock additional use cases for carriers. Because those photos often become available on day one of the claim, they provide invaluable information to inform segmentation, liability and injury causality decisions earlier than ever before. This also represents true network effects. Carriers who have adopted smart estimate photo capture technology on the APD side, where parties are enabled and guided to take photos of their damage to submit to the carrier, will also be capturing the photos needed for calculating Delta-V. CCC has relationships with 18 of the top 20 carrier APD teams, representing over 90% of auto policies, so odds are most casualty organizations can turn to their APD peers to leverage these photos.”

Tools like Delta-V can be helpful for smaller casualty claims, as well. Many of these matters are adjudicated fairly quickly on the time scale of casualty claims, and that may feel good enough. But that handling speed happens with human intervention, and it may still be happening on much longer timescales than that same claimant experiences on APD. 

What if casualty adjusters knew about the details and physics of the APD claim? With Delta-V data, they can see whether the scale of injuries was appropriate and reasonable, as well as the cost of treatment. 

This has a flywheel effect, where closing out these matters quickly and efficiently frees expert adjusters to work on the matters that need more attention. You end up saving money on the entire system by offloading these simpler, clearer cases sooner thanks to insights brought over the wall from the APD tools being deployed.

And that’s exactly what can be done today that was not possible before. Using data from the APD experience, like Delta-V, carriers can have meaningful insights brought into their decision making on casualty claims, affecting segmentation, assignment and settlement decisions. 

Sutton talks about it as finding a way to allay people’s fears that carriers are trying to take advantage of them, as popular plaintiff’s bar ads suggest. She says, “When you can reassure people through data, a video, the facts on how fast the car was going or other behaviors, you can show claimants that they're being treated fairly. That goes a long way to resolving cases reasonably.”

But none of this should exist in a vacuum. This data and these tools aren’t meant to replace the expertise required by casualty claims. Instead, they are about enhancing it so better decisions can be made faster. 

Remember, good claims handling is about paying the right amount as quickly as possible. Tools like Delta-V can help casualty adjusters make the right decisions to do that.


Bryan Falchuk

Profile picture for user BryanFalchuk

Bryan Falchuk

Bryan Falchuk is the founder and managing partner of Insurance Evolution Partners, an adviser and consultant to carriers and their partners in the insurance ecosystem.

4 Technology Trends for 2022-2023

The trends enrich the digital experience of customers, reduce operating costs, improve service and take capacities to a new level.


Graphic of different workers

Technavio expects the insurance technology market will grow 45% annually. Let’s consider technology trends that will determine the growth and development of the insurance industry.

AI for predictive analytics in insurance

The profitability of an insurer largely depends on how the company works with information, analyzing it and making forecasts. Therefore, firms are trying to implement data analytics on a large scale. Artificial intelligence is one of the technologies that help to do this efficiently.

McKinsey estimated that in 2030-2040, 10% to 55% of insurance processes will be automated (underwriting, claims processing, record keeping, invoicing). The introduction of AI will make it possible.

By analyzing a large amount of data, AI in insurance can help you take preventive actions: to set better prices for services; identify insurance policy candidates with high risk; detect fraudulent activities; anticipate trends in the insurance business; and process claims faster.

Some digital banking research companies show that firms using predictive analytics reduce their loss ratio by 3% to 9%.

In addition, AI allows insurance companies to achieve a decent level of personalization, which is something that 80% of customers want so much. A smart algorithm evaluates the behavior of an insurance company's client on social networks and websites to offer more favorable and convenient policy conditions.

AI enables faster underwriting and claims processing, which is a big step forward in improving customer experience (CX). For example, insurance companies reduce premiums for careful drivers who have not been in an accident for three to five years. They also offer discounts to drivers who drive less than 7,000 miles a year. Such personalization increases customer loyalty and commitment to a brand.

The Internet of things for loss prevention

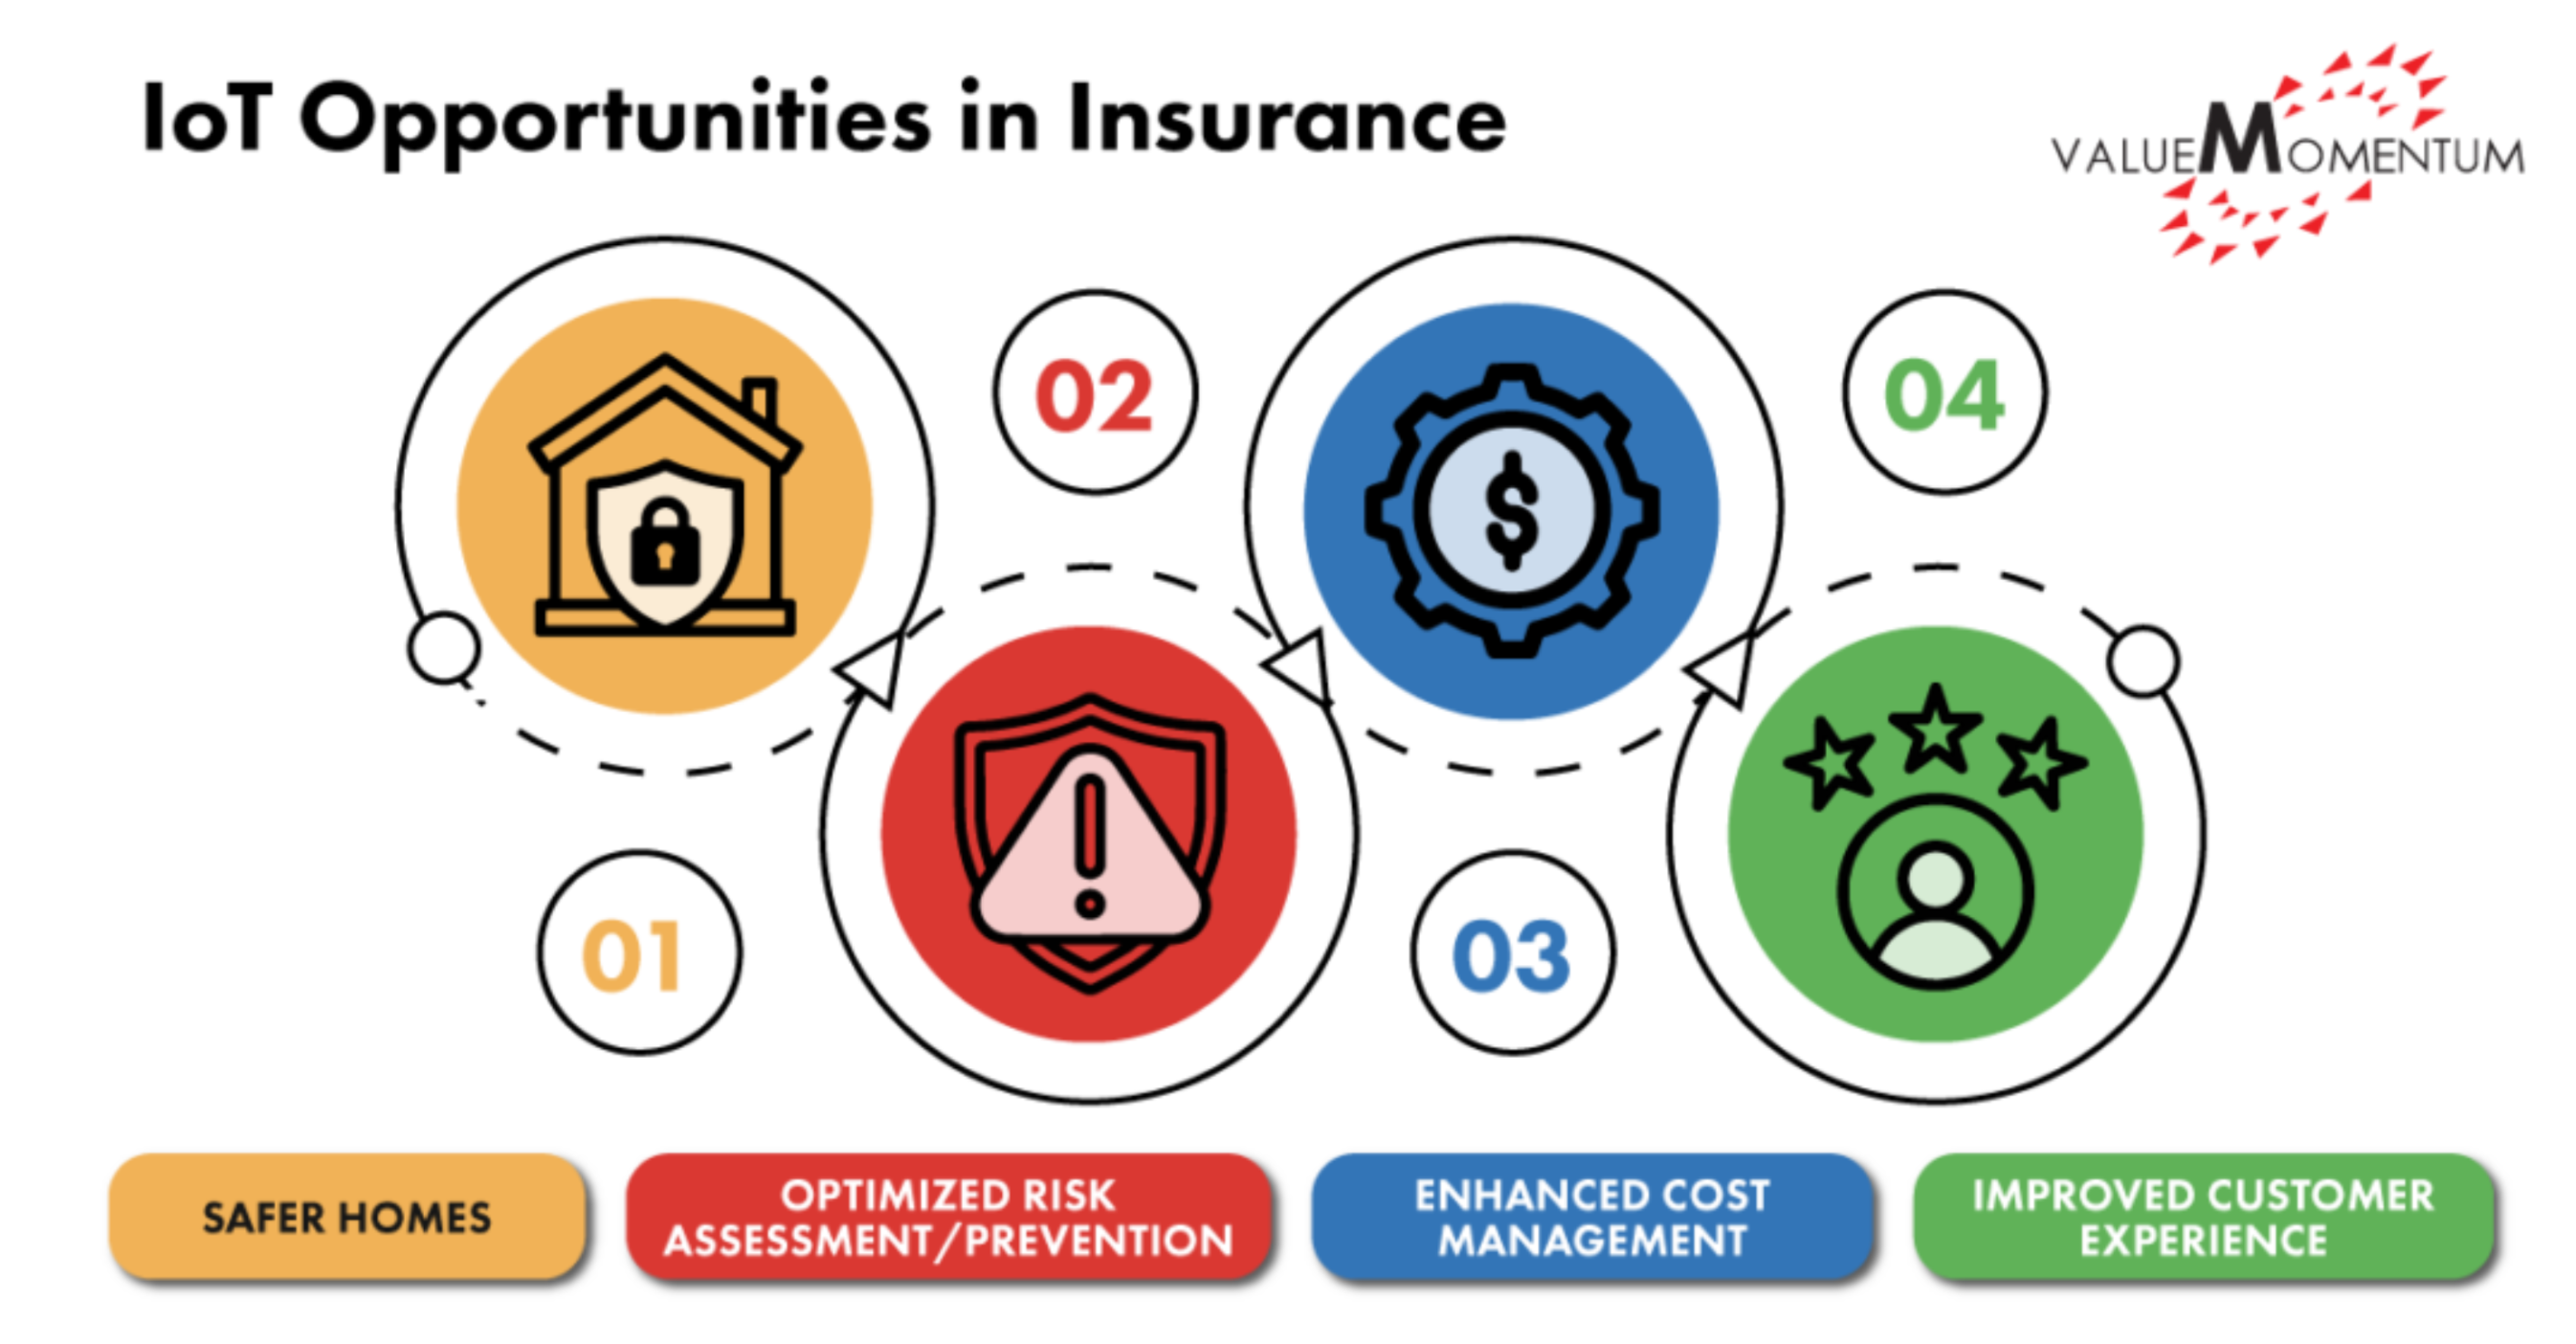
The IoT connects smart homes, smartphones, smart watches, speakers, self-driving cars and a range of other devices and generates valuable data for the insurance industry.

Long before the advent of IoT devices, insurance companies gave discounts to homeowners who had security systems installed. Now. insurers can offer profitable policies with IoT equipment. When a policyholder installs such a device at home, an organization can track any anomalies on the premises.

A connected device will notify agents if an incident occurs. Thus, an insurance company can prevent damage -- for example, from a faulty boiler in a commercial building. The insurer warns the client to take action before the appliance breaks down or explodes. The insurer protects the client and prevents large losses.

Insurers are interested in connected devices, and Allied Market Research predicts that the global insurance IoT market will grow from $8.63 billion in 2019 to more than $300 billion in 2027. Clients will be able to directly influence the cost of policies, and insurers will influence costs and profitability.

IoT Opportunities in Insurance

Chatbots for 24/7 communication with customers

Although chatbot technology is based on AI and machine learning, we have decided to put this trend in a separate category. A virtual assistant communicates with a client and accompanies them in case an insurance agent is unavailable. Servion predicts that, by 2025, 95% of all consumer interactions will be carried out through virtual assistants (by phone or chat).

A chatbot advises policyholders in a chat, and customers do not need to wait until an agent is free. The virtual assistant answers questions at any time of the day or night, on weekdays, weekends and holidays. 64% of users appreciate the round-the-clock availability of bots and are ready to communicate with them instead of a person. Operators freed from heavy workloads can deal with more complex issues or create more interesting proposals.

Chatbots can accompany clients at all stages of applying for a policy or claim. Thanks to virtual assistants, policyholders report incidents from anywhere and at any time. Applicants do not have to hold the line waiting for an agent. Instead, they turn to personal assistants that put customers in touch with the right person to process applications further.

The information about an insured event collected by a chatbot is recorded in documents. Therefore, an applicant needs to fill out fewer paper documents to file a claim. At the same time, a smart algorithm evaluates validity and legitimacy to avoid fraudulent false claims.

For example, an insurance company in Zurich implemented Zuri, a virtual assistant. As a result, the firm was able to automate 84% of customer interactions, provide instant solutions to 70% of problems and increase website visitor engagement by 10%. The use of chatbots in insurance plays a decisive role. According to NMSC, the global chatbot market in BFSI will increase from $586 million in 2019 to nearly $7 billion in 2030.

See also: Insurance Technology Trends for 2022

Drones for risk and loss assessment

Unmanned aerial vehicles are gradually being adopted not only in rescue operations and cargo delivery. They are successfully used in research operations in the insurance business. Insurance organizations are learning to use drones to assess risk before issuing a policy, calculate the number of losses after incidents and suggest preventive maintenance of insured objects.

Insurance companies already use 17% of all commercial drones, and they will deploy more aerial assistants in the coming years. UAVs are needed in insurance when adjusters cannot get to the scene of an incident due to dangerous conditions. Drones are sent there to ensure the validity of a claim and avoid delays in processing.

They enter dangerous areas, such as destroyed houses after natural disasters, to confirm the credibility of claims and assess the damage. According to Intellias, a drone can process three houses in an hour. An adjuster needs a whole day to carry out this task.

Drones assess the condition of roofs, plumbing or heating systems and send data to the cloud so that agents can use it. Experts analyze the information and assess the risks of breakdowns or damage.

In some cases, drones help conduct an entire investigation. For example, an insurance company used Dronotec devices to determine the cause of a fire on the French coastline. The fire destroyed more than 80 homes, and a client of the insurance firm was blamed for the loss. Insurance agents used drones to create a 2D map of the area. Based on meteorological data, experts determined the direction of the wind and identified the hotbed of fire. It turned out that the client was innocent. Thus, the company saved itself from paying compensation of 100 million euros. In such cases, drones are “insurance” for insurers.

Conclusion

Technology trends are transforming the insurance industry into insurtech. They enrich the digital experience of customers, reduce operating costs, improve service and take capacities to a new level. Given the competition in the insurance market, companies following these trends can become leaders.

Information technology is bringing insurance firms into untapped markets, helping to improve business models. Innovation builds the next generation's entrepreneurial culture.


Alexandr Khomich

Profile picture for user AlexandrKhomich

Alexandr Khomich

Alexandr Khomich is CEO at Andersen Lab. 

He collects and works with data in a diverse set of interests across machine learning, finance and technology. 

Next-Gen Billing Platforms for Healthcare

Instead of experiencing a blizzard of statements and notices, employees get a single, simple statement summarizing all their care, regardless of where they received it. 

person holding a binder and flipping the page

Employee benefits consultants (EBCs) and employers too often overlook the growing discontent employees feel with skyrocketing out-of-pocket (OOP) costs compounded by overly complicated healthcare billing systems. Employees are at their wits' end dealing with endless medical bills and notices that rarely add up. What is and is not covered by their plan isn’t clear. Then they are inundated with endless medical bills and notices, but they can’t discern what they owe and to whom. 

This stress and confusion can have a multiplier effect across the workforce, exacerbating employee satisfaction and retention problems. 

But innovations in healthcare billing and payment platforms offer EBCs new ways to not only simplify the employee-patient experience when dealing with healthcare bills but make it easier and more affordable for them to access the care they need. Making healthcare billing less confusing and more cost-effective can benefit all:

  • Employees become better-informed consumers who are more in control of their medical expenses and, more importantly, more engaged in their care.
  • Employers lower their plan design costs while improving the well-being of their employees and their families. 
  • Providers spend less money and use fewer resources chasing patient payments and more time on patient care.  

The systemic causes

The U.S. healthcare insurance industry has seen a significant shift in recent years as employers shift the financial burden of medical costs on to employees. This shift is due largely to employers moving more staff into high-deductible health plan (HDHP) options. Faced with skyrocketing healthcare costs, employers need to share more of the payments with employees to bring down costs and cover all. But it has resulted in growing out-of-pocket (OOP) contributions from the employees. 

Nearly one-third of American workers were enrolled in high-deductible plans last year, according to the Kaiser Family Foundation. And that trend is expected to grow. 

EBCs are helping employers temper the financial pain of high-deductible plans by designing plans with supplemental benefits and concierge services. But while welcomed by employees, these extra services can add complexity to the billing/payment experience. Employees now find themselves buried in a blizzard of Explanation of Benefits (EOBs) and "what you owe" statements. They have to wade through multiple invoices for deductibles and other payments, in addition to invoices from their health plan. 

Worse yet, higher OOP cost pressures combined with increased billing confusion are causing many employees to postpone or forgo the care they need. A recent survey from Discover Personal Loans found that more than half (52%) of Americans experiencing medical financial pressure are putting off seeing a specialist, or being seen for a sickness (41%), or undergoing treatment plans recommended by their doctor (31%). At the same time, 56% of Americans said they felt “completely lost” when it came to understanding how their health insurance worked, with nearly half (47%) confused about which services were covered or considered out-of-network, according to a Bend Financial study. Employers recognize that this is an unsustainable position – employees delaying getting needed care due to cost and confusion will ultimately lead to more expensive, emergent needs for care.  

See also: 4 Steps to Support Patient Financial Health

The fix

Despite their drawbacks, HDHPs are not going away any time soon. In fact, they can benefit employers and employees in a number of ways. For instance, they can help employees who need lower monthly premiums. HDHPs can also be combined with health savings accounts, allowing employees to make tax-free contributions to pay for their deductibles, co-pays and other medical expenses. And some experts contend that HDHPs encourage employees to become smarter, more discerning price/quality shoppers when seeking care. 

Employers, of course, benefit from lower premiums and an improved bottom line. 

The key for EBCs is to demonstrate the value of the HDHP plans by building in financial resiliency, transparency and simplicity for employees and their families. New payment platforms are creating a more patient-centric experience across the entire billing lifecycle. These platforms work by guaranteeing prompt full payments to healthcare providers in exchange for giving employees more affordable repayment plans for their OOP costs. They shift the financial relationship away from providers to specialized service providers that take the inefficiencies out of the system and streamline the payment process for all. This dynamic means that employees with HDHPs will no longer be chased by collections or face demands for pre-payment for care when finances are tight. As soon as a claim is adjudicated, providers get 100% of the in-network allowed amount. 

To simplify employee engagement, EBCs can automatically enroll all employees – even those with less-favorable credit histories – and issue credit for all allowed charges up to their OOP max, regardless of their credit standing. Or they can receive credit for OOP costs at low to no interest, while constructing a payment schedule that fits the employee’s need. 

These platforms also help eliminate the confusion surrounding billing. Instead of experiencing a blizzard of statements and notices, employees get a single, simple consolidated statement summarizing the totality of their care, regardless of where they received the care. 

Final thoughts

Today’s archaic billing processes cause enormous stress, confusion and dissatisfaction among employees, employers and providers alike. New healthcare payment financing platforms give EBCs the opportunity to optimize the value of an employer’s healthcare plan by reducing complexities and providing an affordable payment path for employees who might otherwise struggle to pay high deductibles. The result is that employees are better-informed, more in control of their medical expenses and, most importantly, more engaged to seek the care they need.


Brian Marsella

Profile picture for user BrianMarsella

Brian Marsella

Brian Marsella is President of HPS/PayMedix. He has been in the healthcare industry for 30 years and has gained significant experience across many disciplines (underwriting, client management, sales, marketing, product, consulting, network management, board leadership and community engagement). His background has allowed him to develop an extensive network and understanding of how buying decisions are made by employers, carriers, consultants and providers. His passion to enhance the way in which healthcare is evaluated, consumed and delivered is evident in the challenges he has taken on in the past and what he will be looking to impact moving forward.