Download

A (New) Interview With Alex Wittenberg

ITL's Paul Carroll interviews Alex Wittenberg, a partner at Oliver Wyman, on all the progress insurers have made in underwriting the transition to clean energy -- and on all the complexity they have to confront.

Interview with Alex Wittenberg

Alex Wittenberg

For this month's ITL FOCUS on resilience and sustainability, we turned once again to Alex Wittenberg, a partner at Oliver Wyman, with whom we spoke a year ago. He says insurers are making real progress on understanding how to underwrite the transition away from fossil fuels and to renewable energy, but there's an awful lot of complexity that goes into that assessment.

While insurers have generally maintained their commitment to facilitating a clean-energy future, they have reoriented their approach. They recognize that even the most aggressive scenarios for a net-zero future envision heavy use of oil and gas in 2050, so insurers are taking more of a long-term view. They are also taking more of a portfolio view, looking at the whole mix of clients and their energy sources and at the mix of geographies where clients operate, rather than just viewing them as a series of individual companies. 

And that's just the start of the adaptations insurers are making. Alex goes into detail below.


ITL:

We had an illuminating conversation a year ago about, among other things, the opportunities for insurers that will arise as the world shifts toward renewable energy sources but also about the difficulties of underwriting extraordinarily complex projects such as offshore wind. What are some of the big changes that have occurred since then?

Alex Wittenberg:

It’s a fairly significant development that major property/casualty insurers have departed from the NZIA [Net-Zero Insurance Alliance, whose members commit to decarbonizing their underwriting portfolios]. Last year, at this time, we were talking about how the NZIA was basically adding members every other week. Then, earlier this year, they started losing individual members, including the largest property/casualty insurers and reinsurers, such as Munich Re, Swiss Re, SCOR, Zurich and Allianz. Eventually, they lost all the founders, including the chair of the group, AXA XL.

There's a lot of speculation that the departures were driven by aggressive political tactics in the U.S. on behalf of approximately 23 state attorneys general, based on anti-competition allegations. That is not an insignificant reason, but the reality was that, as members got closer to following through on implementation, many also began to realize that perhaps they were on a pathway that wasn't aligned with their – or their insureds' – long-term view of an orderly energy transition. And for a lot of the insurers, there were practical considerations: “Are we ready to do this? Do we have the resources? Can we get the right information?”

If anything, NZIA implementation may have inadvertently created an energy transition with less financial underpinning.

If you consider the IEA [International Energy Agency] and its three different core scenarios for the energy future to 2050, whichever one you happen to believe, they all acknowledge that we are on a long journey.

To be clear, I don't think any insurers are stepping back from their individual corporate commitments. I think they're being more thoughtful about putting their commitments on a timeline that reflects the commercial reality of both the transition and of their insurance or reinsurance company.

ITL:

What does that look like? What should somebody be doing in 2024/2025 to support the longer-term energy transition?

Alex Wittenberg:

Well, there are a few things that we advocate. Increasingly, insurers are getting better at looking at their whole portfolio, as a collection of assets and not just as individual client names. If the insurer writes some oil and gas companies, utilities, pipelines, renewables – those are actually a collection of underlying assets with specific carbon attributes. Taking a portfolio view allows the insurer to consider how insuring specific organizations impacts their asset mix and to create the optimal mix of traditional and renewable sources that meets their transition pathway.

Also, insurers need to take a long-term view of their portfolio. It is more important for carriers to be going in the right direction with the right clients than it is to attempt a short-term overhaul of their book of business by applying rigid restrictions. There will be stops and starts driven by a variety of external factors that will make this a bumpy road, and each carrier will need to chart its own path to having the portfolio of clients and assets it wants in the long term.

ITL:

There’s been a backlash against ESG [environmental, social and governance efforts], especially in the U.S., not as much in Europe. I wonder whether insurance companies can go out and say they're trying to promote the energy transition and so forth, or whether they're having to back off on some of their pronouncements on the topic.

Alex Wittenberg:

I would separate supporting the energy transition from anything that's politically charged, on either the right or the left. I don't think there's a lot that's politically charged about saying you're supporting the long-term energy transition. I think many are recognizing that we're going to have a mix of fuels. Even in the most aggressive of the IEA scenarios, there will still be carbon-based fuels in the mix in 2050. So, I don't think anyone's denying that the transition is occurring, and that the transition needs to be supported. More importantly, insurers have a huge role to play in the transition.

Leaving politics aside, there's a lot of discussion about how we are going to finance the transition, but what’s often ignored is that not much gets financed that isn't insured. And the scale of this transition is significant.

It used to be that a power plant would get built in your state, and it would be insured, and the regulators didn't really think about the insurance. Now, due to the scale, exposure and complexity – such as found in offshore wind – insurance capacity is becoming increasingly scarce. It is increasingly clear that facilities of this nature are not going to be insured in the same way it would have been 10 years ago or even when the project was conceived. The insurance industry has a critical role to play in mobilizing the capital to underpin these projects so that they actually get done.

I know it sounds kind of trite, but the expression we use is, “No insurance, no finance. No finance, no project. No project, no transition.” In my 30 years of doing this, insurance isn't usually considered the linchpin of anything, but in this case it will be a key element for the energy transition to move forward at the scale required.

ITL:

I know we talked about some of this last year, but can you walk me through offshore wind? How would that work? I assume onshore wind is sort of quantifiable. We've done it. But walk me through the complexity of an offshore project.

Alex Wittenberg:

None of this has gotten particularly better since we talked last year. Large losses are occurring across a variety of renewable and traditional energy sources, and the projects are getting significantly larger and are being situated in more challenging locations.

Utility-scale renewables projects in solar, wind and storage are unique projects and are leveraging constantly evolving technology. Underwriters do not have the benefit of decades of historical exposure and loss data to evaluate future performance and price risk with precision, and understanding the engineering complexity has been a constant challenge.

The scale of these projects is also difficult to understand. You're talking about something that is huge. In offshore wind, if you consider the GE Haliade-X wind turbine, the mast height can be up to 260 meters (the Eiffel Tower is 300 meters), and an individual blade is 100 meters long, making a 220-meter rotor. A single turbine can generate up to 14MW of power. And a single wind farm may have upwards of 200 of these turbines. (Note that the largest approved U.S. offshore wind project is Ocean 1, with 98 turbines planned; Dogger Bank in the U.K. has 270).

Complicating the obvious potential are offshore losses, which can be costly and difficult to resolve. While there is a clear physical damage component to losses, business interruption costs can be more significant and less predictable, often exacerbated by a lack of available vessels to make repairs. The supply chain implications for replacement parts, such as turbines, transformers or cables, and potential obsolescence issues, also impact loss quantums and are dependent on backlog at the manufacturers of critical equipment. And the longer the interruption, the more cost the insurers incur, as the operator continues to have an obligation to provide power.

ITL:

If I'm trying to find financing for offshore wind, to stick with that example, and I have to get the insurance, how do I work through this with an insurance company?

Alex Wittenberg:

The public utilities commission (PUC) in a jurisdiction usually has authority over new projects, and they're used to seeing insurance included, usually a fairly significant amount. Due to the reasons we've discussed, the companies deploying these projects are going to have to resort to different risk finance structures. They're going to involve larger retentions, likely through increased participation from corporate captives; they’re likely to involve a smaller commercial insurance market participation excess of a much larger retention and with significant sub-limits for natural catastrophe perils. And they may involve catastrophe bonds (CAT) bonds or parametric products if the projects are CAT-exposed.

The problem is that your typical PUC is not populated with insurance experts who are going to fully understand these types of complex structures. They are going to want to see traditional insurance with reasonable retentions, because from their standpoint that is how you best insulate the rate base.

But that's not realistic.

There's a huge educational component, because the ways that a project may have to resort to transferring risk aren't necessarily bad, they're just different. A project will effectively transfer the risk or diffuse the risk into different pools of capital via an insurance company or a series of insurance companies. That educational piece is something that isn't easy to do but needs to be done.

ITL:

It sounds like a massive project for the insurers, too, to get smart about these complex projects.

Alex Wittenberg:

Many insurers we work with on the energy transition will readily admit that they need more technical advice and technical support. But there is a definite scarcity of quality resources, so they can’t all acquire the resources that they need. A lot of the strong technical people, especially in renewables and alternative fuels, are not going to be working for an insurance company; rather, they will be on the front lines of renewables and fuel development.

There is a larger pool of engineers who join insurance carriers after a long career elsewhere. In the nuclear space, perhaps they come out of the U.S. Navy, and they join an insurer as an engineer in one of the nuclear pools. But in renewables, it's not quite the same. There's not a backlog of folks who have been doing this for decades and are looking for a transition.

The second issue is converting technical knowledge into underwriting advice. It's one thing to say, "Well, we understand failure rates, and we understand the failure rates under different meteorological circumstances.” But now you need to turn that knowledge into a price. So insurers need to get a lot better about understanding and pricing the risks, and they need to do it without running egregious loss ratios as they learn. And those that have experienced losses or underpriced the risks often curtail their appetite or retreat altogether. It's a challenge.

Are there ways out of these challenges? Absolutely. Over time, the markets are likely to settle out, and probably in a different place than they are today. I think some of the carriers are going to say, "OK, we're going to write this, but we're not going to write it the way that we used to write everything else in our energy portfolio. We’re going to want to define our appetite for certain technologies, we're going to want to increase deductibles and we're going to sublimit specific perils and be more precise about geographic concentration."

Over time, both individual carriers and the overall market are going to better understand the underlying drivers of profitability and provide a much more stable, albeit potentially smaller, source of capacity. I think they are already getting there.

Another complicating factor, beyond underwriting and technical concerns, is that the carrier management teams are still wrestling with reconciling the commercial reality of the long-term transition in their energy books and their public climate commitments. These internal contradictions are difficult to resolve in the short term and lead to insurer underwriting decisions that can seem inconsistent to both brokers and insureds.

ITL:

We had a conversation last year about many of these topics, and we are having one again this year. Let’s say we have one next year. Are we making progress?

Alex Wittenberg:

Most insurers, when they left the NZIA, recognized that they were going to have to take a lot more responsibility to support the energy transition and couldn’t just rely on third-party scoring of the names in their portfolio. They were going to really need to understand the underlying data and underlying assets in their portfolios and how they wanted to manage their portfolio and its transition over the long term.

Many companies are certainly undertaking the necessary work, and that’s progress. However, this isn't going to be something that can be easily fixed in a couple years. This isn’t just about setting guidelines for an internal referral network that will say "yes" or "no" to offering coverage; there needs to be a sincere effort to understand what is in the portfolio, the planned changes in the insured’s asset mixes and the targeting of new clients. Insurers are starting to understand the implications of their commitments and how to align those with the transition of the energy book. That's all positive.

The other real positive is the long-term approach. There are a lot of ways to look at the energy transition. Some insurers are more conservative and will stick with a portfolio that has more traditional energy within it and migrate over time. Some will want to move faster to new sources. The marketplace needs an assortment of carrier approaches to ensure an orderly transition, and while it will not be smooth it seems to be moving in the right direction.

Insurers are trying to solve problems, too. The industry is moving forward; the market is not sitting still. A lot of large insurers are making themselves available to support the energy transition by supporting traditional energy assets in portfolios, while insureds work to address real world challenges such as providing affordable, reliable baseload power.

ITL:

The New York Times had a piece recently saying that new, renewable energy sources are coming online faster than people thought, but I worry a lot about the grid. It just can’t do what we need it to do. It seems to me that we almost need to start over and declare that we're going to build an interstate highway system of the grid.

Alex Wittenberg:

A big challenge is that many new renewable generation facilities aren’t near an interconnection point with the existing grid. Also, the public doesn’t necessarily want utility scale generation nearby. New transmission and distribution and other grid infrastructure must be considered a priority if the energy transition is to occur at scale.

Unfortunately, insurers don’t usually want to insure operating, above-ground transmission and distribution lines. Construction of the grid would be fine from an insurer's perspective. It’s when you turn it on and make it susceptible to a variety of perils that it becomes less attractive.

ITL:

That makes sense. I found this fascinating. Anything I didn't touch on that you want to talk about from a personal or an Oliver Wyman perspective?

Alex Wittenberg:

There's one thing that I think insureds could do better and could think about more strategically. Energy is a global industry, right? Everyone generates power, needs power, transportation fuels, etc. But in the U.S., an individual utility tends to be organized by state, or maybe in their region of the country. The same occurs in Canada.

The insurance industry is different, it is a very globally fluid capital market. And although insurers are based in certain places and get regulated by individual states or countries, the capital tends to flow to where it can generate the best returns. That means the insureds need to think about the implications of their strategies on their ability to attract insurance capital in a globally competitive marketplace.

It's also important that the insurer looks at their energy portfolio across all of their geographies, so they can make equitable decisions on where to accelerate the move to renewables as an offset to a slower pace in another part of the world.

I’ll add that I'm still very positive directionally, actually more positive than I was last year. Last year felt a little dire, as though the insurance industry was basically going to abandon the ship, and there were not going to be sufficient options to address the projects that are required to accelerate the transition. While working with a number of the large commercial insurers and energy specialist markets, we have found that they are committed to thinking strategically about solving for the energy transition challenges, even if it means charting a new path.

ITL:

This was great. Thank you for your time, Alex.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Creating an Automation Strategy and Roadmap

How insurers prioritize automation projects, aligning with their existing automation landscape.

OZ Digital Consulting banner

We often hear insurance professionals say, “I know I need to begin to automate my business and operations, but where do I start? With a policy admin system? If so, which one? Or should I focus on automating underwriting and rating capabilities?”

In this webinar with the National Association of Mutual Insurance Companies (NAMIC), Murray Izenwasser, Senior Vice President of Digital Strategy for OZ Digital Consulting, elaborates on the essentials of an effective automation strategy — and why it matters in insurance.

Tune in to get insights as he delves into the automation maturity model and roadmap and how this helps insurers prioritize automation projects, aligning with their existing automation landscape.


SPEAKER

Murray Izenwasser

Murray Izenwasser
Senior Vice President, Digital Strategy
OZ Digital Consulting


Contact us if you would like to learn more about how the right automation strategy can drive digital transformation.


ITL Partner: OZ Digital Consulting

Profile picture for user OZDigitalConsultingPartner

ITL Partner: OZ Digital Consulting

OZ is a global digital technology consultancy and software delivery and development partner founded to enable business acceleration by leveraging modern technologies I.e., Artificial Intelligence, Machine Learning, Data Analytics, Business Intelligence, Micro Services, Cloud, RPA & Intelligent Automation, Web 2.0/3.0, Azure, AWS, and many more.   

Our certified consultants bring a diverse array of backgrounds and skill sets to the table, leveraging the latest outcome-driven technologies and methodologies to address the unique, constantly evolving challenges modern businesses face. We accomplish this by supporting the digital innovation goals of our clients, keeping them ahead of the competition, optimizing profitable growth, and strategically aligning business outcomes with the technologies that drive them – all underpinned by decades of mission-critical experience and a shared culture of continuous modernization. OZ will work side by side with you to fully leverage our relationships with the world’s leading technology companies so you can reap the benefits of best-in-class implementation, integration, and automation—making the most of your technology investments and powering next-gen innovation.

How AI technologies Are Turbocharging Insurance Distribution

The evolving role of CRM systems, cloud-based tools, and the transformative impact of AI and ML will have a profound impact on insurance sales strategies and operations.

insurance customer

By Venkat Malladi, Co-founder and CTO, Vymo Technologies

Before we leap into the future, let’s go back to the basics. The seven parts of a sales lifecycle are prospecting, making contact, lead qualification, lead nurturing, proposal, discussions and negotiations, and lastly conversion. Sellers go through this journey with every lead and we all know how rocky and challenging the actual cycle is.

CRMs were introduced to accelerate the sales lifecycle and help the seller. And help sellers with a centralized data repository, better lead management, streamlined processes, structured activity and task management, reporting and to an extent analytics. Although the CRM is ubiquitous to a sales hierarchy today -- we know that it is largely disliked by sellers and hardly used.

The quest now is to increase CRM adoption among sellers. Making the tool intuitive and easy to use, mobile-first and a single interface vis-a-vis the multitude of systems sellers need to access are top of mind challenges that sales teams are looking to solve to make this happen.

Here is where cloud-based sales engagement tools and platforms are raising adoption numbers. These tools provide an app-based, unified experience, remove the need to toggle between systems, retrieve data from CRMs and give it to sales teams as nugget-based insights, and capture activities easily allowing them to close their daily targets faster,  and  improving their daily productivity. 

So far. So good.

Can sales performance be boosted further? What can sellers look forward to in the coming decade? Tools that can navigate a seller from prospecting to conversion via a least resistance path with intelligent interventions? Playbooks that can pinpoint sellers to best actions that steer towards conversion? Technology that can understand a lead status and tell the salesperson exactly what to do based on another seller’s recent experience?

The need for such intuitive technology coupled with Generative AI is just the turning point sales teams need towards the future.

Here are four ways AI tools can help sales transform the way they work in the coming decade.

  1. Sharp Solution Building - It is almost like you can read the customer’s mind! Beyond relying on historical data that an organization has, generative AI can help analyze real-time customer conversations and enrich existing customer information. Such thriving data thanks to AI and ML can help sales teams design products and solutions that are bespoke and personalized. Not only this, with such deep customer insights, AI opens up the potential of cross-sell and upsell opportunities helping sales teams do a lot more with the data on hand.
  2. Heightened efficiency of day to day working - Imagine a Donna Paulson (of Suits) to help your sellers through the day! With effective use of AI, tools can track activities, help with daily planning, take notes and remind sellers on their meetings, a quick update before a meeting, the best solution to pitch based on customer profile and explain the next best steps.
  3. Transformative Training and Onboarding - Sales training is a high priority across industries. For example, in the Insurance industry, attrition is a significant problem. 89% of agents quit within the first three years of joining. And coupled with this is the retirement of baby boomers - seasoned agents who have a wealth of knowledge. So the insurance agency is looking hard at two things:
    1. How do I train new recruits faster so they start selling as soon as possible?
    2. How do I retain the rich knowledge that a tenured agent has, to pass on to the new recruits, younger workforce?

    AI can prove to be quite a lever here. It is possible to analyze seller behavior and performance across thousands of salespeople to understand best behavior and practices. This becomes a rich source of learning and can be built into effective training programs for sales, empowering them to get on the ground faster. And intervene with tailored lessons as they need support on the ground. Likewise, AI can encapsulate best behaviors of senior sellers and guide the newer teams to mirror this behavior.

  1. Better Sales Leadership: Rich, real-time information on sales team performance, and customer profiles can help leaders get both wider and deeper visibility into engagement and gaps. It is almost like gazing into a crystal ball. But this is no magic - it is technology. Such clarity can help leaders rework on strategy, intervene and coach as appropriate and ensure that both seller and customer engagement is optimum.

It is a great time to start exploring AI and ML in sales technology. As customer profiles evolve, sellers should up their game by understanding customers better than ever. AI provides the means.


ITL Partner: Vymo

Profile picture for user VymoPartner

ITL Partner: Vymo

Vymo is an intelligence-driven Sales Engagement Platform built exclusively for insurance and financial services sellers and field managers. Enterprises large and small can drive higher sales productivity, build deeper client engagement, and address client needs with bottom-up insights and collaboration. 

65+ global enterprises such as Berkshire Hathaway, BNP Paribas, AIA, Generali, and Sunlife Financial have deployed the platform to deliver actionable, objective insights to its executive and their teams. Vymo has a proven revenue impact of 3-10% by improving key sales productivity metrics, such as conversion percentage, turnaround time, and sales activities per opportunity. 

Gartner recognizes Vymo as a Representative Vendor in the Sales Engagement Market Guide and by Forrester in the 2022 Wave report on sales engagement platforms.

Reinsurers Are Pulling Back

CAT events, combined with other economic factors, are making reinsurance either impossible or difficult to secure.

Dark grey image with trees that look black and with a big flames and smoke emerging

KEY TAKEAWAY:

--When contemplating reinsurance, consider the following best practices: 

  • Stay profitable by managing your risk profile.
  • Keep an eye on the profitability of your reinsurers. 
  • Build a stable of reinsurance contacts and get to know them personally.
  • Don’t shop only on price. Think long term.
  • If you’ve had a series of CAT losses, prepare discussion points and arguments against rate or retention changes--why those losses are blips rather than the beginning of trends. 
  • Work your reinsurance program throughout the year, not just at renewal. 

----------

The unprecedented wildfire in Hawaii and the tragic devastation it has left in its wake is the latest catastrophe to wreak havoc and devastation within our communities, and by extension on the insurance industry. Insured losses related to the natural catastrophe that has killed more than 100 people to date and burned roughly 2,200 acres and 3,500 buildings is projected to be the second largest insured loss ever recorded in Hawaii. The insurance industry will respond as it also does -- quickly and efficiently and, in the process, return to insureds billions in loss payments to help them recover and rebuild. Unfortunately, CAT events like this, including hurricanes, wildfires and floods, are hitting our communities and the insurance industry hard. Combined with other economic factors, they are making reinsurance either impossible or difficult to secure.

So, what’s in store for reinsurance, and what does it mean for carriers looking to place risk? Taking a good look at what’s causing prices to rise and how capacity has been affected can help to shed some light on the issue. A deeper understanding of what’s causing this market tightening also uncovers steps carriers can take to ensure they remain attractive to reinsurers, keep costs down and sustain capacity. 

The Origins of Today’s Hard Market

Last year, Hurricane Ian crumpled Florida with $60 billion in insured losses. But it’s been years of costly CATs in the form of hurricanes, wildfires and floods that have contributed to challenges in today’s insurance marketplace. P&C carriers were paying out enormous losses and passing them off to the reinsurance marketplace. At the same time, economic influences such as inflation and rising interest rates are exacerbating the situation. As a result, carriers and reinsurers are taking a step back, with some exiting the market entirely. 

It’s not just the economic climate and recent onslaught of CATs that are driving insurers and reinsurers away, causing them to boost rates or rethink terms and conditions. For example, the retrocession market has become a virtual ghost town. Investors have largely left this market, which allows for yet another layer of risk transfer, and are seeking better returns on their investments from the fixed income and equities markets. While we are seeing some potential changes in this market, they should not yet be considered a trend.

As the economic climate has changed, so, too, have agency and policyholder attitudes toward insurance to value. While policyholders, and agents to some degree, were once complacent when it came to making sure properties were adequately insured to value, CATs and rising inflation are leading policyholders to request and insurers to demand an increase in the value of their property on their policies. Agents have also come to the realization that they could be found negligent under an errors and omissions exposure if they failed to bring their client’s attention to rising rebuilding costs. In the past, insurance companies were underpricing business and relying on reinsurers to share in the risk. That’s no longer the case. 

See also: How Cedents Can Win Reinsurance Race

The View From the Carrier

From our perspective at Pennsylvania Lumbermens Mutual Insurance (PLM), a carrier in the wood niche, the reinsurance market was fairly solid in the spring of 2022, but change was rumored to be on the horizon. Capacity issues were brewing, compounded by major losses. By late summer or early fall, reinsurers were signaling they were having problems in terms of profitability, and we knew the coming renewal season on the property side would be challenging.

In late 2022, we started to feel the impact. Quotes from many of our reinsurance partners were coming in unprofessionally late. We also saw changes to our terms and conditions coming in at the last minute. It was a very different and chaotic reinsurance marketplace. Prices surged dramatically, and reinsurance partners we had worked with in the past would no longer provide the retentions we historically had in place. They were no longer interested in assuming the same levels of risk. While we expected pricing and capacity to be a problem, we did not foresee the quotes coming in late or last-minute changes to terms and conditions. For us, this was problematic, as we send our renewal quotes out 30 to 45 days prior to expiration in many cases to comply with different state regulations. Because the reinsurers had delivered terms and conditions late, we did not have the information necessary to really understand the cost structure on our end before that 30 to 45 days. 

Fortunately, as a mutual insurer, PLM does not have to make short-term decisions. We do not have to report our quarterly results to Wall Street. We can take a longer-term perspective, and we know our niche. As a specialty insurer, we are good at what we do, and we can demonstrate that. While reinsurers might traditionally run away from a high-severity business like ours, for those looking to back front-line underwriters, we’re an attractive partner. 

Finding Value in a Year-Round Strategy

In a tumultuous market like this, it’s critical not to take your foot off the gas. We work on our reinsurance program throughout the year. We visit our existing reinsurers here in the U.S., and in England and Germany, sharing our results and talking about what is going on in the marketplace.

At the same time, we work to identify new reinsurers. We are always talking to reinsurers, trying to interest them in taking a “watch line,” where they would take maybe 1% of our property program or property CAT program just to get a feel for what it looks like and how we do things at PLM. 

Thinking ahead is critical for us. Those insurers that fail to plan ahead and come to their reinsurance renewal unprepared may see their rate is up 20% or more. They must make up for that increase with their own rate increase. Homeowners insurers, for example, have to seek approval from their state insurance department, and that can take time, in some cases a considerable amount of time. We have seen some resistance from certain states in the approval process. As a result, some of these states are seeing carriers constricting their willingness to write new business or ceasing to write new business entirely.

Smaller insurers that fail to plan ahead may have to take on reductions in retention ratios, and that can become difficult to handle. Small mutual and small stock companies rely on reinsurers, and they need to stay on top of their relationships or they could come up short. I’ve talked to others who have said there is no way they can be profitable as a company this year or next year because of the cost of their reinsurance. We at PLM do not feel that way; we are committed to finding a path to profitability without assuming inappropriate increases in risk.

See also: A Breakthrough in Wildfire Safety

Looking Ahead

While I might like to say the reinsurance market is turning a corner, we are only partially through the 2023 hurricane season, and no one can pretend to know if reinsurance pricing will remain high or even spike again. Smart insurers will be prepared. 

One of the best ways to prime for another challenging renewal season is to put yourself in the shoes of the reinsurer. They’ll want to see that your company is profitable and not only that you made a good return but that you protected your reinsurers at the same time. You’ll want to convince them that you are in this for the benefit of both companies. 

At a high level, when contemplating reinsurance, consider the following best practices: 

  • Stay profitable by managing your risk profile.
  • Keep an eye on the profitability of your reinsurers. 
  • Build a stable of reinsurance contacts and get to know them personally.
  • Don’t shop only on price. Think long term.
  • If you’ve had a series of CAT losses, prepare discussion points and arguments against rate or retention changes--why those losses are blips rather than the beginning of trends. 
  • Work your reinsurance program throughout the year, not just at renewal. 

Some industry experts I’ve spoken to feel that today’s reinsurance issues are a one-time blip. I don’t think that’s the case. Regardless, carriers need to think about how they will approach their reinsurance partners and what those reinsurers will want to see from them, as well as the types of rate increases and terms and conditions they are willing to accept. 

Reinsurance is a necessary component of what we do. Let’s understand how we can best work together to move our industry, as well as those we protect, forward.


John Smith

Profile picture for user JohnSmith

John Smith

John Smith is president and chief executive officer at Pennsylvania Lumbermens Mutual Insurance (PLM).

With more than 40 years in the insurance industry, he has been a part of PLM since 1998.

Cybersecurity Standards for Insureds Are a Must

We need a set of universal, standardized cybersecurity requirements for insured organizations, adopted across the cyber insurance market.

Orange and yellow cyber transparent code overlayed against a blue IT room

KEY TAKEAWAYS:

--The standards, while they couldn't provide total protection, by any means, could greatly reduce policyholders' risks of cyber attacks.

--The standards need to be imposed on an industrywide basis because any insurer that imposed the standards on its own would risk losing business to less strict competitors.

--There would also need to be provisions for checking, in a scalable way, to make sure that insureds are following basic cyber hygiene.

----------

While all types of insurance present a host of variables only partially enumerable in actuarial calculations, cyber insurance presents many unique, abstract challenges. It is almost impossible to accurately predict the connectedness of systems: whether the attack frequency will rise or fall, which verticals will be most targeted by hackers and, without deep security audits, which specific organizations are adhering to rigorous cybersecurity practices.

For example, while the rates of serious global cyberattacks including ransomware have been increasing (overall) for many years, 2022 saw a decline in overall ransomware attacks. For some experts, this may have been predictable: War efforts will often divert hacker attention away from financially motivated attacks to those that support patriotic and militaristic motives (and a drop in the crypto market also reduced the profitability of attacks). But this threat reduction caught many by surprise. Regardless of reason, the result on the cyber insurance market was tangible: Reduced claim frequency and severity increased margins and lowered the perceived risk exposure in the short term, and higher margins and lower risk exposure (combined with new entrants to the market) started to softened terms and conditions once again. 

As some cyber insurers have vied for premium dollars, many of the recently introduced controls used to reduce underlying risk, including requiring minimum cybersecurity controls of their insureds, have fallen by the wayside. When we no longer have a means of controlling risk—such as requiring risk management controls—expanding capacity is no longer tethered to real-world data, making it far less attractive to carriers. This uncertainty has been underscored by the incoming data of 2023, which has shown that ransomware (as only one attack modality), is once again surging despite little else changing in the overall geopolitical environment, demonstrating yet again the importance of gaining risk visibility wherever possible.

What is needed, we argue, is a set of universal, standardized cybersecurity requirements for insured organizations, adopted across the cyber insurance market. By requiring insureds to meet basic, essential cybersecurity controls, we can, to some degree, mitigate the risks and make them more predictable.

Many cyber insurers would like to impose standards to reduce risk; but doing so on their own can hurt them while more risk-tolerant competitors are willing to waive limiting terms and conditions to attract insureds. This endless cycle, however, is contributing to a lower overall standard of cyber rigor in organizations and higher risk for the insurance industry. It is impractical to expect more than a few bold insurers to take a stand on this issue; thus, we believe that reinsurers are in a better position to leverage their influence toward this goal. This would be comparable to the type of collaborative action we saw in the industry when striving for a more unified war exclusion. By requiring insurers to require a universal set of minimum security standards, reinsurers could not only capture more certainty around loss performance and exposure, they could also level the playing field for cyber insurers, making minimum standards a norm vs. a competitive differentiator they wield to the detriment of risk predictability. The result would be improving enterprise cybersecurity stature and reducing risk for the insurance industry overall, setting the stage for further sustainable growth. 

For example, today, business interruption represents nearly 60% of cyber-related losses; the best way to reduce these losses is to ensure organizations are strategically securing their infrastructures as a condition of their cyber insurance policies. 

See also: Cybersecurity Trends in 2023

What Kinds of Cyber Standards Should Be Required?

As cybersecurity experts, we understand that no set of controls guarantees companies won’t be breached. However, there are basic hygiene controls that no organization should be without. We argue that the insurance industry should work together to not only define a minimum set of cybersecurity standards, but also bring in cybersecurity experts to determine how those controls should be deployed and checked in a scalable way to ensure they are effective. Some controls that should be considered include:

  • Multi-factor authentication (MFA) deployed universally, wherever it is supported
  • Endpoint detection and response (EDR) tools coupled with next-generation anti-virus software
  • Segregated, redundant and immutable backups
  • Patching and vulnerability management processes for critical updates
  • Security awareness training for employees
  • Privileged access management

Yet, it isn’t enough to merely require that organizations check the box on these items. It’s essential that details be clearly spelled out regarding how they are implemented. For example, backups are not effective if their security features are not properly configured, if they are included as a member of the active directory domain or if they are not immutable (if they can be deleted or moved outside of the very rigorous, two-key-turn and retention policies set by the company and system). We suggest that reinsurers create a panel of experts to consider which controls be mandated and the specific details of how these controls should be executed to ensure they are effective for both organizational health and for mitigating risk. 

Risk Is a Fact in Security and Insurance—But There’s More We Can Do

In cybersecurity, we live with the reality that breaches can happen even to the most cyber-dedicated organization. That doesn’t make their security efforts futile—without these safeguards, organizations would be open to virtually daily intrusions. While we must live with risk uncertainty in cyber insurance, setting universal, minimum cybersecurity standards for organizations would provide far greater risk reduction and visibility.


Marko Polunic

Profile picture for user MarkoPolunic

Marko Polunic

Marko Polunic is Fenix24's managing director based in Munich.

He leads efforts to expand Fenix24's offering into the E.U. and globally by fostering relationships with ecosystem partners-such as digital forensics and incident response (DFIR) firms, law firms, insurance brokers and cyber insurance carriers.

Polunic has a deep history (10-plus years) in the insurance and incident response industry, having led the cyber and IoT practice for the largest cyber reinsurer, Munich Re. Following his time at Munich Re, Polunic became CrowdStrike's director of business development for the EMEA region.

Polunic holds a diploma degree in quantitative business administration from the University of Tübingen, Germany.

Learning From Failure

Learning from failure is hard for business leaders, but it is essential for success. So, go forth and fail fabulously!

A man in a suit holding a briefcase and an umbrella standing in the ocean under a cloudy sky

Every successful entrepreneur or CEO has dealt with failure at some point. It took Thomas Edison 10,000 attempts to perfect the light bulb, 36 publishers rejected Arianna Huffington and Milton Hershey had three candy-related ventures fail before he founded Hershey's.

Whether you're running a small startup or a Fortune 500 corporation, shifting your thinking to learn from failure is one of the hardest lessons for most business leaders but also one of the most essential for future success.

As Franklin D. Roosevelt once said, "A smooth sea never made a skilled sailor."

Learning from failure is a crucial skill that can lead to personal growth, resilience and improved decision-making. Here's some advice for someone who wants to learn from failure:

  1. Shift Your Perspective: View failure as a learning opportunity rather than a defeat. If perfection is the standard, you're creating an unhealthy work environment where fear of failure will hamper you and your employees' ability to be creative and find innovative solutions. Instead, embrace a growth mindset, understanding that failures are stepping stones toward improvement and success.
  2. Avoid Attributing Blame: When facing failure, avoid blaming yourself or others. Instead, objectively analyze the situation to understand what went wrong and why. Go beyond surface-level reasons for failure. Dig deep, conduct a postmortem to uncover the underlying factors contributing to the outcome and examine your assumptions, strategies, communication and execution. Look at failure as a chance to identify factors you can control and improve to mitigate the same mistakes from happening again.
  3. Feedback: Although it might be challenging, embracing honest feedback about your and your company's failures can provide valuable sources of information and learning opportunities you might have yet to notice on your own. This can help you assess your progress, challenge your biases, improve your products and services and learn things. In fact, a global survey by the Economist Intelligence Unit found that what set top-performing companies apart was the use of feedback loops, stating that effective feedback brings speed to delivering strategy.
  4. Document Lessons: Successful business leaders and businesses perform trials and embrace errors. You can only get better at something by practicing and learning from your mistakes. So, write down what you've learned from the failure. Create a document or journal where you record the details of the defeat, the analysis and the lessons you've gained. This helps solidify your insights and prevents repeating the same mistakes.
  5. Adapt and Pivot: Accept that failures will happen in business and adapt your approach to the lessons learned from loss. Adjusting your approach when a failure occurs is critical to fostering long-term resiliency for your business. Apply the insights gained from failures to pivot and refine your strategies, adjust your goals and develop new approaches to make better decisions moving forward.
  6. Celebrate: Acknowledge your progress, even if it's small. Every step toward improvement counts, and recognizing your efforts can boost your motivation to keep learning. Taking pride in your achievements allows you to pinpoint precisely what you've successfully done so that you can repeat it in the future. So, the next time you successfully handle a challenging situation or a task that you've struggled with, take the time to acknowledge and celebrate your accomplishments with your peers. It'll encourage them to do the same.
  7. Set Realistic Expectations: When setting expectations, specificy your businesses and personal goals. Then, break down the most significant goals into more manageable expectations and understand that setbacks don't define your worth or abilities. For example, let's say you want your company's EBITA to increase by 10% by the end of the year. In that case, focus on a 2.5% EBITA increase per quarter and continuously reevaluate your expectations to ensure you have the staff, time and financial capabilities to realistically achieve your goals.
  8. Practice Iteration: Approach your goals with an iterative mindset of continuous learning, progression, feedback and improvement. As you implement changes based on what you've learned from experiences, constantly monitor your progress, assess outcomes and refine your strategies as needed. For instance, if you're releasing an insurtech product, you'll need to continuously experiment with it, get feedback about its weaknesses and keep tabs on disruptive industry trends so you can make adjustments and deliver a game-changing product.
  9. Stay Persistent: Failure is inevitable. In fact, 90% of startups fail. It's not a question of if you'll fail but rather when. Failure can be discouraging, but remember that success often involves persistence. Use your newfound knowledge to keep moving forward, even in the face of challenges.

See also: NFIP's Failure Fuels New Risks

Even Amazon CEO Jeff Bezos says that his company's growth and innovation are built on its failures: "If you're going to take bold bets, they're going to be experiments. And if they're experiments, you don't know ahead of time if they're going to work. Experiments are, by their very nature, prone to failure. But a few big successes compensate for dozens and dozens of things that didn't work."

Don't be afraid to share your failure stories with others. Sharing your experiences can help others learn from your mistakes and create a supportive community that values growth and learning. Be patient with yourself and focus on the journey of continuous improvement rather than perfection. Learning from failure doesn't mean dwelling on the negatives. It's about finding humor and growth in the most unexpected places.

So, go forth, fail fabulously, and remember the best view comes after the hardest climb!

Driving Growth Via Embedded Insurance

What if we could influence the way that consumers perceived the value of risk mitigation and insurance for a personal asset?

Two people at a car dealership in front of a car and talking to each other

Few people wake up in the morning excited to purchase an insurance product. At best, insurance is considered a "push" rather than a "pull" product. Often, it's a requirement based on legislation or contractual conditions. Rational buyers aim for the best possible deal (based on lowest price and perhaps coverage considerations) -- but what if we could influence the way that consumers perceived the value of risk mitigation and insurance in relation to a personalized asset?

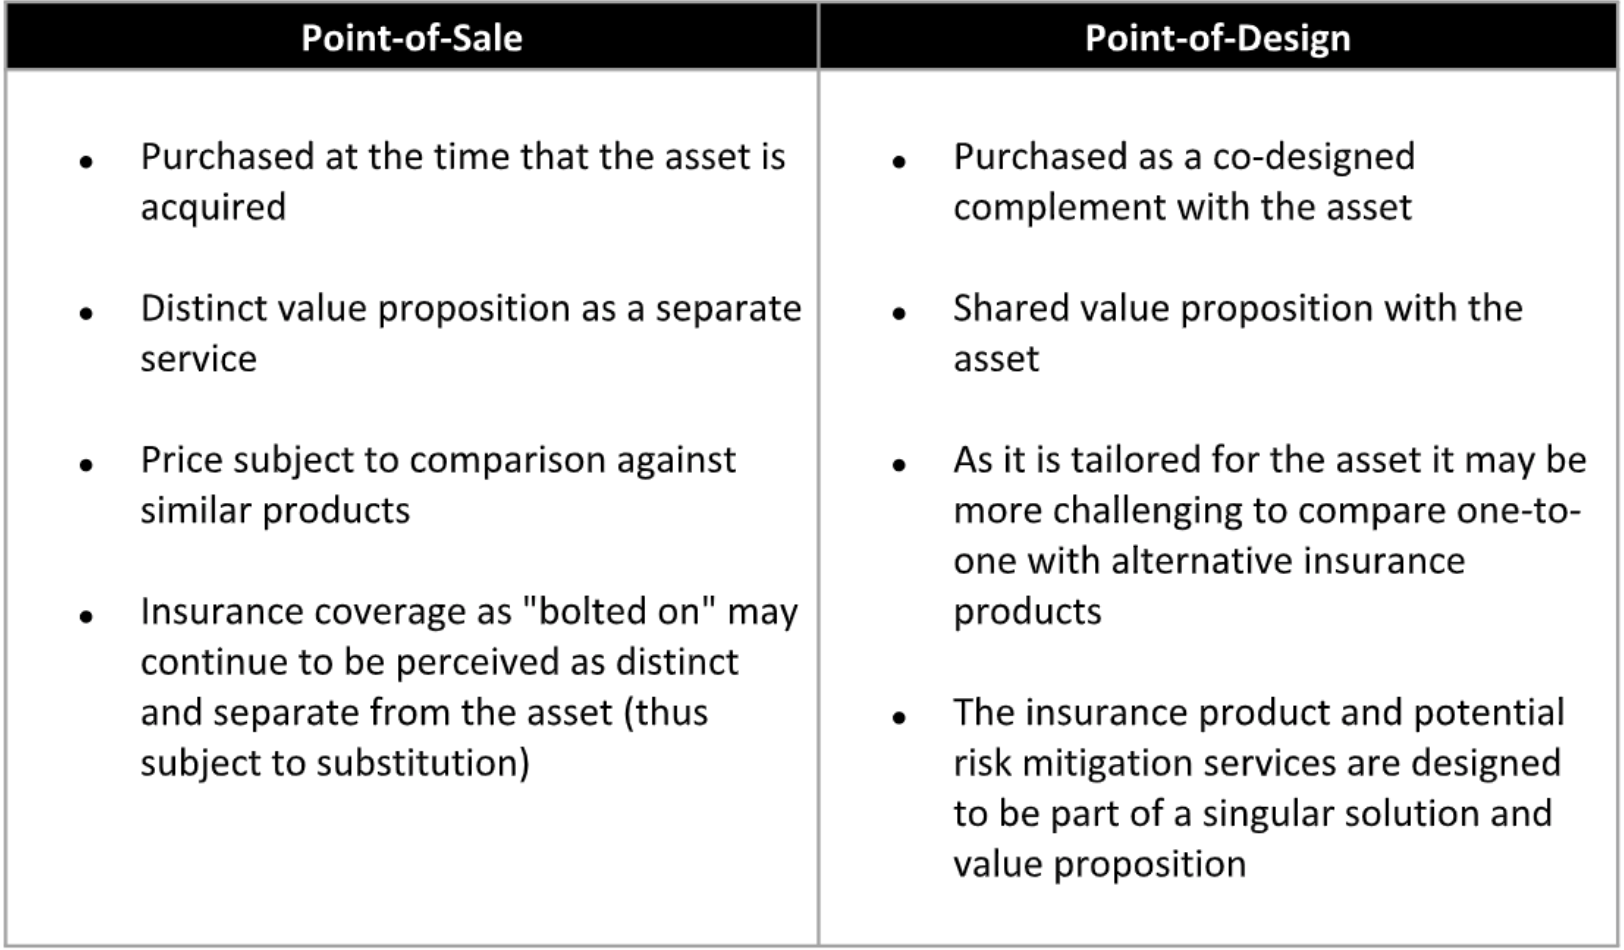
Embedded insurance at the point-of-design may be a way to address this challenge and thereby support insurance sales and distribution.

Embedded insurance at the point-of-design involves creating assets that incorporate insurance products as natural complements with a shared value proposition. This process involves re-imagining the role of risk mitigation and insurance coverage as both a means of protecting the value of the asset and a source of resilience.

Embedded insurance at point-of-sale, by contrast, is an add-on product that is discrete from the asset and, as such, is an arbitrary complement.

Embedded Insurance at Point-of-Design as Part of a Distribution Strategy

What if the structure of point-of-design embedded insurance supported insurance distribution growth by wrapping a "push" product within a "pull" product? 

We can visualize this concept as a set of layers: 

  1. The first layer is the asset. Perhaps the asset may be personalized by the consumer such that it can be modified to suit preferences or may engage with them in a way that's tailored to them. Over time, consumers see themselves reflected in the asset. 
  2. The second layer is the cost of ownership. We may divide this into two categories -- pure expense and protection of value: 
    • Pure expenses may include maintenance, fuel, replacement parts and so on;
    • Costs associated with protecting the value of the asset may include risk mitigation (recommended activities that consumers may adopt to manage the risk associated with damage or loss to the personalized asset) and insurance (the cost of resilience or the capacity to return to a pre-loss state after a defined event). 

If the asset is sufficiently desirable and engaging -- "pulled" by the consumer -- and the risk mitigation and insurance components are considered to be part of the overall proposition and help to protect the value of the asset, then it follows that consumers may be prepared to purchase the overall bundle on the basis of the asset's desirability.

Further, the more that consumers consider the asset to have intrinsic value the more they may see these costs as an investment in mitigating loss of value -- and may be prepared to increase risk and insurance spending. An example may be if insurers provide guidance on how to increase a property's utility or overall valuation or boost the resale value of a vehicle. 

If we leverage personalized recommendations to help consumers enhance the perceived or actual value of the asset, we may increase both its attractiveness and consumer preparedness to pay for further insurance services.

See also: Time to Raise Your Embedded Insurance Game

Personal Lines Examples 

Prevention and protection become a dynamic part of home ownership. 

  • Insurers could provide home buyers with a home-styling app that scanned the dwelling inside and out and provided personalized recommendations on how to redesign based on the owner's personal preferences -- perhaps recommending artworks, sound systems and acoustic materials or renovations such as skylights or natural heating and cooling options. 
  • The app may also recommend ways to enhance the property value, such as landscape gardening, adding a patio or renovating a kitchen, calculating estimated benefits once complete. 
  • The service could provide options for smart devices that mitigate risk of property damage or loss.
  • Further, the insurer may provide access to trusted service providers who can fulfil these recommendations. 
  • Complementing the property redesign, a flexible homeowners coverage could recognize the individual characteristics of the property and provide coverage accordingly, offering additional coverages and updates as changes are introduced. 

The insurance program becomes a risk and resilience service that helps to optimize resale value as well as supporting driver safety.

Chart with two columns comparing point-of-sale and point-of-design for embedded insurance

  • Existing auto telematics programs for insurance typically focus on improving driving behavior through incentives such as reduced premiums. 
  • Insurers may collaborate with original equipment manufacturers (OEMs) to incorporate pay-as-you-drive coverage, tailored for each line of vehicles and recognizing their individual risk factors and features, with an in-car customer experience that emphasized safe driving to protect the re-sale value of the asset. 
  • The interface may provide personalized guidance on aesthetic or performance enhancements, such as addressing scratches and dints or detailing services, with recommended providers to support. 

Summary

Increasing perceived value does not necessitate that willingness to pay for insurance services will increase -- studies have demonstrated that the factors that influence willingness to pay are numerous and differ by customer segment -- yet it is reasonable to suggest that helping consumers enhance actual or perceived asset value, coupled with risk mitigation activity and protection, may lead to greater retention and potentially upselling opportunity. 

With embedded insurance, by tailoring it to the risk and the individual's choices we tie the value proposition of the asset and the insurance product together. By helping consumers increase the real and perceived value of the asset through personalized recommendations, and making it easy to protect, we can give consumers more reason to pay for risk mitigation and protection. Regular engagement and genuinely valuable guidance may create benefit for consumers and insurers alike.


Chris Bassett

Profile picture for user ChrisBassett

Chris Bassett

Chris Bassett is a management consultant with over 10 years of experience in operations strategy. 

He is the founder of Green Bean Consulting Group, which helps leadership teams step outside familiar thinking to tackle complex operational challenges more effectively.

The Key to Transformation? It’s Not Technology

Insurers can overcome the many challenges of digital transformation by dropping their technology-first mindset and adopting a people-centric one. 

Woman sitting on a bed with a computer on her lap and looking contemplative

KEY TAKEAWAY:

--For transformation to occur, key stakeholders must have the five C's in place: customer, capacity, competency, culture and communication.

----------

Sixty-one percent of people say resources (a category that includes both cost and people) are the biggest challenge to digital transformation, according to a poll during an Accelerate webinar hosted by Equisoft. But life insurance companies can overcome this challenge by dropping their technology-first mindset and adopting a people-centric attitude. 

For change to be successful at life insurance companies, key stakeholders must have the five C's in place: customer, capacity, competency, culture and communication. For life insurance companies looking to extract the anticipated value from their digital transformation, here are a few suggestions on how to improve each of the five.

Customer

Insurers cannot forget what drives these initiatives to begin with: the customer, both the agent and policy holder. Companies need to keep the customer at the center of decision making at all levels. This keeps both IT and business on the same page and working toward the same goals. Digital transformation cannot be a pure IT strategy; it needs to be a business transformation strategy. Organizations need to preserve products and processes that engage customers but also build new capabilities to support goals to scale and innovate to enhance engagement. 

See also: Going Beyond Incremental Transformation in Insurance

Capacity

While technology is still a key component of digital transformation, the journey can’t succeed if employees don’t have the capacity to oversee the implementation and maintain the existing legacy systems during the transition and avoid compromising their other projects.

When it comes down to it, the human capital will end up absorbing the change being pushed by leadership. It may not always be possible to have a dedicated team to oversee the transformation, especially in life insurance organizations that are limited in people resources and budget. So insurance companies should consider looking to outside technology companies for assistance with the transformation.

Not only will this offset some of the heavy lifting typically placed on internal employees, but it may also help organizations think outside of the here-and-now to gain a bigger picture of how digital transformation fits into overall organizational goals — both short-term and long-term. Collaborating with external partners can also help with establishing a stakeholder chart, including analyzing who will be the most affected by the transformation and what needs to be done to make the transition smooth. 

Competency

When you think about change in organizations, it’s not just about modifying workflows, it’s also about changing the skills that people need to leverage to get business done. An organization may be able to operate legacy systems, but it’s another matter to overhaul those and build updated or more modern solutions from scratch and educate others on how to use them. While organizations might have a set of people who are experienced in transformation, the organization as a whole is unlikely to share this expertise. Teams need to have the right digital skills and if those aren’t in place yet, an upskilling process must be set up before life insurers can even continue.

When faced with differing competency levels, a solution is to take the greenfield approach, either on your own or in collaboration with a trusted technology partner. With the greenfield approach, instead of modifying existing systems, the new platform is created from a clean slate without the need for new code to be written and with no restrictions or dependencies on legacy technology. This allows insurers to create an open environment for integration with innovative digital insurance technologies that streamline new business and underwriting processes. It also gives insurers time to roll out the change and adopt additional competencies required for success. 

While this can be a good solution, companies need to make sure they understand how their system-by-system greenfield approach aligns with the overall digital transformation plan, shifts to digital thinking, ensures the flexibility of the new system and obtains buy-in from all stakeholders. 

Culture

A more intangible key to a successful digital transformation is culture. When embarking on this kind of journey, organizations need to create a culture that embraces change, adaptability and resilience. Participants need to be okay with being uncomfortable and acknowledge shortcomings when they occur. If your stakeholders aren’t on board with technology change, then they’ll become roadblocks to your success instead of champions.

Implementing this type of change-oriented culture requires buy-in from organizational leaders, both at the C-suite level and the middle management level. Company leaders need to work toward creating and sustaining an environment in which people want to be part of change and pushing the business toward a more market-competitive position. 

But most importantly, companies should empower employees to make decisions about the project and foster ownership over the change management experience. This gives the employees a voice and encourages them to become far more involved in the process. They'll be more inclined to think through what obstacles may arise, what opportunities the new solution may create and how best to take advantage of the transformation. These are all great outcomes for the organization and not always seen in some of the “top-down” initiatives.

To create this culture of change, life insurers need to make sure all involved parties are aligned around a shared digital transformation vision. Additionally, key stakeholder group representatives should be looped in as early as possible, especially during the planning and scoping stages. If everyone has had a hand in building the vision, it’s easier to foster enthusiasm for the project and overcome obstacles, should they occur. 

See also: Insurtechs' Role in Transformation

Communication

Just as leaders need to foster a culture that’s accepting of change, they also need to openly communicate what the organizational goals are, how the company is working toward those goals and what additional asks are needed of employees. Transparency will ensure that employees understand their roles in this journey and how they can contribute. 

Part of being honest is being forthcoming when mistakes are made. It’s this truthfulness that will establish a sense of trust within the organization and give leaders an opportunity to demonstrate initiative based on how they’re rectifying the situation. 

Communication goes both ways. Leaders need to be open to receiving and incorporating feedback from employees to create a digital transformation pathway that works for everyone. Doug Lipp, the former head of Disney University, discussed the "walking the park" approach during his keynote address during last year’s Equisoft Elevate event. By frequently and consistently walking the park — or connecting with key stakeholders to gain a fresh perspective on where changes and improvements can be made — life insurers can learn about pain points in the value chain and identify ways that their digital transformation efforts can alleviate them. When you establish regular discourse as a default rather than the exception, you provide clear paths for employees and partners to share ideas and concerns. 

Change management is what drives success, but communication is what allows you to create opportunities for your team to be successful. 

Wrap-Up

Technology may be the impetus for digital transformation, but the people behind the initiative ultimately drive the change and determine the journey’s outcome. Change management, coupled with effective communication and a focus on people, creates opportunities for insurers to succeed. By placing your people at the heart of digital transformation, you can navigate the challenges of digitalization and harness its full potential.


Brian Carey

Profile picture for user BrianCarey

Brian Carey

Brian Carey is senior director, insurance industry principal, Equisoft.

He holds a master's degree in information systems with honors from Drexel University and bachelor's degrees in computer science and mathematics from Widener University.

Using AI to Better Manage Closed Blocks

Consolidators that are in the business of acquiring closed life insurance blocks often face challenges. Data and AI strategies offer a way out.

Blurry and angled photo showing a long hallway with blue, purple, and pink lights showing data sets on both sides

KEY TAKEAWAYS:

--Managing closed blocks is a drain to insurers' capital and leads to a higher price per policy.

--Strategies led by data and AI can let life insurers reimagine closed blocks, improve operational efficiency and enhance the customer experience.

---------

Growth and cost optimization being the twin engines for sustainability, life insurers need to innovate products and services to cater to new realities such as longevity, retirement gaps and holistic wellness but at the same time focus on operational efficiency of legacy or closed blocks for better capital usage and reserve management. As a result, insurers must leverage technology advancements, data & AI strategy to manage closed blocks effectively. 

With insurers adopting various strategies such as reinsurance, outsourcing and consolidation to harness the proportionate locked-in capital, industry deals with complexities of asset liability management, regulatory demands, depreciating returns, administration of siloed products in legacy tech stack, process inefficiencies, etc., leading to higher costs and hurting customer experience.

Organizations can adopt two approaches to unwind the complexities and achieve operational efficiency: 

  • Drive Simplification & Digitization
  • Governance & Controls

Drive Simplification & Digitization

In dealing with the complexity of closed blocks, organizations can drive simplification in the following ways:

Cloud-based data lake – Consolidators that are in the business of acquiring closed blocks often face challenges such as long cycle time for integrating systems, data and the processes of acquired books. Cloud can be used to migrate the acquired book off its legacy platform, streamlining data extraction, data ingestion, processing, etc. Timelines for future acquisitions can be shortened and closed blocks managed effectively.

Low-code, no-code – Monolithic legacy systems often face challenges when it comes to administering closed books because of a lack of the needed skillsets, complexity in product administration, huge development costs for conversion, etc. Low-code, no-code platforms will significantly reduce the development life cycle and maintenance, enabling a transition to modern technology that eases integration with contact center operations and provides a seamless customer experience.

Digital twin – Process inefficiencies in customer servicing such as policy inquiry, FNOL, adjudication, payouts, etc. lead to increased price per policy. Application of process mining tools in conjunction with a digital twin -- a virtual representation of physical entities, data, its relationships and behavior -- will help identify bottlenecks and establish process and persona twins to streamline business process, aid in merging portfolios to achieve economies of scale and reduce cost of operations.

Generative AI – Productivity of IT operations and experience of in-force policy holders can be enhanced by query generation (i.e., converting natural language queries to SQL), data engineering, validation, aid in policy and claim servicing, bordereaux processing and customer service chatbots enabled with features such as claim summarization, document Q&A, etc.

See also: Moving Beyond Data Lakes

Governance & Controls

AI/ML for accelerated rate filing – As the risk profile of the customer changes, insurers managing in-force policies of legacy products need to be agile in filing in-force rate actions to state regulators. Traditional methods of data acquisition and processing of information (placed coverages, incurred claims) and projections for forecasting are time-consuming and often takes months. Automated data discovery, intelligent data extraction, ML-based DQM, centralized assumptions hub, etc. will enable lineage and traceability to regulators and accelerate rate filing and rate revision, thereby improving profitability.

Data governance and KPI model office for performance management - Establishing effective data controls and governance to measure the performance via key performance indicators (KPIs) is critical for enterprises to manage capital effectively. For instance, data quality issues in the customer data domain will affect the ability to merge the portfolios for optimization, establish a unified view of the customer for cross-sell and up-sell strategies, etc.

Way forward

Higher price-per-policy for managing closed blocks in the industry presents a significant opportunity for insurers to harness the combinatorial power of data and AI to improve their operations and governance, enhance customer service through digitized process and make capital management more effective.


Prathap Gokul

Profile picture for user PrathapGokul

Prathap Gokul

Prathap Gokul is head of insurance data and analytics with the data and analytics group in TCS’s banking, financial services and insurance (BFSI) business unit.

He has over 25 years of industry experience in commercial and personal insurance, life and retirement, and corporate functions.

The MGA Market Boom

While MGAs continue to expand and add foundational channels, there is an interesting shift in their approach to insurtech.

Low angle image of tall glass office buildings against a bright and cloudy sky

KEY TAKEAWAY

--A third of MGAs are planning to add insurtech partners over the next three years, and 40% expect to expand/grow their current partners in the space, such as distribution platforms or digital agencies. Affinity relationships and partnerships with other MGAs/MGUs are also likely to develop significantly among more than half of MGAs.

----------

There is no arguing about the strength of the managing general agent (MGA) market in 2023. MGAs’ agility, innovation and focus on specialty and complex lines have positioned them for continuous growth. Conning reported the MGA market grew by 24% in 2022, with associated premium volumes estimated to be more than $85 billion.

Much of MGAs’ success can be attributed to how versatile they can be. Incumbent MGAs are leveraging advanced tech capabilities and new channel strategies to propel their growth in a market with increasing competition. The latter has become especially critical as MGAs have a broader role in the distribution landscape and seek to expand their reach in an increasingly hardening market.

A new ReSource Pro research report examines the channel distribution plans of MGAs in 2023, including their current partnerships, their expectations about how distribution will change in the next few years and their strategies to expand various channel partners. Considering the many challenges in the market today, such as rapid technological advancements, evolving customer expectations and a volatile economic environment, MGAs are exploring aggressive plans to grow certain distribution channels.

While MGAs continue to expand and add foundational channels, such as wholesalers and retail agents/brokers, there is an interesting shift in their approach to insurtech. A third of MGAs are planning to add insurtech partners over the next three years, and 40% expect to expand/grow their current partners in the space, such as distribution platforms or digital agencies. Affinity relationships and partnerships with other MGAs/MGUs are also likely to develop significantly among more than half of MGAs.

Regardless of the channel partner an MGA chooses, conducting thorough due diligence and ensuring strategic priorities align across parties is essential. Identifying partners that strengthen market position will be key to MGAs’ long-term success.


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.