Download

How AI Can Boost Insurers' Operational Efficiency

AI is automating workflows, improving risk assessment, reducing claims costs, and accelerating decision-making.

A white robotic hand palm facing up with a light blue light shining out of it forming the shape of a lightbulb against a dark blue background

In today's intensely competitive insurance industry, optimizing underwriting processes, minimizing claims leakage, and improving overall operational efficiency are pivotal for enhancing profitability. Artificial intelligence (AI) is transforming these areas by automating workflows, improving risk assessment, reducing claims costs, and accelerating decision-making.

Enhancing people power is the key to improving processes and results across underwriting and claims. Insurers that embrace AI are positioning themselves for long-term success and a significant competitive advantage.

Streamlining Underwriting to Reduce Operational Costs

With AI-powered solutions, underwriters can efficiently process vast datasets from multiple sources, uncovering hidden insights and patterns that may not be immediately apparent.

Underwriters at a major specialty insurer traditionally relied on manual entry and review of various documents within submission packages (e.g., emails, applications, ACORD forms, loss runs, and schedules). This effort further taxed overworked underwriting teams, increasing the risk of errors and inconsistencies and potentially slowing customer response times.

Deploying AI-powered data extraction and classification automated critical operations by identifying key data points and streamlining data entry into the carrier's underwriting systems. The carrier's AI systems, augmented by human-in-the-loop validation and feedback, significantly improved data quality and accuracy over manual entry. Increased speed and efficiency helped human experts leverage their experience more effectively to focus on more complex risk analysis, making underwriting decisions, and strengthening broker relationships.

Upgrading to AI expands underwriters' resources for:

  • Increasing Premium Growth: Underwriters often face a multitude of submissions, many of which may not align with the company's risk appetite or underwriting guidelines. AI enables insurers to efficiently process unstructured data, such as policy applications, medical records, and financial statements, helping underwriters swiftly identify and prioritize submissions that align with business objectives. This targeted approach reduces time and resources spent on less promising submissions, leading to significant cost savings and improved underwriting efficiency.
  • Improving Speed to Quote: AI can streamline the quoting process by automating manual tasks such as data collection, risk assessment, and document processing. Using machine learning algorithms and natural language processing, AI rapidly analyzes applicant data and gives underwriters the necessary insights to generate quotes efficiently. Accelerating the underwriting process significantly enhances operational efficiency and improves customer experience with timely quotes.
  • Lowering Loss Ratio: AI plays a crucial role in enhancing risk management by leveraging advanced models to more accurately predict potential risks. By analyzing historical data, market trends, and other influencing factors, AI helps flag high-risk policies early in the underwriting process. This enables insurers to mitigate potential losses through actions such as refining pricing strategies or offering more tailored coverage.

AI-driven automation can enhance underwriting productivity by optimizing workflow automation, improving document processing speed, and integrating predictive analytics for better risk selection. Underwriting productivity can potentially double in terms of premium per underwriter without substantially increasing the number of risks underwritten.

Reducing Claims Costs Through AI Integration

Claims management has historically been a resource-intensive process, but AI is revolutionizing how insurers handle claims by automating key aspects of claims intake, processing, and settlement. For example, it took a leading specialty carrier's mail room teams three to five days to index claims submissions, necessitating significant overtime work. Team members indexed documents during work hours, causing delays in other areas. The situation became untenable, with claims managers processing data during lunch hours and even at home on weekends. By using an AI agent, these teams reduced mailroom turnaround times to under one hour and cut items reviewed manually by 60%, greatly boosting business results, increasing capacity for peak load times, and improving workers' lives on and off the job.

AI-accelerated claims management helps insurance businesses create a competitive advantage by:

  • Improving Efficiency: AI automates repetitive tasks, minimizing manual errors, and accelerating decision-making to drive greater operational efficiency. AI-powered tools can extract and analyze demand packets and subrogation demands, offering insights that enable claims experts to reduce excessive claim payouts.
  • Reducing Cycle Times: AI's capability to rapidly analyze vast amounts of data enables quicker claims resolution and significantly reduces cycle times. AI also accelerates decision-making by automating key processes such as claims triage, document verification, and fraud detection.
  • Increasing Customer Satisfaction: AI streamlines claims management by automating repetitive administrative tasks, like data entry and document verification. These improvements are freeing claims teams and adjusters to concentrate on customer-focused activities such as handling complex claims, delivering personalized support, and providing updates. This leads to enhanced customer relationships and overall customer satisfaction.

By integrating AI into claims management, insurers can significantly reduce costs while improving efficiency, speed, and the customer experience. By addressing both expense reduction and indemnity cost savings, AI helps insurers significantly reduce overall claims expenditures.

The Financial Impact of AI Integration

AI adoption is no longer optional – it is a strategic imperative for insurers looking to enhance financial and operational performance. There need to be clear strategies and guidance to accelerate AI implementation and maximize return on investment (ROI).

Key success factors for AI adoption include:

  • Ensuring Data Quality: AI models are only as effective as the data they are trained on. Clean, structured, and well-integrated data is critical for AI success.
  • Strategic Partnerships: Many insurers face talent shortages and technical barriers. Collaborating with AI vendors specializing in insurance can accelerate implementation, enhance outcomes, and be an overall more cost-effective approach.
  • Human-in-the-Loop (HITL) Systems: AI should complement human expertise, not replace it. Implementing HITL into insurance workflows ensures AI outputs are reviewed and refined by experienced professionals.
  • Focusing on Quick Wins: Deploying AI in targeted areas – such as claims triage, underwriting automation, and fraud detection – allows insurers to realize benefits faster and build momentum for broader AI adoption.

Integrating AI into underwriting and claims management is transforming the insurance industry by streamlining processes, improving decision-making, and enhancing customer satisfaction. By reducing operational costs, improving pricing accuracy, and minimizing claims expenses, AI directly contributes to the profitability of insurance companies. As AI adoption continues to grow, insurers that prioritize strategic implementation and data-driven decisions will be best positioned to gain a competitive edge in the evolving marketplace.
Renters Insurance Develops a Split Personality

Renters insurance has traditionally been aimed at people just setting out in life. But another market is emerging — downsizing Baby Boomers.

Red and White Signage Near the Wooden House

Agents and brokers may do well to approach the rental insurance market with something of a split personality these days.

Traditionally, renters insurance was a policy geared toward people just setting out in life. They didn't own a home yet, but they still needed the property and liability coverage rental policies offered.

That market still exists, of course, largely with Gen. Z customers. But with today's demographic shifts, another lucrative market is emerging that needs rental policies — downsizing Baby Boomers.

The younger sibling of homeowners insurance, rental insurance still accounts for a nearly $6 billion market. More renters carry rental insurance than don't, with a reported penetration rate of 60%, making rental insurance a potentially attractive line to regularly promote.

Baby Boomers are at the peak of their home equity, while also facing an empty nest and more house than they need. Increasingly, many Baby Boomers are cashing in, selling their longtime home and using that equity to rent a more manageable space. This makes them a prime audience for a rental sales pitch, but with a new angle on the value proposition.

Changing value proposition

The traditional sales pitch for rental insurance is geared toward someone in their 20s. They have either moved out of their parents' home or off campus from their dorm, and they need to protect their limited belongings.

These Gen. Z customers have lower net worth and typically less than $20,000 in total belongings, making their rental insurance policy much less than $20 per month.

At that lower price point, those young adults would be protected from damaged property or theft or if a guest was injured in their home. For the record, the most common in-home accident claims were from poisoning, quickly followed by falls.

Without a nest egg to fall back on, that protection could be the difference between financial calamity if the worst were to happen.

Many landlords even require their tenants to take out a rental policy as a term of the lease.

But with Baby Boomers, that value proposition is turned on its head.

While Gen Z is buying rental insurance because they don't have much net worth and a loss could spell financial doom, Baby Boomers not only have financial resources but also have high-value property that needs to be covered.

A Baby Boomer policy would skew to a much higher coverage limit than a Gen Z policy would, with correspondingly higher premiums.

"A Baby Boomer is going to have family heirlooms, things like jewelry, electronics, and a lot of other things that are going to need to be scheduled," said Patrick Foy, senior director of strategic planning for TransUnion's insurance business. "A $20,000 policy isn't going to cut it for them."

Additionally, Baby Boomers will likely need to protect off-premises property, such as a storage unit that houses high-value collectables. And since the off-premises coverage limits will be a percentage of the total property coverage, if that storage unit had particularly high value items, it might even warrant its own dedicated policy.

And all the while, Baby Boomers' higher net worth means the liability protections found in a rental insurance policy help them more because they have more to lose.

Marketing messages and channels

Communicating the value of a renters policy takes two largely different strategies for these different generations.

"Younger customers are comfortable with non-agent interaction," Foy said.

A Gen. Z customer wouldn't blink an eye about buying a policy online or through an app, while the older customers tend to want more personal attention.

Insurers are primarily reaching out to the Gen. Z market through digital advertising – whether that is through web display ads, or increasingly audio or video ads on podcasts or streaming services.

Some digital ads also can reach the Baby Boomers, but for them, the marketing channels tend to be more centered on direct mail and some terrestrial television and radio advertising — with personal relationships with agents being one of the most valuable channels.

"It isn't a one-size-fits-all approach anymore," Foy said.

Regardless of which channel reaches which group, one common benefit both groups should know about is the additional living expenses provision. With the prevalence of natural disasters, such as wildfires and hurricanes, the additional living expenses provision can be a strong selling point, provided their policy includes coverage for natural disasters. That way if they face a mandatory evacuation or can't move back in because their home is damaged, those added costs can be covered.

And while Gen Z may not initially reach out through an agent, pulling them in through rental insurance could pay serious dividends down the road. Once they are in the insurance company's ecosystem, they are already within reach when they are ready for the more grown-up policies, such as auto, homeowners, or umbrella lines.

Don’t Roll the Dice Selecting a New Core Platform

Learn how leading organizations are leveraging this innovative approach to enhance efficiency, scalability, and security. Dive into real-world case studies and expert insights to stay ahead in the ever-evolving landscape of risk management.

blue dice

Mitigate risk with true cloud SaaS


Selecting an insurance core platform can be challenging as buyers weigh the available options. Increasingly, insurers are relying on cloud for new implementations yet the nuances between the critical differences between them remain elusive for many decision-makers. Understanding those differences could be the determining factor between a profitable and future-proofed digitalization strategy or one that results in significant impairments or even the loss of competitive advantage.

Download the eBook Now  


Sponsored by: Origami Risk


ITL Partner: Origami Risk

Profile picture for user OrigamiRisk

ITL Partner: Origami Risk

Origami Risk delivers single-platform SaaS solutions that help organizations best navigate the complexities of risk, insurance, compliance, and safety management.

Founded by industry veterans who recognized the need for risk management technology that was more configurable, intuitive, and scalable, Origami continues to add to its innovative product offerings for managing both insurable and uninsurable risk; facilitating compliance; improving safety; and helping insurers, MGAs, TPAs, and brokers provide enhanced services that drive results.

A singular focus on client success underlies Origami’s approach to developing, implementing, and supporting our award-winning software solutions.

For more information, visit origamirisk.com 

Additional Resources

ABM Industries

With over 100,000 employees serving approximately 20,000 clients across more than 15 industries, ABM Industries embarked on an ambitious, long-term transformation initiative, Vision 2020, to unify operations and drive consistent excellence across the organization.  

Read More

Webinar Recap: Leveraging Integrated Risk Management for Strategic Advantage

The roles of risk and safety managers have become increasingly pivotal to their enterprises' success. To address the multifaceted challenges posed by interconnected risks that span traditional departmental boundaries, many organizations are turning to Integrated Risk Management (IRM) as a holistic approach to managing risk, safety, and compliance. 

Read More

The MPL Insurance Talent Crisis: A Race Against Time

Managing Medical Professional Liability (MPL) policies has never been more complex — or more critical. With increasing regulatory demands, growing operational costs, and the ongoing talent drain, your team is expected to do more with less.  

Read More

MGA Market Dominance: How to Get & Stay Ahead in 2025

Discover key insights and actionable strategies to outpace competitors and achieve lasting success in the ever-changing MGA market. The insurance industry is transforming rapidly, and MGAs are at the forefront of this change. Adapting to evolving technologies, shifting customer needs, and complex regulatory demands is essential for staying competitive.

Read More

AI Can Fix Everything in Insurance. Right?

There is no question about whether AI can improve insurance. Rather, the questions are about which functions, how extensively and when. 

An artist’s illustration of artificial intelligence

Every time we read an article or a marketing piece espousing the astounding power of AI as applied to insurance, we cannot help but think about Gus Portokalos. 

If you recall, Gus was the bride’s father in the 2002 hit movie "My Big Fat Greek Wedding," who famously suggests, "Put some Windex on it!" as a solution to all manner of problems, including cuts and scrapes. Gus proudly related every word, phrase and meaning back to his Greek ancestry as a solution or fix to each conversation. A lot of people are treating AI in the same fashion.

Even the typically thoughtful Bill Gates gushed that AI is "the first technology that has no limit" and “could be as revolutionary as the internet or mobile phones.” 

Claims 

Claims is an area eyed for more efficiency, greater accuracy, and better customer experience despite some of the negative implications of a machine denying claims, and associated efforts to ban such usage. Particularly sensitive and controversial use-cases are for direct customer interaction, even for loss intake, known as FNOL (First Notice of Loss), which is highly manual and would have tremendous ROI.

FNOL 

FNOL is where each claim begins in the cycle. In fact, timely reporting is a key condition of the insurance contract. The claim reporting process is part interview, part explanation, in which customers are asked a series of questions to capture when, how and what happened to whom. Once this information is gathered and keyed into the system, an assignment(s) is made to one or more adjusters where the process unfolds.

Prior to the development of today’s call centers, claims were reported individually by local agents filling out ACORD forms and mailing them in to the insurance company. Fast-forward, these insurance call centers have been optimized with numerous technologies that identify and queue callers, manage workflow and workloads and even detect customer sentiment through voice analysis. Some have leveraged outsourcing and off-shore resources but mostly on a limited basis such as after-hours and overflow support. Overall, the industry has demonstrated limited desire to fully automate FNOL, prized as the golden moment-of-truth where a live service representative can gather information and provide an empathetic, caring touch. 

Digital FNOL options are slowly gaining, yet the massive, human-centric call centers still exist, and carriers remain cautiously conservative about disruption, although this is changing because of evidence that conversational AI can perform much of the loss reporting process more accurately. New entrant insurtechs like Lemonade were built as digital-first, bypassing the call center concept, but are true outliers compared with incumbents.

The P&C insurance industry's written premiums just crested the $1 trillion mark for the first time, per S&P, with some 8% or greater growth expected in the next two years, according to AM Best. Claims account for roughly $600 billion, not including the cost to manage claims which is upward of another $100 billion. Given these financial realities, it is easy to see both the challenge of getting things right and the huge potential to streamline and lower costs.

Chatbots

Chatbots have been around for several years, and, although still relatively early stage in sophistication, consumers are rightly impatient with partial or pre-programmed support. Voice systems that misunderstand responses are mocked as a punchline – “Did you say statement balance? I said representative!” Although not all bots are created equal, with some quite impressive, their limitations have been in the way for insurers and left to industries like telecom, which are notorious for lesser service and where choice is not a priority. AI promises to eliminate chatbot limitations, making for human-like conversations.

Still, the concept of phone call claim reporting to essentially provide information in a 15- to 20-minute conversation or longer has become an atypical experience in today’s world. Imagine Amazon taking orders by phone only to have a call back a day later to take payment and shipping information. That is essentially the P&C industry’s method of claim reporting. Call in the claim today and an assigned adjuster calls back tomorrow – give or take a few hours or a couple days. This is an outdated mindset and process and a technology failure.

Balancing Efficiency and Empathy; One Size Does Not Fit All

There is a debate about human touch and technology, with two camps divided on what policyholders really want. Decisions are often made in a blanket approach devoid of recognition of the huge variance in claim type scenario, ranging from a fender bender to a fatality, theft of a single item to an injured worker. It's one size fits all when it comes to FNOL, with the loudest voices protecting the virtues of a caring human, ready to help console callers. As valid as this approach might have been over the years, we can't ignore demographics and so-called liquid or multi-channel experiences, where consumers interact differently with modern systems in one setting and expect similar systems in others. Nor should empathy be an excuse for an inefficient customer experience.

Meanwhile, AI is getting a lot of attention, and insurers are cautiously eager to reap the benefits. Surveys show insurer C-suites as bullish on AI, and studies suggest more than half of all jobs can be automated, but fear of data privacy, litigation, regulation and AI’s mysterious power has restrained the industry. Some states are moving to ban the use of AI in claims denials, which seems premature and is designed to address the exception, because most claims are covered and paid. Consequently, AI co-pilot and assistant models have become popular and safer concepts. 

GenAI

GenAI has gained traction as a way forward because of proven efficiency gains in summarizing documents, reports, email, and other information, focused on internal insurance process. A recent report by Allstate demonstrated that GenAI letters were considered superior and more empathetic as compared with those written by humans. This raises questions about the whole human vs. technology paradigm. In fact, this example highlights the deeper issues around competence, confidence and other factors that can make or break an experience.

Conversational AI

So, should we think of AI making everything better in insurance? 

Conversational AI is amazing technology, enabling two-way dialog and facilitating real questions and answers. Several of the conversational FNOL demos and recorded scenarios are mind-blowing, whether applied to gather partial information or an entire claim report. Companies like HiMarley, which advanced communications in texting and claim guidance, are using conversational FNOL. Liberate Voice AI is another such provider and is likewise revolutionizing claim intake. Still others, like Interactions, which uses technology and human assistance in the background, and Assured, which offers structured digital claim intake tools, are among many more emerging in the FNOL space.

The use cases are boundless given the many variations and complexities of insurance processes and the immense volume of associated data, structured and unstructured, and the high number of external integrations. While the bulk of these processes are relatively simple and straightforward and therefore lend themselves well to AI automation, a smaller but meaningful number are complicated and require extensive specialized experience, judgment and empathy, which are less suited to AI automation alone.  At least, this is current thinking, until some are bold enough to push forward and prove otherwise.

Harnessing AI Superpowers

There is no question about whether AI can improve insurance. Rather, the questions are about which functions, how extensively and when.  

In a recent interview with the New York Times, Reed Hastings, a co-founder of Netflix, stated, "The A.I. change, I think, will be much bigger than the social networking change." Reflecting as much caution as enthusiasm about AI, Hastings recently donated $50 million to his alma mater, Bowdoin College, to launch the Hastings Initiative for AI and Humanity and become a leader in studying the consequences, and guiding beneficial uses, of artificial intelligence.

As with the greatest man-made inventions that have shaped human history, including the wheel, printing press, electricity, airplane and internet, AI is likely to drive unimaginable benefits, innovation and unexpected consequences. Unlike these earlier advances, however, AI may the first man-made invention that threatens its creators. We have been warned!  


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.

Signs of an 'Insurtech Spring'

After a loooonnnngggg insurtech winter, the daffodils and crocuses are emerging. Spring, mostly driven by AI, seems to be upon us.

Image
man walking in flowers

While the search for innovation in insurance has been relentless in the dozen years I've been involved with the industry, the insurtech movement has waxed and waned. For years now, funding for insurtech startups has simply waned. It fell from some $16 billion in 2021 to roughly $4 billion last year as some big ideas didn't pan out and as the industry came face to face with more immediate problems, such as the soaring costs for auto insurers.

But the explosive gains in the stock prices of Lemonade, Hippo and Root got me to take another look at the trends in insurtech startups, and there are signs of spring after the long winter. Although I learned that those three marquee names still have a good ways to go before they can be crowned successes, there seem to be lots of interesting ideas bubbling to the surface, principally in AI but also in other areas. 

Those ideas likely won't lead to 2021 sorts of investment numbers -- AI startups generally don't require huge amounts of capital to launch -- but the impact could still be huge. 

I credit the term "insurtech spring" to Teddy Himler, founder and managing partner at Optimist Ventures, whom I met through the (highly recommended) weekly Insurtech Rap hosted by our friend Dave Wechsler, principal at OMERS Ventures. I followed up with Himler, whose take on the last several years of insurtech is that "mobile didn't really have much of effect on the insurance industry. Okay, sure, you could click your way into a renter's policy or whatever, but the mobile and cloud waves didn't affect the economics or the value chains, or the efficiencies of insurance broadly."

By contrast, he said, "AI, machine learning, IoT, big data synthesis, all of that makes a huge difference."

Himler said the gains in efficiency will be so radical that you can imagine "an autonomous brokerage, scanning leads, ranking leads, automatically filling out PDFs, distributing those PDFs to the wholesalers and the carriers that are in their network, and then quoting and binding."

Short of that sort of breakthrough, there are also all sorts of opportunities to improve processes via AI and to create "co-pilots" and AI agents that support the work, in particular, of agents, underwriters and claims representatives. The question is whether those innovations will occur inside existing insurance companies or whether they will come from outsiders that will be acquired or will sell services to incumbents. 

Himler said the innovation will happen outside-in because "the talent doesn't want to go to work with the large insurance companies." He added that he doesn't see insurtech startups as disruptive. 

"I hate using the word 'disruptive,'" he said. "I think [insurtechs are] so complementary to what insurance companies are doing."

Adam Chadroff, a principal at Equal Ventures, said the need for innovation related to climate catastrophes will also drive a rebound in insurtech investing, as will M&A prospects, highlighted by the recent announcement that Munich Re is buying Next Insurance for $2.6 billion. But he agreed that incumbents will turn to startups for AI innovations as they get frustrated with the slow pace of internal progress. 

He wrote earlier this month: 

"Large carriers today are experimenting with home-grown solutions, but the writing is on the wall that they will have more success with customizable, scalable third-party platforms compared to internal developments. Already, >50% of decision makers surveyed at large carriers cite accuracy/reliability and implementation costs as top barriers to pursuing more/faster GenAI investments. Moreover, there is already a large lag between testing solutions and actually implementing them in production, which speaks to the challenges in AI deployment and the need for specialized software and service providers."

He added:

"The real question then is whether this is the domain for venture-backed vertical AI startups or for leading transformation/implementation consultancies: will it be the best engineers who win, or blue chip firms that know how to navigate large carriers? To date, revenues are pouring into the latter; Accenture has been eating most other firms’ lunch, with a whopping $3 billion in gen AI related bookings last year. Our view, though, is that best-in-class technical solutions do not have to be mutually exclusive from enterprise reliability. We believe the winning formula here is the player that can provide leading vertical AI innovation alongside the stability of a consulting firm, and we believe that company is overwhelmingly likely to be a new entrant."

David Gritz, co-founder of InsurTech NY, offered an intriguing analogy for insurtechs in a webinar hosted by Denise Garth at Majesco:

"If you think about how R&D is done in the biomedical industry or the pharmaceutical industry, it’s not usually the Mercks and the Pfizers and the Johnson & Johnsons that are developing innovative products and working at the cutting edge. They are the ones that have the distribution. They have the market share, and they have the controls and the ability to handle regulation.

"Instead, it’s the biotech startups, or the pharmaceutical startups that work in labs, get through clinical trials, and then when they’re proven, then the incumbents acquire them. I think that’s very much what we’re going to see over the next 10 years in insurtech. Insurtech is a great sandbox to play and to test out new concepts, whether it’s technology that can be adopted to improve workflow, or it’s new products that don’t really exist today."

As I said, the stock prices of the biggest insurtech names were what first caught my eye -- Lemonade's and Hippo's shares have roughly doubled since last summer, while Root's price has more than tripled -- but I'd say they're just a small part of the growing optimism. As Matteo Carbone explains in one of his usual, remarkably thorough analyses, the big three are getting their heads above water but are still struggling enough that they aren't likely to be the main models for future innovation. 

I realize that venture capitalists tend to see opportunities for venture capital. As the old saying goes, if your only tool is a hammer, the whole world looks like a nail. 

But I think the VCs I've quoted have a point. Even if a lot of incumbents manage the confusing transition to an AI-driven world successfully, many won't, and they'll be open to innovations from outsiders. 

We'll still have the normal problems with fit. An AI startup's technology still has to mesh with the IT systems of the incumbent. The processes of the startup and larger companies have to be compatible. Individuals within the different corporate cultures have to get along. And so on and so on. 

But at least there's a spark for the first time in quite a while.

In the meantime, if you must know, it was 79 degrees in northern California today and will be in the low 80s tomorrow, so I'm certainly feeling spring.

Cheers,

Paul

P.S. If you want to see what sorts of insurtechs have been getting funded, here and here are compilations of the latest sizeable rounds.

Redefining Risk Via Continuous Underwriting

Continuous underwriting enables insurers to monitor individual risks and portfolio trends in real time and alert clients.

Mountain road in Iceland

As we introduced earlier in this series, here and here, the insurance industry is modernizing, leveraging data and technology to transform how risk is assessed and managed. Continuous underwriting enables insurers to monitor individual risks and portfolio trends in real time—without prohibitive increases in expenses.

The impact of these advancements extends far beyond individual insurance transactions or an insurer's loss ratio. This shift creates an insurance system that enhances safety, lowers costs, and strengthens financial stability. A well-functioning insurance mechanism fosters economic growth by reducing consumers' reliance on personal rainy-day funds, allowing capital to be reinvested into businesses, innovation, and economic expansion.

The insurance industry plays a crucial role in providing incentives to businesses and individuals to adopt better risk management practices. Those who manage risks effectively benefit from better pricing and terms, while higher-risk entities face difficulty securing the coverages they desire at an affordable rate. A key example of this transformation is seen in the workers' compensation market, where automation and improved workplace safety have driven a historic decline in claim frequency, leading to 11 consecutive years of rate reductions.

Traditionally, risk assessments occur at renewal—sometimes at every third or fifth renewal—or after a claim, allowing newly introduced hazards to go undetected until effective intervention is no longer possible. Continuous underwriting shortens the review intervals, allowing insurers to quickly identify deteriorating risk conditions and influence positive changes before losses occur. Businesses, property owners, and individuals have stronger incentives to adopt safer practices—such as better building maintenance, fire prevention measures, and cybersecurity defenses. Over time, these efforts reduce preventable losses, leading to safer, more stable communities.

As more businesses and individuals improve their risk profiles, insurance costs decline, making coverage more affordable for everyone. Small businesses—often burdened by high insurance costs—stand to benefit significantly, allowing them to invest more in growth and job creation. Additionally, with fewer catastrophic losses, the insurance industry's financial stability is strengthened, reducing market volatility and ensuring that coverage remains widely available, even in high-risk areas.

One of the most critical societal benefits of continuous underwriting is its ability to equip communities to anticipate and mitigate natural disasters. Instead of waiting until renewal to adjust policies, insurers can detect increased hazards—such as outdated infrastructure, poor fire mitigation, proximity to wildfire-prone vegetation, or rising flood risks—and work with policyholders to address these issues before disasters strike. This proactive approach leads to fewer uninsured losses, faster recovery times, and a more resilient economy in the face of climate change and an increase in extreme weather events.

With real-time assessments, consumers gain a clearer understanding of how their risk management choices directly affect their premiums and carrier options. Rather than facing sudden rate increases at renewal, policyholders are granted the opportunity to make improvements and see immediate financial benefits. This shift toward increased transparency in pricing and coverage decisions will create a fairer and more dynamic insurance marketplace.
As continuous underwriting becomes the industry standard, companies have incentives to adopt safer, more sustainable, technologically advanced practices. Investments in cutting-edge risk prevention tools result in the ability to secure broader coverage at a lower rate. This accelerates innovation across industries, from construction and manufacturing to healthcare and retail, benefiting society as a whole.

Many of these advancements include the growing use of loss prevention devices. Today, insurers are subsidizing or providing sensors that monitor and alert for temperature changes, water leaks, or gas buildups. In food service, smart handwashing stations instantly detect the presence of bacteria or allergens, reducing contamination risks. Surveillance and inventory tracking tools, such as smart tags, are preventing loss and theft. These technologies not only reduce claims but also improve overall safety and efficiency across industries.

As we look to the future, advances in technology and data accessibility will continue to reshape the insurance industry. In the past, obtaining a quote could take weeks via mail or fax. Today, it takes minutes through integrated agency management systems. The industry is building a more seamless, automated insurance marketplace, where policies are continuously updated based on real-time data.

Imagine a system where insurers adjust pricing dynamically, 24/7, based on real-time changes in a policyholder's risk profile. In such a world, consumers could automate coverage selection, seamlessly switching to the best-priced policy—just as financial markets respond to changes with immediate adjustments to stock prices. Regulatory challenges notwithstanding, this vision aligns with the increasing push for efficiency, fairness, and consumer empowerment in the insurance industry.

Continuous underwriting represents a transformative shift in insurance—one that will have profound benefits for society. By encouraging risk management, we are cultivating safer communities, lower insurance costs, and a more stable financial system. Businesses and individuals are better protected against unforeseen losses, and insurers have the tools to help prevent disasters rather than just responding to them.

Underwriting entities that embrace continuous underwriting will thrive, while those that resist may struggle to remain competitive. More significantly, the insurance industry has the opportunity to become a powerful force for societal progress—enhancing economic resilience, strengthening disaster preparedness, and empowering consumers for generations to come.


Bill Deemer

Profile picture for user BillDeemer

Bill Deemer

Bill Deemer, CRM, CIC, AU, AAI, is head of underwriting at Rainbow.

Deemer is a 20-year-plus commercial insurance veteran, focused on using his well-rounded perspective to improve the insurance transaction by blending underwriting fundamentals with progressive strategies.


Andrew Clark

Profile picture for user AndrewClark

Andrew Clark

Andrew Clark is vice president of underwriting at Rainbow.

Previously, he spent five years in the U.S. Navy as a nuclear trained submarine warfare officer.

Lemonade, Hippo and Root Are Back, but....

The three prominent insurtechs recently released results that are encouraging, but all still face significant hurdles.

Abstract image representating big data with turquois and red circles of varying sizes surrounding lines in the middle

Sorry for being delinquent about publishing my newsletter over the past few months: It has been due to a lack of time (I was writing three white papers) and inspiration. The newsletter has now reached its third anniversary, with 43,219 of you choosing to subscribe. Respecting your time over these 36 months, inspiration worthy of your attention has struck me just 21 times.

Many of you have asked when I might provide my perspective on the recent facts and figures of the trio I have followed: Lemonade, Hippo and Root. Now, with their annual financial results available, is an opportune moment to examine the performance of the three publicly listed U.S. P&C insurtech carriers.

There is, for sure, some good news for their fans (and shareholders).

Lemonade

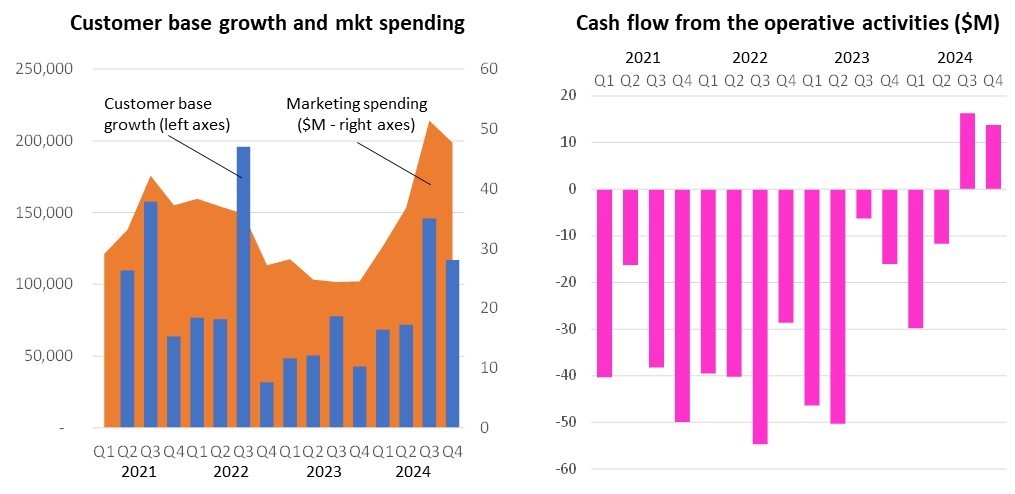
Significant growth. The company almost reached the 2.5 million customer milestone, and the last two quarters showed an increase of the customer base not seen since 2021 (excluding the effect of the Metromile acquisition), with growth aligned with the 2022 promises.

Cash flow positive. For the first time in Lemonade's history, the operative activities generated positive cash flows in the past two quarters ($16 million in Q3 and $11 million in Q4).

The loss ratio has progressively improved (73% '24 gross loss ratio compared with 85% in 2023).

Hippo

The top line has grown. Total generated premiums – which includes the iconic Hippo’s homeowner business, premiums generated by their agency, and the Spinnaker fronting business – has grown from $1.1 billion to $1.3 billion in 2024

The company had its first profitable quarter (after a historical series of losses): $44 million net income in Q4 ‘24

The combined ratio (gross) significantly improved, with a healthy landing below 80%.

Root

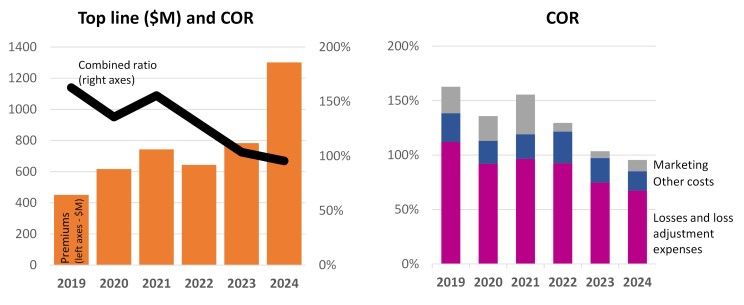
The top line has grown to $1.3 billion in '24 from $800 million in '23.

Profitable. For the first time, they close the year with a positive bottom line ($31 million in profits in ‘24 vs $144 million loss in ‘23)

Combined ratio (gross) healthy, below 100%. The loss ratio has significantly improved – consistent with market trends – and the administrative cost incidence has been under control.

BUT there are significant reasons for not being too optimistic about these insurtech ventures.

Lemonade

The company still loses a ton of money. Net losses accounted for about $200 million in ’24 (a bit less than the $218 milliion in ’23), bringing the cumulative losses since the creation to $1.27 billion and reducing shareholder equity below $600 million.

The gross combined ratio is still well above 100% (each dollar of premium has cost them more than $1.20).

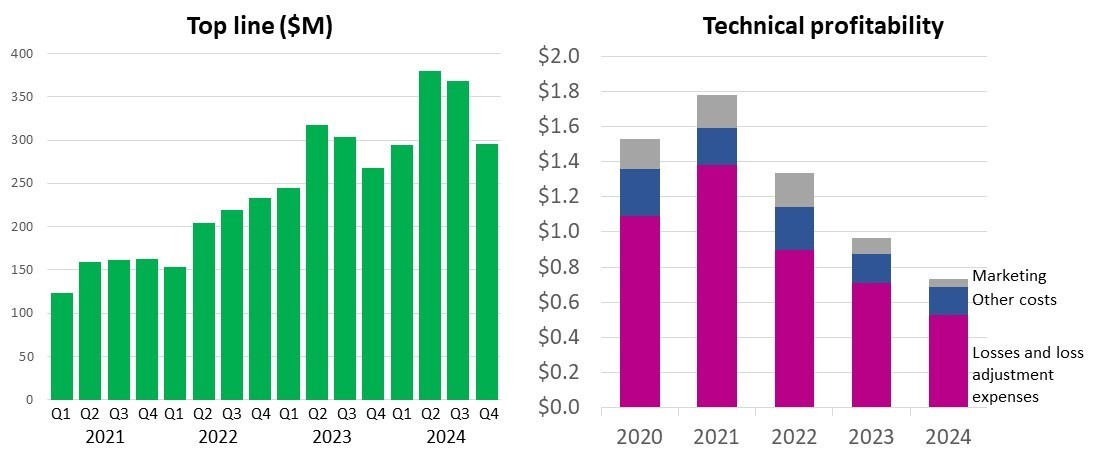
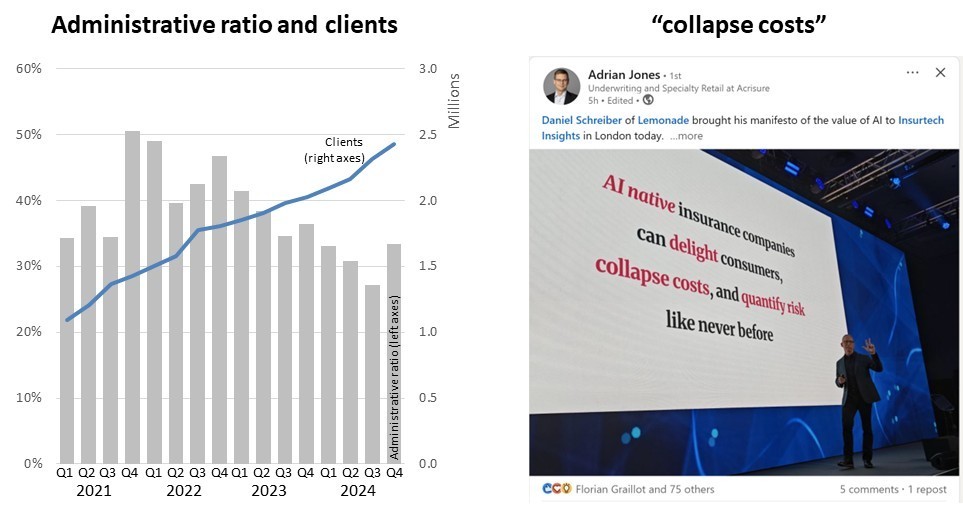
They are sill far from being an efficient insurance carrier. All their costs (excluding claims, loss adjustment expenses, and marketing) still gravitate above 30% of premium. “Collapse cost” [thanks to my friend Adrian Jones for the snapshot below] can be seen as a hope, an over-promise, or a bul***it depending on your taste for Lemonade.

Hippo

The positive results of the last quarter have been boosted by $46 million thanks to the sale of First Connect (Hippo’s independent agent platform).

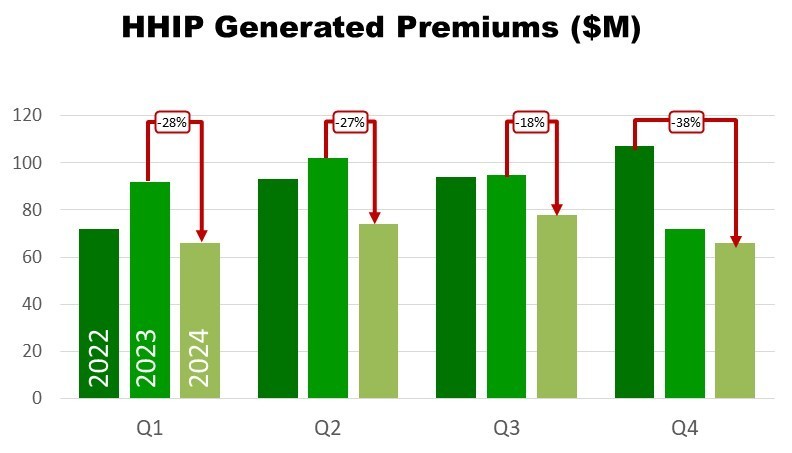
The fronting business is the only profitable business, and its top line grew double digits. As the last newsletter edition highlighted, “The only segment consistently generating profits is the business of giving UW capacity to MGAs [...] further confirming that the acquisition of Spinnaker in 2020 has been the best management decision in the history of this venture.” No significant changes here: The fronting business ("insurance-as-a-service") made $24.4 million in profit, while the original Hippo business (HHIP) lost more than $50 millon in '24.

Hippo’s original homeowner business (HHIP) has been further pruned, landing a 73% gross loss ratio in ’24 (101% in ’23). A cherry-picked sub-$300 million homeowner insurance portfolio is a humble position from which to (re)start. After burning $1.27 billion to build this business, this doesn't exactly seem a milestone to celebrate.

Root

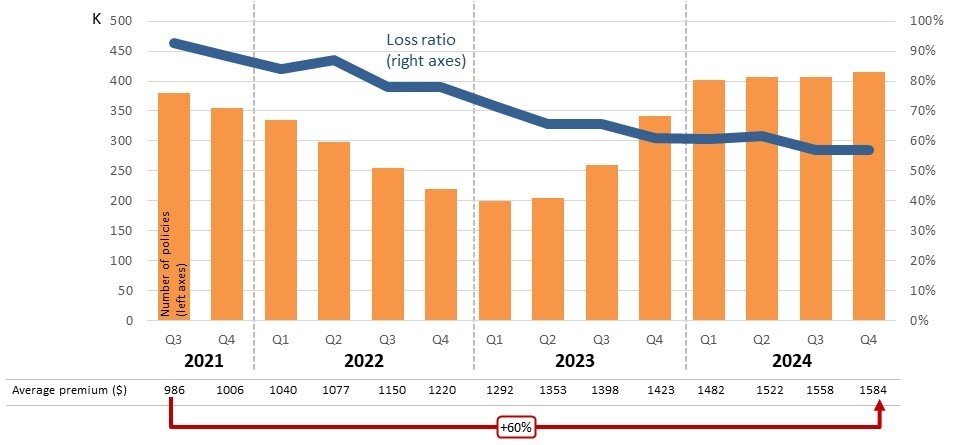
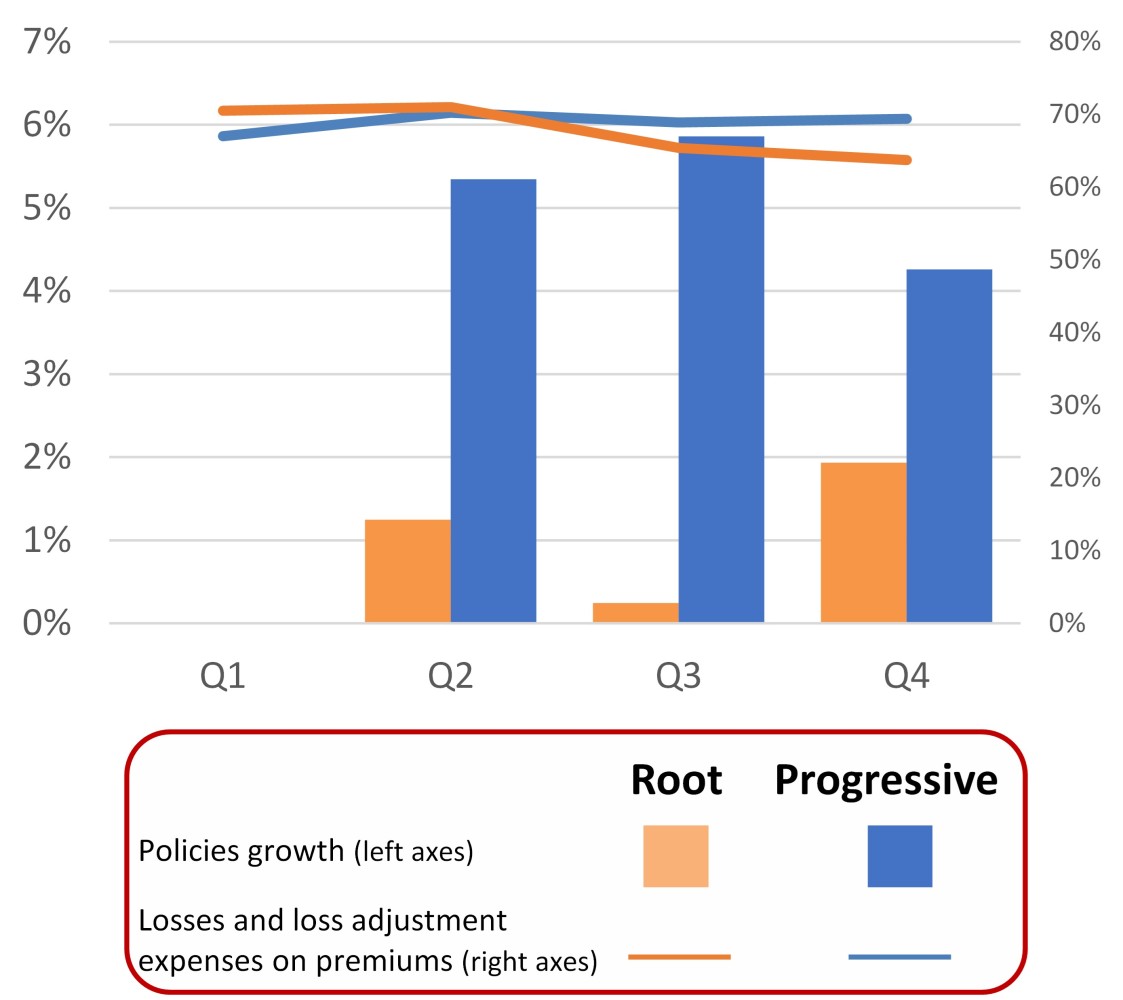
Vanished portfolio growth. Root has been stuck slightly above 400,000 policies for the past four quarters, with prudent marketing spending and constant increase of the average premium, which allowed them to keep the gross combined ratio below 100%.

But the magic moment when the auto insurance market dislocation allowed them to grow, even significantly increasing prices, is gone. Now, almost all the big incumbents are back to profitability and will start chasing new business again. How will Root deal with this scenario? Will they be able to consistently show the growth you expect from a “challenger”? Or, will their journey fail to create anything relevant in the market's competitive dynamics and only slowly repay the $1.7 billion they have burned until now.

Much of Root's equity narrative, and a substantial portion of Lemonade's projected upside from its investor day, revolve around automotive telematics. Yet, compared with current telematics best practices, both appear rather amateurish.

Telematics (when used well) is a social good because it increases the availability and affordability of coverage. This happens when the carrier becomes able to provide the same level of coverage for a lower price to a significant part of the portfolio while maintaining the target level of profitability. To do this, telematics data must be used to 1) match rate to risk better, 2) manage claims better, and 3) reduce expected losses.

Our dear insurtech Lemonade talks only matching rate to risks, or pricing sophistication (Lemonade had one slide on claims at its investor day and 21 charts about telematics. Lemonade makes promises about the future (as always).I

Root, meanwhile, talks about a current capability, their supposed superiority in matching price to risk. So let’s compare Root performance with the best practice (Progressive) in using telematics data for pricing sophistication. The competitive gap emerges clearly: Progressive has grown the number of policies by more than 16% in the past nine months, Root only a modest 3.5%.   

About the second telematics use case: Telematics and claims seem to be a match made in heaven. Instead of waiting for the policyholder's first notice of loss, the insurance carrier is informed in a timely way that something happened and has objective information about the dynamic and probable consequences of the event. 

The third usage of telematics data, totally ignored by our dear insurtechs, is to keep accidents from happening. Let's focus on one of the less-known but more important approaches: real-time actions. About this, I want to share an abstract of the interview with Massimiliano Balbo di Vinadio , vice president of sales LA at Targa Telematics , one of the members of the IoT Insurance Observatory .

MC: What is Targa's history, and how did the journey lead to the acquisition of Viasat?

MBV: "Targa Telematics is a technology leader with over 20 years of experience in developing cutting-edge solutions that help businesses, organizations, and communities fully leverage the Internet of Things and AI. The company offers a wide range of software solutions for vehicle rental companies, financial institutions, insurance companies, brokers, and large fleet managers. These include insurance telematics, fleet management, and asset management solutions.

In 2006, the company acquired Targa Infomobility from Fiat Auto, which specialized in infomobility services, satellite anti-theft systems, and fleet management. In 2012, Targa Drive was established to provide insurance companies with telematics solutions.

In 2023, Targa took a significant step by acquiring the Viasat Group, expanding its presence in key European markets such as Italy, France, Portugal, Poland, Romania, Spain and the U.K., but also in Chile. This acquisition strengthened its position in the insurance market, allowing Targa to offer advanced telematics insurance solutions, meeting the increasing demand for data-driven, personalized insurance.

In January 2024, Targa expanded its telematics portfolio by acquiring Drive It, a spin-off from Earnix. This acquisition has introduced MaaS (mobile as a sensor) functionalities and further strengthened Targa's AI capabilities.

With its extensive experience and continued innovation, Targa Telematics now offers a comprehensive portfolio of insurance solutions."       

MC: Risk prevention has been discussed frequently at the plenary sessions of the IoT Insurance Observatory. What is Targa's experience with real-time feedback to drivers? Can you share any facts and figures about the risk reduction achieved?

MBV: "Risk prevention is a significant topic and Targa Telematics is at the forefront of this. Our experience with real-time feedback to drivers showcases the power of telematics in fostering safer driving behaviors and reducing insurance risk. A standout feature of Targa Drive is its coaching module, which delivers real-time audio notifications to guide drivers during their journeys, helping them adjust unsafe behaviors on the spot. Drivers also receive daily or weekly feedback aimed at improving their driving style and promoting sustainable driving habits over time. This personalized approach has led to significant risk reduction and behavior improvement among our users.

The drivers can be further motivated through metrics on streaks (continuous safe driving days) and trends that offer an objective view of their progress. A customized reward program can be also made available for insurers, allowing them to deliver promotions and incentives tied to the driver's recorded improvement. This helps insurers enhance engagement while fostering a continuous improvement culture among policyholders.

We also see notable success with our windscreen devices, which are equipped with advanced sensors, including GPS tracking, and three-axis accelerometer. These devices collect crucial data for crash management, speed monitoring, geofencing, and emergency call services. The coaching function in these devices, delivered through non-intrusive LED indicators, provides real-time guidance to help drivers improve their habits. Several of our customers have successfully integrated this device into their operations, reducing accident rates and promoting safer driving. On average, customers who have adopted this solution have reported a 30% improvement in their drivers' scores."

MC: What is your vision about the future of auto insurance?

MBV: "IoT and AI are set to revolutionize the mobility landscape and therefore key players such as insurances, leasing and rental companies just to name a few. By focusing on prevention through better driving behaviors, combined with the power of data analytics, the industry can reduce claims frequency and severity, delivering more sustainable and customer-friendly outcomes."

How to Spot Emerging Risks (Really Early)

In this Future of Risk interview, Praedicat founder Dr. Robert Reville explains how it combs the scientific literature to spot risks like talcum powder years before mass litigation happens.  

future of risk


Robert T. Reville

Dr. Robert T. Reville is the CEO and cofounder of Praedicat, the liability risk analytics company.  Praedicat’s risk models are used for underwriting and risk management by leading P&C insurers and global industrials.

Prior to co-founding Praedicat, Bob was Senior Economist at the RAND Corporation, where he conceived and led an R&D project mining the text of peer-reviewed science to identify emerging "next asbestos" risks. The project provided the foundation for Praedicat and Bob traded policy research for start-up life. Bob's research career focused on liability, risk and insurance. He was the Director of the RAND Institute for Civil Justice, a liability research center which published influential research on asbestos; and co-director of the RAND Center for Terrorism Risk Management Policy, which published research on terrorism insurance that was cited in congressional debates over the Terrorism Risk Insurance Act. Bob has also written over a dozen studies on workers' compensation. He received his Ph.D. in economics from Brown University.


Here is the interview transcript:

Insurance Thought Leadership

Congratulations again on being a finalist for the Global Innovation Award. I thought I'd start out by asking you to tell us a bit about what you've been doing at Praedicat.

Robert Reville

Sure. Well, thank you for having us here and for the honor of being a finalist. Praedicat is a liability emerging risk analytics company. We started calling ourselves a casualty catastrophe modeling company back in 2012, and we quickly learned that the industry didn't really understand what casualty catastrophe was. When we explained what it was, that we were an emerging risk modeling company, they said, Oh, well, that makes sense.

We stopped calling ourselves casualty catastrophe back then, though we are returning to it now. Essentially, what we do is we identify emerging risks early, ideally seven to 10 years before litigation can even start. We do it by using AI on scientific literatures. We're trying to find where a scientist is hypothesizing in journal articles that some chemical or product or business activity results in bodily injury or environmental damage. We then we track the science as it evolves into a literature that can potentially be used in litigation as scientific evidence.

Once the science gets to a certain critical mass, we model the potential litigation that could emerge. We convert the model into company profiles, and we sell it as a SaaS [software as a service] product to insurers, who use it for underwriting, exposure management and, increasingly, for informing pricing and reserving and the like.

Insurance Thought Leadership

You had some pretty impressive examples of how many years you were ahead of a number of issues that are cropping up, like talcum powder. Do you want to talk about a few of those?

Robert Reville

Sure. When we were first launching our product, which was in 2013, the system already had in it the PFAS chemicals and talc and Roundup and chlorpyrifos. All of those are in litigation today, but the litigation started really after we launched. And every mass litigation that has started since 2013, when we launched our product, was in our system before the litigation began.

Some of them were completely off the radar screen of the industry. Sometimes, there's already a certain amount of buzz around something, and it, you could argue, is not that hard to catch. But there were some things that we caught that no one was thinking about, and then litigation started shortly thereafter. And we were found to really have delivered some useful early warnings.

Insurance Thought Leadership

There were a couple you mentioned that I'm curious about, that you say are in the pre-litigation phase now. There's one whose name I can't pronounce: phthalates.

Robert Reville

Right.

Insurance Thought Leadership

You'll say it right. And microplastics. I wonder if you could talk a little bit about those.

Robert Reville

Sure. Phthalates is a chemical that is an additive to plastics, typically added to polyvinyl chloride, which I think is possibly the most widely used plastic. It essentially makes polyvinyl chloride softer and flexible. So it's used in medical tubing. It's used in toys, things like rubber duckies. It's used in food packaging. It's used in all kinds of consumer packaging. 

It's so widely used, in fact, that it recently started to be called the everywhere chemical. Everybody is talking about forever chemicals for the PFAS. The everywhere chemicals are the phthalates. 

Recently, at the end of 2022, litigation started over hair relaxers, alleging that people who have their hair straightened frequently, that the chemicals that are put on their scalp, that they get into the bloodstream and can lead to uterine cancer. The scientific literature around these hair relaxers is pretty small, probably not strong enough to support litigation, but the plaintiffs’ attorneys have put in their complaints about the ingredients that go into the hair relaxers, and the number one ingredient that they highlight is phthalates.

What the plaintiffs are arguing is that it's the phthalates in the hair relaxers that cause the uterine cancer. The science is a little bit stronger about that than it is about the hair relaxers themselves.

Insurance Thought Leadership

To probe a little bit on that. When you spot something like this, insurance companies are buying this information from you, and they're changing how they underwrite? Or what exactly happens once you identify a problem like this potential one?

Robert Reville

When an insurance company works with us, the first thing they normally do is they take their casualty book of business and they enter it into our system. We model it, and we identify the exposure to all of the emerging risks in their portfolio. 

A typical situation would be, let's say, a particular company runs their model, and we find that the number one emerging risk in their portfolio is phthalates. At that point, they'd say, Oh, we need to control our total exposure to phthalates. So they develop an underwriting strategy that says, Well, if it's a chemical company, then we don't want to write that any more.

Then if there’s a downstream user of the chemical, such as a metal tubing manufacturer, we have a referral process. We want to evaluate the way the company handles the chemical, and then we want to control our total aggregations. 

All that data flows into an underwriting strategy, and then the underwriters at the company will follow the instructions that go with the strategy. So they have a new submission or a renewal, and they call up [the instructions]. They see that there's exposure to phthalates. There's either an exclusion required or a referral, and then when [a policy] is actually written, it goes into the exposure management system to control the total aggregation. That's an example.

Insurance Thought Leadership

Okay. So I cut you off. You were saying….

Robert Reville

Well, I was about to say that the question on phthalates in hair relaxers is, if the science has accepted that the phthalates are causing the uterine cancer, then what we expect is that it'll spread from hair relaxers to all these other uses. Then we'll have a full-on, everywhere chemical litigation that's happening at the same time we have the forever chemical litigation. That's potentially a worrisome situation for casualty insurance. 

Insurance Thought Leadership

Okay. And then microplastics?

Robert Reville

Microplastics are the breakdown particles as plastics degrade in the environment. And, as I mentioned, we track science from the time of the early studies as an early warning system. The literature around microplastics has grown faster than any literature we have been tracking since the beginning of Praedicat. There are now about 15,000 studies published that are examining the impact of microplastics in the environment, the way in which microplastics can enter the body, the way in which they're carried by weather around the globe, where they go once they enter the body, how they end up in the brain. 

Recently, there was a study that actually was looking at how microplastics, which are in the atmosphere primarily in urban areas because of tires -- they come off of tires – actually attract water vapor at different temperatures than clouds normally form at. They start to form clouds and can change weather patterns.

The extent of impact of microplastics in the environment is so great that the potential avenues for litigation being identified in the scientific literature are pretty enormous. We think the impact could come out in many different ways and are working with our clients around exactly how to think about where the exposures might be. There has been some litigation, nothing insurance-relevant yet, but consumer litigation and the like. We are seeing 65 cases in the U.S. courts right now…. We can start to get a sense of who the defendants might be and start to work with our clients early on what their total exposure might be.

Insurance Thought Leadership

That's fascinating. Any other things we ought to be watching for?

Robert Reville

Well, we have 300 in our system. 

I would say that another area that is worth talking about is generally climate. Climate is an area where there has been some litigation. In particular, there are about 50 cases in the U.S. courts, typically brought by states’ attorneys general, and they are alleging that, typically, oil and gas companies have caused climate change. Those cases are really the first wave of potential litigation over climate. And when we say climate, we expect there's going to be potentially litigation over what caused climate change. That may also be followed by litigation over failure to protect against the consequences of climate change. We've already seen some of this. 

I'll give you a quick example, though, of the kinds of unexpected things that will happen as a result of climate change. The scientific literature, in the mid-2010s, about 2015 or 2016, started to identify this issue that increasing droughts and increasing heat were causing concentrations of arsenic in soil. Rice plants tend to pick up the arsenic from the soil, and so some scientists started to argue that because of the fact that baby food uses rice as its backbone, that there would be litigation over elevated levels of arsenic in rice in baby food. We actually caught that literature and highlighted it to our clients before the litigation began. Then in 2021, a congressional report came out looking at heavy metals in baby food, specifically identifying elevated levels of arsenic, and the litigation was off to the races. 

It's still going on. There are, I think, both baby food manufacturers and retailers named as defendants. There are, I think, over 100 defendants so far, thousands of cases, and we'll see where it goes. But the interesting thing is all that was caused essentially by the changes in the environment from climate change.

You could argue that's the first product liability that resulted from climate change. Those kinds of things, we expect to see more of. 

We're also doing a lot of work on potential liability consequences after urban heat waves. Scientists have argued that in coming years the potential is for there to be heat waves that are worse than anything we've ever seen. If combined with blackouts, there could be a large amount of deaths in urban areas. Given those types of models, we have looked at the potential liability consequences for companies that would arguably have been responsible for taking care of vulnerable parties. So nursing homes, schools, day cares, etc., also habitational real estate. 

This is a phenomenon that hasn't yet happened, but it's worth working through the liability consequences, given the projections coming from the climate scientists. 

Insurance Thought Leadership

Great. A bunch more reasons for me not to sleep at night. 

Thanks for taking the time. Congratulations on being a finalist, and I'll be fascinated to follow your work.

Robert Reville

My pleasure.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Uncertainty Is the New Normal

Uncertainty is at a generational high in almost every aspect of our lives, creating major challenges -- and opportunities -- for insurers.

A large teal blue wave starting to crash into the sea against a blue sky background

Until recently, it was said that the only constant was change – now the only constant is uncertainty. 

Uncertainty is at a generational high in almost every aspect of our lives: socially, financially, politically, and technologically. One of the most serious consequences of this uncertainty is its impact on risk assessment across all lines of insurance. However, it also represents a major opportunity for insurers.  

The model of risk transfer is centuries old and thrives on predicting when and how much known exposures are likely to happen and what the costs involved are. Thus, not all risks are insurable -- such as moral hazards where the incentives are misaligned. Risk transfer is further disrupted when doses of uncertainty distort predictive models.  

Uncertainty exists when the magnitude (frequency and severity) of possible future events is obscured, making reasonably accurate forecasts unreliable. As uncertainty grows, the ability to effectively manage risk is proportionally reduced.

The implications of this new normal for insurance are existential for some insurers and more expensive for all, as it becomes harder to assess and properly price risk in the face of so much uncertainty. Not to mention the havoc that uncertainty wreaks for most consumers and businesses, including on insurers’ ability to plan and adjust. A result is uncertainty about insurance availability, degree of premium increases and extent of reduced coverage.

To make matters worse, several carriers seeking to contain risks have been withdrawing from regional markets where recent losses have unexpectedly spiked as a result of unprecedented losses from extreme weather exacerbated by ill-prepared mitigation. These pullbacks, which already target approximately 15% of U.S. property, are not only detrimental to policyholders in the affected regions but also undermine the benefits of risk pooling for all policyholders.     

Yet the idea of insurance is to provide a promise of protection and safeguard against uncertainty. This goes beyond the functional insurance contract and strikes an emotional nerve, as well – peace of mind. The proverbial security blanket serves in more than one way, and the industry will hopefully find the right balance.

Trade/Geopolitical Uncertainty

In the wake of President Trump’s on-again, off-again, up-again, down-again trade tariff announcements – and the retaliatory counter tariffs from the world’s largest countries – economic uncertainty has evolved almost overnight. Markets are similarly volatile, prompted by the uncertainty of how far tariffs and reciprocal action will go. At present, we are now officially in a stock market correction, in which a stock market index drops by more than 10% and indicates pessimistic investor sentiment.

Facing unexpected market volatility and geopolitical uncertainties, normally optimistic dealmakers are sounding a more cautious note for the coming weeks and months but are confident the pace of mergers and acquisitions will pick up later this year.

The costs associated with auto and property insurance are especially exposed to tariff impacts, including increased cost for new and used vehicles, repairs and replacements parts. Bob Passmore, department vice president of personal lines at APCIA (American Property Casualty Insurance Association, the primary national trade association for home, auto, and business insurers), estimates that the impact of tariffs on personal auto insurance could range from $7 billion to $24 billion.

Undoubtedly, even higher premiums will follow quickly, and the insurance protection gap will continue to widen should retaliatory tariffs actually stick. Either way, insurers are watching loss costs closely.

Consumer Sentiment

Consumers sentiment is down significantly month-over-month and year-over-year. It slid nearly 10% from January and fell for the second straight month. The decrease was unanimous across groups by age, income, and wealth. The Consumer Sentiment Index fell to 64.7 in the February 2025 survey, down 9.8% from 71.7 in January and 16% below last February’s 76.9.

Consumer sentiment is considered a leading indicator of economic activity. Sentiment levels can also affect consumers’ willingness to make large purchases such as automobiles. Over the last 18 months, policyholder behavior has changed around smaller losses. They forgo making claims for fear of premium increases or select higher deductibles and drop coverages. Meanwhile, credit card debt is over $1.21 trillion; negative equity in auto loans has reached a record, and late payments are on the rise.

Executive Stress

More than two-thirds of executives polled in a recent survey reported feeling more stressed at the beginning of 2025 than they did at the start of 2024. The survey, conducted by Wakefield Research on behalf of Sentry Insurance, found stress levels elevated in 67% of participants. At the same time, 74% of executives said they were not completely confident that their company’s current insurance coverage is adequate.

Economic uncertainty (47%), supply chain challenges (44%), costs of employee health care (41%), labor shortages (38%) and inflation (36%) ranked as the top five concerns among the survey participants.

Extreme Weather Uncertainty

The continuous increase in extreme weather events, and the attendant economic and human losses, are not new but are being made worse by what is now emerging as compound weather events. Cascading extreme weather events are unleashing billions in additional damages. This was clearly and tragically witnessed from the LA area wildfires, where fire prevention and responses proved shockingly inadequate. Add in regulatory rate suppression, and this becomes an untenable scenario.  

More than 100 fires ignited in South Carolina, Oklahoma and New York last weekend, fueled by a combination of arid air, dry fuels, and gusting winds, all compound weather events. We have much less data and research on these so-called secondary weather perils as compared with hurricanes. And convective storms have proven to be more challenging to translate into risk management.

Researchers and experts warn that the frequency and impact of compounding events will increase and that developing better models and preparedness strategies is crucial to mitigate the risks ahead, with some looking to Japan's earthquake preparedness culture and massive investment as a potential model.

Managing Uncertainty in Insurance

Even in periods of extreme uncertainty, there are several strategies available to carriers aside from rate actions.

Rising catastrophe losses, technological transformation, and evolving risk landscapes are forcing insurers to fundamentally rethink their approaches to underwriting, claims processing, and customer engagement, according to Datos Insights.

Insurers can diversify their portfolios to reduce the impact of any single line. At present, profitable auto lines are now highly coveted as competition has surged. Just a couple of years ago, insurers were shedding personal lines policies, as rates could not keep pace. Auto insurance lines are now forecast to have favorable loss ratios through 2027. The advantage goes to carriers growing their auto books profitably with rate-friendly tailwinds.

Excess and surplus lines grew 12%, reaching $81.6 billion in premiums last year, further demonstrating diversification opportunities. Similarly, the MGA distribution model expanded hand-in-glove, serving specialized markets and regions such as coastal exposed areas.

Carriers have always used sophisticated pricing and underwriting models, and the application of AI is expected to make them even better when it comes to ingesting more data and testing risk models -- as in digital twin comparisons and visualizing impacts well beyond just numbers on paper. This is extremely valuable in projections because historic models look backward to look ahead.

Likewise, investing in claims is a priority as worthy efforts to streamline are balanced with controlling loss costs at a time when adjuster resources are squeezed from retirement “brain drain” at the most skilled levels. Technology investment must go beyond core system upgrades to greater digitization while orchestrating the multitude of new tools, integrated provider partners and the numerous insurtech opportunities circling the tower and waiting for a landing spot.

New insurance products, high consumer awareness translating to greater insurer/policyholder engagement and joint risk management are evolving and opportune. 

Now more than ever in our insurance history, greater resilience and innovation coupled with a transition to a Predict & Prevent defensive posture is critical and urgent. 


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.

What Trump's Tariffs Could Do to Insurers

Michel Léonard, the Triple-I's chief economist, remains an optimist on the U.S. economy but warns that "we're in an environment of extraordinary uncertainty."

Michel Leonard ITL quarterly interview

Paul Carroll 

Things are so crazy in Washington DC these days that I can’t ask you for the sorts of precise predictions on inflation, GDP, prospects for the insurance industry, etc. that we usually discuss. What passed for U.S. economic policy this morning could be rather different by this afternoon. So I’ll ask you, more generally, what key trends we should watch out for in terms of the effects of tariffs and in terms of the broader economy.

Michel Léonard

Yes, while our conversations are generally pretty evergreen, I’ll note that we’re talking on March 7th at 1:00 PM Eastern time, which is relevant given yesterday's announcement about suspending some tariffs on Canada. Let me outline where we stand and the key baselines we should consider.

Regarding the economy, while growth has been diminishing, the economy has remained resilient. The key question now is whether this resilience is sufficient to survive the current instability and uncertainty. As of this first quarter, I believe we still have enough GDP momentum to weather what we're seeing now, even if these conditions continue for a full quarter. However, the risk of GDP contraction rather than growth is certainly present.

On inflation, we've seen it coming down to sustainable levels, which we define as 2% to 3%. The Fed has indicated it will tolerate inflation up to 3% before taking action. Looking at the baseline for interest rates and monetary policy over the next year, the trend line remains accommodative, with two main concerns: inflation resulting from tariffs and potential policy misjudgments. 

As [former Fed Chairman Alan] Greenspan used to say, the medication must fit the disease. It's important to remember that rising interest rates are effective when inflation is driven by consumption. Higher interest rates can drive down demand. However, when inflation is driven by tariffs or other factors related to consumption, raising interest rates doesn't work.

We're likely to see inflation hovering between 2.5% and slightly above 3%, without factoring in geopolitical risk. Continued geopolitical risk will put upward pressure on inflation. 

Looking at the big picture for the economy, I still see this year being resilient, ending with flat to slightly positive growth.

Paul Carroll

The Atlanta Fed recently forecast a potential 2.5% to 3% annualized decrease in GDP for the first quarter. Is that an outlier, or might that be correct?

Michel Léonard

When considering benchmarks for comparison, I think back to the first year of COVID, when we faced tremendous uncertainty around March 2020 regarding GDP projections. Firms like JP Morgan and Goldman were suggesting potential contractions of up to 30% -- numbers that were unprecedented but that made sense given the unique circumstances.

We're again in an environment of extraordinary uncertainty. We may be getting tired of describing everything as unique and new, but this situation truly is, perhaps even more so than before. 

At this point, I don't think we can clearly distinguish where performative policymaking ends and where the real impact on growth and growth expectations begins. Just yesterday, we saw another 30-day postponement in the imposition of tariffs, and there's fatigue around that. The market today is hovering flat after one of the worst weeks in a year, and there's fatigue there, too, as we would expect. While I traditionally focus on the real economy as an economist, my current concern is market sentiment.

The resistance in the market that keeps prices from going even lower stems from those of us who remain optimistic about growth this year -- and there are fewer and fewer of us on the optimistic side. Each time there's a performative announcement, the market's recovery within the following days becomes less robust. 

That exhaustion could lead to the Atlanta Fed's -2.5% projection happening for the full year, but that would require a very significant correction in this quarter and next quarter, and I don't think we're there. I don’t think that sort of contraction in the first quarter alone is possible. 

Paul Carroll

How much do you think Trump’s tariffs could drive up replacement costs, which have been such an issue for insurers in recent years?

Michel Léonard

Double-digit tariffs are not marginal adjustments. They're not about moving production -- they're about stopping production entirely.

Let me break this down step by step. First, as a baseline, we can look at what we experienced during COVID. Certain segments of the economy and insurance were particularly affected -- especially the auto sector. Due to supply chain issues, used auto prices soared. Interestingly, autos and motor vehicles are also key targets of potential current and future tariffs, so there should be some parallel with the COVID situation.

The impact of tariffs is already visible through uncertainty alone. People are already changing their purchasing decisions regarding cars. For example, in Canada, buying patterns are shifting. I'm originally from Canada, and my brother, who owns two American cars and was considering a third, suddenly changed his mind about buying another American vehicle. Similarly, bourbon producers in Kentucky are seeing demand drop because Ontario's liquor board, the world's largest buyer of alcohol, followed by Quebec, is already making different purchasing decisions.

For motor vehicles, we will inevitably see a significant drop in underlying growth, even if tariffs are suspended indefinitely, because the uncertainty is already present. This affects replacement costs for parts and repairs, though less so for labor. During COVID, replacement costs for motor vehicles -- both personal and commercial -- rose around 60%, largely due to used auto prices. I could see this happening again, following a similar timeline.

Ultimately, I believe we'll retain some version of Auto Pact, the predecessor to NAFTA. We'll likely end up with a cosmetic renegotiation -- remember, the current North American free trade agreement was negotiated by President Trump. The real question is timing -- whether it takes one month, three months, or six months. Insurance underwriters and industry professionals should be prepared for increases that could approach those COVID-era numbers for motor vehicles, the longer this situation persists.

And these double-digit increases in tariffs on lumber, auto parts and other materials don't just mean higher replacement costs – they mean many materials aren't available through the supply chain.

During COVID, lumber was still available, but we just couldn’t get auto parts and used cars. Now, we need to anticipate that goods will be stuck in transit at borders, creating significant delays. For people on both sides of the transaction – whether it's carriers handling rebuilding and repairs or homeowners getting their properties repaired – the issue is going to be time. We'll likely see more delays and uncertainty than we did during COVID.

Paul Carroll

I suspect we’re just getting started on the effects of these policy changes and all the uncertainty that surrounds them. Even if Trump’s protectionism proves short-lived – and I’m not sure it will – companies will have to rethink their global strategies. That could cause major changes to supply chains… and the companies that insure them.

Michel Léonard

As an American who immigrated from Canada, I've been shocked by how seriously other countries are taking these developments on protectionism. Those of us looking at this professionally know these are serious issues, but we also see a performative form of policymaking.

Those of us in the U.S. lived through the changes during the first Trump term, but it doesn't seem the rest of the world experienced it the same way we did. I've been surprised by that, and I think it's significant in terms of the damage done. It's quite difficult to imagine that the same level of trust will remain, for better and for worse. 

There are certain areas where change is good, and even if it's constructive destruction, sometimes it is useful. But I do think there is a great deal of damage. 

Paul Carroll

Do you see any historical parallels to what we’re going through?

Michel Léonard

What we're facing is potentially comparable to Margaret Thatcher's first two years as prime minister in the U.K. When Thatcher came in, she cut government spending, privatized industries, and moved extremely rapidly. She was actually on track to lose her position until the Falklands War came about and allowed her to recover politically. During this period, the U.K. experienced one of the deepest recessions since World War II.

That's the kind of economic pain we could be talking about here, but potentially on an even larger scale because it's the U.S. The agenda we're seeing now is even more transformative. The individuals involved in the current administration are much more like outsiders compared with those in Thatcher's administration, which makes this an even more striking parallel.

We're potentially looking at unemployment reaching high single or double digits, which in the U.S. has rarely happened since the Great Depression. This is why I'm concerned about the scale of transformation. We're not just looking at a typical stock market correction of 5% or 7% -- we're potentially looking at something that combines the impact of all previous corrections together. 

I haven’t given up. I’m still an optimist. But the potential implications go far beyond simple replacement costs, and that's what makes this situation particularly challenging.

Paul Carroll

Thanks, Michel. Fascinating, as always. 


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.