Download

Data Science: Methods Matter (Part 4)

Putting models into production is the fun part -- but requires not only testing but also a plan for monitoring and updating as time goes on.
|
Putting a data science solution into production after weeks or months of hard work is undoubtedly the most fun and satisfying part. Models do not exist for their own sakes; they exist to make a positive change in the business. Models that are not in production have not realized their true value. Putting models into production involves not only testing and implementation, but also a plan for monitoring and updating the analytics as time goes on. We’ll walk through these in a moment and see how the methods we employ will allow us to get the maximum benefit from our investment of time and effort. First, let’s review briefly where we’ve been. In Part 1 of our series on Data Science Methods, we discussed CRISP-DM, a data project methodology that is now in common use across industries. We looked at the reasons insurers pursue data science at the first step, project design. In Part 2, we looked at building a data set and exploratory data analysis. In Part 3, we covered what is involved in building a solution, including setting up the data in the right way to validate the solution. Now, we are ready for the launch phase. Just like NASA, data scientists need green lights across the board, only launching when they are perfectly ready and when they have addressed virtually every concern. See also: The Science (and Art) of Data, Part 2   Test and Implement Once an analytic model has been built and shown to perform well in the lab, it’s time to deploy it into the wild: a real live production environment. Many companies are hesitant to simply flip a switch to move their business processes from one approach to a new one. They prefer to take a more cautious approach and implement a solution in steps or phases. Often, they choose to use either an A/B test and control approach or a phased geographic deployment. In an A/B test approach, the business results of the new analytic solution are compared with the solution that has been used in the past. For example, 50% of the leads in a marketing campaign are allocated to the new approach while 50% are allocated to the old approach, randomly. If the results from the new solution are superior, then it is fully implemented and the old solution removed. Or, if results in one region of the country look promising, then the solution can be rolled out nationwide. Depending on the computing platform, the code base of the analytic solution may be automatically dropped into existing business processes. Scores may be generated live or in batch, depending on the need. Marketing, for instance, would be a good candidate to receive batch processed results. The data project may have been designed to pre-select good candidates for insurance who are also likely respondents. The results would return an entire prospect group within the data pool. Live results meet a completely different set of objectives. Giving a broker a real-time indication of our appetite to quote a particular piece of business would be a common use of real-time scoring. Sometimes, to move a model to production, there’s some coding that needs to happen. This occurs when a model is built and proven in R, but the deployed version of the model has to be implemented in C for performance or platform considerations. The code has to be translated into the new language. Checks must be performed to confirm that variables, final scores and the passing of correct values to end-users are all correct.  Monitor and Update Some data projects are “one time only.” Once the data has appeared to answer the question, then business strategies can be addressed that will support that answer. Others, however, are designed for long-term use and re-use. These can be very valuable over their periods of use, but special considerations must be taken into account when the plan is to reuse the analytic components of a data project. If a model starts to change over time, you want to manage that change as it happens. Monitoring and updating will help the project hold its business value, as opposed to letting its value decrease as variables and circumstances change. Effective monitoring is insurance for data science models. For example, a model designed to repeatedly identify “good” candidates for a particular life product may give excellent results at the outset. As the economy changes, or demographics change, credit scoring may exclude good candidates. As health data exchanges improve, new data streams may be better indicators of overall health. Algorithms or data sets may need to be adapted. Minor tweaks may be needed or a whole new project may prove to be the best option if business conditions have drastically changed. Monitoring the intended business results compared with results at the outset and results over time will allow insurers to identify analysis features that no longer provide the most valid results. See also: Competing in an Age of Data Symmetry Monitoring is important enough that it goes beyond running periodic reports and having hunches that the models have not lost effectiveness. Monitoring needs its own plan. How often will report(s) run? What are the criteria we can use to validate that the model is still working? Which indicators will tell us that the model is beginning to fail? These criteria are identified by both the data scientists and the business users who are in touch with the business strategy. Depending on the project and previous experience, data scientists may even know intuitively which components within the method are likely to slide out of balance. They can create criteria to monitor those areas more closely. Updating the model breathes new life into the original work. Depending on what may be happening to the overall solution, the data scientist will know whether a small tweak to a formula is called for or an entirely new solution needs to be built based on new data models. An update saves as much of the original time investment as possible without jeopardizing the results. Though the methodology may seem complicated, and there seem to be many steps, the results are what matter. Insurance data science continually fuels the business with answers of competitive and operational value. It captures accurate images of reality and allows users to make the best decisions. As data streams grow in availability and use, insurance data science will be poised to make the most of them.

John Johansen

Profile picture for user JohnJohansen

John Johansen

John Johansen is a senior vice president at Majesco. He leads the company's data strategy and business intelligence consulting practice areas. Johansen consults to the insurance industry on the effective use of advanced analytics, data warehousing, business intelligence and strategic application architectures.

What Next After Fatal Tesla Crash?

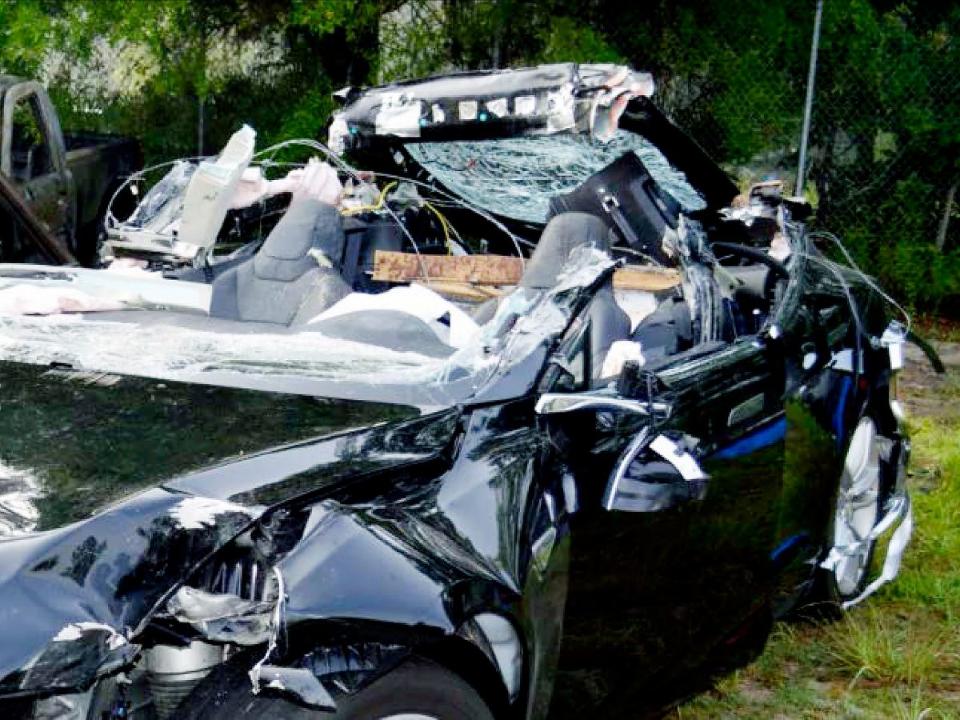
Despite the crash and considerable trepidation, the author soon found himself trusting his Tesla to drive while he attended to email.

|
At first, the thought of letting my car drive itself seemed frightening. But the highway was almost empty, and the lanes were clearly marked, so I took the risk and engaged the autopilot function in my new Tesla Model X. Yet I couldn’t let go of the steering wheel. I didn’t want to put my life in the hands of software. This was two weekends ago as I drove to Big Sur, Calif. The fear lasted about five minutes. Curiosity got the better of me, and I let go of the steering wheel to see what would happen. The car continued to drive just fine; it didn’t need me. After a couple of minutes, the car beeped and displayed a message on the dashboard asking me to put my hands back on the wheel — a feature the automaker added to ensure drivers were in the front seat and attentive. But 20 minutes later, I had one hand on the wheel and was checking email with the other as the car did the driving for me. I did take full control when the road was narrow or the terrain was uneven, but, by and large, I became as comfortable with the car’s autosteer function as I am with cruise control. Yes, self-driving cars pose new risks, as evidenced by the recent fatal crash in Florida, when a Tesla in autopilot mode hit a large truck that crossed its path. The Tesla software cannot handle local roads, intersections or extreme hazards yet. There are limits to every technology. It is the same scenario as using cruise control on local roads — you just shouldn’t do it. Three out of four U.S. drivers have the same fears I did, according to a AAA survey. The same survey revealed that only one in five would actually trust a driverless vehicle to drive itself with them inside. I have no doubt, however, that, once they get behind the wheel of one, they, too, will be checking email as I did. They’ll feel as comfortable with software driving their cars as they are with software flying their airplanes. See also: Is Driverless Moving Too Fast? Tesla calls its software “autopilot,” but it really is nothing more than cruise control on steroids. The autosteer function keeps the car in its lane, reads road signs, drives as much over the speed limit as you ask and slows or stops if there is a slower vehicle or obstruction ahead. If you want to pass someone, you engage the turn signal, and the car will move itself to the adjacent lane when it can. I found this to be safer than changing lanes myself because of the blind spots. The advantage the Tesla has is that it can see in all directions at the same time. It literally has eyes in the back of its head. I also learned how self-driving cars could prevent accidents when a car jumped into my lane just as the setting sun blinded me. My car automatically slowed down and gave way. No, it didn’t honk. Self-driving cars will improve our lifestyles and make the world smaller. They will prevent tens of thousands of fatalities every year. The best part is that they will do to pesky, dangerous human drivers what the horseless carriage did to the horse and buggy: banish them from the roads. Software malfunctions will surely cause unfortunate accidents along the way. There will also be ugly public debates, efforts by incumbent businesses to create legislative barriers and a lot of confusion. But the technology is coming — whether we are ready or not. And I for one can’t wait to receive the software upgrades that will let the car do all of the driving. I look forward to enjoying the scenery or working during my commute. See also: 7 Wonders of the Driverless Future If political leaders and lawyers in the U.S. try to stop progress — as is very likely — other countries will still adopt the new technologies and take the lead. We will end up playing catch-up with the rest of the world and miss out on the most amazing transition of our lifetimes.

Vivek Wadhwa

Profile picture for user VivekWadhwa

Vivek Wadhwa

Vivek Wadhwa is a fellow at Arthur and Toni Rembe Rock Center for Corporate Governance, Stanford University; director of research at the Center for Entrepreneurship and Research Commercialization at the Pratt School of Engineering, Duke University; and distinguished fellow at Singularity University.

The Start-Ups That Are Innovating in Life

Start-ups such as LifeDrip and Smart Asset are going after distribution, product, client experience, speed, productivity and more.

|
In my last post, I provided categories within which to organize the innovation players within life insurance. Both start-ups and legacy businesses are pursuing solutions to industry pain points. Attention is being paid to distribution, product, client experience, speed, productivity, big data, compliance and other areas within the life category where inefficiency exists or where client needs are not met today. The very complexity of life insurance will be a deterrent, at least in the near term, to the volume of innovations versus what we have seen in other areas of InsurTech. Much of the innovation, including the examples presented here in my April post, aim at specific issues with the current model for life insurance, versus taking a clean-sheet approach. Entrants into the space aim to solve adviser problems, become the new intermediaries between the carriers and the client or assist the carriers themselves. For their part, carriers are funding and leading transformation efforts. They know they must adapt, but because it’s almost impossible to drive massive change from within an established business model and culture, it is likely that start-ups creating differentiated value that avoid becoming mired in complexity can do well. Here are examples of opportunities: Adviser conversations will move from the kitchen table to digital channels. The Global Insurance Accelerator aims to drive innovation in the insurance industry. Of note in GIA’s 2016 cohort is InsuranceSocial.Media, a tiered offering that automates adviser participation in social media. Based on a user-defined profile, advisers are provided with algorithm-driven content that they can distribute via their social media identities. Hearsay Social is a more evolved startup also enabling adviser social media. The company boasts relationships with seven out of 10 of the largest global financial services companies, among these New York Life, Pacific Life, Farmers and AXA. Hearsay addresses the compliance requirements that carriers have so their advisers can participate in social media: (1) archiving every instance of social media communication and (2) monitoring all adviser social conversations, intercepting compliance breaches. While not sexy, this capability is critical and commands C-suite attention. An early-days market entrant also targeting adviser digital presence, LifeDrip claims to offer an automated marketing platform, including a personalized agent site, targeted content, signals on client readiness to buy and product recommendations. Advisers as intermediaries are unlikely to disappear any time soon, but their role, engagement approach and capabilities must be more tech-savvy to appeal to virtually any consumer segment in this market with buying power. Expect additional new entrants that continue not to write off live intermediaries, and bring to market solutions to reshape the adviser relationship. See also: How to Turn ‘Inno-va-SHUN’ Into Innovation The new intermediaries are digital. Smart Asset promises to simplify big financial decisions, including the purchase of life insurance, with an orientation toward how people make these decisions vs. pushing product. Shoppers can input data to a calculator and determine a coverage target; they are then encouraged to request a quote from New York Life. Smart Asset’s experience will be more credible when it includes multiple providers. It will require marketing investment to scale participation. Its basic approach could appeal to a large segment that will demand simple, low-cost product. PolicyGenius has developed a consumer-friendly interface including instant quotes for life, as well as pet, renters and long-term disability insurance, following completion of an “insurance checkup.” As with other start-ups, this is a data-gathering exercise undoubtedly important to the company’s business model. AXA is an investor in PolicyGenius; the site promotes several major carriers as product providers. Slice Labs is worth calling out because it is a direct-to-consumer play defining itself against a specific, important market segment – the 1099 workforce whose growth is being stimulated by the “on-demand economy.” Think not only about the Uber and Airbnb phenomena, but also the reality of more Americans moving away from traditional employer relationships where automatic access to benefits was a given. Carriers will be viewed as start-up clients. All of the companies mentioned already focus in and around the acquisition of new clients. InforcePro offers an automated solution for agents and carriers providing insights into sales opportunities and potential risks that exist within their current books. Why does this matter? Insurance contracts are inordinately complex – even for the experts. Carriers and agents, particularly in recent years, have been forced to focus more heavily on maximizing the performance of the policies they have issued, versus just trying to sell more. The focus on the relationship with the policyholder has been skimpy. Life insurance policyholders can cancel a policy but cannot be “fired,” and represent continuing exposure, as their future claims can be on the carrier’s balance sheet for decades. With the risks and potential value now more obvious, in-force management has become a priority for focus and investment. See also: Start-Ups Set Sights on Small Businesses Carriers will drive efforts to innovate beyond incremental moves. Haven Life owned by Mass Mutual but operated separately is a digital business whose product line is term life up to a $1 million benefit. The company operates in more than 40 states and represents a bold move for a 165-year old carrier. Nerdwallet rates Haven’s pricing as “competitive” – not the cheapest but well within range. What is interesting about Haven is that it is not just implementing a shift of the same old approach to digital channels: Quotes are available in minutes, and coverage can become effective immediately, with the proviso that medical testing be completed within 90 days of policy issuance. In this space, this approach represents meaningful experience innovation. Last year, John Hancock initiated an exclusive relationship in the U.S. with Vitality, marketing a program that gives rewards to clients who demonstrate healthy habits such as having health screenings, demonstrating nutritious eating habits, getting flu shots and engaging in regular exercise. Rewards range from cash back on groceries to premium reductions. This program is strategically significant because it aims at prevention, not just protection, linking preventative behaviors that clients control to cost savings. Numerous carriers are participating in innovation accelerators, establishing their own incubators or forming dedicated venturing and innovation units. It remains to be seen which of these are what a colleague refers to as “innovation theater” and which are for real -- drivers of new business opportunity. As with any early-stage plays, their stories will emerge over years, not quarters.

Amy Radin

Profile picture for user AmyRadin

Amy Radin

Amy Radin is a strategic advisor, keynote speaker, and Columbia University lecturer focused on why transformation succeeds or stalls in large, complex organizations. 

Drawing on senior leadership roles at Citi, American Express, and AXA, including one of the world’s first corporate chief innovation officer roles, she helps leaders build the capabilities required to absorb, scale, and sustain change.

Learn more at amyradin.com.


Insurance Innovation: No Longer Oxymoron

Life insurance, long a laggard, presents three main opportunities for innovation, and there are signs of, well, life.

|
While most insurance technology start-up activity in the U.S. is concentrated in health and auto, there are signs of life (pun intended) in the life insurance sector. Given the business model challenges reported in my last post, optimists will see upside and big commercial white space throughout the ecosystem. People with the skills, smarts and guts to envision how life insurance could work can lead the sector in new directions. Life insurers ignore the facts at their peril. According to the 2014 Insurance Barometer survey cited in AM Best – Buying Insurance: Evolving Distribution Channels, 83% of consumers would use the internet to research life insurance before purchasing a policy if they had the option. While face-to-face contact with an agent remains the preferred purchase channel, nearly one in four said that given the option they would prefer to research and purchase online. This year’s Insurance Barometer update reports an improving marketplace for life insurance, citing favorable millennial generation attitudes and people’s willingness to share data in exchange for better product pricing. A check-in on what is happening suggests three groups of potential innovation generators emerging:
  • New entrants developing client-centric offerings sitting between the carrier and the client, displacing traditional agents with a digital experience model
  • Start-ups providing B2B solutions to carriers or distributors, addressing pain points in the traditional product and sales model
  • Carriers themselves, a number of whom are experimenting either in the market themselves or via investments in start-ups or accelerators
This post assesses these three sources of innovation. Tomorrow’s post will highlight players across these categories. New entrants can change the game … and that will take time A big beef with the traditional life insurance model is that it is not client-centric. Nonetheless, even the most change-resistant executives will at least nominally agree that a focus on the client is now essential. From that consensus, though, all bets are off with regard to incumbents’ ability to transform from a model where many of the industry’s own employees believe that the agent is the client, to one where the client (i.e., the person purchasing the insurance product) and his or her needs drive the business strategy. It is almost impossible for a time-tested, embedded culture to accomplish a 180-degree pivot, so it's more likely that successful models of client-centricity will come from outside. See also: InsurTech Can Help Fix Drop in Life Insurance New entrants who succeed will:
  • Establish presence and meaning for their brands among client segments whose unmet needs can be supported by the business model, creating differentiation and marketplace advantage.
  • Extract insight from wide sources of data, many not used at all today within the industry, to drive product development, client segmentation, personalized offers and communications, a client journey built upon new models for distribution, servicing, payments and account management, or a pivot from protection to prevention - all with heavy focus on digital possibilities
  • Avoid naivete about the inherent complexity of this industry, starting with:
    • Managing the reality of 50 states’ worth of regulation plus federal oversight from multiple agencies
    • Adhering to tight compliance requirements
    • Assessing the financial and risk implications of claims that won’t occur for decades
    • Recognizing that people are irrational to some degree when making financial decisions
    • Having patience (and patient investors) as even new entrants will be affected by sector dependencies and client dynamics that may take years to evolve
Start-ups will provide B2B carrier and distributor solutions, aiming at resolving automation, speed, productivity, technology, compliance and client experience pain points. When I began to take a close-up look at the insurance industry four years ago, it was exciting to see the low-hanging fruit that could have positive impact with limited downside. Carriers lacked digital and multi-channel capabilities, big data analytics and technologies that had been introduced in consumer financial services at least a decade prior. There are signs of progress. Entrepreneurs are homing in on specific problems, and executives are more open to outsiders. Consider as a starting point three buckets that are filled with pain: agent, client and broader capabilities.
  • The traditional agent model is riddled with issues, e.g.:
    • A continuous decline in the agent workforce,
    • A mismatch between agent demographics and overall population trends,
    • A prospecting model out-of-touch with the times, and
    • A compensation model that encourages churn and does not align interests between the agent and either the carrier or the client
Emerging agent solutions can successfully focus on reducing sales funnel inefficiencies, especially in the areas of:
  • automation solutions to ramp up agent engagement in digital channels (website and mobile app development, social media, compliance, content development, marketing campaign management),
  • hand-held device-based data capture and submission for policy applications; and
  • improved underwriting and application processing for faster approval, reducing error rates and minimizing or eliminating the need for applicants to provide blood and urine specimens.
Start-ups offering B2B solutions will succeed by:
  • Demonstrating real knowledge and expertise in the vertical.
  • Connecting the dots between their solution and drivers of financial success, especially the core metrics against which the industry and the analysts have historically measured performance.
  • Having a constructive attitude – no one wants to hear that the sky is falling, especially executives and advisers within striking distance of their own retirement.
Carriers are innovating to connect directly to the people who own their products, and also to motivate agents to sell. The goal of client-centricity is on top of the list for U.S. life insurers. The challenge is translating what starts off as an intellectual abstraction into resource allocation, structure, governance, talent, prioritization, investment and daily tactical delivery… not to mention demonstrable financial impact that will satisfy boards and investors. See also: Bringing Clarity to Life Insurance   The pressure is on. Carriers are choosing a variety of areas for focus, and stepping beyond expense reduction to shore up results. Commonly on the short list:
  • Advisers – whether captives or third party – have the direct relationship with the client and tend to maintain connections only with top clients who represent additional sales or referral potential.
  • Client relationship management - Carriers transact infrequently with clients or their beneficiaries – contacts focus on premium notifications, claims and questions about policies.
    • Even when clients or beneficiaries reach out, most carriers are in the early days of figuring out responses beyond answering the immediate question.
    • Across the industry, there are millions of clients referred to as “orphans” – people whose agent has died, retired or is no longer affiliated with the carrier. Even if “assigned” to another agent, these clients do not have strong relationships with whoever issued their policy.
    • Carriers have not done a good job understanding their clients and how to improve the effectiveness of these relationships based on behavioral segmentation or other proven tactics. In the language of the carriers, “in-force management” is a relatively new area of focus, driven initially by risk and expense reduction strategies, with some signs of effort to improve client loyalty and satisfaction.
  • Capabilities – Ranging from basic automation to big data to digital and multi-channel experience platforms, e.g.:
    • data management platforms that unify disparate data sources, making them useful in one, dynamic dataset, speeding up execution, as well
    • data analytics, e.g., to enable active and relevant product migration as well as additional sales. product development and exploration of new business models
    • integrated experience for agents and clients across channels
    • data security enhancements
    • e-document management
See also: What’s Next for Life Insurance Industry? The business model and culture that enable results to happen, along with the distractions of running a business of such high complexity, will compete with carrier-led efforts. Without restating the obvious challenges, two worth noting are:
  • The dependency on agents and advisers to drive sales, which makes any direct-to-client conversation controversial, as it may be perceived as competitive with the sales force
  • The diversion of attention in life insurance C-suites right now to address the recent U.S. Department of Labor decision on fiduciary standards. The impacts of this ruling are significant.
A 2015 World Economic Forum research study titled "The Future of Financial Services" concluded that while “the most imminent effects of disruption will be felt in the banking sector … the greatest impact of disruption is likely to be felt in the insurance sector.” For entrepreneurs and investors who see the upside and can tackle the complexity, life insurance is territory that appears, at least for now, to have considerable white space for reinvention.

Amy Radin

Profile picture for user AmyRadin

Amy Radin

Amy Radin is a strategic advisor, keynote speaker, and Columbia University lecturer focused on why transformation succeeds or stalls in large, complex organizations. 

Drawing on senior leadership roles at Citi, American Express, and AXA, including one of the world’s first corporate chief innovation officer roles, she helps leaders build the capabilities required to absorb, scale, and sustain change.

Learn more at amyradin.com.


The Next Opioid Epidemic: Fentanyl

"The synthetic, opium-like drugs were so potent that six of the agents became ill after handling them. One fell into a coma."

|
Fentanyl has been in the news: In 2014, it began being reported on the U.S. East Coast that heroin was being laced with fentanyl, creating a combination that is "untenably addictive." The Sacramento Bee reported in April that 51 overdoses, including 11 deaths, had been reported thus far in the Sacramento area in 2016; toxicologists tied eight of the deaths directly to fentanyl (watch the short video in the article that describes "death as collateral damage" to the drug dealers interested in market dominance). Later in April, the L.A. Times reported the issue had migrated to the San Francisco area, where fentanyl pills made to look like Norco were a primary culprit. The chief health officer in British Columbia proclaimed a Canadian public health emergency because of more than 200 overdose deaths during the first three months of 2016; a large portion of them involved "greenish pills purporting to be OxyContin 80 mg tablets." In June, it was confirmed that Prince died from an accidental overdose of fentanyl, unbelievable because he was an outspoken advocate of clean living (from having a "swear jar" to not consuming alcohol) One of the common threads throughout these stories is China's involvement. The Wall Street Journal published a front-page article on June 23 titled "China's Role in U.S. Opioid Crisis." The opening paragraph sets the stage:
Last spring, Chinese customs agents seized 70 kilograms of the narcotics fentanyl and acetyl fentanyl hidden in a cargo container for Mexico. The synthetic opium-like drugs were so potent that six of the agents became ill after handling them. One fell into a coma.
The article goes on to describe how fentanyl often is disguised as hydrocodone and Xanax on the black market -- dangerous drugs by themselves but not nearly as potent or fatal as fentanyl. Because China does not regulate fentanyl or analogs used to create fentanyl, there is a significant financial incentive for the drug dealers -- $810 of materials can create 25 grams of fentanyl and yield as much as $800,000 in pills sold on the black market. See also: Opioids Are the Opiates of the Masses According to the Canadian Globe's expose on the issue (an excellent look at the black market), accessing fentanyl can be as easy as "Sign up for an account, choose a method of payment, and receive the package in three to four business days." Reinforcing the financial model: "A kilogram ordered over the internet – an amount equal in weight to a medium-sized cantaloupe – sells on the street in Calgary for $20 million, making it a drug dealer’s dream." So, fentanyl is a problem. It's 25 to 50 times more potent than morphine. It's highly addictive. It's available fairly easily on the black market. And it is prescribed by doctors. Way too often. Approved by the FDA and on script pads supplied by the DEA, its federal legitimacy adds to the lack of stigma associated with use. Which is one reason why I think Prince could rationalize his use. A doctor likely prescribed it for his chronic pain -- and other patients fall into that same trap (with fentanyl and other dangerous prescription drugs). According to the FDA's own warnings (as reported on drugs.com):
Because of the risks of addiction, abuse and misuse with opioids, even at recommended doses, and because of the greater risks of overdose and death with extended-release opioid formulations, reserve Fentanyl Transdermal system for use in patients for whom alternative treatment options (e.g., non-opioid analgesics or immediate-release opioids) are ineffective, not tolerated or would be otherwise inadequate to provide sufficient management of pain.
See also: How to Help Reverse the Opioid Epidemic   In my opinion, fentanyl should be used to help people die with dignity during end-of-life care. Period. It's that dangerous. And yet we see it being prescribed, used and paid for. Month. After. Month. If you are prescribing fentanyl: Why? If you are being prescribed fentanyl: Why? If you are paying for someone's fentanyl: Why? Too many people are overdosing and dying not to ask a simple question: Why?

Mark Pew

Profile picture for user MarkPew

Mark Pew

Mark Pew is a senior vice president at Prium. He is an expert in workers' compensation medical management, with a focus on prescription drug management. Areas of expertise include: abuse and misuse of opioids and other prescription drugs; managing prescription drug utilization and cost; and best practices for weaning people off dangerous drug regimens.

InsurTech Boom Is Reshaping Market

Spending on InsurTech looks set to surge: What is your strategy to stay abreast of the new opportunities and threats?

|
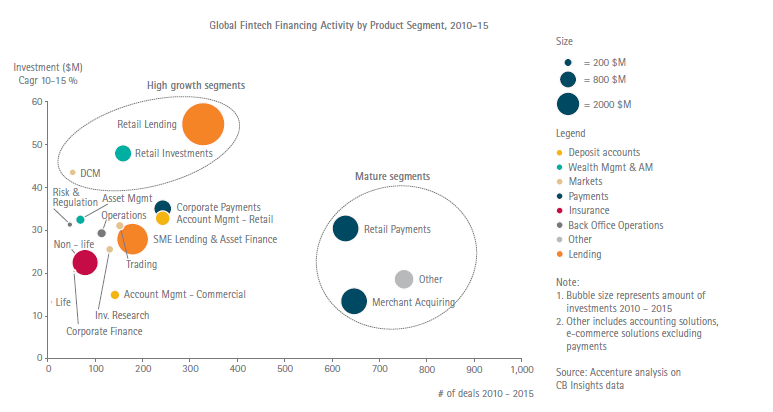
Investment in insurance technology, InsurTech, is climbing fast. It’s going to have a big impact on insurance providers around the world. What is your strategy to stay abreast of the new opportunities and threats posed by InsurTech? Global investment in financial technology, FinTech, continues to soar, and insurance is emerging as its next big target market. Investors around the world poured $22.3 billion into FinTech deals last year – a 75% leap from 2014. InsurTech attracted around $2.6 billion of this outlay. This is still a small slice of total FinTech spending, but it’s a big step up from the previous year’s $800 million. And spending on InsurTech looks set to surge. See also: InsurTech Forces Industry to Rethink In the first quarter of 2016, more than 45 InsurTech deals were sealed, with funding totaling $650 million, according to researcher CB Insights. This is the most deals in any quarter and the second highest amount of investment for such a period. InsurTech firms that attracted funding included Oscar Health, Next Insurance, Lemonade and Slice Labs. Backing came from venture capital firms, private equity companies and the investment arms of big insurers. Why the big interest in InsurTech? One of the reasons is that the FinTech market is maturing. The illustration below shows that, in the clamor for funding, early investment targets such as retail payments and merchant acquisition are being overtaken by new growth sectors, particularly retail lending and retail investments. InsurTech is fast emerging as a new investment opportunity. Insurtech boom will reshape the global insurance market_Cusano (Figure 1) Another reason is that FinTech investors realize that the insurance industry is ripe for disruption. With annual premium revenue of around $5 trillion and assets under management heading toward $15 trillion, the global insurance industry is a huge market. It lags other sectors, notably the banking industry, in adopting digital technology. Insurers need to raise their spending on innovation to ward off rising competition and lure much-needed new customers. See also: Secrets InsurTechs Need to Learn   The upswing in investment in InsurTech firms will have a major impact on the insurance industry around the world. Expect a host of new arrivals to appear in the insurance industry in the next 12 to 18 months. Some of these firms will be marketing niche solutions to established carriers and brokers. Others will be looking to grab a slice of the insurance market by offering specialized insurance products and services built around digital technology. Bottom line…if you haven’t done so already, it’s time to decide how you will respond to InsurTech. This article originally appeared at Accenture.

John Cusano

Profile picture for user JohnCusano

John Cusano

John Cusano is Accenture’s senior managing director of global insurance. He is responsible for setting the industry group's overall vision, strategy, investment priorities and client relationships. Cusano joined Accenture in 1988 and has held a number of leadership roles in Accenture’s insurance industry practice.

Healthcare: Time for Independence

“Employer frustration over the devastating collateral damage from a severely under-performing healthcare system is boiling over.”

|
Forbes carried a good article by Dave Chase, a leader in trying to reform healthcare in the right way. Chase writes, “Employer frustration over the devastating collateral damage from a severely under-performing healthcare system is boiling over.” Click here to read the full article. High health costs are driving U.S. jobs to Mexico and other countries. GE and scores of other companies are exporting high-value jobs. Some are even moving jobs to areas in the U.S. where healthcare costs are less exorbitant. IBM is a good example of the latter. Yet Chase and others have demonstrated that rising healthcare costs can be controlled, and controlled in an employee-friendly way. What an irony. He has created a Declaration of Independence From Traditional Health Insurance. The article lists a number of thought leaders, consultants and employer leaders who have signed that declaration, the goal of which is to create a sustainable healthcare equation in America. Signers include Al Lewis, Jim Millaway, Rajaie Batniji, Brian Klepper, Stan Schwartz, your humble author and others who have implemented effective health programs. This is a revolution worth fighting for.

Tom Emerick

Profile picture for user TomEmerick

Tom Emerick

Tom Emerick is president of Emerick Consulting and cofounder of EdisonHealth and Thera Advisors.  Emerick’s years with Wal-Mart Stores, Burger King, British Petroleum and American Fidelity Assurance have provided him with an excellent blend of experience and contacts.

Ads Can’t Buy You Happy Customers

With auto premiums surging, drivers are asking why they’re paying for insurers to outspend every other U.S. industry on ads by nearly 8%.

|

It seems like you can’t watch television for 10 minutes these days without hearing a sneaky gecko, a suit-clad man named Mayhem or Progressive’s Flo pushing insurance. Insurance ads like GEICO’s bring some humor to your between-show times, and they're definitely better than those psoriasis medication ads. But what’s not so funny is that policyholders are spending billions to broadcast those messages across the airwaves. 

Now, with auto insurance premiums rising faster than they have in nearly 13 years, more drivers are asking why they’re paying for insurers to outspend every other American industry on ads by nearly 8%. In my opinion, it’s a fair question — especially considering that there are better ways to earn satisfied policyholders. 

Ads Don’t Make Happy Customers 

In 2014, S&P Global (formerly SNL Financial) analyzed auto insurance advertising spending and found that GEICO led the pack, spending almost $1.2 billion annually, closely followed by Allstate at more than $937 million. Those figures keep climbing, but do they translate to better service? 

The Consumer Federation of America broke down the ratio of advertising to premiums and found that GEICO spent 6% of its budget on ads in 2013, while Allstate spent 5.7%. Interestingly, Allstate’s recent earnings report showed its net income fell by almost $1.2 billion from the first quarter of 2015 to the first quarter of 2016. GEICO, not to be outdone, had one of its worst years on record in 2015. 

When it comes to customer satisfaction, though, the big spenders aren’t winning. When Reviews.com weighed the nation’s largest auto insurance companies for dependability, financial standing, reliability and customer focus, it was Amica and State Farm that came out on top. What do Amica and State Farm have in common? They’re both policyholder-owned. 

So while investor pressures have put stockholder-owned GEICO and Allstate on top for ad spending, they’re not pleasing customers like mutually owned Amica and State Farm. 

See also: How to Redesign Customer Experience 

There are plenty of differences between mutual companies and investor-owned insurance companies, of course, but a big one is how they spend profits. While policyholder-owned insurers also purchase ads to tempt new customers, they — unlike stockholder-owned insurers — return a chunk of their profits to members in the form of dividends or reduced premiums. 

Cut Ads, Not Service 

Mutual companies have shown that it’s possible to contain — even to reduce — costs while still satisfying customers. After all, when was the last time you saw an Amica ad on television? 

The first — and perhaps most important — step to keeping rates low is to reduce customers’ exposure to risk. Our company recently tightened its underwriting guidelines to contain claims and allow policyholders to benefit from the cost savings. It’s a difficult decision that can hinder sales, but it’s the best way to keep costs low for everyone. Next, find ways to get your name out there that benefit existing policyholders. 

In lieu of ads, we conduct programs called brand energizers that reward the affinity groups we serve. Nurse’s Night Out, for example, treats our life-saving policyholders to an evening of fun, while our Work Hard/Play Hard sweepstakes are a great way to build word of mouth while rewarding customers who are first responders. 

Reward programs are just one way to build your brand without ads. We’ve developed a team of field marketing managers, our brand ambassadors, who make appearances at schools, educational events and other local groups to explain the benefits of our policies. This model costs much less than a national television ad campaign while building our reputation in the communities we serve. 

Hiring captive agents, too, is a good way to structure teams in a way that boosts service, not costs. Our account consultants are rewarded for bringing in new accounts, as well as for their retention efforts, and they’re not tied to particular clients. This creates incentives to provide world-class service to every potential client they encounter. 

See also: Spending on Agents Beats Spending on Ads 

Don’t forget the value of a strong retention program, which captive agents can help with. Happy customers are loyal customers, and the cost of retaining a customer is much lower than earning a new one. According to Bain, a mere 5% increase in customer retention could garner your company as much as a 95% profit increase. 

A focus on retention also builds brand champions who are willing to tell others about their experience. Wouldn’t you rather hear a neighbor’s recommendation than a gecko’s sales pitch? 

Lastly, build a strong surplus to protect yourself against unexpected losses. If a tornado strikes, you’re only as strong as your reserves. Invest in this surplus so you can weather disasters without raising policyholders’ rates in their time of need. 

When I started working in the industry, I rarely saw an insurance ad on television. I’m now sick of them, and I know customers are, too. To keep policyholders happy without dropping billions on ads, try it the old-fashioned way: Cultivate strong relationships and even stronger reserves, focus on retaining customers and build a team of brand advocates. Maybe you — and all of America — can then get back to watching your show in peace.


Mike McCormick

Profile picture for user MikeMccormick

Mike McCormick

Mike McCormick is CMO and senior vice president at California Casualty, an auto insurance provider for educators, law enforcement officers, nurses and firefighters. McCormick has presented at Salesforce's annual Dreamforce conference.

Which to Choose: Innovation, Disruption?

Ask if your market faces unpredictable changes. Then determine how much control you have over those changes.

|
Most executives are averse to risks but, ironically, create the risk of being leapfrogged by unforeseen competitors. Executives focus on innovation but only look for a new idea, device or methodology that incrementally provides greater efficiency or effectiveness, like the fifth blade in a razor or higher-resolution HDTVs. This sort of innovation, sometimes referred to as a sustaining innovation, is not the same as out-of-the-box thinking that leads to disruption. To be sure, sustaining innovation can sometimes produce great success. Google displaced Yahoo as the de facto search engine and web mail provider through incremental, in-house innovations, not through a disruptive strategy. Nevertheless, most companies, including insurers, are now being forced to change their products, service models or delivery systems because of threats from outside the mainstream in the industry. Management and marketing efforts have traditionally touted incremental, continuous improvements -- using words like “faster," "bigger," "better" or "more efficient” -- as a reason why clientele should remain loyal and why business should even expand. The incumbent mature market leaders, no matter how visionary they think they are, often ignore opportunities to invest in disruptive business strategies. Netflix beat Blockbuster in the consumer video market starting in 1997 by coming up with a new business model for DVDs  by mail and by investing in the nascent technology of on-demand, downloading of video content while Blockbuster stayed with its traditional business model of renting DVDs in stores and kiosks. See also: Does Your Culture Embrace Innovation? Disruption is created through inventions or processes that transform and overturn the way we think, behave, buy products, communicate, travel and go about our daily business. It doesn’t have to be based on new technology. Disruption, unlike incremental innovation, displaces an existing market, industry or technology by reimagining something more efficient and wildly better. Disruption looks at the underlying principles and values of a product or service, then rethinks solutions. Disruption is aimed at a set of consumers whose needs are largely ignored by industry leaders. A disruptive innovation trades off performance along one dimension for performance along another, such as simplicity, convenience, values, ability to customize and transparent pricing. Initially, some disruptive models from a niche market (like Uber or Lyft) may appear unattractive to consumers or inconsequential to industry incumbents, but eventually many of these disruptive or enlightened approaches to business opportunities completely redefine the industry. New brands have turned their industries upside down. In fact, smaller companies with fewer resources have knocked many brand name incumbents out of business. Once mainstream customers start adopting an entrepreneurial entrant’s offerings in volume, disruption has occurred. Shilen Patel, founder of business accelerator Independents United, says: “Simply put, innovation is rational whereas disruption is irrational.” Most outrageous business ideas have had loud critics. Not disruption. Companies like Google (Alphabet) thrive by taking crazy ideas called moonshots at a devastating pace and seeing if they can make them believable, deliverable and profitable, knowing that just a small percentage of the ideas will work. So how does a business decide if it needs to innovate or reinvent itself to remain competitive? Corporate executives must ask themselves if their industry is facing unpredictable changes, then decide how much control they have over that change. As Mark Zuckerberg once said: “If we don’t create the thing that kills Facebook, someone else will.” Companies now run the risk of cross-industry disruption, where a high-tech company takes over autonomous transportation or even an industry like insurance. Amazon did just that with retail and is now considering its own drone delivery system, its own shipping fleet and 3D printing to disrupt certain supply industries. See also: 6 Key Ways to Drive Innovation The University of Southern California in 2014 began offering a program for entrepreneurs referred to as “a Degree in Disruption.” Venture capitalist Josh Linkner’s book, The Road to Reinvention, argues that “fickle consumer trends, friction-free markets and political unrest…along with mind-numbing technology advances,” mean that “the time has come to panic as you’ve never panicked before.” Twenty years ago, the disruption in manufacturing was offshoring. Now, the disruptions are technologies like 3D printing, artificial intelligence, transportation innovations and robotics -- and are bringing manufacturing jobs back to home markets.  Investments in sustaining innovations obviously make sense for most companies, but some may choose to strengthen their ultimate market position by investing in enterprises that don’t necessarily align themselves with their core business strategies. Partly because of disruptive innovation, the average job tenure for the CEO of a Fortune 500 company has halved from ten years in 2000 to less than five years today. Eventually, foothold market companies may have to decide on the strategic choice of taking a sustaining, traditional path versus a disruptive one. The same forces that lead incumbent industries to ignore early-stage disruptions also compel disrupters to ultimately disrupt. But if a company’s innovations do change consumer behaviors and force a redrawing and expansion of market boundaries that separate its new business from the culture and processes of old ones – then you really have something.

Jeff Pettegrew

Profile picture for user JeffPettegrew

Jeff Pettegrew

As a renown workers’ compensation expert and industry thought leader for 40 years, Jeff Pettegrew seeks to promote and improve understanding of the advantages of the unique Texas alternative injury benefit plan through active engagement with industry and news media as well as social media.

How to Make Flood Insurance Affordable

A combination of government vouchers and risk-based pricing shows promise.

|
Our study on Charleston County, SC, assesses the cost impacts of flood insurance if premiums were increased to risk‐based prices. We then consider a program that addresses affordability concerns coupled with cost‐effective risk reduction measures. We follow these two principles for flood insurance:
  1. Flood insurance premiums should be priced to accurately reflect risk. Premiums reflecting risk inform individuals as to the hazardousness of the area and encourage investment in cost‐effective adaptation measures.
  2. Issues of affordability should be addressed, but not by subsidizing insurance premiums. Many low‐ and middle‐income homeowners living in older homes in flood‐prone areas are not able to afford flood insurance if premiums are priced to reflect risk.
We determined risk‐based premiums for a subset of National Flood Insurance Program (NFIP) policyholders who live in Charleston County’s inland and coastal Special Flood Hazard Areas (SFHAs) who currently receive NFIP premium discounts despite their location in high-risk areas. If premiums were risk‐based, these homeowners in Charleston County’s FEMA‐mapped high‐risk flood zones that currently receive subsidies would see their costs increase substantially. If premiums were risk‐based, they would increase from their current levels by 108% on average for policies in the high‐risk 100‐year floodplain (A zone) and by 159% on average in the high-risk 100‐year coastal floodplain (V zone). Elevating a house by a few feet can decrease the risk‐based premium by 70% to 80%, saving thousands of dollars annually. However, elevating a house is very expensive. We propose a voucher program that has two key aspects: (1) insurance premiums are based on risk; (2) vouchers are used to offset both the premium and the cost of the loan for risk mitigation. Implementation of the voucher program with mitigation can reduce government expenditures by more than half over a program that does not require mitigation if the cost of elevating a house is around $25,000 in the A zone. In the high-hazard coastal V zone, cost savings can be achieved even when the cost of elevation is as high as $75,000. Mitigation does not lead to reduction in the cost of the voucher if the policyholder’s household income is below $10,000. Elevation is not feasible for all homes, notably those in historic districts. Other actions could also be considered, such as making a higher deductible the standard option. Other mitigation measures might also lead to lower NFIP premiums, such as wet flood‐proofing the ground floor or moving all habitable areas to the second floor in multi‐story homes. Premiums reflecting risk in the NFIP are primarily a function of the designated flood zone, coverage limits and the property’s structural features such as the height of the lowest floor relative to the base flood elevation (BFE). The BFE is the estimated height of floodwaters during a 100‐year flood. Charleston County is vulnerable to both inland and hurricane flood risks so there are incentives for many homeowners to take steps to invest in cost‐effective measures to reduce their risk and hence their risk‐based insurance premiums. To elevate the home, the homeowner would take a 20‐year, 3% interest loan. A voucher would offset both the reduced risk‐based premium and the cost of the loan to elevate the house. We assume that a household earning $50,000 gross income per year can contribute 5% ($2,500) to flood insurance. After the policyholder’s $2,500 contribution, the voucher covers the additional costs. To illustrate, consider a family living in the A zone with a house one foot below BFE where the risk‐based premium is $5,596. As shown in Table 1, at low and medium elevation costs, the annual cost (loan payment plus the flood insurance premium) is less than the voucher would have been had the homeowner not elevated the house. In fact, if mitigation were required, no federal expenditure would be incurred when elevation costs are low, because the loan cost and the risk‐based premium would be less than $2,500. Savings generated from risk mitigation are even greater in the V zone; even when elevation costs are high, the reduction in premium justifies the investment, as shown in Table 2. Table 1: Voucher Costs in the A Zone without and with Elevation (U.S. Dollars)
Insurance voucher – no mitigation
Risk‐based premium without elevation 5,596
Homeowner pays 5% of gross income 2,500
Government voucher 3,096
 
Insurance voucher -- after house elevation Low cost Medium cost High cost
Cost to elevate the house 2 feet 24,635 50,970 74,756
Risk‐based premium after elevation 839 839 839
Annual loan payment (3% interest, 20 years) 1,656 3,426 5,025
Total annual cost 2,495 4,265 5,864
Homeowner pays 2,495 2,500 2,500
Government voucher -- 1,765 3,364
  Table 2: Voucher Costs in the V Zone without and with Elevation (U.S. Dollars)
Insurance voucher – no mitigation
Risk‐based premium without elevation 19,218
Homeowner pays 5% of gross income 2,500
Government voucher 16,718
 
Insurance voucher -- after house elevation Low cost Medium cost High cost
Cost to elevate the house 2 feet 24,635 50,970 74,756
Risk‐based premium after elevation 5,304 5,304 5,304
Annual loan payment (3% interest, 20 years) 1,656 3,426 5,025
Total annual cost 6,960 8,730 10,329
Homeowner pays 2,500 2,500 2,500
Government voucher 4,460 6,230 7,829
  When a family’s income is below $50,000, the homeowners’ proposed contribution would be less than $2,500 and the government’s contribution would therefore increase from the above examples. In both A and V zones, we find that when annual household income is below $10,000 it is cost‐effective for the government to offer a voucher without requiring the house to be elevated. For households in the $10,000–20,000 income bracket, elevation is cost‐effective for the government only when elevation cost is low. In the V zone, for incomes of more than $20,000, a voucher with a mitigation loan is always financially preferable even when the elevation cost is high. State‐Level Natural Disaster Programs in South Carolina South Carolina currently has several natural disaster programs and tax incentives to assist homeowners in purchasing insurance and fortifying homes.
    • South Carolina’s Omnibus Coastal Insurance Act of 2007 created the Safe Home grants program for low‐and middle‐income homeowners to retrofit primary residences against high‐wind and hurricane damages. Families making less than 80% of the county median household income and with home value below $150,000 qualify to receive as much as $5,000 in non‐matching grants. Families with income above that threshold and home value less than $300,000 are eligible for as much as a $5,000 matching grant. From 2008 to 2011, the Safe Home program awarded 2,500 grants totaling $12.1 million.
    • The Residential Retrofit Tax Credit provides state income tax credits of as much as $1,000 for expenses incurred when retrofitting a home against natural disasters. From 2008 to 2011, 670 Residential Retrofit Credits have been claimed, totaling $781,106.
    • The South Carolina Excess Insurance Premium Tax Credit allows homeowner to claim as much as $1,250 in state income tax credit against excess premium paid on property and casualty insurances. Excess premium is defined as the portion of the premium greater than 5% of the taxpayer’s annual gross income. Additionally, the state offers Catastrophe Saving Accounts, which are interest‐bearing accounts not subject to state income taxes if funds are used for qualified catastrophe expenses.
/ul>

Howard Kunreuther

Profile picture for user HowardKunreuther

Howard Kunreuther

Howard C. Kunreuther is professor of decision sciences and business and public policy at the Wharton School, and co-director of the Wharton Risk Management and Decision Processes Center.