Download

Hurricanes test insurance -- and insurance innovation

sixthings

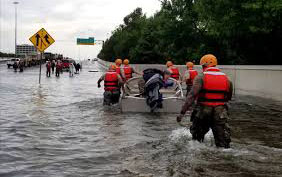
With Hurricane Harvey gone and people in Houston starting to pull their flood-ravaged lives back together, here comes Hurricane Irma. This is what Irma looks and feels like at the moment, as described by our friend and colleague Guy Fraker, ITL's chief innovation officer and a resident of the Florida Keys:

"If the forecasted winds and waves come to fruition, the house will be a total loss. We normally have 1.5- to 2-foot 'waves' on our mile-wide channel. Saturday and Sunday are projected to see 27- to 31-foot waves, lasting 11 to 13 seconds each, for 15 hours. With winds topping 150 mph pushing debris on water 30 feet above normal, this is Andrew all over again."

Guy has a gig in Baltimore this week, and his wife, Becca, is with him, so the one hopeful note is:

"The car is on the fourth floor of the Ft. Lauderdale airport, with essentials, and we loaded up the luggage—so we'll see."  

While we can still hope and pray that Irma, with its currently 180 mph winds, swerves north and away from land, Harvey and perhaps Irma provide the first real test of the newly innovative insurance industry. We've been talking a good game for a couple of years now, but how fast will we really be to pay claims? How good will the drones be at assessing damage? How much smarter have our assessments of risks become? Will "gig" workers make a difference? 

We also, of course, face the question that comes with every disaster: In this moment of truth, are we as an industry really trying to give people peace of mind and get their lives back to normal as quickly as possible, or is that just a marketing claim and something we tell ourselves so we can feel good about what we do? I'm hoping we're sincere and have learned some of the hard lessons from Sandy and Katrina about where points of contention are and about how we need to treat customers. We'll see. 

Finally, we have to figure out what to do with the National Flood Insurance Program, which is set to expire at the end of the month. Even if Washington weren't dysfunctional, an answer would be elusive. We all know that the NFIP doesn't work. What would work is rather harder to define.

If you find these topics half as compelling as I do, then I commend to your attention four articles that we've published over the past week, which I'll describe here rather than just include in the six articles below. I tackle all three topics—the test of innovation, the need to honor our commitments and the NFIP question—in "Harvey: First Big Test for Insurtech." (My advice on the social responsibility front: Be like J.J. Watt, not Joel Osteen.) Bill Wilson suggests a solution for the NFIP in "Time to Mandate Flood Insurance?" Michael Murray suggests that the federal government could get out of flood insurance entirely, in "Harvey Hammers Home NFIP Issue." He also offers a thorough, insightful exploration of the public trust issue in "Hurricane Harvey: A Moment of Truth."

I'm hoping that next week's note will be much cheerier—but not counting on it.

Cheers,

Paul Carroll, Editor-in-Chief

P.S. Back in April, I wrote about— OK, I mocked —Juicero as an example of how innovation can run amok even when smart people are involved. The heavily funded startup's business model was to have you buy a $700 device for the privilege of getting access to the company's overpriced juice—only to have a Bloomberg reporter show that she could squeeze the juice packets by hand faster than the high-powered, super-smart, internet-connected juicer could. Well, Juicero, mercifully, closed up shop over the weekend.

Good riddance—but rest assured that this won't be the last spectacularly bad idea to draw funding. Keep your guard up.


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Are You Ready for Some Football?

How about some insurance on your fantasy football team? The problem is: It isn't really insurance and thus may not be legal.

For millions of Americans, the end of summer marks an important tradition: fantasy football drafts! Even with the National Football League seeing a slight downturn in television ratings for the first time in years last season (the possible causes of which are too complex to address here), fantasy football continues to grow in popularity. The Fantasy Sports Trade Association estimates that almost 60 million people in the U.S. and Canada will play fantasy sports in 2017 (with fantasy football being the most popular). Fantasy football continues to be a colossal enterprise that drives significant interest to the NFL, as well as a wide array of supporting industries looking to monetize our apparently unquenchable love of this game within a game. One such secondary industry, which began developing several years back, is fantasy football insurance. Although some of the original companies may have fallen by the wayside, there are still a few companies selling these "insurance" policies, intended to provide coverage for a fantasy owner’s investment in the event a starting player gets hurt. Although some of the details have changed over the years, these policies continue to raise interesting questions under insurance law. See also: How Literature and the NFL Shed Light on Innovation   As a starting point, let’s recap how fantasy football works. A group of participants, or “owners,” form a league to compete against one another based on the statistical performance of NFL players in real, live games. Teams are typically made up of a quarterback, some combination of running backs, wide receivers and tight ends, a defense and a kicker (with backups for key positions). More advanced leagues may also incorporate defensive players and special teams. Before the NFL season starts, the owners hold a draft – or sometimes an auction – to divide the desirable players (expected to accumulate strong statistics over the season) and build their rosters. Each week during the NFL regular season, fantasy teams square off against each other, earning points based on their players’ performance in NFL games. Whichever squad scores more points that week wins, and the teams that accumulate the most wins have a short playoff during the last few weeks of the season to name an ultimate champion. Fantasy football is popular for countless reasons, but, for many, it’s a form of competition among friends (or even strangers), and, as with any competition, there is an opportunity for wagering. Although many leagues are simply for fun, very often leagues have an upfront buy-in (ranging from a few dollars to thousands), with the champion taking home cash at the end of the season. Fantasy football certainly combines elements of both skill and luck in ways that many more traditional gambling ventures, like slot machines or craps, can’t claim, but, in many regards, fantasy football serves as a statistics-based gambling enterprise. The insurance products available online are intended to protect an owner’s “investment” in the league; that is, the cash buy-in. Typically, an interested owner picks a player he wants covered from a list of eligible players on the insurance company’s website and determines how much “coverage” to buy. Prices vary depending on a few different factors (coverage options, a player’s history of injuries, etc.). For example, in updating the research for this article, I was able to buy a $50 policy on one of my star wide receivers for $6.40 using a coupon code found online. If my insured player misses 8 or more games due to injury, the policy will pay me $50 to make me whole for my league buy-in. But what am I really insuring? All insurance policies require an insurable interest, which means that a policyholder must have a valid legal or financial interest in the thing he wants to insure. People buy insurance policies to cover lots of things: their body, home, car, business, life. We buy insurance for these things because we have an insurable interest in them – if something bad were to happen to them, it would harm us. In most states, to form a valid insurance contract, the insurable interest must exist both at the time the policy is purchased and at the time of the loss. If the policyholder has no insurable interest, the insurance policy is typically deemed void (although many courts still enforce the policy against an insurance company that accepts premiums knowing that no insurable interest exists). A mere “contingent” or “expectant” interest that isn’t based on a legal interest or right is typically not enough to be insurable. Without an insurable interest, the contract essentially becomes a wager that something bad will happen to the thing insured; there is only the upside of a payout if the insured matter is harmed, without any downside to a disinterested policyholder. These fantasy football insurance policies challenge the insurable interest requirement by expanding what kind of interest can be insured. Is owning a player on a fantasy football team, and betting on that team, a sufficient legal interest to be insurable? Maybe, maybe not. Technically, betting on fantasy football is legal in most states, especially those that allow betting on games of skill. The betting also likely complies with federal law: The Unlawful Internet Gambling Enforcement Act of 2006 (UIGEA), which attacks funds transfers associated with internet gambling websites, specifically carves out fantasy sports from its reach. (In recent years, the rise in prominence of daily fantasy sites, such as Draft Kings and FanDuel, has brought the legality of betting on fantasy sports into question, but this article assumes that ordinary participation in a season-long fantasy league with a cash entry fee complies with the statute.) But even if legal, it is undeniable that a fantasy football owner’s sole monetary interest in his players is the league entry fee, which is a wager against the other owners in the league; to the winner go the spoils. The purpose of the insurable interest is to prevent using insurance policies as a form of gambling, so it would make little sense that a policyholder could have an insurable interest in a (possibly legal) wager. In this regard, fantasy football insurance is a wager on a wager, and probably lacks an insurable interest. Another challenge for these insurance products is that the insurance companies have no way of confirming that the policyholder even has the insured player on his or her team. In years past, carriers selling these policies made actually no effort to determine if the policyholder actually had the covered player on a team. Now, at least one company is asking customers to click to confirm that the player is on the customer’s roster, but the insurance company has no way of knowing if the policyholder keeps that player on the roster throughout the season. Trades and other transaction are one of fantasy football’s most popular features, as owners enjoy managing their teams and shuffling their rosters. If I trade away my covered player in Week 2, and he has a season-ending injury in Week 3, the policy should be void, because I no longer hold an insurable interest in the player covered. The insurer also has no way of determining how much my insurable interest should be; policyholders are allowed to buy any level of coverage. See also: 4 Goals for the NFL’s Medical Officer   Because of the absence of a valid insurable interest, these policies do not likely qualify as “insurance” policies under most states’ laws. So what are they? The law would probably consider them to simply be a bet that a particular player will get seriously injured. And not only is it a bet, it’s a bet made over the internet, which raises even more problems. Such bets likely violate federal law. UIGEA allows owners to bet on fantasy football because the outcome reflects the knowledge and skill of the owners and is determined predominantly by the real-world statistics of the NFL players on each owner’s team, but a bet on whether a player will get injured certainly fails this test and is likely considered a violation of the statute. But policyholders don’t need to panic quite yet. Consumers have no liability under the UIGEA – the law solely targets the financial institutions that process the transactions for unlawful internet gaming. In the end, fantasy football insurance companies aim to provide well-intentioned products to owners, ensuring enjoyment of their leagues and mitigation of risks. Most “policyholders” simply have a fantasy football team that they’ve spent some money on and want to hedge their bets in case a star player gets hurt. But do not be surprised to see courts or regulators step in to provide clarity on the legality of these policies if these products ever make a significant jump in popularity.

Joe Balice

Profile picture for user JoeBalice

Joe Balice

Joe Balice is a partner at Brutzkus Gubner Rozansky Seror Weber in Los Angeles. As a member of the commercial civil litigation team, Balice’s core practice is representing policyholders when insurance company carriers deny claims.

Why Do We Still Use So Much Paper?

Moving from paper forms to electronic smart forms reduces internal inefficiencies while improving relationships with policyholders.

Customer experience (CX) has become the lifeblood of nearly every industry in the world. Carriers that once sidelined it in favor of other internal aspects of their business have come to realize that positive and expedient customer interaction is integral to maintaining customer relationships and building new ones. While there are a myriad of ways to accomplish this, a simple yet often underrated way to overhaul CX is to move from paper forms to electronic smart forms. Not simply a cosmetic improvement, it is extremely effective at both reducing internal inefficiencies and improving relationships with policyholders. See also: Why Customer Experience Is Key   Consumers -- especially millennials -- have become accustomed to real-time, above-and-beyond customer service from companies like Amazon and Apple. They prefer to do business with organizations that provide a comparable or superior experience, and insurance is no exception. New entrants like Lemonade attract a millennial consumer base because of their transparency and straightforward communication. A significant part of that is standardizing and digitizing forms so that they don’t become a burden on either the carrier or the consumer, especially with regard to claims. What are the biggest benefits to moving from legacy forms to new templates or web-based smart forms? We break them down here: Smart Forms Eliminate Costly Errors: Insurers face a major problem in that most mistakes are human errors. Handwriting can be hard to read from both colleagues and policyholders. This leads to misinformation that could have severe implications months, or even years, down the line if a claim happens. Another issue is missing information and supplemental forms that are required based on previous responses that never get filled out. Additionally, errors frequently occur on physical forms because consumers aren’t pointed to their mistakes until the forms are already submitted. Insurance forms are often complex and confusing and are difficult to fill out correctly without proper guidance. Oftentimes, there are certain non-obvious questions that only apply to specific applicants. These errors can result in wasted time and resources for carriers who need to decipher illegible handwriting, correct errors or request missing information before submitting the form. One carrier we spoke with said that errors are so common that it takes two to three weeks to get through a process that requires 30 minutes once automated. This delay can be deadly when it comes to new business acquisition, as consumers do not want to wait that long. A digital form can alleviate the problem immediately by guiding the customer through the completion process, such as indicating where information needs to be entered, prompting for additional information based on previous responses or catching unsigned documents. For example, GroupHEALTH Benefits Solutions, a health benefits solution provider, saw a significant improvement when it switched from paper to smart forms. Their original paper-based method was error-prone, and employees had to take considerable time to research and resolve missing or conflicting information. The provider realized it could improve enrollee experiences and save money by implementing digital transformation techniques such as automation and intelligence through smart forms. Once the implementation took place, there was a near-immediate ROI. The new online enrollment process ended up reducing errors, which in turn helped the company focus on providing excellent CX. Confusing Forms Can Lead to Customer Drop-Off: While errors on paper forms can waste significant time and resources for a carrier, the forms can also leave customers angry, frustrated and willing to give their business to a competitor. According to Ernst & Young's Global Insurance Consumer Survey of 24,000 people in 30 countries, 40% of customers left an insurer in the past 18 months. The most interesting finding was that respondents in North America placed “ease of doing business with an insurer” (60%) as more important even than “value for money” (53%) – especially in P&C insurance. Respondents said that, because there were often not many opportunities for carriers to interact with their customers, each touch point became critical to their view of the company. Consider then, the importance of forms, which are the primary source of collecting data between carriers and policyholders. Smart forms create a system that allows only the correct information to display once a question is answered, whittling information down to only what that specific customer needs to know and fill out. At GroupHEALTH, as an example, enrollees would mistakenly assume their company plans included coverage not offered by their employers. This confusion led to customers filling out unnecessary forms and back-and-forth that ate up time and resources and increased frustration levels. After the switch to smart forms, however, the system would automatically prompt enrollees to supply missing information, noticed inconsistencies and flagged missing information. It was a runaway success, with GroupHEALTH estimating that, in just the first two months, it reduced the cost to manage enrollments by 20% to 25% -- just from switching to an online-based method. See also: Key to Digitizing Customer Experience   Digital Forms Help Employees, Too: When there are fewer errors, customers are happier (of course), but so are employees. For every mistake on a manual form, an employee must take time to correct it, send it back and re-process it. This cuts time from providing an excellent customer experience, replacing it with tedious correction work. When an online-based forms procedure is implemented, employees are able to spend more time on sales and customer service, rather than dealing with the mundane tasks associated with keeping track of forms and fixing incorrect ones. Online forms offer real-time customer access to policy details, billing, claims and beneficiary information. All of these are as important to the employees as to the customers because they create an environment of efficiency and transparency. Making changes at the ground level with digital documents may seem like a small step toward providing exceptional customer service in a sea of emerging technologies, but it’s also necessary to the health of a carrier’s bottom line.

David Squibb

Profile picture for user DavidSquibb

David Squibb

David Squibb is the chief sales and marketing officer of Xpertdoc Technologies, a leader in the CXM/CCM technology industry. He has extensive experience in sales, marketing, account management and P&L operations.

So Here’s an Idea on Healthcare Reform

What if providers had to specify a multiple of Medicare fees that they would charge, and carriers specified a multiple they would pay?

If you spend any time writing or speaking about healthcare reform, eventually you’re asked the magic wand question: What would you do? Well, there’s an idea I’ve been thinking about. It’s not a Big Fix. It’s merely something that would improve whatever system is in place – I think – by making the system more simple and transparent. I’m sure it’s riven with problems. And maybe it’s a hot topic, but I’ve missed those articles. In any event, here it is. Please let me know what you think I’m missing. The Mechanics The idea is to have providers (physicians, hospitals, clinics, laboratories, etc.) publicize what they charge using a multiple of what Medicare pays. If Medicare pays $100 for a procedure and a doctor charges $300 for the same procedure, this doctor is a 300% provider. Carriers, meanwhile, will set what they reimburse providers as a percentage of Medicare, as well. If an insurance policy pays as much as $250 for this same procedure, it’s a 250% policy. See also: The Math of Healthcare Reform   The key is that this percentage doesn’t vary based on the procedure. Once a provider or carrier sets its multiple, that figure defines the cost for all treatment and services. Consumers gain two bits of information they lack today: what their provider is charging (300% of Medicare in this example) and what their health plan pays (250% of Medicare here). There’s two advantages to using Medicare as the benchmark for pricing. First, it’s already in use today. Second, it assures both providers and payers are using the same measurement. When you say “300% of Medicare,” doctors and insurers know what you mean whether they’re in San Francisco or San Antonio. (If you’re from elsewhere, it means take the Medicare rate, and multiply it by three). Compare this with today, when all they know is that the carrier pays in-network services on a mysterious discount and out-of-network services based on an unknowable formula. What is reasonable and customary? Under my proposal, however, consumers know what the carrier will pay and what they’re responsible for before they walk through the door for medical care. If the proposal were implemented today, a number of things would remain unchanged. Deductibles, co-insurance and co-pays: still allowed. The Affordable Care Act’s essential benefits: covered. Preventive care: not subject to deductibles and co-insurance. How emergency treatment is reimbursed will need to change to a standard multiple of Medicare for all payers regardless of the facility’s usual percentage so consumers aren’t subject to balance billing. Simplicity and Transparency As noted, this idea overlays the current system; it’s not a substitute. This is an overlay, however, that delivers substantial simplicity and transparency. Consumers know up front which providers they can afford. There would be no networks, so there would be no surprises from out-of-network charges, Consumers choose any doctor fully aware of how much of their bill is covered by their health insurance. If they want more covered, they simply choose another provider. Physicians wouldn’t have to guess what carriers will pay them. They’ll reduce their costs as a lot of unnecessary paperwork goes away. However, they’ll also have to compete with other providers in their community. If a doctor is going to charge a lot more than everyone else, she better have a good reason. Hospitals could no long hide behind their charge masters– a menu of prices they charge for services that no one ever sees and few hospitals can explain or justify. These inflated costs are the starting point for pricing negotiations with carriers, so few people ever see them. (Steven Brill wrote a special report for Time magazine in 2013 that explains charge masters and should be required reading for anyone attempting to reform American healthcare). Consumers and their brokers will be able to compare the value of plans on an apples-to-apples basis. If a 400% policy is more expensive than a competitor’s 500% policy, the carrier better be able to explain why. Consumers won’t face unexpected charges, either. They’ll know if their policy will cover all of a given provider’s expense or if they’ll need to pay a portion of the costs. And they can choose their providers accordingly. Carriers benefit from this proposal, too (unless you’re employed in the networking department). Actuaries will have more certainty in determining the reimbursement required under each plan, regardless of whether the provider is in- or out-of-network. With better information on their exposure, carriers can price more accurately. The simplicity of the system will also reduce operating costs, and that’s critical for carriers needing to meet a legally required medical loss ratio. An Improvement, Not a Revolution I know this idea doesn’t fix America’s healthcare system. The goal is to inject greater simplicity and transparency into whatever system is in place. If transparency advocates are right, this will revolutionize healthcare. I’m not sure I buy into the idea that transparency is all that game-changing, but, to the extent it is, this proposal dramatically increases transparency throughout the healthcare system. Single-payer advocates will not be impressed by this idea. However, I believe, in spite of its current momentum, single payer is a long way away. Single-payer proposals cost too much, impose too much centralized control and are too disruptive. The ACA cost Democrats Congress (and arguably the White House), and Obamacare is far less radical than any single payer plan out there. Imagine the political blowback at a government-run insurance program by voters already fearful of death panels and distrustful of Washington? See also: A Way to Reduce Healthcare Costs   ACA supporters should like my approach. A common criticism is that the ACA doesn’t do enough to make healthcare or healthcare coverage affordable. Simplicity saves money. Transparency empowers consumers to reduce their healthcare costs. The ACA plus a Medicare-pegged healthcare system will help the ACA keep its affordability promise. Advocates of reference-based pricing should also be happy. I’m proposing reference-based pricing on a nationwide scale with everyone using the same reference: the Medicare reimbursement schedule. This goes further than most of the reference-based pricing proposals or implementations I’ve seen, but it’s a logical expansion of the concept. And because both the provider and the payer are referencing the same benchmark, litigation — a too-common result of current reference-based efforts — is unnecessary. This proposal isn’t a panacea. The question is, is it a practical improvement? Please let me know what you think – and what I’m missing here – in the comments. This article first appeared on the Alan Katz Blog. 

Alan Katz

Profile picture for user AlanKatz

Alan Katz

Alan Katz speaks and writes nationally on healthcare reform, technology, sales and business planning. He is author of the award-winning Alan Katz Blog and of <em>Trailblazed: Proven Paths to Sales Success</em>.

Next Step: Merging Big Data and AI

By uniting with AI, big data is swiftly marching toward a level of maturity that promises a bigger, industry-wide disruption.

AI is one of hottest trends in tech at the moment, but what happens when it’s merged with another fashionable and extremely promising tech? Researchers are looking for ways to take big data to the next level by combining it with AI. We’ve just recently realized how powerful big data can be, and, by uniting with AI, big data is swiftly marching toward a level of maturity that promises a bigger, industry-wide disruption. What to expect from the convergence of big data and AI The application of artificial intelligence on big data is arguably the most important breakthrough of our time. It redefines how businesses create value with the help of data. The availability of big data has fostered unprecedented breakthroughs in machine learning. With access to large volumes of datasets, businesses are now able to derive meaningful learning and come up with amazing results. It is no wonder then that businesses are quickly moving from a hypothesis-based research approach to a more focused “data first” strategy. See also: Setting the Record Straight on Big Data   But how is big data driving rapid breakthroughs in artificial intelligence? Businesses can now process massive volumes of data, which was not possible before due to technical limitations. Previously, they had to buy powerful and expensive hardware and software. The widespread availability of data is the most important paradigm shift that has fostered a culture of innovation in the industry. The availability of massive datasets has corresponded with remarkable breakthroughs in machine learning, mainly due to the emergence of better, more sophisticated AI algorithms. The best example of these breakthroughs is virtual agents. Virtual agents (more commonly known as chatbots), have gained impressive traction over the course of time. Previously, chatbots had trouble identifying certain phrases or regional accents, dialects or nuances. In fact, most chatbots get stumped by the simplest of words and expressions, such as mistaking “Queue” for “Q” and so on. With the union of big data and AI, however, we can see new breakthroughs in the way virtual agents can learn by themselves. IPSoft’s Amelia A good example of self-learning virtual agents is Amelia, a “cognitive agent” recently developed by IPSoft. Amelia can understand everyday language, learn really fast and even gets smarter with time. She is deployed at the help desk of Nordic bank SEB along with a number of public sector agencies. The reaction of executive teams to Amelia has been overwhelmingly positive. Google’s DeepMind Google is also delving deeper into big data-powered AI learning. DeepMind, Google’s very own artificial intelligence company, has developed an AI that can teach itself to “walk, run, jump and climb without any prior guidance.” The AI was never taught what walking or running is but managed to learn through trial and error. The implications of these breakthroughs in the realm of artificial intelligence are astounding and could provide the foundation for further innovations in the times to come. However, there are dire repercussions of self-learning algorithms, too, and if you weren’t too busy to notice,you may have observed quite a few in the past. Microsoft’s Tay Not long ago, Microsoft introduced its own artificial intelligence chatbot named Tay. The bot was made available to the public for chatting and could learn through human interactions. However, Microsoft pulled the plug on the project only a day after the bot was introduced to Twitter. Learning at an exponential level mainly through human interactions, Tay transformed from an innocent AI teen girl to an evil, Hitler-loving, incestuous, sex-promoting, "Bush did 9/11"-proclaiming robot in less than 24 hours. Should the evolution of AI concern us? Some fans of sci-fi movies like Terminator also voice concerns that, with the access it has to big data, artificial intelligence may become “self-aware” and may initiate massive cyberattacks or even take over the world. More realistically speaking, it may replace human jobs. Looking at the rate of AI learning, we can understand why a lot of people around the world are concerned with self-learning AI and the access it enjoys to big data. Whatever the case, the prospects are both intriguing and terrifying. There is no telling how the world will react to the amalgamation of big data and artificial intelligence. However, like everything else, it has its virtue and vices. For example, it is true that self-learning AI will herald a new age where chatbots become more efficient and sophisticated in answering user queries. See also: Forget Big Data; You Need Fast Data   Conclusion Perhaps we will eventually see AI bots on help desks in banks, waiting to greet us. And, through self-learning, the bot will have all the knowledge it could ever need to answer all our queries in a manner unlike any human assistant. Whatever the applications, we can surely say that combining big data with artificial intelligence will herald an age of new possibilities and astounding new breakthroughs and innovations in technology. Let’s just hope that the virtues of this union will outweigh the vices.

Anas Baig

Profile picture for user AnasBaig

Anas Baig

Anas Baig is a cyber security journalist and tech writer. He has been featured on major media outlets including TheGuardian, Lifehacker Australia, CSO, ITProPortal, Infosec Magazine, The Next Web, Developer, Tripwire and many others.

Ready for Fourth Industrial Revolution?

The IoT will generate trillions of dollars of economic output -- but we need to start planning now to take full advantage of Industry 4.0.

Every generation or so, technology takes a giant leap forward. Steam power, electricity and computing – each revolutionized the way we live and work. Where once it was the loom, the lightbulb and the mainframe, today it’s the internet’s turn. Since its creation in the 1980s, the World Wide Web has grown at an explosive rate and can now do so much more than help people share information. Today, the web is evolving – to bring together people, businesses, machines and logistics into the Internet of Things (IoT). The IoT is leading the fourth industrial revolution – known as “Industry 4.0.” It has the potential to transform our understanding of how everything can be connected and deliver enormous value to the world. Recent studies have estimated that it could add $14.2 trillion to the global economy by 2030. But if the IoT is to deliver on its immense potential, then businesses also need to get serious about tackling the new risks this era of connectivity promises. A Brief History of Industry 4.0 Before the 1780s, people worked with their hands – there was no such thing as "industry." Then came the steam engine, enabling high-speed transportation and mass production in factories. The world was transformed in that first industrial revolution. The second began in the 1870s with the widespread adoption of electricity, oil and steel – leading to such inventions as the light bulb, the telegraph and the internal combustion engine. In the 1970s and 1980s, the silicon chip heralded the third industrial revolution with the rapid rise of computing and robotics. Today, we are in the midst of Industry 4.0. This is being driven by the global spread of the internet; new technology such as wireless sensors; and the dawn of artificial intelligence (AI). Like its predecessors, Industry 4.0 will transform the way we live and work. See also: Welcome to the Robot Revolution   How Industry 4.0 Will Change Everything At a fundamental level, Industry 4.0 could unite the digital and physical worlds to offer a whole new universe of opportunities to gather and use information. This has the potential to improve efficiency and encourage innovation on a massive scale. Operational efficiencies: When sensors can be placed almost anywhere, businesses are able to gather detailed insight into how their machinery and processes are operating. For example, imagine a company warehouse – it’s been run the same way for years and is functioning effectively. The company decides to install IoT sensors in the warehouse to monitor how the staff pick and place goods on the shelves. Analysis of the data from the sensors shows that forklift drivers are taking 30% longer journeys than necessary. New routes are devised, and productivity increases with minimal investment. IoT can also help improve maintenance processes. Predictive maintenance – which can identify maintenance issues in real time – allows machine owners to perform cost-effective maintenance before malfunctioning technology becomes critically damaged. A key value proposition of industrial IoT is being able to determine ahead of time machinery that might fail, and take action based on that information. For instance, a company in Los Angeles could understand if a piece of equipment in Singapore is running at an abnormal speed or temperature. The company could then decide whether or not the equipment needs to be repaired. Improved understanding of risk: Better visibility into operations helps organizations identify risks and take steps to mitigate them. Many industries say that IoT is helping, or has the opportunity to, lower overall risk in the organization. In 2014, for example, 20% of worker deaths happened in the construction industry. Providing construction workers with wearable tech devices can give companies the data they need to understand how employee accidents happen, so they can improve safety procedures. More sensors collecting device data mean that risk can also be better understood and priced from an insurance perspective. This has already happened in the automotive sector with telematic usage-based insurance. Wireless monitors inside a car or truck can collect precise details on how an individual drives and use that data to construct tailored insurance packages. The growth of a new data economy: The proliferation of sensors means every business is now potentially a data business. Stankard gives the example of a maker of agricultural equipment, which can harvest the data from its devices to design and sell business optimization plans. In the future, the largest revenue stream that companies will likely have is going to come from selling data and selling production efficiency consulting around their own equipment. It’s a completely new business model for a company that for a hundred years was focused on making and selling capital equipment. New World, New Risks The opportunities presented by Industry 4.0 are enormous. But to realize them, we will have to come to terms with an entirely new risk landscape. Cyber Risks Up until the IoT, industrial machinery was not online. There was a physical “air gap” between the production process and the web. The connectivity that Industry 4.0 brings means that this is no longer the case. Cyber risk is consequently amplified. In 2015, hackers in Ukraine compromised sections of the country’s power grid by infecting plant operators’ IT networks with a virus hidden inside an Excel spreadsheet. One study from Kaspersky Labs found that 39% of computers involved in operating industrial infrastructure were subject to a cyber-attack in 2016. Cyber risks themselves are likely to give rise to risks in other areas. For instance, governments are likely to respond to increasing cyber threats with tough new regulations, which will themselves mean new risks for companies. The EU’s General Data Protection Regulations (GDPR), due for implementation in 2018, governs the handling of any data relating to EU citizens, with heavy penalties for non-compliance. Understanding these risks and the regulations they may prompt, and putting into place appropriate measures to mitigate them, will be critical – as will nurturing a culture of collective corporate cyber responsibility. In an age where a single misplaced USB drive can corrupt the operational integrity of entire systems, education and accountability are vital if vulnerabilities are not to become gaping cracks in defenses. Talent Risks A changing world means that the people and skills that businesses need will also change. The first industrial revolution, centered on the British textile industry, put many weavers out of work, prompting riots across the country. But it simultaneously created demand for machine operators. Industry 4.0 is likely to prompt changes of its own to workforces. Overall, there’s no clear consensus on whether the mass automation that will likely become part of Industry 4.0 will have a net positive or negative impact on jobs. Some argue that, as in previous revolutions, technologies like automation will increase wealth and productivity without affecting overall levels of employment. Other studies suggest a more pessimistic future of declining rates of employment and pay. What is certain is that talent requirements will change. It is predicted that there will be a 2 million worker skill gap in manufacturing after the baby boomers start retiring, which will go unfilled between 2015 and 2025. Organizations involved in the future of industry and manufacturing will need to address the lack of skill development with better training and education programs. See also: How to Respond to Industry Disruption   Embracing the Future Industry 4.0 is opening significant opportunities for organizations. From re-evaluating business models to new data-driven revenue streams, the possibilities are limitless. However, there is going to be significant incremental risk, likely posed by cyber and the immense – and growing – amount of connectivity. There is a risk reduction element here, as well. With such levels of connectivity, Industry 4.0 is likely to isolate and improve quality issues and enhance the overall customer experience. Organizations will need to rise to these challenges to fully take advantage of the amazing new opportunities Industry 4.0 will offer.


Michael Stankard

Profile picture for user MichaelStankard

Michael Stankard

Mike Stankard leads the industrial & materials practice group that focuses on growth with major industrial manufacturers including (but not limited to) the following sub-industries: automotive, metals, industrial equipment, building materials, construction/agricultural equipment and defense contractors.

Harvey Hammers Home NFIP Issue

As National Flood Insurance Program comes up for renewal, it may be time for the federal government to get out of the flood insurance business.

The economic devastation and human suffering that Hurricane Harvey inflicted on vast numbers of people will sorely test the National Flood Insurance Program (NFIP) as it comes up for renewal, with the NFIP lapsing if Congress and the president fail to act by the end of the month. Some in the federal government, state regulators, industry experts and this economist favor solutions encouraging private sector participation in flood insurance markets. Near-term, the most likely and wisest course seems to be a short extension allowing the Federal Emergency Management Agency (FEMA) and NFIP to focus on settling claims while politicians and policy experts develop longer-term solutions. With the U.S. Government Accountability Office (GAO) reporting the NFIP was $24.6 billion in debt before Hurricane Harvey, many in government and elsewhere feel significant reforms are needed. Other knocks against the NFIP as currently constituted include its reliance on allegedly inaccurate and out-of-date flood insurance rate maps (FIRMS), its failure to charge actuarially appropriate premiums and policy limits too low to provide adequate insurance protection. Some also contend that the NFIP encourages excessive risk taking and poor land use by providing subsidized insurance coverage for properties that repeatedly get flooded out, effectively divorcing those who choose to reside in flood prone locations from the consequences of their decisions. Uncertainty about the exact extent of the devastation caused by Harvey will persist for some time, as the huge number of properties damaged by the storm, difficult conditions and continuing lack of access to some of the hardest-hit areas all add to the time necessary to assess losses. Further complicating efforts to understand the magnitude of the losses caused by Harvey, published reports often fail to clearly distinguish between economic losses, insured losses covered by private carriers and insured losses covered by the NFIP. Nonetheless, it appears Hurricane Harvey may exhaust the NFIP’s financial capacity, causing the program to go still deeper in debt. See also: Harvey: First Big Test for Insurtech   The NFIP purchased private reinsurance covering 26% of its losses between $4 billion and $8 billion, but Fitch Ratings believes losses from Hurricane Harvey could consume the NFIP’s $1.04 billion in reinsurance protection. As Congress and the president ponder the way forward, the options available to them include several that would facilitate development of private markets for flood insurance akin to the private markets for homeowners insurance. Key elements of such solutions include measures clarifying mortgage lenders’ ability to use flood coverage underwritten by private carriers to satisfy insurance requirements imposed by Fannie Mae and Freddie Mac. The development of private markets for flood insurance will also require that the NFIP adopt actuarially sound pricing. Simply put, private carriers that must cover their costs and earn an adequate rate of return on capital would be at a tremendous disadvantage competing against taxpayer-subsidized coverage from the NFIP. And it would certainly help if carriers currently participating in the NFIP’s WYO Program were allowed to also offer alternative coverage. Currently, the WYO Program includes a non-compete clause that precludes carriers from offering alternative standalone flood insurance. The constituencies supporting increased private sector involvement in flood insurance markets include the National Association of Insurance Commissioners, the Property Casualty Insurers Association of America, the National Association of Mutual Insurance Companies and the American Insurance Association, which have all come out in favor of the Flood Insurance Market Parity and Modernization Act passed unanimously by the House in 2016. Thinking more broadly, there may be no need for the federal government to participate directly in the flood insurance business. Mechanisms akin to state FAIR and Beach Plans could serve as insurers of last resort for property owners unable to obtain coverage from private carriers. Or, we could transition from the NFIP as it exists today to a new NFIP modeled on the Terrorism Risk and Insurance Program (TRIP) introduced after the terrorists destroyed the World Trade Center on Sept. 11, 2001. Under that program, insurers must offer terrorism coverage, with policyholders then free to accept or decline. If insured losses from a terrorist attack exceed specified triggers, the federal government provides reinsurance protection, and insurers subsequently reimburse the federal government. Thinking still more broadly, there may be no need for the federal government to participate in the flood insurance business at all. With trillions of dollars flowing through global capital markets, catastrophe bonds and other insurance-linked securities could enable insurers and reinsurers to obtain all of the capacity necessary to cover flood risk without any federal reinsurance backstop. See also: Time to Mandate Flood Insurance?   An ideal solution would enable one policy to provide coverage for both wind losses and flood losses. As long as those losses are covered by separate policies, policyholders and insurers will remain burdened with having to distinguish wind losses from flood losses— a frequently contentious and often expensive undertaking that adds to the time necessary to settle claims. In any case, private sector insurers and reinsurers now have access to data and sophisticated flood models that enable them to price and underwrite flood risk intelligently. And developments such as the new commercial flood insurance program recently introduced by ISO and Verisk Analytics set the stage for greater participation in flood insurance markets by ever greater numbers of insurers, as will the corresponding personal property flood insurance program they plan to roll out later this year. With state regulators and insurers aligned, it seems all that’s necessary to unleash the power of private markets is action on the part of Congress and the president. Why not send them a postcard?

Michael Murray

Profile picture for user MichaelMurray

Michael Murray

Michael Murray is a University of Chicago-trained economist passionate about providing decision-quality information and insight that helps others profit from deep understanding of both the big picture and subtle nuances.

Harvey: First Big Test for Insurtech

We're all excited by insurtech's prospects -- but it’s easy to feel smart before the test begins. Let's see what Hurricane Harvey shows us.

As Hurricane Harvey finally relents, the insurance industry is about to experience the flip side of a famous line from Warren Buffett. Talking about how investment portfolios shouldn’t be judged in good times, Buffett said, “Only when the tide goes out do you discover who’s been swimming naked.” Well, with the rain and the rain and the rain that Harvey inflicted on Houston and surrounding areas, we’re going to get to see who in the insurance world can swim. That question will take two forms, one that we’ve seen in every disaster since time immemorial, but the other a new one, about insurtech. The normal one is about whether insurers will perform in their moment of truth, or whether we’ll find the kinds of dubious decisions by adjusters and faked engineering reports that led to improperly denied claims and gave insurance a black eye after Superstorm Sandy. In the case of Harvey, the question for the industry is, essentially: Do insurers want to be Joel Osteen or J.J. Watt? As you may know, given that he’s all over TV, Osteen is the senior pastor at a megachurch in Houston who was mocked on social media for being slow to open the doors of his “prosperity gospel” Christian church and provide shelter and aid for those displaced by the hurricane. He says that he has been maligned and that he was always ready to help, if the city had asked, but his many critics have noted that nobody had to ask Houston’s mosques to open their doors and made Osteen the king of memes this week. Osteen is damaged. The only question is how badly. On the flip side is J.J. Watt, the all-everything defensive lineman for the Houston Texans. Very early in the storm, he made a personal pledge of $100,000 and asked for others to kick in, stating a goal of $200,000. Well, his sincerity and concern went viral, drawing donations from tiny to huge, from Drake to Walmart. Last I checked, total donations exceeded $20 million. With the waters receding, Watt and teammates will be personally going around the city, delivering water, clothing and everything else he’s bought to hand out. He could run for king in Texas, and nobody would get in his way. While acknowledging that insurance is a business that has no obligation to pay more than it owes policyholders, I think the choice is clear: Be like J.J. Watt as much as you can. Don’t be Joel Osteen. See also: Harvey: Tips to Avoid Claim Issues   The new question is trickier. The insurtech movement has been around for a few years now, but Hurricane Harvey is the first true catastrophe that has happened during a time when the insurance industry is laying a claim to innovation. (For good measure, Typhoon Hato has been hammering Macau and Hong Kong at the same time.) We’re about to find out how innovative we really are. Some companies are following the traditional playbook and dispatching armies of adjusters to the afflicted region. But we’ll also see the skies filled with drones and will learn how effective they can be at documenting the damage and how much their work still has to be supplemented by humans. We’ll learn a lot about the “gig economy” and whether part-time workers, such as the “Lookers” provided by WeGoLook, can efficiently supplement the full-time insurance workforce, speed the process of claims and slash away at the costs of sorting out a full-on disaster. Supposedly, insurtech is letting everything happen faster. Startups such as ViewSpection and MondCloud provide for self-service on claims, letting individuals send photos and videos and allowing insurers to do triage and pay easy claims quickly. But reality may intrude. Every time I see a photo of some aid facility and spot a sign saying “Free legal services,” I want to applaud those who are helping the injured pro bono, but the cynic in me sees lawyers fishing for clients. I suspect that the hurricane is a full-employment act for every recent law school graduate in Texas. The lawyers, of course, have a vested interest in avoiding quick settlements, so they can work the insurers, take thousands of cases to court and perhaps find some lucrative class actions. Insurtechs, meet lawyers. We’ll have to see how that goes. I don’t often bet against the lawyers. Insurers have begun using chatbots, such as Pypestream’s, in their call centers, which should help handle the deluge of calls that will come in from customers and allow insurers to contact customers more often and more effectively to keep them up to date on the progress of claims. We’ll have to see how insurers do about handling customers' concerns in these hours and days and weeks of need, as well as what role technology plays. Better data and analytics, sometimes powered by AI, are supposedly making us all smarter about mitigating risks, underwriting and everything else, but it’s easy to congratulate yourself on being smart when you don’t face a test. In the real test -- accuracy -- I’d say insurtech startup HazardHub wins early points for putting out an analysis right before the storm saying that $77 billion of property was at risk in Houston, quite a bit higher than other estimates I saw – though lower than some estimates now circulating, and damage estimates always seem to grow, never diminish. We’ll see whether the powerful new analytics let any company in particular get away from the risks in Houston – keeping in mind that ProPublica identified the particular risks in Houston, because of lack of restrictions on real estate development, in a story published last year. If the journalists could spot the risks, how did the insurers do? The verdicts will take weeks and months to come in, because the damage has been so extensive and because problems are still developing in what continues to be a stew of mold, fetid water and chemicals. But we’ll get a sharp sense of where innovation has, in fact, happened and where it needs to go – if we keep our eyes open, evaluate the results honestly and take the lessons seriously. There’s one other question that needs to be answered, too, this one on the government policy level. Flood insurance isn’t working in the U.S., so what do we do about it? Perhaps lulled by a lack of major storms hitting the U.S., homeowners have increasingly declined to purchase policies, so estimates are that 80% to 85% of homes in Houston were not covered. Meanwhile, the National Flood Insurance Program (NFIP), which provides so much of the coverage, is already heavily in debt because it underprices risk and hasn't recovered from Superstorm Sandy. By law, the NFIP needs to be renewed this month, but we’ve all seen how dysfunctional Congress is these days, and Congress has even more pressing priorities this month, such as dealing with the budget and raising the national debt ceiling. The best proposal I’ve seen so far is to require that homeowners and renters insurance, commercial property policies, auto policies and so on all have a flood piece to them, so that citizens carry the responsibility and so that risk is priced in the market, rather than being dumped on the federal government. See also: Time to Mandate Flood Insurance? One person attached a compelling comment to this article on how the federal government, not insurers (and, ultimately, the insured public) will pay for the recovery from Hurricane Harvey: “Homeowners have three options: 1) buy flood insurance through the NFIP, 2) live in a non-flood plain or 3) accept the risk of living in a flood plain. Option 4 of Harvey victims expecting insurers/taxpayers to compensate them for their increased risk is not an option.” A century ago, in the earliest days of IBM, founding CEO Tom Watson Sr. placed signs in offices that said, “Think.” When the company sparked fears of bankruptcy 25 years ago, wags penciled in two words underneath some of those signs, so they read, “Think – or Thwim.” Flood insurance in the U.S. is in “Think or Thwim” mode. I hope we think.


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Time to Mandate Flood Insurance?

We should abolish the NFIP and mandate property coverage by all owners and tenants in property, auto and other policies.

According to this article, only 15% of homeowners in the Houston area have flood insurance: "As of August 2016, just 15% of the 1.6 million homes in Harris County, where Houston is located, had flood insurance, according to emailed data from the Insurance Information Institute, and only 28% of the homes in 'high-risk' areas for flooding." See also: Hurricane Harvey: A Moment of Truth  We all know the reasons why people don’t buy flood insurance. They think, “It’ll never happen to me.” It’s too expensive. They don’t have to. They don’t know they need it. Or, they’re told they don’t need it in idiotic articles like this one that can be found plastered all over the internet: “Unless you live in a flood plain or an area with a history of water problems, don’t even bother buying flood insurance. If none of the homes in the area has ever been flooded, yours is unlikely to be the first.” Last month, in a blog post about healthcare, I raised the issue of whether we should explore an alternative system to how we currently insure catastrophic exposures to loss: I’ve opined for years that we should abolish the National Flood Insurance Program (NFIP) and windstorm pools, mandate property coverage by all owners and tenants and include flood and windstorm damage in standard homeowners, commercial property, auto and other policies. Minimum and maximum catastrophe loadings could be established so that there is some degree of subsidization in more risky areas. CRITICAL, though, would be mandated loss control measures, including zoning restrictions, building codes and so forth. Loss prevention and reduction would be absolutely necessary components of an insurance program, as they should be now. The reality is that, unless the risk of loss is almost definite or coverage is mandated, people simply will not buy the coverage. And if the risk of loss is high, the cost of insurance is either unaffordable or results in adverse selection and repetitive losses. While the focus today is on flood, this holds true for other catastrophic exposures like earthquake. Is this doable? Should property insurance be mandated and include catastrophe premium loadings similar to civil disorder charges applied in the late '60s? Can the risk of loss be spread enough that the private sector can manage it? Can commerce and governments work together to invoke loss control measures to mitigate loss to manageable levels? What are the issues? What are the obstacles? Can they be overcome? See also: Harvey: Tips to Avoid Claim Issues   Your comments are welcome below. And, please, no political rants, just rational and respectful arguments, points and counterpoints.

Bill Wilson

Profile picture for user BillWilson

Bill Wilson

William C. Wilson, Jr., CPCU, ARM, AIM, AAM is the founder of Insurance Commentary.com. He retired in December 2016 from the Independent Insurance Agents & Brokers of America, where he served as associate vice president of education and research.

Why to Refocus on Data and Analytics

Insurers must change direction and move from the data-and-analytics-investment “comfortable zone” and over into innovation.

Data and analytics is a phrase that is probably in 75% of articles and blogs written today on the industry. In fact, data and analytics is used so frequently that it almost appears to be one word – dataandanalytics. SMA research shows that 92% of insurers have data and analytics initiatives under way in 2017. It is the number two initiative, only three percentage points behind customer experience, to which it is closely aligned! The importance of data and analytics to the enterprise is no longer debated. However, there is danger in this. A level of complacency has crept into how insurers are addressing data and analytics requirements. SMA survey results show that, on average, 65% of insurers are investing in reporting and dashboards and scorecards, spanning both personal lines and commercial lines of business. Clearly, it is important to do this because managing day-to-day operations is critical. However, and this is the salient point, investing in these areas is historical – it’s where the money has been going for quite some time. See also: Analytics and Survival in the Data Age   The flip side of this picture is that 80% of survey responders indicate they have no plans for investing in cognitive computing, and 37% have no plans for investing in data and text mining. Use cases follow the same pattern. In terms of the customer and distribution, insurers have been investing in new business analysis and agent performance for years. Yet, 53% of survey responders say they have no plans for using data and analytics for single view of the customer. Numerous other examples abound, as detailed in our research findings. The insurance industry is definitely focused on investing in data and analytics, but the research shows that the investment is in the same areas, for the same purposes. Insurers continue to get good at what they are already good at. And it is hard not to do this … the positive results are compounding! But one huge factor is making this direction untenable – the pace of change. Technology, particularly technology coming from insurtech organizations, is exponentially advancing. Customer expectations and the rapidly evolving nature of risk are figuratively (and somewhat literally) running right along next to these emerging technologies, eager for the value being delivered. When it comes to emerging data sources such as the IoT, wearables and drones, there are a handful of insurers that are embracing the data and developing capabilities. Yet, as many as 82% of insurers have no plans to leverage these data sources. Those insurers advancing with new data sources are rapidly creating a gap that insurers with no plans will find difficult to bridge. This is another example of where the pace of change will have a big influence. See also: Data and Analytics in P&C Insurance   A great percentage of insurers are poised to change direction and move from the data-and-analytics-investment “comfortable zone” and over into innovation. Significant work has been done from an organization and role perspective in terms of data and analytics teams, particularly at an enterprise level. But the measured steps of the past need to be replaced by a faster pace and focused on new targets that emulate the world that we live in. SMA’s recently released report, Data and Analytics in Insurance: P&C View Through 2020, provides a deep dive into the state of data and analytics today, as well as plans for the future. The report also features an updated version of SMA’s proprietary Data and Analytics Spectrum, which provides a framework for insurers to benchmark their initiatives. It also details the various components of a robust data and analytics strategy. Or is it a dataandanalytics strategy?

Karen Pauli

Profile picture for user KarenPauli

Karen Pauli

Karen Pauli is a former principal at SMA. She has comprehensive knowledge about how technology can drive improved results, innovation and transformation. She has worked with insurers and technology providers to reimagine processes and procedures to change business outcomes and support evolving business models.