Download

The New Competitive Advantage

Nowadays, customer experience is the biggest competitive leverage a business could use to win the market.

|||

We are living in an era of overabundance. Consumers have more choices than ever. To survive, companies have switched from product-centric to customer-centric.

Nowadays, customer experience is the biggest competitive leverage a business could use to win the market. I am a big believer in the customer-centric approach. Companies that put customers at the center of their strategy are winners at this new era. Just think about why Google beats Yahoo in the search engine, why Apple can sell a smartphone twice the average market price or why Uber has taken over the taxi market.

A few months ago, I was invited by Anand Chopra-McGowan of General Assembly to give a talk at Telefonica. The topic was about “Frictionless Customer Experience” (FCX). It was the first time I heard about that term. However, FCX instantly captures my attention, because of the natural fit with what I am trying to do with Landbot.io.

The simplest definition I would give about FCX is:

A mindset of a business that pursues continuously the right product to customers at the right moment and in the right channel.

The three key concepts that define FCX are product, moment and channel. So lets take a close look at each one.

Right product

So what is the “right” product? The mission of every business is to provide a product that can solve a problem and satisfy customer’s need. (By "product," I mean anything material or digital goods that you can packetize with a price and some specifications: A software platform or consulting service both can be considered as a product.)

As human beings, we are easily affected by our bias of what’s best for clients.

There is a study by Stanford where a group of students was asked to draw a capital letter “E” on their forehead. Below, you can see the result:

[caption id="attachment_27733" align="alignnone" width="303"] Different ways to write “E”[/caption]
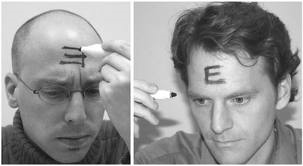
It turns out that we can draw this E in one of two ways: one self-focused “E,” like how you are seeing it as you draw it, and another “E” from someone else’s perspective. In this case, more than 90% of the people drew a self-focused “E.”

That is what happens most the time when we are designing our product. To provide the right product, we need a clear understanding of our customers: Who are they? What are their pains? What do they usually do?

See also: Why Customer Experience Is Key  

Only when we truly comprehend the context of our customers can we design, build and ultimately deliver a product that best fits with their need. A handy tool that can help us understand our customer is the Customer Empathy Map. It’s a collaborative tool we can use to gain a deeper insight into their clients. Below is an example. More information is here
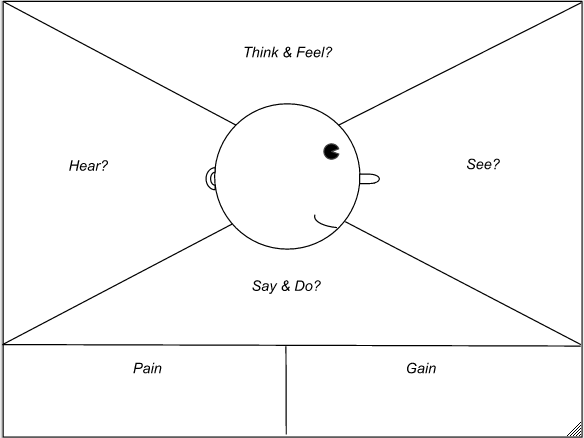
To fill out all the info in the canvas, you can do lots of online research, but the most efficient way would be doing customers interviews. Only by getting out of the building and talking face to face with potential customers can you get all the data needed to understand them.

An excellent example of this is how Snapchat designed its video sharing feature. Before, the videos you saw on the mobile were always in landscape mode. However, Snapchat realized that the natural position for people to use their phone is in the vertical position, so the company designed the whole user experience around vertical videos, which turns out to be a huge success. Now, many camera-related applications have followed this new design paradigm.

Right moment

Once we have built the right product, we have to deliver it to the customer at the right moment. When is that?

Conventional wisdom would say we should provide the product whenever our customers need it most. Therefore, the job of marketers has always been building strong connections between the desire and the product. Then the business has just to be there for customers to consume the product. That’s basically how we have been running businesses in the 20 centuries. When you are hungry, you think of McDonald's, or, when youre thirsty, Coca Cola may be the first that comes to your mind.

However, with the increasing competition in today’s market, the old approach is no longer enough. Recent research by Microsoft shows that human attention span has fallen from 12 seconds to 8 seconds, which is shorter than a goldfish!

If everyone is competing to get the attention of consumers, how can you stand out and win? One possible way is to anticipate the users' needs even before they realize it. To offer FCX, we have to bring our customer communication to another level. We need to think deeply about our customer journey and always be one step ahead to help the client getting the product.

As technology advances, many companies start using big data and machine learning to predict user behaviors. This kind of prediction allows companies to take actions either to prevent undesirable behavior (customer churn) or to provide incentives for good behavior (purchase intention).

A good example, in this case, would be Pepephone, a Spanish mobile virtual network operator (MVNO). It’s known mainly for great customer service and user friendliness.

There was one time when Pepephone suffered a major outrage of its network system late at night. The incident was solved quickly; many customers weren’t even aware of it. However, unlike other telco companies would do, Pepephone called all the clients who might be affected. The company offered a discount to these customers as compensation for the outage, regardless of whether they complained. Actions like this demonstrate how Pepephone has always put their customer in the first place, which in turn helped the company to become No. 1 profitability and customer loyalty in the industry.

Right channel

If we did a great job with the previous two points, we should have a clear understanding of what product we should build and when to deliver it to customers. The last but not least thing we have to take into account is the way (channel) we use to interact with customers. “Be where your customers are” has been the first rule of success for every business. History told us that each time a new “channel” emerges, a whole new market could build around it. Those companies that know how to take full advantage of the new medium become winners at a new market. Think about what Microsoft did with the personal computer, Apple the smartphone, Uber with mobile applications, etc.

So what channel should you use? To choose the best channel, we need to keep in mind two important factors:

  • Target: is your customer using this channel? Think about which kind of user segment you will get using the channel. It doesn’t make much sense for an enterprise B2B company to work on Snapchat because it won’t attract the correct kind of user.
  • Saturation: Most channels tend to reach a saturation point after which it will be tough for new players coming in. Example: It will be quite difficult to start a new mobile app company right now due to the market share of some big corporations. If you look at the ranking of top 10 apps, most of them are from companies like Facebook, Google and Snapchat.
  • Openness: you should look for the flexibility and the scalability you can have with a particular channel. Does it offer tools for third-party developers like APIs? Analyze possible risks of being cannibalized by native solutions from the channel. You don’t want to experience what happened to Meerkat when Twitter banned it from the social network.
See also: How the Customer Experience Is Shifting  

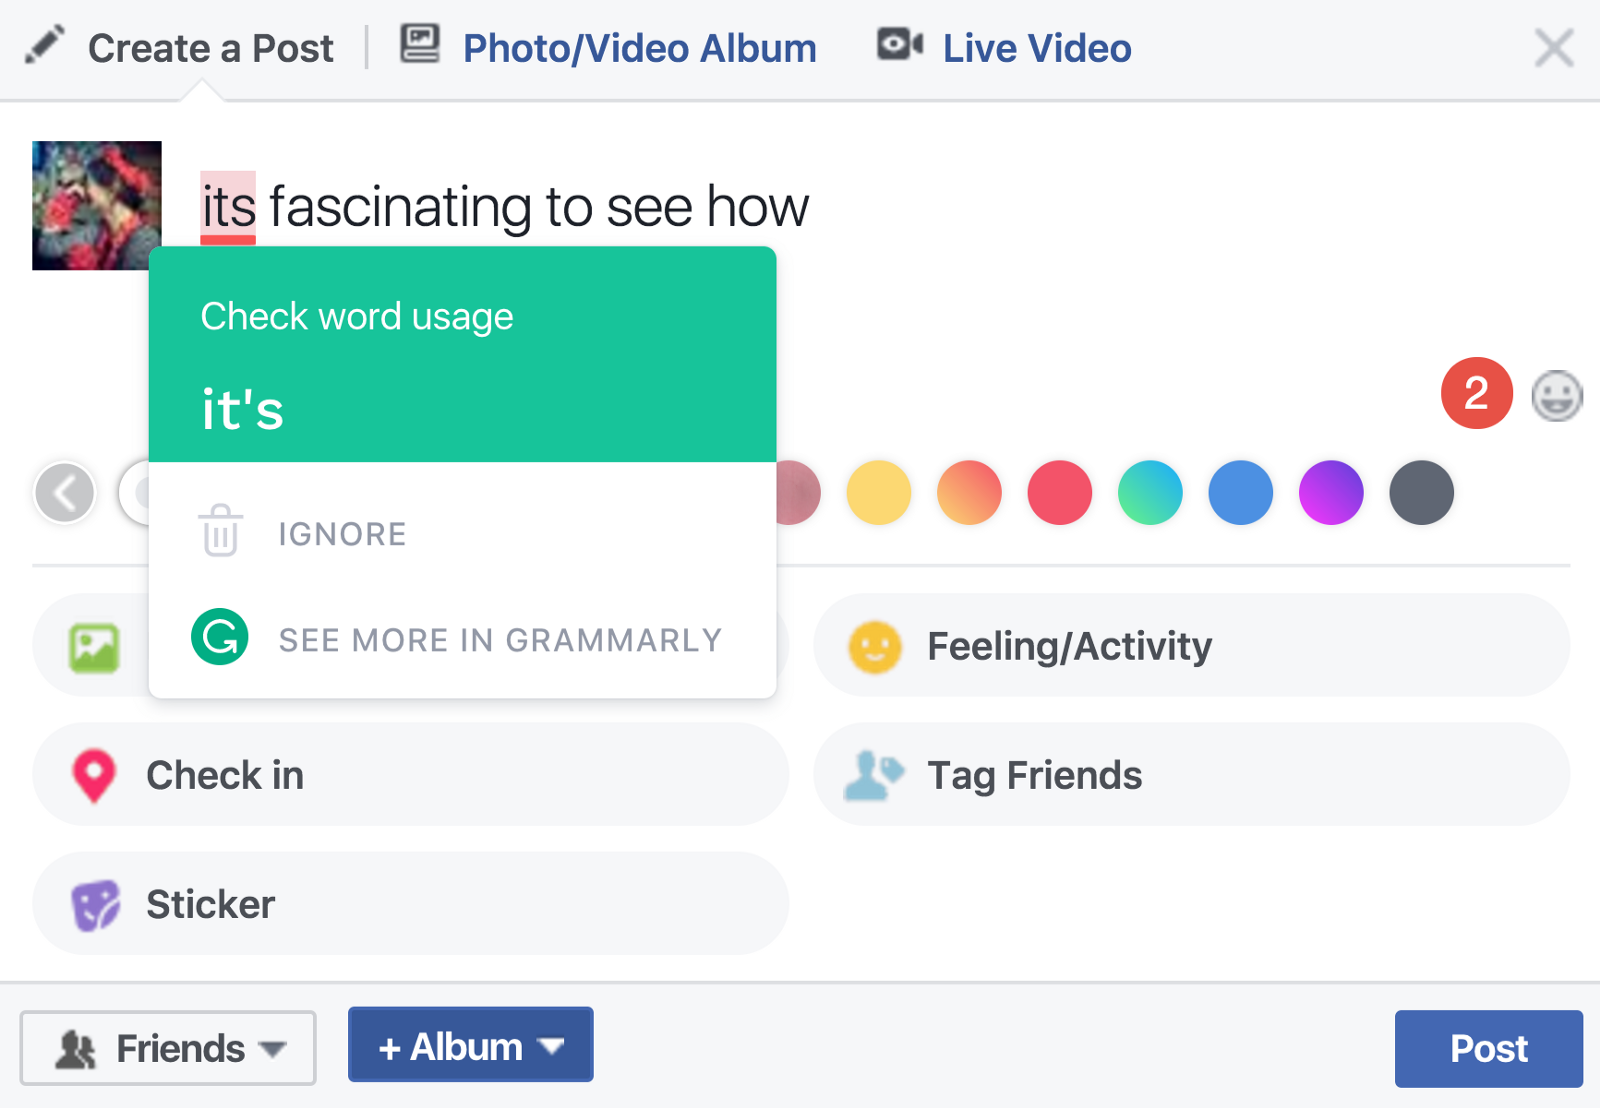
A fascinating case study is Grammarly, the best grammar checking tool on the planet. My friend Hiten Shah wrote a few days ago an in-deep review of how Grammarly grew into millions of users. One key point in the strategy was that the company had designed the product to be where customers are. Grammarly built plugins for Microsoft Office and later as Chrome extensions so people can use it where they need the tool most: when writing a post, filling job forms, editing text documents, etc.

[caption id="attachment_27735" align="alignnone" width="570"] A screenshot of a user editing his facebook post with Grammerly[/caption]
I hope these brief thoughts about FCX could help you design a better product, delivering it to the customer when and where it's needed.

Do you have any thoughts or examples about FCX? Let me know in the comment section. If you enjoy this article and would like to read more about FCX you can support me by giving some claps ? (up to 50 would take less than one minute).
Jiaqi Pan

Profile picture for user JiaqiPan

Jiaqi Pan

Jiaqi Pan is CEO of Landbot.io, an exciting tool that will allow you to turn any landing page into a conversational experience. Since 2015, Pan has also been the CEO of Helloumi, which helps businesses to do customer communication at scale with instant messaging.

Perspectives From Injured Workers

We gathered thoughts from injured workers, whose voices are crucial in workers' comp but are too-seldom heard.

Many stakeholders in the workers’ compensation industry have been engaged in conversations regarding opportunities to improve the workers’ compensation system. The perspective of injured workers has been lacking in these conversations. This perspective has been difficult to obtain because there really are no respected “injured worker” advocacy groups such as there are in the group health setting. Attorneys and unions are not the true voice of the injured worker – they have their own sets of priorities. The voice of the injured worker is an important one. It will help us gain a deeper understanding of the challenges in the workers’ compensation setting as well as give us greater empathy for what they are facing. At the 2016 Comp Laude Gala, the Alliance of Women in Workers’ Compensation sponsored a session featuring injured workers talking about their struggles. It was an extremely powerful and moving experience that left few dry eyes in the packed room. In this article, we attempted to capture the essence of this session. Our goal is for this information to be used to help us better understand the obstacles faced by injured workers so that we can be better advocates for them and, ultimately, achieve better outcomes on claims. The Participants The participants included an injured worker in recovery from his dependency on opioids, regaining his life 14 years after his injury. Another, with two prosthetic legs, continues working and leaves a legacy for the workers’ comp community. A third participant was a woman with incomplete quadriplegia, who started a business helping others with chronic pain. We’ve heard these stories before. The question is, however, what makes these cases different? How have these injured workers been able to get back to function and work despite debilitating conditions that leave others homebound and drug dependent forever? All three of these injured workers have unique personalities that may have contributed to their successes. But the one thing they have in common that was a deciding factor for all was support, positivity and encouragement from people around them – especially those in the workers’ comp industry. The stories they shared should serve as lessons for the workers’ comp community to illustrate that what we say and do makes a difference. It sends a message that by taking responsibility for our actions, words and decisions, we can truly make a difference for injured workers and our companies. The Stories Kenny: “I had never hurt my back in my life, but I twisted it lifting something.” That was in 2000, before his 40th birthday. By 2014, Kenny had undergone two surgeries, multiple implants, epidurals, a myelography – which he described as “the worst thing in my life” – and was prescribed a cocktail of various opioids, including a fentanyl patch and oxycontin. He had been told by a medical professional in a Florida hospital that he would likely be dead in two years from all the medications he was taking. “Your mind just goes,” he said. “You’re useless. Suicide – it’s right there.” Two case managers and several years later, things were no better. Though he wanted to work again, the back fusions on L4 and L5 left him unable to walk and the meds left him in a zombie-like condition. “We were young. It was scary,” said Kenny’s wife, Karen. “I lost my husband, my boys lost their dad.” See also: 3 Reasons to Talk With Injured Workers Kenny and Karen’s story might have continued that way forever, if not for the arrival of their third caseworker 12 years after the initial injury. “It was like she flew in on angel wings,” Karen said. “She took the time to get to know him. Nobody else did.” At the end of their very first conversation, the new caseworker promised she would get Kenny fishing again – one of his favorite pastimes, and said she would go with him. “That’s a really big deal,” Karen said. But the road ahead was not to be an easy one. The caseworker’s plan to send Kenny to a Florida hospital for treatment didn’t sit well; at least, not with Kenny. It wasn’t until the following weekend during a family anniversary party that his sisters, wife and sons convinced him to go along with the treatment plan. At the hospital, he received rehab, biofeedback and the care he truly needed to be able to function again. Six weeks later he was no longer taking the hydromorphine, or the fentanyl, or the oxycontin, or the percocets, or the duragesic patches. Three years later he is still off the medications, including aspirin. He goes to the gym daily to walk, do light stretching and exercise. “I’d tell anyone, ‘Get off the drugs; that’s 50 percent of your pain,’” he said. “Your body will help heal you.” For Kenny, a single individual was able to change his life. A physician had previously told him he ‘was as good as he was going to get.’ The first case worker was “distasteful,” and the second never showed up. But the third caseworker had a different approach. “It just really matters what you say — as a doctor, nurse or case manager. And that was the big difference for us,” Karen said. “She never said anything negative. She always said, ‘we’re going to do that,’ ‘we’re going to get you to that,’ ‘we’re going to go here, it’s going to be great,’ And we believed it.” Becky: It’s been more than a decade since Becky was lying in a hospital bed with a broken neck, two collapsed lungs, all of her ribs on one side broken, and a broken clavicle. A work-related auto accident rendered her ‘an incomplete quadriplegic.’ “My spinal cord was not quite severed; damaged, but not severed,” she explained. “My left side has partial paralysis. My right side looks normal, but I can’t feel hot or cold, sharp or dull [sensations].” Because her body no longer functioned the way it had before the accident, she had to learn how to walk again and to function with one hand — since the other does not work. Then, two years later, she developed burning nerve pain from the neck down. “That was the darkest time for me,” she said. “They tried all kinds of medications. I was depressed, I wasn’t sleeping at night, I stopped exercising, I stopped having any kind of positivity. It was a really, really dark time.” Becky was subsequently diagnosed with a syrinx — a fluid-filled cyst in her spinal cord. In her case, it is essentially inoperable. Becky reluctantly agreed to go to a functional restoration program in California, although she wondered how that could alleviate her pain. “I discovered that pain is an experience, not a sensation. And I get to decide what it means,” she said. “And when the fear goes away, and the negativity goes away, the pain comes down. And when my activity goes up, eventually I’m less sore and I’m better. And life could still be good.” Becky has an active life these days. She and her husband, Barry, have started a company to help people with long-term chronic pain. It is something in which she is intimately familiar. “I still have the syrinx, I still have burning nerve pain from my neck down, it just doesn’t have me,” she said. “I don’t take any meds. I live a very good, a very functional life.” Dwight: Despite losing both legs from two separate work-related incidents, Dwight became a force within the workers’ comp community. He was tired of people looking at his prosthetic legs and decided to give them something special to see. He started creating outlandishly colored hand-painted sneakers – first for himself, then for others. These gained notice in the workers’ compensation community when they were worn by the late David DePaolo, founder of WorkCompCentral, at numerous industry events. Tragically, Dwight passed away in March of this year from heart-related issues, but his positivity and energy are not forgotten. Dwight’s story began seven years ago, when he picked up a staph infection while working in Hong Kong. By the time he returned to Los Angeles, his left leg was dead and had to be amputated. He returned to work with the one prosthetic leg, inspecting some of the world’s tallest buildings. “I loved what I was doing,” he related. Three and a half years later, Dwight suffered another industrial accident, leading to the loss of his other leg. Before his passing, Dwight said his recovery was going, “Pretty good. I started playing golf again.” Having grown up in the Del Mar, California area beach community, he was an avid surfer. “I surfed every day,” he said. “So I got water [prosthetic] legs to surf.” He also had special legs made for running and was doing stained glass artwork for restaurants in the San Diego area. In addition to his hobbies, the father of seven opened Soule Innovations, a business that creates brightly-colored sneakers for people. He and his wife Debbie also donated the shoes to other amputees and war veterans. The Lessons The stories are different. But the messages from these and other injured workers are the same: positivity, peer support, and advocacy are imperative to recovery. Attitude: “After an injury the person dealing with us has to be positive,” Dwight explained. “We’re trying our best, but on the other hand, on the other end of the line, tell me everything’s going to work; tell me you care. It’s so important.” The attitudes of those involved with an injured worker are vital in determining the outcome. Karen tells the story of seeing a medical provider who walked into the exam room, looked at his information and told Kenny “you’re as good as you’re going to get.” On the way home from the appointment, Kenny was crying in the car and asking, “This is it?” Those and other negative conversations kept Kenny in a disability mindset until his third caseworker arrived on the scene. See also: A Better Reality for Injured Workers   Becky related her experience when she was first in the hospital. “As soon as they took the ventilator tube out of me I asked, ‘What’s the prognosis?’ [The doctor] just looked at me and said, ‘You’ll never be normal.’ It was true. I cried after that. Couldn’t move, couldn’t scratch my nose but I didn’t like that answer,” she said. “I asked another doctor the next day. He smiled and said ‘you’re going to walk again.’” The positive reframing of the message made a difference in Becky’s attitude and ultimately, her outcome. Much of Becky’s and Barry’s work with chronic pain patients involves reframing the message. When someone asked what she focuses on while feeling burning nerve pain from the neck down, she responded “You focus on the neck up. There’s always something we can focus on that is ok,” she said. “If everybody’s on the same page – the provider, case manager, adjuster – even if it’s just one person that will speak some kind of positive into your experience, it makes a huge difference.” Nevertheless, the message must be truthful in addition to being positive. “One thing that used to really get to me is if someone said, ‘we’re going to bring you back to normal,’” Dwight said. “If I’m going to be normal, we’re going to cut everybody’s legs off and then we’ll be normal. Normal for me would be impossible. It has to be positive. We all have to work on ourselves.” Advocacy: Peer advocacy is also crucial to a positive outcome. Often the injured worker’s only support is his family, and that can be volatile. “It’s a powerful journey to be a spouse of an injured worker,” explained Barry. Fear creeps in, he said, which can impede recovery. “One of the things that I experienced is that it is really easy to find yourself defaulting to that workers’ comp check that’s coming in the mail. It’s almost a feeling like, ‘you’ve got to stay injured, you’ve got to stay dependent.” For injured workers and their families, showing support and caring can make the difference between an injured worker staying dependent on the system or recovering. “It begins with positivity, looking at what you have rather than what you’ve lost. You have to celebrate what you have, not dwell on what you lost,” Barry said. “I coach family members of people going through pain and that’s what I tell them all the time. We spend a lot of time talking about grieving that loss. At the same time, grief is also acceptance of what you’ve lost and then celebrating what you have. We spend a lot of time on that.” Becky empathizes with her clients who are going through the pain. “We specialize in working with the difficult cases,” she said. “We want to give them hope and support and all they need to be self-managers instead of passive patients.” Hearing and believing what the injured worker says is a crucial part of advocacy. In Becky’s case, her diagnosis of ‘incomplete quadriplegia’ may have expedited the care she received. But a case like Kenny’s, with a questionable diagnosis, is more vague and complex. There can be a stigma attached that can leave the injured worker feeling alone and forgotten. “If somebody’s on drugs for two or three years and nothing is happening, you’ve got to stop it then,” he said. “Thirteen or 14 years is terrible. You go to these doctors and say ‘yes, my back’s killing me.’ They write you a prescription and that’s it. It’s hard.” Kenny spoke of the family-like support he received at the rehab facility as being key in his recovery. For the 12 years before that program, he had only his wife. “If somebody is alone and disabled, I don’t even know how they cope,” Karen said. “Because he was in such a stuporish state that, if I wasn’t there or later on, when [the case worker] came into our lives, if she wasn’t there, he’d probably be dead right now.” Dwight likewise found good support from his provider. “My doctor gave me two options: ‘put you in a wheelchair and give you enough drugs, or get up off your ass and do something.’” He chose the latter.

Kimberly George

Profile picture for user KimberlyGeorge

Kimberly George

Kimberly George is a senior vice president, senior healthcare adviser at Sedgwick. She will explore and work to improve Sedgwick’s understanding of how healthcare reform affects its business models and product and service offerings.

The State of Risk Oversight in 2017

Less than half of the respondents surveyed describe risk management processes as "mature" or "robust."

The percentage of organizations with relatively mature risk management processes increased over recent years, although the majority of organizations still do not believe their processes reflect a “complete” or robust ERM process. While progress is being made, there is still room for significant improvement in risk oversight for many organizations, according to a recently released study, 2017 The State of Risk Oversight: An Overview of Enterprise Risk Management Practices NC State’s ERM Initiative, in partnership with the American Institute of CPAs, has just released its 2017 The State of Risk Oversight: An Overview of Enterprise Risk Management Practices. Based on survey responses from 432 business executives spanning a number of industries, types and sizes of organizations, the report provides detailed insights about the state of maturity of their organization’s current enterprise risk management (ERM) practices. This is the eighth year that we have conducted similar research in partnership with the AICPA. See also: The Current State of Risk Management   This report provides extensive data about the state of maturity about various aspects of an organization’s ERM process. Not only do we provide data about the full sample, but we also separately report findings for the largest sized organizations (revenues > $1B), publicly traded companies, financial services organizations, and not-for-profit organizations. Here is a brief overview of some of the key findings. Risk Environment is Complex Most respondents believe the risks they face are complex and numerous
  • About 70% of large organizations, public companies, and financial services entities perceive the volume and complexities of risks have increased "mostly" or "extensively" in the past 5 years
  • That trend has been consistent over the past several years, suggesting the overall risk environment continues to be challenging to manage for all types of organizations
  • Most organizations have dealt with significant operational surprises in past 5 years
Risk Management Processes Less Advanced Less than half of the respondents describe risk management processes as "mature" or "robust"
  • 25% of full sample describes their risk management processes as "mature" or "robust", with large organizations, public companies, and financial services entities having more mature processes (but less than 50% of those are "mature" or "robust")
  • The majority of organizations do not believe their processes reflect "complete" or formal enterprise-wide risk management
Opportunities Exist to Integrate Risk Management and Strategic Planning Most organizations are struggling to integrate risk management with strategic planning
  • Only about one-quarter of the respondents describe their ERM processes as an important strategic tool with no real differences in that assessment across types of organizations
  • 34% of the full sample do no formal assessments of emerging strategic, market, or industry risks
  • If an entity considers strategic risks, that mostly involves qualitative assessments of risk exposures
Organizations are Strengthening Risk Leadership More organizations are establishing management-level risk committees
  • 58% of the full sample has a management-level risk committee, up from 45% last year
  • Management-level risk committees are more likely for larger organizations, public companies and financial services organizations (around 80%) - an increase of about 10 percentage points over last year
  • We also saw an increase in the designation of individuals who serve as chief risk officer or equivalent
Calls for Increased Senior Management Involvement Strong majority of boards are asking for increased senior executive involvement in risk oversight ("somewhat", "mostly", or "extensively")
  • 67% of the boards for the full sample are calling for more involvement, with even higher percentages of boards asking for greater management involvement in risk oversight at large organizations, public companies, and financial services entities
  • This trend is consistent with prior years, suggesting boards continue to be interested in strengthening risk oversight
See also: 4 Steps to Integrate Risk Management   Future of ERM As organizations peer into the future, the challenge question for the board of directors, senior executives, and other key stakeholders is “how confident are we in our organization’s ability to effectively identify and navigate the unfolding uncertainties surrounding our current business model and new strategic initiatives?” Based on key findings in this report, what opportunities exist to enhance the organization’s risk management thinking so that both sides of the risk and return relationship are sufficiently and effectively managed? This year’s report highlights many other specific findings about various aspects of an effective enterprise-wide risk management process. In addition to providing findings for the overall sample, the report separately highlights key findings for public companies, the largest organizations, financial services organizations, and not-for-profit entities. You can download the full 8th edition here.

Mark Beasley

Profile picture for user MarkBeasley

Mark Beasley

Mark S. Beasley, CPA, Ph.D., is the Deloitte professor of enterprise risk management and director of the ERM initiative at NC State University. He specializes in the study of enterprise risk management, corporate governance, financial statement fraud and the financial reporting process. He completed over seven years of service as a board member of the Committee of Sponsoring Organizations of the Treadway Commission (COSO) and has served on other national-level task forces related to risk management issues.

Getting to ‘Resilient’ After Harvey and Irma

There are many relatively minor and cost-effective measures that homeowners in the vulnerable coastal areas can take. Why don't they?

Before any “lessons learned” speechifying, we should first pray for those who lost their lives and family members and homes and livelihoods to the nearly “biblical storms” Harvey and Irma. For those still in shelters and still being rescued, we wish them Godspeed. There are so many lessons from these two storms. Where to begin? Let’s begin with a word: “resilient.” The Merriam-Webster dictionary defines “resilient” as: (a) “capable of withstanding shock without permanent deformation or rupture; and, (b) tending to recover from or adjust easily to misfortune or change.” Clearly, as we look at our flooded and battered communities in Texas, Florida and South Carolina, we see that they are not meeting this definition. See also: Harvey: First Big Test for Insurtech   As individuals and societies, we strive, as we should, to be as resilient as we can be. Why? Because if we are not resilient in ourselves, our properties, our neighborhoods and our societies, we simply put our misfortunes on our neighbors, involuntarily, whether they can handle those burdens or not. Recall the story of the “Three Little Pigs” that we all learned as children. The two silly pig brothers who danced and sang and built their houses of straw and sticks ended up depending on the brother who built his house of bricks to save them from the huffing and puffing of the big, bad wolf. The wind-blowing wolf is certainly an apt analog for Hurricanes Harvey and Irma. What makes us and our societies resilient? There are several important aspects of lack of resiliency that Harvey and Irma have starkly revealed. The majority of homeowners with flood damages in Texas and Florida in the recent storms did not have flood insurance. Most all of these people owned cars, and, because of state laws, they all had automobile casualty insurance. Driving without insurance would be unlawful, yet their homes, where the majority of their net worth was invested, were without coverage. Whatever their homes were actually made of, they were financial “sticks and straw,” without flood insurance. Flood insurance is a critical component of resilience for the individual and for society at large, which will now direct billions of its tax dollars for FEMA relief. In the case of most homeowners who were wiped out by these storms, they could have afforded flood insurance but opted not to have it. Insurance is one component of resilience, but it is not the only factor. Let’s talk about personal responsibility. There are many relatively minor and cost-effective measures that homeowners in floody areas can take, short of raising their homes on stilts. Flood prevention investments can include: backflow preventers, storm shutters, removable flood barriers, raising electrical outlets, raising HVAC equipment off the ground, minor regrading and installing salt-tolerant vegetation. The list could go on and on. Why don’t most homeowners in the vulnerable coastal areas make these investments? One reason is that they lack comprehensive, flood-risk-vulnerability information about their own properties. The FEMA flood maps’ “binary” approach – in or out of the 100-year flood zone – has not been effective in communicating all of the various flood risks to which homeowners are subject. For example, FEMA flood maps do not include tidal flooding risks, NOAA maximum-storm-surge risks (which may be much greater in flood height) and heavy rainfall/high groundwater risks. This is why my company, Coastal Risk Consulting, developed its online, comprehensive flood risk assessments at www.floodscores.com – to help coastal residents get climate-ready and storm-safe. Once homeowners and their neighbors truly understand their flood risks from the “bottom up,” then, and only then, will they be able to effectively mitigate their personal risks and advocate with their town, county, state and federal representatives regarding the “top down” resiliency efforts -- and appropriation of funds needed to make public infrastructure climate-ready and storm-safe. Both individual and government investments in resilience are required to make us and our communities “resilient,” especially in light of increasingly intense storms. The next resiliency challenge for the owners of properties damaged by Hurricanes Harvey and Irma is whether and how to rebuild to become more flood-resistant in the face of severe weather to come. Many motivational speakers have orated: “In the Chinese language, the word 'crisis' is composed of two characters, one representing danger and the other opportunity.” Whether this is linguistically correct or not, it makes a good point. The multiple billions of dollars of property damages wrought by Hurricanes Harvey and Irma provides society with, perhaps, a generational opportunity: How should the hundreds of damaged communities rebuild themselves? Will they rebuild in the same locations and at the same elevations and with the same “lack of flood preventions”? In “Three Little Pigs” parlance, will they rebuild houses of sticks and straw or will they build “brick” houses that can withstand the floods and winds brought on by the next set of storms? Will local, state and federal governments say “enough is enough?” Will our elected representatives work with our visionary architects and engineers to rapidly change building codes and land use and zoning laws, to begin to make our communities more resilient? See also: Time to Mandate Flood Insurance?   As much as I hope for such a result, I would not, however, bet the house and the dog that our politicians will say what everyone knows they should say, namely, “Enough is enough.”

Albert Slap

Profile picture for user AlbertSlap

Albert Slap

Albert J. Slap is president and co-founder of Coastal Risk Consulting, the first company to provide millions of coastal homeowners in the U.S., as well as businesses and local governments, with online, state-of-the-art, climate risk assessments at an affordable price.

How Underwriting Is Being Transformed

An EY survey finds that initial use cases are narrowly defined but that technologies are advancing key capabilities.

The recently completed EY Digital Underwriting Survey reveals the important and rapid evolution that is proceeding within commercial and specialty insurance. Further, it clarifies the digital technologies and capabilities that are the impetus behind some of the biggest changes to underwriting, the essential function within insurance. The “big idea” behind the results confirms that more insurers recognize that the future is now when it comes to digital. Insurers are planning to accelerate and expand their investments and activities to embrace digital insurance in its many forms. Both in response to the survey questions and in parallel interviews, the underwriting community expressed a belief that individual technologies are making a difference in advancing key capabilities, even if the initial use cases are narrowly defined. See also: Go Digital… but Don’t Change Who You Are   Looking at 12 specific technologies and capabilities, the survey findings reveal that most insurers are investing now and plan to continue to increase investing. Further, they expect to broaden how they use these technologies. The bottom line is that survey respondents see clear and ample opportunities to expand adoption and increase the value to their business. Key themes emerging from the survey
  1. Predictive analytics, big data, underwriting trading platforms and geographic information systems (GIS) are the most mature technologies currently being adopted. More than half of respondents indicate these technologies are in the rollout or refinement stage. However, these technologies have been narrowly focused on just a few specific areas (such as pricing models and demographic and location data).
  2. Blockchain, robotic process automation (RPA) and sensor-based technologies are all high priorities for the future, with organizations planning to commit significant resources. Currently, most insurers engaged with these technologies report activity in the context of research programs, proof of concept or pilots.
  3. There is a strong need for longer and closer monitoring time of early-stage investments and the potential need for more rigor in business case development. Insurers currently measuring investment performance report strong, even compelling, returns, with most meeting or exceeding expectations.
  4. Insurers and brokers agree that underwriting and pricing capabilities are the most important and potentially valuable in terms of future technology investments. These functions and processes have been augmented by the more mature technologies (predictive analytics, big data, automated portfolio management, underwriting trading platforms and GIS), as well as machine learning and sensor-based technologies.
  5. Actuarial has benefited the most from predictive analytics and machine learning, while policy processing has been the focus of RPA initiatives. Product management capabilities have benefited from big data and automated portfolio management.
See also: The Dawn of Digital Reinsurance   The value proposition for digital enablement is strong across and throughout the underwriting function. Digital is as much about culture as it is about tool sets, and underwriting organizations may have a way to go on the cultural front. For example, one reason for the limited applications and narrow use cases is that digital may lack a single unifying vision or leadership sponsor within underwriting. For the business value to be realized in a full and sustainable fashion, with broad adoption, underwriting needs to work more closely with IT and other partners to define and prioritize the use cases for these digital technologies. To see the full report follow this link to EY.com.

Gail McGiffin

Profile picture for user GailMcgiffin

Gail McGiffin

Gail McGiffin is a principal in EY’s insurance practice and leads the underwriting, product, policy and billing offerings. Prior to joining EY, McGiffin was the chief information officer at ProSight Specialty Insurance.

Big Data? How About Quality Data?

Quality data is driving actionable insights for health insurance innovators to improve choice, transparency and user experience.

|
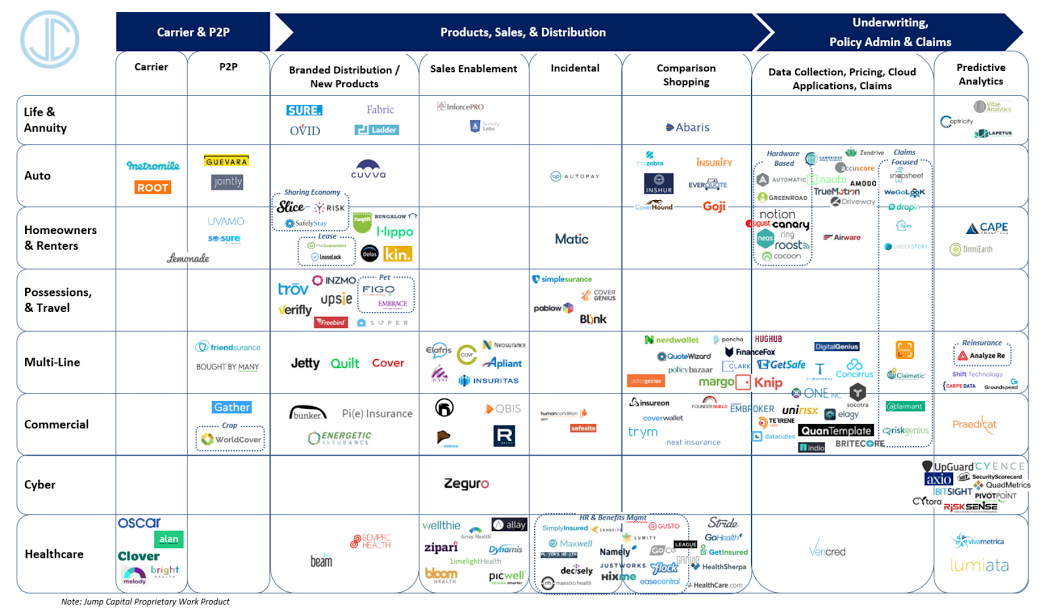
While talking about data has become trendy -- with terms like big data, small data, dirty data all good candidates for buzzword bingo -- the reality is that, big or small, even if it is clean, data is useless unless it drives actionable insights. Data is the foundational layer that underpins almost every industry, and it is a survival requirement for business today. Industries like retail, travel and finance have all tapped into the power of data to drive consumerization. And, while the health insurance sector may have fallen behind these industries, it is catching up, as today’s health insurance consumers are demanding actionable information in the form of choice, transparency and simple user experiences. The good news is that innovators in the space are responding to these consumer demands by creating ground-breaking tools -- tools that leverage modern technology, powerful software design and quality data. Today’s health insurance innovators are making waves in the insurtech industry by building products and features that truly solve consumer pain points. So, who are these innovators? What are they creating? And why is the underlying data so crucial? Who are the innovators? According to CB Insights, $1.7 billion was invested in insurtech in 2016. Essentially, the insurtech category encompasses all new technologies, companies, apps and business models that are pushing to revolutionize the insurance industry itself. And, thanks to advances in technology and funding, this category is seeing rapid growth. See also: Why to Refocus on Data and Analytics  Jump Capital recently pulled together its view of the movers and shakers that are disrupting the insurance industry. With so many new vendors in the market, it is safe to say that there is definitely a lot of moving and shaking going on in insurtech. These companies are finding different ways to meet consumer demands and remove the complexity associated with the insurance industry. The companies included in the healthcare segment of this infographic are, for the most part, delivering new ways to help consumers find, buy and receive health insurance. Collectively, health insurtech platforms answer a consumer cry for help. But none of these platforms are functional, let alone useful, without a foundational layer of quality data on which to build. What are the innovators creating? Health insurtech innovators are working to answer a variety of consumer demands. They’re creating tools that simplify the health insurance shopping experience. Tools that help doctors find prescription drugs that are covered by a patient’s insurance plan. Tools that help consumers find doctors that are in-network. The problems that these platforms solve are many. Here are just a few examples of innovative tools and features being created to deliver value to health insurance consumers: 1. Decision Support Tools for the Individual Market A variety of web-based entities (WBEs) have popped up to help individual consumers find and purchase a health insurance plan that is right for them. PolicyGenius is a good example of an innovative platform doing just that. The company prides itself on delivering simple benefits that are personally designed for the individual. A consumer enters a few bits of information, and PolicyGenius recommends health insurance plans for that individual -- all delivered through a seamless digital experience. 2. Analysis Tools for the Small Group Market Certain broker-facing platforms are starting to build analytical tools that help strengthen group health plan recommendations. These tools allow platforms to compare and contrast different health plans, including each plan’s network, aiding in disruption analysis and delivering value to their employer customers. 3. In-Network Provider Search and Notification Features Many health insurtech platforms offer customers provider-network search and notification features. Stroll Health, for example, delivers personal recommendations for imaging centers based on a patient’s insurance plan. And some HR and benefits administration platforms now have the ability to notify employees if an employee’s preferred doctor drops out of network. Thoughtful features like these save consumers time and money. See also: Next Step: Merging Big Data and AI   Why is the data so crucial? While data may not be the sexiest element of a tech platform, the data layer enables all features. For example, for those broker-facing analysis tools to be useful, the broker platform must have access to accurate and timely data on the benefits and rates of every health plan they’ll compare. For an HR and benefits administration platform to alert an employee when a doctor drops out of network, the platform must first know when that doctor drops out of network. This means the platform must have access to an accurate and extremely granular database of providers in the specific network being tracked. Quality data is what informs today’s innovators, pushing them to take action and build exciting applications that solve real problems. Health is a complex space, but there are many brilliant minds working to improve the health insurance industry. Putting the right data into the hands of these innovators allows them to do what they do best -- solve problems with creative technology solutions. Continuing to do this will allow today’s innovators to respond to consumer pain points and transform the health insurance industry.

Paige Swanepoel

Profile picture for user PaigeSwanepoel

Paige Swanepoel

Paige Swanepoel is the director of marketing at Vericred, a leading healthcare data services company based in New York City. Her focus on enabling technologies that propel consumerism has been a driving force in her career and the success of Vericred.

Life/Annuity M&A Is Heating Up

Buyers are motivated by the current low-interest-rate environment and the opportunity to expand their assets and book of business.

As life insurance and annuity carriers pursue greater market share and growth, a potential solution sits before them: M&A activity. This transactional path, leading to deep consolidation in the life insurance and annuity (L&A) sector in the U.S., is stoking much debate and discussion in company boardrooms. The hunt for elusive growth and profitability for carriers in the U.S. has many players, creating a crowded marketplace for possible consolidation. The multi-headed acquirers come in three dominant forms: large insurance companies, private equity (PE) investors and foreign acquirers, driven largely by the Chinese and Japanese. Insurance carriers intimately know about their competition and what companies in the sector would mesh well within their operations. Executives have the greatest amount of specific industry expertise and therefore can understand the pros and cons in a specific combination. See also: How Life Insurance Agents Can Be Ready Private equity investors have been turning to the life insurance and annuity field for several years to provide consistent returns, as these companies have predictable cash flows. Through these investments, investors can strengthen their returns for assets under management with steady growth. One caveat to this investment approach is the concern of the increasing regulatory state and federal pressures, as navigating through 50 individual state regulatory guidelines can be burdensome and difficult if a company moves out of a state and into a new one. Foreign countries like China and Japan continue exploring opportunities to increase their presence in the U.S., the world’s largest insurance market. Reasons abound: Japanese insurance companies have found U.S. acquisition targets appealing to offset the aging of Japan’s population and to provide a more attractive interest rate environment. Chinese companies have been snapping up foreign companies, including in the U.S., searching for yield on their capital and economic growth. Several reasons exist for this trend of M&A activity.
  1. Buyers are motivated by the current low-interest-rate environment and the opportunity to expand their assets and book of business. This has always been an essential piece of the M&A discussion as market conditions must be favorable to make any transaction worth its while.
  2. Sellers are suffering from the low return on their capital. By exiting less profitable lines of business, they can reallocate their capital for use in other capacities. As contemplation of one’s business clarifies, many carriers may conclude that selling, rather than buying, assets is the chosen path. Selling could stabilize or enhance a company’s bottom line as the capital obtained in a sale can be reinvested in its existing operations or be put to use for another potential acquisition.
  3. Increasing regulations are restricting the ability of companies to productively run their businesses; thus, they are looking for exits. Companies are often stymied by the sheer weight of complying with and managing regulations. Exiting businesses can become appealing.
Regardless of which direction is undertaken, one aspect paramount to success is the importance of ensuring that business continues to operate smoothly. In today’s environment, the role of technology, specifically at a time when companies are implementing and managing digital transformations, can be a beacon of light. And as acquirers delve deeper into possible transactions, increasingly they are employing an outsourcing model to extract more value. See also: This Is Not Your Father’s Life Insurance   Safeguarding a company’s operations and maintaining its continuity through powerful technology and servicing solutions, or what we call “future proofing,” has additional benefits besides the desired functionality. Companies must first build their vision and plans and then bolster them with end-to-end operational services. This step will then enable rapid expansion into new market segments, faster product launches and seamless servicing of open and closed blocks of business. By future-proofing through technology, carriers can drive greater efficiencies, lower costs and produce higher levels of customer satisfaction.

Eric Rea

Profile picture for user EricRea

Eric Rea

Eric Rea is president of SE2, a leading technology and third party administration company focused on the North American life and annuity insurance industry.

Disasters show insurers can change the world

There are opportunities for insurers to take the lead in the "change the world" movement. 

sixthings

The natural disasters of the last week-plus bring to mind the old chestnut: "Other than that, how'd you like the play, Mrs. Lincoln?"

The other-than-the-"assassination" reports have been good, thus far, in the wake of Hurricane Harvey and Hurricane Irma. Irma took an ever-so-slightly unexpected path, so, while electricity is out for millions and will likely be a problem for weeks, the storm visited much less destruction on Florida than expected. Local, state and federal authorities have seemed to react well. Insurance companies are on the scene, trying to pay claims and get people back to their regular lives as soon as possible. Citizens have risen up to to help themselves and others—the drive that I mentioned last week that was led by Houston Texans defensive lineman J.J. Watt has now passed $31 million in donations, not counting the enormous gifts of supplies and transportation he's received.

But we're still left with the "assassination" parts of the hurricanes, and those are dreadful. For instance, our chief innovation officer, Guy Fraker, knows that the eye of Irma passed directly over his key in Florida and that the bridges on both sides of the key have been wiped out. It's not clear when he'll even be able to get back to check on his home. People in Florida and the affected parts of Texas and Louisiana will need months or years to recover. 

As it happens, in the midst of the storms, Fortune put out a list of 50 "Change the World" companies that are turning "doing good into good business." The 50 were chosen based on their social impact, financial results and degree of innovation. I looked eagerly to see how many insurance companies made the list and found...two. Insurance Australia Group was ranked #29, and Allstate was #39. Having two isn't bad representation, given all the other industries competing for just 50 spots, but, with everything the industry is doing to pull Florida, Texas and Louisiana back together, I had certainly hoped for more.

The Fortune list comes at a time when a backlash has developed against the idea that the sole purpose of a corporation is to serve the shareholders by increasing profits and stock price as much as possible. The idea, formulated in 1970 by Milton Friedman, a Nobel-prize-winning economist who was the leader of what's known as the Chicago school, stoked the fever that led to accounting fraud and scandals such as WorldCom and Enron. More generally, a sense is developing that companies have responsibility to all sorts of stakeholders, including employees, customers, communities, the environment and, in the case of our favorite industry, insureds. 

A company to watch is Unilever. It has explicitly taken a "change the world" approach, to the point that it recently faced a takeover attempt by Kraft Heinz, which promised to stoke shareholder returns. Unilever fended off the attempt, the board committed to its more-balanced approach to long-term gains for all stakeholders, and Unilever is certainly reaping PR rewards.

Given the business we're in, I have to believe that there are opportunities for insurers to take the lead in this "change the world" movement. Insurers seem to be off to a good start in the aftermath of Harvey and Irma. Let's hope that continues. Publications like Fortune will notice.

Cheers,

Paul Carroll,
Editor-in-Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Catastrophes and 'Do Little' Syndrome

A $120,000 home was rebuilt 16 times in 18 years at a cost of almost a million dollars. Why do we let this craziness continue?

Cliff Treese of Association Data brought some statistics to my attention involving earthquake (EQ) insurance in California. Going back as far as 2001, the percentage of properties without EQ insurance were: Homeowners       84-88% Dwelling               95-97% Commercial         89-93% So, only about 15% of homeowners, 10% of business owners and 5% of dwelling owners buy EQ insurance. Why? Lots of studies and surveys have been done. It’s too expensive. It doesn't pay much, especially for partial losses, because of percentage deductibles. “It’ll never happen to me.” The government will take care of me. “I thought my regular insurance covered this.” And on and on. One of my favorite quotations is from Gen. Jimmy Doolittle, who said, “The problem with Americans is that we’re fixers rather than preventers.” This is so true in so many ways. Following Hurricane Harvey, it was widely reported that only about 15% of flooded properties had flood insurance. We’ll see what happens, if anything. See also: Harvey: First Big Test for Insurtech  While we can’t prevent earthquakes and hurricanes, we can prevent, to a large extent, their financial impact by buying catastrophic insurance. Private insurers sell EQ coverage and, underwritten by the NFIP, flood insurance. Yes, in many cases, it’s expensive, but what are the alternatives when the exposure is so real? As I posted last week, is it time that such coverage was mandated and included, with a federal terrorism-like backstop, in standard policies covering property damage? Such a solution would be complex and difficult, but what are the alternatives? And, while Gen. Doolittle’s quotation is so often true, it may be even more true that, increasingly, the problem with Americans is that we’re not preventers OR fixers. In the meme I used for last week’s post, I used another quotation from the German philosopher Hegel, who said, “History teaches us that man learns nothing from history.” This may be illustrated in a recent USA Today story about repetitive flood properties with this excerpt: "Instead, NFIP embraced a “flood-rebuild-repeat” model that has spawned an almost $25 billion debt. The National Wildlife Foundation estimated in 1998 that 2% of properties covered by federal flood insurance had multiple damage claims accounting for 40% of total flood insurance outlays, and that more than 5,000 homes had repeat claims exceeding their property value. A recent Pew Charitable Trust study revealed that 1% of the 5 million properties insured have produced almost a third of the damage claims and half the debt." NFIP paid to rebuild one Houston home 16 times in 18 years, spending almost a million dollars to perpetually restore a house worth less than $120,000. Harris County, Texas (which includes Houston), has almost 10,000 properties that have filed repetitive flood insurance damage claims. The Washington Post recently reported that a house “outside Baton Rouge, valued at $55,921, has flooded 40 times over the years, amassing $428,379 in claims. A $90,000 property near the Mississippi River north of St. Louis has flooded 34 times, racking up claims of more than $608,000.” See also: Time to Mandate Flood Insurance?   Wow. Fully 2% of properties insured for flood account for 40% of all flood insurance payments. A $120,000 home was rebuilt 16 times in 18 years at a cost of almost a million dollars. Another home has allegedly flooded 40 times and still another property 34 times, racking up combined payments in excess of a million dollars. WHY? Apparently because we’re not fixers OR preventers AND we learn nothing from history.

Bill Wilson

Profile picture for user BillWilson

Bill Wilson

William C. Wilson, Jr., CPCU, ARM, AIM, AAM is the founder of Insurance Commentary.com. He retired in December 2016 from the Independent Insurance Agents & Brokers of America, where he served as associate vice president of education and research.

Wellness Isn't the Only Scam in Healthcare

New book explains how to vastly cut healthcare spending, delivering big benefits both to employers and employees.

Healthcare meets Network. That is the one-sentence summary of Dave Chase’s new book, A CEO’s Guide to Restoring the American Dream: How to Deliver World-Class Healthcare to Your Employees at Half the Cost. Dissecting the title, the “restoring the American Dream” reference is as follows: While wages have barely budged in the last 20 years, employee compensation has risen quite a bit — with most of the increase being the health benefit. Dave’s observation is that if the health benefit were managed much more tightly, wages could climb noticeably for the workforce without increasing the total employee compensation budget. As for “half the cost,” that number may be overstated…but not by much. For instance, I just saw a wellness vendor send 2/3 of a company’s employees to the doctor because they have “conditions” they didn’t know about, that this vendor “discovered” by — you guessed it — screening the stuffing out of them by flouting clinical guidelines. This employer could save about 3% simply by firing the vendor and not consigning all those employees to the treatment trap. (Of course, there has been no measurable improvement in outcomes from all these doctor visits.) This employer and others could save another 0.5% simply by not insisting that their employees and spouses get annual checkups (and “well-woman” visits) because as readers of this site know, they have no value. The good news is that checkups are not likely to harm employees, which is more than can be said for many wellness programs. See also: Wellness Vendors Keep Dreaming   So we are already saving 3.5%, and we haven’t even done anything hard yet, where “hard” is defined as “something that does not delight employees, like getting rid of ‘pry, poke and prod’ programs.” In other words, “hard” isn’t really hard. Slightly harder opportunities In addition to an expose on wellness, Dave Chase exposes some scams that make wellness look like child’s play. (Wellness is child’s play, in the sense that any fifth-grader knows more arithmetic than a wellness vendor. And a 14-year-old knows more about BMI.) In no particular order, we’ll start with PBMs. Their stock prices have exploded — literally, 300-fold — in the last 30 years.  You think they achieved that growth honestly? They make wellness vendors look like Boy Scouts. They obfuscate everything, with “rebates” and “formularies” and under-the-table payments from drug companies, and all sorts of other things that we probably don’t even know about. Here is a New York Times article that casts just a little light on the subject…but more than enough light to indict the entire industry. It isn’t easy to ditch a PBM, but increasing numbers of alternatives are popping up. A good rule of thumb is, the thicker the contract with your PBM, the more you are getting ripped off.  I invite folks who offer one of these new alternatives to add a comment at the bottom of this posting or on LinkedIn following this posting. Then there are the carriers, who typically make more money, the more money gets spent. The number of scams is mind-boggling. For example, consider Dave’s explanation of what happens when a claim is overbilled: Another fee opportunity is so-called “pay and chase” programs, in which the insurance carrier doing your claims administration gets paid 30-40 percent for recovering fraudulent or duplicative claims. Thus, there is a perverse incentive to tacitly allow fraudulent and duplicative claims to be paid, get paid as the plan administrator, then get paid a second time for recovering the originally paid claim. Good luck trying to ferret your own claims data out of carriers so that you can do your own analysis on them and change policy accordingly. I do quite a bit of work for top-flight carriers, measuring their wellness-sensitive medical events. They always seem to have the data at their fingertips. We can complete the analysis for the year within weeks after claims run-out ends, meaning sometime in April. Meanwhile, I’ve got a Fortune 50 client whose carrier, Optum, still hasn’t managed to provide them (at an extra fee!) with their own event rates for 2016, a delay which more than coincidentally will make it impossible to implement any cutbacks in Optum’s services for 2018 if the event rates show that — hang onto your hats — Optum didn’t achieve anything. Don’t get Dave started on providers, who find highly creative ways to snooker employers and employees.  Like staffing in-network facilities with out-of-network doctors, who then bill patients ridiculously high charges. You need to re-contract with your carrier and put that one on them.  Or, if you’re large enough, recontract with the hospital. And speaking of hospitals, why have Leapfrog D- and F-rated hospitals in your network at all? If a geographic necessity, then at a minimum educate your employees that it might be worth the extra drive to avoid some major complications. Providers also bill companies what they think they can get away with, rather than what a buyer would expect to pay given what others in the area are charging. Because the company is generally not the decision-maker (the employee or doctor generally decides where to go, not based on price), providers often get away with it. An entire chapter is devoted to provider pricing scams and the importance of transparency. See also: A Wellness Program Everyone Can Love   Or, my own personal favorite provider scam, disguising emergency rooms as urgent care centers. (A rather naively idealistic Colorado legislator tried to make freestanding ERs disclose that they are not urgent care centers, but the provider lobbyists prevailed.) A sidebar: Quizzify trains employees to be on the lookout for these scams, which is helpful for the 0.1% of the 150,000,000 commercially insured employees who actually have access to the quizzes. The other 99.9% are on their own. And yet it all comes back to wellness Employer obsession with wellness has caused them to take their eyes off these many other balls, because wellness was supposed to solve everything (including industrial waste, according to HERO stalwart Bruce Sherman). Truly, wellness has been the Maginot Line of healthcare cost containment strategies. While a vastly disproportionate share of resources has gone into wellness, PBMs, carriers, providers and various middlemen simply circumvented these efforts, to dig right into your pocketbooks. I can only scratch the surface here — just go out and buy the book, and then you’ll understand both why when it comes to scamming employers and employees, wellness vendors have a lot to learn, and also why you should be mad as hell and not take it any more.