Download

Why AI Will Eat Insurance

The crux of the problem: Insurance companies, born in the era of the horse-drawn carriage, were not built to capture big data.

||

When food delivery services talk breathlessly about machine learning, feel free to roll your eyes: it’s baked salmon they’re dropping off, not Bayesian statistics.

Insurance is another kettle of fish altogether.

Sultans of stats

The birth of statistics is usually dated to 1662, when John Graunt calculated the probabilities of Londoners surviving to a given age. Lloyds of London started shortly thereafter, and advances in statistics and insurance have been inseparable ever since.

But in recent years, supremacy in statistics has moved to Silicon Valley – a bad omen for the insurance establishment. True, insurers still have some of the finest human statisticians, but the finest statisticians of all are no longer human. They’re machines.

Insurers, of course, have machines, too, but the machine’s secret power is its ability to extract prophetic insights from inhuman quantities of data. If the data isn’t "big," the machine will function as a calculator, not an oracle.

Which brings us to the crux of the problem: Insurance companies, born in the era of the horse-drawn carriage, were not built to capture big data.

Loss ratios are like testicles

Case in point: An executive at one of the largest insurers told me that “other” is the most common cause for a claim. People (unlike bots) lazily tick that catch-all-box, rendering their data useless.

See also: Strategist’s Guide to Artificial Intelligence  

Tons of useful data are lost, too: Often, they’re not machine-readable; other times, it’s the humans who can’t read them (swallowed by a system whose architect retired in the '90s).

The exec went on to say his loss ratio was 54% (in other words, if you paid $100 in premiums, he’d spend , on average , $54 on your claims). Among insurers, this passes for small talk, so he was a little taken aback when I countered that his customers have ,  on average, one testicle. I explained that knowing your customer "on average" offers little insight. Worse, under the guise of a statistical fact, a generalized average often paints a misleading picture.

A loss ratio  –  the gold-standard insurance metric  – is no substitute for deep, textured and rich data. The very kind insurance companies are ill-equipped to collect.

Digital divination

Some insurance buyers take time to understand their coverage, others don’t. Is that predictive? What do our tech choices say about our risk profile?

There are endless such questions, and in a fully digital lifecycle they all get answered. Unlike traditional insurers, tech companies won’t make do with a global loss ratio. They will monitor the loss ratio per device, browser and advertising campaign. They will compare the loss ratio of people who press hard on the screen, to those who don’t; the loss ratio of those who bought insurance from home, to those who bought it on their commute; those who bought it at 4pm, to those who bought it at 2am. Not only will the machine answer all these questions, it will answer a myriad more we didn’t know to ask.

Tech companies gather thousands of times more data than traditional insurers, producing nuanced profiles of their customers and remarkably predictive insights.

"Calculating the probability of future outcomes is the core of insurance, yet incumbents will find it increasingly difficult to remain competitive."
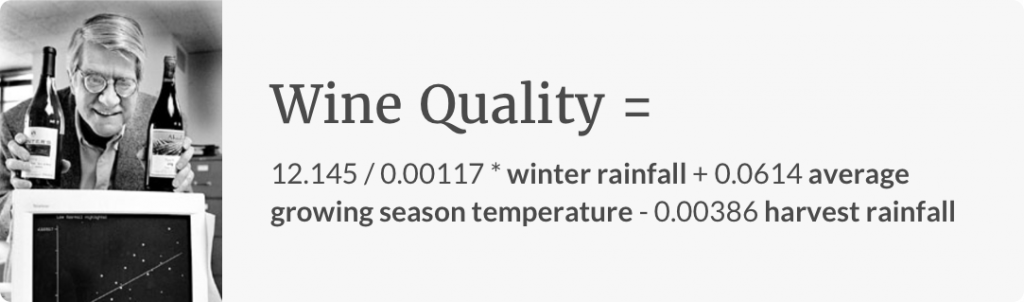
It’s hard to think of a domain that isn’t being upended this way. Want to predict if this year’s cabernet will be a winner? The centuries-old method calls for a connoisseur to swish and spit. Orley Ashenfelter used a multivariate regression to derive a simple equation that outperforms the aficionados:
When the product is wine, the machine can put some noses out of joint. When the product is probability, the machine can transform the industry.
Grab your popcorn, Act 2 is beginning

In recent years the insurance industry has paid close attention to insurance-tech startups. The industry notes how being digital transforms the user experience, appeals to younger consumers and removes costs, while expediting everything. That’s all true, but it is only Act 1.

See also: Lemonade’s New Push: Zero Everything  

While everyone is bedazzled by the tech of Act 1, these delightful apps are generating mountains of data. These will soon reach the billions of entries that machines go to town on, and that’s when Act 2 will begin.

Act 1 showcases the power of technology to transform any business by reducing costs, increasing speed and delighting consumers. But when Act 2 begins, we will see the power of AI to transform insurance in a uniquely powerful way. It will go beyond thrilling customers and driving efficiencies, to being able to quantify risk like never before. That day is nigh.


Daniel Schreiber

Profile picture for user DanielSchreiber

Daniel Schreiber

Daniel Schreiber is CEO and co-founder at Lemonade, a licensed insurance carrier offering homeowners and renters insurance powered by artificial intelligence and behavioral economics. By replacing brokers and bureaucracy with bots and machine learning, Lemonade promises zero paperwork and instant everything.

6 Lessons in Trust From Retailers

The main reason consumers don’t want to buy insurance online directly through a carrier? They don’t trust insurance companies.

When it comes to digital transformation, the insurance industry lags woefully behind other industries, and it is not just a question of technology. Even as the industry advances technologically, developing digital capabilities that rival other industries–from chatbots to IoT–selling insurance direct to consumers (DTC) has proved a difficult code to crack. Even Geico, the darling of online auto insurance sales, still closes the majority of its new policies on the phone, via an agent. The retail ecommerce industry on the other hand has proven to us that there are very few things consumers are not willing to purchase on the internet. From buying groceries to booking airline tickets, consumers are comfortable conducting all kinds of transactions online, from the very simple to the most complex. Every day, millions of people even do their banking online. So what is the deal with insurance? At Cake & Arrow, we have conducted hours upon hours of primary research in the insurance industry, talking to hundreds of consumers, carriers, agents and brokers in an effort to help our insurance clients answer this question and, in turn design better products and experiences. Throughout this process, we have learned a lot about how customers think and feel about insurance, perhaps our most lasting insight being a lesson about trust. The main reason consumers don’t want to buy insurance online directly through a carrier? They don’t trust insurance companies. This is why, even in the golden age of digital commerce, consumers continue to opt to purchase insurance through brokers and agents. On the surface, fixing this problem may seem simple. All carriers need to do is to gain the trust of their customers, right? Easier said than done. While earning trust may seem like a simple enough idea, it is an issue most carriers don’t even know how to begin to tackle. In my experience, when you want to learn to do something well, the best thing to do is to emulate an expert. In the case of consumer trust, it’s the retail e-commerce industry that has, over the past two decades, mastered the art of consumer trust. Each and every day, millions of transactions happen online, and most consumers don’t think twice about ordering their groceries, electronics, clothing, books and everything in between over the internet. This hasn’t always been the case! Gaining the trust of consumers has been a hard-won battle, and those who have done it well (Amazon) are ruling the industry. If imitation is the highest form of flattery, what lessons can the insurance industry learn from the retail industry that can help them foster trust with consumers and drive a truly digital offering? 1. Establish consistent workflows. The retail industry has the benefit of a consistent process across products, stores and platforms. For the most part, everyone basically understands the standard steps in a checkout flow. Select your product, fill in your shipping and billing information and purchase. And while there are of course optimizations that can be made to make an experience better, in general, consumers know exactly what to expect when purchasing a product online. The same cannot be said for insurance. Unlike a book or an item of clothing, insurance is not a static product sitting in a warehouse with a price tag. Insurance products are complex. Coverage and prices are variable based upon any number of risk factors, and complex underwriting rules and changing regulations can make it difficult for consumers to understand what exactly they are buying and how it is priced. This leads to confusion in the process of quoting and buying insurance and to a lack of standardized practices across the board. From a user experience (UX) and design perspective, one of the first steps the industry can take toward gaining consumer trust is to simplify and standardize the quoting process so that consumers know what to expect when buying insurance online and understand each step of the process. And while underwriting rules and regulations will need to be streamlined to establish an effective industry standard, insurance companies can start by being more transparent with users about what to expect in the quoting process, including informing users about how their personal information is being used. This will help customers better understand the quoting process, feel more comfortable dispensing with personal information and give them general confidence in the process by establishing clear expectations. See also: Top 10 Insurtech Trends for 2018   2. Invest in quality visual design. Over the past two decades, we’ve seen retail ecommerce design evolve, following a general trend toward customer-centricity. Flash sites, cluttered home pages and flashy fonts have given way to clean, simple designs that streamline the shopping process, communicate the brand and are organized around customer needs, interests and behaviors. The insurance industry needs to follow a similar path, leveraging user-validated design to create trust with customers. A modern, usable, well-designed website is a signal of legitimacy. It tells customers that a real company is behind a product, and this company cares enough about its customers to invest in the experience. A strong visual design that implements best practices removes that cloud of doubt in the mind of a customer and builds confidence and pride in the end product. In the same way that a strong brand is a promise of quality, a great visual design is an early demonstration that a carrier cares enough about a customer to invest in a quality digital experience that will translate into a quality product. 3. Implement a killer content strategy. Content strategy is just for news sites, magazines and blogs, right? Wrong. Content is an important piece of the sales process. For our retail clients, we have learned that crafting and executing a killer content strategy is critical to helping customers learn about a product, understand occasions for using products and gain insight into the actual value of a product. Effective education about products and services demonstrates a company’s willingness to keep its customers informed. And the more a customer feels he understands what a company does and what its products are about, the more he will trust it. While we often see short marketing messages on insurance carriers' sites, few insurance companies invest in content on their website to help explain to their customers the value of a product or the differences between products, and to educate them on when and where to use the product so they feel empowered when making purchasing decisions. Educational and informative recommendations will help insurance companies establish a rapport with consumers as a trusted adviser. Companies must even be willing to tell customers when a product isn’t right for them and demonstrate that they care about more than a sale, but about helping their customers make informed decisions that benefit them. A killer content strategy will help insurance companies do this effectively. 4. Enable the right level of customization. The best retail experiences allow for just the right amount of customization. When buying clothing online, for instance, we can choose colors and sizes and have a choice of different delivery options. Subscription services like Trunk Club allow shoppers to input information about personal style preferences, including color and pattern preferences, set price points and decide on frequency to receive a custom selection of clothing recommendations when, where and however often they desire. This kind of customization breeds customer loyalty and, like a good content strategy, can help customers being to think of a company as a trusted adviser with their best interests in mind. Insurance companies should explore enabling similar types of customization. While easy packages are just that–easy–they don’t drive stickiness with customers. Giving customers the ability to modify and tweak plans according to their unique needs and circumstances will drive a connection between a customer and a product. In the same way that these types of customizations breed loyalty in retail e-commerce customers, giving customers more control over choosing the kind of coverage they need at a price they can afford is a powerful way of building loyalty and competing with other carriers on something other than price. And while enabling customization is important, it is really critical that companies don’t take things too far, allowing customers too much customization and, in the process, sacrificing the experience. In speaking recently with a carrier, I learned of a story of customization gone wrong. The carrier's data showed that customers who were able to customize a package were more likely to purchase a policy. Emboldened by this piece of data, they created a new quoting page that allowed customers to customize every aspect of their policy. Lacking the qualitative info on how and why people were more likely to convert when customization was enabled and without user testing on the new custom design, they missed some essential information. Allowing their customers to customize everything about their policy made the experience overwhelming, and conversions ended up falling off significantly. I tell this story as a reminder to companies that testing and validating every design decision with users is critical–and one of the reasons the e-commerce industry has been so successful at digital. 5. Play around with promotions. Promotions are one of the most reliable and time-honored means of staying competitive for retailers. Promotions can make or break a business. Free shipping on big orders, Black Friday sales and BOGO (buy-one-get-one) offers are all commonplace in the retail e-commerce industry, and are incredibly effective at creating consumer loyalty and trust. While, in the insurance industry, it is nearly impossible to offer dynamic pricing or let customers actually play with coverages to get a fully custom price due to regulations, discounting isn’t something to be overlooked. Bundling is a real thing, and customers are more likely to purchase a policy if they see a real deal–and understand its benefits. For example, I’ve seen many insurers combine rental insurance with auto insurance at a discounted price. When customers see deals like this, they oftentimes don’t understand the full benefits of the deal. For example, they may not know that rental insurance protects not only their property but also against liability and, considering the coverage, is incredibly affordable. Developing a robust content strategy to better inform customers about deals and the benefits of coverage will not only increase sales and stickiness, but help customers begin to truly appreciate the value their insurance company is bringing to their lives. 6. Leverage user-generated content. When shopping online and in store, we have come to rely on ratings and reviews to help us evaluate products and make purchasing decisions. User-generated content, such as Instagram posts of real customers wearing clothing or jewelry, can help us see how a dress might fit a certain body type or how a piece of jewelry looks in context. This level of transparency sends customers a clear message that as a company you have nothing to hide–further inspiring trust. See also: Sharing Economy: The Concept of Trust   Just like in retail, user-generated content can be integrated into your content strategy and can do the work of educating customers about your products–explaining the difference between certain coverage offers, for example, or why as a carrier you stand out from other companies offering similar products. Real content generated by other customers helps customers understand how a certain policy works--what the service is like, what the claims process is like, what kinds of scenarios are covered. It can be scary to leave your company and offering open to negative user feedback, but, if you are doing your job, it will end up being more useful than it is harmful. Insurance companies still face many hurdles to getting consumers to trust them and to earning the kind of rapport with customers that the retail industry has established over the years. Anything short of a truly standardized process across all carriers and products will continue to cause confusion and suspicion among customers. But there is nothing stopping insurance carriers from taking strategic steps toward customer-centricity, emulating more mature industries like retail e-commerce that have done it well. This article first appeared on the Cake & Arrow website, here.

Christina Goldschmidt

Profile picture for user ChristinaGoldschmidt

Christina Goldschmidt

Christina Goldschmidt is vice president of customer experience and design at Cake & Arrow, leading the team responsible for conducting research to generate user insights, developing the strategy for the experience and content on products for clients and designing the information hierarchy of those products and all interactions.

An Interview With Nick Gerhart (Part 2)

The former Iowa insurance commissioner provides the regulator’s perspective, with a focus on the goals and tactics of the commissioner’s office.

sixthings
I recently sat with Nick Gerhart to discuss the regulatory environment for U.S. insurance carriers. Nick offers a broad perspective on regulation based on his experience: After roles at two different carriers, Nick served as Iowa insurance commissioner and currently is chief administrative officer at Farm Bureau Financial Services. Nick is recognized as a thought leader for innovation and is regularly called on to speak and moderate at insurtech conferences and events. During our discussion, Nick described the foundation for the state-based regulatory environment, the advantages and challenges of decentralized oversight and how the system is adapting in light of innovation. This is the second of a three-part series. The first part focused on the regulatory framework insurers face. In this second part, Nick provides the regulator’s perspective, with a focus on the goals and tactics of the commissioner’s office. Finally, in the third installment, we will discuss the best practices of insurers in compliance reporting. In this conversation, we covered the tactics and process of regulation. In particular, Nick described the interactions – routine and targeted – between career and commissioner. How is a commissioner’s office organized? As I mentioned, the state of Iowa has a financial bureau and a market bureau. Within the market bureau is a fraud bureau. In addition, there is a securities bureau and regulated industries bureau. As commissioner, you have to rely on your staff. In Iowa, each analyst has 10 to 12 companies to cover for a first-level review. We have great people in the state of Iowa, and we had a process for elevating issues. So, if they detected an issue, they would raise it pretty quickly. My goal was “no surprises.” See also: Talking Insurtech With Regulators   Analysts develop a deep understanding of the companies they supervise. We were fortunate, as we had a lot of people who had been there a long time. I would often joke that some of the people in the division knew the company as well as the people within the company because, in a way, they grew up together. What are the touchpoints between a carrier and a regulator? It really varies based on the size of the carrier, to be honest with you. The larger, more complex groups are going to have more touchpoints. Some of the larger companies would come in every quarter to present financials, for instance. On the other hand, you might only see the smaller carriers at a conference. So, it really varies based on the size of the organization and issues within them. We also have other opportunities to interact, as well. For example, there are the NAIC meetings: three every year, including regulators and a number of companies, and there is often open dialogue between consumers, companies and regulators at those meetings. How do you stay current with a carrier’s operations? On the financial solvency side, you get to know a lot of these companies very well – reviewing quarterly blanks, annual blanks and financials. Also, every five years, you do a deep dive exam into these companies on the financial side, which is very cumbersome and, some would argue, burdensome. But, that’s why the system works. It’s important to remember that these companies are not static – you don’t just put the information in a file or in a drawer and forget about it. They’re more like living and breathing entities, unique and changing and, we hope, always getting better. One tool that regulators use to understand the risks of the larger groups is the ORSA. That provides a deep review of the carrier’s risk and is a very powerful tool for insurance regulators. So, the regulators approach each company uniquely? To some degree, yes. I’ve always said: “If you’ve seen one ORSA, you’ve seen one ORSA. If you’ve examined one insurance company, you’ve examined one insurance company.” They might all have a lot of similar issues, but they all have different issues, as well. Regulators need to regulate on risk basis. A number of factors such as size, market and product could lead you to a different approach. Due to resource constraints, it is important to regulate accordingly. In terms of the reporting that comes through, with respect to MCAS [Market Conduct Annual Statement], quarterly, annual, various data calls, how does that work? Those are all electronic now. It used to be paper-based and very laborious and time-intensive. Now, you get on your computer, and it’s just there. This is really a necessity based on the number of companies we regulate and the amount of data. How do you handle and evaluate such a large quantity of information? You can’t really have a formulaic, prescriptive approach; it’s got to be risk-based. What I mean by this is you’re really starting to look for trends and outliers. You tranche it out by line of business, or size of organization, etc. It’s more of trend analysis in the context of what is happening in the marketplace. You can’t say “we’re always going to look for one way to do it.” As you know, things trend differently: from year-to-year or quarter-to-quarter. If you see an anomaly, you start with context. If long-term care complaints spike, it might be simply because rates have increased – which, incidentally, the commissioner approved. You start to look for different trends on the consumer side, but you can’t really dive deep enough to every single thing you get on file to have a picture. How does a risk-based approach factor into your analysis of a carrier’s market conduct data? You look for trends, and I think MCAS [Market Conduct Annual Statement] is an example of how the regulatory system works pretty well. As an industry, we come up with what we think is an acceptable replacement ratio for annuities, or lapses for life insurance, or complaints per premium, etc. If companies fall outside of these benchmarks, you start asking questions. Sometimes, there’s a really good answer. Other times, you may have another issue. And this is really where the state-based system, depending on your point of view, either shines or has issues. Other states could have a different benchmark. Other states may say, “we’re just going to review the top ten because they are the biggest.” My point of view is, just because a carrier is a certain size doesn’t mean that I want to look at them every year. I want to look for risks and problems. You look at things differently with a risk-based approach. Take the ORSA [Own Risk Solvency Assessment], for example. Even though this is a solvency assessment, it also contains market analysis. Continuing the approach of applying context into the other areas that we regulate, and not just the big groups, works well. So, while a small or mid-sized carrier is not going to file ORSA, I think it’s a better regulatory approach than to say, “we determined that you just had too many complaints this year.” See also: How to Bulletproof Regulatory Risk   Is that a benefit of the state-based system? That Iowa might not be discounting the small carriers when they are looking at market conduct, while other states might look at just the bigger players? Absolutely. On the market side, there is definitely a check and a balance. I would say it this way: Commissioner Jones in California told me that he had 220 fraud investigators. Well, the state of Iowa has 115 employees in the whole department, and that includes insurance as well as securities. The state of Iowa has two fraud investigators. Iowa certainly doesn’t need 220, but it’s easy to see the disparity and the size of the market. His biggest issue is the size of the California’s market. It’s the sixth- or seventh-largest in the world. And, it doesn’t have a ton of domiciled carriers. So, Commissioner Jones has different issues and takes a different approach. He may look at annuity sales and complaints per $1,000 in premium, or another metric. California has issues that are more uncommon to them simply due to the size of the market. Are states more likely to identify different issues with a carrier? Yes. We may not see the same issue that another state would because our market is smaller. This is why the concept of checks and balances makes sense. And that is why it works pretty well. You have different states with different markets that identify issues differently from Iowa, or California, or Florida, or another state. Take Florida, for instance. They have a radically different population mix in terms of age and demographics, but also weather events. The issues unique to a state – hurricanes in Florida, earthquakes in California or Oklahoma, etc. – make for different issues and challenges that are best regulated locally. The system works well because it has a check and balance: Each state focuses on issues it identifies, which may not be as relevant elsewhere. Sometimes, it’s related to the size of the state’s market, sometimes it’s related to different risks in that state. Continued….

CES: User Interface Is Front and Center

Imagine a world without passwords, where TV remotes are rare, and mice only show up in the barn.

This year’s CES is no less mind-boggling than in prior years. With 2.7 million square feet of exhibition space, about 4,000 exhibitors, hundreds of sessions and 180,000 people, it is virtually impossible to take it all in. However, there are a few big themes that always emerge, along with a variety of interesting new products – some are potential game-changers while others are head-scratchers. But, I’ll save a more in-depth analysis for another blog to concentrate on one overarching theme I’ve seen from CES2018 – the prominence of the user interface (UI).

This emphasis on the UI is especially interesting because CES has historically been considered a “hardware” show, with the latest and greatest statistics touted by tech companies. Metrics related to speeds, capacities, pixels, size (some devices keep getting bigger while others keep getting smaller) and other units of measure dominate the discussions and marketing materials. But one prevalent thread throughout much of CES2018 is the dramatic expansion and innovation regarding how we interact with computers and the world around us.

See also: Rise of the Machines in Insurance  

Start with the fact that voice assistants are increasingly embedded into new solutions – Alexa, Google Assistant, Cortana, Bixby and others from prominent tech brands are leveraged in home devices, vehicles, mobile devices and many other smart things. Next, consider that haptics and gestures are becoming more advanced and being used to control more devices. New car company BYTON unveiled a car that allows interactions via five simple hand gestures (and that vehicle also has a 49-inch touchscreen and has integrated Amazon’s Alexa). Also, interactions based on our movements continue to be enhanced in the VR world.

Another area in which interaction is rapidly advancing is the use of biometrics. Fingerprints are already broadly used to unlock devices and to gain access to other digital assets, but we increasingly see solutions based on iris scans, facial recognition, hand geometry and other unique aspects of human physiology. We can all hope that the days of the password are numbered (YAY!).

Chatbots are emerging in many places, and people are getting used to interacting with them for sales advice, customer service and tech problems. Many still need to be infused with more AI to perform at a higher level, but there is a distinct trending toward more chatbot use. It is also likely that we will see a resurgence of avatars to give more personality to chatbots. At CES2018, I had my face scanned, and a highly accurate 3D model of my head was created in less than a minute. While the early applications of these types of 3D digital capture and creation tools are designed for virtual reality, using the tools for customer interaction is a natural extension.

See also: Cyber Threats: Big One Is Out There  

Add to this mix the amazing advances in augmented and virtual reality, the appearance of all manner of screens (every size, shape and location possible), tech that adds the sensations of touch and smell to our virtual interactions with machines, and you get a formula that engages all our senses. The digital, connected world is in its infancy and is poised to transform our daily lives. One thing is clear, the way we interact with the world around us will be based on the types of UI advancements that are so front and center at CES2018.

One final wish: Imagine a world without passwords, where TV remotes are a thing of the past, using your fingers to type on a keyboard is rare, and mice only show up in the barn. Sounds like nirvana to me.


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.

Why Is Insurance Industry So Small?

The gap of uninsured or under-insured assets increased fourfold over the past 30 years. What is holding insurance back?

Small? According to Swiss Re, the global insurance industry generated $4.6 trillion in direct insurance premiums, or 6.3% of the global GDP in 2016. Without insurance, flights would not take off, ships would not set sail and you would not be allowed to drive your car. Insurance is a key enabler in the global economy, and, without it, the economy would quickly grind to a halt. How then can the global insurance industry be called small? Over the last few decades, the overall size of the insurance industry has not grown at the same rate as the other major financial markets, and it has struggled to increase its coverage, especially in new and emerging markets. It is a depressing statistic that ClimateWise (a global network of leading re/insurers, brokers and industry service providers) believes the gap of uninsured or under-insured assets had increased fourfold over the past 30 years. So why has the growth in the insurance industry been so sluggish, and what has constrained it? While there are differences between insurance and other financial markets, the growth of the foreign exchange (FX) market was undoubtedly fueled by the creation of an electronic marketplace. Up until the 1970s, the FX market was a very traditional, heavily intermediated, paper-based market. The high costs and length of time needed to complete a FX transaction limited the number of parties that were able to participate. See also: The World Is Flat; Insurance Is Round   Reuters, acting as an independent third-party provider, laid the groundwork for the first electronic FX marketplace in the 1970s by enabling parties to insert FX rates into their system, making them available on-screen to recipients. The electronic marketplace really took off in 1981 when Reuters enabled dealers to instantly communicate with each other to buy, sell or lend money through the same screen. The effect this had was that costs were greatly reduced, market liquidity grew, new participants were attracted to the market and it became possible to create a raft of innovative products. The FX market is now the world’s largest financial market, with more than $5 trillion changing hands daily. Although it may seem far-fetched to call the insurance industry small, it is fair to say that the insurance industry is nowhere near its potential size yet. As so many other industries have done, the creation of an electronic marketplace for the transfer of insurance risks would help drive growth, create efficiencies and stimulate innovation across the insurance market, benefiting the industry as a whole. AkinovA is building such an electronic marketplace for the transfer of re/insurance risks with the support and collaboration of some of the largest market participants. By taking an inclusive approach, AkinovA is bringing together all parts of the insurance value chain to enable the creation of a truly electronic marketplace.

The 'Moment of Truth' for Claims

The pressure is on insurance companies to move beyond incremental improvements and cost-cutting.

sixthings
Claims are a paradox for the insurance industry. Neither consumers nor insurers want claims to occur, but, when they do, they are critically important to both parties. Consumers want speedy resolutions, clear communications about status and, as a bonus, a personal touch. Insurers are looking for efficiency and accuracy and to eliminate the risk of fraud or litigation with claimants. When the claims process breaks down, consumer satisfaction falls and insurer costs go up – that is the penalty for a bad claims experience. In this sense, every claim is a “moment of truth.” In the low-touch relationship between consumers and their insurance companies, claims handling may represent the most important and meaningful interactions. That is why insurers are advised to look beyond mere cost savings and seek a richer, more data-driven and analytics-enabled customer experience that incorporates artificial intelligence (AI) and other advanced technologies. Insurers that get it right will transform claims from a necessary back-office function into a source of competitive advantage, market differentiation and increased customer loyalty. Achieving a seamless customer experience Insurers need to position themselves to win the future against an increasing range of competitive threats, such as insurtechs and other nontraditional players who may enter the market. With some insurtechs offering digital claims processing that can be initiated from mobile devices and completed within seconds, the pressure is on insurance companies to move beyond incremental improvements. To achieve the vision of a seamless and differentiating customer experience, insurers should:
  • Determine which existing data sets can be used to enhance the claims process
  • Identify external data and advanced technologies that can be applied to further reduce costs and remove friction
  • Define and emulate the practices from experienced leaders and the particular insurance use cases that can be piloted and deployed to greatest effect
  • Begin to build the required data and analytics capabilities
The age of experience: insurers vs. the leaders Historically, claims organizations have not been very effective or sophisticated in harnessing the wide variety of data available to them. Today, however, the opportunities are too compelling and potential threats to customer retention too severe to ignore. After all, today’s consumers have higher expectations than ever when it comes to efficiency, accuracy and personalization of service offerings – thanks to the very high standards by leading firms in e-commerce, consumer electronics and transportation. Seamless and intuitive self-service transactions are the rule in a wide range of industries, but an exception in insurance. Customer experience expectations Given that claims is often the most visible, customer-facing function in the insurance business, it is no wonder that it will be measured against other consumer-centric sectors and companies. Insurers may ask themselves if they offer:
  • Personalization capabilities, such as 1:1 pricing, choice of repair facilities, usage-based products, car pickup and delivery services and tailored recommendations
  • Real-time status updates, fast-track claims payouts and electronic submission of documents
  • A single point of contact and hasslefree experience overall
See also: The Cloud’s Vital Role in Digital Revolution   Social media has also upped the ante for insurers relative to the customer experience. The risks and costs of a bad claims experience can be amplified if customers choose to share their dissatisfaction through social media or consumer review sites. Social channels also give customers access to more information about the companies they do business with – information the companies do not necessarily control. The proliferation of advertising by attorneys seeking claimants suggests there are many dissatisfied claimants. Data and analytics in the customer journey The most important difference between the experience offered by insurers and that delivered by digital bellwethers from other industries is the latter’s use of data and analytics to define every step of the customer journey, from promotional offers and upselling recommendations to product returns and complaint handling. The bellwethers deeply mine their own customer records and external data sets (including social media streams) to thoroughly understand customers’ needs, gauge customers’ value and take specific actions based on those insights. This is a proven strategy to achieve customer-centricity at scale, with clear applications to the claims process. What matters to claimants — and how to deliver it Our insurance consumer research confirms that speed, efficiency and transparency are among the most important characteristics of a quality claims experience. Better data can help streamline steps in the claims process, setting the foundation for an enhanced experience and, ultimately, no-touch claims resolution for many claims. Streamlining claims processes Consider the options for insurers seeking to streamline or fully automate “no-touch” or straight-through processing for many basic claims:
  • Property and casualty (P&C) insurers can use historical repair data to dramatically decrease estimating times for different types of vehicles and homes. They can also better manage repair costs and quality based on deeper analysis of these data sets.
  • Advanced telematics data (including video imagery) can be instantaneously captured during an automobile accident and downloaded from the cloud to automatically trigger a first notification of loss (FNOL) entry. Underwriters can “score” the data to determine the extent of loss relative to the automobile’s current value.
  • Social media data can be analyzed to detect fraudulent claims.
  • Drones and satellites can survey damage and collect information about property damage to initiate claims before a homeowner makes contact.
  • Via intuitive apps or other interfaces, insureds can submit photos of damage to their homes or vehicles to initiate the claims process, provided there is no sign of fraudulent behavior (which analytics programs can evaluate).
  • AI can be used to scan claims for the likelihood of fraudulent behavior, while robotic process automation (RPA) can automatically pay claims that fall within certain risk and financial parameters.
Customer engagement Now consider the options for more timely and personalized service:
  • “Chatbots” issue notifications to the policyholder regarding claims status and payment amounts.
  • Voice analytics assesses customer sentiment during phone calls, with appropriate classification and prioritization of resolution.
  • Behavioral analytics are applied to model likely customer needs and identify high-value policyholders or those likely to dispute a claim.
  • Analysis of customer records can identify claimants facing renewal and good candidates for purchasing additional products.
In some of these cases, a quality claims experience can pay immediate dividends. In all of them, insurers can engage at key points during the claims life cycle, with accurate and consistent information delivered on a timely and transparent basis. At the same time, claims teams can focus on high-value interactions, high-risk claims and other exceptions. Common use cases for data and analytics in claims
  • Satellite and drone imagery: capture and analyze satellite data for more accurate damage assessments after storms or natural disasters
  • Voice/biometrics: analyze recording of contact center conversations to identify customers at risk of a negative claims experience, and to match the right claims handlers to the right claimants
  • Automation and no-touch processing: leverage RPA to process all low-risk claims under a certain threshold; then expand straight-through processing to a broader pool of losses, reviewing claims types and policyholder history to evaluate claims risk
  • Vendor analytics: Combine internal data and geospatial modeling techniques to determine best-performing vendors
Claims transformation in action: addressing the claims process with telematics data First steps forward: where to start for a better claims experience As the previous examples show, there are many steps in the claims process that insurers can digitize and streamline for a better experience, no matter where they are on the maturity curve today. The path to full claims transformation is traversed in a series of well- thought-out steps that produce useful learnings and incremental value. Substantial improvements do not necessarily require new technology or huge teams of data scientists. Most insurers can and should start with the data they already have before looking to external data streams or adopting RPA, AI or other advanced technologies. They must also recognize that these once-futuristic-seeming technologies are ready for everyday use in claims. Data The priority should be to use data to create full views of individual claims from multiple perspectives. Internally, that means transactional data and historical customer data. Useful external data streams include:
  • Weather data
  • Consumer credit data
  • Medical billing patterns
  • General loss details information
  • Social media
All of these inputs will help evaluate future risk and leakage risks and support potential process and experience improvements. See also: Go Digital… but Don’t Change Who You Are Technology More mature organizations will look to leverage new data storage and management technologies, such as data lakes, as the basis for advanced analytics and real-time visualization. The most forward-looking insurers may build out data science teams to probe large and diverse data sets stored in analytics ecosystems. Machine learning and visualization techniques can help predict claims risk with greater accuracy and certainty. They can also provide a consistent claims handling approach relative to unbiased reserving, litigation, subrogation and other claim processes. It is important to note that the benefits of more data and more effective analytics extend beyond the customer experience in claims. Organizational factors A better experience in claims is not simply a matter of better technology. Culture and a willingness to embrace change also matter. Test-and-learn approaches may be necessary for insurers with limited digital capabilities. For instance, they may begin by piloting automated processing for claims of relatively small amounts or trying bot-driven notification systems to improve communications. Many insurers must overcome risk-averse cultures to encourage experimentation and “fast failures” in the spirit of learning what works. Some early-adopting insurers have embraced analytics labs or customer experience centers of excellence, where relatively low-risk and low-cost experiments can be carried out in controlled environments. For instance, organizations can analyze the costs and benefits of no-touch processing for claims within certain parameters and creating special “SWAT teams” of experienced claims adjusters to focus on the claims that merit human review and intervention. The path forward to enhanced claims experience No matter where they are on the maturity curve, claims organizations can start to advance the experiences they offer. The bottom line: the experience is everywhere Customer experience was once largely the realm of marketing and service teams. Now, the proliferation of digital channels means the customer experience is everywhere customers interact with companies – from social media to brick-and-mortar spaces to billing and accounting. Further, the experience matters most where customers say it does. In insurance, that means the claims process. To seize this unique “moment of truth” opportunity to strengthen customer loyalty and boost retention, forward-looking insurers will leverage an expanded set of data and adopt more sophisticated analytical tools and techniques. Indeed, more effective use of data and analytics is one of the best ways for insurers to simultaneously improve financial performance, differentiate from competitors and deliver what customers want, which in claims is a fast, accurate, transparent and personalized experience.

David Bassi

Profile picture for user DavidBassi

David Bassi

David Bassi is an industry leader with experience in underwriting. risk management and analytics. He has led efforts at prominent global companies to integrate advances in data science, technology and the capital markets into traditional business models.


Rob Dietz

Profile picture for user RobDietz

Rob Dietz

Rob Dietz is a principal in the advisory services practice of Ernst & Young LLP. He has more than 20 years of experience in property and casualty (P&C) insurance.

What Smart Speakers Mean for Insurtech

Insurance providers cannot ignore this opportunity to use smart speakers to develop better, more convenient ways to serve customers.

||||
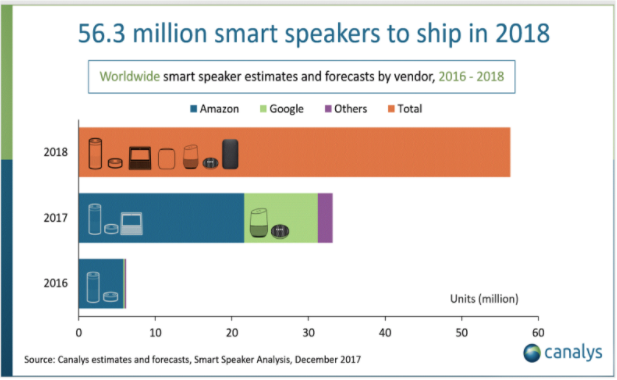
Are the Amazon Echo and Google Home insurtech? They sure are! The two top-selling smart speakers have become so competitive that, in Canada during the past holiday season, each company undercut the other by offering the smaller versions, the Echo Dot and Google Home Mini, for as little as $39.99. For that price, why not buy one and try it out? A recent report from Canalys states that the smart speaker is now the fastest-growing consumer technology. It is growing faster than augmented reality (AR), virtual reality (VR) and wearables, with smart speaker shipments expected to top 56 million units in 2018. See also: Global Trend Map No. 5: Analytics and AI   Since the launch in Canada of the Google Home in July 2017 and subsequently the Amazon Echo in December 2017, the following insurance services have been made available:
  • Aviva Canada — Aviva made a skill for the Amazon Echo to help consumers find answers to common insurance questions and to get an insurance quote. If a person is curious about accident benefits, for example, all they have to do is ask, “Alexa, what is accident benefits coverage?”
  • Manulife — Manulife’s skills for the Amazon Echo advise customers on what is left on their health benefits. Need new glasses but not sure how much coverage you have? Simply ask, “Alexa, ask Manulife Benefits how much do I have left for glasses?”
  • Kanetix.ca and InsuranceHotline.com — Both comparison websites made Google Assistant actions to support comparing car insurance quotes. Drivers just have to request a quote by saying, “Hey, Google, ask Kanetix.ca for a car insurance quote.”
  • RateSupermarket.ca has a Google Assistant action that supports finding the best mortgage rate in any province. All one has to do is say, “Hey, Google, ask RateSupermarket.ca for the best mortgage rate in Ontario.”
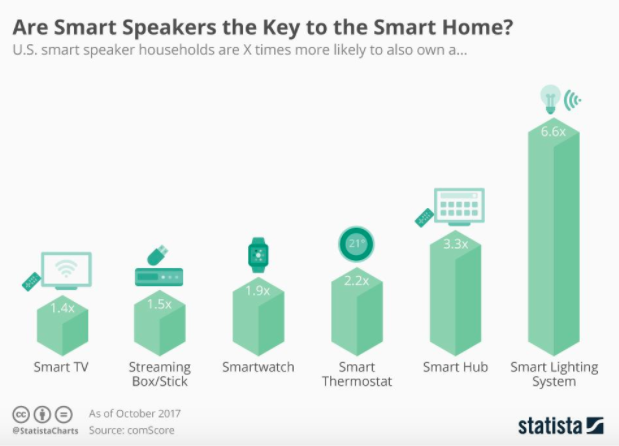
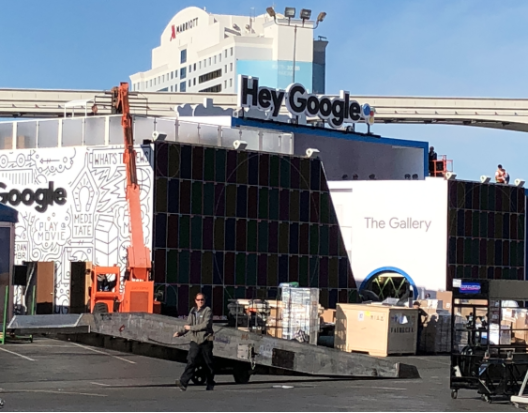
Not only is the smart speaker convenient for finding information, it is also spurring the sales of smart devices and IoT (Internet of Things) technology for the home such as smart plugs, smart appliances and smart entertainment…basically, smart everything. The Amazon Echo and Google Home can be used to turn on the lights, turn on the TV, change the channel and even find the best science fiction on Netflix. Here is some recent data from ComScore and Statista showing the likelihood of IoT ownership for smart speaker households. See also: What I Learned at Google Google rarely has any presence at the Consumer Electronics Show, but this year Google is out in full force going head-on with Amazon Echo. Smart speaker adoption and integration to IoT devices is expected to be a megatrend at this year’s CES, which began yesterday in Las Vegas. The adoption, sales and marketing of both Amazon and Google smart speaker assistants is clearly making this device a must-have in the home. Insurance providers cannot ignore this opportunity to develop smarter, more convenient ways to service their customers. If the smart speaker can really fire up IoT adoption in the home, insurance providers can’t ignore the data it can collect to create better products that improve the management of risk and claims for the household.

Andrew Lo

Profile picture for user AndrewLo

Andrew Lo

Andrew Lo is president and CEO of Kanetix.ca, leading all digital innovation and operations for Kanetix Ltd., Canada’s largest digital customer acquisition platform for insurance and financial services.

Will Amazon Disrupt Insurance?

A look back at predictions from 2017, plus some thoughts on whether Amazon will disrupt insurance. (Short answer: It won't.)

|
In the last months of 2017, I wrote - together with my friend Andrea Silvello - “All the Insurance Players Will Be Insurtech,” and the book was published in the first days of 2018. See also: Is Insurance Really Ripe for Disruption?   I included all the foundations of my insurtech thoughts; the elaboration of many discussions I have had since I published my article “Will fintech newcomers disrupt health and home insurance?” in August 2015; and a review of my five insurtech predictions from a year ago. Here is that look back, followed by a prediction on the hottest discussion at the start of this year: whether Amazon will enter the insurance industry: Prediction: Exit Not everyone will prosper. Although many amazing insurtech companies are seeing great results and scaling up—and many will continue to enter the field—some will surely leave the game, as well. Result I was dreaming of an insurtech unicorn’s exit. Well, dreams become reality sometimes: Well Zong An – the Chinese full stack insurtech – made its IPO with a $10 billion evaluation in fall 2017. Also, Travelers acquired Symply Business for $400 million. On the other hand, Guevara left the game in the second half of the year. This winnowing down, a Darwinian “survival of the fittest,” should ultimately strengthen our industry. Prediction: Reconversion This is the other side of the moon. I saw many initiatives doing a great job putting together a fantastic team and a sexy equity story, and some raised relevant capital, but their business models look (to me) not sustainable from an insurance perspective. I don’t want to claim that no one of them could succeed, and history has already shown how skepticism can be wrong. But I’m expecting to see some players use their great skills and the funding raised to change radically their business models. Result In spring 2017, Trov did a round of financing of more than $40 million with a valuation higher than $300 million, but, from what we heard from the CEO at different conferences, the company is focusing its efforts on a back-end system that insurers can use on their customer base rather than on growing its customer base and portfolio of on-demand risks. Also, Zenefits went through a difficult 2017, stepped back from the brokerage business and started to license its technology as an SaaS (software as a service) player. Prediction: Connected Insurance My two cents are on any insurance solution that uses sensors for collecting data on the state of an insured risk and on telematics for remote transmission and management of data on the insurance value chain. A crazy prediction: Let’s consider the most mature use case, auto insurance telematics in Italy, which represents one of the best practices globally. In the country, I’m forecasting more than 7.5 million cars connected with an insurance provider by the end of 2017 (compared with 4.8 million cars connected at the end of 2015). Result In line with the expectations, Italy’s insurance telematics policies had reached 7 million by the end of third quarter 2017, according to the IoT Insurance Observatory. Prediction: Culture Shift Incumbents are becoming always more interested in debating innovation and concretely testing new approaches, including collaboration with startups. I expect to see this new breeze surround old-style insurance institutions, with a growing awareness on how all the players in the insurance arena will be insurtech players. Result A board member at one of the largest global reinsurers recently summarized the essence of insurance as assessing, dealing and accepting risks using the latest technologies. That’s one sign that the industry is coming around. We saw 3,800 more signs at InsureTech Connect, the world’s most prestigious insurtech conference. In 2016, the conference had 1,200 participants; in October 2017, it sold out with more than 3,800 attendees. Andrea and I were there on the stage and witnessed the incredible energy of those insurance professionals, regulators and startups. Prediction: Sustainability Many value propositions are bundling risk covers and services, thus allowing the insurer to influence behaviors and prevent risk, contributing to the sustainability of the sector. In the next months, I expect to see some insurers becoming more relevant in the life of their clients and act as partners and not only as claim players. Result The speeches of top insurance executives show the sector’s ambition to go in this direction. A slide projected on a wall is just that, however: in the field, we see very few examples of implementation. What will happen in coming years? Unfortunately, I damaged my laptop a few days ago so my crystal ball for the 2018 predictions is also not working...but I want to provide my middle-term view about the issue most-discussed at the end of 2017: Amazon activity in the insurance sector. I predict Amazon will not disrupt the insurance sector. I believe it will do something – especially around insurance coverages on the products it sells – but will not be able to touch the core of the insurance profit pool on either commercial lines or personal lines (auto, property, life, health). My view is based on two main beliefs:
  • One of the key elements to be a successful insurer is underwriting discipline, as highlighted by Mario Greco recently or some famous Warren Buffett sentences in the past. Well, I believe that underwriting discipline conflicts with the culture of any tech giant. Amazon could buy an insurance company or hire talented people to close the gap on insurance knowledge, but the corporate culture doesn’t fit with the insurance business fundamentals.
  • In insurance, each market has its particular characteristics. One size doesn't fit all -- the opposite of how things work in social media or in internet businesses. I'm speaking about what the customers want (need) to buy in the different markets and how they want to buy it. In life insurance - the usual push product, which needs to be sold – digital channel at global levels represent less than 1% of new sales. But even look at auto insurance. The U.K. auto insurance market is controlled by online distribution, and, 10 years ago, insurance executives assumed that all Western European markets would follow the U.K. path within a few years. But auto insurance distribution in Europe continues to be dominated by traditional channels. You can argue that local carriers executed poorly, but even branches of U.K. insurance groups, with their great expertise, couldn't duplicate the success that was had in the U.K.
I don't think things cannot be changed. In fact, I believe there are a lot of opportunities to do things in a different way. But "one size fits all" doesn't work, and I’m skeptical about the tech giants’ ability to deal with those local insurance characteristics. A tech giant based in Silicon Valley or with a European hub in Dublin will dirty its boots on insurance distribution (or other steps of the value chain). It is an interesting time to be in the insurance sector, but I’m pretty confident GAFA (Google, Amazon, Facebook, Apple) and BAT (Baidu, Alibaba, Tencent) will not disrupt this sector.

5 Ways to Fight Price Comparisons

Financial institutions risk being seen as nothing more than a service provider or white label supplier.

||
Virtually everyone agrees that many insurance markets have shifted from push to pull. Technology helps consumers to make better-informed and more rational decisions, and they are making use of this. Customers go through a significant part of the buying cycle before they contact a broker, agent or insurance firm. Although insurers are aware of the transition from push to pull, they have made hardly any adjustments to their customer engagement strategies and required capabilities. Insurance carriers have several ways to key in to the increasing importance of pull strategies. The one closest to home is "When you can't generate sufficient traffic yourself, you can, of course, always use the pull power of others." Consequently, many carriers rely on search engines and comparison sites. Double-edged swords Search engines, review and comparison sites play a key part in the online orientation and choice process in virtually every product category – insurance is no exception. Insurers view search engines and comparison sites with mixed emotions. Comparison sites are like double-edged swords. On the one hand, they create more transparency and convenience for customers and bring in a substantial part of the business. In general insurance, in mature markets, this can be 30% to 40% of the customers. On the other side, both rising costs and dependency on search engines and comparison sites are becoming a major pain point. Leaning too much on search engines and comparison sites may not be a sustainable strategy. If a financial institution is becoming too dependent, it is actually becoming a commodity and could end up being nothing more than a service provider or white label supplier. See also: What Is the Future of Comparison Sites?   Comparison concerns Several insurers we spoke to shared the following concerns:
  • Many consumers start their path to purchase on the websites of brands that are top of mind for them. After that, consumers visit a comparison site to research possibly cheaper alternatives. Even if the insurer is still the best, the customer does not return to the site of the insurer but concludes the deal where he is at that point in the purchase process: at the comparison site. Consequently, the insurer has to pay a high commission to the comparison site, often even significantly higher than the average broker’s or agent’s commission, and all the while the customer had in fact already decided on that particular insurer.
  • Customers coming in via comparison sites are not necessarily the best customers, or the best business. The insurer generates its revenues mainly in segments where it is one of the cheapest – and those are usually not the most profitable segments. Consumers in those segments are by nature more calculative and price-sensitive, and therefore less loyal. Price comparison sites can increase switching rates by more than 30% and have a less favorable claims profile, according to quite a few insurance executives that we have spoken to.
  • The focus on price, rather than the cover and services, may lead insurers to strip their policies, instead of really guiding customers toward the best-fitting solution.
Shift power back Obviously, because of these concerns, many insurers are thinking about how they can shift power back from the comparison sites. We already see the following five strategies to fight price comparison:
  1. U.S. insurer Progressive offers comparisons with competitors on its own website, within the quote that the prospect is getting -- even if Progressive is more expensive. Customers will find that information anyway, so it’s better to tell and explain it yourself. Because the comparison is made using the same covers, customers can be sure they are comparing apples with apples, and price is the sole differentiator.
  2. U.K. insurer Admiral set up its own comparison sites. Dutch insurer Achmea acquired Independer.nl, the largest comparison site in the market. Comparison concept GoBear, an Aegon joint venture, is conquering Southeast Asia.
  3. Different products can be highlighted on your own website with features and benefits that are not offered through comparison sites. Or companies can use a "Lego brick" type of product approach: simple, cheap products that perform well on comparison sites. Once customers are acquired, they can easily add more features and drive complexity.
  4. Companies are creating more awareness through relevant and distinctive branding.
  5. Some leverage the power of customer reviews. Increasing the number of reviews, of course, implies that service has to simultaneously become more important.
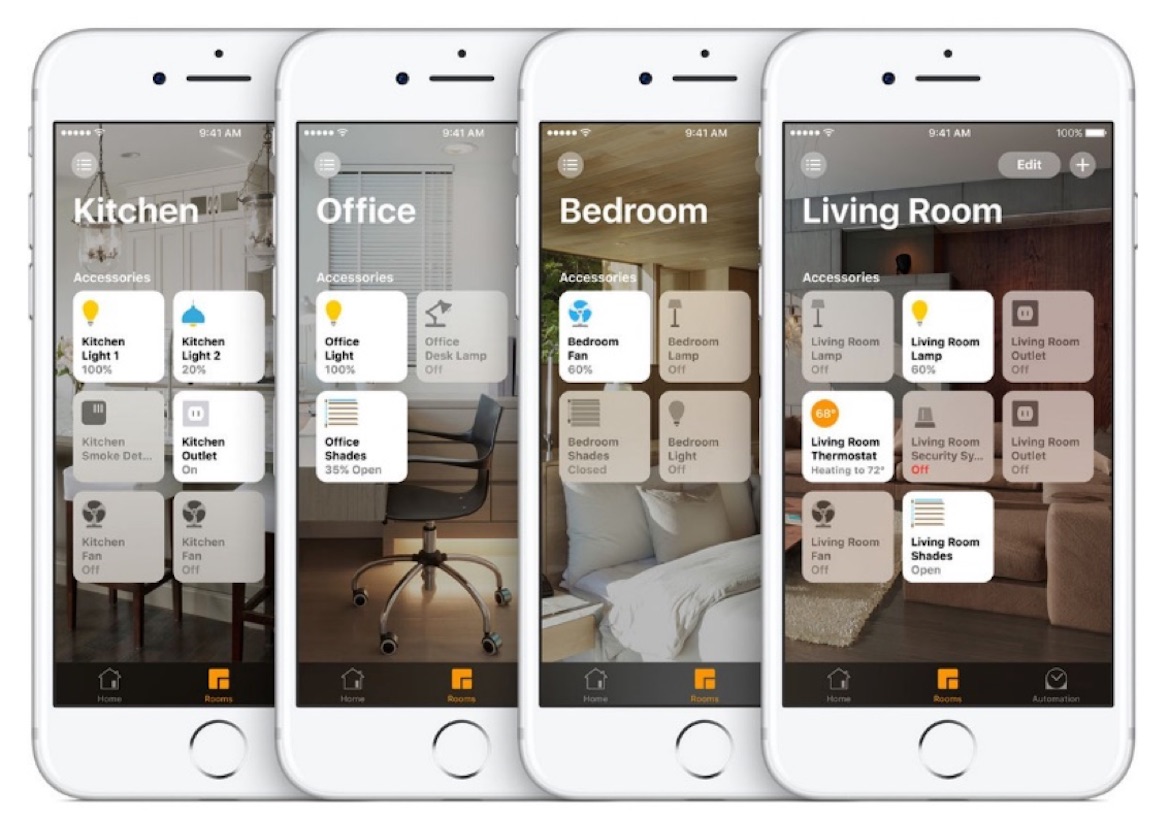
[caption id="attachment_29638" align="alignnone" width="570"] Visual: AEGON’s highly successful GoBear[/caption] Strategy 6. Pull platforms We believe that, apart from these five strategies, there is ample room to make more use of the possibilities that new technologies have to offer. The challenge is to close the gap between the financial institution and the customer. The contact frequency with customers is an essential part of the economic engine. Companies can move from transaction to interaction, from one-way communication to a dialogue and from interaction to intimacy, taking the dialogue from exchanging information to pro-active actions. Sooner rather than later, insurers need to define their own pull strategies and start working with other pull platforms rather than search engines and comparison sites only. GAFA carry pull in their genes In sessions we had the past few years in many boardrooms, one topic kept coming back: the fear of Google, Apple, Facebook and Amazon (GAFA). With regard to customer engagement, what is especially interesting is that all these companies don’t just apply a random number of pull instruments, but literally carry pull in their genes. Apple, for instance, has over time developed a number of successful pull platforms, like the iTunes store and the App Store. In both cases, supply and demand are brought together. Many people decide for the iPhone because of the brand and the design, but an important part of the success lies in the vast number of apps that Apple has created a platform for. Apple HealthKit, the health platform of Apple, gathers data from a wide variety of sources ranging from food and exercise-tracking apps and connected weighing scale to glucose and blood pressure measurement tools. There is also the comparable Apple HomeKit. Both can become just as successful pull platforms in their respective domains as the iTunes and App stores. [caption id="attachment_29639" align="alignnone" width="570"] Visual: HomeKit is Apple's platform for third-party smart home gadgets that talk to each other through iOS devices and are Siri-voice-controlled.[/caption] See also: Insurtechs: 10 Super Agents, Power Brokers Eight key characteristics of Pull Platforms We have analyzed the pull platforms of the companies mentioned above, from non-tech companies like Nike, Danone and Unilever but also from the first financial institutions, fintechs and insurtechs that have established successful pull initiatives. Our analysis revealed that these pull initiatives all have their own mix of eight key characteristics. In our next post we’ll dive into all eight. So stay tuned!

Roger Peverelli

Profile picture for user RogerPeverelli

Roger Peverelli

Roger Peverelli is an author, speaker and consultant in digital customer engagement strategies and innovation, and how to work with fintechs and insurtechs for that purpose. He is a partner at consultancy firm VODW.


Reggy De Feniks

Profile picture for user ReggydeFeniks

Reggy De Feniks

Reggy de Feniks is an expert on digital customer engagement strategies and renowned consultant, speaker and author. Feniks co-wrote the worldwide bestseller “Reinventing Financial Services: What Consumers Expect From Future Banks and Insurers.”

The future is now for autonomous vehicles

As we head into 2018, we’re all trying to figure out what the insurance industry can expect from innovation.

sixthings

As we head into 2018, we’re all trying to figure out what the insurance industry can expect from innovation, and whether this will be the year the industry will embrace transformation. Several of the six articles linked to below will provoke some thoughts, and you’ll see plenty more outlook pieces over the next couple of weeks at the ITL website.

To get the juices flowing, here is a bold prediction from our own Guy Fraker, ITL’s Chief Innovation Officer, as well as a way for you to hear more from him.

First, the prediction. Guy wrote to me:

“Hardly a day goes by without someone publishing an article about why autonomous vehicles (AVs) won’t see deployment until 2025. In fact, 2018 will be the year that scaled deployment begins.

“One reason many people expect a slower rollout is because it takes some 15 years for the whole fleet of cars to turn over, but at least nine capable companies are racing to produce an aftermarket kit that can retrofit existing cars. AutonomouStuff has provided hardware, software and engineering assistance to more than 2,700 organizations that are already operating fleets of cars, trucks and semis that all began as stock vehicles but that are now running autonomously on public roadways. At ITL’s Innovator’s Edge, we are tracking 222 startups dedicated to autonomous vehicles that have received $6.2 billion in funding in just the past 24 months.

“So much for fleet turnover setting the pace. 

“Insurance is playing its part. Munich Re said way back in 2015 that AVs would be a primary growth market. Google’s AV program, Waymo, recently announced an alliance with Trov (after an introduction by ITL) to provide insurance for Waymo’s driverless fleet in Phoenix.

“I, personally, have worked with regulators on the AV issue, including spending two days with Google and 38 state insurance commissioners in 2017. Most states, led by Florida, are inclined to limit regulatory requirements.

“So they won’t stand in the way of innovation, either.”

Now, the way to hear more.

The first major conference of the year—one that features a wealth of insurance industry leadership onstage and in the audience—is the annual Joint Industry Forum, held at the Marriott Marquis in New York City on Jan. 16, and Guy will be speaking there. The event, organized by the Insurance Information Institute, features a panel on the digital technology revolution that includes Guy and two of our good friends: Pete Miller, President and CEO of The Institutes, and Donna Peeples, Chief Customer Officer of Pypestream. The conversation will be led by James Dodge, Practice Leader of Milliman Advanced Analytics. 

The panel will look at how technology can be integrated into supply chains and will tackle Guy’s two threshold questions for insurance executives: 

  1. Are you accepting that transformative change is underway?
  2. Do you have the will to embrace this period as opportunity more than threat? 

The JIF will feature several other panels, including the perennial CEO panel, which will be especially worth hearing for their views of the future. To learn more about the agenda, and register to attend while there is still time, go to JIF Registration. 

Cheers,

Paul Carroll,
Editor in Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.