Download

Innovation Is Really Happening

It’s hard to change when you’re going 100 mph every day. Yet, despite challenges across the industry, a lot of innovation models are appearing.

We talk about innovation all time. Yes, it is mandatory. Yes, your competitors are doing it. Yes, it means fundamental changes within an organization. But what does innovation really mean, and where do you start? An innovation is defined as a new method, process or product. For insurance, the quest to build something new or transforming has quickly become foundational. The focus on innovation has naturally created an industry-wide platform that pushes us to rethink, redesign, reimagine and reinvent our roles, structures, products, services, processes and technologies. We’ve been talking about and tracking innovation for several years now. And creating a culture of innovation is probably still the biggest hurdle. We are operationally focused. We are successful. We’re financially strong. It’s hard to change what you’re doing right. It’s also hard to change when you’re going 100 mph every day. Yet, despite challenges across the industry, we’re seeing a lot of innovation models appear. And in those models, we see segments of change and real action on innovation. See also: Linking Innovation With Strategy   What’s fascinating about 2017 is that almost all insurers in our research (more than 90%) have some type of innovation happening across their companies. It has taken hold, even at a regional- and small-insurer level. It’s happening, from the $500 million companies all the way down to the $50 million companies. It takes the forms of what could either be called an innovation initiative, a digital strategy of which innovation is a part or tracking and partnering with insurtechs and emerging technologies with innovation as a part of that. In other cases, innovation is disguising itself in the strategic initiatives. Or, it’s just flat-out called an initiative within the company in its own right. About half of the insurers are still in the development phases of innovation, trying to define it, trying to figure out the process, the people, how to invest in it. And the other half are maturing. Some of those have been creating and evolving innovation labs for three, five or even seven years. I remember our first SMA Summit, when we gave an Innovation in Action Award to Allstate for creating an innovation lab. It was just the beginning of insurers thinking of innovation in a big way. Now, innovation labs are virtually everywhere, on every scale, inside and outside the structure of the insurance company walls. As an industry, and for most insurers, it’s still a struggle to create innovative thinking and tie it back to strategies and operations – or to flip the approach and take our business strategies and tech investments and innovate those. Or to really find the value for the operations, or to see the value from a customer or agent/broker perspective. At the end of the day, insurers are still required to pay a claim, make money and provide dividends to either their shareholders. Right now, it’s a balancing act between fulfilling the needs of the daily business and progressing into the future with innovation initiatives. See also: Global Trend Map No. 6: Digital Innovation   This year’s SMA Summit is scheduled for Sept. 17, 2018, and the theme is Transformation in Action. I can’t wait to hear the stories shared about the innovations realized. We have come such a long way in so short a time. It’s amazing to think that, just seven years ago, the thought of an innovation lab was groundbreaking. Finally, if you are just beginning, or unsure where to start, remember that starting small works! Just start somewhere. It may take a leap of faith to acknowledge that there are places in your organization that need to be transformed. But today, there is more support than ever – from all of us at SMA, from customers, from solution providers and even from competitors. The time is now. Just jump in! Read our latest research report on innovation: Innovation is Mandatory: SMA Annual Innovation in Insurance.

Deb Smallwood

Profile picture for user DebSmallwood

Deb Smallwood

Deb Smallwood is the founder and CEO of SelfPowerment.

She spent four decades in corporate leadership across the insurance industry, operating at the intersection of business, technology, and organizational transformation. Her leadership inflection point led her to research the experiences of more than 50 high-achieving women and 10 men leaders. This formed the foundation of her book, SelfPowerment: The Inner Shift for High-Achieving Women Who Want More Than Just Success. The work introduces a research-informed framework that redefines success from within and invites women to shift the question from, “Will they choose me?” to “Do I choose them?”

Top Challenge for HR Teams in 2018

In 2018, the key word is going to be “agile,” and human resource teams will be responsible for making it a reality across the organization.

We all have that colleague who overuses buzz words and phrases such as: "synergy," "deep dive" and "low-hanging fruit." Yet, every now and again, a buzz word arises that actually affects your business. In 2018, that word is going to be “agile,” and human resource teams will be responsible for making it a reality across the organization. Business agility is the ability to adapt and respond rapidly to changes in the environment while sustaining success. Depending on the size and stage of your organization, agility may require bold internal policy transformations, a new approach to hiring or paradigm shifts in company culture. Agile isn’t new, so why will it creep up the challenges list in 2018? With questions swirling around whether the economy can sustain its momentum, uncertainty has again set in. Organizations with the ability to quickly adapt to changing business and economic conditions, companywide and HR-focused objectives – particularly those focused on driving growth – won’t have to be compromised. Yet nearly 700 executives reported having little confidence in their companies’ ability to quickly mobilize in response to market shifts. More than 50% of those surveyed did not believe that their culture was adaptive enough to respond. See also: The Human Resources View Of Health Care Benefits Needs To Change  To solve this quandary, CEOs are turning to HR leaders. CEOs are providing a mandate to create a workforce and cultivate a culture that is agile and nimble enough to capitalize on new opportunities and overcome deep-rooted organizational challenges. At Peak Sales Recruiting, we work with HR leaders from some of the most innovative and disruptive companies. Based on their collective experiences and the latest studies, we have compiled three ways human resource and talent acquisition teams can harness the power of agility to drive organizational performance in 2018: 1. Learn from Tom Cruise in "Mission Impossible:" In the popular movie franchise, Cruise leads IMF, a self-managed team that operates outside of government bureaucracy to save the U.S. from evil. In the real world, many leading companies such as Microsoft, Spotify and Airbnb have employed similar strategies. For example, "Scaling Agile @ Spotify" formed cross-departmental teams that functioned like a startup, with Spotify as the incubator. The teams – Tribes and Guilds – had delegated decision-making autonomy on key service and product development initiatives. Their work has been so important that they’ve helped the company keep giants like Apple from stealing market share in a growth segment. Bain research studied 300 large corporations worldwide and found that the top quartile’s key to success was that they spent 50% less time on unnecessary and ineffective collaboration. That is why small, talented teams that work outside of traditional hierarchical management systems can solve mission-critical issues, faster. To be more agile in 2018, HR departments must work closely with C-suite executives on empowering middle and front-line leaders to build nimble, cross-functional teams. 2. Transform internally at scale: A Korn Ferry Institute study found that increasing investment in aligning HR practices with business objectives resulted in a 7.5% decrease in employee turnover and, on a per-employee basis, $27,044 more in sales, $18,641 more in market value and $3,814 more in profit. But in tech, HR departments have traditionally struggled to be aligned with rapid go-to-market plays and shorter product-development cycles. Workforce policy development, talent acquisition tactics and competency and performance review initiatives weren’t in sync with the changing pace of business. Using agility as its foundation, one company approached the problem differently. McKinsey recently released a case study called ING’s Agile Transformation. Recognizing the importance of agility at scale, ING made 3,500 employees re-interview for their jobs. Remarkably, 40% of them ended up in new positions within the company or were let go. In many cases, the change was not because of an employee’s skill set. The issue was whether employees could embrace the constant state of change that financial service and fintech organizations need to remain competitive. ING’s HR department led an unprecedented overhaul of their organization, and this experience can be replicated across organizations in 2018. 3. Hire change agents with a versatile skill set: The phrase, “We have always done it this way,” is the kryptonite to success. Economic volatility and advances in technology, in certain cases, render last year’s business plan obsolete. While it is not necessary to reinvent the wheel every time, HR departments must evolve their competency models to hire people possessing change agent traits and experiences. Steve Jobs famously said that, if you want to hire change agents, hire pirates. He wanted employees who would challenge the status quo and were flexible, diverse, passionate and results-oriented. If HR departments do not bring in fresh people and ideas, the company will fail to improve in 2018. See also: Hacking the Human: Social Engineering Due to rapid changes in technology and the global economy, business agility will be a key differentiator between company failure and success. Being agile while maintaining company values and processes is a tightrope that CEOs are asking human resource professionals to figure out. Never has a buzz word meant so much.

Keith Johnstone

Profile picture for user KeithJohnstone

Keith Johnstone

Keith Johnstone is the head of marketing at Peak Sales Recruiting, a leading B2B sales recruiting company launched in 2006. Johnstone leads all marketing activities and has successfully grown revenue and lead volume every quarter.

A Growing Challenge: Managing Talent

Savvy businesses are responding to a tight labor environment by reevaluating their recruitment, retention and compensation practices.

sixthings
Recruitment and retention of sufficient workers presents a growing challenge for many U.S. businesses in manufacturing, construction and many other segments of the economy. Competition for workers continues to grow as the improving economy drives down unemployment and applies pressure on employers to increase wages. U.S. Bureau of Labor Statistics November employment statistics, for instance, showed employment continued to trend up in professional and business services, manufacturing and healthcare. While most businesses welcome the uptick in business opportunities, the pressure to increase wages threatens the ability of many of these businesses to take full advantage of these new opportunities. While welcoming the strengthened manufacturing economic performance, the National Association of Manufacturers says manufacturers continue to say that the inability to attract and retain a quality workforce is one of their top concerns. Employers in the healthcare and services industry increasingly are reporting similar challenges. With tightening immigration standards making it more difficult to close gaps with foreign labor, savvy businesses are taking the initiative to respond to this changing labor environment by reevaluating their recruitment, retention and compensation practices. In addition to looking to recruit new workers from the ranks of the under- and unemployed, many businesses increasingly are looking to recruit employed workers from other employers by offering sweeter compensation, work-life balance, promotion or other sweetened employment opportunities. Businesses competing for the same workers will want to review their existing employment and compensation packages to help promote their ability to recruit workers and to retain existing workers. See also: What Is the Business of Workers’ Comp?   In recognition that other businesses may target their best workers, businesses should shore up their compensation and retention practices and strengthen their noncompetition, trade-secret and other critical workplace protections to guard against disruptions from loss of key personnel. When conducting these activities, businesses should not rely on past legal experience. Federal and state law has evolved significantly regarding noncompetition, trade secret and other business intelligence safeguards. Businesses that have not done so in the past year should consider engaging experience counsel to review their existing policies and practices for possible witnesses and opportunities for enhanced strength. Businesses also may want to discuss opportunities for bonus or other golden handcuffs compensation packages to give key workers incentives to stay with the organization. Employers also should recognize that departing employees may take advantage of opportunities to air resentments. In the face of these risks, employers will want to ensure that their existing wage and hour, harassment, safety and other workforce policies and practices are currently compliant as well as be prepared to respond to any allegations of past misconduct. Employers should carefully conduct exit interviews and investigate any alleged misconduct or other negative feedback to mitigate potential risks and liabilities. Employers also should consult with experienced employment and employee benefits counsel about appropriate design, administration and documentation of these policies, practices,i arrangements and activities.

Cynthia Marcotte Stamer

Profile picture for user CynthiaMarcotteStamer

Cynthia Marcotte Stamer

Cynthia Marcotte Stamer is board-certified in labor and employment law by the Texas Board of Legal Specialization, recognized as a top healthcare, labor and employment and ERISA/employee benefits lawyer for her decades of experience.

10 Insurtechs for Dramatic Cost Savings

Merely adding a digital channel or an app doesn't work. This only adds cost and increases complexity in the IT landscape,

Winning insurtechs tap into the key challenges that insurance carriers are facing. In this post, the second of seven different flavors of winners in fintech insurance: insurtechs that drive dramatic cost savings. Although emerging markets are witnessing significant growth, most mature markets are saturated and experience margin pressure. This will show little or no change in the years to come. Insurers are looking for ways to operate more efficiently in every major part of the costs column: in claims expenses, costs of operations and customer acquisition costs. Technology purchases and investments by insurance carriers will further explode in these areas. And so will the number of fintech solution providers that want to cater to that need. Learn from digital pure players Technology definitely eroded the barriers to entry. Successful pure-play digital insurers know how to leverage technology to defy the conventions related to cost drivers that incumbents still work with. According to McKinsey research, incumbents for instance are not able to operate profitably with fewer than 1 million policies. They hardly seem to benefit from scale economies, and for incumbents the costs of using broker channels barely differ from using digital channels. “The difference with pure-play digital insurers like InShared could not be bigger," says Irene van den Brink, director of business development at InShared, the first fully digital insurer player on the Dutch market. In only five years, it achieved 10% market share in online car insurance, the highest NPS score in the market as well as the lowest cost ratio. “We run 500,000 policies with a core team of only 35 FTE [full-time employees]. But the scalability becomes even clearer when I tell you that 1 million policies could be managed by just a few more FTE and not the doubling of FTE you would see in a traditional model. With our digital model, we have proven to run a portfolio of P&C (non-life) at a 10% cost level, where we see that more traditional direct players have a cost level between 20% and 30% and broker models even higher than that. And this is just the beginning: Adding volume to our operations means we can go as low as 75 to 8% expense ratios, leveraging the full potential of a digital model.” Apart from how digital new entrants leverage technology, we believe that two other factors are essential that explain the difference with incumbents. First, having started from a clean slate, digital new entrants lack the complexity of a wide product portfolio, multichannel operations and having to comply with existing processes and IT infrastructure. Second, they understand this and stick to it. Successful digital new entrants are complexity-averse by nature. That is why they succeed in scale economies where incumbents don’t, and that is why they succeed in keeping their cost base that much lower. This is where many incumbents go wrong. Van den Brink says: “Virtually every insurance companies has embraced the need for a digital solution. But merely adding a digital channel or an app is not the way forward. In fact, this only adds costs and increases complexity in the IT landscape, it adds databases, systems and the links needed become an even bigger spaghetti.” This is important to keep in mind when implementing fintech solutions to achieve substantial cost savings. The fintech solutions should address the root cause; they should dramatically reduce the complexity of current operations. See also: Top 10 Insurtech Trends for 2018   Go where the money is Insurers spend between 60 and 80 cents of each euro of premium on claims. This means ample opportunities for fintechs that provide innovative solutions that reduce this amount. Think of solutions for improved claims management and fraud detection. Due to insurance fraud, 60 billion euro is lost each year in Europe and the U.S. alone. Of all fraudulent claims, 65% go undetected. Insurers spend no less than 240 million euro annually to tackle fraud. 10 insurtech solutions that dramatically reduce such costs Everledger is using the technology behind bitcoin to tackle the diamond industry’s expensive fraud and theft problem. The company provides an immutable ledger for diamond ownership and related transaction history verification for insurance companies, and uses blockchain technology to continuously track objects. Everledger has partnered with different institutions across the diamond value chain, including insurers, law enforcement agencies and diamond certification houses across the world. Through Everledger’s API, each of them can access and supply data around the status of a stone, including police reports and insurance claims. OutShared recently launched the CynoSure digital insurance platform, a complete head-to-tail digital insurer-in-the-box. CynoSure is a SaaS solution that covers the back-office system-of-record to all front-end web and app interfaces. For instance, with CynoClaim (one of CynoSure’s key modules) more than 60% of all claims can be managed automatically, resulting in lower costs as well as increased customer satisfaction. The platform can be used for both new market offerings and the renovation of established operations migrated to the platform. Results of the first implementations are promising: as much as a 50% decrease in costs and 40% increase in customer satisfaction. CynoSure takes six to nine months to implement, whether it is new or a migration – quite spectacular in the insurance industry, as well. (InShared is powered by OutShared) EagleView Technologies provides aerial imagery, data analytics and geographic information solutions. Thanks to a fleet of 73 aircraft (and drones) that capture images on a year-round basis, EagleView’s library contains more than 250 million images spanning 12 years. This provides the most comprehensive current and historical view of properties available. Insurers use the library, data and visualization tools for instance to identify pre-existing conditions and estimate storm damage to roofs, leading to better decision-making in claims adjusting. In most cases, it is not necessary anymore to visit the site. In addition to these cost reductions, faster closing of claims leads to increased customer satisfaction Enservio software uses demographic and other information to estimate the value of contents in a home. The software is, for instance, used to settle claims. Imagine a house being destroyed by a hurricane. The software allows the insurance company to reduce time-consuming negotiations, to eliminate discussions and to pay the claim three times faster. Lexmark health insurance solutions provide carriers with the tools to expedite claims processing, simplify communications and reduce costs. The solutions extract data from claims forms with an accuracy rate of 90% or more, eliminating most manual data entry and boosting straight-through processing. Specific content management solutions integrate with legacy systems to provide health insurance document management for unstructured content in any form – paper, email, web forms, faxes, print streams and industry-standard formats – giving instant access to for instance claim adjusters. AdviceRobo solutions use a machine-learning platform that combines data from structured and unstructured sources to score and predict risk behavior of consumers. AdviceRobo, for instance, provides insurers with preventive solutions applying big behavioral data and machine learning to generate the best predictions on default, bad debt, prepayments and customer churn. Predictions are actionable because they are on an individual level. Shift Technology leverages data science to detect and model weak and strong signals of fraud, including fraud by organized gangs. Shift Technology has developed algorithms to model data analysis of insurance policies and insurance claims, and external data while integrating the expertise of insurers. To be implemented and configured, the solution requires limited technical or financial investment. The solution is provided in a SaaS model and charged based on the volume of claims processed. The platform is used by general insurance companies as well as other actors in the insurance ecosystem, such as expert networks. Not really insurtech, but too interesting not to include: PartsTrader is an online car parts marketplace that U.S. insurer State Farm is using to dramatically improve the repair process. Repair delays caused by parts ordering issues result in millions of dollars in rental vehicle expenses daily across the industry, and high parts costs are reducing the number of vehicles that can be repaired. Using PartsTrader addresses both problems. The objective is to improve parts availability, quality, order accuracy, competitive pricing and process efficiency. The LexisNexis Intelligence Exchange data platform allows insurers, among others, to review an incoming claim, for instance against claims made with other insurers, resulting in faster settlement of genuine claims and coordinated investigations of suspicious claims. The platform also detects potential insurance fraud; e.g. misrepresentation and non-disclosure of relevant facts, and lapsing of a policy in the second or third year due to, for instance, deliberate churning by an agent. QuanTemplate is a cloud platform to analyze, report and communicate bespoke insurance information between parties. The software is built for the complex, collaborative world of the wholesale reinsurance markets. The users can manage their whole workflow within one app. The platform reduces time and cost spent on reporting and analytics, while increasing speed and transparency. See also: Global Trend Map No. 7: Internet of Things The Internet of Things potentially has a huge impact on claims – by preventing an incident or by warning so that the damage doesn’t get worse. Connected devices provided by companies like Nest deploy sensors and Wi-Fi technologies to detect and report things like a leak under the sink before a pipe burst or to automatically shut off the stove when someone leaves home – so that house owners can handle burning toast before it becomes a burning toaster and insurers can avoid hefty claims later. Liberty Mutual and American Family Insurance already teamed up with Nest to decrease costs. Similar preventive measures are promoted in ever-more-connected cars. VitalHealth Software develops cloud-based eHealth solutions in particular for people with chronic diseases such as diabetes, cancer and Alzheimer’s. The company was founded 10 years ago by, among others, Mayo Clinic. The impact is huge because chronic diseases account for the majority of healthcare costs. VitalHealth Software features include care providers participating and collaborating in health networks, gaining web-based access to shared, protocol-driven disease management support based on established clinical guidelines, seamlessly integrated to and accessed from within existing electronic health records. Clients and partners of VitalHealth Software include top five health insurance carriers in Latam, Europe and China, eager to improve patient care and health costs management simultaneously. All solutions that we featured in this blog have one thing in common: On the one hand, they contribute to significant cost savings, but on the other hand they improve customer engagement. Combining the two should be a leading design principle in digital transformation efforts. Nest, OutShared, Everledger, AdviceRobo and VitalHealth Software are among the insurtechs that will showcase their innovative solutions at DIA Barcelona. In our next post, we will focus on the third flavor of winners in fintech insurance: insurtechs that play new roles in the value chain. So stay tuned! You can find the article originally published here.

Roger Peverelli

Profile picture for user RogerPeverelli

Roger Peverelli

Roger Peverelli is an author, speaker and consultant in digital customer engagement strategies and innovation, and how to work with fintechs and insurtechs for that purpose. He is a partner at consultancy firm VODW.


Reggy De Feniks

Profile picture for user ReggydeFeniks

Reggy De Feniks

Reggy de Feniks is an expert on digital customer engagement strategies and renowned consultant, speaker and author. Feniks co-wrote the worldwide bestseller “Reinventing Financial Services: What Consumers Expect From Future Banks and Insurers.”

Core Transformation Is Not Negotiable

Many insurers still struggle to even provide real omnichannel customer service, or offer timely and transparent claims settlement.

||

Many insurers are focused on how to innovate, but most do not have a stable, cost-efficient core to support and fund their innovation efforts. Both are necessary.

We’ve all read the productivity articles about the world leader who eats the same thing for breakfast, repeats the same 40-minute workout and reads the newspaper in the exact same order. We’ve heard about elite athletes with rigid pre-game routines, down to the music they’ll listen to before the match. The take-home message from this is that you need a stable foundation if you’re going to do amazing things. And in the case of insurers, a stable, efficient core is essential to enabling innovation. A stable core is essential for innovation It’s easy to focus on the shiny, emerging technologies that promise to up-end the insurance industry: artificial intelligence (AI), the Internet of Things (IoT) and blockchain, to name a few. Do these things have far-reaching implications for insurance? Yes. Are there startups leveraging new technologies that may eventually disrupt the industry? Of course. But when many insurers still struggle to provide real omnichannel customer service, or offer timely and transparent claims settlement, it’s almost irresponsible to be asking which company or technology will disrupt insurance. Part of the issue is that the industry tends to clump two distinct opportunities together. First, there are the core competencies that insurers must master: the user experience, personalized offers, timely and transparent claims service. Get these pieces right, and you may not win—but do them poorly, and you will inevitably lose. Separate from this are the new technologies that capture headlines; if scaled successfully, these cool innovations can pave the way to an insurer’s future revenue streams. Brilliant basics and cutting new ground At Accenture, we call these two opportunities the Brilliant Basics and Cutting New Ground. By getting the Brilliant Basics right, insurers foster a stable core—the strong foundation that’s necessary to enable innovation, in the form of Cutting New Ground. By injecting new digital technologies to transform the core, it becomes cheaper and more efficient to do the Brilliant Basics. This approach is aligned with what’s recommended by the Accenture Disruptability Index, which identified insurance as being vulnerable to disruption and recommended optimizing to improve structural productivity. See also: Core Transformation – Start Your Engines!   Successful core transformation can create efficiencies, reduce the cost to serve and improve growth—all of which frees investment capital to fund Cutting New Ground initiatives. These innovation initiatives should be viewed like a portfolio of digital investments. Low-risk, low-reward projects may be more likely to succeed and deliver incremental growth. High-risk, high-reward projects may be less likely to succeed—but if they do, they can enable an insurer to establish a definitive competitive advantage. Given insurance’s risk aversion, it’s definitely a cultural shift to embark on a project knowing it may not succeed, so viewing Cutting New Ground as a portfolio of investments can be one way to mitigate cultural concerns. Consequently, insurers need both pieces. Brilliant Basics can enable a stable core and generate investment capital that make it possible for insurers to focus on Cutting New Ground. Brilliant Basics is the elite athlete’s pre-game routine; Cutting New Ground is the game-winning performance, and maybe a record-breaking one at that. To get started, insurers should consider the following questions:
  • What are your Brilliant Basics and what will it take to deliver them?
  • What are the foundational capabilities required to both deliver those Brilliant Basics and to set up the organization for cutting-edge innovation?
  • What is Cutting New Ground for the industry in general, and your organization in particular?
Transform the core to enable innovation It’s no longer enough to talk about digital channel strategy or digital operating models. We live and work in a digital world, and insurers need an appropriately digital strategy, period. This double-barreled strategy of using Brilliant Basics to become more efficient and create investment capital can enable an insurer to place smart bets with Cutting New Ground initiatives. See also: ‘Core Transformation’ May Not Be Enough Done properly, Brilliant Basics can help insurers better connect with customers. By layering successful innovations on top of it, they can begin to see the stepping stones to becoming a competitive, digitally enabled business.

Michael Costonis

Profile picture for user MichaelCostonis

Michael Costonis

Michael Costonis is Accenture’s global insurance lead. He manages the insurance practice across P&C and life, helping clients chart a course through digital disruption and capitalize on the opportunities of a rapidly changing marketplace.

Cycle Time Is King in Workers' Comp

What is the best way to get injured workers rapidly back on track? Five levers are key to solving the problem.

|
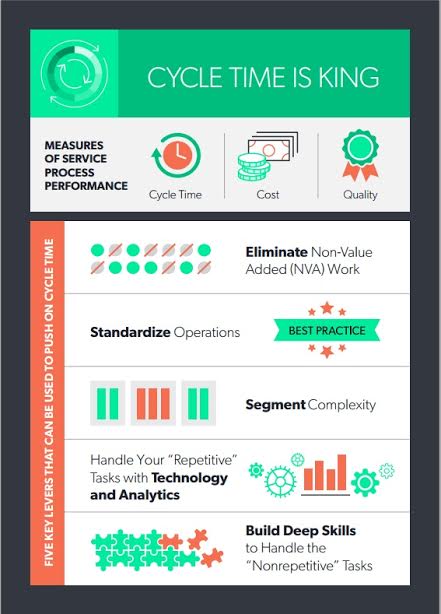
Workers’ compensation is essentially a collection of related actions taken by the employer, payer, provider and injured worker in the service of the injured worker’s recovery and return to work. Putting the injured worker at the center of this activity is critical, as discussed in the previous article in this series, Five Best Practices to Ensure the Injured Worker Comes First. But what is the best way to achieve our objective of getting injured workers rapidly back on track? What processes, tools and systems do we put in place? What problems should we focus on? Critical to answering these questions is a framework that is based on years of handling service operations across a range of industries (airlines, retail banking, healthcare, etc.). Any service process can be measured based on its performance along three dimensions:
  • Cycle time — time to complete one cycle of an operation (e.g., from opening to closing of a claim).
  • Cost — the cost to go through a cycle of the process.
  • Quality — the error rate that occurs as you go through a cycle.
It’s a truism in process improvement that you can improve only one or two of these factors at a time, at the expense of the others. While this is true if we push on cost or quality, pushing on cycle time improves all three metrics. This is an important finding that’s worth restating. If we endeavor solely to reduce cycle time, we can improve all three metrics — cost, quality and cycle time — without sacrifice. To explain why, let’s look at a few examples. Redesign efforts that focus on costs usually aim to increase the productivity of the current team and system. While this helps in reducing unit costs in the short term, it adds more strain on the system overall. The increased strain leads to increased error rates, which in turn leads to increased need for redundancy checking and longer cycle times. Costs start increasing as a result — the exact opposite effect of what we intended. Redesign efforts that focus on reducing error rates typically add additional checks/rechecks in the process, leading to higher costs and longer cycle times. Once the redundancy checks are in place, it is difficult to change anything in the process because there is a fear that quality might suffer. As a result, you are stuck with a slower, costlier process. See also: The State of Workers’ Compensation   Redesign efforts that focus on cycle time reduction push us to take a deeper look at the process. Long cycle times are typically caused by unnecessary delays in the process. In a service operations setting, delays are like inventory in manufacturing. They are in place to buffer any inefficiencies and variabilities in the essential process. Reducing delays requires us to make each step in the process more reliable and more standardized. As we do that, we strip away the layers of unused time in the process. The reduced waste lowers costs and error rates, as there are fewer failure points. The result is reduced cycle time, reduced error rates and reduced costs. In short, if there is one thing you should focus on to improve the injured worker’s experience, it is around making the process go faster for him or her. Respect cycle time, and all else will follow. Here are five key levers that can be used to push on cycle time:
  1. Eliminate non-value-added (NVA) work – Remove work that does not need to be performed and work that is not part of putting the injured worker first.
  2. Standardize operations – Establish best practices for straightforward tasks.
  3. Segment complexity – Break down your steps into “repetitive” and “non-repetitive.” Repetitive tasks are ones that can be accurately and comprehensively laid out in a flowchart. Non-repetitive tasks are ones that address a variety of cases and can’t be clearly laid out in a flowchart.
  4. Handle your “repetitive” tasks with technology and analytics – Automate the repetitive tasks as much as possible. They are not a good use of your team’s time. Build up your technology and analytic capabilities not only to automate these processes but also to alert you in case of exceptions.
  5. Build deep skills to handle the “non-repetitive” tasks – Train your team extensively to handle the complex, non-repetitive tasks (e.g., handling a complex claim heading toward attorney involvement). Use an apprenticeship-based model to train the team handling these tasks. Cross-train select staff so they can go where the need is like a SWAT team, enabling you to reach economies of scale with existing resources.
Workers’ compensation is a complex system with myriad rules and regulations that guide the provision of medical and disability benefits to injured workers. By putting the injured worker first and focusing obsessively on shaving days/minutes/seconds off the process of getting an injured worker back on track, we believe we can make a big dent in reducing the $250 billion-a-year impact of occupational injuries on the U.S. economy. See also: 5 Best Practices on Injured Workers   Read Dr. Gardner’s first article in this series: Five Best Practices to Ensure the Injured Worker Comes First As first published in Claims Journal.

Laura Gardner

Profile picture for user LauraGardner

Laura Gardner

Laura B. Gardner is chief scientist and vice president, products, CLARA analytics. She is an expert in analyzing U.S. health and workers’ compensation data with a focus on predictive modeling, outcomes assessment, design of triage and provider evaluation software applications, program evaluation and health policy research.

Strategies in 2018: The New Balancing Act

Insurers must consider how to incorporate digital transformation, insurtech, emerging technologies and others into their strategies.

Senior executives at insurance companies, like their peers in other industries, are charged with developing and executing the right set of strategies that will lead to success. In years past, strategists at insurance companies have had at their disposal a relatively standard array of strategies to chose from, their job being to prioritize and balance the investments and resources devoted to each. Do we expand our distribution channel network? Put more focus on new products and services? Modernize our foundational policy, billing and claim systems?

These questions and others were the traditional types of questions that executives had to address. Those traditional areas are still important and must be part of the mix for modern insurer strategies. However, a new class of strategic initiatives has emerged that is growing in importance. Now, insurers must consider how to incorporate digital transformation, insurtech, emerging technologies and others into their business and technology strategies.

These “New World” initiatives are poised to reshape the insurance industry, and it is essential that every insurer build them into their plans. A sizable challenge ensues – combining the traditional strategic initiatives with these new world initiatives into just the right blend to make each company successful, today and in the future. This is the new balancing act that executives must tackle – and some may feel like they are teetering on a high wire.

SMA has been tracking the evolution of insurers' strategic initiatives for many years. The changes in these initiatives paint a picture of an industry in transformation and are highlighted in a new SMA e-book, "Strategic Initiatives in Insurance, 2018 and Beyond." The e-book covers the different paths that property/casualty and life/annuity insurers are taking and identifies how companies are prioritizing 12 strategic initiatives (five traditional, six new world and innovation, which spans the old and new).

Several interesting phenomena are occurring. For one thing, more and more executives consider their companies to be in transformation mode, actively trying to redesign and reshape the company for higher growth in the digital age. In addition, both innovation and digital have swept over the industry like a tsunami. About 90% of insurers have significant initiatives for digital transformation and corporate-wide innovation. CEOs feature their digital strategies and investments in their letters to shareholders and earnings calls with Wall Street financial analysts. Chief digital officers are a hot commodity in the industry. Regarding innovation, more insurers are trying to move beyond the early stages to create a broad-based culture of innovation that is sustainable and organic.

One other interesting development is the clear recognition that core systems must be modern to support the demands of a digital, connected world. Modern policy, billing and claim systems are the essential enablers that allow insurers to capitalize on the opportunities for new products, new channel partners, new business models and significant operational improvements.

See also: Strategies to Combat Barriers to Insurtech  

Finally, it is fascinating to observe the industry as it engages with insurtech and emerging technologies. Not that long ago, technologies like mobile and analytics were considered “emerging.” Now they are table stakes and supportive of a new class of technologies like artificial intelligence, drones, the Internet of Things and many more. The insurtech movement has exploded onto the scene, with well over a thousand startups relevant to the industry. The industry is increasingly engaging with insurtechs and exploring emerging tech, with each company prioritizing based on their lines of business and business models. This year – 2018 – is likely to be an exciting one for the industry as the transformation continues. Stay tuned for interesting developments as insurers execute on their strategic initiatives.

Click here for more information on SMA’s recent e-book, Strategic Initiatives in Insurance, 2018 and Beyond.


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.

10 Mistakes Amazon Must Avoid in Health

Most so-called innovation in healthcare is the equivalent of trying to optimize oil lamp technology to get better lighting in homes and cities.

|||
There is something far more interesting about the Amazon, Berkshire and JPMorgan Chase (let’s call them ABC) than the 1 million-plus lives they employ. There have been similar initiatives announced before along with countless business group on health coalitions that have made no meaningful dent in the wildly underperforming status quo healthcare system. The BUCAs (Blues United Cigna Aetna) have been adept at fighting off efforts like these. But this time, I predict it will be different. In this piece, I will explain why past efforts have failed. In a follow-on piece, I’ll explain why the ABC health initiative has great potential to be very unlike past employer-led efforts. Note: I reference my book, which can be found on Amazon or downloaded for free. See also: Open Letter to Bezos, Buffett and Dimon  10 reasons past efforts have led to failure:
  1. No focus on healthcare industry business practices: As my business partner, a securities attorney with various securities licenses, often points out: Practices that are standard in healthcare would land him in jail in financial services. The staggering level of conflicts of interest and lack of disclosure is why the Health Rosetta community crowd-sourced the Plan Sponsor Bill of Rights (“plan sponsor” is a fancy term for employer/healthcare purchaser), Benefits Advisor Code of Conduct and Benefits Advisor Disclosure Form to establish new industry norms. Past efforts didn't seek to change industry norms. As long as these practices persist, there will be little change.
  2. No sustained CEO-level champion: This translates into a lack of organizational backbone. One analysis of a past failed employer-led effort said, “The lack of available data has long prevented employers from figuring out where their biggest expenditures were coming from.” There is no freaking way Amazon CEO Jeff Bezos would accept that. It is a common trope for the BUCAs to say that the claims data they process for self-insured employers (roughly two-thirds of the workforce) is proprietary to the BUCA. That’s laughable on its face, but most employers back down despite the absurdity of that claim. Clearly Bezos and Berkshire CEO Warren Buffett have shown they are long-term-oriented for strategic initiatives.
  3. BUCA fiduciary duty has trumped employer fiduciary duty: As a BUCA executive put it to me, “We (BUCA) are legally required to enable price gouging by hospitals.” I outlined the reasons why in Chapter 3 of my book, What You Don’t Know about the Pressures and Constraints Facing Insurance Executives Costs You Dearly. This dynamic is in direct conflict with employers' fiduciary duty as I outlined in Chapter 19 of my book, where I quoted a Big Four risk management practice leader, “ERISA Fiduciary Risk is the Largest Undisclosed Risk I’ve Seen in my Career.” There are two areas of legal jeopardy that are now snapping CEOs to attention. Chapter 7, Criminal Fraud is Much Bigger Than You Think, is just the tip of the iceberg on ERISA fiduciary risk, but it is so blatant that we’ve heard dozens of cases in the works triggered by the lack of oversight. An additional thread of fiduciary legal front is emerging -- activist shareholders are realizing how straightforward it is to slay the healthcare cost beast and improve earnings. Sadly, for many corporations, the only thing that spurs action is a legal target on their back. There is a simple calculator that translates removal of healthcare waste into market cap impact. Here's one example of something that has already happened: A multinational manufacturer simply implemented one proper musculoskeletal management program by having physical therapists working with employees and workplace ergonomics. This is translating into $2 billion of market cap impact (calculate savings times price-earnings multiple). One of the foremost experts in employer benefits, Brian Klepper, estimates that 2% of the entire U.S. economy is tied up in non-evidence-based, non-value-add musculoskeletal procedures. [See Chapter 12, Centers of Excellence a Golden Opportunity, for more]
  4. Coalitions co-opted: Too many business coalitions on health are supported by limited funding from employers, so they seek sponsorship from the very players whose business imperative is to redistribute money from employers to the healthcare industry incumbents. The people running these coalitions typically walk on eggshells trying to avoid offending their sponsors, and nothing substantive changes. Some have meaningful revenue streams from incumbents that largely perpetuate the status quo at a slightly better price.
  5. Threats of business reprisal: I’ve heard of many instances where a BUCA threatens an employer's revenue. BUCAs book lots of hotel rooms, buy lots of computer hardware, etc. Any effort to rein the BUCA in is fought furiously. Often the CEO of the employer isn’t even aware that it has happened. The risk-averse HR/benefits leader simply backs down out of fear there will be internal blowback for jeopardizing revenue, and the dysfunction persists. The message that CEOs implicitly or explicitly send to HR/benefits leaders is, “Keep our people happy and don’t get us sued.” In other words, a guarantee of risk aversion.
  6. Employer groups keep their “deals” proprietary: Classic short-term thinking. The employer may gain some short-term advantage and can claim a “win,” but the overall market they operate in remains unchanged. It is a key part of BUCAs’ divide-and-conquer strategy. Even a huge employer normally has a small usage share in a given market, so their impact is muted when the BUCA holds their deal terms proprietary rather than establish new market norms available to all employers.
  7. Lack of rethinking of healthcare payment and delivery: Most so-called innovation in healthcare is the equivalent of trying to optimize oil lamp technology to get better lighting in homes and cities. Or, putting recycling bins in a coal plant and calling it "green energy." The healthcare system has become a Gordian Knot designed by Rube Goldberg built up over the last 100 years. Those of us working on the Health Rosetta blueprint and Health 3.0 vision recognize that it is time for a reset. That approach has allowed smart employers to spend 20% to 40% less per capita with superior benefits and outcomes.
  8. Primary care ignored: As I pointed out in the open letter mentioned above, you can’t have a functioning healthcare system without proper primary care. Primary care has been brutally undermined. To the extent there has been focus on primary care, it has been to pile some niceties on top of a fundamentally flawed model. As one primary care innovator put it, putting wings on a car doesn’t make it an airplane. Having written the seminal paper (summary, detailed) on direct primary care (DPC) five years ago, I find it striking how few benefits professionals have heard of DPC, let alone adopted it. Value-based primary care couldn't be more different than the drive-by, hamster wheel primary care that has become the dysfunctional norm.
  9. Lack of supply chain mindset: Most employer-led efforts have not rolled up their sleeves because they are working on the mistaken assumption that healthcare is too complicated to tackle themselves. That is only true if you do not apply the proper resources. As a single company, Caterpillar applied a supply chain mindset (something Amazon has in spades) to their drug spending and fired middlemen who were not adding value. Seemingly every company says employees are their most important asset. Considering that health benefits are typically the second biggest cost after payroll, why wouldn’t a company want to ensure they get the greatest payback by carefully managing their healthcare supply chain? In Chapter 9, You Run a Health Care Business Whether You Like it or Not, I detailed how IBM’s mindset shift had the dual benefit of lower healthcare costs and a high-performance workforce.
  10. Lack of moral standing: Past employer efforts have not articulated a compelling reason that clearly benefits the best interests of the public and their employees. Rather, past initiatives were easy to perceive as antiseptic corporate blather meant to enhance their bottom line. Thus, it is easy to position the employer as the bad guy. For example, as I pointed out in my open letter to Bezos, Buffett and JP Morgan CEO Jamie Dimon, employers are the key enabler of the opioid crisis. Thus, it can’t be fixed without a major shift by employers (see Chapter 20, The Opioid Crisis: Employers Have the Antidote). Facing the largest public health crisis in 100 years, there is a moral imperative to address this situation. Taking leadership on this issue solves an internal issue (no doubt, ABC employees are afflicted with opioid overuse disorders at the same rate as the general public) while tackling a much broader societal issue.
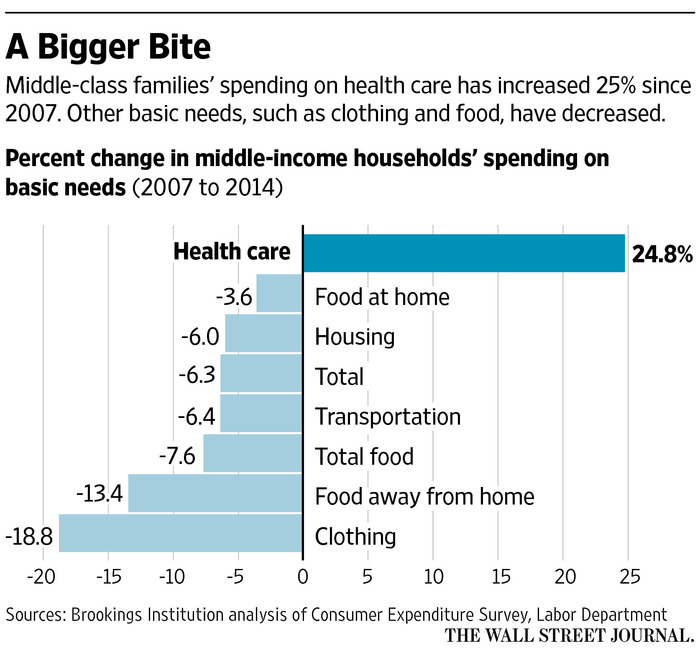
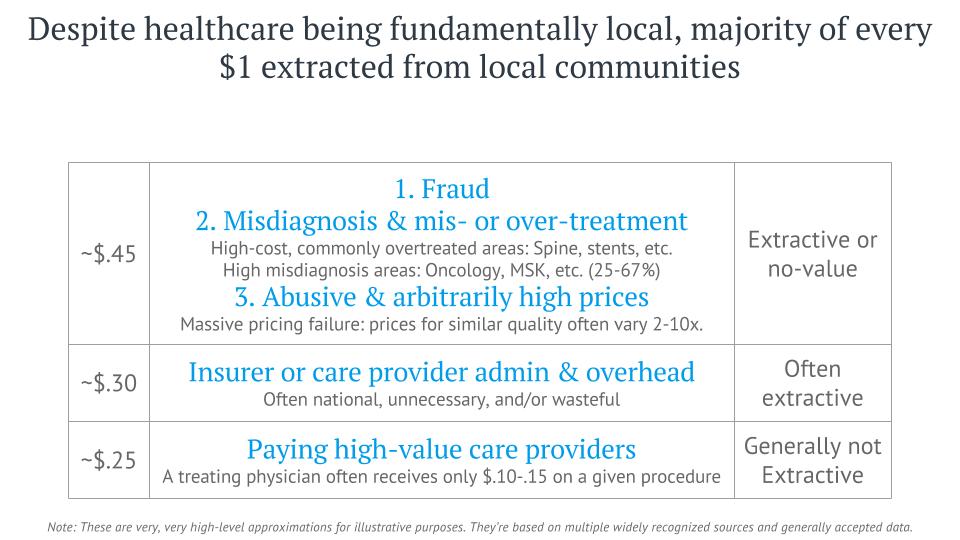
In all of the case studies in my book, the employers treated their employees like adults and explained what was going on at a macro (see the "bigger bite" graph) and micro level to explain how they wanted to ensure their teams could achieve the American Dream. Successful employers point out that healthcare is blocking the American Dream for 60% of the workforce. The math simply doesn’t work: 60% of the workforce makes less than $20 per hour, and the average family of four premiums are $26,000; in addition, greater than 50% of households have less than $1,000 in savings (largely due to healthcare costs), and more than 50% of the workforce has over a $1,000 deductible. See also: Whiff of Market-Based Healthcare Change?   It’s no wonder that Buffett called healthcare the tapeworm on the U.S. economy. The handwriting was on the wall following the Michigan primary that showed that populism was being driven, overwhelmingly, by healthcare’s hyperinflation as was pointed out in Healthcare Drives Middle Class Economic Depression & Trump/Sanders Campaign Success. In the follow-on piece, I’ll outline how the ABC health initiative has the potential to have as big an impact on U.S. healthcare as the Affordable Care Act. I leave you with a quote and a slide from a presentation I gave recently that will give a preview of the opportunities available for this new initiative. Note how little of every dollar goes to the value creators in healthcare.
"Your margin is my opportunity.” - Jeff Bezos

Dave Chase

Profile picture for user DaveChase

Dave Chase

Dave has a unique blend of HealthIT and consumer Internet leadership experience that is well suited to the bridging the gap between Health IT systems and individuals receiving care. Besides his role as CEO of Avado, he is a regular contributor to Reuters, TechCrunch, Forbes, Huffington Post, Washington Post, KevinMD and others.

The Race to Quantum Computers

As progress in the field accelerates at an exponential rate, 2018 should see an avalanche of breakthroughs toward “quantum supremacy.”

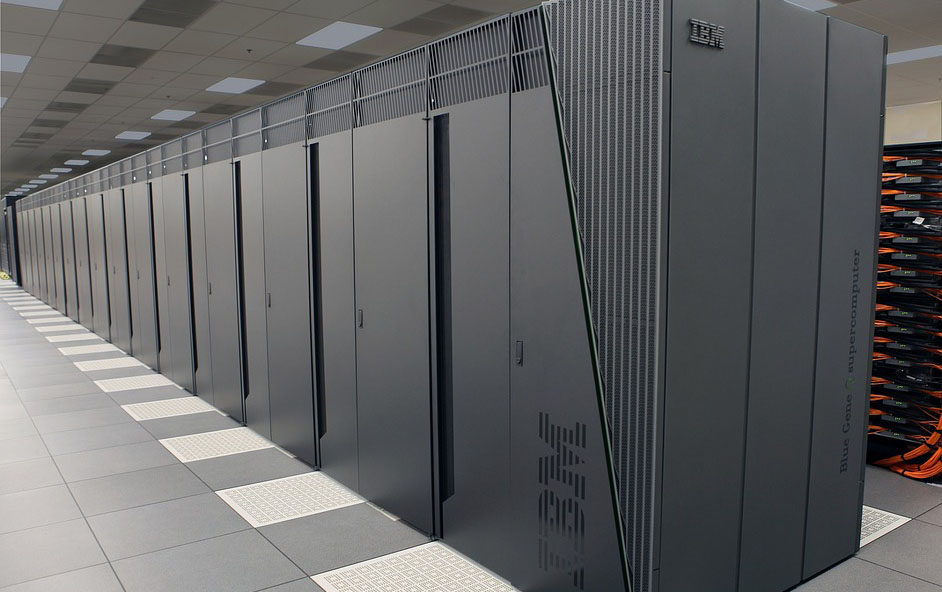
While much of the media attention has been focused on the race among nations to develop the most powerful artificial intelligence systems, an equally crucial race has been heating up: the race to build the first working quantum computers. As progress in the field accelerates at an exponential rate, 2018 should see an avalanche of breakthroughs. It is a race for “quantum supremacy,” when a quantum computer demonstrably and markedly outperforms a classical supercomputer for any class of problems. Booth Google and IBM, two leaders in quantum computing, have laid out plans to achieve this goal. Intel  also has a horse in the race, announcing a new 49 qubit neuromorphic chip designed for quantum computing research. See also: Digital Transformation: How the CEO Thinks   The stakes are enormous. Quantum computers promise to set a new paradigm for solving some of the hardest math and computing problems today—problems such as analyzing the interactions of multiple genes in health outcomes, modeling the energy states of chemicals and predicting the behavior of atomic particles. They also might make the internet inherently insecure by quickly cracking modern cryptography used to lock our IT infrastructure and the web. One thing is for sure: The era of quantum computing is coming on soon, and the world will never be the same. Put simply, quantum computers use a unit of computing called a qubit. While regular semiconductors represent information as a series of 1s and 0s, qubits exhibit quantum properties and can compute as both a 1 and a 0 simultaneously. That means two qubits could represent the sequence 1-0, 1-1, 0-1, 0-0 at the same moment in time. This compute power increases exponentially with each qubit. A quantum computer with as few as 50 qubits could, in theory, pack more computing power than the most powerful supercomputers on earth today. This comes at a timely juncture. Moore’s Law dictated that computing power per unit would double every 18 months while the price per computing unit would drop by half. While Moore’s Law has largely held true, the amount of money required to squeeze out these improvements is now significantly greater than it was. In other words, semiconductor companies and researchers must spend more and more money in R&D to achieve each jump in speed. Quantum computing, on the other hand, is in rapid ascent. One company, D-Wave Systems, is selling a quantum computer that it says has 2,000 qubits. However, D-Wave computers are controversial. While some researchers have found good uses for D-Wave machines, these quantum computers have not beaten classical computers and are only useful for certain classes of problems—optimization problems. Optimization problems involve finding the best possible solution from all feasible solutions. So, for example, complex simulation problems with multiple viable outcomes may not be as easily addressable with a D-Wave machine. The way D-Wave performs quantum computing, as well, is not considered to be the most promising for building a true supercomputer-killer. Google, IBM and a number of startups are working on quantum computers that promise to be more flexible and likely more powerful because they will work on a wider variety of problems. A few years ago, these flexible machines of two or four qubits were the norm. During the past year, company after company has announced more powerful quantum computers. In November 2017, IBM announced that it has built such a quantum machine that uses 50 qubits, breaking the critical barrier beyond which scientists believe quantum computers will shoot past traditional supercomputers. The downside? The IBM machine can only maintain a quantum computing state for 90 microseconds at a time. This instability, in fact, is the general bane of quantum computing. The machines must be super-cooled to work, and a separate set of calculations must be run to correct for errors in calculations due to the general instability of these early systems. That said, scientists are making rapid improvements to the instability problem and hope to have a working quantum computer running at room temperature within five years. And here’s where the confluence of quantum computing and AI looks so promising. As we are seeing the first major impacts of wide-scale artificial intelligence, we are also realizing that classic semiconductor-based computing limits our ability to solve the biggest problems that we had hoped artificial intelligence could tackle. They expect quantum computers to start performing very useful calculations well before they’re ready to leave the freezer. See also: 7 Steps for Inventing the Future   Quantum computing promises to step into that breach and provide the rocket fuel needed to solve these grand challenges. Precisely targeted medical treatments, radically cheaper energy production and new types of super-strong materials are all breakthroughs that quantum computing could make possible by performing billions and billions of calculations simultaneously in a relatively small package. Google researchers demonstrated the promise when they used quantum computing to simulate the electron structure of a hydrogen molecule, a key step toward moving chemical design from empirical measurement and educated guesses to more proper engineering and simulation. (This will also work for drug discovery.) The perils of quantum computing are also real. Quantum computers will be able to easily crack most forms of encryption in use today (although security experts are already at work on creating codes that are not crackable by qubit attack). Should Russia or China, for example, gain quantum computing dominance—which is entirely possible—they could use their advantage for even more sophisticated hacking and decrypting of encoded communications. Between governments, big companies, startups and university labs, some of the brightest engineering minds are rushing toward quantum supremacy. This literally could shift the global balance of power. This article was written by Vivek Wadhwa and Alex Salkever.

Vivek Wadhwa

Profile picture for user VivekWadhwa

Vivek Wadhwa

Vivek Wadhwa is a fellow at Arthur and Toni Rembe Rock Center for Corporate Governance, Stanford University; director of research at the Center for Entrepreneurship and Research Commercialization at the Pratt School of Engineering, Duke University; and distinguished fellow at Singularity University.

How Not to Transform P&C Core Systems

Many projects fail to fully realize their potential benefits due to three oversights.

The insurance industry continues to invest heavily in transforming their legacy policy, billing and claims applications. But are carriers actually realizing what was promised to the business? Core transformation can be so much more than a legacy technology replacement. In our experience, many projects fail to fully realize their potential benefits due to three common oversights:
  • Digitization without differentiation – Projects that simply upgrade their core systems but fail to change the customer engagement.
  • Limited focus on information data – Too much focus on transactional data elements and not using a comprehensive informational data approach.
  • Failure to foster innovation – Modernizing applications but failing to leverage these tools to support continuous improvement and innovation.
In fact, 67% of insurance respondents to PwC’s 2017 CEO survey see digitalization and innovation as very important to their organizations. Specific to the insurance industry, CEOs noted that the area they would most like to strengthen to capitalize on growth opportunities is digital and technological capabilities, followed by customer experience (reflecting the connections between the two). Insurers are looking for more than just modernization of core systems. They expect a successful digital, analytics and organizational transformation that can enable them to unlock the full potential that a core transformation has provided to them. Carriers should be asking themselves the following questions to determine if they’re achieving the full benefits of expanding beyond core. Is the organization:
  • Leveraging the new platform to change the customer engagement model?
  • Leveraging analytics-based insights with a clear vision and plan to translate that into value based capabilities?
  • Promoting continuing innovation – both internally and to customers?
Key opportunities beyond core
  • Digital differentiation: Putting the customer at the center of the business is a driving success factor for any core transformation effort. With the maturation of customer portals and digital platforms, insurers can now focus on customizing the digital layer while retaining the back-end core systems as out of the box as possible.
  • Data and analytics: As the volume of data has grown, insurers have implemented new big data technologies and reporting structures. The challenge remains to translate data into insight, and we have seen an emerging trend of establishing a chief digital officer and corresponding analytics business units that can span across the various data silos and business units.
  • Innovation: Within the context of innovation, a significant majority of carriers dedicate 1% to 5% of their IT budgets to research and development (R&D). We believe carriers should pursue a two-pronged approach to innovation that leverages both internally generated innovation as well as strategic partnering with emerging insurtech companies.
  • Insurtech: Carriers should think beyond their internal businesses to identify and collaborate with an increasingly robust insurtech community of startups. This will allow carriers to implement innovative technologies through a combination of partnering strategies.
See also: Insurtech in P&C: It’s Not About the Tech   Digital differentiation We have seen a significant maturation of portal and digital platform offerings in the market in the past two years. This shifts the balance for carriers that now have the ability to leverage commercially available offerings that previously required custom builds in-house or through extension of the core policy, billing and claims products. What this means for carriers is that digital strategy can now complement the core transformation journey. Carriers are now pursuing a “digital first” strategy that places the customer value proposition first when prioritizing project work. In this model, the core application’s UI / UX is kept nearly out of the box, with the focus of UI / UX customization performed on the digital layer. We believe this approach results in the best of both worlds, resulting in a highly conforming set of core systems and a carrier-unique digital experience delivered through the custom digital layer. To achieve these goals, projects should:
  • Leverage commercially available digital products as the foundation for your digital layer;
  • Implement APIs between the back-end core applications and the digital layer;
  • Leverage the enterprise digital layer for all external-facing interactions, including intermediaries and customers.
Insurers are placing greater emphasis on their digital offerings as a key customer differentiator, shifting customization from the core applications to the digital layer. Data and analytics Big data implementations have hit a critical mass, with nearly all carriers either pursuing a data lake-style implementation or planning one. Carriers that have implemented big data implementations have benefited from faster enterprise-level deployments, but at a cost of retraining the data and analytics business units. In some cases, these projects have shifted the reporting development to the respective business units, which must up-skill to support this previously IT-led work. We have also observed a growing trend of the chief digital officer (CDO) and the creation of a specific analytics business unit within organizations. This reflects the belief that data is no longer the domain of individual siloed business units, and carriers must now use data cross-business to achieve true customer insights. Finally, carriers are now looking at new monetization opportunities as a result of their data stewardship. For example, one international carrier is now investigating how to monetize their supply chain data for automobile repair networks. Other possibilities include data provider relationships with original equipment manufacturers and even competitors who may use the carrier’s repair cost history to better price risks in the local market. Trends in data and analytics include the introduction of new big data tools and techniques, new business units to leverage data across the enterprise and a renewed focus on monetization of insurers' data. Innovation We make a distinction between “invention,” which represents the creation of a capability versus “innovation,” which is the application of that invention to the marketplace. For insurers, invention is rare and generally coincides with a change to both the technology and regulatory landscape (e.g., credit scoring). Insurers should focus on innovation and how to leverage emerging technologies and evolving customer expectations into your business. Insurers that lead in innovation exhibit the following traits:
  • A mechanism to capture innovative ideas across the enterprise (e.g. innovation workshops, targeted interviews from front-line employees, etc.);
  • A project funding and prioritization structure that links new ideas to internal capital budgeting and executive priorities;
  • A willingness to fail early and often. For example, Google X (Google’s innovation arm) gives employees incentives to end a project early if it makes sense to do so.
The good news is an emerging insurtech ecosystem is growing, which allows insurers access to a pool of experimental projects and partners. Insurers should look to implement a two-pronged innovation model that includes internally derived innovation as well as a partnership model with leading insurtech vendors. Insurtech The exponential growth of insurtech funding and company formation reflects the belief that the insurance space is ready for transformation. Because the insurtech ecosystem is still evolving, it will remain unclear who will ultimately become leaders within the space. As a result, insurers should look to a combination of partnering models to hedge against an uncertain future. Some models we have observed include:
  • Joint venture – The insurer and insurtech company form an exclusive joint venture. The insurer provides seed capital and is able to influence the insurtech more greatly than in other models.
  • Strategic partnership – The insurer takes a leadership role in partnering with the insurtech, usually at favorable economic terms with the goal of growing the partnership over a longer period.
  • Acquisition – The insurer makes a strategic acquisition. This is a less common model due to the capital required and concern about the effect a merger may have on the acquired company
  • Service provider – The insurtech is considered a provider and works on a pre-defined contract term. This model may be pursued for smaller proofs-of-concept or for new products the insurer is experimenting with
Regardless of the partnering model, we have seen both life and P&C carriers successfully work with emerging insurtech companies to roll out innovative products and features. In the life space, the use of health-tracker-style devices, apps and policy discounts have helped move insurers to a health-monitoring and lifestyle adviser. See also: P&C: Back-End Systems Unite!   Insurers should look to leverage insurtech opportunities to continue to broaden their customer value proposition, both through increased customer touch points and risk management features. Implications
  • Digital experiences, not the back-end core application, are the true customer differentiator. As a result, insurers should look to establish a customizable digital platform that interacts with a nearly out-of-the-box set of back-end core applications.
  • Data and analytics will both increase in volume and frequency, requiring carriers to look across individual business units and data silos to form truly actionable customer insights.
  • Innovation will originate internally within the company, but also from an emerging insurtech ecosystem of companies.
  • Insurtech is still evolving ,and picking winners will be difficult. Insurers should look to a combination of partnering models to ensure the best trade-off of engagement and risk.

Scott Busse

Profile picture for user ScottBusse

Scott Busse

Scott Busse is a director at PwC Advisory in the insurance practice. He has over 13 years of consulting experience helping clients undergo change and realize value through the strategic use of technology and information.


Imran Ilyas

Profile picture for user ImranIlyas

Imran Ilyas

Imran Ilyas is a partner with PwC’s insurance practice, combining 20 years of industry and management consulting experience, primarily in the P&C insurance industry for global, national and regional carriers. He co-leads PwC's policy admin practice.