3 Ways to an Easier Digital Transformation
Being methodical, teams can achieve a hybrid IT cloud infrastructure that allows for improved operations at manageable costs.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Richard Dresden leads a team of sales, consulting, channel and solution architecture professionals who partner with Ensono clients on their IT transformation needs.
Executives who can reframe metrics will energize employees and increase their organizations’ innovation effectiveness.
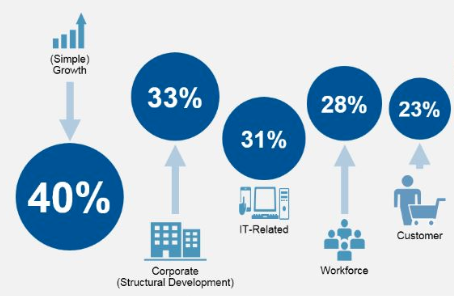
Responders are taking some measure of credit for moving their organizations ahead of competitors in the race for growth and relevance. The Gartner survey findings further reveal that the priorities ranked two through five – including new partnerships and M&A (part of corporate development), new technologies, workforce capabilities and the customer – all presumably enable the No. 1 priority on the C-suite list, which is, no surprise, growth.
Add to the priority to-dos an additional leverage point that may be too buried to get well-deserved attention: to develop innovation metrics that monitor and accelerate the conversion of insights and ideas to sources of value for all stakeholders.
Neither attempts at defining surgically precise metrics nor peering into one’s crystal ball will lead to helpful innovation metrics.
Using legacy performance measures to assess concepts that may have little resemblance to established products and services, or treating innovation as an immeasurable, both turn out to undermine potential opportunities. Only the C-suite is empowered to assign new metrics that can nurture these investments and judge them appropriately, and that may not conform to the standards the entire organization has been taught are right. Choices should have rigor, be reasonable for the evaluation of potentially unprecedented products and services, and be able to hold their own even in zero-sum resource allocation processes.
See also: Innovation — or Just Innovative Thinking?
Early in my career, an executive gave me valuable advice, more recently reinforced in conversations with corporate leaders, startup founders and investors as I undertook the research for my book, The Change Maker’s Playbook. Back then, my team and I were seeking seed funding for a new concept. In a presentation to this particular executive, we shared copious financial analyses, including five years’ worth of P&Ls carried out to the penny. He waved aside our spreadsheets and told us, “Don’t seek a level of precision that cannot be possible when you are looking at something so new.”
Growth opportunities are put at risk when overly precise and backward-looking metrics, from old business models, are applied to gauge potential impact and measure their worthiness to be moved forward.
Instead, executive teams can adopt common-sense approaches to ensure discipline – the right kind of discipline — for evaluating emerging business models.
For an early-stage, new-to-market concept, what is most important is to ask the right questions, rely on judgment where facts simply do not exist, seek metaphors from other sectors or markets and accept good enough data that can be refined along the way. Smart questions answered in fast test-and-learn cycles can lead to relevant metrics and keep innovation projects moving closer to success or the set-aside file.
Here are five suggested questions to find the right metrics for your innovation initiatives:
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Amy Radin is a strategic advisor, keynote speaker, and Columbia University lecturer focused on why transformation succeeds or stalls in large, complex organizations.
Drawing on senior leadership roles at Citi, American Express, and AXA, including one of the world’s first corporate chief innovation officer roles, she helps leaders build the capabilities required to absorb, scale, and sustain change.
Learn more at amyradin.com.
85% of corporate strategists say innovation is critical for their organizations. Yet the vast majority are focused on incremental changes.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Marty Agather is a proven thought leader and accomplished writer and speaker on insurance innovation. He blogs frequently on insurance topics. In addition, Agather speaks at insurance industry conferences and events on varied topics.
Used separately, e-signature and document management systems are ineffective. But their interplay makes dealing with regulatory changes simple.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Jesse Wood is the CEO of document management software vendor, eFileCabinet.
Anyone who thinks innovation is about an "aha" idea, the best partners or great talent should take a look at this article on the history of General Magic.
It had the best idea, essentially designing an iPhone 6 in the early 1990s. It had the best partners: Founded by Apple, the company had all the major telecommunications companies as investors, from AT&T on down. The talent was off the charts. General Magic was run by the stars of the original Macintosh team and included others who went on to develop the iPod, iPhone and the Android and, as if that weren't enough, to found Nest and even eBay.
Yet the company sold only 3,000 units to what executives acknowledged were friends and family and burned a $100 million hole in the ground.
Students of Silicon Valley history will note that this epic bust occurred during the interregnum at Apple, after Steve Jobs was forced out in 1985 and before he returned in 1997. But the genius theory of innovation doesn't explain the problems at General Magic, either. In fact, the problem was that there were too many geniuses at the company.
Guy Fraker, our chief innovation officer, says people often think that innovation means thinking outside the box. In fact, he says, innovation efforts need a box, to focus people on the right customer need, the right technologies, the right costs and so on. The trick is to frame the box the best way possible.
"A disparate innovation collection lacking a clear mandate, shared focus and unifying goals," Guy says, "results in a more chaotic, minimally effective launch and problems with scaling."
And the General Magic effort was as disparate a collection as could be. At a time when WiFi didn't exist, when the Internet was still in its formative stages, when few people were even using email -- and were using faxes that had to somehow be integrated with the mobile phone being designed -- General Magic was trying to do everything at once.
There was no box in sight. In fact, many of the later innovations by team members at General Magic occurred because someone put a box around a particular problem and solved it. The iPod, for instance, occurred because Jobs wondered whether he could put 1,000 songs in someone's pocket.
I still love the General Magic name. It drew on the Arthur C. Clarke quote that "any sufficiently advanced technology is indistinguishable from magic," combined with the belief that in the tradition of General Electric and General Motors there was now room for a General Magic.
But it's a harrowing example of how not to innovate.
Cheers,
Paul Carroll
Editor-in-Chief
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Paul Carroll is the editor-in-chief of Insurance Thought Leadership.
He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.
Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.
The more informed employees are, the wiser they’ll be when it comes to making the right lifestyle and healthcare choices.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Al Lewis, widely credited with having invented disease management, is co-founder and CEO of Quizzify, the leading employee health literacy vendor. He was founding president of the Care Continuum Alliance and is president of the Disease Management Purchasing Consortium.
Companies that excel at customer experience recognize that they’re in the business of shaping memories, not just experiences.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Jon Picoult is the founder of Watermark Consulting, a customer experience advisory firm specializing in the financial services industry. Picoult has worked with thousands of executives, helping some of the world's foremost brands capitalize on the power of loyalty -- both in the marketplace and in the workplace.
A customized model that is fit-for-purpose one day can soon become obsolete if not updated for changing business practices and real-world data.
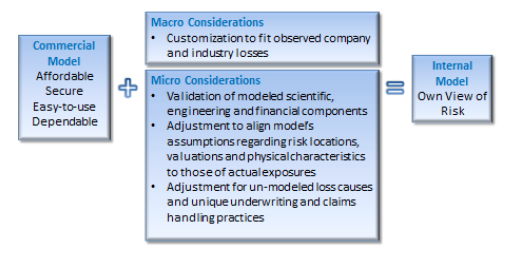
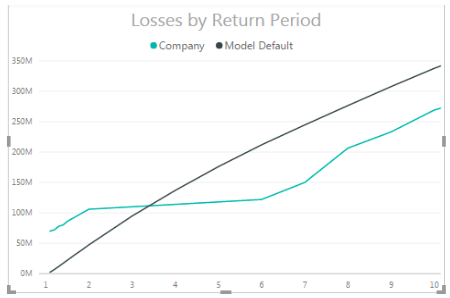
To the extent resources allow, (re)insurers should analyze several macro- and micro-level considerations when evaluating the merits of a given platform. On the macro level, unless a company’s underwriting and claims data dominated the vendor’s development methodology, customization is almost always desirable, especially at the bottom of the loss curve where there is more claim data; if a large insurer with robust exposure and claims data is heavily involved in the vendor’s product development, the model’s vulnerability assumptions and loss payout and developments patterns will likely mirror that of the company itself, so less customization is necessary. Either way, users should validate modeled losses against historical claims from both their own company and industry perspectives, taking care to adjust for inflation, exposure changes or non-modeled perils, to confirm the reasonability of return periods in portfolio and industry occurrence and aggregate exceedance-probability curves. Without this important step, insurers may find their modeled loss curves differ materially from observed historical results, as illustrated below.
A micro-level review of model assumptions and shortcomings can further narrow the odds of a “shock” loss. As such, it is critical to precisely identify risks’ physical locations and characteristics, as loss estimates may vary widely within a short distance - especially for flood, where elevation is an important factor. When a model’s geocoding engine or a national address database cannot assign location, there are several disaggregation methodologies available, but each produces different loss estimates. European companies will need to be particularly careful regarding data quality and integrity as the new General Data Protection Regulation, which may mean less specific location data is collected, takes effect.
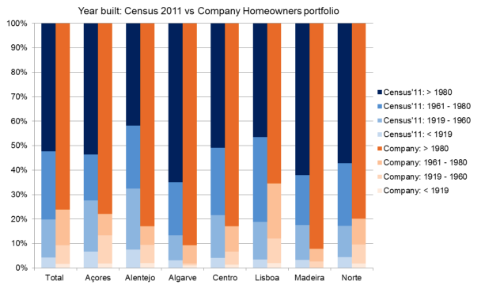
Equally as important as location is a risk’s physical characteristics, as a model will estimate a range of possibilities without this information. If the assumption regarding year of construction, for example, differs materially from the insurer’s actual distribution, modeled losses for risks with unknown construction years may be under- or overestimated. The exhibit below illustrates the difference between an insurer’s actual data and a model’s assumed year of construction distribution based on regional census data in Portugal. In this case, the model assumes an older distribution than the actual data shows, so losses on risks with unknown construction years may be overstated.
There is also no database of agreed property, contents or business interruption valuations, so if a model’s assumed valuations are under- or overstated, the damage function may be inflated or diminished to balance to historical industry losses.
See also: How to Vastly Improve Catastrophe Modeling
Finally, companies must also adjust “off-the-shelf” models for missing components. Examples include overlooked exposures like a detached garage; new underwriting guidelines, policy wordings or regulations; or the treatment of sub-perils, such as a tsunami resulting from an earthquake. Loss adjustment difficulties are also not always adequately addressed in models. Loss leakage – such as when adjusters cannot separate covered wind loss from excluded storm surge loss – can inflate results, and complex events can drive higher labor and material costs or unusual delays. Users must also consider the cascading impact of failed risk mitigation measures, such as the malfunction of cooling generators in the Fukushima nuclear power plant after the Tohoku earthquake.
If an insurer performs regular, macro-level analyses of its model, validating estimated losses against historical experience and new views of risk, while also supplementing missing or inadequate micro-level components appropriately, it can construct a more resilient modeling strategy that minimizes the possibility of model failure and maximizes opportunities for profitable growth.
The views expressed herein are solely those of the author and do not reflect the views of Guy Carpenter & Company, LLC, its officers, managers, or employees.
You can find the article originally published on Brink.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Imelda Powers has advised worldwide (re)insurers on catastrophe exposure management for more than 20 years. Her works include model development, statistical simulation and insurance-linked securities.
Agents who give personalized advice and advocacy when needed represent the great upside and the future of the agency channel.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Sam Fleming is vice president of product marketing with Imprezzio. A true visionary and leader, Fleming’s enthusiasm and passion for discovering new applications of technology fuels a creativity that translates to incredible business solutions.
A core system that was top of the line in 2013 may be showing its age. Systems now need to be “digitally native."
Insurers, I have some good news and some bad news. Insurers have made tremendous progress in core modernization, purchasing and implementing new core systems and beginning to adapt their businesses to take full advantage of modern core systems’ capabilities. This is genuine cause for celebration – insurers that have made or are making these efforts are advancing their companies and our industry in general.
As insurers were engaged in these core modernization efforts, though, the personal lines market and technology itself have kept moving forward. A core system that was top of the line in 2013 may be showing its age unless it has been continually upgraded to serve the capabilities needed in 2018 and beyond. This may not be the most welcome news for those still thinking about core systems with an average lifespan of 10 years or more, but this is our new reality.
This is especially true for personal lines insurers, which are typically the first to catch the core modernization wave. They have also tended to be the leaders regarding new computing capabilities. It was true for mainframe systems, client servers, web-based applications. Now, heading into the new era of computing, it is true with computing trends like microservices and serverless computing coming to the fore. This is not technology for technology’s sake – insurers need to be able to handle an increasing number of transactions, including multi-threaded calls, and that increase is approaching an infinite number.
See also: 2018’s Top Projects in Personal LinesFurther pressure comes from the insurtech startups active in the personal lines market. The original, widely known insurtech startups in P&C insurance were focused on personal lines. As the insurtech movement has matured, startups’ focus has widened to commercial lines and workers’ comp as well as crossing product lines. However, startups have been active in personal lines the longest, and those insurtechs that have thrived have gained market experience and are beginning to focus on organizational maturity. That means that for incumbent personal lines insurers, their insurtech counterparts tend to be comparatively robust and mature when compared with the commercial lines insurtechs I discussed in my earlier blog.
A key characteristic of insurtechs is that they are digitally native companies. That means that they are natively fluent, with enormous quantities of data and digital interactions, and their technology is geared toward this.
Core systems that can be described as “digitally native” have an edge in the digital market going into the future. Even though digital has been a crucial focus area for years, the insurance industry is still learning what a truly digital business entails – and what technology is needed to support it. Insurtech startups have given the insurance industry new examples of how to operate in the digital world.
Few core systems are built with the digitally native characteristics, but the core systems marketplace is beginning to adapt. Continued evolution toward open APIs and new data sources will provide insurers with the opportunity to interoperate with the new distribution channels and directly with the customer.
Whether you are a large insurer that is trying to support new digital brands and new product models (on-demand, telematics and others dependent on high amounts of data) or a small regional insurer trying to power consumer service portals, the key question is data availability and digital connectivity with the consumer and agent.
So, for insurers asking themselves: “Do we really need to think about modernizing our modern core systems?” the better question may be this: “Are your modern core systems digitally native?”
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Karen Furtado, a partner at SMA, is a recognized industry expert in the core systems space. Given her exceptional knowledge of policy administration, rating, billing and claims, insurers seek her unparalleled knowledge in mapping solutions to business requirements and IT needs.