Download

Meeting Members Where They are: Why Farm Bureaus are Embracing Frictionless Billing and Payments

Farm Bureaus advocate for farmers and offer modern digital payment options through partnerships like InvoiceCloud's with Georgia Farm Bureau Insurance.

farmer

Farm Bureaus are so much more than insurers – they’re considered the voice of farmers and ranchers nationwide. Between advocacy at federal and local levels, educational programs, and the general empowerment of farming families, Farm Bureaus are actively building a sustainable future of safe and abundant food, fiber, and renewable fuel for our nation and the world. 

At the center of every Farm Bureaus’ mission are its members, those who have dedicated their lives to farming and ranching. In its simplest form, the aim of Farm Bureaus is to meet its members where they are today and empower them to keep running day-to-day operations while focusing on the future. 

One operational piece that’s critical for both members and Farm Bureaus is paying (or collecting) insurance premiums. And in a world where the modern consumer can make one-click purchases on Amazon or easily pay other bills online, outdated or manual payment processes can be a major source of frustration for your members.

By offering easy paths to self-service, Farm Bureaus can cater to both traditional preferences and the more modern preferences of next-generation farmers coming up today. This begins by providing a seamless customer experience where it matters most.

What do members want out of their payment experience? 

To help billers stay aligned with customer payment preferences, InvoiceCloud conducts an annual survey of ~2,100 bill payers nationwide to determine the current state of online payments. Data from our most recent survey (available for download December 2022) indicates several overarching trends that should give you a sense of the payment experience your members are expecting: 

  1. Digital: In general, digital insurance payments have increased across the board since 2020. Mobile and online portals were the two most popular and preferred payment channels, but mobile took the top spot as the most used and most preferred for the first time. 
  2. Convenient: The #1 word selected when respondents were asked how they would “describe their ideal payment experience.”  
  3. Automatic: There’s been a 5% spike in automatic payment enrollment since last year, especially among folks aged 60 and older. 

All of these descriptors apply to the needs of farmers – they required quick, easy ways to get their Farm Bureau premiums paid every cycle, so they can spend more time on the countless other daily operations that should be taking precedence. Even from the Farm Bureau perspective, leveraging an online payment portal streamlines manual tasks and offers bureau employees more time to focus on critical member issues and needs. 

So, what would your member’s ideal digital payment experience actually look like? Here are a few examples of how to identify a truly frictionless payment experience: 

  • One-time payments: This frictionless payment options allow members to pay quickly with only their member number, policy number, or account number – no passwords needed. 
  • More Ways to Pay: Members should be able to choose from multiple payment channels (online portal, mobile device, text message, etc.) and methods (credit card, Apple Pay, ACH, etc.), and each option should be as easy to use as the next. 
  • Payment Reminders: Farm Bureaus should allow members to opt in to email, text, calendar, and phone reminders so they never miss a bill again. 
  • Review and Store Invoices: Members enrolled in paperless billing should be able to receive and review invoices online any time they’d like. 
  • Automatic Payments: Allow members to “set it and forget it” with easy automatic payment enrollment capabilities. 

Options like these are crucial to helping Farm Bureaus remove friction from their payment experience, therefore making life more convenient for members and staff alike. 

Why Georgia Farm Bureau partnered with InvoiceCloud 

In the spring of 2022, Georgia Farm Bureau Insurance selected InvoiceCloud as its next online payment solution. The goal was to give its 250,000 members a variety of frictionless options for securely paying bills electronically. 

George Monk, General Manager of Georgia Farm Bureau Insurance, shared that the decision stemmed from the organization’s responsibility to meet members where they are today. 

“Our members rely on us as partners in everything that they do, so it’s essential that every interaction we have with them, be it in-person or via automated means, be as personable and pleasant as possible. The convenience and sophisticated payment options that come with InvoiceCloud give our members the options, intuitive experience, and peace of mind they’ve come to expect as part of a larger organization designed to improve the lives of our members.” 

– George monk, Georgia Farm Bureau Insurance General Manager

Want to learn more about how InvoiceCloud can help improve the high-value member experience of receiving bills and making payments? We’d love to connect and understand more about your goals! Schedule a no-obligation call here or watch the video below to hear a little more about who we are.


Sponsored by ITL Partner: InvoiceCloud
 

Originally Posted By InvoiceCloud


ITL Partner: InvoiceCloud

Profile picture for user InvoiceCloudpartner

ITL Partner: InvoiceCloud

InvoiceCloud pioneered Software as a Service (SaaS) in the electronic bill presentment and payment (EBPP) industry. We help insurers increase customer, agent, and employee satisfaction while streamlining the payment process and maximizing operational efficiencies. Our easy-to-use platform improves policyholder retention by removing friction from your most frequent and sensitive customer interactions from premium payments to digital disbursements. Our true SaaS solution delivers the latest innovations immediately without costly customizations.

4 Keys to Reducing Late Premium Payments and Cancellations

Insurers are working on reducing late premium payments and cancellations through online payment strategies.

woman reading

Many insurance organizations share common pain points when it comes to collecting premium payments – but what’s the biggest, top-of-mind challenge that keeps insurers up at night? We wanted to know, so we asked 106 insurers who attended a recent live webinar the following question: 

Which objective is most important for your insurance organization? 

  • Decrease payment-related phone calls 
  • Decrease inbound paper checks 
  • Decrease print and mailing fees 
  • Reduce late premium payments and cancellations 

With 62% of the vote, the majority of insurers asked selected “reduce late payments and cancelations” as their most critical organizational goal. This makes perfect sense, considering that late or delinquent payments often lead to policy cancellations, spikes of policyholder churn, and a negative impact on your organization’s revenue flow. 

How can you reduce late premium payments and cancellations? 

Since delayed payments are such a major concern for so many insurers – perhaps yourself included! – we wanted to offer 4 ways your organization can utilize online payment technology to combat late premium payments and prevent policy cancellations. 

1. Provide flexible payment options

The past year has seen a tremendous shift if the way customers are making payments, and it’s more important than ever to offer policyholders flexible payment options.

For example, “pay later” mobile wallet options enable your customers to pay their bill over time and can even safeguard your collections in the process. Options like PayPal’s Pay in 41 and PayPal Credit2 allow your organization to get paid upfront while offering your customers the flexibility they need. Giving customers the ability to schedule payments in advance can help drastically, too. While this feature may not be right for all customers, for payers who are experiencing a sporadic flow of income, scheduling payments ahead of time may allow them to make payments while income is consistent.

2. Prioritize communication with policyholders

In all relationships, communication is key. This is especially true for insurance organizations and their policyholders. Clear communication doesn’t just ensure for consistent collections, but can also greatly improve your customer’s experience, which can boost CSAT scores and online adoption rates. 

One great way to communicate with your customers is through Outbound Campaigns —messages that your organization can send to customers to remind them of upcoming bills, late payment notices, and much more. These campaigns not only establish a consistent channel to communicate with your customers but also are critical to preventing late and/or canceled premium payments.

3. Remove roadblocks from the payment process 

A stellar policyholder experience is critical to the success of your organization, so making the premium payment process a simple and seamless is one easy way to reduce late premium payments. Your organization can simplify the payment process by removing any roadblocks to an effortless, completed payment. 

For instance, not requiring customers to log-in or register each time they need to make a payment; an optimized guest checkout route is not only efficient, but can encourage your customers to pay online more frequently. In fact, a recent Invoice Cloud survey found that 38% of respondents said ‘convenience’ was the number one reason they chose to make a payment online, and forcing your customers to register or log-in is the opposite of convenience. 

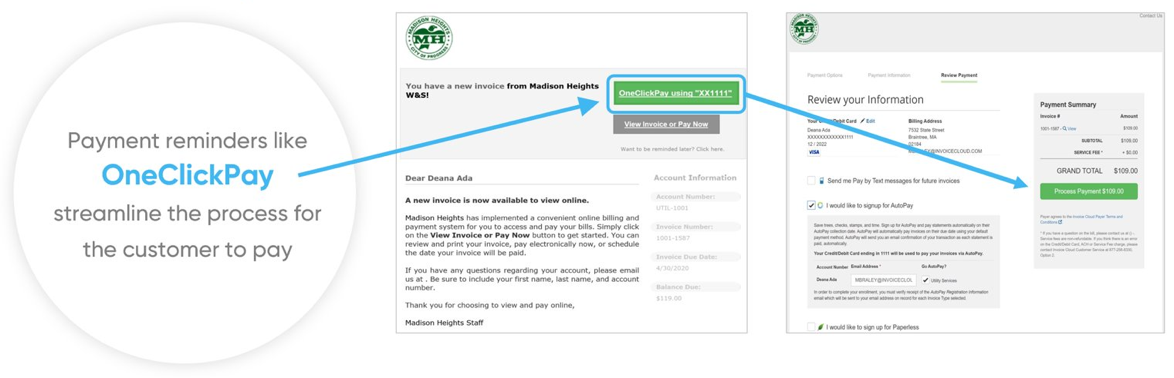
Pay by text and “one click” payment options (like Invoice Cloud’s OneClickPay) are also great for streamlining the payment process.  

These features not only increase online adoption rates but result in more consistent payments overall. If customers are offered a simple way to pay a bill, they’re more likely to make a payment sooner than later — improving internal efficiencies and giving your organization peace of mind knowing most premium payments will be paid on time each billing cycle.

4. Drive to self-service enrollment 

Encouraging policyholders to enroll in self-service payment options like AutoPay and paperless billing are key for locking in consistent payments. Your organization can do this effectively by offering customers a payment solution that is designed to encourage policyholders to enroll in these options at every customer touchpoint, including: 

  • On their bill 
  • On the payment screen 
  • In the confirmation email after a payment has been made 

Ready to get started? 

Evaluating and, subsequently, innovating your organization’s premium payment experience is undoubtedly the quickest way to improve premium consistencies and reduce cancelled policies. 

Luckily, Invoice Cloud has everything you need to start offering a better premium payment experience. Download our free content package, The CIO Toolkit: Resources for Insurance Chief Innovation Officers, and you’ll receive: 

  • Research report: Keeping Up with Millennial Policyholders 
  • Podcast: PC360’s Insurtech Center Podcast Series – How technology is supercharging CX in the insurance industry 
  • Infographic: Customer Experience in Insurance 
  • On-demand webinar: Novarica + Invoice Cloud – Embracing Positive Disruption: How Technology is Transforming the Insurance Industry 
  • Case study video: California Mutual Insurance Company 
  • BONUS WORKSHEET: The Insurance Innovation Checklist 


Sponsored by ITL Partner: InvoiceCloud
 

Originally Posted By InvoiceCloud


ITL Partner: InvoiceCloud

Profile picture for user InvoiceCloudpartner

ITL Partner: InvoiceCloud

InvoiceCloud pioneered Software as a Service (SaaS) in the electronic bill presentment and payment (EBPP) industry. We help insurers increase customer, agent, and employee satisfaction while streamlining the payment process and maximizing operational efficiencies. Our easy-to-use platform improves policyholder retention by removing friction from your most frequent and sensitive customer interactions from premium payments to digital disbursements. Our true SaaS solution delivers the latest innovations immediately without costly customizations.

True SaaS for Insurance: Meeting Policyholder Expectations Today and Tomorrow

This passage emphasizes the importance of meeting evolving customer expectations in insurance through true Software as a Service (SaaS) solutions.

digital cloud

As is true across all industries, customer expectations are constantly evolving for insurance providers. While the wants and needs of customers may change, one thing remains the same — policyholders will not renew policies with insurance providers that don’t meet their expectations.

One McKinsey study shows that satisfied customers are 80% more likely to renew their policies. However, only 15% of customers are satisfied with their insurers’ digital experience.

The fact that insurance carriers who provide best-in-class customer experiences generate 2 to 4 times more growth in new business and 30% higher profitability than carriers with an inconsistent customer focus demonstrates just how critical satisfactory customer experience truly are.

Exceed expectations with true SaaS for insurance

Software as a Service (or SaaS) is a software delivery model that provides all the benefits of a single software interface for all of your core systems, without the need for continuous updates by your IT department. Translation? Your organization enjoys all of the benefits of owning software without the trouble of managing and maintaining it.

For insurance companies in particular, SaaS is ideal because it’s secure, customizable, scalable — all of which works to increase policyholder satisfaction and retention. This delivery model also empowers insurers to digitally transform while allowing employees to place emphasis on core business functions rather than IT maintenance.

When choosing a SaaS vendor to work with, however, it’s important to make sure you’re signing up for a true SaaS solution. Sometimes, companies practice what’s called cloudwashing, or running traditional software on a cloud instance and marketing it as a “true SaaS” solution. In a cloudwashing scenario, multiple versions of the software still exist, as opposed to a cloud native solution, where only a single version or platform exists.

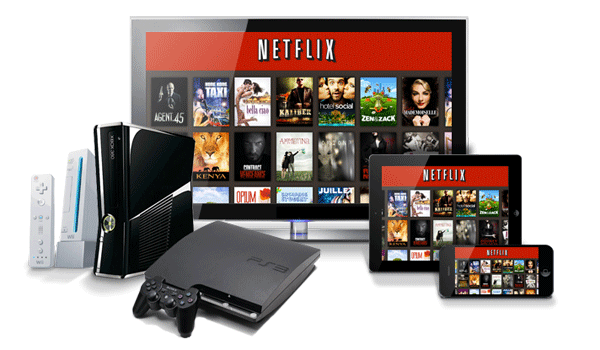
Take Netflix, for instance. As a true SaaS platform, Netflix has one single instance solution that all subscribers have access to. When a new show or movie comes to the platform, users will automatically have access to the program on any channel they use to stream.

Cloudwashed solution, however, require users to undergo costly and time-consuming customizations every time a new functionality is available. This can not only interupt daily operations, but frustrate policyholders and strain finite resources in the process.

What does cloudwashing look like?

It’s crucial for insurance companies to be able to identify true SaaS solutions from those that are cloudwashing. To ensure you’re choosing a true SaaS solution, be sure to ask yourself these questions: 

  • Are all of your customers on the same codebase or are they on variations of a common codebase? True SaaS is a single-instance, multi-tenant platform, meaning all clients are on the same base software code and platform, but others can simultaneously use the same code. 
  • How much time and effort goes into updating your system? Are internal IT resources being overextended to manually update software? True SaaS software would automatically update when a new feature and functionality was available.
     
  • Does your software provider’s website accurately depict what they provide?  If a provider’s website promotes “SaaS-based” solutions instead of “true SaaS,” it’s most likely cloudwashing. 

So, what do policyholders expect? 

Most importantly, it’s important to understand that hosted solutions, even if they are cloudwased, cannot futureproof user experience to consistently meet policyholder expectations. Research shows that 45% of policyholders are looking to switch providers within the next year, which means it’s never been more important for insurance organizations to evaluate the customer experiences they’re providing.

In order to keep up with these expectations, insurance companies first need to understand exactly what their policyholders expect. In a recent webinar, the InvoiceCloud team unveiled the results of a recent survey to explore what policyholders want and how insurers can leverage this data.

A few of their key findings include: 

  • Digital payments are table stakes: Only 6% of policyholders prefer to pay bills by mail. By far, more people preferred to pay either online or via mobile device 
  • Make digital payment options frictionless: 89% of non-digital payers would be willing to make online payments if they were easier to find and use. 
  • Leverage targeted communications: Policyholders are less likely to miss a premium payment if a reminder (or reminders) catered to their preferences is sent.

Overall, it’s clear that policyholders have high digital expectations, which insurers can fail to meet. Leveraging true SaaS solutions enables insurance organizations to consistently meet changing expectations, while reducing internal workloads.

Don’t take our word for it, see it for yourself! Watch the video below to learn how Ellington Mutual enhanced its policyholder experience with InvoiceCloud’s true SaaS engagement and payments solution.

Sponsored by ITL Partner: InvoiceCloud

ITL Partner: InvoiceCloud
Profile picture for user InvoiceCloudpartner

ITL Partner: InvoiceCloud
InvoiceCloud pioneered Software as a Service (SaaS) in the electronic bill presentment and payment (EBPP) industry. We help insurers increase customer, agent, and employee satisfaction while streamlining the payment process and maximizing operational efficiencies. Our easy-to-use platform improves policyholder retention by removing friction from your most frequent and sensitive customer interactions from premium payments to digital disbursements. Our true SaaS solution delivers the latest innovations immediately without costly customizations.

7 Common Mistakes on Innovation

As generative AI throws many innovation efforts into high gear, here are seven ways that such initiatives have failed in the past. 

Image
innovation

Why make the same mistakes that others have been making for years? Why not learn from those mistakes and avoid them? 

That may seem like an obvious point, but the vast majority of business literature focuses on success stories. It seems people like reading about successes more than they like reading about failures. People certainly like talking about their successes more than they like focusing on their failures.

But, being a contrary sort, I've focused on lessons to be learned from failures for going on 20 years now, in conjunction with Chunka Mui. He and I have written one book, "Billion Dollar Lessons," based on voluminous research into corporate failures and have published two others that build on those lessons. 

Drawing from those books and his consulting work, Chunka recently wrote a piece on seven key lessons to be learned from others' failures on innovation efforts. I'll share those here, along with some commentary from me to tailor those lessons to what's happening in insurance. 

What's happening in insurance is real progress, as far as I can see -- and I'm seeing a lot through the application process for the Global Innovation Awards, which ITL and the International Insurance Society hand out annually. (Yes, that's a plug for you to consider applying for an award, which you can do here.)

But mistakes still get made, of course, and generative AI creates loads of opportunities for companies to either succeed big or to let those same old, same old mistakes creep in. 

Let's have a look at how Chunka phrases the key mistakes to avoid. 

Chunka's essay on LinkedIn lists these seven admonitions:

--Don't think like a venture capitalist.

--Don't aim low.

--Don't put all your eggs in one basket.

--Don't spread your leadership too thin.

--Don't underestimate the corporate antibodies.

--Don't quit too early.

--Don't get too invested in an idea.

1. Don’t think like a venture capitalist.

I watched IBM try to be a venture capitalist in the '80s and '90s and Intel try in the '90s and aughts. The companies thought their insights into computers and processors would let them identify winners. They thought the investments would provide cachet to the startups, too, and incorporated their products and services into the portfolios of the IBM and Intel sales forces. 

Didn't work. IBM and Intel didn't pick many winners, and their attempts to help tended to smother the start-ups.

Chunka explains why venture capital isn't even the right game to be playing for innovators. 

"Despite the allure of Silicon Valley," he writes, "don’t conflate corporate innovation with venture capital. There are major differences. Large company innovators are not financiers. Their primary objective should not be to maximize return by investing in a large portfolio of start-up companies." 

Even a successful venture capital portfolio won't move the needle much for a major insurer, and a VC effort could very well distract companies from what really matters: innovating (alone or with startup partners) in ways that will make a difference across the enterprise.

I haven't seen many insurers making the VC mistake in recent years, but the temptation will be there with generative AI, especially as some startups go public and valuations pop.

2. Don’t aim low.

Chunka writes, "Meaningful innovation and true business model reinvention can only arise from aspirations of the kind that took Amazon from books to AWS cloud services, and Apple from Macs to iPhones." 

That claim may not resonate so much in insurance, where companies like Lemonade that tried to reinvent the industry haven't been faring so well. But companies still need to think big, even if they're just exploring how, say, generative AI can be used in distribution, underwriting or claims. You can start off imagining reinventing the agency, having continuous underwriting or moving to straight-through processing of claims, even if you know you won't get there overnight and know you won't be reinventing the business model of the whole company. 

3. Don’t put all your eggs in one basket.

When the CEO or even the head of a unit has an idea for innovation, it tends to become THE idea. Everyone working for the CEO or unit head tends to quash any objections and does their utmost to make the idea pan out. But even a really good idea -- and many ideas aren't that great -- often fails, so it's important to have a portfolio of potential innovations. 

"Given the uncertainty of technological change, it doesn’t make sense to have only one alternative," Chunka writes.

4. Don’t spread your leadership too thin.

But, but, but... don't have too many alternatives percolating at any one time. 

As Chunka says, "In corporate innovation, the constraining resource is management attention, not capital. There’s only so much of it available. No one can keep track of one or two dozen nascent businesses while still running a company day to day. The head of the business can’t delegate the work, either," for any project that could have a transformative effect. "It's impossible to neutralize naysayers, build the necessary alignment, or guide the organization through the necessary transitions. Our experience is that the right number of killer options is usually three or four, and no more than five."

5. Don’t underestimate the corporate antibodies.

"Almost every organizational bias favors protecting the status quo," Chunka writes. "People are going to find every possible way to make a radically new idea fail. They’ll try to steal the money or poach the people. They’ll throw up technological obstacles.... So, perhaps corporate innovators’ most difficult but important job is to block the antibodies long enough that [innovations] get every means to prove themselves. Having a manageable number of options and the right level of CEO support is critical."

6. Don’t give up too early.

I've written many times that our mantra about innovation is Think Big, Start Small, Learn Fast, and I may seem to be contradicting our admonition to kill ideas the very moment you know they won't work. But this point of Chunka's is different. It's about being willing to make an investment and stick with it -- barring those clear signs of failure -- even if your bet is a long shot.

Chunka explains: "Take a lesson from the concept of pot odds in poker. The notion is that you don’t just figure out whether you have a better-than-even chance of winning a pot. You calculate what it will cost you, now and possibly after future cards, to compete for a pot. You compare that number with the size of the pot, then compare that ratio to what you think your odds of winning are. If you have to bet $1,000 to have a shot at a $10,000 pot, even a 20% chance of success might justify the risk. In other words, evaluate the size of the additional investment against the size of the potential market as you evaluate whether to renew" an innovation effort.

7. Don’t get too invested in an idea.

This is one of the hardest issues to sort out. When do you fish, and when do you cut bait? 

The best way we've come up with is to set the rules ahead of time. Otherwise, proponents and opponents of an idea will arguing about the rules and complicating the discussion while you're trying to make an important decision. 

As Chunka puts it, "Set up regular reviews, agreed to ahead of time, [to decide] whether to continue funding. The analysis has to be done afresh each time, so you don’t get carried away by the amount of money already invested. The question has to be: How much additional money will we need to invest, and might the bet be worthwhile? When a bet no longer looks good, set it aside, regardless of how much financial and emotional capital has been poured in."

******

Innovation is tricky, but you can at least increase your chances of success if you absorb the mistakes that others have made before you. 

Cheers,

Paul

Mapping the Intensifying Flood Threat

As climate change transforms destructive floods into a primary peril, insurers and companies with valuable assets in harm's way need better tools. 

Person Riding a Bicycle during Rainy Day

In 2023, four massive floods in the U.S. caused more than $1 billion in damage each. From California to Florida to the Northeast and East Coast, they struck in different seasons and geographies but were united by a common thread: Their intensity defied the expectations of many experts. 

In addition to these billion-dollar catastrophes, the U.S. endured numerous smaller but still destructive floods. Whether the source was surging high tides in coastal communities or relentless atmospheric rivers that overwhelmed storm drains, the floods destroyed homes, disrupted businesses and endangered lives.

The U.S. isn't alone. Globally, flooding affects more people than any other natural peril. While floods have traditionally been considered secondary perils – the kind that happen relatively frequently but generate modest losses – climate change is super-charging their impact by making them larger, less predictable and costlier, more like primary perils such as Atlantic hurricanes or typhoons. 

A major challenge in understanding and preparing for evolving flood threats has been that maps used to assess and quantify flood risk often haven't kept pace with a changing climate. One government assessment concluded that U.S. flood hazard maps, for decades a key resource for communities to set building standards or determine flood insurance premiums for vulnerable properties, "didn't reflect the best available climate science." 

See also: AI, Aerial Imagery Can Help Spot Flood Risks

Hazard intensification

As one of the world's largest reinsurers, Swiss Re has long tracked natural catastrophe loss trends, including from floods. While urbanization, population growth and accumulation of assets in exposed regions have historically been main drivers of insured losses, our experts have determined that changing climate will become an increasingly important factor in rising future losses.

And with climate change contributing to intensifying hazards like extreme rainfall or powerful ocean storm surges that harbor potential to cause bigger floods, access to powerful tools to understand these evolving risks is growing more urgent. Simply put, we must get better at predicting what's to come, especially when a warming planet makes the past a less-reliable guide to future threats.

Fortunately, powerful tools are becoming available. For instance, this month, Swiss Re Reinsurance Solutions, our division focused on delivering data-driven risk insights to clients, achieved a milestone when we integrated independently validated, high-resolution U.S. flood maps into CatNet. This is our risk assessment tool that insurers and companies may rely on to analyze exposures to natural catastrophe risks. 

These U.S. flood maps were developed by our subsidiary Fathom, the U.K.-based water intelligence company that Swiss Re acquired last year to supply clients with dynamic flood risk assessments. Founded in 2012 by scientists at the U.K.'s University of Bristol, Fathom's hydrologists, software engineers, modelers and geographic information system (GIS) developers have created the most accurate digital terrain model of the U.S., with a resolution of 10 meters per pixel.  

See also: Property Underwriting for Extreme Weather

One platform, multiple risk models

Reinforcing modeling resources with maps supports insurers and companies to create more sophisticated climate-driven flood risk scenarios, instead of relying on historical data alone. Multiple flood-risk models on a single platform allows simultaneous comparisons, enabling more comprehensive risk assessments.

Beyond visualising flood risks more accurately, insurers can integrate data into their underwriting models to assess and price risk more confidently. Thus equipped, they can pinpoint and address exposures to vulnerable regions, adjust terms and conditions and exclusions to reflect evolving risks and even identify new, promising geographical areas to pursue growth.

Similarly, U.S. flood maps can help companies determine where their biggest risks will emerge, informing adaptation strategies aimed at avoiding losses today and tomorrow. Communities can leverage mapping technology to better understand how and where to grow, to protect citizens and economies. Fathom already provides flood data via the World Bank to help 16 climate-vulnerable countries future-proof themselves against disaster.

The U.S. suffers the largest absolute annual economic losses from natural catastrophes of any nation. With climate change, it faces increased exposure to rising weather-related losses, including from floods like those in 2023. This January, for instance, San Diego County, California, became the latest place to be declared a federal disaster area after rainfall eclipsed records, damaged hundreds of homes and washed cars away. 

While residents described being taken off guard by what some called a 1,000-year storm, climate change actually means such events can no longer be considered anomalies. To prepare and adapt for this new reality, flood maps that keep pace with the forces of a warming world are an essential tool.  

Revolutionizing Customer Engagement: The Impact of Omnichannel Experiences in the Insurance Industry

Gain insights from a study on 250,000 P&C insurance customers' multichannel engagement and receive 10 tips for better customer experiences.

omnichannel

Discover strategic game-changing insights in the latest publication from insured.io, "Revolutionizing Customer Engagement: The Impact of Omnichannel Experiences in the Insurance Industry":

  • Uncover the 25% increase in renewal rates for users of multiple service channels
  • Learn actionable strategies such as SMS alerts and IVR services
  • Dive into real-time engagement solutions that foster customer loyalty
  • Gain comprehensive insights based on a study of 250,000 P&C consumers
  • Elevate your insurance business with data-driven and practical approaches

Download now and revolutionize your customer experience!

Sponsored by: ITL Partner: insured.io


ITL Partner: insured.io

Profile picture for user insured.io

ITL Partner: insured.io

Insured.IO provides mid-market insurance carriers with the most complete and modern SaaS customer self-service platform for mobile, desktop, and telephone IVR that is affordable and can be maintained with minimal ongoing technical support. It serves the complete insurance product lifecycle, including sales, payment, FNOL, and analytics. Using cloud-native technology, the platform easily and quickly integrates with any insurance core systems and can be tailored to each carrier’s unique needs. It delivers real-time data synchronized across all channels, providing greater process automation, reduced CSR utilization, and great business intelligence that improves operating performance. Insured.IO can be up and running in as little as 60-90 days.

Carriers Must Lead on Cyber Solutions

The top three bad cybersecurity practices are all common among insurance agencies. Carriers can help, for just $1 per agency per year.

Cyclone Fence in Shallow Photography

The U.S. Cybersecurity and Infrastructure Security Agency (CISA) has a list of bad cyber practices, all of which are common among insurance agencies:

  1. Use of unsupported or end-of-life software
  2. Use of known, fixed or default passwords and credentials
  3. Use of single-factor authentication for remote or administrative access to networked systems

Carriers and agencies cite competing priorities, expense and problems with operational interruptions as reasons for not implementing crucial cybersecurity measures. These objections can be short-sighted in view of the high severity of a breach. 

IBM’s “Cost of a Data Breach Report: 2023” says, “Organizations with fewer than 500 employees reported that the average impact of a data breach increased from $2.9 million to $3.3 million,” a 13% increase from 2022. Organizations of more than 25,000 employees saw a 2.5% decrease in average losses from a data breach, to $5.4 million in 2023, the report states. Still, the financial hits for large companies are painful, with regulatory and reputational consequences, as well.

The risk of system shutdown from ransomware attacks and the potential costs of liability for the dissemination of proprietary information far outweigh the expense of protection. Happily, there are steps carriers and agencies can take that are comparatively inexpensive that will also improve efficiency in transactions.

Unsupported software

An average agency does business with 10 to 12 carriers, and a large agency could have as many as 30 carrier partners. It is very likely that each carrier has a different update cycle for its software. A breach to the weakest link, maybe because a security patch was not applied, could affect all the other carriers an agency is doing business with. 

Each carrier will say it has a robust authentication process. However, do all the carriers the agency connects to have an equally strong process? A common and secure method to authenticate system access can reduce the breach risk for all participants.

See also: Risks, Trends, Challenges for Cyber Insurance

Use of known, fixed or default passwords and credentials

It is difficult to remember even one complex password. How many 15-character passwords with uppercase, lowercase, numeric and symbols requirements can you remember? It’s not surprising that agency representatives use the same password across multiple carriers to increase efficiency. It makes sense if convenience is the primary concern. 

Independent agents may log in to each carrier multiple times in a day. This requires switching between authentication credentials – ID, password, multifactor authentication (MFA) – with each access request. As CISA indicates, using a fixed or default credential across accounts increases the breach risk. Once one carrier is compromised, use of a common password also puts the other agency carrier partners at risk.

Even worse, in some agencies, there is a single, shared login for all users to simplify access. Use of this practice means a cybercriminal has to gain the credentials of only one user for all account data to be compromised, and potentially open a gateway to carrier systems.

To solve the cybersecurity issue and improve efficiency, carriers, technology partners and agents must work together. MFA will help the entire independent agent channel be more secure. For example, our SignOn Once makes it operationally easy to enable the agency management system to be a single authentication point. The agency management system generates a unique token for a user at login, and that acts like a key to unlock entry into carrier agent portals. It isn’t shared, and it changes every day. Cost for carriers is about $1 for each of their agencies for the year. 

Use of single-factor authentication

Multifactor authentication – where login with an ID and password is verified by input of a secondary piece of information – is becoming an industry standard. This additional information can be a code or clicking on a link delivered to a secondary device, such as a cell phone. With the rise in cyberattacks, both regulators and cyber insurers are advocating for or, in some instances, mandating its use. MFA prevents a bad actor from entering a system with just a stolen ID and password. It’s an incredibly important deterrent to cybercrime.

Crowdstrike says that “80% of all breaches use compromised identities.” Because totally preventing access to user IDs – and even associated passwords – may be impossible, especially with the burgeoning abilities of artificial intelligence, having that second layer of protection provided by MFA is essential.

See also: How to Combat the Surge in Ransomware

Carriers can lead the way on cybersecurity

With the increasing threat of cybercriminals, taking the simple step to protect access to systems at the agency level would seem to be a no-brainer. Moreover, the impending threat of AI-generated audio and email fakes that replicate the voice or tone of a trusted source suggests hackers may gain even greater access to login credentials. Affordable cybersecurity measures are needed ASAP.

Carriers can, and should, take the lead by working together to protect all industry stakeholders. Security is not an area for carriers to compete. Ask your carrier partners to invest $1 in your agency each year to strengthen your security posture and increase operational efficiency.


Alvito Vaz

Profile picture for user AlvitoVaz

Alvito Vaz

Alvito Vaz is executive director of the ID Federation. 

He has more than 30 years of leadership experience in the insurance industry. He has held technology leadership positions at Progressive and Travelers, and, in the agency automation space, he has worked with comparative rater and management system solution providers. 

He is a member of ACORD's Property & Casualty Steering Committee and is an inaugural member of IIABA's Agents Council for Technology (ACT).

Re-Imagining the Actuary in the Gen AI Era

AI will help automate repetitive tasks, improve accuracy, increase efficiency and enable actuaries to function as business strategists.

An Artificial Intelligence Illustration on the Wall

In the digital world, where risk postures and behaviors are changing and new risks are emerging, actuaries need to function as business strategists, looking beyond historical data and increasing agility in rate filings.

Disparate data stores and lack of granularity across the enterprise, coupled with legacy systems, have forced actuaries to spend significant effort on data processing. This affects their work in core activities, such as 

  • Reserving Studies
  • Rate Filing
  • Risk Analysis
  • Profitability Studies

Also, traditional generalized linear models (GLMs) may not be able to handle very large or high-dimensional data sets and unstructured data (telematics, sensors, images, etc.), limiting their accuracy or effectiveness to capture behavioral changes, forecast claim cost trends and revise their assumptions. Heavy reliance on spreadsheets for rating and lack of governance and traceability pose delays in filing rates and responding to audit inquiries. 

Generative AI as a companion for actuaries

The advancements in AI can be leveraged to alleviate the burden on actuaries and serve as a companion to improve their productivity and agility. Below are some applications where Gen AI can assist actuaries in streamlining workflows and enhancing capabilities:

  • Data Processing for Experience Analysis: A significant amount of time is spent in cleansing and preparing data for analysis. AI can be leveraged to automate tasks such as pattern recognition, data correlation, outliers, transforming data into formats suitable for modeling (model input file generation, etc.) 
  • Data Enrichment: Based on pattern recognition and data correlation, a synthetic data generator can be leveraged to fill in the missing values in applicable scenarios, such as claims processing. Experience analysis can be enriched with additional socioeconomic, health or financial data, allowing the insurer to build up a more granular understanding of policyholders and factors that lead to differences in experiences across various cohorts.
  • Code Conversion for Models: As part of actuarial transformation and tech debt reduction, organizations are increasingly migrating their code base from legacy technologies to R and Python, etc. Gen AI can analyze existing code, capture the tacit knowledge or business logic and create baseline code that serves as a jumpstart for modernization.
  • Model Documentation: From a model governance standpoint, documentation plays a critical role to enable transparency and maintainability, but documenting complex actuarial models is time-consuming. In this context, Gen AI can analyze the model code and automatically create baseline technical documentation in natural language based on format, structure, etc. provided as input as part of prompt engineering. Quality can be enhanced by integrating prompting language and a retrieval augmented generation (RAG) process.
  • Scenario Analysis: Scenario analysis is critical for assessing the risk exposure and defining mitigation strategies. In this context, digital twin (an AI-driven, multi-model, simulation-aided platform) can be leveraged to construct hypotheses, run various “what-if” simulations and determine the impact to the portfolio. The explainability component of digital twins enables actuaries to make informed decisions.
  • Operational Efficiency: As part of the monthly or quarterly close, operations often face challenges manually traversing through various linked spreadsheets to identify and prepare inputs or references for the model run. An AI model can be used to analyze and document the upstream and downstream links relevant to a specific spreadsheet, process or output report. 

These applications help to automate repetitive tasks, improve accuracy and increase efficiency and enable actuaries to focus on the core, as a business strategist.

See also: Balancing AI and the Future of Insurance

Human + AI Partnership

To realize the true value of human/AI partnership, governance and guardrails are the foundation, and Gen AI needs to be leveraged responsibly and aligned to ethical standards and regulations. As part of its evolution, Gen AI will play an assist and augment role, and actuaries (human) will still be responsible for defining model parameters, interpreting results, driving strategies and ensuring twin objectives are met. Re-imagined actuaries in collaboration with data scientists will drive innovation in continuous underwriting, loss reserving, product innovation, sustainable investments, personalized pricing and profitability, transforming the insurer.


Prathap Gokul

Profile picture for user PrathapGokul

Prathap Gokul

Prathap Gokul is head of insurance data and analytics with the data and analytics group in TCS’s banking, financial services and insurance (BFSI) business unit.

He has over 25 years of industry experience in commercial and personal insurance, life and retirement, and corporate functions.

D&O Insurance Pricing May Be Inadequate

After aggressive increases helped firms recover from a decade of woeful rates, premiums are declining. The shift may be too much too soon. 

Person Holding Pen Pointing at Graph

Current pricing trends in the directors’ and officers’ insurance market could yield premiums that prove inadequate to cover potential claims, owing to growing risks for which senior corporate directors and officers are held responsible.

After a decade of woefully inadequate rates in the U.S. D&O insurance segment that led to consistently unprofitable underwriting results, aggressive pricing increases in 2020 and 2021 finally made inroads for D&O insurers and led to much-needed market stabilization. These pricing increases also attracted capital to the market from strong underwriters with new, creative approaches to public D&O underwriting. 

However, beginning in the second quarter of 2022, D&O premiums began to decline materially in most sectors, as did retentions, resulting in much more favorable pricing for insureds. (Insured retentions tend to decline as markets grow softer, as clients can shop around for coverage.) Direct premiums written declined by nearly 10% in 2022, due largely to the economic environment that made M&A and IPOs less attractive. Less M&A and IPO activity diminishes demand for public D&O coverage.

D&O pricing in 2023 continued the momentum from the prior year, and renewal pricing was essentially flat, on average, by the end of the year. This has offered a reprieve for risk managers and brokers, but with pricing changes sinking below economic inflation, fear began to rise that the pendulum may be swinging back to rate inadequacy. 

See also: The 'B' Word: Bankruptcy and D&O

Third-quarter 2023 results show an uncertain picture for the D&O line going forward. Premiums declined for a sixth straight quarter on demand shifts and pricing changes; AM Best’s estimate for 2023 is $12 billion, which would constitute an 11% drop from the previous year. The number of IPOs declined again, to 72 in 2023, the lowest since 2009 during The Great Recession. With results leveling out and demand for transactional liability coverage declining, average pricing on D&O accounts has since fallen dramatically.

At the same time, the direct calendar year loss ratio for the line has also fallen, reflecting the realized benefit of the substantial up-pricing of renewals and new business from 2020 through early 2022. The direct loss ratio of 51.5 through third-quarter 2023 is on track to be the lowest in nine years, improving the industry’s underwriting performance. If results continue to be favorable and prior accident-year reserve development does not trend adversely, additional capacity may flow into the D&O market. That loss ratio does not factor in the potential impact that adverse loss reserve development could have on the net, bottom-line results for D&O insurers. With more lawsuits being settled or adjudicated as courts fully open following pandemic-driven closures and delays, the true profitability of policies underwritten is still maturing -- prior accident years 2017-2020 remain unknown.

AM Best is assigning a negative outlook to the D&O liability insurance market segment for 2024. Prior to this year, the D&O market outlook was captured under the professional liability catch-all, even as D&O represented the dominant line. That outlook was revised in 2020 to negative, so the new outlook on the D&O segment for 2024 is not a deviation from the previous few years.

An increase in players in the D&O market is a factor in the outlook, as the influx brings additional capacity and declined pricing amid growing exposures. Also included in the negative D&O outlook are expanded liability risks, as the business environment has become increasingly more complex and connected. Cyber and data breaches are becoming ever more pervasive in all different business sectors, particularly for businesses that rely on personal data. At the same time, new data protection laws and related disclosure requirements have added to the minefield senior executives must navigate to protect against potential litigation. The rise of generative artificial intelligence (AI) opens a whole new avenue for the plaintiffs’ bar, as well. Depending on how companies integrate AI into their decision-making process, corporate directors and officers could be accused of algorithmic biases in risk selection or underwriting decisions.

Inflation over the past 18 months, as well as interest rate increases to fight inflation and market volatility, have created negative pressure for stock prices and funding for privately held companies, which could result in shareholder and derivative actions. The bank failures of last year also have led to intense scrutiny of banks’ executive leadership and boards of directors. 

The rising cost of litigation owing to societal trends, such as broad interpretations of liability contracts, legal advertising and more plaintiff-friendly juries continues to drive increases in loss frequency and severity, and large, public-facing companies are particularly vulnerable. Litigation financing has been used for a range of lawsuits, including complex multidistrict and class-action litigation, in which D&O liability cases can specifically come into play. Third-party funders provide financial help in exchange for an interest in any recovery, and the financing can be offered to law firms that are unwilling or unable to fund a potentially protracted case or to help underfunded claimants directly. For D&O insurers, litigation funding pressures claims costs by driving up the magnitude of awards and settlements.

See also: Insuring Risks Amid AI's Constant Evolution

As the costs of litigation continue to rise, companies are becoming more likely to explore settlement opportunities even when the facts may be on their side. According to Woodruff Sawyer, settlement dollars during the first half of 2023 were up slightly more than 29% year over year, with settlements over $20 million up about 33% from the same period in 2022. These trends are apparent in underwriting results near year-end 2023.

If interest rates remain high and inflation persists, access to credit markets will become increasingly difficult, as companies struggle to balance the need for profits with prudent debt management. D&O insurers will need to better assess and adequately price for the ever-changing risk exposures while effectively focusing on evolving regulatory requirements.


David Blades

Profile picture for user DavidBlades

David Blades

David Blades is an associate director within the Credit Rating Criteria, Research & Analytics Department of AM Best, a global credit rating agency with a focus on the insurance industry.

A Resurgence in Credit Card Fraud

After years of decline, the number of compromised credit cards sold is on pace to exceed 34 million this year, a major reversal.

Close up of colorful computer code

Credit card fraud would seem to be a frequent, lucrative method of monetary gain for cybercriminals. While this was the case for many years, activities over more recent years have shown otherwise. The number show that cybercriminals were losing interest in selling and buying stolen credit card information. But lately, the global underground market for compromised cards seems to be on the upswing again, climbing steadily from the end of 2023 and continuing this year.

It's both surprising and sadly predictable -- a reminder that there's rarely a "done and over with" in cybersecurity battles.

See also: Cyber's Evolving Threat Landscape

Understanding the world of stolen credit cards

At Cybersixgill, we collect millions of pieces of data from the deep, dark and clear webs each day to better understand the actions of digital fraudsters who are continually seeking ways to enrich themselves, so we can help businesses protect themselves.

In 2019, more than 140 million compromised credit cards were listed for sale on underground markets. The number then plummeted each year, and by 2022, the total number of compromised cards dropped to 9.1 million. The price of cards dropped, as well.

In September 2022, we analyzed why the number of cards declined and attributed it to a fall in both supply and demand. On the supply side, it became more difficult and less attractive to compromise cards. For those on the demand side, security measures were making it harder to use a card in fraudulent ways. Our conclusion was that those who looked to profit from cybercrime pursued other methods, such as ransomware.

A change of course in late 2023

Through the first 10 months of 2023, average sales of compromised cards were about the same as in 2022. But beginning in November, sales shot up dramatically -- so much so that overall annual sales jumped 25% from 9.1 million in 2022 to more than 12 million in 2023.

These trends continued into January and February 2024, setting the number of compromised credit cards sold on pace to exceed 34 million this year, representing a major reversal after years of decline.

Seeing this data, we had to dig deeper and figure out what was going on.

What's the reason?

Our research shows that a particular dark web market -- one that had been dormant for a while -- recently re-opened. The re-emergence of this market has shifted the entire landscape of compromised credit cards; since mid-November 2023, it has listed more cards than any other market. In fact, it has accounted for about 65% of ALL compromised cards for sale and is solely responsible for the overall rise in cards.

See also: Cyber Insurance at Inflection Point

Why is this market bucking such a significant trend?

First, we posited that the universalization of EMV chips and better e-commerce site security made it more difficult to compromise cards compared with the heyday of Magecart attacks of 2018. (If you're not familiar, Magecart is a collective of cybercriminal groups that inject digital credit card skimmers on e-commerce and payment websites. These groups have been active since 2015 and gained momentum in 2018 with successful breaches of well-known brands such as British Airways and Ticketmaster.) It could be, however, that the operators of this renewed market discovered a new attack technique or carried out a major breach, enabling them to accrue a massive supply of cards.

Second, we considered that threat actors had far better opportunities to make money, specifically with ransomware and crypto-exchange hacking. However, things have changed over the last few years. With so much effort on the part of organizations and governments to fight ransomware, only the most sophisticated groups can carry out successful attacks. And crypto-exchange hacking appears to have declined significantly, as well.

Therefore, it could be that the operators of this market determined that carding was indeed their most lucrative and least risky option, and they reincarnated their old operation.

Now what?

It remains to be seen if recent activity in this fraudulent card market is an anomaly or if it represents a new trend. Will it be able to sustain the number of cards? Will other markets increase their supplies? Will new markets emerge?

Fortunately for consumers and issuers, the Payment Card Industry Data Security Standard (PCI DSS) is undergoing changes that promise to make credit card payments safer than they were previously. These broad changes, which represent the first major update since 2016, begin this month and go into full effect a year later.

Governmental action also plays an important role: Banks are under increasing regulatory pressure to minimize credit card fraud. Additionally, law enforcement may choose to pursue markets for stolen credit cards more aggressively, as they do with ransomware.

Consumers need to be wary of suspicious activity and check their accounts regularly to spot any charges they don't recognize. They should use a card with an EMV chip to prevent skimming attacks and be highly cautious so as not to fall for phishing email schemes.

In our increasingly interdependent digital world, cybercriminals are permanent residents, not temporary visitors. We need to acknowledge their presence and stay diligent.


Dov Lerner

Profile picture for user DovLerner

Dov Lerner

Dov Lerner heads Cybersixgill's security research team and writes the company's annual "State of the Underground" report that looks at trends in cybercriminal activities.