Paul Carroll, Editor-in-chief of Insurance Thought Leadership.
Pricing gets far less attention than claims or underwriting, yet is important. How is the pricing function being modernized in insurance? And how should it be?
Kumarappan Sundaram, Managing Director, PwC US
Pricing gets less attention partly because a lot of the work is infrastructure: platforms, data flows and deployment processes. It is not a front-office workflow that a new tool can visibly transform.
Modernization can be uneven. Personal lines are well on their way. Commercial lines are earlier in the journey and still rely heavily on underwriter judgment and rating engines embedded in policy administration systems.
How pricing should be modernized can largely be a question of sequence. The foundation comes first: decoupling rating from the policy admin system. At the moment, actuaries produce pricing logic, which they hand to IT, which embeds the logic in a rating engine that sits within a policy admin system. So, making a change to the pricing logic means waiting for a new release of the policy admin system. If you decouple, you can make changes to ratings as and when you want.
Once you’ve decoupled, you should build reliable data flows and establish clear governance.
You can then go to the next level of capabilities, like advanced analytics and AI. Let’s say you have a $10 billion book. You’re considering changing a particular rate factor from X to Y, maybe related to driver age. Advanced analytics can help you understand the impact of the rate change on the whole book. The actuaries can then decide whether to make that rate change. Carriers can help deploy and monitor pricing changes quickly and safely.
Paul Carroll
From a technology standpoint, what are the most important shifts in P&C pricing and rating?
Kumarappan Sundaram
Pricing is moving from a periodic project to a continuous capability. With catastrophe volatility and shifting market conditions, treating pricing as an occasional exercise is hard to sustain.
Two shifts stand out. First, dedicated pricing platforms. Rating, models and rules increasingly sit on purpose-built platforms rather than inside the core policy system. Second, modern software discipline. Version control, automated testing and continual monitoring of live models are becoming standard.
Paul Carroll
What is driving carriers to invest in sophisticated pricing platforms now?
Kumarappan Sundaram
Five things.
First, speed-to-market of rate changes. Moving from quarterly or annual releases, gated by IT and policy admin deployment, to something near-continuous is the key value. Decoupling rating logic from the core policy system is also a practical starting point for core modernization, delivering value without an entire core replacement.
Second, loss cost volatility and trend uncertainty. Social inflation, repair and parts costs, tariffs and secondary-peril catastrophe losses make trend assumptions go stale faster. Carriers want faster feedback from emerging claims experience that they can incorporate into price.
Third, segment-level control. Carriers want to grow where they are well priced and hold the line where they are not, which means testing, deploying and monitoring changes at a granular level.
Fourth, regulatory and governance demands. Filing, documentation and explainability requirements keep growing. Audit trails can be far easier to build in than to retrofit.
Fifth, data ecosystem expansion. Telematics, geospatial and property-level data, cat model output and third-party enrichment should flow into rating at quote speed, which can often be the real integration challenge.
A CFO will often ask how the benefit is measured, so programs should define measurement up front.
Paul Carroll
Underwriting and pricing are tightly linked conceptually, but loosely coupled in practice. Why is that, and can they be brought into phase?
Kumarappan Sundaram
The link is strong in theory but weak in practice, mainly for technology and operating-model reasons.
Start with systems and data. Pricing logic sits in a rating engine or pricing platform, while underwriters work in a different workbench based on the data in the submission, so the two rarely share a view of the risk. Then there are different rhythms. Pricing changes on a release cycle, while underwriting decisions are made submission by submission. Overrides and discounts help fill the gap. Finally, the feedback loop is weak. Why underwriters override a price rarely flows back to pricing in a structured way, so a valuable signal is lost.
Modern pricing platforms increasingly aim to close this gap. Bringing them into phase is mainly an integration and governance task. Pricing can be exposed as a service that the underwriting workbench calls in real time, connected to appetite, distribution, retention and claims signals. Overrides can be captured as data, and authority and guardrails can be made explicit. In complex commercial risks, underwriter judgment legitimately plays a larger role, so the aim there is visibility and learning, not automation.
Paul Carroll
How can modern pricing technology help carriers price emerging risks?
Kumarappan Sundaram
Emerging risks, such as cyber, climate-related perils and new auto and energy technologies, may not come with deep loss history. A modern platform helps in four ways.
First, new data sources as proxies. Outside-in cyber scans, geospatial and property-level data, and vehicle and telematics data give carriers signals where claims history is thin. The platform brings them together with internal experience and subject matter specialist judgment, with clear rules for how the weighting shifts as claims data builds.
Second, scenario testing. Teams can test prices against stress scenarios, such as a major catastrophe or a systemic cyber event.
Third, fast, controlled learning. Small, measured changes show what a new risk is worth sooner and with less exposure than a book-wide change.
Fourth, flexible product design. Configurable rating makes it easier to adjust deductibles, sublimits and endorsements as understanding of the risk develops.
The limit can be that technology cannot create data that does not exist. For novel risks, the platform helps carriers learn and adjust quickly, alongside accumulation controls, reinsurance and underwriting oversight.
Paul Carroll
What impact is AI having on pricing and rating, and where should leaders be skeptical?
Kumarappan Sundaram
I would separate what is emerging with clear value from what is still unproven.
The clearest near-term value is GenAI around the pricing process. The more underrated opportunity is in the work surrounding the price: drafting and reconciling rate filings, translating pricing specifications into platform configuration, documenting changes, summarizing competitor filings and preparing data. These steps slow the path to market, and errors are easier to review than in a pricing decision itself.
What is still unproven is AI acting on pricing decisions. The idea of agents that monitor performance, propose rate actions and test them is compelling. But pricing is regulated and auditable, and many carriers are not ready for autonomous rate changes. For now, I expect AI to propose and people to approve, so the quality of that review is the real control.
As AI capabilities become widely available, proprietary data, speed of deployment and governance are likely to matter more as differentiators. Carriers that treat AI as a standalone upgrade, without the platform and operating model underneath it, risk building capability they cannot put into production.
Paul Carroll
What would you advise a carrier to do first?
Kumarappan Sundaram
Measure your cycle time, from the point a pricing change is approved to the point it is live throughout the various channels. Many carriers have never seen that number, and it shows where value is being lost. Then prioritize platform and process changes that shorten it. Put governance in place before scaling AI, and start with one or two lines where faster pricing has a clear, measurable payoff. Resist modernizing everything at once.
Paul Carroll
Thanks. This is all super helpful.
--
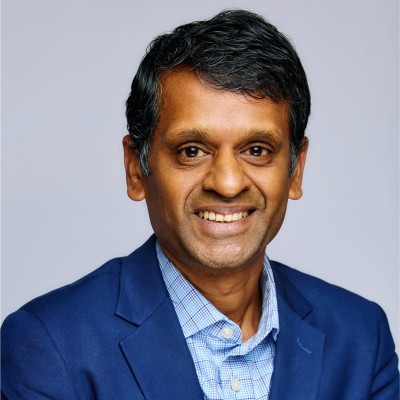
Kumarappan (Kumar) Sundaram is a Managing Director in PwC’s Property and Casualty Operations and Technology practice and a leader of its Insurance Core Transformation and Pricing/Rating offering. With more than two decades of consulting experience, he partners with US and UK P&C carriers, from large international insurers to small regional ones, across personal, commercial, and specialty lines, with depth in commercial and specialty. He has led numerous large-scale programs modernizing policy, claims, and pricing/rating operations, and works with PwC’s strategy, management, technology, and actuarial teams to deliver integrated solutions, thought leadership, and sales.
--
Sponsored by PwC