Download

5 Mistakes CFOs Make on Healthcare

CFOs must recognize that healthcare is a capital allocation strategy—it needs the supervision of an executive with P&L responsibility.

sixthings
Which sounds worse: getting shortchanged by a cashier at the grocery store or losing your life savings to a Bernie Madoff-type investment?The answer is obvious. Still, it’s a good metaphor for how to manage your healthcare investment and, more importantly, the glaring flaws in how healthcare is administered and delivered. First, some background. The Employee Retirement Income Security Act of 1974 (ERISA) was designed to protect employee benefits, including health plans. The person exercising authority over a health plan is a “fiduciary” and legally bound to act in the best interests of the participants. But, according to a recent article, chief financial officers (CFOs) are facing millions of dollars in personal liability suits due to a lack of “fiduciary oversight.” Whether the cause is negligence, omission or imprudent management, the result isn’t good: a potential lawsuit for the company and executive, mishandled or wasted money and shortchanged employees. Throw the Department of Labor into the mix (it's been keeping a close eye on 401k plan fiduciaries in recent years), and the choice is cut-and-dried: Most companies need to up their game. See also: A Way to Reduce Healthcare Costs   Here are the five biggest mistakes CFOs make when designing, purchasing and managing their health plans. 1. Taking a gamble. CFOs of middle-market companies are gambling with the organization’s healthcare by taking 19 to 125 times more risk than they should. Why would any organization risk $500,000 or $1 million when it can reduce exposure to less than $8,000? It’s even more shocking at large companies when the bottom line is exposed to unnecessary healthcare overspending. Healthcare managers wager millions of dollars by ignoring reducible risk, and the mistakes hurt the bottom line. C-suite executives are surprised when I explain why “best practices” don't work—until I show how many millions of dollars are trapped inside their healthcare budget. 2. Surrendering responsibility to unqualified departments and managers who don't have P&Ls. I always ask CFOs one simple question: "By a show of hands, who would hire a HR-level executive to lead a $100 million division of your company?" No CFO has ever raised a hand. Yet the company’s healthcare investment is often treated as an operating expense that’s delegated to operations managers who don't have the time or expertise to make the best-informed decisions. Too often, these decisions end up in the hands of consultants who, most often, will take a boilerplate path of least resistance by recommending "best practices" that only major in minor outcomes. 3. Not all healthcare costs are created equal. For many, health-plan management falls outside standard business supply chain cost-control strategies. So, shift perspectives: Negotiate the highest utility for every dollar invested in the healthcare supply chain. Hospitals, outpatient surgery centers, physicians and pharmacy account for more than 90% of claims, and all can be negotiated. Successful cost reductions must focus on four areas: wasteful spending, excessive fees, poor quality and non-transparent pricing. Who in his right mind would shop at a grocery store and fill up two carts, then leave knowing he’ll receive a bill 30 days later and only then be told how much everything costs? Well, that’s how most healthcare works. 4. Not involving senior executives. I always ask CFOs: "Which two 'best practices' are most effective in reducing the frequency and severity of your claims this year?" The CFO soon realizes that, despite a legacy of best practices, there has been negligible improvement, with millions left on the table. The CFO must be directly involved and recognize that healthcare investment is a capital allocation strategy—it requires the supervision of an executive with P&L responsibility. 5. Not knowing what you’re paying for. Most CFOs don't know whether their company’s medical plan pays retail, wholesale or institutional charges. Like with a 401k, it's a CFO's fiduciary responsibility to know the healthcare broker's and consultant’s total compensation. It’s imperative to ask the right questions to uncover where your dollars are going. Familiarize yourself with fees, commissions, bonuses, overrides, incentives, profit sharing, contingent fees, expense reimbursement allowances or performance-based compensation—because they all add up. See also: Healthcare Debate Misses Key Point   Being uninformed can cost your company a lot of money, or worse. When explaining in court that you consistently supervised and overpaid by as much as 10x for a poor-performing, low-quality medical plan, ignorance is no defense. So there you have it: five common mistakes to avoid when buying healthcare. Take ownership, talk to an expert and educate yourself on sourcing the best solution for your company. You really can’t afford not to.

Craig Lack

Profile picture for user CraigLack

Craig Lack

Craig Lack is "the most effective consultant you've never heard of," according to Inc. magazine. He consults nationwide with C-suites and independent healthcare broker consultants to eliminate employee out-of-pocket expenses, predictably lower healthcare claims and drive substantial revenue.

Chatbots and Agents: The Dynamic Duo

Just 42% of insurers support a seamless user experience. They need to emphasize their omnichannel offerings, like chatbots.

Just like Batman and Robin, strong teams are made up of complementary partners. In the insurance world, this partnership is often the human agent and a technology counterpart. Take a Geico agent and the virtual assistant Kate. Kate’s AI-enhanced offerings and "always on" abilities serve as the perfect sidekick to the local insurance agent. As customer expectations have evolved, the insurance industry has had to change along with it. We’ve seen this with the rise of digitally native insurance companies like Hippo that streamline the application and sign-up process for homeowners insurance, as well as with more traditional organizations like Amica Insurance, which is revamping its digital strategies by working with IBM to give adjusters stronger tools to fulfill routine tasks. See also: Hate Buying? Chatbots Can Help   Today, anything short of a flexible, convenient and digitally mature experience is behind the times. It’s important for insurance companies to recognize that, given these advances and the diverse needs of policyholders, they will need to scale their offerings and implement more advanced services to support human agents. Though humans will never be replaced by chatbots, chatbots’ unique ability to personalize and automate processes has enormous potential in enhancing the relationship between the insurer and the policyholder. How Can Chatbots Enhance the Insurance Experience? Customers are becoming more and more comfortable with user interface (UI) technologies like Amazon Echo and Google Home and are exhibiting a more diverse set of expectations for digital capabilities in every facet of their lives. Chatbots can help supercharge insurance organizations with their ability to simplify everyday tasks. These virtual assistants have the potential to enhance efficiencies for both the insurer and the policyholder, especially when it comes to researching offerings, purchasing a policy and filing an insurance claim. Policy Exploration Researching different insurance policies can be a daunting task. It’s difficult for buyers, especially first-timers, to know what the best policy might be for their needs and budget. When looking at the insurance equation from the top of the funnel, chatbots have the potential to help win a customer’s business with their intuitive interface and educational support. Getting the right information up front is important for customers so that they aren’t surprised by anything down the line. Chatbots can process data at extraordinary speeds and help to make sure that customers are getting the right policy and the necessary information so they feel comfortable with their purchase. With the ability to quickly scan through the wealth of information on the internet and recognize user patterns, chatbots can ensure that policy offerings are accurate and tailored to the needs of the customer, helping insurance organizations make a great first impression. Purchasing When it comes to purchasing a policy, the process can be clunky, filled with unfamiliar industry jargon and massive amounts of paperwork. Chatbots can make the quote process much smoother for buyers by helping customers quickly navigate the intricacies of the buying process, while also simplifying it by auto-filling difficult questions with the assistance of third-party sources and natural language capabilities. Insurers are freed to work on more complex customer needs and issues without being bogged down by endless amounts of paperwork, leading to greater internal efficiencies. Claims and Payments The situations in which policyholders file claims don’t always happen within traditional business hours. The 24/7 nature of chatbots makes sure that customers have access to assistance when they need it, whether that means information about their policy or guiding them through what to do in the case of a car accident. The payment and claims process typically involves multiple steps, and the automated nature of chatbots can help streamline this experience in a way that helps both insurers and policyholders. A large number of calls that policyholders make to their insurance organization are about the claims process. Chatbots can field these calls and provide users with a complete look at the status of their claim in real time, just as if they were tracking a UPS package. Given that calls are typically about the status of a claim, chatbots are particularly good at fielding them because they can access this information within their database. See also: How Chatbots Change Open Enrollment   Looking Forward The insurance industry still needs a drastic digital transformation as it migrates from policy-centric strategies to more customer-centric ones. In addition to updating their technology, insurers need to shift their antiquated mindsets and processes toward innovation, especially as younger generations with higher digital standards gain greater purchasing power. If these organizations want their digital transformation to be sustainable, they’ll need to integrate digital mindsets throughout the culture of their organization, making sure everyone understands the value of digital investments and will continue to implement them. As it stands, just 42% of insurance organizations support a seamless user experience. If insurers want to satisfy users, they’re going to need to emphasize their omnichannel offerings, like chatbots, to create a solid foundation for further technology advancements. As the needs of the digitally savvy consumer become increasingly important, each insurance company will need to figure out how to stay relevant to this new generation, and having a chatbot by their side is a step in the right direction.

John Cammarata

Profile picture for user JohnCammarata

John Cammarata

John Cammarata is the insurance transformation leader at PointSource. As the lead for architecture and development at PointSource, Cammarata is continually identifying ways that technology and digital engagement patterns are the catalysts behind disruption in the insurance industry.

U.S. Insurance Deals: Insights on First Half

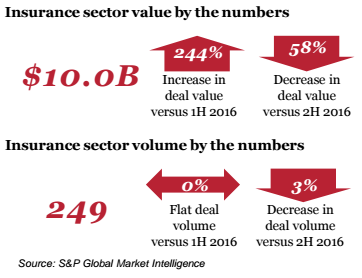
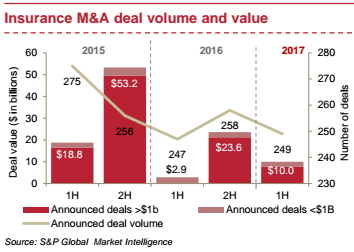
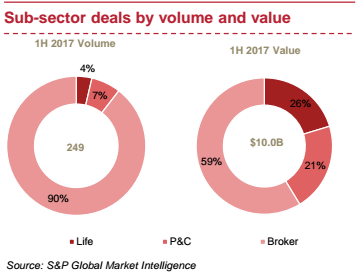
Deal value in the U.S. insurance sector more than tripled to $10 billion in the first half of 2017, compared with $2.9 billion in the first half of 2016.

|||||
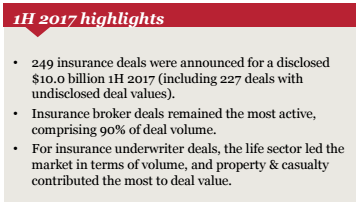
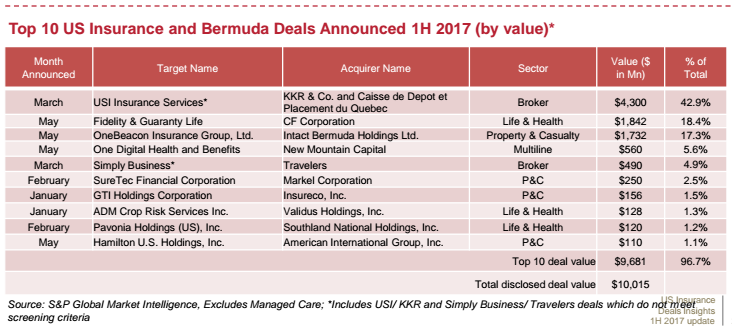
The U.S. insurance sector announced that deal value has more than tripled to $10 billion in the first half of 2017, compared with $2.9 billion in the first half of 2016. Activity remains robust in the brokerage sector. The largest announced deal in the period was the acquisition of insurance broker USI by an investor group including private equity firm KKR and Canadian pension fund CDPQ for $4.3 billion. Among insurers, megadeals have been affected by uncertainty in terms of the direction of tax and regulatory reforms, although some clarity has come by way of the implementation of the Department of Labor’s fiduciary rule. A healthy appetite for deals should continue in the second half of the year as insurers seek to divest capital-intensive or underperforming businesses, and newly funded PE-backed insurers continue to pursue U.S. insurance sector assets. Highlights of 1H 2017 deal activity Evolving nature of deals in 1H 2017 There were only three announced deals valued in excess of $1 billion, amounting to a total of $7.8 billion, in the first half of 2017:
  • An investor group including private equity firm KKR & Co. and Canadian pension fund CDPQ completed a $4.3 billion acquisition of USI Insurance Services from Onex.
  • In a separate deal announced in June 2017, USI agreed to acquire Wells Fargo Insurance Services in a transformational transaction. Terms were not disclosed.
  • In May 2017, a special purpose acquisition company, CF Corporation, including funds affiliated with Blackstone and Fidelity National Financial, announced a $1.8 billion acquisition of annuities and life insurer Fidelity & Guaranty Life. The transaction followed the lapse of Anbang Insurance Group’s agreement to acquire U.S. Fidelity & Guaranty Life after failing to secure the necessary regulatory approvals.
  • Canada’s largest P&C insurer, Intact Financial, acquired specialty insurer OneBeacon from White Mountains for $1.7 billion.
See also: Insurtech: How to Keep Insurance Relevant   Other significant deals emphasized interest in expanding digital capabilities, specialty offerings and small- to middle-market presence, as well as focus on managing capital, including:
    • An investor group including New Mountain Capital LLC, Achilles Acquisition LLC, acquired small to mid-size employee benefits agency One Digital Health and Benefits for $560 million.
    • Markel Corporation acquired SureTec Financial Corporation for $250 million and renamed its specialty and U.S. insurance segment Markel Surety Corporation.
Deals that did not meet our S&P screening, but are notable for their scale or intent, include:
  • Travelers announced the purchase of U.K.-based Simply Business, a digital commercial broker, for $490 million.
  • Aegon (Transamerica) offloaded its two largest U.S. run-off businesses, payout annuities and bank-owned/corporate-owned life insurance to Wilton Re via reinsurance.
Key trends and insights Sub-sector highlights
  • Life and Annuity: The sector has been suffering through a persistent low-interest-rate environment that has weighed on insurers’ investment portfolios. Nevertheless, the U.S. Federal Reserve has raised the fed funds rate two times this year, and there are signs that other central banks are considering tighter monetary policies as inflation increases. Opportunities remain for insurers to exit capital-intensive or non-core businesses, with continuing investor interest in closed blocks and narrow concentrations. In a recent reinsurance deal, Canadian pension owned Wilton Re acquired two run-off blocks (annuities and COLI/BOLI) from Aegon/Transamerica.
  • Property & Casualty: Deal activity declined in the first half of 2017, as companies continue to manage macro pressures. However, opportunities remain for small to medium-size companies to build much-needed scale through consolidation.
  • Insurance Brokers: The segment continued to be the most active in terms of deal volume in 1H 2017. The most activity came from several serial acquirers buying regional brokers, further consolidating the market. The five most active acquirers were Hub International, NFP, Arthur J. Gallagher, AssuredPartners and Acrisure.
See also: Insurance Coverage Porn   Conclusion and outlook Even though announced deals have been light in the first half of 2017 compared with the second half of 2016, activity should intensify in the remainder of 2017 as insurers focus on cutting costs, achieving scale and enhancing and streamlining or consolidating dated technologies.
  • Macroeconomic environment: The muted economic recovery, persistent low interest rates and geopolitical uncertainty continue to constrain insurers’ revenues and profitability. Life insurers have used both divestitures and acquisitions to manage the low-return environment and transform business models.
  • Regulatory environment: Increased oversight and uncertainty have heavily influenced insurers’ business models and strategies, forcing many to exit businesses, often through divestiture. The current presidential administration appears to favor the easement of certain regulations, which could be a positive for insurers subject to the SIFI rule. Furthermore, the U.S. Department of Labor Fiduciary Rule has officially gone into effect, which may have implications for insurers that use exclusive agents.
  • Technology: Insurers have been slower to adopt new technologies compared with banks and other financial services companies. But the times may be changing; insurers are increasing technology investments, including the recent acquisition of Simply Business by Travelers.
  • Asian inbound interest: The past several years have seen Asian firms expand their footprint in the U.S. insurance market. While Asian investors maintain a global appetite, regulatory and shareholder skepticism remains a hurdle. A bid by Anbang to acquire Fidelity and Guaranty fell through in April, and China Oceanwide’s acquisition of Genworth has yet to close and is facing a new CFIUS review.
  • Canada, too: Closer to home, there is evidence of increased appetite from Canadian buyers. In the first half of 2017, the second largest pension manager in Canada teamed up with KKR & Co. to acquire broker USI Insurance Services, and the largest P&C insurer in Canada, Intact Financial, acquired specialty insurer OneBeacon.
  • Public offerings: Several major global insurers have responded to the low-growth environment in the U.S. with significant divestitures or restructuring. After receiving final approval in June, MetLife plans to spin off its U.S retail business, the new Brighthouse Financial, in August. A.XA announced in May its intention to exit its U.S. operations in a 2018 IPO. There is market speculation that other large insurance companies have similar divestiture or restructuring plans.
  • Private equity/Hedge Funds/Family Offices: Insurance brokerage has historically been the most active insurance subsector for private equity given the limited regulatory environment, straightforward operating model and attractive, leverageable cash flows. However, private equity firms have been entering the life and annuity market with confidence that they are better investment managers than insurers.

John Marra

Profile picture for user JohnMarra

John Marra

John Marra is a transaction services partner at PwC, dedicated to the insurance industry, with more than 20 years of experience. Marra's focus has included advising both financial and strategic buyers in conjunction with mergers and acquisitions.

Essential Elements on School Risk Control

Risk management is ever-changing and evolving in K-12 schools. It is vital to stay on top of emerging issues.

At the 2017 annual PRIMA conference, Ariel Jenkins and Kevin O’Sadnick of Safety National led a conversation on the essential elements of school risk control programs. School visitor management consists of entrance hardening (add extra set of doors or windows, and visitors have to check in), criteria for visitors (parents, teacher visitors and grandparents), 100% use of photo ID for staff/visitors and use of security cameras. Violent, Combative and Disruptive Students De-escalation/assault cycle training should be able to recognize this behavior and early intervention and keep an event from getting out of hand. There need to be clear protocols that consist of restraint training and use of school resource officers. Violence against teachers needs to be reported and documented. See also: Future of Insurance: Risk Pools of One   Active Shooter Event Effective methods to reduce active shooters events are visitor screening procedures, school/district website content, training for staff (Run,Hide, Fight method), and lockdown procedures (general or emergency lockdown). Post-incident procedures include an emergency communication (is there a procedure in place and specific to each event?), PR/news/press releases and crisis and grief counseling. Controlling Special Education Risks
  • 46% alleged discrimination against students with disabilities
  • Claim of not receiving “free appropriate public education”
  • Increased complaints related to retained and isolation
Is a special education teacher considered a high-risk job? Yes. There is more emphasis on motor skills learning activities. A student-assisted transfer requires hands-on physical assistance to move a student. The risk of these are biting, hitting and back injuries. The transfers are not normally voluntary. In a school setting, the safe patient handling policy should address the use of mechanical devices to the place of manually lifting and transferring students with disabilities. Training in positive behavior management and de-escalation. For a lift policy, best practices is 30 to 35 pounds maximum lift without equipment and no two-person lifts or transfers without using equipment. If a student cannot safely, reliably and cooperatively stand and pivot for a student-assisted transfer, use adaptive mobility devices. Social Media and Bullying There are different measures and different trends we can look at to create student and teacher interaction policies. Make sure to document any instances that occur. There are outside vendors that have training for monitoring social media. There need to be consequences and repercussions for bullying and social media intimidation. These policies and procedures need to be shared with parents. See also: Space, Aviation Risks and Higher Education   Risk management is ever-changing and evolving in K-12 schools. It is vital to stay informed and stay on top of emerging issues that can affect the safety of the staff and students in your school districts. It is important to create policies and procedures to ensure the safety of all involved.

3 Innovation Lessons From Jeff Bezos

In baseball, an at-bat's success is capped at four runs. In business, "every once in a while you... hit the ball so hard you get 1,000 runs.”

|
Jeff Bezos just became the world's richest man. His creation, Amazon, is an incredible company. The consistency and breadth of innovation it has produced over the past two decades is awe-inspiring. Bezos is undoubtedly the force behind this relentlessness, and I find him fascinating to listen to and study. In the following 38-minute interview, he gives us a compelling glimpse into the mindset he’s created at Amazon that underpins its success. Some of the points struck a chord with me, so I’ve made a short summary below. The 3 principles of Amazon People see Amazon differently. Is it an e-commerce site, a retailer, an innovative tech company? Its products and services range from cloud computing, original content, direct publishing platform, Alexa and many other things. So how should we think about Amazon? Bezos sees Amazon more as an approach:
“We have a very distinctive approach that we have been honing and refining and thinking about for 22 years. It’s really just a few principles that we use, as we go about thinking through the different activities we work on.”
See also: Time to Rethink Silicon Valley?   Those few principles are: 1. Customer obsession This is the fundamental driving force behind Amazon’s business. Instead of, say, a competitor obsession, technology obsession or product obsession model. These other models can work just fine. A competitor obsession can be a very good strategy for some companies: You have to watch your competitors very closely. If they latch onto something that’s working, you duplicate it as quickly as possible. It means you don’t have to be a pioneer, and you don’t have to venture down many blind alleys. But there are disadvantages, and the customer obsession model is the one Bezos believes is right for Amazon, in combination with the following two principles. 2. A willingness, or even an eagerness to invent and pioneer This marries very well with the customer obsession. According to Bezos, customers are always dissatisfied, even when they think they are happy. They actually do want a better way; they just don’t know what that way should be yet. Customer obsession is not just listening to your customers, but it means inventing on their behalf. It’s not their job to invent for themselves, you must be the inventor and the pioneer for them. 3. Long-term oriented Bezos encourages his employees not to think in two- to three-year timeframes, but in five- to seven-year timeframes. People often congratulate Bezos on quarterly results, but for Bezos these results were actually baked in about three years ago. Today, he’s thinking about a quarter that’s going to happen in 2020. Next quarter, for all practical purposes, is probably already done and has been done for a couple of years. But the long-term mentality is not a natural way for humans to think. Bezos believes it’s a discipline that you have to train and build for.
“If you start thinking this way, it changes how you spend your time, how you plan, where you put your energy. Your ability to look around corners improves. Many things just get better.”
In conclusion, Amazon is an approach and a collection of principles that they embed into how they think and work. Failure and the importance of experimentation Despite being the world's richest person, and Amazon being wildly successful, what keeps Bezos sharp and focused? It’s the fear of Amazon losing its way in one of the key areas mentioned above. Or that they become overly cautious, or failure-adverse, and therefore become unable to invent and pioneer.
“You cannot invent and pioneer if you cannot accept failure. To invent, you need to experiment. If you know in advance that it’s going to work, it is not an experiment.”
Failure and invention are inseparable twins. But it’s embarrassing to fail. If you have a 10% chance of a 100x return, you should take that bet every time, but you will still be wrong nine times out of 10, and you’ll feel bad about every one of those nine failures, even embarrassed. Overcoming this fear is vital, particularly in the technology business. In technology, the outcomes can be very long-tailed, with an asymmetric payoff. This is why you need to do so much experimentation. As an illustration:
“In baseball, everybody knows that if you swing for the fences, you hit more home runs, but you also strike out more. But baseball doesn’t go far enough [as an analogy for technology]. No matter how well you connect with the ball, you can only get four runs. The success is capped at those four runs. But in the technology business, every once in a while you step up to the plate, and you hit the ball so hard you get 1,000 runs.”
This asymmetric payoff makes it obvious to experiment more, increasing the chances of that 1,000-run hit. It’s important to make this distinction on failure, though: The right kind of failure is when working on an invention, an experiment that you cannot know the outcome of. The wrong kind of failure is when you have some operational history in the task, where you know what you’re doing, but you just screw it up. This is not a good failure. An example from Bezos:
“We’ve opened 130 fulfillment centers now; we’re on the eighth generation of our fulfillment center technology. So if we opened a new center, and just messed it up, that’s not an experiment, that’s bad execution.”
Defining your big ideas Any entrepreneur, organization or governmental institution should identify their big ideas that encapsulate what they’re trying to do. There should only be two or three of these big ideas. The main job of a senior leader is to identify those important ideas, and then to enforce great execution on them throughout the organization. The good news is that the big ideas are usually incredibly easy to identify, and in most cases you’ll already know what they are. For Amazon’s consumer business, the three big ideas are:
  • Low prices
  • Fast delivery
  • Vast selection
“How do we always deliver things a little faster? How do we always reduce our cost structure, so that we can have prices that are a little lower?”
See also: The Key to Digital Innovation Success   The big ideas are stable. They will most probably be the same in 10 years. Customers will still like low prices and faster delivery. No matter what happens with technology, these things will still remain true.
“When you have your big ideas, you can keep putting energy into them. You spin up flywheels around them, and they’ll still be paying you dividends 10 years from now."
Bezos also discusses machine learning, renewable energy and space exploration, but not once in the entire discussion does he mention the word "innovation." A reminder that those who really do innovate don't talk about innovation.

Tim Woods

Profile picture for user TimWoods

Tim Woods

Tim Woods is vice president of marketing for HYPE Innovation. With a background in software development, Woods has worked for more than a decade on software and services solutions that support the innovation initiatives of some of the world’s largest organizations.

Autonomous Vehicles: Truly Imminent?

Are autonomous vehicles inevitable? Probably. Are they imminent? Probably not, at least on a widescale basis.

sixthings
Just from casual observation, if “disruption” is the hot topic in industry media, self-driving or autonomous vehicles might not be far behind. I’ve read predictions that a proliferation of autonomous vehicles will be among us (or vice versa) in five to 10 years. Is that likely? I have my doubts, though I’m increasingly persuaded that the day is coming, even if it’s not clear how or to what extent the transition to autonomous vehicles will transpire and what impact it might have on our industry. Fortune magazine published an article titled, “What’s Taking So Long for Driverless Cars to Go Mainstream?” The article notes that “significant technical challenges remain unsolved" but opines that “societal friction” will be the greatest impediment to adoption, delaying full autonomy “for at least a decade.” I think that length of delay is highly optimistic. There is a LinkedIn discussion about this here if you want to join the dialog. The article discusses three societal impediments that could slow adoption:
  • Ethics. If the vehicle recognizes that a wreck cannot be avoided and the choices are limited to running off a cliff and killing the vehicle occupants or ramming through a crowd of children, how will that decision be made, and who is going to be legally responsible for the consequences, if anyone?
  • Job Losses. The article says there are four million jobs involving the transportation of people and property, not counting all of the support positions, along with other businesses that are transportation-related and dependent on human operators.
  • Hacking. What are the possibilities of “weaponizing” wired vehicles? I’ve been writing about this for several years. Given the media attention to hacks of wired vehicles already taking place to illustrate vulnerabilities, what would happen if terrorists hacked into a gasoline tanker truck and sent it at 70 mph into an elementary school? With the “Internet of Things” (perhaps #3 on the list of industry hot topics), we well know the many vulnerabilities of everything from smart phones to internet-connected HVAC controls.
These are just three among many, many issues that must be addressed before ANY significant autonomous vehicle traffic is permitted. The article also cites reports that an Uber driverless vehicle ran a number of red lights last year. Aside from the loss potential, when that happens, who gets the law-enforcement citation? The vehicle? If someone is injured or property is damaged, who gets sued? Today, the vast majority of claims are due to driver error. When the inevitable autonomous vehicle claims occur, who gets sued…fleet owners, vehicle manufacturers, mechanics, software programmers or others we can’t even conceive of now? How will this change our legal system? See also: Driverless Vehicles: Brace for Impact   Another article that challenges predictions that we are no more than a decade away from significant autonomous vehicle use is “Self-Driving Cars: Flawless Ride? Carmageddon?” Questions it raises include: Does the entire roadway system need to be re-engineered to accommodate both autonomous autos and human-operated autos? How will millions of miles or roads and an inventory of conditions, signs, laws and special situations be kept up to date and communicated to vehicle systems? How will decisions be made when accidents are inevitable? What about software bugs? Questions I’ve raised in past writings include: How will an autonomous vehicle “know” that a traffic light is out? How will it detect a red light if the direct glare of the setting sun washes out the color? Will traffic equipment need to be re-engineered, and at what cost? How will it be tested and maintained? How will driverless vehicles respond to unanticipated road construction or weather conditions? How will they respond to circumstances not contemplated by their programming? With regard to software bugs, “rebooting” your car, unlike your PC or tablet, while moving at 70 mph may not be an option. Fellow insurance nerd Mike Edwards told me about driving through his neighborhood one day and noticing, by glancing under the chassis, several sets of little feet behind a mini-van parked in a driveway near the street. Although the posted speed limit was 30 mph, he slowed almost to a stop just in case a child ran into the street…which happened. Fortunately, he was able to just stop in time. Could an autonomous vehicle be programmed with that kind of awareness? I’m certainly not an expert, but I have my doubts. Multiply this kind of incident several million times a year. Finally, one of the more interesting commentators on autonomous vehicles is Thomas Frey, futurist at the DaVinci Institute and, according to his bio, Google’s top-rated futurist speaker. Here is a LinkedIn Pulse article he wrote: “25 Shocking Predictions About the Coming Driverless Car Era in the U.S.” His predictions include four million autonomous cars replacing 50% of all commuter traffic. In a city of two million people, only 30,000 autonomous cars might be sufficient to handle transportation needs. It’s still not clear to me how 150,000 people leaving the vicinity of an Ohio State vs. Michigan football game will be able to access a limited number of largely single- or dual-passenger autonomous vehicles in Columbus or Ann Arbor. I’m not even convinced that autonomous vehicles can effectively handle rush hour transportation without there being tens of thousands of vehicles idle during non-peak hours. Will people willingly share vehicles with strangers at close quarters, and how might that contribute to crimes against persons? Will people be OK with taking twice as long to get somewhere with slower traffic and possibly multiple drop-offs like airport shuttles today? Under most current laws, as much as 40% of state and local sales taxes could be lost if individual auto sales become a thing of the past…what are the funding alternatives? The same issue surrounds state and federal fuel tax revenue. Remarkably, Frey predicts that, within 30 years, fully 25% of current jobs will be lost due to autonomous vehicles (e.g., he says 80% of police manpower goes to traffic control and will largely be unnecessary). New York City would allegedly lose more than $2 billion in income from traffic fines alone. Airport revenues would plummet, given the claim that 41% of it comes from parking and ground transportation fees. On the upside, according to the author, we would save $500 BILLION annually in healthcare costs (though two other sources site the negative impact of fewer organ donations due to fewer auto accidents). The list, good and bad, goes on and on…take a look at his predictions at the link above, including one for the insurance industry. Are we moving not to a “sharing” economy but to a “hiring” or “renting” economy where there is little in the way of ownership of high-ticket items like homes or autos? Perhaps, though I’m not sure any of us can predict what is going to happen with any degree of certainty or say how soon it will happen. The closest large-scale implementation of semi-autonomous vehicles so far is probably our aviation system. Air transportation is highly automated, from take-off to landing, but the pilot(s) are able to take control if necessary. Even so, traffic control of aircraft is only marginally automated. Humans often prevent tragedy through the oversight, coordination and intervention of air traffic control centers all over the country with individual aircraft. This system has demonstrated itself to be quite effective, given the very low incidence of casualties associated with commercial flight. See also: The Evolution in Self-Driving Vehicles But this centralized, coordinated control aspect may be largely responsible for the success of the system. Unlike autos, no one is currently advocating that individual aircraft become autonomous. That’s interesting given that the number of aircraft in the air at any given time is tiny compared with the number of vehicles on the road, and probably no one would argue that there are a lot fewer structures and people to hit in the sky vs. a congested city. So, what makes the pundits believe that tens of thousands of individual autos can coordinate themselves effectively without some sort of centralized control or the ability to communicate between each other? Currently, when a driver makes a mistake or wrong decision, the adverse results are limited to a single accident, usually with one or a few vehicles involved. If a programmer makes a mistake or wrong decision, the adverse results could be astronomically higher. Are autonomous vehicles inevitable? Probably. Are they imminent? Probably not, at least on a widescale basis. What do you think? As always, feel free to add your thoughts in the Comments section below.

Bill Wilson

Profile picture for user BillWilson

Bill Wilson

William C. Wilson, Jr., CPCU, ARM, AIM, AAM is the founder of Insurance Commentary.com. He retired in December 2016 from the Independent Insurance Agents & Brokers of America, where he served as associate vice president of education and research.

What Makes U.S. Healthcare Different?

The need for freedom of choice has limited the effectiveness of care management programs and produced expensive healthcare.

|
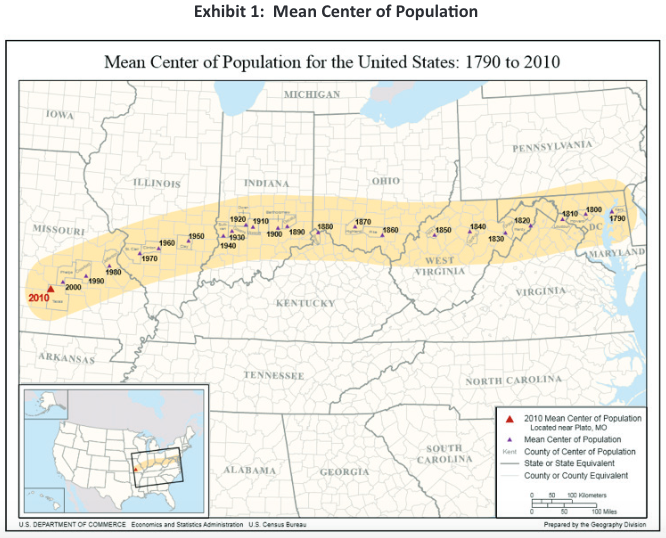
We in the U.S. spend a lot on healthcare. Whether expressed as the cost per service, the cost per person or as a percentage of the gross domestic product, the high cost of healthcare is well documented. While solutions to this situation have been suggested for many years, the expensive reality continues. Is it possible that unique characteristics of the American healthcare environment create special challenges? This article discusses several unique aspects. Geographic Diversity The U.S. is a diverse country with population centers scattered throughout the country. The mean center of population currently lies in Missouri. As the inset map shows, this is east and south of the geographic center of the U.S. The major population centers in the eastern half of the country pull it east. The major population centers in the south pull it south. More than 10% of the population is in one major southwestern state, California. Major metropolitan areas can be found throughout the country: San Francisco and Los Angeles in the Southwest, Dallas and Houston in the south Midwest, Chicago in the upper Midwest, Boston and New York in the northeastern part of the country, Atlanta and Miami in the Southeast. Why is this important? More than 90% of the Canadian population lives within 100 miles of the U.S. border. The oft-touted Canadian system serves a population that is concentrated in a thin band of land. In a concentrated environment, it is possible to have a more efficient allocation of resources. In the Canadian provinces with significant rural populations (e.g., Alberta and Saskatchewan) the provinces use regional health authorities to take responsibility. See also: A Road Map for Health Insurance   American Definition of Quality Quality is difficult to universally define. Many times people say, “I know it when I see it” or, more importantly “I know it when I don’t see it.” Over the past 15 to 20 years, quality has been objectively defined, to the point that it is consistently measured across health systems. One of the best definitions of quality is “providing the right service, at the right time, to the right patient as efficiently as possible.” The American definition of quality usually includes a high degree of access and a significant sense of urgency. Other countries do not see waiting as a deterioration in quality. In fact, queuing, or waiting lines, are accepted. The American ideal is getting healthcare now, not tomorrow, not next week or next year. Most Americans see waiting as a reduction in quality. Health systems that require pre-authorization or approval of referrals are frequently viewed as substandard because those systems create barriers that patients have to work through. In countries with socialized healthcare systems, patients regularly have to wait. Much of this wait is associated with fiscal limits within the system restricting the available resources. In the U.S., the excess capacity in the system almost always provides an adequate supply of healthcare resources, so the required waiting time is very limited. The waiting line is caused by either quotas or specific budgets for specific procedures, producing a rigid form of rationing. In the U.S., waiting occurs when the physician was booked or the schedule was full. This queue is not a budget-driven constraint. The U.S. healthcare system is recognized as one of the highest-quality in the world (e.g., high cancer screening rates). Although the quality of care is generally quite high, some of the measured outcomes suggest that the U.S. health system is not advancing as much as would be hoped. One example is the efforts to eliminate breast cancer. Screening for breast cancer is higher than it has ever been, but so is the rate of breast cancer. Perhaps improved detection has identified more cases. Freedom of Choice Americans value freedom of choice; they like to make decisions for themselves. Americans value going where they want to get care, choosing who they want to provide that care, oftentimes deciding what care they want and getting it when they want to get it. This has resulted in broader networks offering more choices than needed. This has resulted in higher-than-necessary utilization of specific services, including new technology. The need for freedom of choice has limited the effectiveness of care management programs. Freedom of choice combined with limited cost sharing results in expensive healthcare. One unfortunate consequence is the negative opinion that develops regarding any administrative process that limits freedom of choice. Programs that focus on limiting medically unnecessary care are accused of disrupting the physician/patient relationship. Healthcare Resource Planning In most states, there is very limited overall resource planning. At various times, some states have implemented certificate of need programs for specific types of providers. But, for the most part, there are no formal limits to the number of providers or types of providers. In most urban markets, there is an oversupply of providers. Rural markets are often plagued with a shortage. Some markets are so desperate for providers that significant compensation is offered to lure them. Why is this important? Healthcare tends to be a market that fails to respond to traditional supply and demand economics. In the general economy, the greater the supply, the lesser the demand and the lower the prices. In healthcare, the higher the supply, the greater the induced demand and the continuation of higher prices. Informal studies suggest that utilization levels positively correlate with supply. One of the reasons for escalating costs is the continued oversupply of healthcare providers. One of the best examples of effective resource planning is the approach implemented by Kaiser Foundation Health Plan. Kaiser carefully plans the supply of professional services based on a long-established staffing model. As the associated membership grows, they move from a combination of “nearby owned facilities” and “rented facilities” to “owned facilities.” Kaiser carefully manages the strategic transition to a “wholly owned delivery system” and manages the resources based on membership growth. Kaiser avoids excess capacity and maintains a cost-effective delivery system. Countries with socialized healthcare systems are much more involved with resource planning than the U.S. The competitive nature of healthcare in the U.S. is much more focused on capturing market share than defining appropriate resources for a region. Less effective resource planning drives up the cost of care. Wide Variations in Efficiency The efficiency of regional healthcare systems varies significantly from one geographic market to another. Delivery system care patterns have emerged based on local needs, regional care practices and the extent of provider involvement in the financing of care. Markets like Portland, OR, have developed extremely efficient in-patient care patterns with a larger portion of their healthcare dollar going to professional providers. Other markets have emerged at the same time with much less efficient patterns. In-patient utilization patterns vary by more than 35% to 45%. Analyses show no clinical rationale to support the observed variation. The U.S. is one of the few countries exhibiting this level of variation. Experts generally concur that much of this variation is caused by personal physician preference. Tax-Sheltered Benefits The current tax-sheltered employee benefit approach emerged during the post-WWII era where employers were seeking creative ways to attract, hire and keep employees. The tax law enabled employers to write off the cost of benefits and provide their employees a valuable tax-sheltered employee benefit. The tax law provides this favorable status only to employer-sponsored programs. Individual health insurance benefit programs do not enjoy this same tax advantage. Tax reform efforts have considered eliminating this difference. Self-funded employer-sponsored benefit programs, including those involving labor union negotiations (i.e., Taft -Hartley plans) are also tax-advantaged. This is an important issue when discussing transitions to alternative systems. What role will employers play? What about programs negotiated by labor unions? How will we unravel the tax-advantaged funding of healthcare costs by the employer? Diverse Insurance and Claims Administration The employee health benefit marketplace has grown significantly with a large variety of organizations targeting the effective administration of such programs. Merger/acquisition activity has transformed the marketplace into a handful of major players and a large number of regional players. Third party administrators (TPAs) are active in the market supporting the self-funded and self-administered benefit programs. The federal government provides government-sponsored coverage for the elderly and disabled (Medicare) and for beneficiaries in lower socio-economic levels (Medicaid). Many of these programs outsource the administration and risk taking to the private sector. Healthcare administration in the U.S. includes a significant private sector involvement. There is little uniformity between different health plans. There are limited standards to streamline the process. Public/Private Sector Cost Shift The U.S. healthcare system incorporates a significant cost shift between the government-sponsored programs and the private sector programs. The private sector pays a much higher amount for identical services than the public sector. Within the private sector, each carrier/health plan is required to negotiate payment rates, which can vary substantially from one carrier to the next. The variability in reimbursement increases administrative costs for both the providers and the health plans or administrators. See also: Healthcare Debate Misses Key Point   Hesitancy to Declare Healthcare a Human Rights Issue In the U.S., there has been a hesitancy to declare healthcare a human rights issue. In Canada, the Canada Health Care Act defines five principles:
    • Public Administration: All administration of provincial health insurance must be carried out by a public authority on a non-profit basis.
    • Comprehensiveness: All necessary health services, including hospitals, physicians and surgical dentists, must be insured.
    • Universality: All insured residents are entitled to the same level of healthcare.
    • Portability: A resident who moves to a different province or territory is still entitled to coverage from the home province during a minimum waiting period. This also applies to residents who leave the country.
    • Accessibility: All insured persons have reasonable access to healthcare facilities. In addition, all physicians, hospitals, etc., must be provided reasonable compensation for the services they provide.
A quick internet review will show considerable discussion defending both opinions: It is a right, or it isn’t a right. Dominant emerging thought focuses on what is called Triple Aim: a strong focus on quality and customer satisfaction, improving the population’s health status and reducing costs of care. They are admirable goals, but all require the definition or identification of a population. Who is the population? Is it everyone? Is it just the segment I am concerned about? Recent healthcare reform efforts have focused on minimizing uninsured, which was a step toward universality. Ironically, the American’s demand for freedom of choice also includes freedom from being told that they must buy insurance and what kind of care they should pay for. Summary These nine issues provide an initial list of unique characteristics of the U.S. healthcare system. When working toward solutions to resolving the high cost of care, these issues must be considered. This is not an exhaustive list but does begin to highlight what makes American healthcare different.


David Axene

Profile picture for user DavidAxene

David Axene

David Axene started Axene Health Partners in 2003 after a successful career at Ernst & Young and Milliman & Robertson. He is an internationally recognized health consultant and is recognized as a strategist and thought leader in the insurance industry.

Six Innovators to Watch - July 2017

sixthings

We may be in the dog days of summer, but that doesn't mean that the insurtech world is taking a vacation. Far from it. Innovation is expanding so fast that we're now tracking nearly 2,000 companies on our Innovator's Edge platform. We realize that keeping up with such a profusion of companies, people and ideas is hard, so we're here to do whatever we can to help.

One tool that has proved popular is our monthly list of "Six Innovators to Watch." Here are the startups we've highlighted to date (March, April, May and June). And, here, now are the Six Innovators to Watch for July:

Casentric

Casentric works with property and casualty insurers to lower the cost of personal injury settlements through more accurate and balanced evaluations of the liability, pain and suffering, medical, wage and other components of a personal injury claim. The company has built intuitive, web-based software to guide adjusters to develop evidence-based critical analysis of claims, resulting in more accurate claims and reserves—and ultimately more consistent and predictable costs. Cleveland-based Casentric’s solution also generates data that can be used to identify trends and benchmarks for accuracy and consistency. Learn more about Casentric at: https://www.innovatorsedge.io/companies/casentric-llc

Click2Sure

Click2Sure is a South Africa-based innovator that saw an opportunity to embed the sale of insurance into online ecommerce platforms, making it simple and affordable to offer product coverage at point of sale for high-value products and services. Finding few insurers ready to participate in this new approach for one-click insurance, the company created a full-stack digital insurer to provide coverage administration, distribution, underwriting and claims and has secured participation from several reinsurers. Click2Sure is partnering with e-commerce companies, retailers and online service providers to deliver its solution in Africa and looking to expand in South America and Asia. Learn more about Click2Sure at: https://www.innovatorsedge.io/companies/click2sure

DataRobot

DataRobot wants to make machine learning a core competency of insurance companies. The Boston-based company provides a platform designed to help insurers unleash the power of A.I. through automation of data modeling. Incorporating a library of hundreds of the most powerful open-source machine learning algorithms, the DataRobot platform provides the fastest path to A.I. competence for organizations of all sizes, helping operating teams find useful information in their data. Founded by insurance analytics veterans, the company is helping companies develop models to analyze claims for fraud, automate risk analysis and provide claims triage, among other needs. For more information about DataRobot, visit: https://www.innovatorsedge.io/companies/datarobot

InsuredMine

InsuredMine offers a digital policy management tool for consumers to easily manage their various insurance coverages and interactions—renewals, premium payments, claims and more—and receive policy recommendations and information to make them a more informed customer with greater control over their financial protection. Dallas-based InsuredMine aims to deliver analytics that allow consumers to modify and update their coverage needs more quickly and receive competitive bids based on their previous coverages and buying habits. While designed to empower consumers, the technology also delivers data and insights to carriers and relies on insurance agents and brokers to deliver the solution to their customers. For more information about InsuredMine, visit: https://www.innovatorsedge.io/companies/insuredmine

QBIS Insurance Solutions

QBIS is focused on streamlining small business insurance, helping agents and brokers, MGAs and carriers better serve and engage with the digital customer of the future. Oakland, Calif.-based QBIS has created a virtual MGA to provide a business owners policy for agents and brokers placing small commercial risks, and has created a suite of software modules for MGAs and carriers that want a dynamic workflow to take new commercial insurance products to market in an engaging, customer-friendly way. The QBIS platform gives customers self-service capabilities, enables agents to create campaigns to promote the digital solution and allows underwriters to more easily access risk data to support underwriting decisions. To learn more about QBIS, visit: https://www.innovatorsedge.io/companies/qbis-insurance-solutions-inc

ROC Connect

ROC Connect offers a “smart home as a service” solution to insurers and other businesses that seek to harness the power of smart devices and get to market more quickly with IoT solutions. ROC Connect offers an interactive hub that consumers can use to manage all of their smart home devices and sensors, capturing information in the cloud and providing insurers with a tool to engage with customers, capture data and deliver new products and services that drive revenue. ROC Connect, based in Palo Alto, Calif., is currently working on a solution that would analyze smart home data to generate a safety score for a property, which could be used by insurers for better underwriting and loss prevention. Learn more about ROC Connect at: https://www.innovatorsedge.io/companies/roc-connect

The Innovators to Watch honorees are drawn from among the nearly 1,800 insurtech companies that are featured in Innovator’s Edge, a technology platform created by ITL to drive strategic connections between insurance providers and insurtech innovators. From this growing pool, only those companies that have completed their Market Maturity Review—a series of modules designed to help insurers conduct baseline due diligence on the innovator and make a more informed connection—are eligible to be considered for Innovators to Watch, helping them to stand out in this crowded diverse field.

Cheers,

Paul Carroll,
Editor-in-Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Is 'Connected Health' for Real?

A reduction in loss ratio of around 50% seems to be achievable through consistent and intelligent implementation of "connected health."

sixthings
"Connected health" might shape the future of healthcare and of health insurance. I define it as any insurance solution based on sensors for collecting data on the state of an insured risk and of telematics for remote transmission and management of the data collected. Connected health offers a great capacity to register, deposit and analyze data that comes from the users themselves, giving the insurer never seen before insight into actual behaviors and lifestyles. While “connected insurance” applies in many areas -- with auto insurance leading the way -- health insurance is a more delicate field that will probably face more obstacles on the road to a connected future. See also: Healthcare Needs a Data Checkup Insurance covers can be differentiated by client segments, and the insurer can propose different levels of assistance based on specific tools and services. Typical examples of health services are:
  • Medical contents in multiple formats;
  • Call center for emergencies;
  • Pharmaceutical products ordering and home-delivery;
  • E-health with specific devices for specific target patients (elder, heart problems and diabetes patients, etc.), including alerting on possible critical health conditions.
Furthermore, professional medical advice can be delivered in multiple ways (messaging, call, video). Discounted prices for doctors and medical structures can be proposed through a preferred network, while having the option of doing bookings and payments online. Another plus is to have one’s complete medical history stored in digital format to allow easy access. With the objective to push through the adoption of healthier behavior and raise engagement, solutions include: gamification based on wearables and tailor-made goals, wellness content in multiple formats and agreements with gyms, shops and other types of service providers. [caption id="attachment_27044" align="alignnone" width="570"] Source: Connected Insurance Observatory[/caption] Connected insurance in the health sector is affecting the whole insurance value chain and generating real value for the insurance P&L. According to Matteo Carbone, founder of the Connected Insurance Observatory, five main value creation levers emerge:
  • Risk selection;
  • Risk-based pricing;
  • Value-added services;
  • Loss control;
  • Loyalty and behavior “steering” programs.
Data collection can improve the overall quality of the underwriting process, allowing price adjustments or covenants. Devices can measure client behavior and collect data to customize covers and propose prices or discounts based on a one-to-one approach instead of a traditional approach based on averages. The ability to monitor the "quantity" and "level" of risk exposure is now possible and can be applied to the single customer. Value-added services have a double aim: on the one hand to guide clients toward desired behavior, on the other hand to offer services to clients. Some ancillary services are proposed to the insured clients to exploit relevant data detected; these services could be directly supplied by the insurance company or by means of an ecosystem of specialized partners. Connected insurance can enable the development of a more efficient and faster claims management processes, while limiting the portfolio loss ratio. Behavior programs use information gathered on the behavior of clients to direct them toward less risky solutions. A good reward system is a key, and programs based on innovative gamification approaches are a must, to keep clients engaged. [caption id="attachment_27045" align="alignnone" width="570"] Source: Connected Insurance Observatory[/caption] Experts estimate a huge potential reduction in loss ratio on medical reimbursement by implementing this innovative approach in health insurance. Starting from the current health losses on an average traditional portfolio, best practices show a potential saving of 20% by driving the choices of the insured within preferred networks of doctors and medical structures. The use of m-health tools can help lower claim costs by an additional 10%, while the implementation of loyalty and behavior “steering” can contribute a further 15%. In synthesis, a reduction in loss ratio of around 50% seems to be achievable with a consistent and intelligent approach in the implementation of these levers. Predictive and preventive alerts can potentially play a huge role, too, but that has still to be proven. See also: Unconnected World, and What It Means   Insurance companies should gradually move from their traditional positioning as health insurer of an ill person (playing the role of claims manager and expense payer) toward that of a 360-degrees health counselor aiming to insure lower risk and healthier customers with a customer-centric, tailor-made approach. Innovation should aim to transform the health insurance company from a simple payer to a player in the customer health journey. The industry has to move from a “cure” to a “care” approach. So, is connected health insurance any good? It is a win-win for both insurer and insured. The insurer optimizes internal processes and cuts costs while the insured has incentives to live a healthier life!

Andrea Silvello

Profile picture for user AndreaSilvello

Andrea Silvello

Andrea Silvello has more than 10 years of experience at internal consulting firms, such as BCG and Bain. Since 2016, Silvello has been the co-founder and CEO of Neosurance, an insurance startup. It is a virtual insurance agent that sells micro policies.

Will Brandless Become the Biggest Brand?

And could a platform-based company dominate insurance without holding any risk or employing any underwriters and adjusters?

sixthings

The platform economy is becoming a driving force of innovation and growth, as companies create digital platforms to enable interactions between individuals or businesses that need something and individuals or business that provide something. The “something” may be a product, service, money, labor or other asset of value.

The distinguishing characteristic of platform economy companies is that they generally have high market value while owning no assets and having few employees. The world’s largest movie house owns no cinemas (Netflix). One of the largest and most valuable retailers in the world owns no inventory (Alibaba). The largest personal transportation company owns no vehicles (Uber). The list could go on. Amazon, of course, has been the quintessential platform company, although its acquisition of Whole Foods now extends its capabilities beyond digital.

But there’s a new kid on the block of platform-economy companies, and that entrant is Brandless. What is its model? And what does the whole notion of the platform economy have to do with the insurance industry?

See also: Lessons From 3 Undisrupted Brands  

The Brandless Brand

Brandless is a new online grocery retailer with a simple value proposition. Every item for sale is three dollars. The company provides healthy, socially conscious options such as organic, gluten-free, vegan and environmentally friendly products, obtained by fair trade principles. Although the company is not selling name brand items like Amazon and other online retailers do, Brandless is nonetheless connecting suppliers that create the products to buyers that are looking for items with these characteristics. It could be just another of many online-only retailers that are based on a digital platform. Or it could grow to become a dominant force in grocery. The irony is that the biggest challenge it may face is building the Brandless brand, something that is already underway despite the company name.

Insurance and the Platform Economy

There are three implications for the insurance industry from the platform economy overall. First, and perhaps foremost, is how customers and their risks are evolving. Platform companies are reshaping industries, becoming companies with major insurance needs in their own rights while causing incumbents in their industries to rethink their businesses or venture into building their own digital platforms. In addition, the risk profile is different for these platform-based businesses, as they are likely to have huge cyber-risk exposure but limited needs for workers’ comp and property coverages.

The second implication for insurers is that other emerging “economies” such as the sharing economy and the gig economy are based on digital platforms. They are “instances” of a platform economy. For example, the gig economy enables independent individuals to offer their labor and skills to a company or another individual who needs it, with the platform operator taking a fee for making the connection. The sharing economy, in particular, is already important for insurers, as it influences the ownership and use of assets by individuals, such as cars, homes, and bikes.

Finally, insurers must consider the rise of the platform economy models in the insurance industry. The early models tend to be digital agents and brokers, performing a similar function to live agents today, but doing it via modern digital platforms that may be easier, faster and lower-cost than traditional distribution channels. It is generally understood that digital agents will have a big impact on certain segments of the insurance industry. It remains to be seen if the platform economy model will succeed in other parts of insurance, such as for peer-to-peer insurers, claim repair networks or subsets of the gig economy for insurance industry professionals like adjusters and loss-control engineers.

See also: 3 Ways to Boost Trust in Your Brand  

Platforms and the Future

One thing is certain. Insurers should investigate and understand the developments in the platform economy. As many insurers strive to become more digital, the creation of digital platforms and capabilities within the enterprise will position insurers to participate in other dimensions of the platform economy. Brandless may or may not become a big brand, but the momentum for the platform economy is unmistakable and something in which insurers should be actively engaged. Will there be a future platform-based company in the insurance industry that becomes the largest force in insurance without holding any risk or employing any underwriters and adjusters?


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.