Download

The Insurance Alignment Gap: Where Insurer Priorities and Customer Protection Needs Converge…and Diverge

Insurers are modernizing for efficiency, while customers seek affordability, trust, and protection. This report reveals how closing the alignment gap can create lasting value.

Insurance

Insurers are prioritizing cost reduction, profitability, modernization, and AI. Customers are looking for something different: affordability, trust, preparedness, and protection that feels relevant to the risks they face every day.

This growing alignment gap matters. Modernization and AI investments deliver their full value only when customers see and feel the benefit. When insurer priorities and customer expectations drift apart, confidence erodes, and so does the opportunity to help customers build financial resilience.

Based on original research with both insurers and insurance customers, this report examines where priorities align, where they diverge, and how insurers can connect business transformation to customer value. It explores three areas that matter most to building confidence and resilience:

Relevance. Customers want protection that reflects their everyday risks. Learn how insurers can deliver coverage that feels meaningful and worth the cost.

Personalization. Tailored products, pricing, and communications help customers feel understood and prepared. Learn how personalization supports trust.

Digital engagement. Digital experiences shape how customers perceive their insurer. Learn how to use them to strengthen confidence and connection.

Whether you lead strategy, product, distribution, customer experience, or technology, this report offers a research-based view of what customers expect and how your transformation priorities can meet them.

Read the Report


Sponsored by Majesco


ITL Partner: Majesco

Profile picture for user majescopartner

ITL Partner: Majesco

Majesco isn’t just riding the AI wave — we’re leading it across the P&C, L&AH, and Pension & Retirement markets. Born in the cloud and built with an AI-native vision, we’ve reimagined the insurance and pension core as an intelligent platform that enables insurers and retirement providers to move faster, see farther, and operate smarter. As leaders in intelligent SaaS, we embed AI and Agentic AI across our portfolio of core, underwriting, loss control, distribution, digital, and pension & retirement administration solutions — empowering customers with real-time insights, optimized operations, and measurable business outcomes.


Everything we build is designed to strip away complexity so our clients can focus on what matters most: delivering exceptional products, experiences, and long-term financial security for policyholders and plan participants. In a world of constant change, our native-cloud SaaS platform gives insurers, MGAs, and pension & retirement providers the agility to adapt to evolving risk, regulation, and market expectations, modernize operating models, and accelerate innovation at scale. With 1,400+ implementations and more than 375 customers worldwide, Majesco is the AI-native solution trusted to power the future of insurance and pension & retirement. Break free from the past and build what’s next at www.majesco.com


Additional Resources

The Second Half of Agentic AI

Read More

The Insurance Alignment Gap: Where Insurer Priorities and Customer Protection Needs Converge…and Diverge

Read More

Operational Value and Impact of GenAI and Agentic AI

Read More

Reimagining Insurance for a More Resilient Future

Read More

State of Core Solutions Transition: Which Tech Priorities Are Being Carried Out?

Read More

Finding Value in Today's Volatility

New data sources, better models, scenario planning and faster processing of information can help insurers turn today's "polycrisis" into value for themselves and for customers.

Image
Insurance

I don't know about you, but I'm a bit wary when I pick up my phone first thing in the morning and check on the state of the world. There's rioting where? A convective storm or wildfire destroyed what? The war in Ukraine or Iran took what turn? Inflation was how high, or job growth how low?

And the volatility is building on itself, creating what some of our authors have dubbed the "polycrisis." Economic problems lead to rioting in France, which destabilizes the Western alliance, which emboldens Putin in Ukraine, which feeds the political crisis in the U.S., which....

The insurance industry generally dislikes volatility. Insurers want a decade or two of data on a risk so they can price it properly. But how do you understand risks that appear so suddenly and can interact in such complex ways?

To get a sense, I turned to Dawn Miller, the chief commercial officer at Lloyd's and CEO of Lloyd's Americas, who explained how new data sources, better models, scenario planning and just generally processing information faster can at least help. 

Let's have a look.

Here is the full interview I did with Dawn. And here is a link to this year's Global Insurance Forum, which our sister organization the International Insurance Society is holding at Lloyd's in London on Nov. 15 and 16 on the theme, "Turning Volatility Into Value." But I'll summarize:

Dawn says, "We're seeing innovations in modeling—additional data transparency being plugged into some of those core models that we've always used to look at some known perils. The perils aren't changing, but our ability to understand them is getting better, sometimes dramatically. There's also an opportunity for geopolitical assessments, economic assessments, and social demographic assessments to all play a role."

She adds that some firms like at least some volatility because it creates more potential for upside and "fits as a diversifier into their portfolios. We see others wanting the longer-tail risk. This may not be as volatile, but they want it for their own investment reasons. Our role [at Lloyd's] is to create the environment for all those different profiles to exist and to all benefit from the diversification of our marketplace. It's not an either-or—the alpha seekers or the beta seekers. It's having both in an environment where they can coexist."

Dawn cautions that today's environment is full of "new layers of complexity": "In the past, our market would focus on certain CAT risks, certain natural perils happening in one place at one time. Now we're seeing multiple risks interact at the same time, from natural catastrophes and supply-chain disruption to inflation, geopolitical uncertainty and demographic risks. And those are just to name a few.... It takes an enormous amount of creativity to predict the layers of complexity around us today."

But she's optimistic about the industry's ability to innovate, including through Lloyd's Lab and the Lloyd's Academy, to help the insurance industry react faster as perils develop and interact. She also sees the industry cooperating, including through the ecosystem that Lloyd's fosters:

"Innovation, whether it is the birth of a new product, or the birth of a new structure, or how we deal with some of the extreme large-scale infrastructure, energy, supply chain, and transportation issues that we see around the world—that is going to take more than one mind to solve."

When I wake up tomorrow morning, I'll still peek at my phone with one eye open to check on the state of the world, but all is not lost.

I hope to see you in London so we can discuss the polycrisis and its many implications in person.

Cheers,

Paul


Gen Z Drives Insurance Claims Transformation

Gen Z's demand for instant digital experiences is forcing insurers to modernize claims payments or risk losing policyholders.

Insurance

As digital natives who've grown up tethered to smartphones and social media, the Gen Z population's effect on today's consumer trends is well documented. Young shoppers' demands for instant gratification in consumer transactions have ushered in an era of in-app shopping, next-day shipping, and fast, friction-free digital payment options.

Gen Z's influence is extending to the insurance claims process, as well. More and more, Gen Z's preferences are pushing the industry to uplevel its claims experience – to make it faster, more convenient, more tied to mobile, and more transparent to the policyholder. InvoiceCloud's 2026 Claims Experience survey of 1,000 U.S. policyholders shows Gen Z is nearly twice as likely as the overall population to prefer a digital wallet for claims payments (13% versus 7%).

Recent research shines a light on policyholders' discontent with what they identify as their biggest deal breaker: an unacceptably slow process for paying claims.

The InvoiceCloud survey found that only 9% of policyholders received their claims payment within two days. Meanwhile, a quarter of respondents say it took more than a week to receive their claims payout, while an unfortunate 13% waited "several weeks" to get these urgent funds.

This could cause ripple effects. In a 2022 report, "Transforming claims and underwriting with AI", Accenture estimated that poor claims experiences could put up to $170 billion in global insurance premiums at risk through 2027. The InvoiceCloud survey shows how these risks could materialize. At least 75% of policyholders surveyed say they would consider switching carriers after a single negative claims experience. That's a high percentage in any field, but it's particularly high in personal-lines P&C, where switching providers is often easier than it is in commercial, E&S, or other specialty markets.

Improving the claims process

How do insurance carriers improve the claims process? Our research found that speed and transparency matter most of all to policyholders. When asked directly, 30% named a faster claims payment after approval as the single change they want most, more than any other option, while 22% preferred clearer status communication. Gen Z echoes that second point: 24% named clearer, more consistent communication about payment status as the one change they would make, on par with the 21% who named faster payment.

Another issue: Many carriers have modernized inbound premium payments, but outbound disbursements still rely on paper checks and manual processing. Paper checks create fraud risk, delivery problems, and extra work for commissions and return premiums.

The next generation of policyholders is demanding two changes to this payment structure. They prefer a shift to digital, and they want choices.

Digital disbursement platforms can support a wide variety of options including ACH/direct deposit, debit cards, virtual cards, and digital wallets. Direct deposit to a bank account is policyholders' favorite payout, preferred by 52% of respondents, more than all other options combined. Printed checks still account for 19%, likely reflecting legacy carrier processes rather than genuine preference. The gap between generations is wide: 32% of Baby Boomers prefer a printed check, compared with just 9% of Gen Z.

If slow payouts can lead to defections, digital insurance payments can operate as a retention tool.

Insurance carriers can do this by ensuring this critical touchpoint becomes an easy experience end-to-end, from allowing policyholders to self-serve through digital premium payments, paperless billing, and automatic payments, to instant disbursements delivered however policyholders prefer to receive funds.

Real-time digital disbursements are funds sent electronically and received quickly, without a paper check in the middle. For insurance carriers, this means agent commissions and return premiums move through digital payment processing solutions rather than the mail. More importantly, it means getting funds into policyholders' hands fast, when it matters the most.

Raising expectations

As younger policyholders account for a larger share of the insurance market, experiences they've grown accustomed to in other walks of life will increasingly become expectations for insurance as well.

For many, this translates to being able to complete more transactions on smartphones. Digital payments enable customers to choose a payment method from their phone, receive payment notifications, track payment status, access transaction details, and receive funds directly into an eligible account or wallet. That matters most to the youngest policyholders. When asked for the easiest way to access funds in an emergency, 19% of Gen Z chose a mobile wallet, compared with 5% of Baby Boomers, while only 9% would withdraw cash at a bank, compared with 34% of Baby Boomers.

Gen Z's imprint on insurance claims is becoming more pronounced. Today's policyholders want to have insurance claims processed and paid out faster. But they want more. They want the entire journey – culminating in how and when they get paid – to feel as immediate and seamless as any other digital financial transaction.


Ray Walsh

Profile picture for user RayWalsh

Ray Walsh

Ray Walsh leads InvoiceCloud's insurance vertical, helping property and casualty carriers modernize the way they bill, collect, and disburse payments to policyholders. 

He previously served as vice president of enterprise sales at Brightcove and senior vice president of global sales at TransAct Technologies.

Walsh sits on the board of Greater Springfield Habitat for Humanity, where he currently serves as board president. He studied business management at Albertus Magnus College.

Turning Volatility Into Value

Amid today's heightened uncertainty, Dawn Miller, chief commercial officer at Lloyd's, explores how insurers can innovate their way to value both for themselves and for their clients. 

Insurance

Paul Carroll

We’re in an exceptionally volatile period, with major geopolitical and economic risks on top of climate-driven catastrophes, nuclear verdicts, and more. The International Insurance Society’s annual Global Insurance Forum in November, which you’re sponsoring and hosting at Lloyd’s, has as its theme this year: "Turning Volatility Into Value." How do we do that?

Dawn Miller

I'm just coming off some time at CIAB [Council of Insurance Agents and Brokers] in Colorado, and the topic that is on everyone's mind, in addition to market conditions, is how multiple perils are intersecting with global trends to create an increasingly varied and complex risk landscape, with some risks well modeled and others less so. 

In the past, our market would focus on certain CAT risks, certain natural perils happening in one place at one time. Now we're seeing multiple risks interact at the same time, from natural catastrophes and supply-chain disruption to inflation, geopolitical uncertainty and demographic risks. And those are just to name a few. It’s the interaction among these different risks that is adding new layers of complexity.

We have innovations that allow us to model with more transparency, and we can bring in supplementary models to assess risk. That's a good thing. But it takes an enormous amount of creativity to predict the layers of complexity around us today.

Paul Carroll

Yes, some people who’ve written for us refer to a “polycrisis.” You mention modeling. Is that the main way insurers make sense of all these complicated connections, or is it improvements in scenario planning, or something else?

Dawn Miller

I believe it's multiple things. We're seeing innovations in modeling—additional data transparency being plugged into some of those core models that we've always used to look at some known perils. The perils aren't changing, but our ability to understand them is getting better, sometimes dramatically. 

There's also an opportunity for geopolitical assessments, economic assessments, and social demographic assessments to all play a role. The modeling itself is a bit of a Rubik's Cube with multiple facets to it.

Paul Carroll

Wall Street talks a lot about alpha and embraces volatility because it creates opportunities. Historically, insurers have not liked volatility. How do you change that thinking?

Dawn Miller

Given that Lloyd’s is guiding a marketplace, we're creating the conditions for success for the world's best risk takers to attach the risks they want to underwrite with capital. We see a mix in our marketplace. We do see investors coming in looking for some of that volatility. That’s what they like, and it fits as a diversifier into their portfolios. We see others wanting the longer-tail risk. This may not be as volatile, but they want it for their own investment reasons.

Our role is to create the environment for all those different profiles to exist and to all benefit from the diversification of our marketplace. It's not an either-or—the alpha seekers or the beta seekers. It's having both in an environment where they can coexist.

Paul Carroll

Volatility requires agility not just for those transacting in your marketplace but for you, too. How is Lloyd's getting faster at identifying opportunities and scaling the winners as quickly as possible?

Dawn Miller

In March, we launched our new five-year strategy, Advance and protect. It is designed to sharpen Lloyd’s financial edge and maximize our unique capital advantage, including by creating a more efficient and flexible marketplace by making the platform more investable, clear, transparent and agile.

Right now, there's some additional reporting, different ways of working, maybe some duplicated oversight here and there—things that have grown up over time for all the right intentions, but maybe as we evolve are not as pragmatic any more. All of those cause a little bit of extra cost, whether it's in time or resources, because time is money at the end of the day.

So we're making things much clearer, making it much more cost-efficient, making sure we are an engine for driving new talent into the marketplace, attracting the best talent and then recycling them back out as advocates and having the marketplace stronger for their being with us. You're creating an ecosystem that is the center of attracting the world's best risk takers, the best capital together with the best brokers, best clients, the best risk.

What that gives us is the ability to innovate. When we think about Lloyd's and the underpinnings of our strategy, our superpower is our capital diversification benefits. Our other superpowers are around our license structure, the framework we have for innovation, the ability to syndicate risk rapidly, our very strong financial strength ratings.

Innovation, whether it is the birth of a new product, or the birth of a new structure, or how we deal with some of the extreme large-scale infrastructure, energy, supply chain, and transportation issues that we see around the world—that is going to take more than one mind to solve. And we are the marketplace for that sort of solution creation.

Paul Carroll

At ITL, in our little way, our mantra is: Nobody is as smart as everybody.

Dawn Miller

That's exactly right. Our role is to convene a marketplace, creating those conditions for success. It happened 338 years ago when people came together over a cup of coffee and said, Let's share this risk so we can get these ships across the globe. Today, the same principle of combining expertise and capital continues across the underwriting room, Lloyd’s Lab and Lloyd’s Academy. 

Paul Carroll

I’m glad you mentioned the lab and the academy, because, as an old hand on innovation efforts, I wanted to ask how they fit into your broader innovation ecosystem.

Dawn Miller

Absolutely. As you know, Lloyd's Lab launched in 2018 to make sure we had a place to accelerate—not necessarily incubate, and I want to make that distinction—new risk-taking ideas or risk-servicing ideas. Over time, we've grown to have about 160 alumni.

This past cohort, Cohort 17, just went through a selection process. We received 280 applications from 31 countries. Fifteen companies were invited to pitch to the market, and 10 were selected for the 10-week Accelerator program. The market plays a central role in that selection process because the Lab is designed to respond to real market needs. 

The focus of Cohort 17 has been in areas where the Lloyd’s market is actively seeking solutions that improve how the market operates day to day to strengthen its ability to respond to the complexity of today’s risk landscape and this can be seen through the themes: operational efficiency, new products and experimental innovation. 

What does that mean? They come in at all different stages of businesses and ideas. They have mentors from the marketplace. They hone, shift, and massage their product and their service. Then they exit the other end, generally about 80 to 85% of them, with either capacity for a proof of concept or a service contract or service proof of concept into the marketplace. That ranges from new products—cloud downtime, wildfire, data analytics—to a whole variety of services.

They work their way through the market, with an accelerated cover holder process. Some of them, like Parsyl, started in the Lloyd’s Lab. Parsyl began by using data and technology to tackle risks in global health supply chains, then became a Syndicate-in-a-Box and now has in-principle approval to become a full syndicate. That’s the process of taking innovation, testing and proving it in the market, and ultimately giving it the opportunity to scale.

They're a part of our ecosystem once they come out as alumni, and they stay within our ecosystem around the world. We continue to help by giving them opportunities to be exposed to end clients, to regulators, to investors, etc.

Paul Carroll

How do you expect these topics—including innovation, geopolitical risk, and emerging technologies—to be developed at the Global Insurance Forum?

Dawn Miller

I always look forward to the Global Insurance Forum; it's a place where market leaders and market practitioners are coming together to exchange on an equal level. We’re reflecting the trends of the times, whether that’s private credit, scaling innovation or how we move beyond the tactical. This year’s theme, “Turning volatility into value,” really captures that. It’s about moving beyond reacting to uncertainty and using better insight, specialist expertise and flexible capital to anticipate changing needs, build solutions and give customers the confidence to invest and grow. 

The companies that come together are from all around the world. Everybody's lens is going to have a slightly different take on how they deal with geopolitical risk or how they're dealing with supply chain or how they're dealing with credit risk or what they're facing at that exact moment. Bringing all of that together allows us to create a narrative that firmly implants how our industry is driving resilience forward.

Our industry provides the oxygen for the economies around us. And I believe we allow our industry to represent itself or be represented by others in a way other than that. I wish we talked more about the outcome our industry enables: resilience. We need to explain insurance through communities, businesses and economies it enables to recover and thrive and persist. 

The forum also creates a great opportunity to bring some of our young leaders to the table. Their perspectives are varied and rich, and we need that diversity of thought. 

Paul Carroll

As someone who’s covered technology innovations for decades, I confess that it was only about 15 years ago that I realized that none of that happens without insurance. Every major innovation—the personal computer, the internet, the smartphone, social media, search engines, GPS, the driverless car—comes with risks, and nobody can take those risks without some sort of protection. 

Dawn Miller

Right. Isn't it funny? We all sort of take it for granted. 

If we could just reframe the conversation and talk more clearly about how insurance creates resilient communities, helping them thrive, we would give people a much better understanding of the value our industry provides. At Lloyd’s, we don’t just seek to understand risk, we take it on, bringing together expertise, capital and risk appetite to help businesses move forward.

The issue couldn't be more important than it is right now, with the multiple layers of risks that surround us.

Paul Carroll

Thanks, Dawn. It’s always great talking with you. 

Dawn Miller

Thank you for having me, Paul; always a pleasure.

If you’re interested in attending the Global Insurance Forum, you can register here.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Car Thefts Are Plunging. Why?

Car thefts in the U.S. tumbled to their lowest levels in decades in 2025, and are down a further 21% this year. The trend is likely to continue, too.

Image
Insurance

The recent report that auto thefts fell 21% in the U.S. in the first half of the year reminds me of a friend's carjacking some 30 years ago — surely the shortest in history. 

My overeducated friend, with degrees from Brown and the Sorbonne, had just added a certification as an auto mechanic and liked cars that required constant tinkering. While driving near his home in Washington, DC, one afternoon, he stopped at a stop sign, and a pedestrian motioned to him that he had a question. Tim rolled down his window, and the man shoved a gun in his face, ordering him out of the car.

The man got in, engaged the clutch and drove... two feet. He tried again, but the car stalled after two more feet. He tried a third time. A fourth. He hadn't even made it halfway into the intersection before he jumped out, threw the keys at Tim's chest and ran off. 

I'd never thought of having a diseased clutch as an anti-theft device but have watched with interest over the years as actual devices have continually improved. They've now gotten to the point that, combined with other factors, thefts fell 17% in 2024, tumbled 23% last year, to the lowest levels in decades, and are way down again this year. The good news for insurers is likely to continue, too.

Let's have a look. 

Some of my optimism stems simply from the steady modernization of the car fleet. Even though soaring prices for cars have encouraged people to hold on to cars longer than in the past, older, more vulnerable cars are steadily being retired, and that trend will continue. 

In the face of public pressure, companies whose cars were most likely to be stolen have also issued software patches and other updates — as a result, the percentage of car thefts of Kias and Hyundais fell to 14% of the total last year, from 16% in 2024 and 21% in 2023, even as the total of thefts dropped precipitously. 

Meanwhile, the supply chain has sorted itself out post-COVID, so thieves can't rack up the sorts of profits they did from stealing scarce parts in recent years. The U.S. war on Iran may unsettle the supply chain again, including by pushing sales of electric vehicles during a time of high gasoline prices, but the effects have been muted so far, and I suspect they'll remain so.

Law enforcement has stepped up efforts to prevent all sorts of crimes, and car thefts are a visible target at just about all levels of policing. I'm not sure how much more severe enforcement can become, but, especially in a fraught political environment, I don't see that anyone will relax.

Potentially the most important — but fraught — factor that will determine how much car thefts keep falling relates to surveillance technology. Flock has built a massive business by installing cameras on roads nationwide that take pictures of license plates and respond to, among other things, alerts from police departments about stolen vehicles. There are lots of efforts to also figure out how to knit together all the images being gathered by dashcams, which are currently in about one in 10 vehicles in the U.S. and which are being adopted quickly. 

Combining all those feeds could provide real-time intelligence for police departments, making it far easier to catch thieves and creating a massive disincentive for them to steal cars in the first place.  

But....

We've also seen how surveillance can be abused, as I wrote in August. Flock faces a scandal because dozens of police officers used its technology to stalk current and former romantic partners, and the temptation to use surveillance illicitly will only increase as the technology becomes more powerful.

My gut tells me that it will take time, perhaps years, to sort through all the tensions between law enforcement and privacy but that we'll eventually get to the point where some severely circumscribed uses of license plate readers will take another cut out of auto thefts. The privacy issue is one we've mostly navigated with Ring cameras and surveillance cameras on building, so there's a blueprint for progress

The bad guys are always innovating, just as the good guys are, but I think the favorable glide path for car thefts should continue.

Cheers,

Paul

P.S. My other bizarro car theft story, this one involving a nephew and an odd situation for the adjuster:

While my nephew was visiting DC last year, his Hyundai was stolen off the street by four kids — who drove the car right past him as he was talking with the police officer who responded to his report of the crime. They took the car on joy rides for a few days — as evidenced by the thousands of dollars of traffic violations they ran up in DC and Maryland — then used it in a drug deal that went bad. 

The car wound up full of bullet holes, and a friend of the kids was shot. Panicking, the kids put the badly wounded girl in the trunk of the car and dumped her in front of her high school. These young geniuses then abandoned the car and tried to run off but were promptly apprehended by school security. (The girl healed fine.)

The insurance issue was that the adjuster couldn't look at the car because it was in police custody as a crime scene. So my nephew's insurer kept him in a rental car for weeks until it finally satisfied itself that the car was a total loss and wrote him a check for a new one.

My nephew spent weeks unwinding the traffic tickets. He actually had to drive to Baltimore from Philadelphia to appear in court and provide evidence that he couldn't have been at the wheel for the moving violations because he wasn't in Maryland when they occurred. 


AI Shapes Customer Demand While Measuring It

AI systems now shape customer choices through recommendations and interactions, making causal identification essential to distinguish genuine needs from system-influenced demand.

Insurance

When companies talk about understanding customer needs, they often assume a simple path:

Underlying Need → Observed Demand

A customer has an underlying need, even if they cannot fully articulate it. Through questions, data, and observed behavior, companies try to work backward from what the customer says or chooses, to understand what that person actually needs.

Demand discovery has therefore traditionally been treated as a process of finding something that already exists.

In a previous article, I argued that reproducing an outcome is not the same as understanding the causal mechanism that produced it. The same distinction applies to customer demand: observing what customers choose is not the same as understanding why that choice emerged.

What deserves more attention is the arrow in the middle.

The path from underlying need to observed demand is never empty. What customers see, how they are questioned, what recommendations they receive, and how they interact with a system can all shape the demand that eventually becomes visible.

AI makes this issue more important.

When systems begin deciding what to present, how to rank options, what question to ask next, what to recommend, or what action to take based on a prediction, the observed demand that companies ultimately see may already contain the influence of the system itself.

How much of the demand we observe reflects what the customer already needed, and how much emerged through the interaction itself?
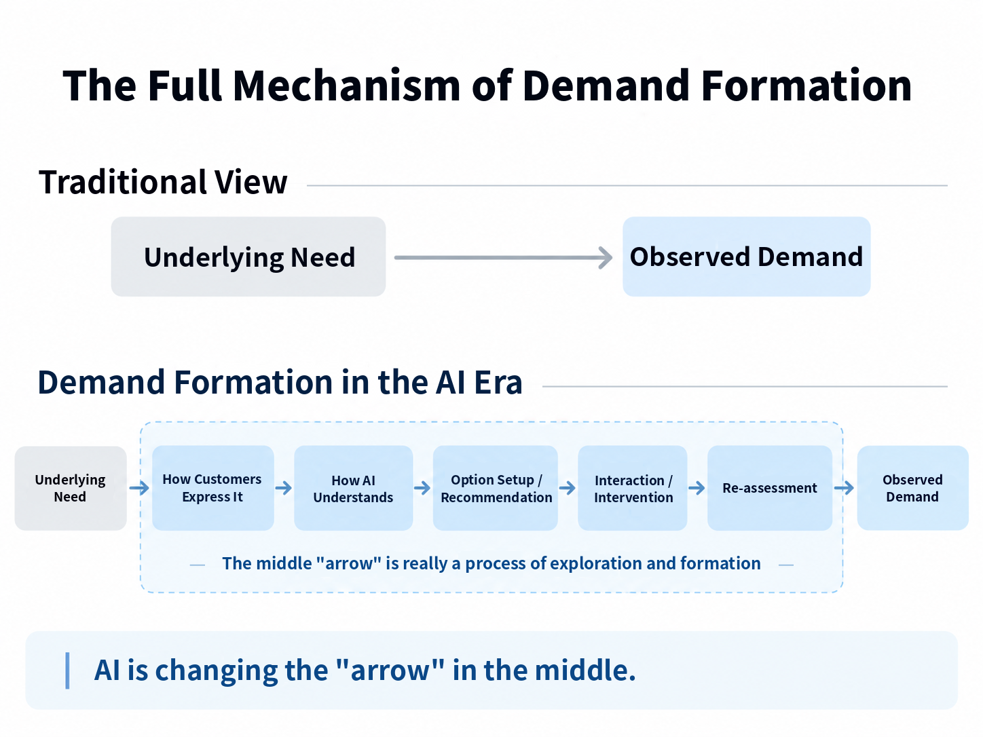
Figure 1. The full mechanism of demand formation.

1. We Have Treated the "Arrow" as Too Simple

Suppose a customer chooses Product A from three options. The intuitive conclusion is straightforward:

The customer chose A, so A must best reflect their preference.

But before making that inference, there is another question:

Why did this customer see these three options in the first place?

In the age of recommendation systems, different customers are rarely shown identical choices. A system may use previous behavior, income, browsing history, search activity, and other signals to determine which products are most relevant to present. The real process may therefore look more like this:

The system evaluates the customer → determines which options the customer sees → the customer chooses from those options.

In 2021, researchers from Cornell and Stanford described this problem in a paper titled "Choice Set Confounding in Discrete Choice." Many preference models infer what people prefer from the choices they ultimately make. But the choice set itself may already depend on the chooser's characteristics and existing preferences. Recommendation systems are a classic example.

If that mechanism is ignored, two different things can easily become mixed together:

What the customer already preferred, and what the system chose to place in front of them.

The hotel-booking example in the study makes this easy to understand.

Suppose a recommendation system has already filtered hotels based on a user's preferences, and the user consistently chooses the cheapest hotel among those presented. A model might conclude that price is the dominant factor in that person's preference.

But that conclusion may overstate the importance of price. Location, star rating, or other attributes may already have been filtered earlier in the recommendation process. Once researchers accounted for this confounding, price became less dominant, and other factors became more important.

Preference is not the same as underlying need. But choices and expressed preferences are important behavioral signals companies use to infer what customers need. 

That means demand discovery cannot focus only on what the customer ultimately chose. It must also consider the choice environment in which that decision was made.

2. AI Does Not Just Influence What We See. It Can Change What We Choose.

Choice set confounding tells us that a final choice cannot be understood independently of the options that preceded it. But there is an even more direct question:

Can AI recommendations themselves change what people choose?

A 2026 Pension Portfolio Experiment posted on arXiv provides a clear example. Researchers recruited 400 South Korean employees who were actually enrolled in workplace defined-contribution pension plans. In a simulation, participants first allocated a hypothetical pension balance across 11 investment products. They were then randomly assigned one of two AI-generated recommendations: one relatively aggressive and concentrated, the other relatively conservative and diversified.

Participants could then revise their original portfolios. Three findings stand out:

  • 81% changed their portfolios after receiving the AI recommendation.
  • Among those who revised, 95% moved in the direction suggested by the AI.
  • The difference between the two AI recommendations was partially transmitted into the final portfolios: the resulting difference between the two participant groups was about 37% as large as the original difference between the recommendations.

In other words, people did not simply follow the AI wholesale. But different AI recommendations still produced different final decisions.

The effects went beyond superficial portfolio changes. Participants who received the more aggressive recommendation ended up with higher expected returns and volatility, less exposure to low-risk products, and more exposure to high-risk products. The study did not find a significant improvement in risk-adjusted performance, but AI clearly changed the risk structure participants ultimately accepted.

The important point is the causal relationship:

Different AI recommendations produced different final choices.

Participants still retained much of their original judgment. The final decision was therefore neither purely human nor purely AI-generated. It emerged from the interaction between the two.

Now consider what happens next. If a company later observes those revised portfolios and records them as new evidence of "customer preference," that data already contains some of the influence created by the AI itself.

At that point, saying "The customer chose A, therefore the customer prefers A" is no longer a sufficient inference.

3. When a Model Begins to Influence the World It Will Later Observe

This leads to another important idea: Performative Prediction.

In 2020, researchers at UC Berkeley used this term to describe situations in which a prediction, once used to support a decision, changes the very outcome being predicted.

Consider a simple credit example. A bank predicts that a borrower has a high probability of default and therefore charges a higher interest rate. But the higher interest rate increases the borrower's repayment burden, which may itself increase the probability of default. The sequence becomes:

Prediction of high default risk

↓

Higher interest rate

↓

Actual default risk changes

The model appears to describe the world, but once deployed, it also begins to influence the world it is describing. Similar dynamics can occur in traffic prediction, policing, recommendation systems, and financial markets. Applied to demand discovery, the mechanism might look like this:

The model predicts that a customer may need A

↓

A is shown more prominently

↓

A is recommended

↓

The interaction increasingly centers on A

↓

The customer ultimately chooses A

At this point, the first layer of influence has already occurred: AI has affected the customer's choice.

The pension experiment shows that this can happen in practice. But there is a second layer. If the company then uses that choice as training data for the next generation of its model:

The customer chooses A

↓

The system records "customers like this prefer A"

↓

Similar customers are more likely to be shown A in the future

The company is no longer merely observing demand. It is beginning to participate in the formation of the demand it will later observe. This does not mean the model is necessarily wrong. The problem arises when companies forget that their own ranking, recommendation, and interaction mechanisms have already entered the causal process. They may then treat outcomes partly produced by the system as if they were pure evidence of the customer's original preferences.

4. The Path From Underlying Need to Observed Demand Is a Formation Process

The apparently simple relationship:

Underlying Need → Observed Demand

can therefore be expanded into something closer to this:

Underlying Need

↓

Customer Expression

↓

AI Interpretation

↓

Option Configuration / Recommendation

↓

Interaction / Intervention

↓

Customer Reassessment

↓

Observed Demand

Several mechanisms operate inside this process.

  • Choice architecture: determines what the customer sees and how alternatives are arranged.
  • Interaction: determines how the system asks, responds, and continues the conversation.
  • Recommendation: introduces new information and direction into the customer's judgment.
  • Intervention: occurs when the company acts on the model's judgment in ways that affect subsequent responses or decisions.

None of these mechanisms is entirely new. What AI changes is its scale, personalization, speed, and ability to operate continuously. There is also an important distinction to make. The fact that demand is shaped through interaction does not necessarily mean it is being distorted.

In many real situations, customers themselves may not fully understand what they need at the beginning. A well-designed discovery process can use questions, comparisons, and different scenarios to help customers clarify what they actually value.

The interaction therefore has two simultaneous functions. On one hand, it generates new signals and reduces uncertainty about the underlying need. On the other hand, the way questions are asked, options are presented, and recommendations are made can also influence how customers think and respond.

In the past, demand discovery was easier to think of primarily as a form of measurement. With AI, measurement and intervention increasingly occur at the same time.

The challenge is therefore not to eliminate intervention altogether. It is to distinguish between signals that reflect a relatively stable underlying need and signals that were caused by a particular question, choice set, or recommendation.

5. From Collecting Answers to Identifying Causes

If a company relies mainly on correlation, the logic is straightforward:

The customer chose A → therefore the customer needs A.

But once the system itself has participated in presenting, recommending, and explaining A, that inference becomes less reliable.

The more important question becomes: If the conditions were different, would the same need still appear?

  • Would the customer still choose A if A had not been recommended first?
  • If the price changed, would the customer still value the same type of protection?
  • If the customer saw a different set of alternatives, would the expressed preference remain?
  • If family responsibilities changed, would the need for protection change as well?

These are fundamentally counterfactual questions: If a particular condition had been different, would the outcome also have been different?

The contrast can be summarized as a shift from a traditional approach based on observed behavior and correlation to a causal approach that varies conditions and interventions to test demand hypotheses.

By introducing different conditions and interventions, companies can test competing demand hypotheses. Some changes should theoretically have little effect on a genuine underlying need. Other causal factors, when changed, should produce corresponding changes in demand. When customer responses behave consistently with these causal hypotheses, companies have stronger grounds for believing they are identifying the underlying need rather than merely predicting an observed response.

The choice set confounding research points in the same direction. When companies understand the variables used to assign choice sets and the mechanism by which those choice sets were generated, causal methods such as inverse probability weighting and regression controls can help reduce confounding and recover preferences more accurately.

AI therefore does not make genuine customer needs impossible to understand. But it changes what understanding requires. Companies cannot simply accumulate more behavioral data and expect the truth to emerge automatically. They need to understand the conditions under which each signal was generated, and whether the signal still holds when those conditions change.

A more mature AI demand-discovery process therefore cannot stop at:

Ask questions → collect answers → predict demand

It also needs to:

Form a demand hypothesis

↓

Design appropriate questions and scenarios

↓

Observe responses under different conditions

↓

Control for possible confounding

↓

Continuously revise the judgment of the underlying need

For example, a customer may ultimately choose Product A for very different reasons:

  • The customer genuinely needed A from the beginning.
  • The system placed A in front of the customer first.
  • The system repeatedly recommended A.
  • The way the questions were framed directed the customer's attention toward A.
  • Other relevant alternatives were never presented.

The observed choice may look identical in every case, but the mechanism that produced it is not.

Interaction is therefore no longer just a way to collect more data. Every interaction can also become a test of a demand hypothesis. The goal is therefore not simply to improve the predictive accuracy of observed demand. It is to improve the company's causal ability to identify underlying need.

Conclusion: Put the Company Back Into the Causal Chain

Traditionally, the challenge of demand discovery has been to look beyond surface-level statements and choices to understand what customers actually need. AI adds a layer. Once a system begins participating in option design, recommendation, questioning, and decision-making, the observed demand that a company sees may already contain the influence of its own AI.

Companies can therefore no longer ask only: How do we infer underlying need from observed demand?

They must also ask: Through what mechanism was this observed demand produced?

And once measurement and intervention can no longer be cleanly separated, companies need more than stronger predictive models. They need causal methods that can continuously improve their ability to identify underlying needs while interacting with and influencing customers.

A mature AI demand-discovery system should incorporate intervention into its design so that every question, option, and interaction helps distinguish among three things:

what the customer already needed, what the system itself helped cause, and what became clearer through the interaction.

If companies want to understand demand in the AI era, they must begin by putting themselves back into the causal chain.
David Lien

Profile picture for user DavidLien

David Lien

David Lien is a partner at Lingxi (Beijing) Technology. 

He wrote “Decoding New Insurance” (2020), which ranked among JD.com’s top books. Lien has held leadership roles at Sino-US MetLife, Sunshine Insurance and Prudential Taiwan, leading digital transformations and multi-channel marketing. A 2018 e27 Asia New Startup Taiwan Top 100 nominee, he holds a patent for the "Intelligent Insurance Financial Management System." 

Insurers Adopt Property-Level Fire Suppression Analytics

Property-level fire suppression analytics enable insurers to assess individual risk characteristics beyond traditional community-wide classifications, improving underwriting precision.

Insurance

Fire-related losses remain one of the most significant and persistent sources of property claims for insurers. While catastrophic wildfires often dominate headlines, everyday residential and commercial structure fires continue to generate billions of dollars in insured losses each year. According to the National Fire Protection Association, U.S. fire departments responded to approximately 470,000 structure fires last year, resulting in an estimated $15.3 billion in direct property damage.

For decades, property insurers have relied on community-wide fire protection classifications to help evaluate fire risk. Those classifications have provided a consistent framework for assessing local fire protection capabilities and incorporating that information into underwriting and pricing decisions. They remain an important part of property underwriting today.

But the underwriting environment has changed. Rising replacement costs, tighter underwriting margins, increasingly sophisticated catastrophe models, and unprecedented access to geospatial data are reshaping how insurers evaluate property risk. At the same time, advances in cloud computing, geospatial analytics, and artificial intelligence now make it possible to evaluate fire suppression characteristics at the individual property level rather than relying primarily on community-wide averages.

That evolution changes the underwriting question. Beyond knowing whether a property sits within a well-protected fire district, insurers can assess how quickly firefighters can reach it, establish a reliable water supply, and begin limiting damage—and what those capabilities mean for expected fire losses.

Fire Protection Is Not Uniform Within a Community

Traditional fire protection classifications evaluate important characteristics of a community, including fire department resources, staffing, emergency communications, equipment, and water supply infrastructure.

Those measures remain valuable, but they also reflect an era when insurers had far less visibility into fire suppression at the individual property level.

Two homes located within the same fire protection district can have meaningfully different fire suppression profiles. One property may be minutes from multiple staffed fire stations, have excellent road access, and sit within a short hose lay of a nearby hydrant. Another may require a substantially longer response, rely on fewer responding stations, or have more limited access to reliable water supplies.

From an underwriting perspective, those properties do not present the same level of expected loss, even if they share the same district-wide classification.

That distinction becomes increasingly important because fire severity depends heavily on timing. Every minute required to reach a property, establish a water supply, and begin suppression can influence how much of a structure is ultimately damaged.

The Operational Variables That Matter

Modern geospatial analytics now allow insurers to evaluate fire suppression through a far more operational lens. Rather than assigning a single assumption to every property within a district, carriers can evaluate characteristics such as:

  • Road-network drive time from responding stations
  • Distance to nearby hydrants or other reliable water sources
  • The number of stations capable of responding within defined drive-time thresholds
  • Staffing models, including career, volunteer, or blended departments
  • Suppression redundancy if one station is unavailable or already committed
  • How these variables interact to influence expected fire severity

Each factor provides useful information individually. Together, they offer a much more realistic picture of how quickly suppression resources can reach a property and begin controlling a fire.

That operational perspective moves underwriting beyond geographic averages and toward a better understanding of how individual properties are actually protected.

Why Hydrant Data Matters

Among the many operational characteristics that influence fire suppression, hydrant proximity is one of the clearest examples of why property-level intelligence matters. Reliable hydrant location data allows insurers to evaluate a characteristic that can have a measurable effect on and relationship to claim severity at an individual property.

Research has shown that homes located within approximately 250 feet of a fire hydrant experience about 9% lower fire severity than homes located 250 to 500 feet away. At greater distances, the differences become even more pronounced. Homes located within 250 feet of a hydrant or other reliable water source can experience nearly half the fire loss severity of comparable properties located more than 1,000 feet away.

Historically, hydrant information was often treated as a simple eligibility measure—a property either met a distance threshold or it did not. Today, comprehensive hydrant datasets enable evaluation of hydrant proximity as a continuous risk variable, providing a more detailed understanding of how water availability can influence fire outcomes.

Hydrant proximity is only one component of a property's overall fire suppression profile. But when combined with drive-time modeling, station staffing, road network analysis, and station density, it becomes part of a much richer operational picture of how quickly suppression resources are likely to reach a property and limit loss.

From Classification to Prediction

Perhaps the most significant evolution is that many of these variables can now be evaluated against actual insurance claims.

Rather than relying primarily on generalized assumptions about community fire protection, insurers can increasingly identify which combinations of operational characteristics most closely correlate with fire severity and economic loss.

That represents a meaningful shift in underwriting philosophy. Instead of asking whether a property belongs to a particular fire district, insurers can ask more predictive questions. How quickly are suppression resources likely to arrive? How rapidly can firefighters establish a reliable water supply? Which operational characteristics are most closely associated with severe claims?

Those insights allow carriers to differentiate between properties that may appear similar under traditional classifications but have materially different expected loss characteristics.

A Broader Transformation in Property Underwriting

Fire suppression analytics is part of a broader movement across the property insurance industry.

Whether evaluating wildfire exposure, hurricane risk, flood susceptibility, hail damage, or severe convective storms, insurers are steadily moving away from broad geographic assumptions and toward property-level intelligence.

The goal is not simply to collect more data. It is to use data that more accurately reflects the factors that drive actual losses.

That approach enables more precise underwriting, more refined pricing, improved portfolio management, and better identification of profitable business opportunities. It also allows carriers to recognize lower-risk properties that might otherwise be overlooked when entire districts are treated similarly.

Turning Insight into Underwriting Decisions

Community classifications remain a useful foundation for evaluating fire protection. Property-level suppression analytics adds the detail needed to distinguish risks within those communities.

For insurers, the practical value lies in translating those differences into underwriting and pricing decisions that more closely reflect each property's expected loss. A home with faster access to staffed stations and a reliable water supply may warrant a different assessment from one with fewer resources or longer response times—even when both share the same community classification.

Innovation Creates Potential. Execution Creates Performance.

Automotive services companies that execute consistently at scale outperform those that simply innovate first or grow fastest.

Insurance

The automotive services industry has no shortage of new ideas. The harder challenge is turning those ideas into consistent commercial results.

A pilot, product launch or signed agreement can demonstrate progress, but none of those milestones proves that a business can perform at scale. Commercial value develops when customers adopt the product, the program becomes part of daily operations, and the organization can deliver consistently as participation and transaction volume grow.

Building a product and building a sustainable business around it require different capabilities. A strong concept may create the initial opportunity, but long-term performance depends on sound product and pricing decisions, underwriting alignment, implementation ownership, scalable service infrastructure, reliable data, and clear accountability.

Dealers and companies that manage those elements well are better positioned to turn market opportunities into measurable results. They may not be the first companies to enter a category or the largest providers in the market. Their advantage comes from being able to deliver consistently after the initial sale.

Early Success Does Not Prove Scale

Being first to market can create an early advantage, but that advantage has limited value if the business cannot support customers after launch.

A similar shift is taking place in insurtech, where investors are placing greater emphasis on demonstrated commercial traction. According to CB Insights' State of Insurtech 2025 report, just 24% of 2025 insurtech deals with a Commercial Maturity score went to companies in its earliest "Emerging" or "Validating" categories, compared with 46% of deals across the broader venture market.

The shift reflects a more practical evaluation of innovation. Investors still value new ideas, but they are directing more capital toward companies that can demonstrate commercial maturity, scale and repeatable performance.

Automotive companies should apply the same standard when evaluating a product or provider. They should look at how many customers are actively using the product, how reliably the service is being delivered, and whether the provider can manage a significant increase in volume without weakening the customer experience. They should also test whether the economics remain viable as participation and transaction volume grow.

Early results matter, but they do not provide a complete picture of how a program will perform at scale.

Scale Changes the Requirements

The pressure to execute at scale applies to established companies just as much as it does to startups.

The U.S. auto dealer market remains highly fragmented, but consolidation continues as larger dealership groups expand through acquisitions and new franchise opportunities, according to Morningstar's 2026 analysis of the sector.

At the same time, broader M&A activity remains active. KPMG's 2026 Global M&A Outlook found that 56% of surveyed dealmakers expected their M&A pipelines to be higher in 2026 than in 2025, with private equity respondents reporting particularly strong deal expectations.

Consolidation can provide access to more capital, technology and operating resources, but it also creates additional complexity. A larger organization has more customers, systems, processes and service points to manage. Without a disciplined operating structure, each addition creates another opportunity for inconsistency.

For dealers, insurers, F&I administrators and automotive service providers, company size is only one consideration. The more important question is whether the organization can maintain its service standards as volume, complexity, and customer expectations increase.

Scale changes the operating environment. More claims are submitted. More customers require support. More systems must connect. More handoffs occur between teams and partners. A process that works at low volume can become a point of failure when transaction levels increase.

That is why scale must be tested operationally, not assumed.

Execution Is a Business Capability

A scalable operating model must support additional volume without creating corresponding service problems.

Claims should be processed according to consistent standards whether a program serves 1,000 customers or 100,000. Customer service teams should provide the same level of support across markets. Technology should connect with a partner's existing systems without requiring a new manual workaround for every implementation.

Execution also requires coordination across areas of the automotive services industry that have traditionally operated independently. F&I products, tire and glass services, repair networks, and roadside assistance may have different operating models, but customers experience them as parts of the same service journey.

When a handoff fails, the customer does not distinguish between the company, system or department responsible for the problem. The failure affects every brand associated with the transaction.

Managing those handoffs requires defined processes, clear ownership and testing under real operating conditions. It also requires continuing improvement based on service data, partner feedback, and customer outcomes.

For that reason, execution should be managed as a core business capability.

Hiring more people does not automatically create scale. Adding technology does not automatically create scale. Expanding into more markets does not automatically create scale. The processes behind the operation must remain reliable as transaction volume and complexity increase.

AI Amplifies the Operating Model

The same principle applies to AI.

Technology can increase the capacity of a sound operating model, but it cannot substitute for one.

AI can improve areas such as scheduling, claims intake, customer communication, and workflow management. It can reduce manual work, improve response times, and help teams manage higher transaction volumes.

But if the underlying data is unreliable, workflows are inconsistent, or responsibilities are unclear, automation carries those weaknesses into the new process. In some cases, it can expose them faster by increasing the amount of work moving through the system.

Companies evaluating AI should therefore look beyond the technology itself. They should examine the operating environment in which it will be used.

  • Is the data reliable?
  • Are the workflows clearly defined?
  • Are exceptions understood?
  • Is ownership clear when something goes wrong?

The quality of the infrastructure, data, and processes will have a direct effect on the quality of the result.

How to Evaluate a Partner

Automotive companies should evaluate potential partners based on their ability to perform, rather than relying primarily on company age, size, funding, or market visibility.

The evaluation should include practical operating questions:

  • Has the provider demonstrated that its infrastructure can manage meaningful volume?
  • What happens when claims spike or demand changes unexpectedly?
  • Which parts of the implementation are proven, and which are still being developed?
  • Can the provider integrate with existing systems and processes?
  • Does it have the service infrastructure to support customers after launch?
  • Are its pricing and underwriting models aligned with the economics of the program?
  • Who owns the implementation?
  • Who is accountable when something does not work?
  • Can the provider support growth without creating a corresponding increase in service failures or operating costs?

These questions provide a clearer view of the provider's operating model than a sales presentation alone.

Technology should be evaluated as part of that model, not separately from it. Its value depends on how well it supports implementation, service delivery, customer experience and growth.

The automotive services industry needs new products, stronger technology and better approaches to longstanding problems. Innovation creates the opportunity, but execution determines whether that opportunity becomes a durable business.

A concept may be promising. A pilot may produce strong initial results. An agreement may create expectations.

A sustainable business develops when an organization can repeat that success across customers, markets, and transaction volumes while maintaining reliability, sound economics, and accountability.

In automotive services, the strongest competitive advantage is the ability to deliver what was promised consistently and at scale.

AI Fraud Finds a Weak Spot

AI-generated fake IDs are flooding rental applications, turning lease approvals into unsecured credit decisions with little regulatory oversight.

Insurance

In September 2025, a man calling himself Igor was approved for two apartments in Hollywood, each renting for $5,300 a month. His bank statements, proof of employment and ID all cleared. Two days later, the landlord's bank flagged the cashier's checks for first and last month's rent as fraudulent.

When the owner, Michael Renkow, got to the building, one door was pinned shut from the inside. Meanwhile, in another unit, a woman who had paid Igor to sublet told him she had established residency and wasn't leaving.

The eviction took seven months, and Renkow said the whole episode cost him about $90,000. In May 2026, he was thinking about selling the building altogether.

If a bank had onboarded a customer that way, it would be a compliance scandal. But in rental housing, it barely made the news, and the only reason we know how it ended is that the suspect used his real face on the fake ID. Police eventually tracked him down, but not until January this year--four full months after the initial lease was signed.

Leasing is one of the least protected onboarding checkpoints in the financial system, and AI has found it.

A credit decision nobody deems as one

Think about what a lease actually is. A 12-month lease at $5,300 a month is roughly $63,600 in rent extended on trust, plus the keys to an asset worth far more. That's an unsecured credit decision by any reasonable definition, and yet, it's usually made by a leasing agent with a deadline, looking at PDFs.

The deadline is part of the problem. Chris Rankin, CEO of screening company Rent Butter, told Bisnow that tighter competition and ever-larger portfolios are pushing property managers to fill units faster, making it hard to look closely at every application.

In a lender's world, speed and scrutiny are traded off deliberately, whereas in leasing, speed usually wins by default.

Banks have spent years hardening this exact moment. In November 2024, in fact, the U.S. Financial Crimes Enforcement Network (FinCEN) issued an alert warning financial institutions that criminals were using generative AI to fake identity documents and get past verification controls.

Most financial institutions responded with the tools they already had. Think customer identification programs, liveness checks, suspicious activity reports, and a regulator watching. When one bank flags a fake identity, that signal goes somewhere; a landlord who spots a forged pay stub usually just rejects the applicant, who is free to try the building down the street.

Leasing does have a federal rulebook, but it points in a different direction. Under the Fair Credit Reporting Act, the FTC treats tenant screening companies as consumer reporting agencies, with a duty to keep their reports accurate. This protects applicants from being wrongly denied because of bad data, which is important but doesn't tell a landlord how to catch an applicant whose data is fake.

That part is left to each operator's budget and judgment. Yet, a leasing office has an inbox and a vacancy target.

The fakes got cheap

Most people underestimate how easy this has become. MRI Real Estate Software, for example, bought 200 AI-generated fake IDs, some for as little as $5, and tested them against standard verification tools, finding optical character recognition readers, the industry default, caught only 24%.

Recently, a Checkr survey of 1,400 landlords across 14 U.S. cities concluded that, in San Francisco alone, 85% of them are worried about application fraud. One in three had discovered identity theft in their buildings, and 70% had discovered or suspected application fraud that ended in an eviction.

Most respondents actually found out only after the tenant had moved in. At the worst possible time to learn anything.

Industry-wide, a National Multifamily Housing Council survey found that respondents wrote off an average of nearly $4.2 million in bad debt over 12 months, and about a quarter of it was tied to nonpayment by tenants who got in with fraudulent applications.

Fraud also runs the other way. The FBI's 2025 Internet Crime Report logged 12,368 real estate fraud complaints and $275 million in losses, a category that includes fake listings aimed at renters.

Where losses land

When a fraudulent tenant gets in, the cost doesn't stay with one landlord, but shows up as bad debt, legal fees, damaged units, and months of lost rent. Then, it spreads.

Owners are already squeezed on insurance. Property insurance costs for securitized multifamily properties rose 58% over five years, according to New York-based analytics firm Trepp, making it their fastest-growing major expense.

A tenant who lied their way in is also unlikely to carry real coverage, so when something goes wrong, the damage and liability tend to fall on the owner's policy. That feeds loss history, renewals, and eventually the rent everyone else in the building pays.

Deposit alternatives and liability programs have to price in those losses, too, meaning honest renters end up subsidizing those dishonest ones.

But fintech has already worked out that you can't win an arms race over what a PDF looks like. Lenders moved to verifying at the source, with direct payroll connections, bank data, and continuous signals instead of one-time snapshots.

Leasing should do the same.

The good news is that a lot of source-verified data already moves through the leasing workflow, but it just isn't treated as risk data. Does a renter's insurance policy actually bind at lease signing? Is the "third-party policy" someone uploaded real, and does it stay active? Did the deposit payment clear through a traceable instrument?

A fair objection

Consumer advocates would push back on the story as told so far, and they have a record to point to. Much of the fraud data, including some of the figures above, comes from landlord trade groups and screening vendors, who have a commercial interest in the problem looking big.

They also have evidence that more screening doesn't automatically mean better screening. The National Consumer Law Center's Digital Denials report, for example, found that tenant screening reports often carry inaccurate eviction and criminal records, that landlords frequently rely on a single automated score, and that the harm falls disproportionately on Black and Latino renters.

Regulators have acted on this before. In 2023, the CFPB and FTC asked a federal court to order TransUnion to pay $11 million to consumers plus a $4 million penalty over its tenant screening practices. The CFPB has also noted that there is no proof screening reports actually predict how someone will behave as a tenant.

Then, there's the cost. The FTC is now examining rental fees across the whole lease, from application to move-out, while NCLC separately argued that some proptech products, like security deposit alternatives, end up making renting more expensive. If every new fraud check becomes another fee on applicants, honest renters pay for a problem they didn't create.

That's a fair point, and it shapes what a good answer should look like. Verifying at the source and reusing signals that already exist in the lease lifecycle should make leasing cheaper and fairer for the honest majority, not more expensive.

Banks learned long ago that onboarding is where fraud is cheapest to stop. Rental housing is learning the same lesson one eviction at a time, and landlords far and wide are paying for it.

The 2027 Chief Claims Officer

Chief claims officers must transform their departments into AI-native ground-truth engines or risk becoming the bottleneck in enterprise transformation.

Insurance

For decades, the mandate of the chief claims cfficer was relatively clear: build a strong organization to investigate claims, control costs, manage litigation, negotiate settlements, and deliver fair outcomes.

That mandate is no longer sufficient.

The 2027 chief claims officer has a much bigger job: build the insurer's ground-truth engine—an AI-native operation that produces superior outcomes, industrializes negotiation excellence, and converts what claims learns into intelligence for the entire enterprise.

This is not simply about using AI to make legacy claims processes more efficient. AI is turning insurance into an information business—and the most important ground truth in that business is generated in claims. Claims reveal what actually happened to the risks the insurer underwrote, what drove the loss, and what ultimately determined its economic outcome.

To compete in an AI world, insurers will need to capture that ground truth, make it machine-readable, and use it to improve underwriting, pricing, reserving, and portfolio management.

That puts claims—and the chief claims officer—on the front line of this unprecedented transformation.

A new competitive environment

Claims officers in traditional claims organizations face urgent and pressing competition from two sources at once. On one side is an increasingly industrialized plaintiff bar. On the other side is a new generation of AI-native insurers, poised to move forward.

On the first side, consider Morgan & Morgan. The personal-injury giant says it has invested roughly $300 million in technology and AI and plans at least $1 billion more over the next decade. Its proprietary MX2 platform supports medical-record extraction, case research, document generation, demand letters, and trial preparation, while Injury.com digitally acquires and qualifies potential claims.

Private equity is adding fuel, investing in personal-injury platforms to scale technology, analytics, marketing and standardized operations.

The plaintiff bar is turning claim development and negotiation from individual craftsmanship into an industrial system.

On the second side, a new generation of AI-native insurers is being built without decades of legacy technology, workflows and organizational baggage.

Companies such as Corgi are attempting to build insurance businesses from inception around modern data architectures, AI agents and technology-speed iteration. McKinsey has warned that AI-native insurance businesses can increasingly build and refine products in weeks while incumbents remain calibrated to annual planning cycles and multi-year transformations. 

Legacy insurers are being squeezed from both directions: out-innovated by the plaintiff bar in the contest over outcomes and potentially out-architected by AI-native insurers in the contest over how insurance itself operates.

Claims sits directly in the middle. That changes the requirements of its leader.

1. Level the playing field with the plaintiff bar

The plaintiff bar has largely approached AI as a weapon for improving economic outcomes. Carriers have largely approached it as a tool for workflow efficiency.

AI-powered demand packages are working. Carriers are only beginning to experiment seriously with the corresponding AI-powered offer package. Meanwhile, sophisticated plaintiff organizations are accumulating data, developing proprietary AI and attracting enormous capital.

The plaintiff bar is both the threat and the proof point.

They are investing their own money—and increasing institutional capital—because better case development, persuasion, and negotiation improve their economics.

The CCO must build institutional capabilities that can match increasingly industrialized counterparties.

2. Institutionalize negotiation excellence

Most carriers have some excellent negotiators. That is no longer enough.

If negotiation materially affects indemnity outcomes, it cannot remain an individual skill distributed unevenly across thousands of claims professionals. The organization should know who its elite negotiators are, why they outperform and how those behaviors can be replicated.

Carriers that cannot identify, measure and reproduce negotiation excellence do not really possess a negotiation capability. They possess individual negotiators.

The CCO must turn individual excellence into measurable institutional capability.

3. Stop putting AI band-aids on pre-AI claims operations

Many carriers can produce an impressive list of AI-centric projects: summarize a file, extract information, draft correspondence, analyze a demand, route work, search notes, or give adjusters Copilot.

Those applications can create real value. But old process plus an AI tool means slightly better old process.

McKinsey has warned about layering new technology onto legacy insurance operating models. BCG similarly distinguishes between deploying AI into existing processes and reshaping workflows around AI.

The CCO must redesign the operating model, not merely automate the existing one.

4. Build machine-first claims

The traditional claim file was built primarily for humans. Documents, notes, emails, medical records, and litigation materials accumulate while experienced professionals gradually construct an understanding of what happened.

In an AI-native operation, every claim should progressively become a machine-readable representation of the claim—the people, events, evidence, injuries, allegations, relationships, negotiations and outcomes.

That structured claim becomes the substrate on which specialized AI agents can continuously reason. Instead of occasionally asking AI to summarize a file, machines continuously read, structure, monitor, compare, detect, and prepare.

The CCO must make claims machine-readable while elevating, not diminishing, human judgment and action.

5. Build and lead a hybrid workforce

The future claim officer will have two kinds of capacity at their disposal: human expertise and machine intelligence.

AI agents will increasingly read, structure, monitor, research, compare, detect, analyze and prepare. Humans will increasingly concentrate on judgment, investigation, strategy, creativity, empathy, supervision, accountability and negotiation.

That will make exceptional claims professionals more important, not less.

Imagine an elite negotiator supported by agents that continuously understand the evidence, medical history, venue, plaintiff counsel, negotiation history, and comparable outcomes.

The machine handles much of the cognitive preparation. The human concentrates on what exceptional humans do best: think, strategize, persuade, read the counterparty, exercise judgment, and negotiate.

The CCO must become the architect of human and machine capacity—designing how each works together to produce better outcomes.

6. Make every negotiation a learning event

A sophisticated plaintiff demand should eventually meet an equally sophisticated carrier response. But the bigger opportunity comes afterward.

Every demand, analysis, strategy, offer, response, counteroffer, and outcome must become institutional knowledge in the same way that the plaintiff bar is institutionalizing these events.

Which plaintiff firms consistently outperform? Which strategies work against them? Which facts change settlement value? Which negotiators outperform expectations? Where does the organization systematically overpay?

Every negotiation should make the next negotiation smarter.

The CCO must ensure every claim and negotiation makes the organization smarter.

7. Elevate claims into the insurer's ground-truth engine

This is where the transformation extends beyond claims.

Underwriting begins with hypotheses about risk. Pricing quantifies them. Reserving updates them. Claims discovers what was actually true.

Claims learns what caused the loss, how injuries developed, what evidence mattered, how attorneys behaved, which defenses and negotiation strategies worked, and what the risk ultimately cost.

Yet much of that knowledge remains trapped in PDFs, notes, litigation files and the heads of experienced claims professionals.

Claims should continuously produce structured intelligence that flows into underwriting, pricing, reserving, risk, reinsurance and portfolio management.

The claim is no longer simply something to resolve and close. It is one of the insurer's richest proprietary information assets. The CCO must turn claims knowledge into enterprise intelligence—making the claims organization the feedback loop that allows the entire enterprise to learn.

8. Don't let claims become the transformation bottleneck

This may be the requirement that matters most to the rest of the C-suite.

A legacy insurer can modernize distribution, underwriting, pricing and portfolio management. But if its richest source of ground truth remains trapped inside a document-centric, human-first claims operation moving through multi-year transformation cycles, the rest of the enterprise eventually hits a wall.

AI-native competitors do not have to unwind decades of organizational architecture before redesigning how humans, machines and data work together. Incumbents do. That makes speed itself a competitive capability.

The modern CCO must protect the integrity of a massive, consequential operation while simultaneously making it capable of continuous change.

The plaintiff bar is moving at technology speed. AI-native competitors are being built for technology speed. Claims cannot continue moving at insurance speed.

The CCO must ensure claims leads rather than constrains the insurer's AI transformation.

The mandate has changed

None of these requirements eliminates the traditional responsibilities of the CCO. Claims still must be handled fairly; customers, regulatory obligations, litigation, reserves and operational discipline still matter.

But those responsibilities are increasingly table stakes.

Sophisticated plaintiff organizations are industrializing the pursuit of settlement dollars while AI-native insurers are being architected as technology-speed information businesses. Between them sits a claims organization that, at many incumbents, was designed for another era.

That creates both a threat and an extraordinary opportunity.

Carriers that generate that ground truth better, negotiate from it more effectively, make it machine-readable and distribute it throughout the enterprise will possess something more valuable than a more efficient claims department. They will possess a continuously learning insurance enterprise.

As chief claims officers enter 2027, the question is no longer whether their departments will use more AI. It is whether they can transform their departments into a competitive advantage rather than the bottleneck preventing the enterprise from changing with it.


John Burge

Profile picture for user JohnBurge

John Burge

John Burge is an engineer/attorney-turned-entrepreneur and operating executive at SigmaSight.

For the last 25 years he has led technology startups and turnarounds in the medical, insurance and litigation verticals, including managing a $400 million portfolio of medical malpractice runoff. Prior to becoming an entrepreneur, he was a product liability litigator and served in engineering roles with Upjohn and Eastman Kodak.